
 Wood Fiber Insulation Market | 2026-2036
Wood Fiber Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Fiber Insulation Market Analytics
Residential retrofit contractors is rotating toward wood fiber solutions as energy renovation mandates tighten across European markets. STEICO leverages its integrated forestry-to-insulation supply chain to dominate Central European project pipelines. Hunton Fiber anchors Nordic demand through its Norway-based production of high-density fiber boards. GUTEX competes on breathable wall system expertise, positioning its products within German passive house certification channels.
Wood fiber insulation consists of mechanically processed softwood fibers, typically bound with magnesite or pure wood lignin, forming boards with thermal conductivity values ranging from 0.038 to 0.045 W/mK and hygroscopic moisture-buffering capacity. Manufacturers compress these fibers under heat to create rigid boards, soft boards, or loose-fill blown insulation for wall, roof, and floor assemblies requiring vapor-permeable thermal barriers. Rigid boards command the largest volume share due to their compatibility with timber frame construction and established mechanical fixing protocols. Blown insulation represents the fastest-expanding product type as retrofit contractors seek cavity-fill solutions for irregular building geometries. Soft boards retain strong positioning in historic building renovations where breathability and minimal compression stress prove decisive for heritage preservation.
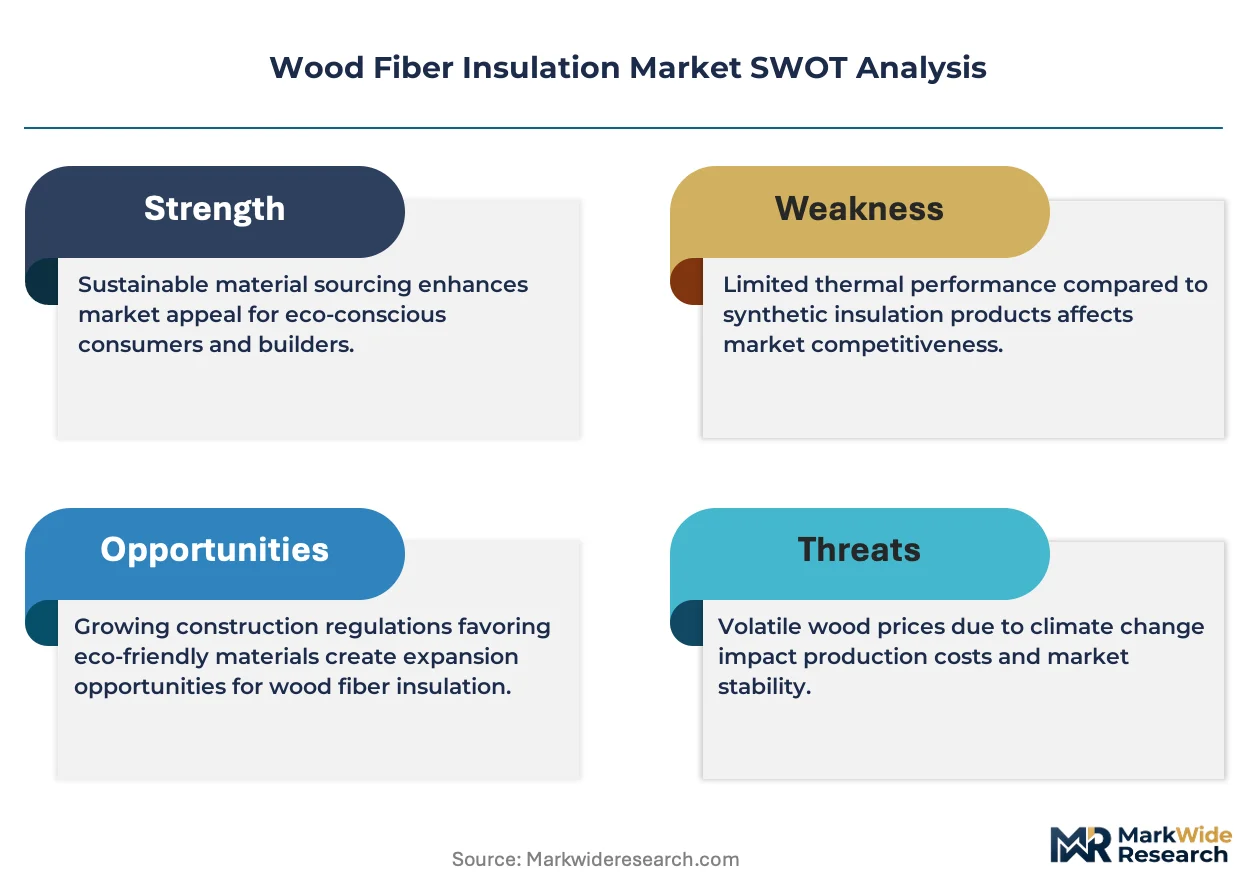
EMA's Construction Products Regulation framework governs CE marking requirements for wood fiber insulation sold across EU member states, while REACH compliance restricts certain chemical binders and drives manufacturers toward lignin-based alternatives. Germany's Building Energy Act and France's RE2020 environmental regulation collectively tighten thermal performance mandates and embodied carbon thresholds for new and renovated structures. Stakeholders must monitor evolving national transpositions of the EU Green Deal's building renovation targets and assess lignin-binding technology maturation as a determinant of cost-competitive, regulation-compliant supply expansion.
Market Dynamics
The EU Green Deal's building renovation targets are compressing project timelines across Central Europe, forcing contractors to abandon mineral wool in favor of lignin-bound wood fiber systems that satisfy both thermal performance mandates and embodied carbon thresholds without supply chain recalibration.
Growth Catalysts
- France's RE2020 environmental regulation:New construction and major renovations must demonstrate reduced lifecycle carbon emissions, directing specification teams toward bio-based insulation materials with verified Environmental Product Declarations.
- Retrofit contractor procurement:Residential energy renovation mandates in Germany and Austria are creating dedicated purchasing agreements for cavity-fill blown insulation products compatible with irregular historic building geometries.
- Lignin-binding chemistry:Manufacturers are eliminating synthetic magnesite binders to preempt REACH restrictions on chemical additives, unlocking premium positioning in certified passive house supply chains.
Market Restraints
- Softwood fiber supply concentration:Nordic pulp mill integration with insulation manufacturing creates dependency on Swedish and Norwegian timber harvest cycles subject to climate-related supply interruptions.
- Cost structure rigidity:Energy-intensive defibration and compression processes expose producers to natural gas price volatility that synthetic insulation competitors avoid through polymer feedstock hedging.
- Technical limitation in high-rise applications:Fire resistance ratings for uncoated wood fiber boards fall below regulatory thresholds for buildings exceeding 22 meters in multiple German federal states.
Strategic Opportunities
- Polish manufacturing expansion:Underdeveloped domestic production capacity relative to projected renovation volumes creates first-mover advantage for lignin-binding technology licensing agreements.
- Timber frame multi-family construction:Prefabricated panel assemblers in Austria and Switzerland are specifying rigid wood fiber boards as structural sheathing-thermal barrier composites.
- CE marking harmonization:EMA's Construction Products Regulation streamlining is reducing national certification duplication costs for cross-border project bidding.
Industry Challenges
- Certification timeline compression:CE marking documentation for novel lignin-bound formulations requires extended fire reaction testing protocols that delay commercial launch windows.
- Moisture management expertise scarcity:Installation crews lack training in hygroscopic material behavior, generating liability exposure when vapor-permeable systems are paired with impermeable retrofit membranes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Fiber Insulation Market |
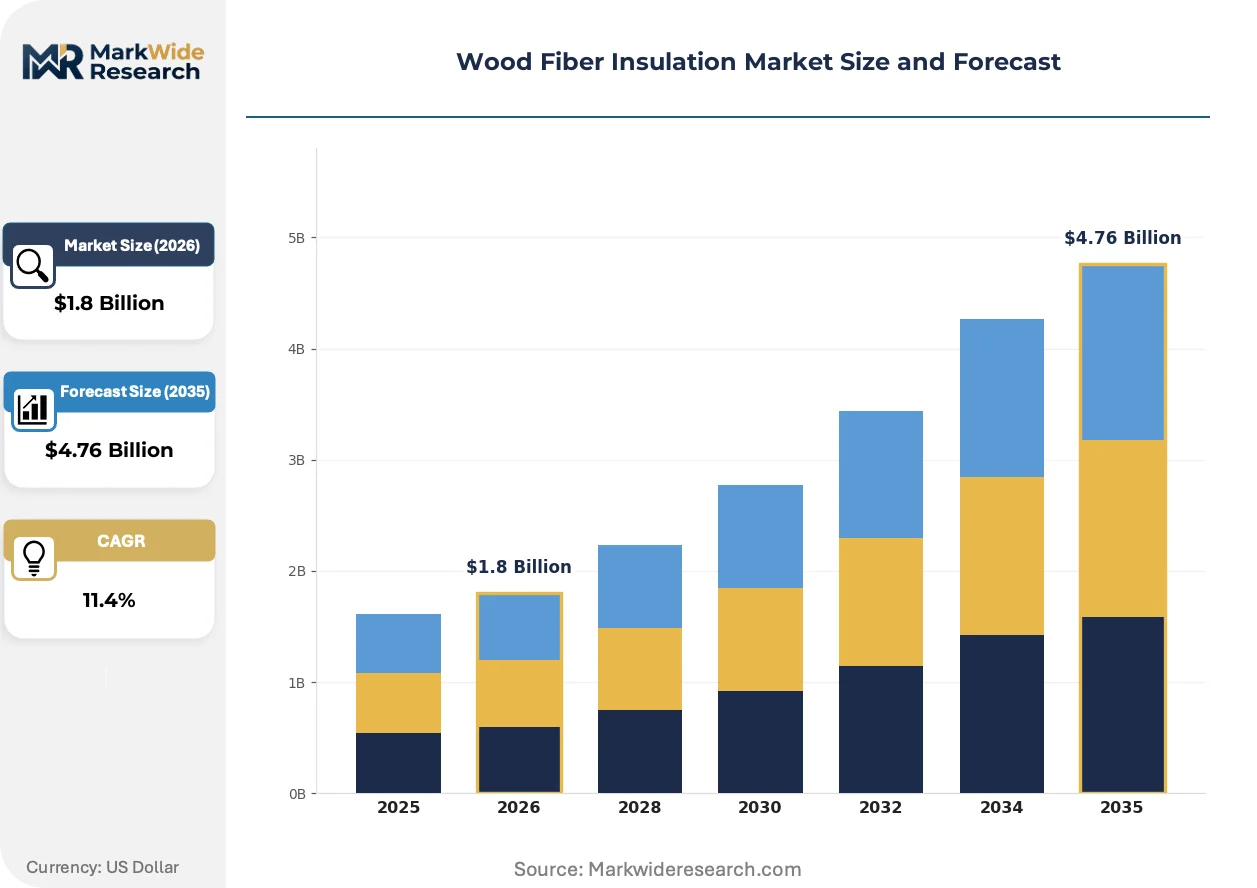
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Boards, Soft Boards, Blown Insulation, Spray Insulation Application: Residential Buildings, Commercial Buildings, Industrial Settings, Agricultural Structures Installation Method: Mechanical Fixing, Adhesive Bonding, Insulating Systems, Loose Fill End User: Contractors, Architects, Homeowners, Builders |
| Companies Covered | Hunton Fiber, Soprema, STEICO, Agepan, Knauf Insulation, GUTEX, TimberHP, Celenit, PAVATEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Fiber Insulation Market Evolving Landscape
Binding chemistry innovation is fragmenting established product hierarchies as manufacturers race to eliminate petrochemical inputs ahead of regulatory phase-outs. Three concurrent developments are restructuring competitive positioning.
Dry-process lignin activation technology is fragmenting the binder supply landscape. This approach extracts and reactivates natural wood adhesives without magnesite supplementation, reducing embodied carbon by eliminating mined mineral inputs. Austrian and German pilot facilities are scaling production for 2026 commercial deployment. The technology is fragmenting incumbent supply relationships between insulation producers and chemical additive suppliers.
REACH authorization reviews are accelerating binder substitution timelines. ECHA's scrutiny of formaldehyde-releasing agents in conventional wood-based panels is extending to insulation binders, compelling reformulation investments. German manufacturers are pre-emptively certifying lignin-only products to secure specification in public procurement channels where chemical hazard screening now occurs.
Heritage building conservation officers are mandating breathable insulation retrofits. This specification preference is displacing synthetic cavity-fill alternatives in protected structure renovations across Bavaria and Baden-Württemberg. Contractors are retraining installation crews in soft board handling techniques to capture municipal heritage preservation contracts.
Wood Fiber Insulation Market Segmentation
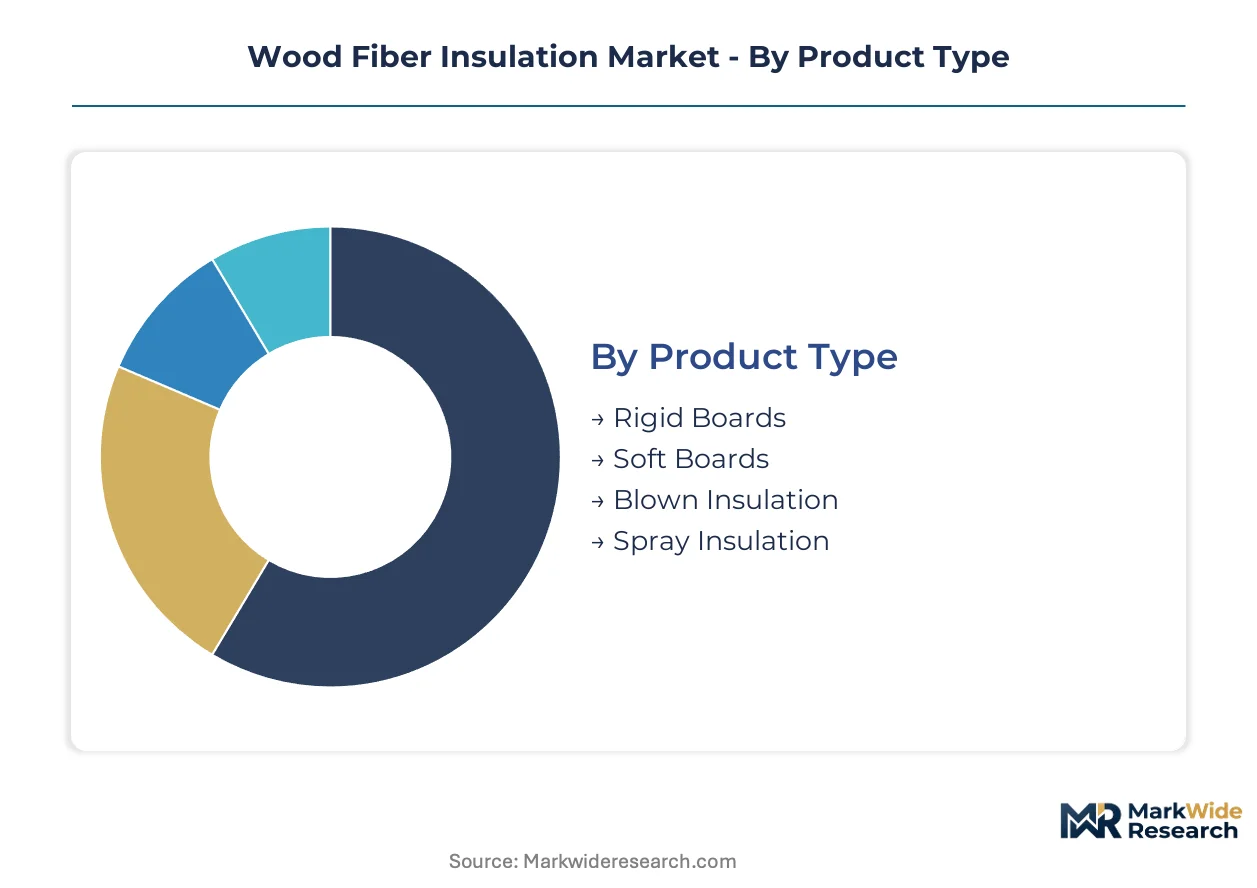
Wood fiber insulation segmentation reflects divergent technical requirements across construction methodologies and regulatory environments. Product form factors determine compatibility with timber frame, masonry retrofit, and heritage preservation protocols. Installation method selection directly impacts labor certification needs and project timeline compliance under EU Green Deal renovation targets.
Product Type:
REACH authorization timelines for chemical binders are fragmenting competitive positioning between magnesite-bound and lignin-only formulations across product categories.
- Rigid Boards:High-density compressed fiber panels with thermal conductivity values between 0.038-0.045 W/mK serve as structural sheathing-thermal barrier composites in Austrian and Swiss prefabricated timber frame construction. German passive house certification channels specify these boards for wall and roof assemblies requiring mechanical fixing compatibility.
- Blown Insulation:Mechanically processed loose-fill fibers distributed through pneumatic cavity-fill equipment address irregular geometries in historic building retrofits across Bavaria and Baden-Württemberg. Residential retrofit contractors in Germany and Austria are securing dedicated purchasing agreements for this product type as energy renovation mandates compress project timelines.
- Soft Boards:Low-density flexible panels bound with lignin or magnesite provide vapor-permeable thermal barriers with minimal compression stress for heritage preservation projects.
- Spray Insulation:Moisture-activated adhesive formulations applied through specialized equipment create monolithic thermal envelopes in agricultural structures and industrial settings with complex surface topographies.
Rigid boards handle the majority of throughput; blown insulation is expanding most quickly on share as retrofit volumes accelerate.
Application:
Cost tier differentiation separates premium heritage-compliant systems from standard new construction specifications across building typologies.
- Residential Buildings:Single-family and multi-family structures dominate volume consumption, with German Building Energy Act thermal performance thresholds driving specification toward bio-based materials with verified Environmental Product Declarations.
- Commercial Buildings:Office and retail structures in Nordic markets specify rigid boards for timber frame multi-family construction compatibility.
- Industrial Settings:Manufacturing facilities and warehouses with large surface-area-to-volume ratios employ blown and spray systems for rapid envelope completion.
- Agricultural Structures:Barns, storage facilities, and livestock housing utilize cost-optimized soft board and loose-fill configurations where breathability prevents condensation damage.
Residential buildings absorb the dominant share of production volume; commercial buildings are climbing the fastest as timber frame construction expands.
Installation Method:
Customer type concentration among specialized contractors versus generalist builders determines method selection and training investment requirements.
- Mechanical Fixing:Screw and staple attachment protocols for rigid boards align with established timber frame construction workflows and CE marking harmonization for cross-border project bidding.
- Loose Fill:Pneumatic cavity-fill distribution requires crew certification in hygroscopic material behavior to prevent liability exposure from improper vapor-permeable system pairing.
- Adhesive Bonding:Cold or hot-applied attachment systems for soft boards on irregular substrates in historic masonry structures.
- Insulating Systems:Pre-assembled panel configurations with integrated wood fiber layers reduce on-site labor for prefabricated construction in Austria and Switzerland.
Mechanical fixing commands the largest installation volume; loose fill is gaining share fastest as retrofit contractor procurement intensifies.
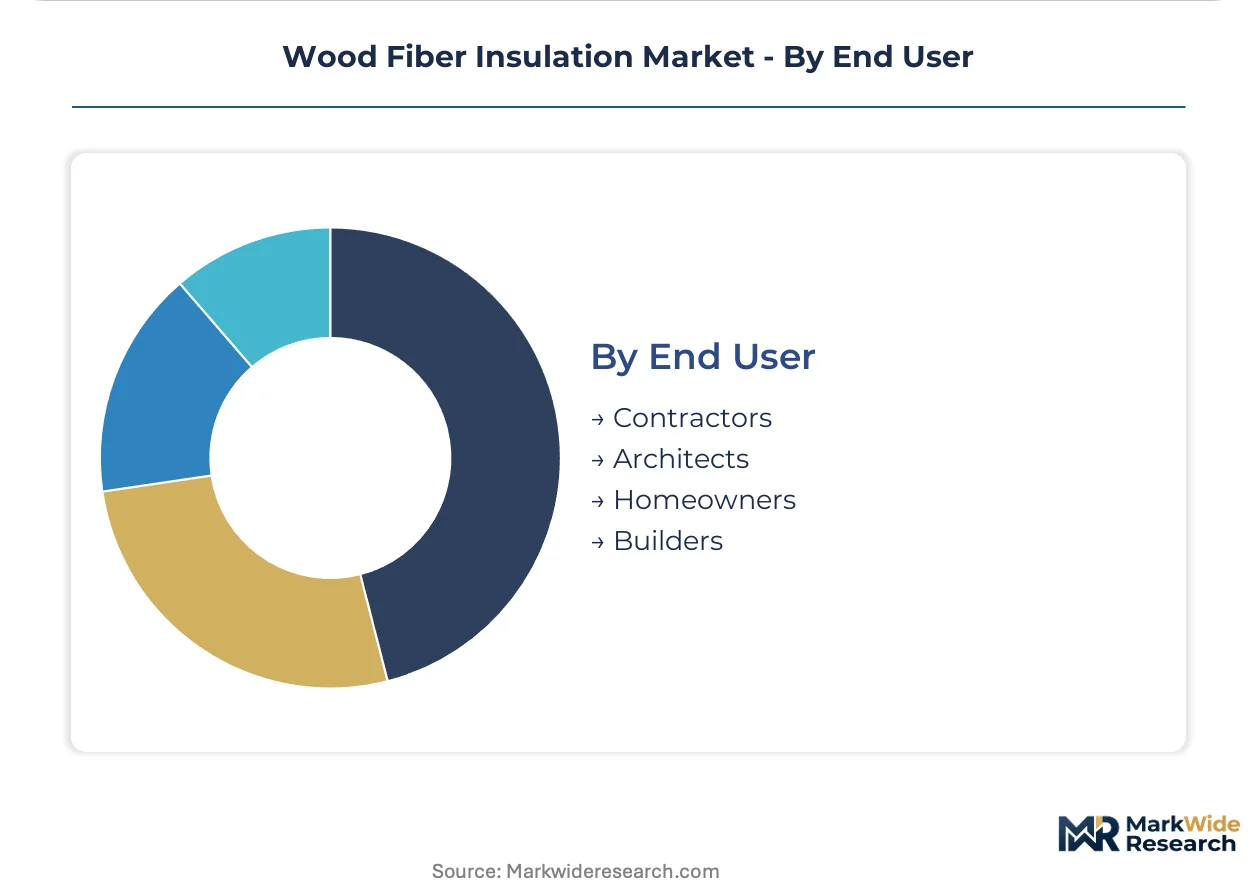
End User:
Margin structure varies sharply between specification-influencing professionals and price-sensitive direct purchasers.
- Contractors:Residential retrofit specialists in Germany and Austria are rotating procurement toward lignin-bound blown insulation systems that satisfy embodied carbon thresholds without supply chain recalibration. Municipal heritage preservation contracts require retrained installation crews in soft board handling techniques.
- Architects:Specification professionals in France direct project teams toward bio-based materials demonstrating reduced lifecycle carbon emissions under RE2020 environmental regulation.
- Builders:Volume construction firms prioritize cost-optimized rigid board procurement for new timber frame multi-family developments.
- Homeowners:Direct purchasers in single-family renovation segments respond to energy subsidy programs and thermal performance mandate awareness.
Contractors represent the largest end-user category by volume; architects are expanding their influence fastest as environmental regulation tightens specification control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine rail freight corridor underwrites Central European wood fiber distribution, connecting Nordic pulp mills to German manufacturing clusters and onward to Swiss construction markets.
Germany
Residential retrofit contractors in Bavaria and Baden-Württemberg are securing dedicated purchasing agreements for cavity-fill blown insulation. The Building Energy Act tightens thermal performance thresholds for existing structures. The Stuttgart manufacturing cluster hosts multiple rigid board producers serving passive house certification channels.
France
Architects in Île-de-France direct specification teams toward bio-based materials with verified Environmental Product Declarations. RE2020 environmental regulation mandates reduced lifecycle carbon emissions for new construction and major renovations. The Lyon-Auvergne corridor anchors prefabricated timber frame panel assembly operations.
Sweden
Nordic pulp mill integration with insulation manufacturing creates concentrated softwood fiber supply for export markets. The country's national building regulator enforces stringent moisture management standards for hygroscopic materials. The Västra Götaland region hosts vertically integrated forestry-to-insulation operations.
Austria
Timber frame multi-family construction in Vorarlberg and Tyrol specifies rigid wood fiber boards as structural sheathing-thermal barrier composites. National energy efficiency programs subsidize bio-based insulation retrofits for single-family housing. The Salzburg-Tyrol industrial corridor specializes in dry-process lignin activation pilot facilities.
Poland
Underdeveloped domestic production capacity relative to projected renovation volumes attracts technology licensing interest. EU Green Deal building renovation targets compress project timelines across Masovia and Silesia. The Warsaw metropolitan area concentrates distribution logistics for cross-border Central European supply.
Wood Fiber Insulation Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and supply chain control dimensions. The market structure consolidates around integrated forestry operators and specialized insulation fabricators. Three archetypes dominate: pulp-integrated multinationals, regional timber-to-insulation specialists, and chemical-agnostic technology licensors. Capacity expansion and lignin-binding technology licensing represent the dominant competitive moves.
Within the pulp-integrated tier, Hunton Fiber and STEICO exemplify Nordic and Central European supply chain control strategies. GUTEX occupies a position among German passive house certification specialists. These three entities represent divergent approaches to binder chemistry transition and geographic market focus.
| Leading Market Players |
|---|
| Hunton Fiber |
| Soprema |
| STEICO |
| Agepan |
| Knauf Insulation |
| GUTEX |
| TimberHP |
| Celenit |
| PAVATEX |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Nordic pulp mills and Central European insulation manufacturers lock in softwood fiber supply access while anchoring price visibility across volatile natural gas input cycles. These arrangements concentrate procurement power among integrated operators who control both forestry assets and defibration capacity.
Pricing Analysis
Volume-discount tiering structures separate passive house-certified rigid boards from standard-grade soft boards and unclassified loose-fill products. Certification grade and geographic delivery cost serve as the primary price differentiation drivers. Pricing pressure stems from energy-intensive compression processes exposed to natural gas volatility that synthetic insulation competitors avoid through polymer feedstock hedging. Residential retrofit contractors exhibit the highest price sensitivity due to compressed project timelines under EU Green Deal mandates, while heritage preservation officers accept premium positioning for breathable lignin-bound systems.
Supply Chain Analysis
Nordic pulp mill integration with insulation manufacturing creates a chokepoint where Swedish and Norwegian timber harvest cycles constrain softwood fiber availability for export markets. The supply chain draws from Swedish pulp operations, Norwegian high-density board fabrication, and German rigid panel compression facilities. Raw material dependencies center on softwood pulp, magnesite or lignin binders, and natural gas for thermal processing. Single-source vulnerability runs through concentrated Nordic pulp supply exposed to climate-related harvest interruptions. Distribution runs through the Rhine-Alpine rail freight corridor connecting production clusters to Swiss and Austrian construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward residential retrofit contractors as energy renovation mandates consolidate procurement volumes among specialized firms capable of meeting compressed EU Green Deal timelines.
For Market Incumbents: Compound supply chain control through captive softwood fiber sourcing or long-term pulp mill partnerships to defend against lignin-binding technology licensors eroding magnesite-bound product margins. Prioritize CE marking harmonization investments to reduce national certification duplication costs for cross-border bidding in Swiss and Austrian timber frame markets. For New Entrants and Emerging Players: CE marking fast-track for lignin-only formulations unlocks specification in German public procurement channels where chemical hazard screening now occurs. Target Polish manufacturing expansion where underdeveloped domestic capacity relative to projected renovation volumes creates first-mover advantage for technology licensing agreements. Pursue heritage building conservation officer relationships in Bavaria and Baden-Württemberg where breathable insulation mandates displace synthetic alternatives. For Investors and Strategic Acquirers: Regional timber-to-insulation specialists with integrated forestry assets and established passive house certification channels represent the optimal acquisition target archetype for long-term viability across the 5-10 year regulatory transition window. Monitor lignin-binding technology maturation as the inflection indicator determining cost-competitive supply expansion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Lignin-Binding Technology Licensing | Eliminates REACH-restricted magnesite inputs while securing premium passive house certification positioning. |
| Backward Integration into Forestry Assets | Captive softwood fiber supply insulates margins from Nordic pulp mill pricing volatility and harvest interruptions. |
| CE Marking Harmonization Investment | Reduces national certification duplication costs for cross-border project bidding in Central European markets. |
| Heritage Preservation Contractor Certification | Captures municipal contracts in Bavaria and Baden-Württemberg where breathability mandates displace synthetic insulation. |
| Polish Manufacturing Capacity Buildout | Addresses underdeveloped domestic production relative to EU Green Deal renovation targets across Masovia and Silesia. |
Research Methodology
A standing panel of residential retrofit contractors, heritage preservation officers, lignin-binding technology R&D directors, and ECHA regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from EU Construction Products Regulation filings, REACH authorization review documents, national building energy act transpositions, and timber trade flow databases. Bottom-up project pipeline assessments triangulated against top-down macro renovation target allocations.
Consistency checks validated volume and value outputs against external benchmarks including EU Green Deal building renovation target progress reports and national energy efficiency program disbursement records. The analytical framework modeled product type, application, installation method, and end-user segments across the projection horizon. CAGRs were derived from regression analysis of historical retrofit completion rates against regulatory mandate intensity. Industry-specific forecast inputs included lignin-binding technology commercialization timelines and Nordic pulp mill capacity utilization rates.
Underlying assumptions cover sustained EU Green Deal building renovation target enforcement, stable Nordic softwood fiber harvest cycles, and lignin-binding technology scale-up feasibility, with deviation risk concentrated in natural gas price volatility and REACH authorization timeline extensions. Practitioners should keep alternative scenarios live as ECHA binder restriction reviews and national building code transpositions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
North America Activated Carbon Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
Injection Mold Hot Runners Market
Industrial Materials
Industrial Round Wood Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
United States Graphite Electrodes Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Continuous Mesh Belt Furnaces Market
Industrial Materials
Static Mixer Market
Industrial Materials
Heat Shrink Tubing and Sleeves Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Global Industrial Fastener Seal Market
Industrial Materials
North America Medical Plastics Extrusion Market
Industrial Materials
GCC Heat Treating Market
Industrial Materials
Felt Gasket Market