
 Steel Cord Market | 2026-2036
Steel Cord Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Cord Market Intelligence
High-tensile and super-tensile specification tiers is collapsing the gap between premium performance and mainstream radial tire production across the steel cord value chain. Bekaert leverages its integrated wire-to-cord manufacturing footprint across Belgium and China to sustain quality consistency at scale. Sumitomo Electric Industries anchors Japanese supply security through captive metallurgy partnerships and precision drawing capabilities. ArcelorMittal competes from upstream, controlling raw wire rod supply into cord conversion plants in Europe and Brazil.
Steel cord consists of multiple fine steel wires twisted into strands and cabled into reinforcement structures, typically manufactured from high-carbon steel with carbon content between 0.70% and 0.95% and tensile strength exceeding 2,800 MPa for super tensile grades, engineered to absorb dynamic loads and maintain dimensional stability under cyclic stress in rubber matrices. Radial tire applications dominate volume absorption, with super tensile and extra super tensile material grades capturing expanding share as OEMs pursue lightweighting targets. Conveyor belt and heavy machinery segments occupy stable replacement-driven demand pools with lower growth elasticity but durable margin profiles.
China's SAMR enforces GB standards for steel cord dimensional tolerance and fatigue performance, while the EU's REACH regulation restricts hazardous substance content in rubber-steel bonding treatments. The US EPA and OSHA jointly influence plant emissions and workplace exposure limits at domestic cord manufacturing facilities. Stakeholders must monitor evolving tensile grade certification requirements and regional carbon intensity rules for electric arc furnace feedstock.
Market Dynamics
Radial tire lightweighting mandates from automotive OEMs are compressing the performance gap between super tensile and extra super tensile grades, forcing metallurgical upgrades across the steel cord value chain.
Growth Catalysts
- EU REACH chemical compliance:Restrictions on hazardous bonding treatments accelerate adoption of cleaner rubber-steel adhesion chemistries in European tire plants.
- Electric vehicle platform loads:Battery-electric vehicle weight distributions increase per-tire load requirements, pulling higher tensile grades into mainstream passenger applications.
- East Asian manufacturing clusters:Concentrated tire production in China, Japan, and South Korea sustains demand density for just-in-time cord supply.
Market Restraints
- Wire rod supply concentration:Arc furnace feedstock availability constraints in Europe limit domestic cord production scaling.
- High-carbon steel price volatility:Scrap metal and iron ore input swings compress margin predictability for cord converters.
- Aramid fiber substitution:Advanced polymer reinforcements capture select conveyor belt and aerospace applications requiring corrosion immunity.
Strategic Opportunities
- India tire capacity expansion:Domestic OEM localization and export hub strategies create demand for localized cord supply.
- Smart tire integration:Steel cord structures capable of embedded sensor accommodation enable next-generation tire pressure and wear monitoring.
- EU Green Deal carbon border adjustments:Preferential treatment for low-emission arc furnace feedstock rewards early decarbonization investments.
Industry Challenges
- Precision drawing talent scarcity:Multi-stage wire reduction expertise concentrates in aging workforces across Belgian and Japanese plants.
- GB standard fatigue certification timelines:China's SAMR extended approval cycles delay new grade commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Cord Market |
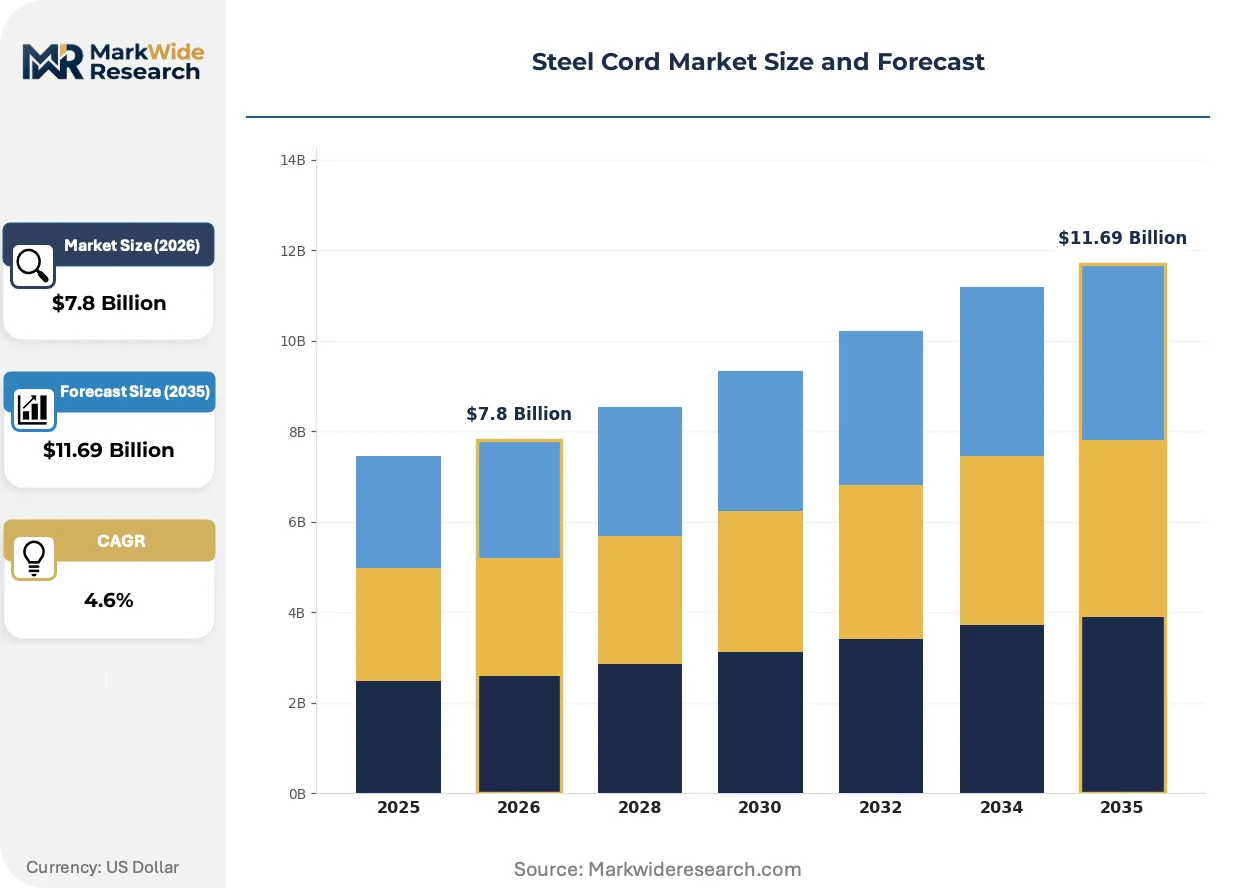
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Conveyor Belts, Industrial Applications Material Grade: Super Tensile, Extra Super Tensile, High Tensile, Regular Tensile End User: Tire Manufacturers, Construction, Automotive, Aerospace Application: Automotive Rubber, Heavy Machinery, Mining, Others |
| Companies Covered | Bekaert, Sumitomo Electric Industries, ArcelorMittal, HYOSUNG Advanced Materials, Henan Hengxing Science & Technology, Bridgestone, Jiangsu Xingda Steel Cord, Tokusen Kogyo, Shougang Century, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Cord Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry restrictions are rewriting manufacturing protocols across steel cord production, with implications for equipment investment cycles and supplier qualification timelines.
Ultra-fine wire drawing technology is decomposing the traditional tradeoff between tensile strength and fatigue resistance. Tier-one tire manufacturers in Germany and South Korea now specify 0.15mm filaments for ultra-high-performance passenger segments. This capability compression is collapsing the premium-mainstream grade boundary that structured pricing for two decades.
REACH Annex XVII restrictions on cobalt-based adhesion promoters are forcing rubber-steel bonding chemistry transitions across European cord finishing lines. The regulation's industrial consequence is accelerated qualification of silane-based and plasma-treated alternatives. Tire makers with integrated cord operations in Belgium and Spain face compressed reformulation timelines to maintain OEM supply contracts.
Consolidated procurement desks at multinational tire groups are displacing fragmented regional buying. Direct mill-to-plant contracts now dominate volume planning for radial tire reinforcement, with spot market participation relegated to maintenance and specialty grades. This concentration is most visible in Japanese keiretsu supply structures, where captive cord operations face externalization pressure from group procurement centralization.
Steel Cord Market Segmentation
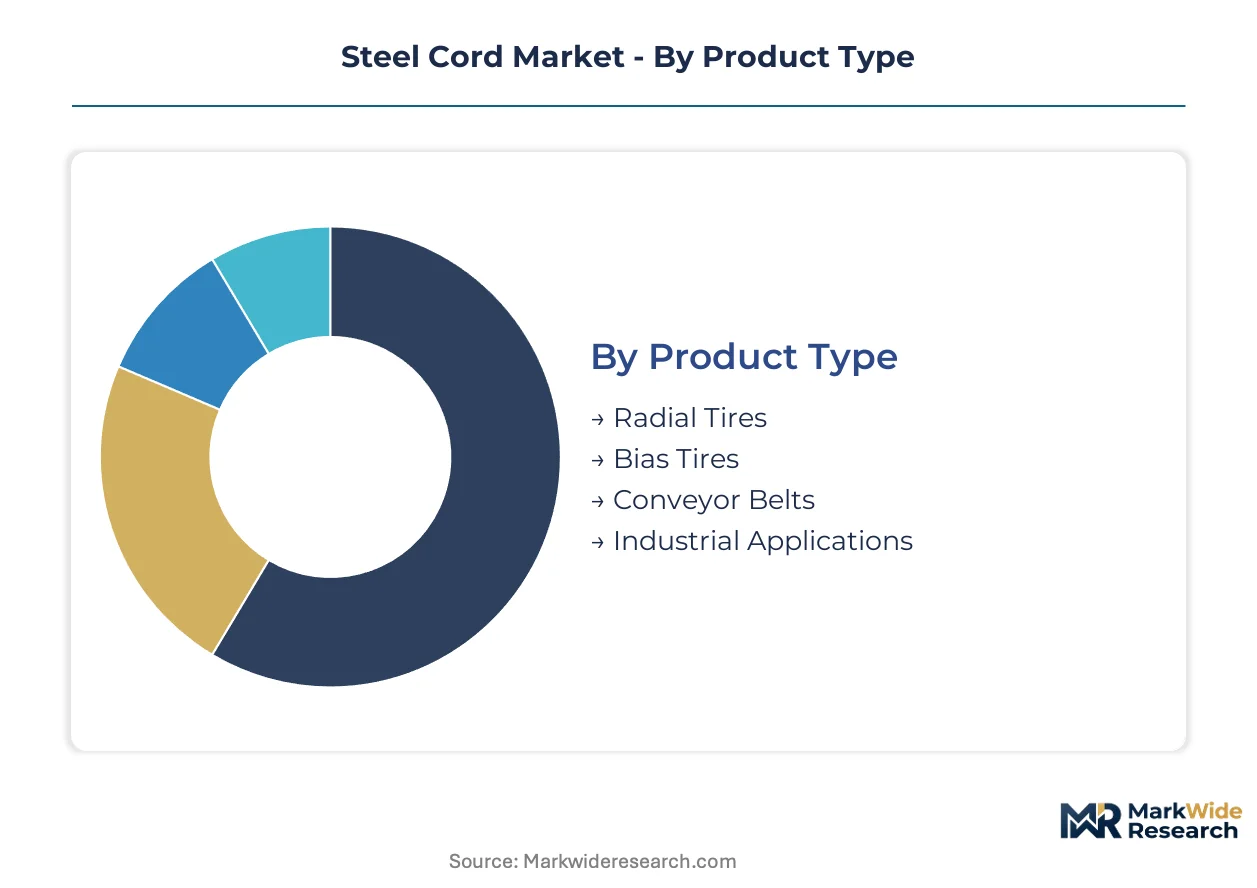
Steel cord segmentation reveals how substitution pressures and performance tier migration reshape procurement patterns across tire and industrial reinforcement applications. Understanding grade boundaries and end-use concentration enables suppliers to calibrate metallurgical investments against actual demand elasticity.
Product Type:
Aramid and hybrid polymer reinforcements threaten conveyor belt and select industrial segments most acutely, while radial tire applications maintain steel's structural dominance through fatigue performance requirements.
- Radial Tires:Multi-strand steel cables engineered for belt and carcass reinforcement absorb dynamic loads under cyclic stress. Passenger and commercial vehicle OEMs in Germany, Japan, and South Korea specify super tensile grades for lightweighting compliance, with extra super tensile penetration accelerating in electric vehicle platforms.
- Bias Tires:Cross-ply construction relies on lower-grade cord specifications with simpler manufacturing tolerances. Demand concentrates in agricultural and off-road equipment segments across India and Brazil where cost sensitivity outweighs rolling resistance targets.
- Conveyor Belts:Longitudinal reinforcement for mining and bulk material handling faces active substitution from aramid fiber in corrosive environments. Steel maintains share in high-tension, high-impact applications requiring cut resistance.
- Industrial Applications:Hose reinforcement, air springs, and elevator cables occupy fragmented demand pools with specification diversity. Replacement cycles and maintenance schedules drive procurement timing rather than OEM platform launches.
Radial tires anchor the volume base while conveyor belts face the steepest share erosion from polymer substitutes.
Material Grade:
Cost tier stratification determines equipment investment recovery timelines, with premium grades requiring precision drawing capabilities that concentrate in Belgian and Japanese manufacturing clusters.
- Super Tensile:Carbon content between 0.80% and 0.95% delivers tensile strength of 2,800-3,200 MPa for mainstream radial tire platforms. Chinese tire plants consume the largest absolute volumes as domestic OEMs upgrade fleet efficiency ratings.
- Extra Super Tensile:Ultra-high carbon metallurgy achieves 3,400+ MPa for electric vehicle load compensation and ultra-high-performance segments. South Korean tire manufacturers specify 0.15mm filaments for flagship passenger models.
- High Tensile:Mid-grade specifications serve commercial vehicle retread markets and developing economy OEM supply. Price elasticity remains highest in this tier as converters balance scrap input costs against finished cord premiums.
- Regular Tensile:Legacy grades persist in bias tire construction and non-critical industrial hose applications. Volume declines steadily as grade boundaries compress upward.
Super tensile grades generate the revenue base while extra super tensile specifications climb the fastest through electric vehicle platform penetration.
End User:
Customer type concentration determines contract structure, with integrated tire manufacturers capturing volume discounts that independent converters cannot match.
- Tire Manufacturers:Captive cord operations at Bridgestone, Michelin, and Goodyear facilities compete against merchant suppliers for internal procurement. Direct mill-to-plant contracts dominate volume planning with spot market relegation to maintenance grades.
- Construction:Precast concrete and geotechnical reinforcement applications specify epoxy-coated or galvanized variants for corrosion protection. Project-based procurement creates demand lumpiness tied to infrastructure spending cycles.
- Automotive:Non-tire applications include control cables, seat reinforcement, and suspension components. Specification diversity fragments volumes across multiple sub-tier suppliers.
- Aerospace:Aramid and carbon fiber capture primary structural applications, leaving steel cord in legacy control cable and non-structural reinforcement roles. Qualification timelines exceed five years for new grade adoption.
Tire manufacturers command the volume base while construction end users expand most quickly through infrastructure stimulus programs.
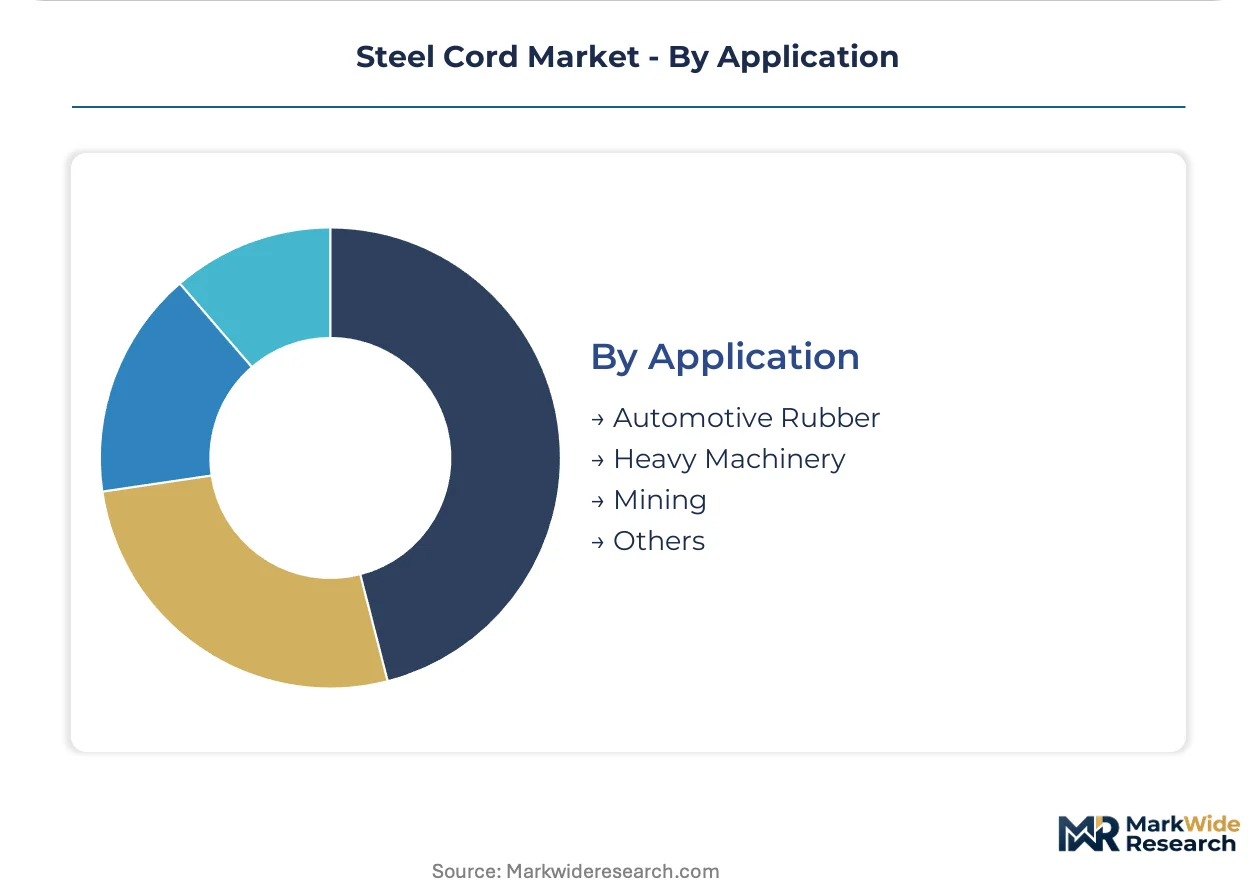
Application:
Application maturity determines margin stability, with established automotive rubber applications facing price compression against mining and heavy machinery segments with durable replacement economics.
- Automotive Rubber:Tire belt, carcass, and bead wire applications absorb the majority of super and extra super tensile production. REACH compliance requirements in European finishing lines accelerate chemistry transition costs.
- Heavy Machinery:Earthmover and agricultural tire reinforcement operates on extended product life cycles with less frequent grade upgrades. Replacement demand provides margin stability independent of OEM platform launches.
- Mining:Conveyor belt and dump truck tire applications prioritize cut resistance and impact absorption over weight reduction. Aramid penetration remains limited by capital equipment replacement inertia.
- Others:Elevator ropes, hose reinforcement, and air spring applications occupy niche specification territory with low volume concentration.
Automotive rubber anchors the volume base while heavy machinery applications gain share through mining capacity expansion in Australia and Chile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel cord trade flows reveal pronounced regional asymmetries. East Asian manufacturing clusters generate substantial export surpluses, while European and North American markets absorb merchant supply through direct mill-to-plant contracts rather than domestic production scaling.
China
Domestic tire OEMs upgrade fleet efficiency ratings, pulling super tensile grades into mainstream passenger platforms. SAMR enforces GB standards for dimensional tolerance and fatigue performance, extending approval cycles for new grade commercialization. Jiangsu and Shandong provinces concentrate cord conversion capacity serving just-in-time supply to tire plants in Qingdao and Shanghai.
Japan
Keiretsu supply structures face externalization pressure from group procurement centralization, reshaping merchant supplier access. METI oversees industrial standards coordination with automotive OEMs. Kansai and Chubu regions host precision drawing operations tied to flagship tire manufacturing in Osaka and Nagoya.
South Korea
Electric vehicle platform loads drive extra super tensile penetration in ultra-high-performance segments. MFDS and national standards bodies align tire safety regulations with export market requirements. Busan-Ulsan manufacturing corridor anchors cord supply integration with domestic tire export hubs.
Germany
REACH Annex XVII restrictions on cobalt-based adhesion promoters force rubber-steel bonding chemistry transitions across finishing lines. KBA and ECHA jointly influence tire plant compliance timelines. Industrial clusters in North Rhine-Westphalia and Baden-Württemberg concentrate OEM procurement desks and integrated cord operations.
United States
EPA and OSHA jointly influence plant emissions and workplace exposure limits at domestic manufacturing facilities. Retread markets and commercial vehicle segments sustain demand for high tensile grades. Southeast manufacturing belt expands tire capacity, creating localized cord supply requirements independent of import dependence.
Steel Cord Market Key Industry Players
Listed leaders compete with private specialists across metallurgical capability and geographic footprint. The vendor base consolidates around integrated wire-to-cord manufacturers, merchant converters dependent on external wire rod supply, and captive operations at multinational tire groups. Three archetypes dominate: upstream-controlled steelmakers, precision drawing specialists, and vertically integrated tire-cord operations. Competitive moves center on capacity expansion in India and Southeast Asia, plus metallurgical upgrades to extra super tensile specifications.
Among Belgian and Japanese precision fabricators, Bekaert and Sumitomo Electric Industries exemplify integrated wire-to-cord manufacturing archetypes. ArcelorMittal anchors upstream-controlled positioning through raw wire rod supply into conversion plants. These three represent divergent strategic foundations—geographic integration, captive metallurgy partnerships, and upstream resource control—shaping how each archetype responds to grade migration pressures and regional demand shifts.
| Leading Market Players |
|---|
| Bekaert |
| Sumitomo Electric Industries |
| ArcelorMittal |
| HYOSUNG Advanced Materials |
| Henan Hengxing Science & Technology |
| Bridgestone |
| Jiangsu Xingda Steel Cord |
| Tokusen Kogyo |
| Shougang Century |
| Others |
Cost & Logistics Intelligence
Thirty-to-forty-five day wire rod inventory cycles at Belgian and Japanese precision fabricators concentrate pricing power with integrated wire-to-cord manufacturers, while merchant converters face margin compression from scrap metal input volatility. The supply chain's geographic clustering around East Asian tire production hubs reinforces contract-based procurement dominance over spot market participation.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure across radial tire reinforcement supply. Three-tier pricing structure across super tensile, extra super tensile, and high tensile grades differentiates on fatigue certification tier and volume scale commitments. Cost compression in high tensile grades is intensifying because Chinese tire plants upgrade fleet efficiency specifications. Retread markets and agricultural equipment OEMs in India and Brazil exhibit highest price sensitivity, while electric vehicle platform engineers at South Korean tire manufacturers show lowest sensitivity for extra super tensile premiums.
Supply Chain Analysis
China, Japan, and South Korea anchor steel cord conversion capacity serving just-in-time supply to tire manufacturing clusters. Production draws from high-carbon wire rod feedstock, cobalt-based adhesion promoters transitioning to silane alternatives, and ultra-fine drawing dies for 0.15mm filament specifications. Single-source vulnerability concentrates in Belgian and Japanese precision drawing expertise pools facing aging workforce constraints. Distribution runs through direct mill-to-plant contracts with consolidated procurement desks at multinational tire groups, displacing fragmented regional buying.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform loads are disrupting grade boundaries, compressing the premium-mainstream divide that structured steel cord procurement for two decades. EU REACH Annex XVII restrictions on cobalt-based adhesion promoters accelerate chemistry transition investments across European finishing lines.
For Market Incumbents: Fortify captive metallurgy partnerships and precision drawing capabilities against merchant converter encroachment. Extend extra super tensile certification timelines to capture electric vehicle load compensation demand. Defend against aramid fiber substitution in conveyor belt segments through cut resistance performance benchmarking. For New Entrants and Emerging Players: China's SAMR GB standard fatigue certification fast-tracks offer entry pathways for qualified super tensile supply. Target India's domestic tire capacity expansion as the most penetrable geography, where localized cord supply lags behind OEM localization strategies. Pursue joint venture structures with established wire rod suppliers to bypass metallurgy partnership barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational tire groups externalizing captive cord operations under procurement centralization pressure. Long-term viability centers on extra super tensile capability and low-emission arc furnace feedstock positioning. Watch EU Green Deal carbon border adjustment implementation as the signal indicating preferential treatment timing for decarbonized supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Extra Super Tensile Capacity Expansion | South Korean tire manufacturers specify 0.15mm filaments for flagship electric vehicle platforms. |
| Backward Integration into Wire Rod Supply | ArcelorMittal's upstream control over European and Brazilian feedstock secures converter margin stability. |
| REACH-Compliant Bonding Chemistry Transition | Silane-based and plasma-treated alternatives replace cobalt promoters across Belgian and Spanish finishing lines. |
| India Tire Belt Localization Partnership | Domestic OEM export hub strategies create demand for regional cord supply independent of East Asian imports. |
| Smart Tire Sensor Integration R&D | Steel cord structures accommodating embedded pressure and wear monitoring enable next-generation tire platforms. |
Research Approach
The analysis maps radial tire, conveyor belt, and industrial hose reinforcement segments, each validated through procurement directors at tire manufacturers, technical R&D leads at cord converters, and plant managers at wire rod suppliers. Primary interview findings triangulate against customs and trade data, SEC filings from listed steelmakers, tire industry association production statistics, and GB standard certification records. Bottom-up volume modeling from grade-specific consumption patterns reconciles with top-down market sizing across the analysis window.
Consistency checks against external benchmarks validate volume and value outputs throughout the forecast period. The analytical framework models material grade tier, end-use application, regional production cluster, and tensile strength specification dimensions. CAGRs derive from segmented demand elasticity assessments calibrated to electric vehicle penetration curves and tire lightweighting compliance trajectories. Industry-specific inputs include OEM platform load requirements and SAMR approval cycle timelines.
Underlying assumptions cover electric vehicle weight distribution trends, REACH enforcement intensity, and arc furnace feedstock availability, with deviation risk concentrated in high-carbon steel price volatility and precision drawing talent scarcity. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory chemistry transition costs and regional carbon intensity rules. Recalibration cycles align with material shifts in GB standard certification timelines and EU Green Deal implementation phases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Lip Seals Market
Industrial Materials
Asia-Pacific Wood Based Panel Market
Industrial Materials
Polyurethane Insulation Board Market
Industrial Materials
Global Graphite Electrodes Market
Industrial Materials
Global Polycarbonate Sheets Market
Industrial Materials
Industrial Gaskets Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
Hose Reinforcement Wire Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Asia-Pacific Industrial Flooring Market
Industrial Materials
Extruders and Compounding Machines Market
Industrial Materials
Pultrusion Products Market
Industrial Materials
Couplings Market
Industrial Materials
Precipitated Silica Market
Industrial Materials
Modified Wood Market
Industrial Materials
Global Medical Plastics Extrusion Market