
 Europe Advanced Building Materials Market | 2026-2036
Europe Advanced Building Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Advanced Building Materials Market Insights
German engineered timber producers is shifting capacity toward cross-laminated mass panels for mid-rise construction. Saint-Gobain leverages integrated glass and insulation manufacturing to control raw material flows across Benelux plants. BASF SE anchors its position through polymer chemistry R&D for low-carbon concrete admixtures. Kingspan Group plc competes via insulated panel systems optimized for cold-chain and data center envelopes.
Europe advanced building materials encompass engineered substances with specified thermal conductivity below 0.035 W/m·K, compressive strength exceeding 20 MPa, or smart-responsive properties for structural monitoring, manufactured through controlled chemical synthesis, mineral fusion, or biogenic processing to reduce operational energy and embodied carbon in the built environment. Insulation products lead value generation as building envelope retrofits dominate renovation spending across Northern Europe. Smart materials and eco-friendly solutions are expanding fastest where EU Green Deal funding ties public procurement to lifecycle assessment thresholds. Composite materials command premium positioning in seismic and blast-resistant infrastructure applications.
The EU Green Deal, ECHA REACH restrictions on hazardous substances, and national transpositions of the Energy Performance of Buildings Directive constrain formulation choices while creating compliant product premiums. EMAS-registered manufacturers gain preferred supplier status on publicly tendered renovation contracts in Austria and Denmark. Stakeholders must track how the EU AI Act's risk classification affects building-integrated sensor networks and automated climate control systems.
Market Dynamics
The EU Green Deal's renovation wave mandate is compressing product development cycles across Europe's advanced building materials sector as manufacturers race to reformulate for embodied carbon compliance before public procurement deadlines.
Growth Catalysts
- Renovation Wave Mandate:The EU Green Deal compels member states to retrofit public buildings, creating guaranteed demand for aerogel insulation and low-carbon concrete across Northern Europe.
- German Residential Retrofit Programs:Public funding for social housing energy upgrades accelerates specification of cross-laminated timber and vacuum insulation panels in multi-family construction.
- Smart-Responsive Materials:Building-integrated sensor networks for structural health monitoring gain traction in seismic zones of Italy and Greece, opening new specification channels.
Market Restraints
- Silica Supply Concentration:Aerogel and advanced glass production depends on high-purity silica sources concentrated in Nordic mining regions, exposing manufacturers to input volatility.
- ECHA REACH Compliance Costs:Reformulation to eliminate restricted flame retardants and biocides extends R&D timelines by 18-24 months for insulation producers.
- Conventional Concrete Substitution:Lower first-cost engineered cementitious composites from Eastern European producers threaten premium positioning of geopolymer and bio-based alternatives.
Strategic Opportunities
- Île-de-France Net-Zero Social Housing:Public-private partnerships in France's capital corridor fund pilot projects for whole-building lifecycle carbon tracking, creating reference sites for EU-wide replication.
- Cold-Chain Infrastructure Expansion:Data center and pharmaceutical logistics construction in Benelux and Ireland drives demand for ultra-high-performance insulated envelope systems.
- AI Act Risk Classification Alignment:Early certification of building-integrated climate control algorithms as "limited-risk" AI systems opens preferential procurement pathways in Austria and Denmark.
Industry Challenges
- Building Physics Simulation Talent:Shortage of engineers trained in hygrothermal modeling and lifecycle assessment software delays product optimization for specific climate zones.
- EMAS Registration Timeline:Environmental management system certification required for public tender eligibility in Denmark and Austria demands 12-18 month implementation cycles.
- Legacy Masonry Integration:Retrofit contractors struggle to achieve thermal bridge-free connections between new high-performance panels and existing stone or brick substrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Advanced Building Materials Market |
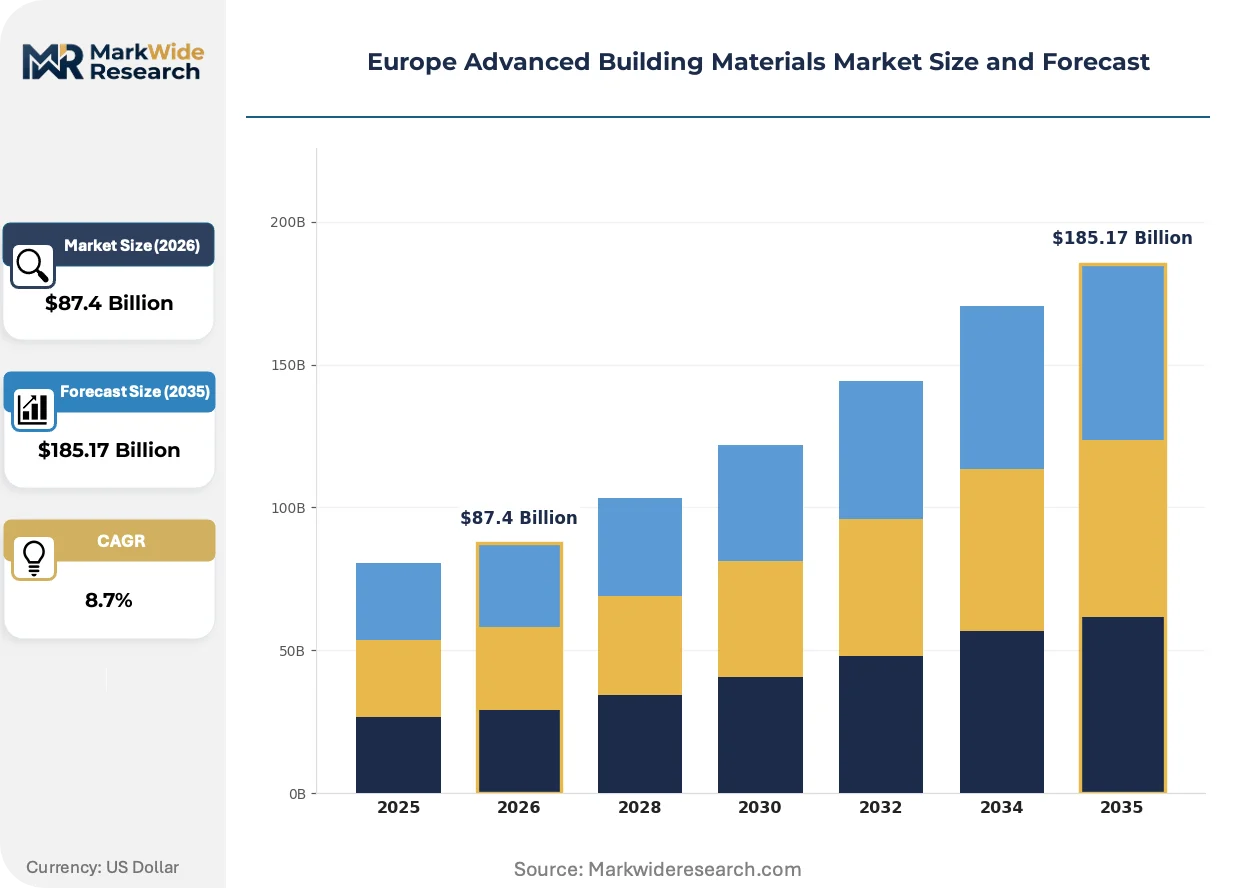
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulation, Concrete, Adhesives, Coatings Material: Glass, Wood, Steel, Composite Application: Residential, Commercial, Infrastructure, Industrial Technology: Smart Materials, Eco-friendly Solutions, Modular Building, Prefabrication |
| Companies Covered | Saint-Gobain, BASF SE, Kingspan Group plc, Knauf Insulation, ROCKWOOL International A/S, Sika AG, Holcim Ltd, Etex Group, Wienerberger AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Advanced Building Materials Market Trends and Innovations
Cross-laminated timber engineering is reshaping structural material selection across European mid-rise construction, while regulatory pressure on embodied carbon accelerates alternative binder chemistry and digital building passports transform how performance is verified and traded.
Mass timber hybrid systems combining cross-laminated panels with steel connectors are expanding into six-to-twelve story residential and office construction in Germany, Austria, and Switzerland. Developers in Munich and Vienna specify these systems to meet municipal timber-first zoning while maintaining seismic resilience. The technology is expanding into markets previously dominated by reinforced concrete, compressing structural material decision timelines from months to weeks.
The EU AI Act's risk-based classification framework is recalibrating investment in building automation. Manufacturers of climate-responsive facade systems must now document algorithmic transparency for "limited-risk" categorization to maintain eligibility for public procurement in Denmark and Austria. Smart glazing and automated shading producers in the Netherlands and Belgium are restructuring product architectures to isolate sensor networks from high-risk decision loops, with Benelux emerging as the testing ground for compliant building-integrated AI.
Digital building passports are displacing static energy certificates as the primary compliance document in French and German public tenders. These dynamic records track material provenance, embodied carbon, and performance degradation across a structure's lifecycle. Contractors in the Île-de-France corridor now bundle passport generation with envelope retrofit work, while insurers in Germany begin pricing coverage based on passport-verified maintenance histories. The shift is most visible in social housing procurement, where asset managers use passport data to optimize renovation sequencing across portfolios.
Europe Advanced Building Materials Market Segmentation
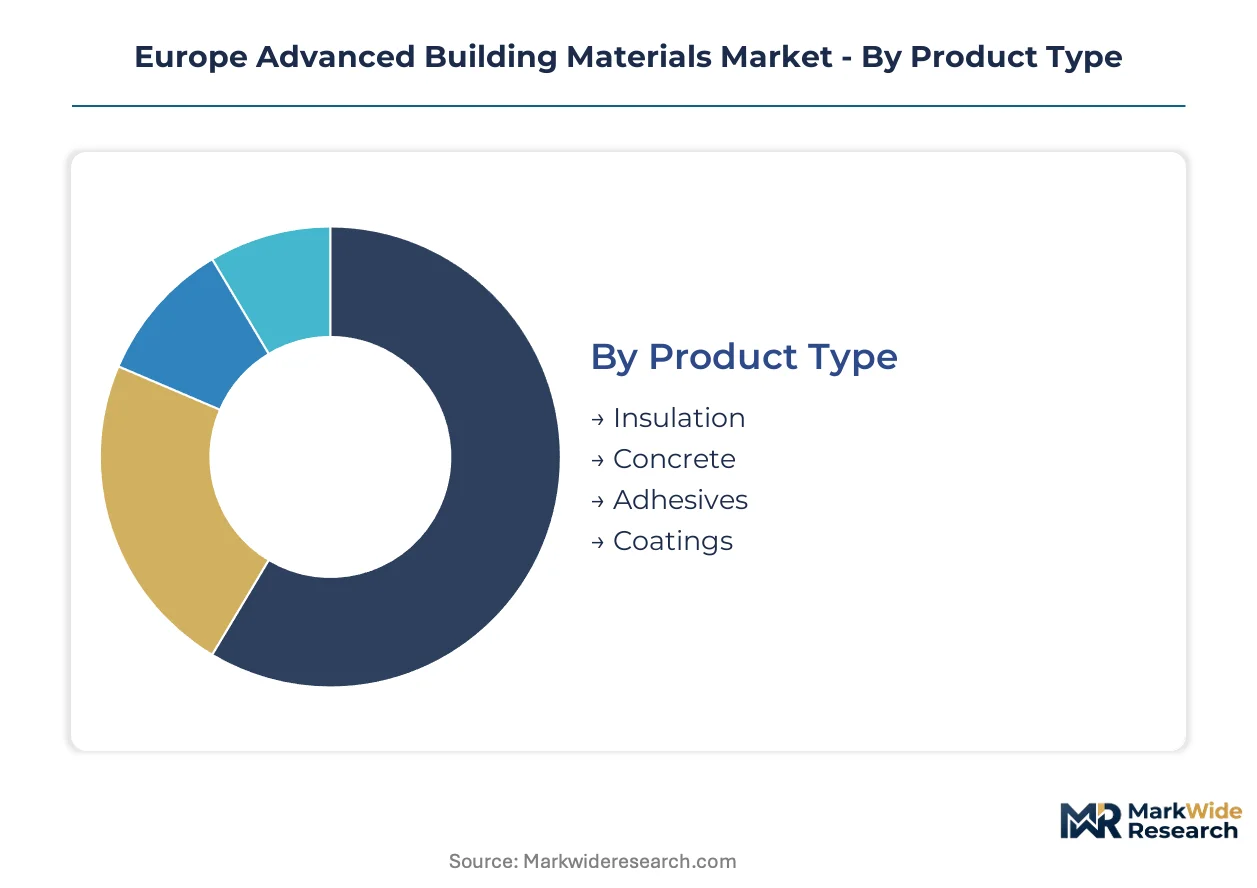
Segmentation in Europe's advanced building materials market reveals how regulatory pressure and performance specifications fragment procurement channels. Manufacturers must align certification portfolios with distinct segment requirements to capture public renovation contracts.
Product Type:
EMAS registration and CE marking requirements vary sharply across product categories, with insulation facing the most stringent thermal performance verification under the Energy Performance of Buildings Directive.
- Insulation:Aerogel panels, vacuum insulation, and advanced mineral wool achieve thermal conductivity below 0.035 W/m·K. German residential retrofit programs concentrate demand in multi-family social housing across Bavaria and North Rhine-Westphalia, where contractors bundle envelope upgrades with digital building passport generation.
- Concrete:Low-carbon and geopolymer formulations reduce embodied carbon through alternative binders. French public-private partnerships in the Île-de-France corridor specify these materials for net-zero social housing pilot projects requiring whole-lifecycle carbon tracking.
- Adhesives:ECHA REACH compliance drives reformulation away from restricted isocyanates and solvents.
- Coatings:Smart-responsive and phase-change materials integrate with building automation systems for dynamic thermal management.
Insulation sits at the top of the volume ranking, with concrete climbing the fastest as embodied carbon mandates tighten.
Material:
Raw material sourcing geography determines supply security and EMAS audit complexity for European manufacturers.
- Glass:Integrated manufacturing across Benelux plants controls silica flows for advanced glazing and insulation. Saint-Gobain's vertical integration from float glass to finished facade systems captures value through captive raw material supply.
- Wood:Cross-laminated timber and mass panels expand into six-to-twelve story construction in Germany, Austria, and Switzerland. Munich and Vienna municipal timber-first zoning compresses structural material selection timelines.
- Steel:High-strength alloys and corrosion-resistant grades serve seismic infrastructure in Italy and Greece.
- Composite:Fiber-reinforced polymers command premium positioning in blast-resistant and seismic applications.
Glass maintains volume leadership through building envelope retrofit dominance, while wood gains share fastest on mid-rise construction code changes.
Application:
Public procurement rules under the EU Green Deal renovation wave create divergent compliance pathways across end-use segments.
- Residential:Social housing energy upgrades across Northern Europe drive specification of integrated envelope systems. Danish and Austrian tender eligibility requires EMAS-registered suppliers with verified lifecycle assessment documentation.
- Commercial:Data center and pharmaceutical logistics construction in Benelux and Ireland demands ultra-high-performance insulated envelopes for cold-chain integrity.
- Infrastructure:Seismic and blast-resistant specifications in Southern Europe favor composite and engineered cementitious materials.
- Industrial:Process heat containment and cleanroom applications require specialized thermal performance guarantees.
Residential commands the largest project pipeline, with commercial expanding most quickly on logistics and digital infrastructure buildout.
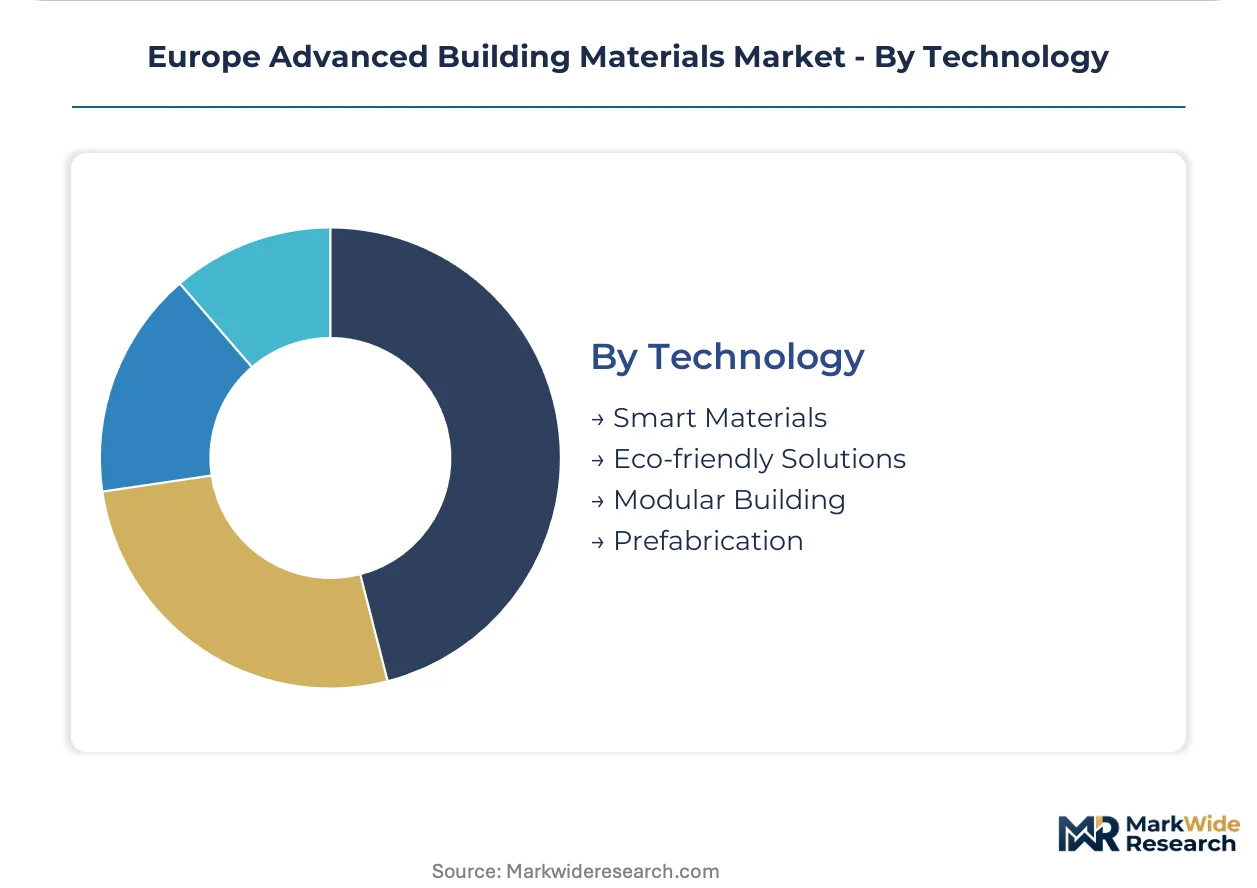
Technology:
The EU AI Act's risk classification framework splits technology segments into distinct regulatory treatment tiers.
- Smart Materials:Building-integrated sensor networks for structural health monitoring must document algorithmic transparency for "limited-risk" categorization. Netherlands and Belgium producers restructure product architectures to isolate sensor networks from high-risk decision loops.
- Eco-friendly Solutions:Bio-based binders and mineralized waste streams reduce embodied carbon for EU Green Deal compliance. Kingspan and BASF anchor positions through polymer chemistry R&D and panel system optimization.
- Modular Building:Factory-controlled quality reduces on-site waste and accelerates project delivery for constrained urban sites.
- Prefabrication:Off-site envelope assembly ensures thermal bridge-free connections that retrofit contractors struggle to achieve with legacy masonry substrates.
Eco-friendly solutions hold the broadest specification base, with smart materials gaining traction fastest where AI Act compliance opens preferential procurement pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate formulation activities to jurisdictions with streamlined EMAS registration pathways, compressing compliance cost differentials across Northern and Southern Europe.
Germany
Bavarian timber clusters and North Rhine-Westphalian insulation manufacturing anchor demand for cross-laminated panels and vacuum insulation systems. The national building energy code transposes EPBD requirements into municipal timber-first zoning ordinances. Munich contractors bundle envelope retrofits with digital building passport generation for social housing portfolios.
France
Net-zero social housing mandates in the Île-de-France corridor concentrate specification of geopolymer concrete and whole-lifecycle carbon tracking systems. The national low-carbon strategy enforces embodied carbon thresholds on publicly tendered renovation contracts. Public-private partnerships in Greater Paris fund pilot projects serving as reference sites for EU-wide replication.
Netherlands
Benelux data center construction and pharmaceutical logistics expansion drive demand for ultra-high-performance insulated envelope systems. The national building decree implements EU Green Deal renovation wave targets through accelerated permit pathways for passive house-certified materials. Eindhoven-region smart glazing producers restructure product architectures for EU AI Act limited-risk certification.
Austria
Viennese municipal timber-first zoning compresses structural material selection timelines for six-to-twelve story residential construction. EMAS registration requirements for public tender eligibility filter supplier pools toward environmental management system-certified manufacturers. Tyrolean mass panel engineering clusters supply cross-border projects into Southern Germany and Northern Italy.
Denmark
Social housing energy upgrade programs concentrate envelope retrofit spending in Copenhagen and Aarhus metropolitan corridors. The national building regulation mandates lifecycle assessment documentation for insulation products procured through public tenders. Danish contractors pioneer thermal bridge-free panel connections for legacy masonry substrate integration.
Europe Advanced Building Materials Market Competitive Landscape
German and French producers anchor one tier; Benelux specialists hold differentiated positions in smart-responsive facade systems. The vendor base stratifies across integrated material conglomerates, focused insulation engineers, and timber-technology specialists. Three archetypes dominate: silica-flow controllers, polymer chemistry innovators, and mass-panel fabricators. Capacity expansion and EMAS registration acceleration represent the dominant competitive moves as public procurement deadlines compress.
Among France-based material conglomerates, Saint-Gobain exemplifies vertical control from raw silica through finished facade systems. BASF SE anchors the polymer chemistry tier through captive R&D infrastructure for low-carbon admixture development. Kingspan Group plc occupies a position in the insulated panel specialist tier, with product architectures optimized for cold-chain and data center envelope applications.
| Leading Market Players |
|---|
| Saint-Gobain |
| BASF SE |
| Kingspan Group plc |
| Knauf Insulation |
| ROCKWOOL International A/S |
| Sika AG |
| Holcim Ltd |
| Etex Group |
| Wienerberger AG |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal embodied carbon thresholds gate both qualified supply and premium-tier pricing access, as manufacturers lacking EMAS registration or lifecycle assessment documentation face exclusion from public renovation tenders across Denmark and Austria while compliant producers capture margin premiums on certified low-carbon concrete and aerogel insulation systems.
Pricing Analysis
Distributor margins of 12-18 percent on insulation products compress as direct-to-contractor channels expand for large-scale social housing retrofits in Germany and France. Three-tier pricing structure across premium certified, standard CE-marked, and economy non-registered levels separates EMAS-registered suppliers from commodity competitors. Price differentiation hinges on digital building passport bundling and thermal conductivity performance grades. Cost compression in standard mineral wool is intensifying because Eastern European producers are flooding Benelux distribution networks with lower-first-cost alternatives.
Supply Chain Analysis
High-purity silica feedstock for aerogel and advanced glass production rests on Nordic mining operations in Norway, Sweden, and Finland, exposing manufacturers to input volatility when winter logistics constrain bulk transport. Alternative binder chemistry for geopolymer concrete draws from industrial waste streams and bio-based feedstocks sourced from Benelux chemical clusters and French agricultural processing. Single-source vulnerability concentrates in specialty flame retardants facing ECHA REACH phase-out timelines. Distribution runs through regional building merchant networks with direct-to-contractor bypass gaining share on large public projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal renovation wave mandates compound demand for compliant materials, with EPBD transposition deadlines in Germany and France creating predictable procurement windows through 2030.
For Market Incumbents: Hedge silica supply exposure through backward integration into Nordic mining partnerships or long-term offtake agreements with Norwegian producers. Accelerate EMAS registration for Austrian and Danish tender eligibility before 2026 procurement cycles lock supplier pools. Defend margin position against Eastern European cementitious substitutes by bundling digital building passport generation with envelope retrofit contracts.
For New Entrants and Emerging Players: Begin with AI Act limited-risk certification for building-integrated climate control algorithms, targeting Netherlands and Belgium smart glazing procurement where regulatory clarity precedes broader EU adoption. White-space exists in thermal bridge-free panel connection systems for legacy masonry retrofits across Danish social housing. Pursue public-private partnership pilot structures in France's Île-de-France corridor for reference site establishment.
For Investors and Strategic Acquirers: Roll-up economics work for regional insulation specialists with EMAS registration and digital passport capabilities because public tender eligibility is consolidating procurement toward pre-qualified supplier pools. Five-to-ten year viability favors manufacturers with captive low-carbon binder chemistry and cross-border mass timber engineering clusters. Watch ECHA REACH restriction expansion timelines as inflection indicators for reformulation R&D spending requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| EMAS Registration Acceleration | Unlocks public tender eligibility in Denmark and Austria where environmental management certification filters supplier pools. |
| Digital Building Passport Integration | Captures value-added bundling opportunities with French and German social housing asset managers optimizing renovation sequencing. |
| Alternative Binder Chemistry R&D | Secures positioning against ECHA REACH restrictions on traditional cement formulations while meeting embodied carbon thresholds. |
| Nordic Silica Supply Partnerships | Mitigates input volatility exposure for aerogel and advanced glass production through captive raw material arrangements. |
| AI Act Limited-Risk Certification | Opens preferential procurement pathways in Netherlands and Belgium for building-integrated sensor network and climate control systems. |
Research Methodology
Direct dialogue with plant managers at insulation manufacturing facilities, procurement leads at German and French social housing developers, EMAS certification auditors, and distribution channel partners in Benelux combined with secondary validation against EU Green Deal policy documents, ECHA REACH substance restriction databases, national building code transpositions, and customs trade data for silica and timber feedstock flows. Bottom-up and top-down triangulation cross-checked production capacity announcements with public tender award volumes.
Bottom-up modeling aggregated segment-level demand across insulation, concrete, adhesives, and coatings product types with material-grade, application, and technology dimensions over the projection horizon. Top-down validation referenced macro construction spending forecasts and EU Green Deal funding allocation trajectories. CAGRs derived from polynomial trend fitting to historical procurement volumes with regulatory milestone adjustments. Industry-specific inputs included EPBD transposition timelines and EMAS registration pipeline data.
Several conditions sit outside the modeled scope, including potential ECHA REACH expansion to additional flame retardant categories and unannounced revisions to EU AI Act risk classification thresholds for building automation systems. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
2D Materials Market
Advanced Materials
Cathode Materials Market
Advanced Materials
Global Next Generation Anode Materials Market
Advanced Materials
Silver Nanowires Market
Advanced Materials
Bioactive Glass Market
Advanced Materials
Global Electrochromic Materials Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
Wood Foam Market
Advanced Materials
Lab-Grown Rough Diamond Market
Advanced Materials
Transparent Wood Market
Advanced Materials
High-Purity Amorphous Boron Market
Advanced Materials
Global Advanced Composites Market
Advanced Materials
Global Synthetic Diamond Market
Advanced Materials
Cathode Active Material Market
Advanced Materials
Carbon Prepreg Market