
 Stainless Steel Cable Ties Market | 2026-2036
Stainless Steel Cable Ties Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel Cable Ties Market Analysis
Automation in cable bundling systems is narrowing the performance gap between manual and machine-installed stainless steel ties. Panduit Corporation leverages its North American manufacturing footprint to sustain rapid fulfillment for industrial contractors. HellermannTyton Group anchors its position through specialized coating technologies that extend salt-spray resistance in marine environments. Band-It Company dominates the heavy-duty segment with rolled-ball-lock designs engineered for extreme vibration settings.
Stainless steel cable ties are corrosion-resistant fastening devices manufactured from 304 or 316 grade austenitic steel, typically 0.25 mm to 0.40 mm in thickness, with self-locking ball-bearing or ladder-type mechanisms designed for permanent or releasable bundling in temperature ranges from -80°C to 538°C. Their primary purpose is securing cable bundles, hoses, and piping in environments where polymer ties degrade from UV exposure, chemical attack, or thermal stress. Heavy-duty ties command the largest revenue pool due to premium pricing in oil and gas and shipbuilding applications, while releasable variants represent the fastest-expanding category as maintenance-intensive industries prioritize serviceability over permanent fastening. Aerospace and electrical verticals concentrate demand for small and medium sizes with MIL-SPEC or UL certifications, whereas construction contractors drive volume in large and extra-large formats for structural cable management.
The US Occupational Safety and Health Administration mandates flame-resistant cable containment in underground mining and tunneling operations, directly specifying metallic ties in certain MSHA-equivalent environments. China's State Administration for Market Regulation enforces GB/T standards for tensile strength and chemical composition that determine market access for imported stainless steel fastening products. The European Union's RoHS and REACH frameworks restrict hazardous substance content in coated or plated variants, pushing manufacturers toward passivated bare steel finishes. Stakeholders must monitor evolving national building codes and energy infrastructure standards that increasingly specify metallic cable management for fire safety and longevity in critical installations.
Market Dynamics
Offshore oil and gas operators are consolidating procurement around corrosion-resistant fastening systems as subsea infrastructure ages and replacement cycles compress, while China's GB standards tighten material certification requirements that reshape import eligibility.
Growth Catalysts
- OSHA flame-resistant mandates:US underground mining and tunneling operations now specify metallic cable containment, directly expanding addressable demand for stainless steel ties in MSHA-equivalent environments.
- Subsea infrastructure renewal:Gulf Coast petrochemical corridors across Texas and Louisiana are replacing polymer fasteners with 316-grade stainless systems to withstand salt-spray and thermal cycling.
- Automation in bundling systems:Machine-installation compatibility is narrowing performance gaps with manual ties, enabling high-throughput deployment in shipyard and aerospace manufacturing lines.
Market Restraints
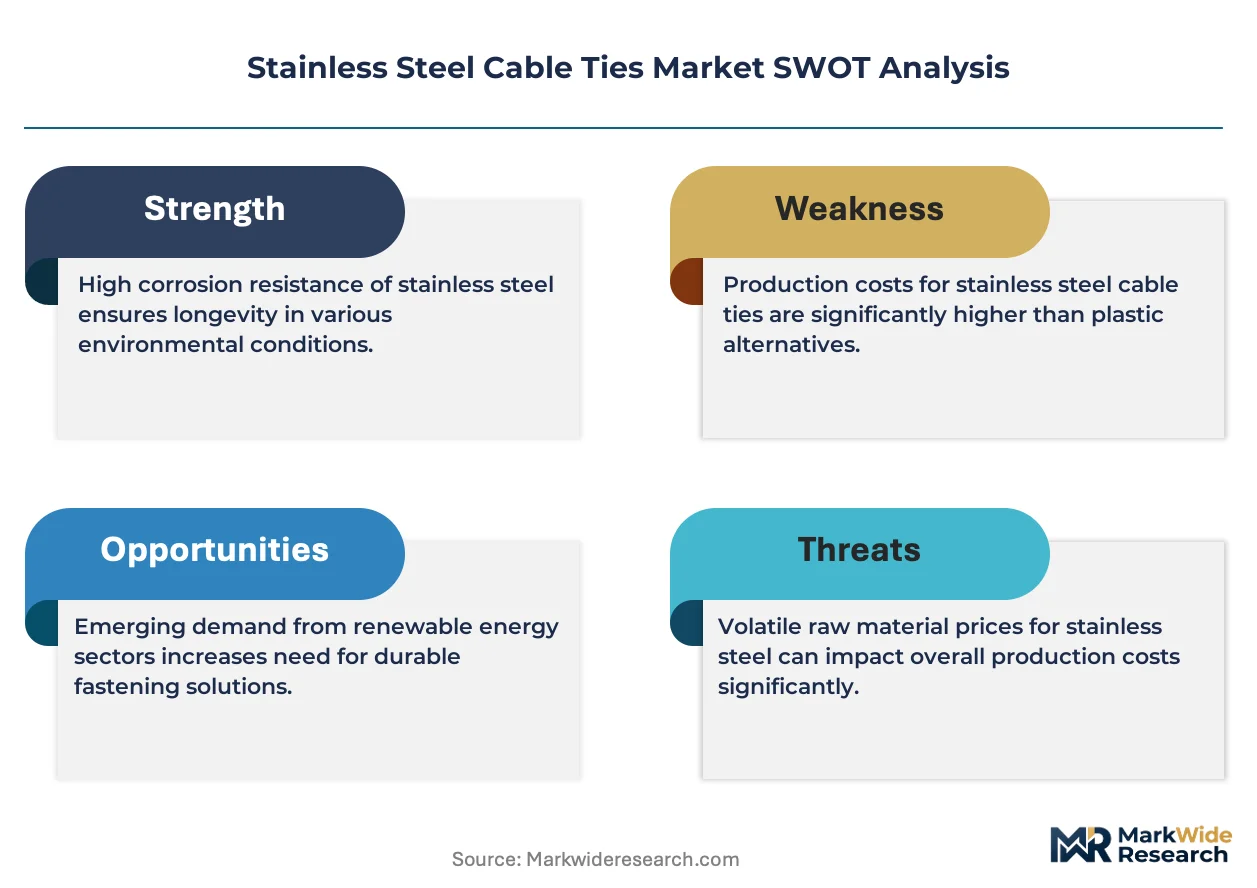
- Nickel price volatility:304 and 316 grade austenitic steel contains 8-14% nickel, exposing manufacturers to London Metal Exchange fluctuations that compress margin predictability.
- Polymer substitution in benign environments:Nylon 12 and PEEK cable ties retain cost advantage in indoor electrical and datacenter applications where UV and chemical exposure remain minimal.
- REACH compliance friction:EU restrictions on hazardous substance content in coated variants force reformulation toward passivated bare steel finishes that sacrifice certain aesthetic and fingerprint-resistant properties.
Strategic Opportunities
- Releasable variant expansion:Maintenance-intensive industries in Germany and Japan are prioritizing serviceable ladder-type mechanisms over permanent ball-lock designs, opening premium pricing tiers.
- Dual carbon alignment in China:SAMR enforcement of extended producer responsibility frameworks creates procurement preference for domestically certified metallic fastening products with traceable recycled content.
- Aerospace certification convergence:MIL-SPEC and UL certification bundling is reducing supplier qualification overhead for tier-2 contractors serving electrical and avionics verticals.
Industry Challenges
- Welding metallurgy expertise scarcity:Rolled-ball-lock production requires precision laser welding of 0.25-0.40 mm strip stock, constraining capacity expansion to facilities with qualified technicians.
- Multi-jurisdiction certification lag:Simultaneous pursuit of GB/T, ASTM, and EN standards extends product launch timelines by 14-22 months for entrants targeting cross-border infrastructure projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel Cable Ties Market |
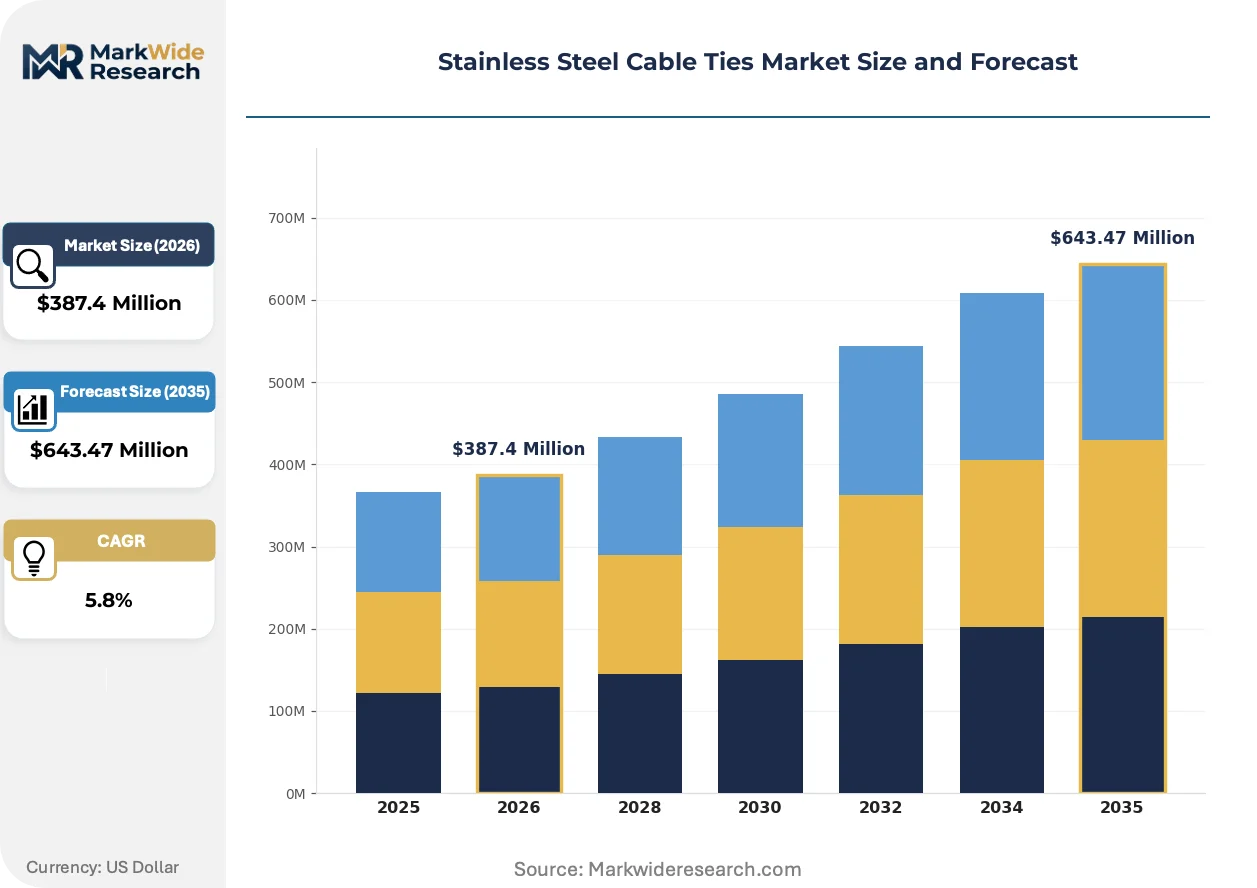
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $643.47 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Ties, Heavy-Duty Ties, Releasable Ties, Infinitely Adjustable Ties Industry Vertical: Aerospace, Automotive, Construction, Electrical End User: Manufacturers, Distributors, Retailers, Contractors Size: Small, Medium, Large, Extra Large |
| Companies Covered | 3M Company, Partex Marking Systems, Panduit Corporation, TE Connectivity Ltd., Advanced Cable Ties, Inc., HellermannTyton Group, Band-It Company, Amphenol Corporation, ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel Cable Ties Market Emerging Trajectories
Material science advances and regulatory harmonization are compressing traditional product lifecycles while reshaping buyer qualification criteria across heavy industrial verticals.
Laser-welded micro-joints are collapsing the durability gap between stamped and machined ball-bearing mechanisms. Offshore platform contractors in Norway and Brazil are specifying these ties for riser and umbilical management where vibration fatigue previously mandated over-engineered solutions. The technology is collapsing procurement trade-offs between unit cost and field-replacement frequency.
REACH and RoHS framework convergence in the European Union is restricting cadmium and hexavalent chromium content in plated finishes. Manufacturers serving marine and chemical processing end-uses are migrating toward electropolished 316L surfaces that eliminate coating dependency. German shipyards and Dutch offshore fabricators are now requiring bare-passivated certification for subsea cable tray installations.
Buyers in petrochemical and power generation verticals are consolidating supplier relationships around vertically integrated producers with in-house melting and cold-rolling capacity. Distributor networks in the US Gulf Coast and Rotterdam port complexes are losing share to direct mill relationships as procurement teams centralize technical qualification. This concentration is most visible in Texas and Louisiana, where EPC contractors now specify approved manufacturer lists with single-source provisions for critical path installations.
Stainless Steel Cable Ties Market Segmentation
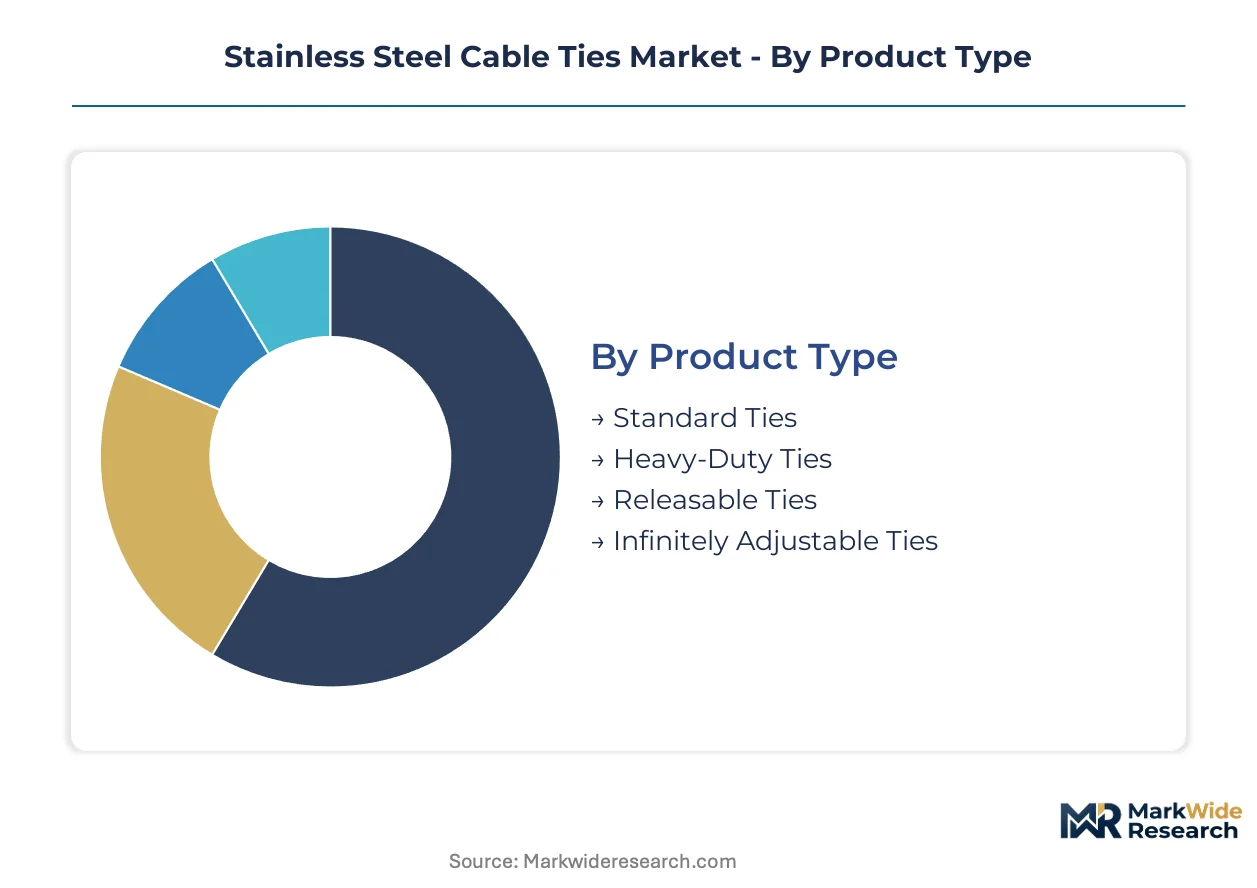
Stainless steel cable tie procurement patterns diverge sharply across product grades and end-use contexts, with service requirements and replacement cycles dicting margin structures more than raw material costs. Understanding these fault lines enables suppliers to align inventory and technical support resources with actual demand concentration.
Product Type:
After-sales service intensity varies dramatically across product categories, with heavy-duty installations requiring field engineering support for tension calibration and corrosion monitoring while standard ties move through transactional distribution channels.
- Heavy-Duty Ties:These 0.35-0.40 mm thickness variants with rolled-ball-lock mechanisms withstand tensile loads exceeding 500 pounds in subsea riser and vibration-heavy petrochemical environments. Gulf Coast EPC contractors in Texas and Louisiana specify these for critical path infrastructure where failure triggers shutdown costs. Demand concentrates in offshore oil and gas as subsea asset replacement cycles compress.
- Releasable Ties:Ladder-type mechanisms with serviceable locking points enable repeated access for maintenance-intensive electrical and avionics applications. Japanese automotive manufacturers and German industrial automation firms are prioritizing these over permanent ball-lock designs to reduce lifetime service costs.
- Standard Ties:0.25 mm thickness 304-grade variants serve general construction and indoor electrical bundling where chemical exposure remains minimal.
- Infinitely Adjustable Ties:Continuous-loop designs accommodate irregular bundle diameters in shipbuilding and heavy machinery applications.
Heavy-Duty Ties holds the largest share; momentum sits with Releasable Ties.
Industry Vertical:
Application environments determine specification rigor, with certification requirements and thermal cycling exposure creating distinct procurement workflows across verticals.
- Aerospace:MIL-SPEC certified small and medium ties with traceable 316L chemistry and laser-welded micro-joints serve avionics harness management in commercial and defense aircraft. FAA-equivalent documentation requirements extend qualification timelines but lock in multi-year supplier relationships.
- Electrical:UL-listed ties dominate datacenter and utility scale solar installations where fire resistance and UV stability exceed polymer capabilities. Chinese GB standards and European CE marking create dual-certification burdens for cross-border projects.
- Automotive:Under-hood thermal management drives demand for 316-grade ties in electric vehicle battery pack routing.
- Construction:Large-format ties secure structural cable trays and temporary scaffolding in infrastructure megaprojects.
Aerospace commands premium pricing tiers; Electrical generates the highest unit volumes.
End User:
Channel configuration shapes technical support delivery, with direct mill relationships displacing distributor networks in specification-heavy procurement contexts.
- Contractors:Field installation crews require rapid fulfillment and on-site tensioning tools for oil and gas and shipyard projects. Direct manufacturer relationships in Rotterdam and Houston port complexes are consolidating procurement around approved vendor lists with single-source provisions.
- Manufacturers:OEM integration demands lot traceability and statistical process control documentation for aerospace and automotive tier-1 supply chains.
- Distributors:Stock-and-sell models face margin compression as procurement teams centralize technical qualification.
- Retailers:Hardware and industrial supply chains serve maintenance-repair-operations demand with standard-grade inventory.
Contractors drive specification authority; Manufacturers anchor long-term contract value.
Size:
Dimensional requirements correlate with bundle diameter and load-bearing needs, creating distinct manufacturing setup constraints across the range.
- Small:4-8 inch lengths with 50-120 pound tensile ratings serve avionics and precision instrumentation harnessing. Aerospace and electrical verticals concentrate demand for these formats with MIL-SPEC or UL certifications.
- Large:14-30 inch lengths secure structural cable management in construction and offshore platform applications. Texas and Louisiana petrochemical corridors specify these for process piping and cable tray installations.
- Medium:8-14 inch general-purpose formats bridge industrial and commercial applications.
- Extra Large:30+ inch specialty ties accommodate submarine umbilical and wind turbine tower routing.
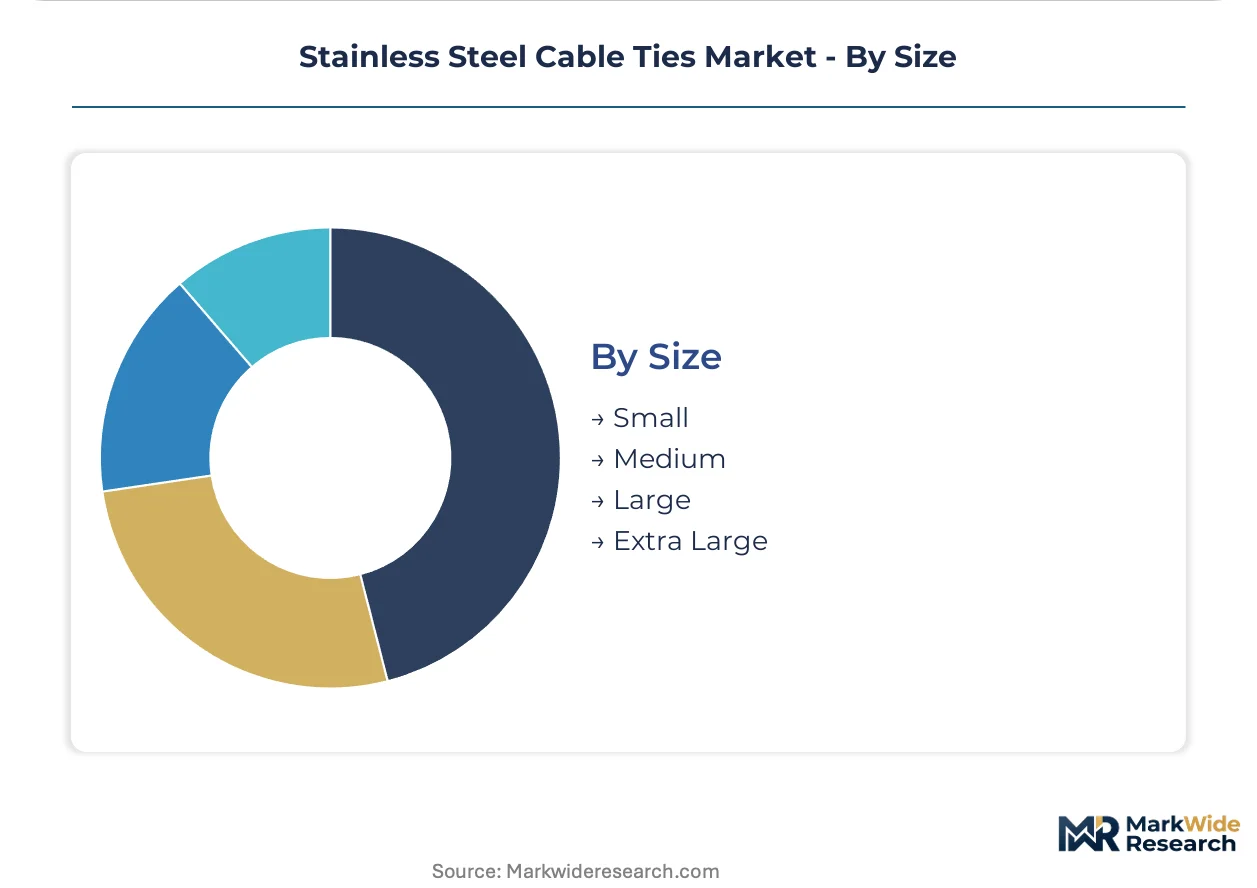
Large holds the dominant revenue position; Small exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial contractors and EPC firms dominate procurement across major stainless steel cable tie markets, with specification authority concentrating in port-adjacent petrochemical clusters and aerospace manufacturing corridors.
United States
OSHA mandates flame-resistant cable containment in underground mining and tunneling operations, directly expanding metallic tie deployment in MSHA-equivalent environments. The US Occupational Safety and Health Administration enforces strict material specifications for subterranean electrical infrastructure. Gulf Coast petrochemical corridors across Texas and Louisiana specify 316-grade stainless systems for salt-spray resistance in offshore platform and refinery applications.
China
State Administration for Market Regulation enforcement of GB/T standards for tensile strength and chemical composition reshapes import eligibility for foreign fastening products. SAMR's extended producer responsibility frameworks create procurement preference for domestically certified products with traceable recycled content. Yangtze River Delta shipyards and Pearl River Delta electrical manufacturers are consolidating supplier relationships around vertically integrated domestic producers with in-house melting capacity.
Germany
REACH and RoHS framework convergence restricts cadmium and hexavalent chromium content in plated finishes, pushing manufacturers toward electropolished 316L surfaces. The European Chemicals Agency enforces hazardous substance limits that eliminate coating-dependent variants from marine and chemical processing applications. Hamburg shipyards and Ruhr industrial automation clusters now require bare-passivated certification for subsea cable tray and automotive harness installations.
Japan
Automotive manufacturers prioritize releasable ladder-type mechanisms over permanent ball-lock designs to reduce lifetime service costs in maintenance-intensive electrical systems. The Ministry of Economy, Trade and Industry oversees JIS standards alignment with international aerospace certification requirements. Kansai industrial automation firms and Nagoya automotive tier-1 suppliers are driving fastest-category expansion for serviceable fastening formats.
Norway
Offshore platform contractors specify laser-welded micro-joints for riser and umbilical management where vibration fatigue previously mandated over-engineered solutions. The Norwegian Maritime Authority enforces stringent material traceability for subsea infrastructure in North Sea oil and gas fields. Stavanger and Bergen port complexes anchor procurement consolidation as EPC contractors centralize technical qualification around direct mill relationships.
Stainless Steel Cable Ties Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered qualification environments. The vendor base organizes around vertically integrated manufacturers with captive steel melting and cold-rolling capacity, mid-scale fabricators with precision welding expertise, and distribution-focused entities serving transactional maintenance-repair-operations demand. Three archetypes dominate: premium-tier specialists with aerospace certifications, heavy-duty producers serving oil and gas verticals, and volume-oriented standard-grade suppliers. Competitive moves concentrate on backward integration into raw material supply and geographic expansion through port-adjacent distribution hubs.
Among North American channel controllers, Panduit Corporation and Band-It Company exemplify contrasting strategic positions. Panduit leverages its manufacturing footprint to sustain rapid fulfillment for industrial contractors. Band-It occupies a position within the heavy-duty segment through rolled-ball-lock designs. HellermannTyton Group anchors the specialist tier with coating technologies addressing marine environment durability.
| Leading Market Players |
|---|
| 3M Company |
| Partex Marking Systems |
| Panduit Corporation |
| TE Connectivity Ltd. |
| Advanced Cable Ties, Inc. |
| HellermannTyton Group |
| Band-It Company |
| Amphenol Corporation |
| ABB Ltd. |
| Others |
Supply Flow & Price Mechanics
Nickel price volatility on the London Metal Exchange compresses margin predictability across all three pricing tiers while simultaneously forcing buyers toward long-term offtake contracts with Chinese and South Korean mill suppliers. This commodity exposure dictates both the spread between heavy-duty premium products and standard-grade economy tiers and the geographic concentration of cold-rolling capacity.
Pricing Analysis
Cost-plus contracts with London Metal Exchange nickel indexation dominate procurement between Gulf Coast EPC contractors and 316-grade suppliers, creating automatic pass-through for input fluctuations. Price differentiation rests on MIL-SPEC certification grade and bundled field engineering support, with aerospace and subsea oil and gas buyers exhibiting lowest sensitivity due to failure-cost exposure. Cost compression in standard-grade 304 products intensifies because nylon 12 substitutes retain cost advantage in benign indoor environments.
Supply Chain Analysis
Contract manufacturing concentration sits with precision laser welding specialists in Germany, Japan, and South Korea who control rolled-ball-lock production for heavy-duty variants. Raw material feeds from Chinese and Indonesian nickel pig iron smelters, Finnish cold-rolling mills, and Indian 304-grade strip producers create multi-node dependency. Single-source vulnerability concentrates in 0.25-0.40 mm precision strip supply qualified for aerospace traceability. Distribution runs through direct mill relationships displacing Rotterdam and Houston port-adjacent distributor networks in specification-heavy procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified laser welding technicians for micro-joint production represent the binding constraint on capacity expansion, with fewer than twelve facilities globally capable of aerospace-grade ball-lock fabrication. This capability scarcity rewards early certification investment and captive skill development.
For Market Incumbents: Harden supply security through backward integration into precision cold-rolling capacity or long-term offtake with Finnish and Japanese strip mills. Invest in dual GB/T and MIL-SPEC certification bundling to reduce supplier qualification overhead for tier-2 contractors. Defend against polymer substitution in datacenter verticals by emphasizing flame-resistant metallic containment for OSHA-mandated environments. For New Entrants and Emerging Players: Pursue releasable ladder-type mechanism production for maintenance-intensive German industrial automation and Japanese automotive tier-1 supply chains, where serviceability premiums exceed permanent ball-lock pricing. Target Chinese domestic certification with traceable recycled content alignment under SAMR extended producer responsibility frameworks. Enter through specialized coating-free electropolished 316L surfaces for REACH-compliant European marine applications. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated producers with captive melting and in-house welding expertise over distribution-dependent fabricators. Long-term viability hinges on aerospace certification moats and port-adjacent logistics positioning. Monitor nickel price volatility amplitude and Chinese GB standard enforcement intensity as inflection indicators for margin compression versus expansion cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Strip Production | Captive supply of 0.25-0.40 mm 316L strip eliminates single-source dependency on Finnish and Japanese mills. |
| Dual Certification Bundling (MIL-SPEC/GB/T) | Combined qualification reduces 14-22 month product launch timelines for cross-border infrastructure projects. |
| Laser Welding Micro-Joint Capacity Expansion | Enables entry into Norwegian and Brazilian offshore riser specifications previously closed to stamped mechanism suppliers. |
| Electropolished Bare Steel Finish Migration | Eliminates REACH compliance friction from cadmium and hexavalent chromium restrictions in German shipyard procurement. |
| Direct Mill Relationship Consolidation | Displaces Rotterdam and Houston distributor networks in Texas and Louisiana petrochemical corridor procurement. |
Methodological Framework
The analysis maps heavy-duty, releasable, standard, and infinitely adjustable product categories, each validated through procurement directors at Gulf Coast EPC contractors, aerospace tier-1 supply chain managers, German shipyard technical specifications officers, and Japanese automotive harness engineers. Primary fieldwork combined with secondary validation from customs trade data, OSHA enforcement records, SAMR certification databases, and SEC filings of publicly listed fastening manufacturers. Bottom-up unit economics triangulate against top-down industry spend estimates.
Assumptions held fixed include continued REACH and RoHS framework convergence restricting plated finishes, sustained OSHA flame-resistant mandates in underground operations, and persistent nickel price volatility. The analytical framework segments by product thickness grade, end-use vertical certification requirements, mechanism type, and regional regulatory cluster. CAGRs derive from installed base replacement cycle compression in subsea infrastructure and machine-installation adoption curves in shipyard automation.
Macroeconomic conditions sit as an overlay; deviation in London Metal Exchange nickel pricing bandwidth, Chinese dual carbon policy enforcement intensity, or Gulf Coast petrochemical capital expenditure cycles would shift the trajectory. Quarterly review of SAMR certification approval velocity, OSHA citation patterns for non-metallic containment, and North Sea offshore platform maintenance scheduling is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
Solid Surface Materials Market
Industrial Materials
Global Cast Acrylic Sheet Market
Industrial Materials
2-in-1 Material Rack Correction Machine Market
Industrial Materials
Industrial Films Market
Industrial Materials
Static Mixer Market
Industrial Materials
Global Polycarbonate Sheets Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Global Glass Wool Board Sales Market
Industrial Materials
Polymer Bearing Market
Industrial Materials
Welding Consumables Market
Industrial Materials
Extruders and Compounding Machines Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Middle-East and Africa Engineering Plastics Market