
 Expanded PTFE (Eptfe) Market | 2026-2036
Expanded PTFE (Eptfe) Market Size, Share, and Industry Trends Forecast 2026-2036
Expanded PTFE (Eptfe) Market Analysis
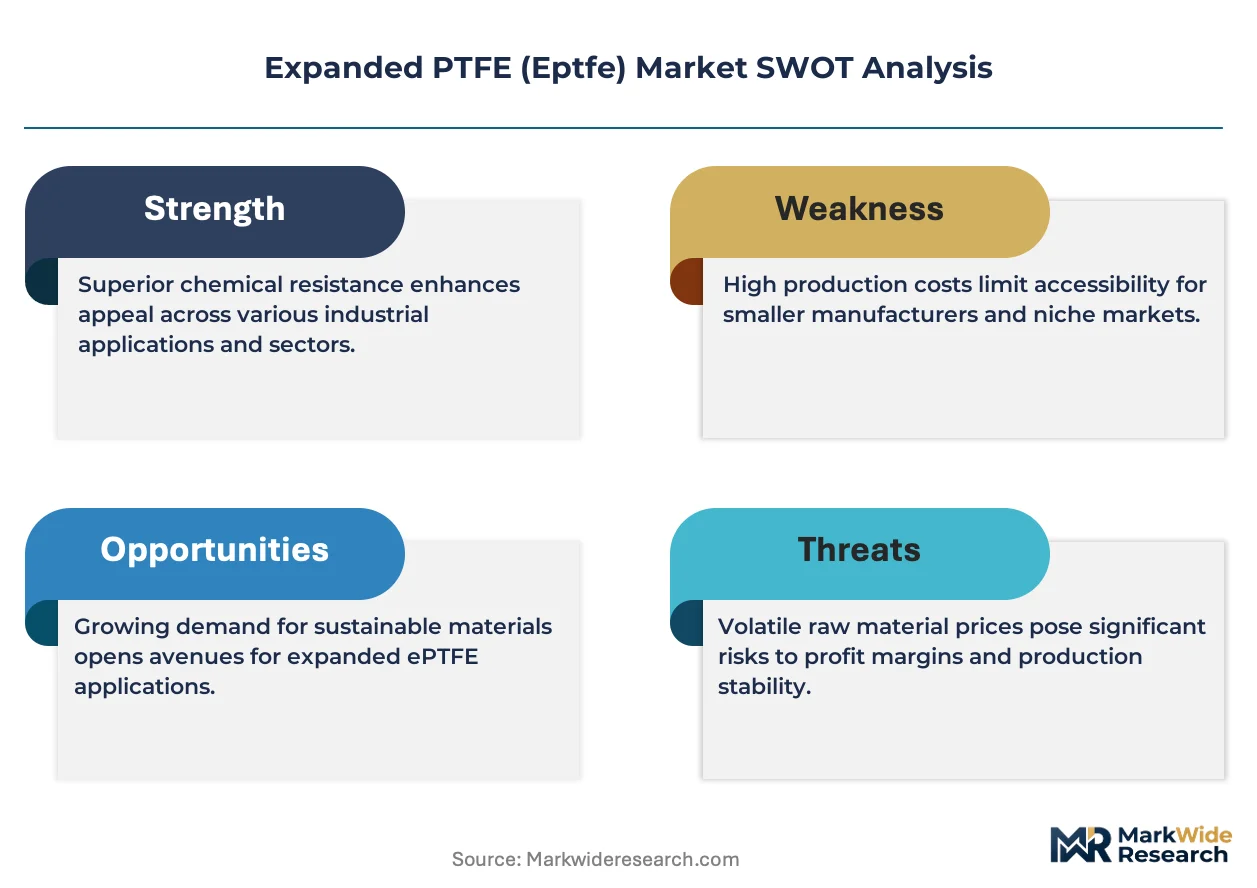
Medical device buyers are redrawing procurement priorities toward implant-grade ePTFE membranes, pulling volume away from traditional industrial sealant purchasers. W.L. Gore & Associates, Inc. leverages its vascular graft heritage to dominate high-margin medical segments. Donaldson Company, Inc. anchors its position through filtration systems for heavy-duty engines. Compagnie de Saint-Gobain S.A. competes across architectural membrane and industrial gasketing with integrated fluoropolymer capabilities.
Expanded PTFE consists of a microporous structure created through mechanical expansion of sintered polytetrafluoroethylene, yielding pore sizes from 0.1 to 15 microns and porosity exceeding 70 percent while retaining chemical inertness across a 260°C service range. Sheet and film formats command the largest revenue share in sealing solutions for chemical processing infrastructure, where corrosion resistance justifies material premiums. Tubing applications in medical filtration represent the fastest-expanding margin pool, as OEMs specify validated cleanroom extrusion protocols. Gasketing demand in electrical insulation remains mature, with pricing disciplined by long-term supply agreements to transformer manufacturers.
FDA 21 CFR 177.1550 governs food-contact ePTFE in the United States, while the EU MDR imposes clinical evidence requirements on implantable grades, compressing market access timelines for uncertified suppliers. China's NMPA and Japan's PMDA maintain divergent biocompatibility testing protocols, fragmenting registration strategies for multinational suppliers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions in Europe and North America, as precursor chemistry scrutiny threatens feedstock availability across all product tiers.
Market Dynamics
Medical-grade ePTFE procurement is displacing industrial sealing volumes as implantable device manufacturers consolidate supplier relationships around validated cleanroom extrusion capabilities. This demand rotation is compressing margin pools for legacy gasket producers while elevating membrane specialists with vascular graft heritage.
Growth Catalysts
- EU MDR implantable mandates:Clinical evidence requirements for cardiovascular grafts are locking in certified suppliers and extending contract durations for compliant membrane producers.
- German chemical processing clusters:Corrosion-resistant infrastructure investments in Ludwigshafen and Leverkusen are sustaining premium membrane consumption for reactor sealing.
- Cleanroom extrusion protocols:Validated tubing production for dialysis filtration is expanding addressable margin pools as OEMs specify particle-controlled supply chains.
Market Restraints
- Fluoropolymer feedstock concentration:Precursor PTFE resin production concentrates among three global chemical conglomerates, exposing membrane converters to allocation risk during supply shocks.
- REACH per- and polyfluoroalkyl substance scrutiny:ECHA regulatory pressure on fluorinated chemistry is threatening feedstock availability across medical and industrial product tiers.
- Silicone substitution in soft-tissue repair:Elastomeric alternatives are capturing select hernia mesh applications where compliance costs outweigh performance premiums.
Strategic Opportunities
- India's CDSCO fast-track pathway:Streamlined biocompatibility recognition for US FDA-cleared devices is opening vascular graft opportunities in Mumbai and Hyderabad hospital procurement networks.
- Architectural tensile membrane convergence:Integration with photovoltaic laminates is creating new specification channels for weather-resistant ePTFE composites in stadium and airport construction.
- Japan METI carbon-neutral material mandates:Low-emission fluoropolymer processing incentives are favoring suppliers with closed-loop manufacturing investments.
Industry Challenges
- Cleanroom operator scarcity:Validated extrusion technicians with ISO 14644-1 Class 7 experience command wage premiums that compress converter margins.
- Dual regulatory filing complexity:Parallel FDA 510(k) and EU MDR technical documentation requirements extend product launch timelines by eighteen to twenty-four months.
- Legacy equipment retrofit costs:Particle monitoring and laser micrometer integration for medical-grade tubing lines demands capital commitments exceeding smaller converters' balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expanded PTFE (Eptfe) Market |
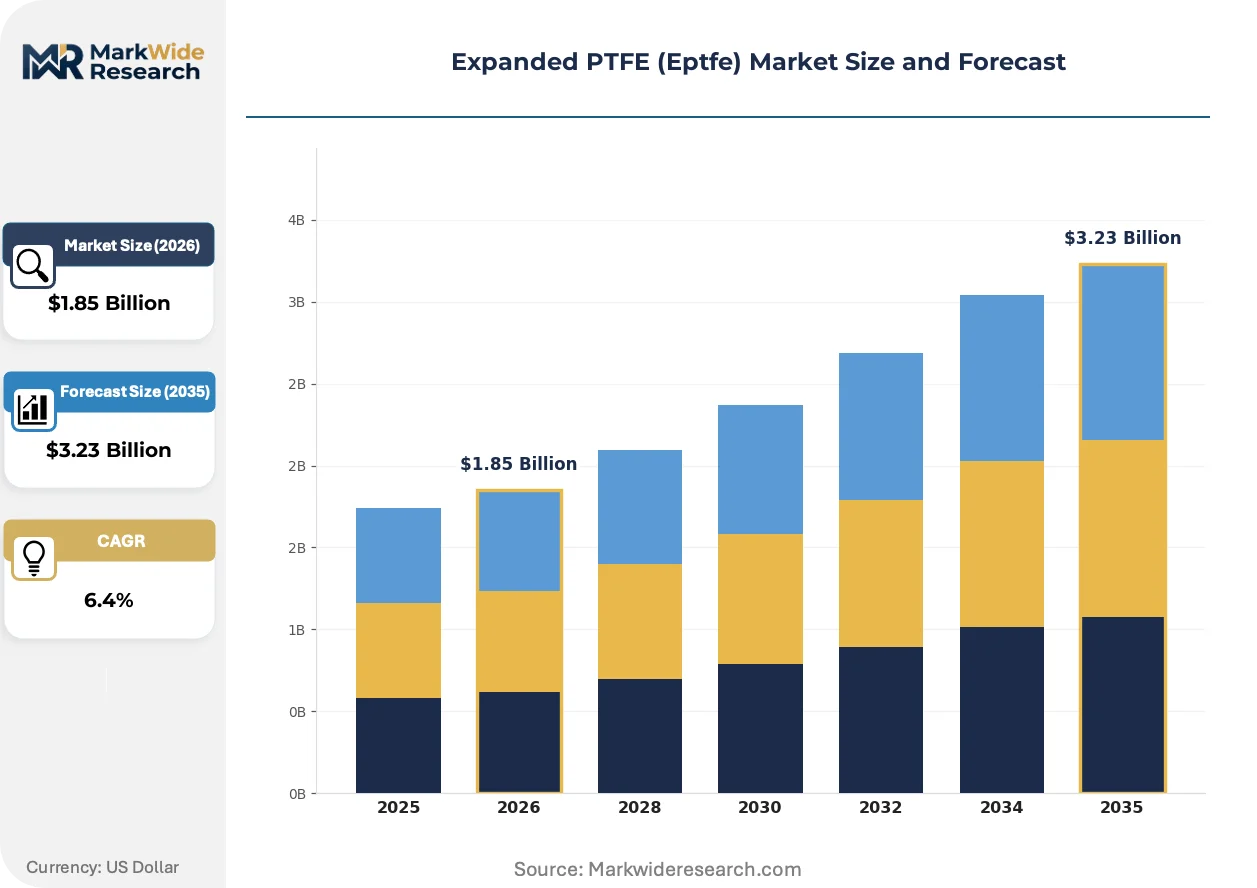
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Film, Gasketing, Tubing End User: Aerospace, Automotive, Chemical Processing, Electrical Application: Sealing Solutions, Insulation, Filtration, Coating Form: Flexible, Rigid, Molded, Laminated |
| Companies Covered | W.L. Gore & Associates, Inc., Donaldson Company, Inc., Compagnie de Saint-Gobain S.A., Nitto Denko Corporation, Rogers Corporation, Markel Corporation, Zeus Industrial Products, Inc., Lenzing Plastics GmbH & Co. KG, Teadit Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expanded PTFE (Eptfe) Market Emerging Trajectories
Layered manufacturing approaches are fragmenting traditional ePTFE specifications as end-users demand property gradients unachievable through single-step expansion. This evolution is redrawing competitive boundaries between membrane converters and integrated materials platforms.
Multilayer co-extrusion is decomposing monolithic membrane architectures by bonding expanded PTFE substrates with thermoplastic polyurethane or fluorinated ethylene propylene skins. Cardiovascular device manufacturers in Massachusetts and Minnesota are specifying these composites for vascular access grafts requiring thromboresistant luminal surfaces. The technology is decomposing historical price premiums attached to homogeneous ePTFE sheets by enabling tiered performance pricing.
REACH restriction proposals on per- and polyfluoroalkyl substances are accelerating substitution assessments across European medical device supply chains. ECHA regulatory development is forcing membrane converters to document precursor chemistry chain-of-custody back to polymerization. Implantable grade suppliers with existing fluoropolymer backward integration are capturing specification share as registration timelines compress for qualified sources.
Hospital procurement consolidation is compressing supplier panels as integrated delivery networks in Texas and California mandate single-source vascular graft contracts with ten-year total-cost guarantees. Group purchasing organizations are displacing individual hospital material committees as the primary decision node for implantable membranes. This concentration is most visible in US academic medical center networks where procurement standardization across fifteen to twenty facilities has eliminated second-source specifications.
Expanded PTFE (Eptfe) Market Segmentation
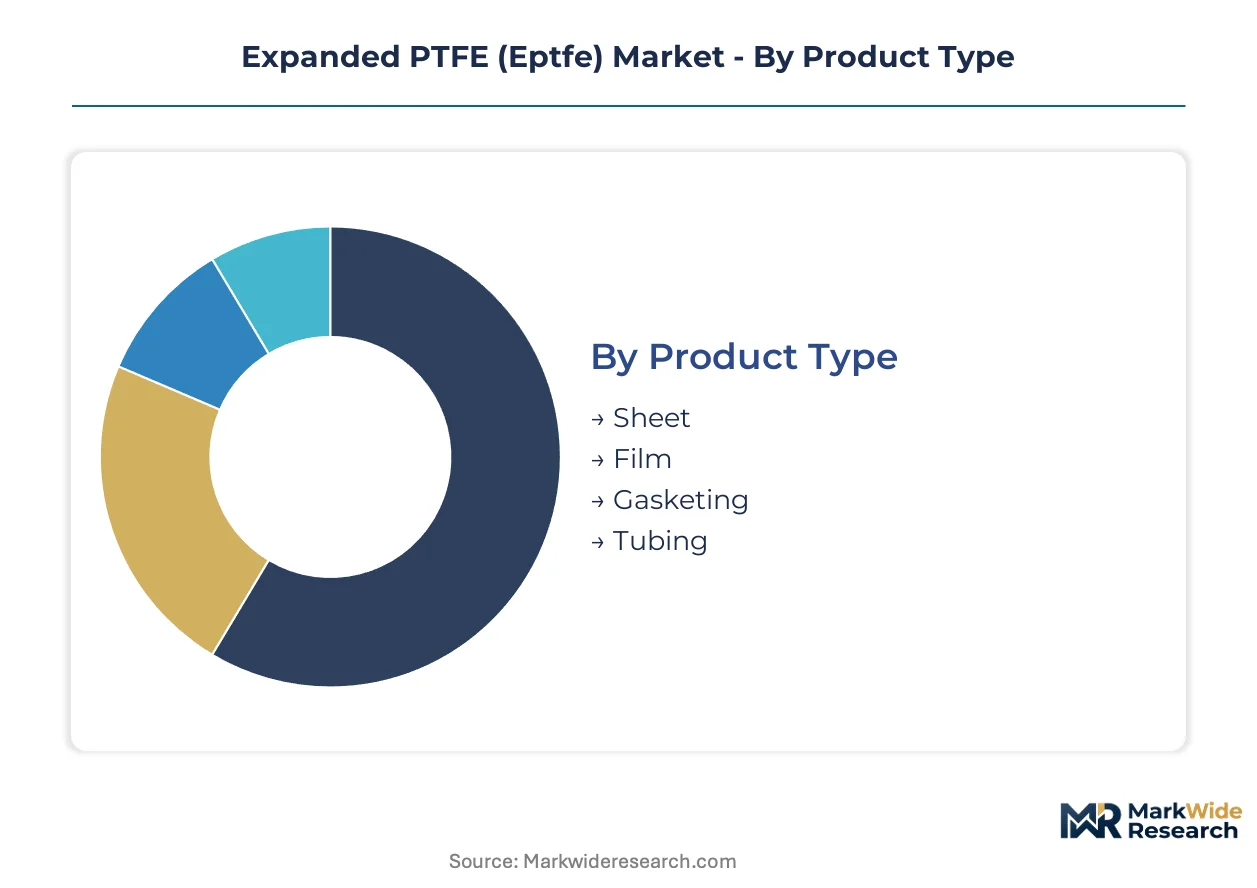
ePTFE market dynamics fragment sharply across product formats and end-use specifications. Medical device OEMs impose cleanroom validation requirements that industrial buyers rarely match. Architectural and filtration applications demand property gradients achievable only through multilayer co-extrusion.
Product Type:
Margin pools concentrate in medical-grade tubing and high-porosity membranes where cleanroom extrusion capabilities create supplier scarcity.
- Sheet:Monolithic expanded PTFE sheets with 70-80% porosity serve chemical processing infrastructure in Germany's Ludwigshafen corridor. BASF and Covestro facility maintenance programs specify 3-5mm thickness grades for reactor gasket replacement cycles.
- Tubing:Validated cleanroom extrusion yields luminal surfaces for vascular access grafts. Massachusetts and Minnesota cardiovascular device clusters specify particle-controlled supply chains with ISO 14644-1 Class 7 protocols, elevating margin capture for qualified converters.
- Film:Thin-gauge membranes laminate into architectural tensile structures for stadium roofing.
- Gasketing:Compressed sheet formats seal transformer and switchgear assemblies under long-term supply agreements.
The dominant share belongs to Sheet, while Tubing is closing the gap fastest.
End User:
Application-specific certification requirements split procurement patterns between regulated implantable devices and industrial maintenance cycles.
- Chemical Processing:Corrosion-resistant sealing in Germany's Leverkusen and Ludwigshafen clusters sustains premium membrane consumption. Reactor flange specifications demand 260°C service range validation with PTFE precursor traceability under REACH scrutiny.
- Aerospace:Lightweight insulation for engine nacelles and fuel system sealing drives specification rigor. FAA fire-resistance standards and OEM qualification protocols extend supplier approval timelines beyond eighteen months.
- Automotive:Heavy-duty engine filtration systems specify Donaldson membrane architectures.
- Electrical:Transformer gasketing maintains mature demand patterns with disciplined pricing.
Chemical Processing commands the largest procurement volumes, yet Aerospace exhibits the steepest expansion trajectory as engine efficiency standards tighten.
Application:
Performance tiering separates validated medical grades from commodity industrial specifications.
- Sealing Solutions:Chemical processing infrastructure in Germany's industrial corridor consumes premium sheet and gasket formats. Corrosion resistance justifies material premiums over elastomer alternatives in sulfuric acid and chlorine handling environments.
- Filtration:Dialysis membrane specifications require validated tubing extrusion with particle monitoring. OEMs in Massachusetts specify cleanroom protocols that compress qualified supplier panels.
- Insulation:Electrical transformer applications maintain steady demand through utility maintenance cycles.
- Coating:Surface modification layers bond ePTFE substrates to thermoplastic polyurethane skins.
Sealing Solutions retains the dominant position, though Filtration gains share fastest as dialysis device production scales.
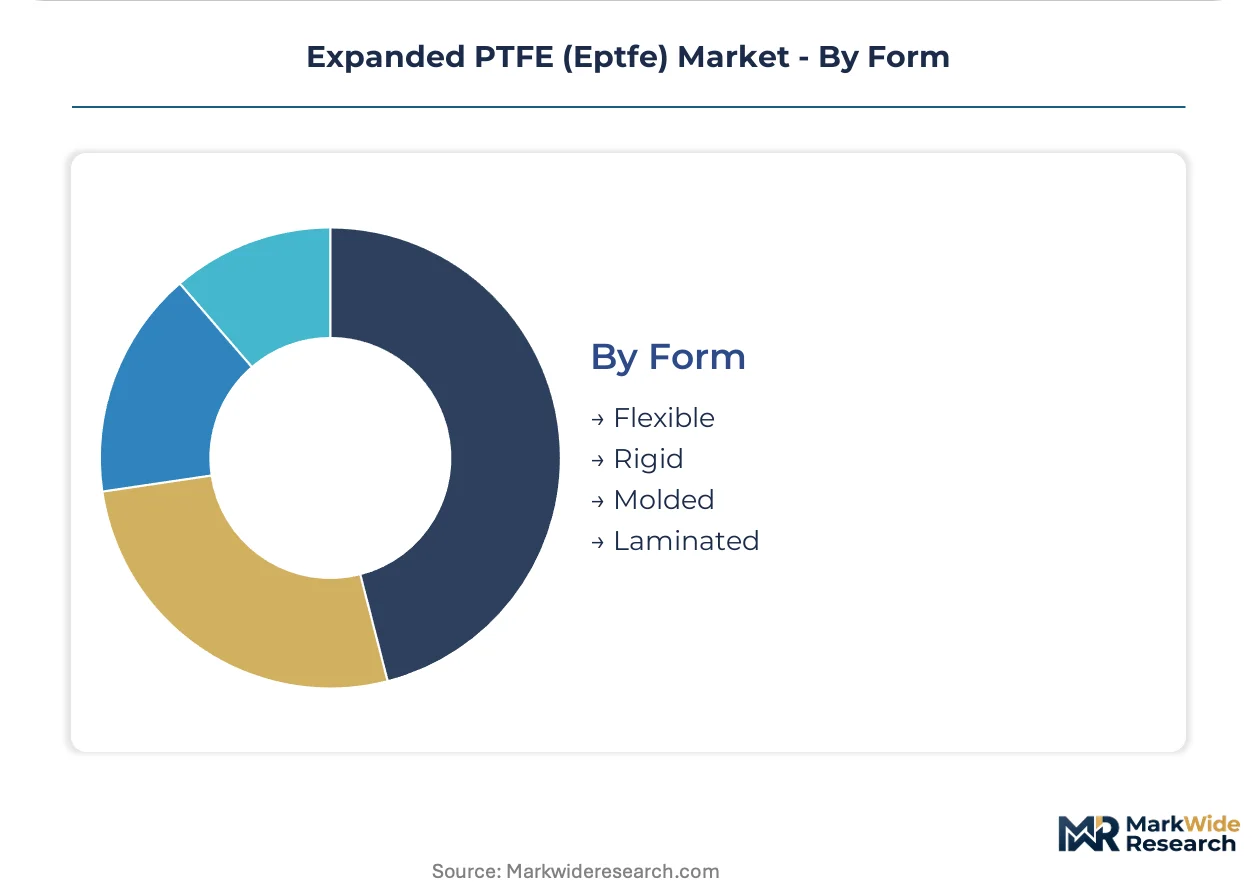
Form:
Processing method determines property gradients and end-use accessibility.
- Flexible:Conformable membranes adapt to complex geometries in vascular graft and hernia mesh applications. Soft-tissue repair specifications favor pliability over structural rigidity.
- Laminated:Multilayer architectures bond ePTFE with fluorinated ethylene propylene or thermoplastic polyurethane skins. Cardiovascular device manufacturers specify thromboresistant luminal surfaces through co-extrusion.
- Rigid:Structural formats support electrical insulation and mechanical sealing.
- Molded:Custom geometries serve specialized component integration.
Flexible formats hold the largest installed base, while Laminated structures expand most quickly through medical composite adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three chemical conglomerates control precursor PTFE resin production, exposing membrane converters in Germany, the United States, and Japan to allocation risk during supply shocks. This concentration shapes procurement security calculations across medical and industrial tiers.
United States
FDA 21 CFR 177.1550 governs food-contact ePTFE while cardiovascular device clusters in Massachusetts and Minnesota specify cleanroom extrusion protocols. Hospital procurement consolidation across Texas and California academic medical centers has compressed supplier panels for implantable membranes. Massachusetts-based OEMs drive validated tubing demand for vascular access grafts.
Germany
REACH per- and polyfluoroalkyl substance scrutiny from ECHA threatens feedstock availability for membrane converters serving chemical processing infrastructure. BASF and Covestro facility maintenance programs in Ludwigshafen and Leverkusen sustain premium sheet consumption for reactor gasket replacement cycles. Germany's industrial corridor anchors European corrosion-resistant sealing demand.
China
NMPA maintains divergent biocompatibility testing protocols from FDA and EU MDR, fragmenting registration strategies for multinational suppliers seeking vascular graft approvals. Yangtze River Delta chemical processing investments sustain industrial membrane consumption. Shanghai and Suzhou medical device manufacturing clusters are scaling dialysis filtration component production.
Japan
METI carbon-neutral material mandates favor suppliers with closed-loop fluoropolymer processing investments. PMDA regulatory requirements parallel FDA stringency for implantable grades, extending approval timelines for uncertified membrane sources. Osaka-based cardiovascular device manufacturers specify thromboresistant composite specifications.
India
CDSCO fast-track pathways for US FDA-cleared devices are opening vascular graft opportunities in Mumbai and Hyderabad hospital procurement networks. Domestic chemical processing infrastructure expansion in Gujarat sustains industrial gasket demand. Maharashtra medical device manufacturing incentives are attracting membrane converter investments.
Expanded PTFE (Eptfe) Market Vendor Landscape
Concentration sits with diversified materials platforms and specialized membrane converters. Three chemical conglomerates dominate precursor resin supply, creating tiered dependency structures downstream. Strategic archetypes include integrated fluoropolymer producers with backward control over polymerization, medical-grade specialists with validated cleanroom capabilities, and industrial gasket fabricators competing on scale. Dominant competitive moves encompass dual regulatory filing investments for FDA and EU MDR alignment, plus capacity commitments to hospital procurement consolidation.
Among diversified materials platforms, Compagnie de Saint-Gobain S.A. and Nitto Denko Corporation occupy positions spanning architectural membranes and industrial gasketing. W.L. Gore & Associates, Inc. exemplifies the medical-grade specialist archetype with vascular graft heritage. These three represent distinct competitive vectors: integrated fluoropolymer breadth, Asia-Pacific membrane diversification, and implantable device validation depth.
| Leading Market Players |
|---|
| W.L. Gore & Associates, Inc. |
| Donaldson Company, Inc. |
| Compagnie de Saint-Gobain S.A. |
| Nitto Denko Corporation |
| Rogers Corporation |
| Markel Corporation |
| Zeus Industrial Products, Inc. |
| Lenzing Plastics GmbH & Co. KG |
| Teadit Group |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at cleanroom extrusion facilities in Massachusetts and Minnesota shapes price floors across medical-grade tubing tiers, concentrating margin capture among validated suppliers while compressing legacy gasket producer returns.
Pricing Analysis
Three-tier pricing structure across implant-grade, industrial-grade, and commodity-grade levels stratifies the market. Price differentiation hinges on FDA 510(k) certification status and ISO 14644-1 cleanroom validation, with medical device OEMs absorbing premiums for particle-controlled supply chains. Cost compression in industrial sealing runs through silicone substitution threats in hernia mesh applications. Chemical processing buyers in Germany exhibit lowest price sensitivity due to corrosion resistance requirements, while automotive filtration purchasers negotiate volume-driven contract terms.
Supply Chain Analysis
Inventory buffers for PTFE precursor resin stretch six to nine months as converters hedge against allocation shocks from the three dominant chemical conglomerates. Feedstock production concentrates in the United States, Germany, and Japan, drawing from fluorspar mining and hydrofluoric acid processing. Single-source vulnerability pervades medical-grade membrane supply, where FDA master file documentation locks in qualified converters. Distribution runs through direct OEM contracts for implantable grades and industrial distribution networks for sealing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone elastomer advances in soft-tissue repair pose immediate substitution threats that incumbent ePTFE suppliers must neutralize through performance differentiation and regulatory lock-in.
For Market Incumbents: Consolidate supplier relationships with cardiovascular device OEMs through ten-year total-cost guarantees that match hospital procurement consolidation timelines. Deepen backward integration into PTFE polymerization to secure feedstock allocation priority during supply shocks. Counter silicone substitution by emphasizing thromboresistant luminal surface performance in vascular graft specifications. For New Entrants and Emerging Players: Anchor in India's CDSCO fast-track pathway for US FDA-cleared devices, targeting Mumbai and Hyderabad hospital procurement networks with validated tubing offerings. Penetrate the architectural tensile membrane segment through photovoltaic laminate integration for stadium and airport construction. Pursue co-development partnerships with regional chemical processors seeking corrosion-resistant sealing alternatives. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane converters with existing fluoropolymer backward integration and established FDA master file documentation. Long-term viability rests on regulatory moat durability rather than manufacturing scale alone. Watch REACH restriction finalization timelines as the critical inflection indicator for feedstock availability and qualified supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Regulatory Filing Investment | Parallel FDA 510(k) and EU MDR alignment extends contract durations with cardiovascular OEMs. |
| Cleanroom Capacity Expansion | ISO 14644-1 Class 7 validation in Massachusetts captures dialysis filtration specification share. |
| Backward Integration into Polymerization | In-house PTFE resin production secures allocation priority during precursor supply shocks. |
| Hospital System Partnership | Single-source contracts with Texas and California academic medical centers eliminate second-source competition. |
| Architectural Composite Development | Photovoltaic laminate integration opens stadium and airport construction specification channels. |
Methodological Framework
A standing panel of biomedical engineers, hospital GPO contracts managers, cleanroom extrusion technicians, and chemical processing procurement leads provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, SEC 10-K fluoropolymer disclosures, and REACH restriction proposal tracking. Bottom-up demand modeling across tubing, sheet, and gasket formats triangulated against top-down chemical industry capacity assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end-use industry, application performance tier, and regional regulatory cluster dimensions. CAGRs derived from segmented growth rate reconciliation incorporated cleanroom capacity expansion timelines, hospital procurement consolidation trajectories, and ECHA regulatory development milestones.
Material uncertainties — REACH per- and polyfluoroalkyl substance restriction finalization, cleanroom operator wage inflation, and silicone substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions documented in primary fieldwork without claiming predictive precision. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Plastic Injection Mold Market
Industrial Materials
Global Thermally Modified Wood Market
Industrial Materials
Soil Stabilization Materials Market
Industrial Materials
Wood Protein Market
Industrial Materials
Global High Pressure Seals Market
Industrial Materials
Polycarbonate Panels Market
Industrial Materials
Extruders Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Industrial Heaters Market
Industrial Materials
Powder Funnels Market
Industrial Materials
Hardfacing Rods Market
Industrial Materials
Global Polycarbonate Sheets Market
Industrial Materials
Neoprene Foam Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Modified Wood Market