
 United States Engineering Plastics Market | 2026-2036
United States Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Engineering Plastics Market Analytics
Direct distribution from resin producers to Tier-1 automotive suppliers is tilting as compounders build regional technical service centers closer to Midwest manufacturing clusters. BASF leverages its Wyandotte, Michigan technical hub to sustain just-in-time delivery contracts with Detroit-area automakers. DuPont de Nemours, Inc. anchors its position through specialized Zytel nylon formulations for under-the-hood thermal applications. Celanese Corporation differentiates via captive acetyl chain integration that controls feedstock cost volatility.
Engineering plastics encompass thermoplastic polymers with mechanical and thermal properties exceeding commodity plastics, typically with continuous service temperatures above 100°C and tensile strengths surpassing 40 MPa, serving load-bearing structural applications across transportation, electrical, and industrial equipment. Nylon and polycarbonate (PC) dominate volume flows through injection molding channels serving automotive underhood and electrical connector segments. 3D printing technology is expanding fastest from a small base, driven by aerospace prototyping demand and filament-grade material qualification programs at Ascend Performance Materials.
The EPA Corporate Average Fuel Economy standards and NHTSA safety regulations jointly compel automakers to substitute metal components with certified engineering plastics, while OSHA workplace exposure limits shape compounding plant capital allocation. FDA food-contact and medical device regulations create parallel specification tracks for Eastman Chemical Company and SABIC healthcare-grade polymer lines. Stakeholders must monitor how California Air Resources Board zero-emission vehicle mandates cascade into material specifications for battery electric vehicle platforms.
Market Dynamics
Automotive electrification is compressing material qualification cycles while EPA tailpipe emissions rules tighten lightweighting mandates, forcing compounders to co-develop thermal management grades with Detroit-area OEMs under 18-month validation windows rather than traditional 36-month programs.
Growth Catalysts
- NHTSA CAFE Standards:Federal fuel economy mandates compel automakers to substitute 40-60 pounds of metal per vehicle with certified engineering plastics in underhood and structural applications.
- Battery Electric Vehicle Thermal Management:EV battery housings and coolant manifolds require nylon and PPS grades with continuous service temperatures above 150°C, opening specification slots previously held by aluminum die castings.
- Great Lakes Manufacturing Corridor Concentration:Proximity of injection molding capacity to Detroit, Cleveland, and Chicago assembly plants sustains just-in-time resin delivery contracts with sub-500-mile logistics loops.
Market Restraints
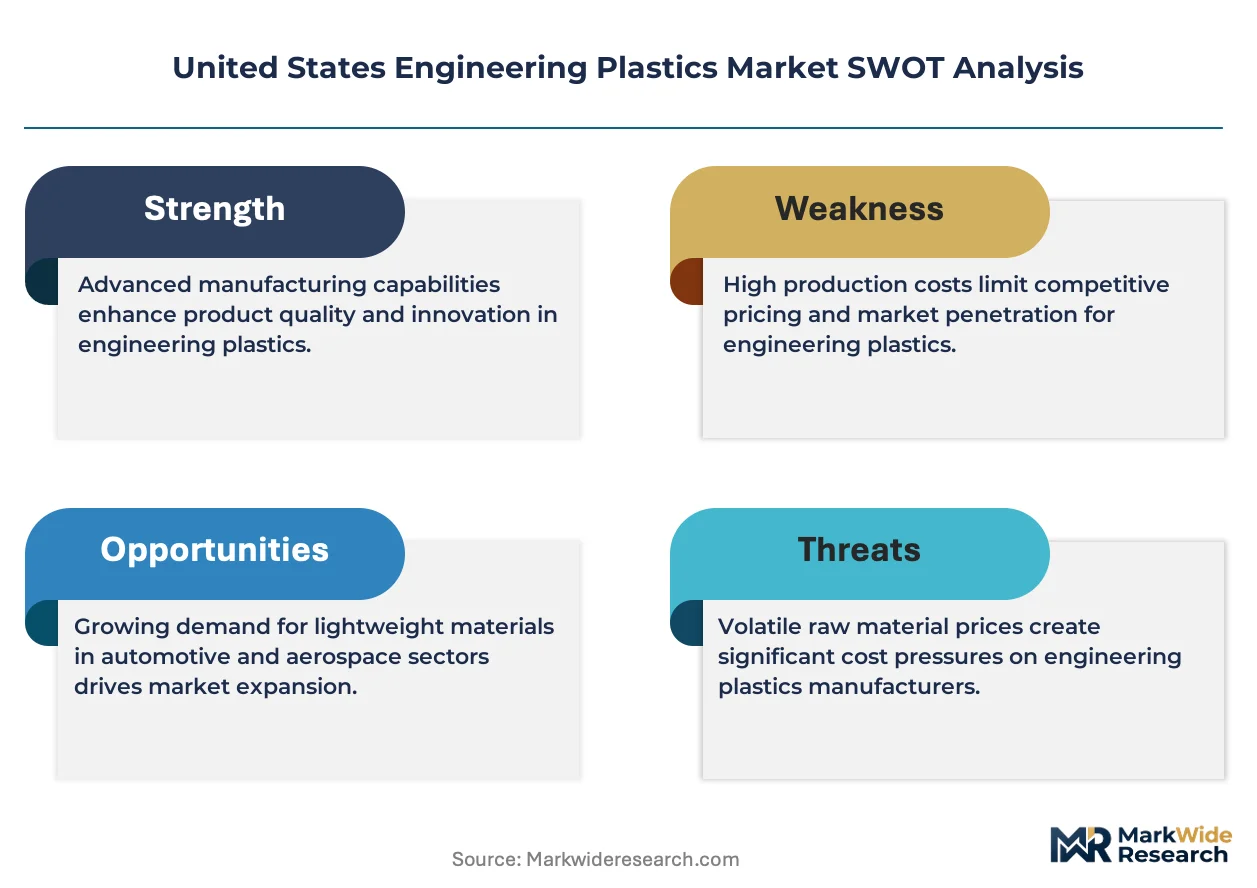
- Caprolactam Feedstock Volatility:Nylon 6 supply chains remain exposed to benzene and cyclohexane price swings that compounders cannot fully pass through under indexed automotive contracts.
- Gulf Coast Petrochemical Concentration:Over 70% of domestic polycarbonate precursor capacity clusters along Texas-Louisiana chemical corridors, creating hurricane and freeze-risk exposure.
- OSHA Respirable Crystalline Silica Limits:Compounding plant investments in enclosed material handling systems add $2-4 million per facility to comply with 2016 revised exposure standards.
Strategic Opportunities
- Ohio River Valley Shale Proximity:Appalachian ethane feedstock cost advantages support regional polypropylene and acrylonitrile-butadiene-styrene capacity expansions serving Midwest automotive.
- FDA Medical Device Grade Qualification:Healthcare-grade polycarbonate and PSU lines for surgical instruments and drug delivery devices command 40-60% price premiums over automotive grades.
- 3D Printing Filament Aerospace Adoption:FDM and SLS prototyping demand at Wichita and Seattle-area defense contractors is qualifying filament-grade nylons for limited production runs.
Industry Challenges
- Polymer Rheology Modeling Talent Scarcity:Injection mold flow simulation expertise for thin-wall battery housing designs commands salary premiums that mid-size compounders struggle to match.
- UL94 V-0 Recertification Burden:Reformulated flame-retardant packages to meet revised EPA chemical assessments require 12-18 month retesting cycles that delay new product launches.
- Legacy ERP Integration with Customer EDI:Tier-1 supplier portals demand real-time inventory visibility that forces compounders to replace aging MRP systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Engineering Plastics Market |
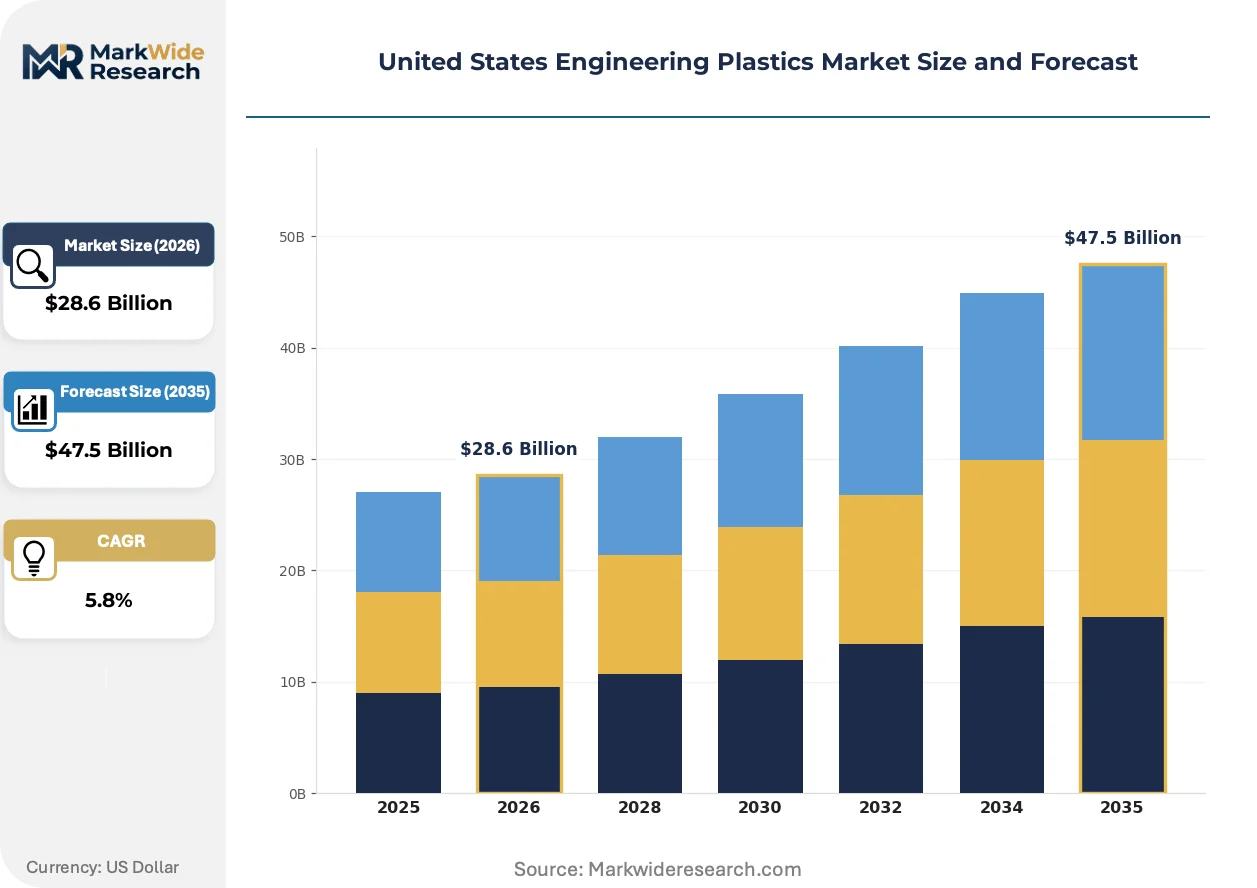
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PBT, PC, PMMA, Nylon End User: Aerospace, Automotive, Electrical, Consumer Goods Application: Manufacturing, Insulation, Structural Components, Automotive Parts Technology: Injection Molding, Extrusion, Blow Molding, 3D Printing |
| Companies Covered | SABIC, DuPont de Nemours, Inc., BASF, Dow Inc., Eastman Chemical Company, Celanese Corporation, Ascend Performance Materials, Solvay S.A., Covestro AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Engineering Plastics Market Evolving Landscape
Material science breakthroughs and regulatory recalibration are compressing product development cycles while reshaping how engineering plastics specifications get written and enforced across automotive and healthcare verticals.
Long-fiber thermoplastic (LFT) compounds with 12-25mm glass fiber reinforcement are rendering obsolete short-fiber nylon and PP grades in front-end modules and seat structures. Ford and Stellantis have shifted 2026 platform specifications to LFT for crash-relevant parts. This technology is rendering obsolete legacy metal-to-plastic conversion programs that relied on isotropic mechanical properties.
EPA greenhouse gas standards for light-duty vehicles finalized in 2024 mandate fleet-average CO2 reductions that automakers can only achieve through aggressive mass decompounding. The rule's 2027-2032 phase-in compresses material substitution timelines. Battery electric vehicle platforms face the most stringent requirements, driving polycarbonate blends into panoramic roof modules previously specified in glass.
Automotive procurement organizations are consolidating resin suppliers to single-source relationships per material family, reversing the previous dual-source mandate. Tier-1 injection molders now face qualification costs exceeding $500,000 per resin grade, pushing mid-size compounders toward toll manufacturing arrangements. This concentration is most visible in Michigan and Ohio, where Magna and Lear have reduced approved nylon suppliers from six to three since 2022.
United States Engineering Plastics Market Segmentation
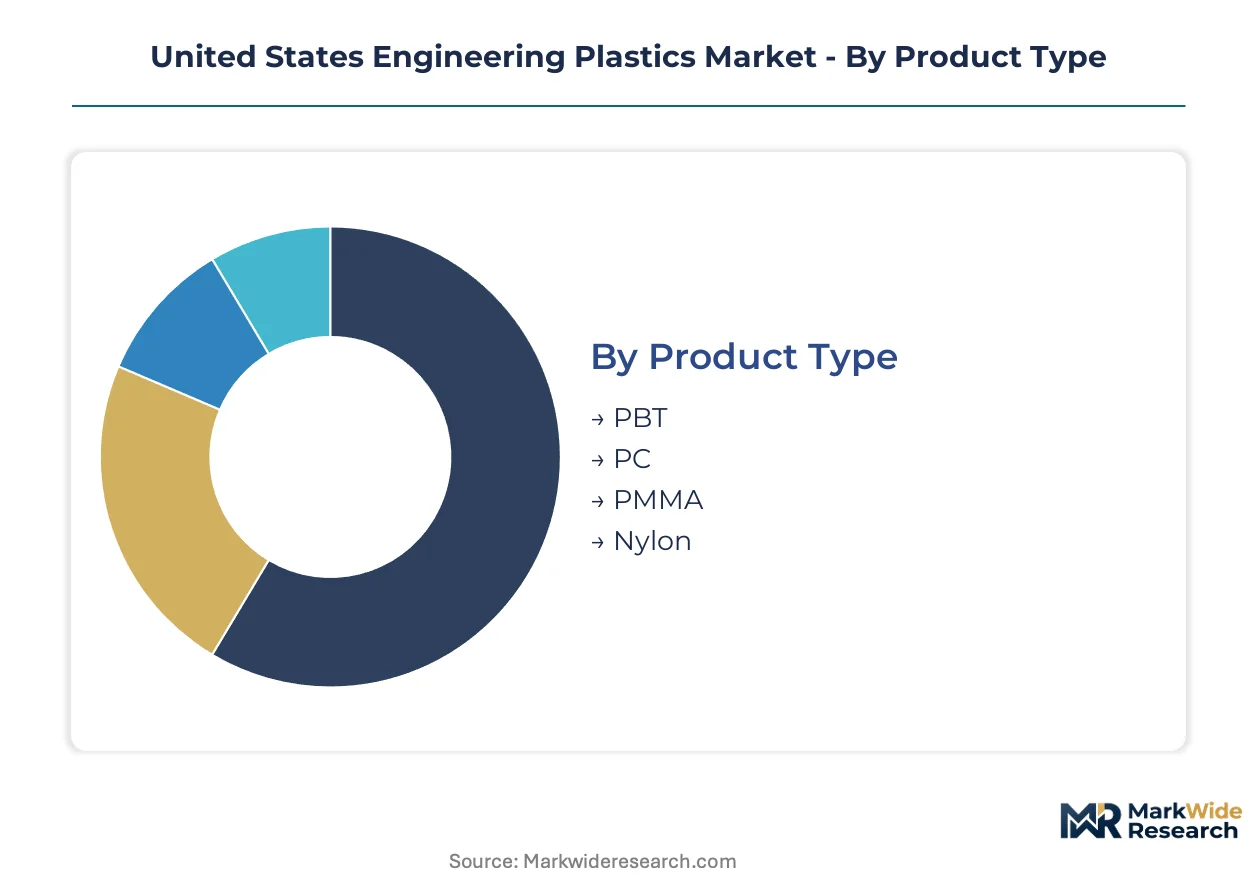
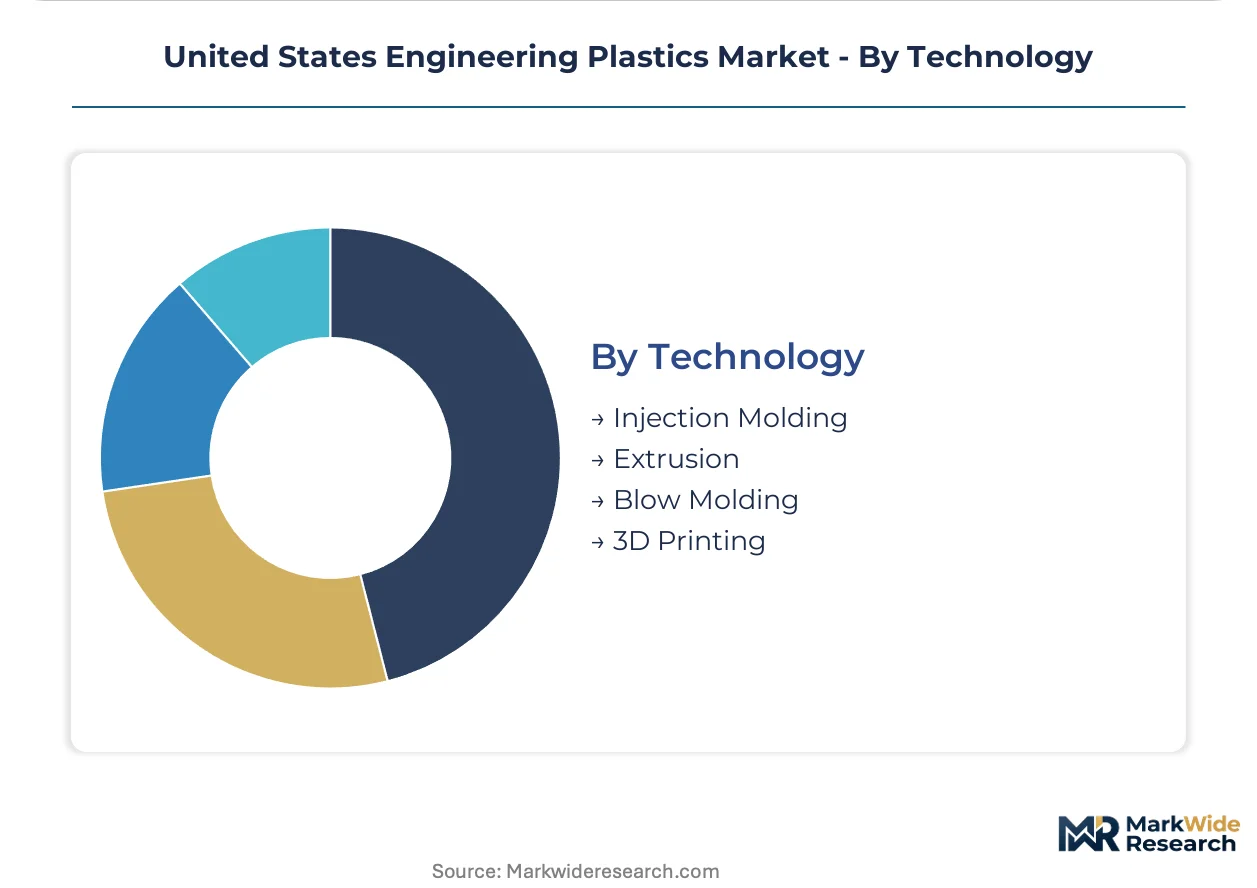
Engineering plastics procurement in the United States follows distinct technical and commercial logics across material chemistry, end-use specifications, and processing technology. Each segmentation dimension reveals different competitive dynamics and margin structures that compounders must navigate.
Product Type:
Mature commodity-adjacent grades dominate tonnage flows while specialty polymers capture expanding specification slots in thermal-critical applications.
- Nylon:Polyamide formulations spanning PA6 and PA66 chemistry serve underhood automotive components requiring continuous service temperatures above 150°C. Michigan and Ohio assembly plants consume the majority of domestic volume for engine covers, intake manifolds, and transmission components facing EPA lightweighting mandates.
- Polycarbonate (PC):Aromatic carbonate polymers deliver optical clarity combined with impact resistance for EV battery housings and panoramic roof modules. The material is displacing glass in Detroit-area BEV platforms where mass reduction targets have tightened.
- PBT:Polybutylene terephthalate offers dimensional stability and electrical insulation for connector housings in automotive and industrial equipment.
- PMMA:Polymethyl methacrylate provides UV-resistant optical performance for lighting lenses and display applications.
Nylon retains volume leadership across the Great Lakes corridor; polycarbonate holds the steepest expansion curve as electrification reshapes thermal management requirements.
End User:
Customer concentration varies sharply by technical qualification burden and contract duration, with automotive procurement patterns diverging from aerospace validation cycles.
- Automotive:Tier-1 suppliers in Detroit, Cleveland, and Chicago metropolitan areas specify certified grades for powertrain, structural, and interior applications under NHTSA safety and EPA emissions compliance. OEMs now consolidate to single-source relationships per material family, elevating qualification costs.
- Electrical:Connector and housing manufacturers demand UL94 V-0 flame-retardant packages for switchgear, circuit breakers, and EV charging infrastructure. Reformulation cycles to meet revised EPA chemical assessments extend time-to-market.
- Aerospace:Wichita and Seattle-area defense contractors drive filament-grade nylon qualification for FDM and SLS prototyping, though production volumes remain limited.
- Consumer Goods:Appliance and electronics housings utilize cost-optimized grades with less stringent thermal requirements.
Automotive commands the largest tonnage position; aerospace delivers the most rapid specification growth as additive manufacturing matures.
Application:
Functional requirements determine resin selection more than end-use industry, with thermal and mechanical load specifications crossing traditional sector boundaries.
- Automotive Parts:Battery housings, coolant manifolds, and thermal management components require nylon and PPS grades replacing aluminum die castings. Long-fiber thermoplastic compounds with 12-25mm glass fiber reinforcement are rendering obsolete short-fiber grades for crash-relevant front-end modules.
- Structural Components:Load-bearing seat structures and underbody shields utilize LFT compounds meeting Ford and Stellantis 2026 platform specifications.
- Insulation:Electrical and thermal barrier applications demand specialized formulations for wire coatings and battery module separators.
- Manufacturing:General industrial equipment housings and machinery components utilize standard injection-molded grades.
Automotive parts applications anchor current volume; structural components are climbing the fastest as LFT technology displaces legacy metal-to-plastic conversions.
Technology:
Processing method selection constrains material formulation and dictates regional service center placement relative to molding capacity clusters.
- Injection Molding:Dominant conversion technology for high-volume automotive and electrical components across Michigan, Ohio, and Illinois manufacturing corridors. Just-in-time resin delivery contracts require technical service centers within 500-mile logistics loops.
- 3D Printing:Filament-grade material qualification programs at Ascend Performance Materials and regional compounders support aerospace prototyping demand. FDM and SLS processes expand fastest from a small base.
- Extrusion:Profile and sheet production for construction and industrial applications.
- Blow Molding:Hollow component production for fluid handling and packaging applications.
Injection molding maintains absolute volume dominance; 3D printing is gaining share fastest as filament qualification accelerates defense contractor adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates along the Great Lakes manufacturing corridor while Gulf Coast feedstock regions face hurricane exposure premiums. Regional specialization patterns reflect automotive OEM clustering and petrochemical infrastructure geography. EPA and NHTSA regulations cascade unevenly across state-level manufacturing zones.
Michigan
Detroit-area automakers drive nylon and polycarbonate consumption for battery housings and thermal management. NHTSA CAFE standards compel metal-to-plastic substitution in underhood applications. BASF operates its Wyandotte technical hub to sustain just-in-time delivery contracts within 150-mile logistics loops.
Ohio
Cleveland and Toledo assembly plants specify long-fiber thermoplastic compounds for 2026 platform crash-relevant parts. Ohio EPA air quality permits shape compounding plant capital allocation decisions. The state anchors regional technical service center placement for compounders serving Midwest injection molding clusters.
Illinois
Chicago metropolitan electrical connector manufacturers demand UL94 V-0 flame-retardant packages for EV charging infrastructure. OSHA respirable crystalline silica limits drive enclosed material handling investments at compounding facilities. Aurora and Rockford house specialized toll manufacturing arrangements for mid-size compounders.
Texas
Gulf Coast polycarbonate precursor capacity clusters expose supply chains to hurricane and freeze-risk disruptions. EPA regional enforcement patterns affect petrochemical plant emission compliance costs. Houston and Beaumont host over 70% of domestic bisphenol-A and phosgene feedstock production.
Pennsylvania
Appalachian shale ethane feedstock cost advantages support regional polypropylene capacity expansions. Pennsylvania Department of Environmental Protection permitting timelines influence plant construction schedules. Pittsburgh and Philadelphia metropolitan areas concentrate healthcare-grade polycarbonate demand for medical device manufacturing.
United States Engineering Plastics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation and compounding. The United States market exhibits tiered consolidation with resin producers, compounders, and technical service providers occupying distinct value positions. Three archetypes dominate: integrated petrochemical-resin producers, specialized engineering plastics compounders, and regional toll manufacturing operators. Capacity expansion and qualification cost consolidation represent the dominant competitive moves as OEMs reduce approved supplier lists.
Among integrated petrochemical producers, SABIC and BASF occupy positions spanning upstream feedstock through certified automotive grades. DuPont de Nemours, Inc. exemplifies the specialized compounder archetype with focused nylon formulations. Celanese Corporation represents backward-integrated players controlling acetyl chain feedstock costs. These three anchors illustrate how competitive positioning diverges between scale-driven resin platforms and formulation-focused technical specialists.
| Leading Market Players |
|---|
| SABIC |
| DuPont de Nemours, Inc. |
| BASF |
| Dow Inc. |
| Eastman Chemical Company |
| Celanese Corporation |
| Ascend Performance Materials |
| Solvay S.A. |
| Covestro AG |
| Others |
Value Network & Pricing Analysis
Caprolactam feedstock volatility determines both automotive contract pricing spreads and compounding plant location decisions across the Great Lakes corridor. Benzene and cyclohexane price swings compress margins on indexed nylon formulations while forcing compounders toward captive acetyl chain integration or regional toll manufacturing arrangements.
Pricing Analysis
Customization-premium spreads separate certified automotive grades from standard injection molding compounds. Three-tier pricing structure across premium, standard, and economy levels reflects UL94 V-0 flame-retardant certification, FDA medical device clearance, and volume scale commitments. Pricing pressure stems from OEM consolidation to single-source relationships per material family, which elevates qualification costs that compounders cannot fully recover. Tier-1 automotive suppliers exhibit the highest price sensitivity due to pass-through contract structures, while healthcare-grade polycarbonate buyers accept sustained premiums for surgical instrument applications.
Supply Chain Analysis
Supplier-financing facilities and extended payment terms have become standard procurement instruments as Tier-1 molders face qualification cost burdens exceeding five hundred thousand dollars per resin grade. Geographic supply concentration centers on Texas and Louisiana for polycarbonate precursor production, with Michigan and Ohio anchoring nylon compounding capacity for Detroit-area automakers. Raw material dependencies include bisphenol-A and phosgene for polycarbonate, caprolactam for nylon 6, and adipic acid for nylon 66. Hurricane and freeze-risk exposure along the Gulf Coast represents the dominant structural vulnerability. Distribution runs through regional technical service centers within five-hundred-mile logistics loops of injection molding clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States engineering plastics demand sits in early-cycle expansion as battery electric vehicle thermal management specifications displace aluminum die castings. NHTSA CAFE standards and EPA tailpipe emissions rules jointly accelerate metal-to-plastic substitution timelines.
For Market Incumbents: Build formulation moats around nylon and PPS grades qualified for continuous service temperatures above 150°C in EV battery housings. BASF and DuPont de Nemours should deepen captive acetyl chain integration to offset caprolactam volatility. Celanese Corporation must defend its position against emerging toll manufacturing arrangements by embedding technical service teams within Detroit-area OEM development cycles.
For New Entrants and Emerging Players: Medical device-grade polycarbonate and PSU lines for surgical instruments represent the most penetrable entry point given forty to sixty percent price premiums over automotive grades. Ohio River Valley shale proximity supports regional polypropylene capacity expansions serving Midwest automotive injection molders. A go-to-market angle anchored through FDA qualification partnerships with Pittsburgh and Philadelphia metropolitan device manufacturers bypasses entrenched automotive supplier consolidation.
For Investors and Strategic Acquirers: EPA greenhouse gas standards for light-duty vehicles finalized in 2024 reshape the acquisition landscape toward compounders with validated thermal management grades under eighteen-month qualification windows. Long-term viability across a five-to-ten year horizon favors backward-integrated specialists controlling feedstock cost volatility. Acquisition targets should demonstrate UL94 V-0 recertification capabilities and active long-fiber thermoplastic compound development. The signal to watch is California Air Resources Board zero-emission vehicle mandate cascades into material specification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetyl Chain Feedstock | Celanese Corporation's captive supply of methanol and acetic acid insulates margin compression from benzene price swings. |
| Regional Technical Service Center Expansion | BASF's Wyandotte hub sustains just-in-time delivery contracts within 150-mile loops of Detroit automakers. |
| FDA Medical Device Grade Qualification | Eastman Chemical healthcare-grade polycarbonate lines command sustained premiums for surgical instrument applications. |
| Long-Fiber Thermoplastic Compound Development | Ford and Stellantis 2026 platform specifications for crash-relevant parts favor 12-25mm glass fiber reinforcement grades. |
| Toll Manufacturing Partnership Arrangements | Mid-size compounders in Aurora and Rockford leverage shared compounding capacity to amortize OSHA silica compliance investments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Tier-1 automotive procurement managers, OEM platform engineers, compounding plant technical directors, and regional distribution channel partners. Secondary validation drew from SEC 10-K filings, American Chemistry Council industry reports, EPA regulatory dockets, and customs trade data for engineering plastics import flows. Bottom-up resin consumption estimates were triangulated against top-down automotive production forecasts and content-per-vehicle assumptions.
Calibration against historical nylon and polycarbonate volume trajectories anchored the analytical framework across the analysis window. Segmentation dimensions modeled include material chemistry grade, end-use industry vertical, thermal performance tier, and regional manufacturing cluster proximity. CAGRs were derived from regression analysis of substitution elasticity against EPA lightweighting mandate stringency indices, incorporating EV battery housing specification rates and long-fiber thermoplastic adoption curves as industry-specific forecast inputs.
Practitioners should monitor NHTSA rulemaking timelines and California Air Resources Board zero-emission vehicle mandate expansions for early signals of qualification cycle compression. Forecasts reflect assumptions regarding automotive electrification penetration and metal-to-plastic substitution elasticity under EPA Corporate Average Fuel Economy standards. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Wire Hoods Market
Industrial Materials
Global Jet Mill Market
Industrial Materials
Warehouse Drums and Barrels Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
North America Machined Seals Market
Industrial Materials
Static Mixer Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
United States Graphite Electrodes Market
Industrial Materials
Atomizing Metal Powder Market
Industrial Materials
Magnetic Separator Market
Industrial Materials
Global Industrial Dust Collector Market
Industrial Materials
Plastic Injection Mold Market
Industrial Materials
Briquetting Press Market
Industrial Materials
Industrial Round Wood Market
Industrial Materials
Global Metal Anodizing Market