
 Extruders and Compounding Machines Market | 2026-2036
Extruders and Compounding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Extruders and Compounding Machines Market Analysis
Premium extruder specifications is decoupling from commodity machine pricing as torque density, energy recovery, and Industry 4.0 integration become non-negotiable for automotive and medical compounders. Coperion GmbH leverages its co-rotating twin-screw platform to dominate high-performance polymer applications. Davis-Standard LLC anchors North American demand through extensive rebuild and service infrastructure. Nanjing KY Chemical Machinery Co Ltd competes aggressively on delivery speed for mid-tier plastic processing lines across Asia.
Extruders and compounding machines are continuous-processing systems that melt, mix, homogenize, and shape polymeric or food-based materials through rotating screws within temperature-controlled barrels, typically operating at pressures from 50 to 500 bar and temperatures up to 400°C depending on resin type. Twin screw configurations lead capital expenditure in plastic processing due to superior dispersive and distributive mixing for filled and reinforced compounds. Co-rotating technology captures the fastest expansion as compounders replace batch operations with continuous pharmaceutical and chemical formulation lines. Specialty extruder demand concentrates in aerospace and medical tubing where low-temperature processing preserves heat-sensitive bio-polymers and fluoropolymers.
EPA emissions rules for plastic processing facilities in the United States and REACH chemical restrictions in Europe are forcing equipment upgrades with sealed venting and closed-loop cooling. FDA material-contact surface standards for pharmaceutical manufacturing limit supplier qualification to vendors with documented compliance histories. China's GB standards for energy efficiency in polymer machinery, enforced by SAMR, are reshaping import requirements and local procurement criteria. Stakeholders must monitor how carbon-border adjustment mechanisms and extended producer responsibility laws in major manufacturing jurisdictions alter total cost of ownership calculations for extruder investments.
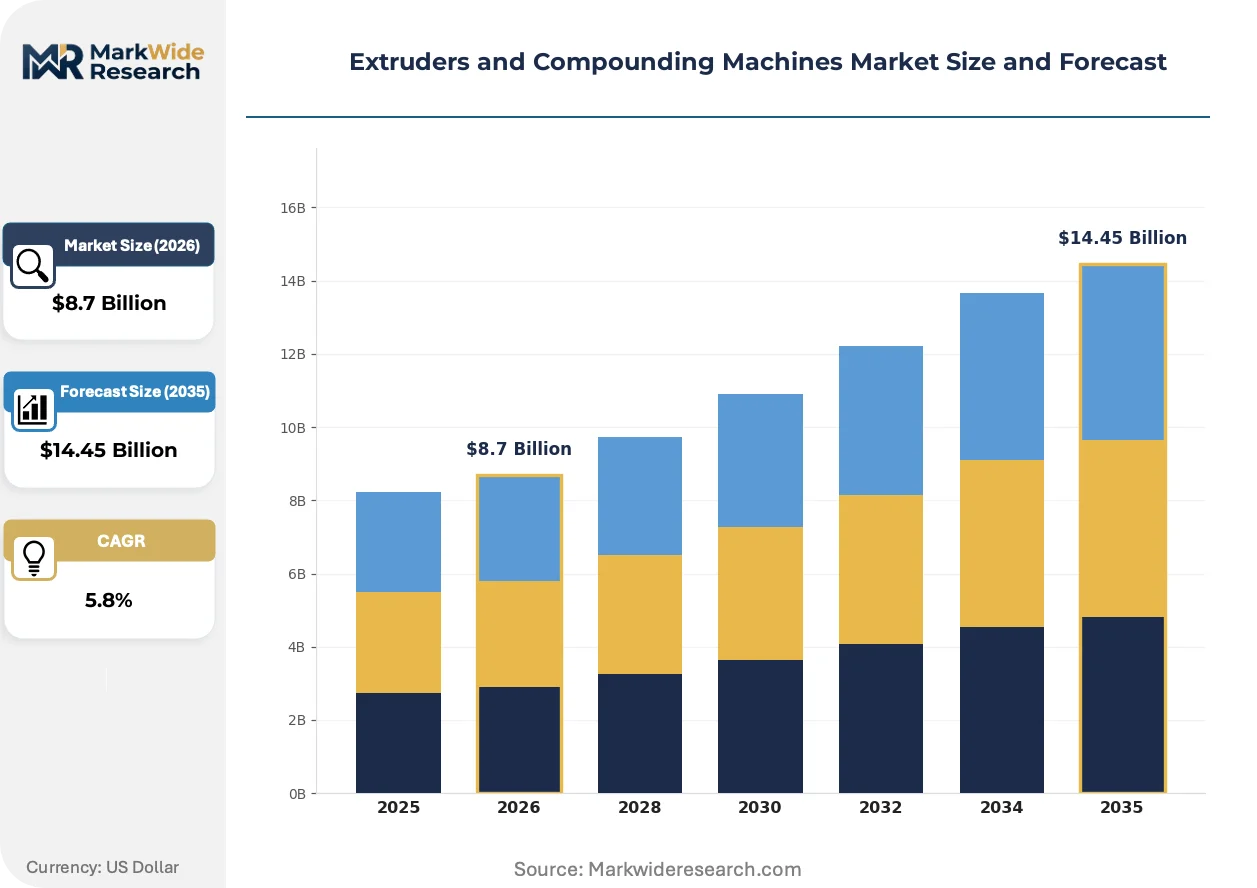
Market Dynamics
Automotive lightweighting mandates and pharmaceutical continuous manufacturing adoption are pulling capital toward high-torque twin-screw platforms with integrated energy recovery systems, decoupling premium specifications from commodity pricing tiers.
Growth Catalysts
- REACH chemical restrictions:European compounders must upgrade to sealed venting and closed-loop cooling systems, forcing equipment replacement cycles across polymer processing facilities in Germany and France.
- China's Yangtze River Delta polymer cluster:Concentrated demand from automotive and packaging compounders drives procurement of mid-tier plastic processing lines with rapid delivery requirements.
- Continuous pharmaceutical manufacturing:FDA material-contact surface standards accelerate replacement of batch operations with co-rotating twin-screw systems for active pharmaceutical ingredient formulation.
Market Restraints
- Specialty alloy supply concentration:Bimetallic barrel liners and corrosion-resistant screw materials depend on limited European and Japanese metallurgical suppliers, creating input cost volatility.
- High-torque gearbox technical limitation:Power density requirements above 16 Nm/cm³ strain existing drivetrain designs, extending qualification timelines for automotive compounders.
- Carbon-border adjustment friction:EU CBAM documentation requirements on embedded emissions increase compliance overhead for importers of Asian-manufactured extrusion equipment.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic formulation capacity expansion creates demand for pharmaceutical-grade compounding systems with documented FDA compliance histories.
- Biopolymer processing technology convergence:Low-shear screw geometries combined with nitrogen blanketing systems enable heat-sensitive polylactic acid and starch-based compound production.
- Rebuild and service channel innovation:North American compounders increasingly source remanufactured screws and barrels through OEM-authorized service networks rather than capital equipment purchases.
Industry Challenges
- Process control engineering skill gap:Integration of Industry 4.0 sensors and model-predictive temperature control requires scarce automation expertise that machinery suppliers struggle to staff.
- Legacy system integration complexity:Brownfield sites face downtime risks when connecting new twin-screw lines to existing material handling and downstream cooling infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extruders and Compounding Machines Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Screw, Twin Screw, Compounding Extruder, Specialty Extruder Application: Plastic Processing, Food Production, Chemical Formulation, Pharmaceutical Manufacturing Industry Vertical: Aerospace, Automotive Components, Packaging Solutions, Consumer Goods Technology: Co-rotating, Counter-rotating, High-Throughput, Low-Temperature |
| Companies Covered | Coperion GmbH, Leistritz AG, Bausano SpA, Davis-Standard LLC, Milacron Holdings Corp, Kabra Extrusiontechnik Ltd, Japan Steel Works Ltd, Reifenhäuser GmbH & Co KG, Nanjing KY Chemical Machinery Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extruders and Compounding Machines Market Emerging Trajectories
Energy recovery systems and digital twin simulation are compressing commissioning timelines while regulatory pressure on emissions intensifies equipment specification requirements across polymer processing.
Direct-drive torque motors with integrated regenerative braking are consolidating power transmission architectures in high-performance extruder designs. Automotive compounders in Germany and China specify these systems to eliminate gearbox maintenance and capture waste heat for barrel temperature control. The technology is consolidating supplier tiers by disqualifying traditional belt-drive and gearbox-dependent vendors from premium automotive qualification programs.
EPA emissions rules for plastic processing facilities mandate sealed venting systems and volatile organic compound capture on all new extrusion lines. Equipment manufacturers must now engineer closed-loop cooling circuits and fume extraction as standard rather than optional configurations. Medical tubing producers in the United States face the steepest compliance costs, driving preference toward vendors with pre-validated environmental control packages.
Compounders increasingly unbundle after-sales service contracts from initial equipment purchases, selecting third-party rebuild specialists for screw and barrel refurbishment. This procurement fragmentation disrupts traditional OEM recurring revenue models and compresses spare parts margins. The pattern is most visible in North American automotive supply chains, where tier-one compounders negotiate multi-site service agreements independent of machine procurement.
Extruders and Compounding Machines Market Segmentation
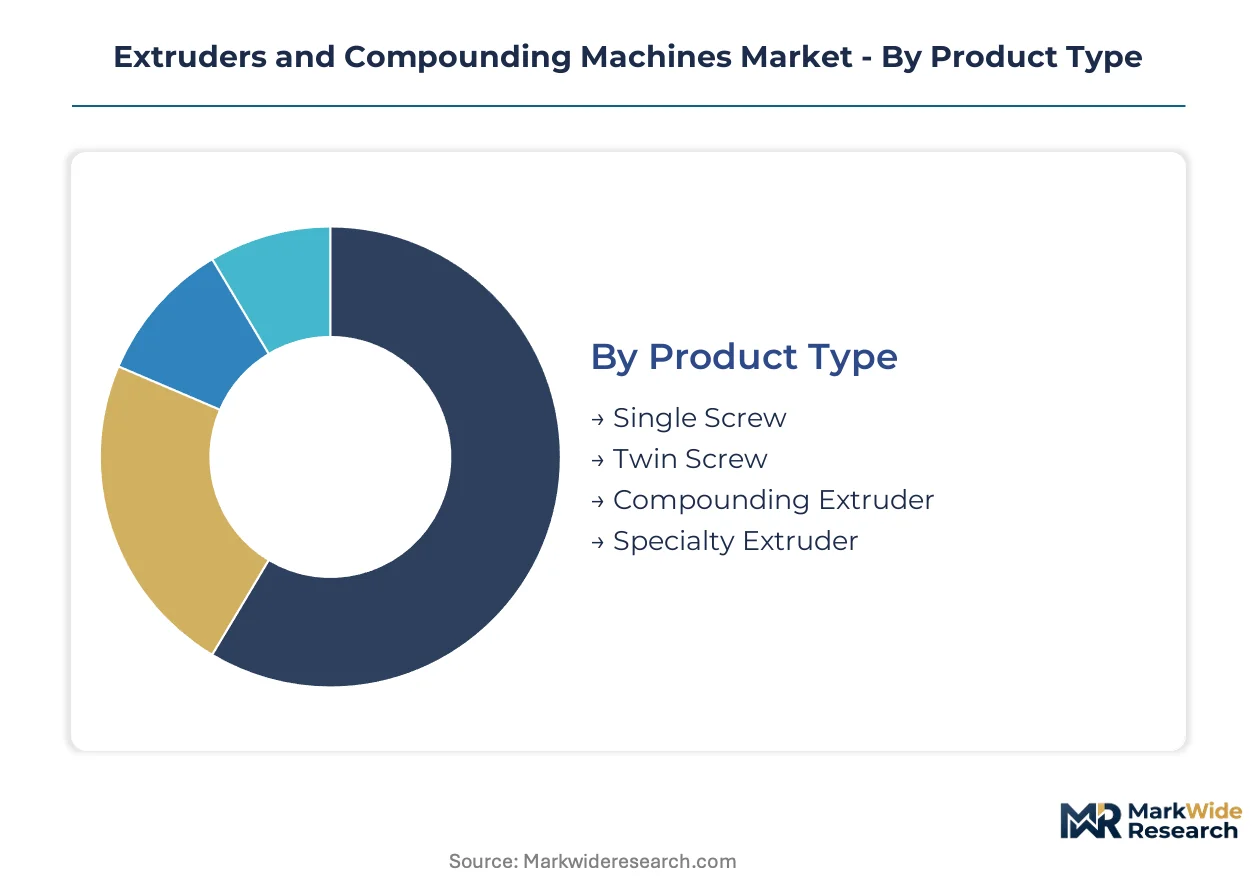
Segmentation in the extruders and compounding machines market reveals how torque density requirements and regulatory compliance are fragmenting procurement patterns across end-use verticals. Equipment specification tiers now diverge sharply between commodity plastic processors and pharmaceutical compounders demanding FDA-validated surface standards.
Product Type:
Supply concentration in high-torque drivetrains favors vendors with captive gearbox manufacturing, creating tiered qualification barriers across screw configurations.
- Twin Screw:Co-rotating configurations deliver superior dispersive mixing for filled polymer compounds. Automotive lightweighting programs in Germany and China specify these systems for continuous glass-fiber reinforced production lines. REACH-mandated sealed venting upgrades accelerate replacement of aging batch equipment.
- Specialty Extruder:Low-shear geometries with nitrogen blanketing preserve heat-sensitive bio-polymers and fluoropolymers. Medical tubing producers in the United States and aerospace compounders drive specification toward documented FDA compliance histories and AS9100 quality systems.
- Single Screw:Dominates high-volume commodity plastic processing with simpler maintenance profiles and lower capital thresholds.
- Compounding Extruder:Purpose-built systems integrate downstream pelletizing and cooling for masterbatch production.
Today's leader: Twin Screw. Tomorrow's challenger: Specialty Extruder.
Application:
Cost tier stratification separates validated pharmaceutical systems from standard plastic processing lines, with compliance documentation driving 40-60% price premiums.
- Pharmaceutical Manufacturing:Continuous processing adoption replaces batch operations for active ingredient formulation. FDA material-contact surface standards limit supplier qualification to vendors with documented compliance histories and ASME BPE certification.
- Plastic Processing:Volume concentration in China's Yangtze River Delta polymer cluster drives procurement of mid-tier lines with rapid delivery requirements. SAMR-enforced GB energy efficiency standards reshape import specifications.
- Chemical Formulation:REACH restrictions on volatile emissions force sealed venting and closed-loop cooling upgrades across European facilities.
- Food Production:Extrusion cooking and texturized protein systems operate under FSSAI and FDA food-contact material regulations.
Pharmaceutical Manufacturing commands the steepest expansion trajectory as continuous processing displaces batch operations.
Industry Vertical:
Customer type fragmentation splits demand between automotive tier-one compounders seeking energy recovery integration and packaging processors prioritizing throughput economics.
- Automotive Components:Lightweighting mandates pull capital toward high-torque platforms with integrated regenerative braking. Direct-drive torque motors eliminate gearbox maintenance while capturing waste heat for barrel temperature control.
- Aerospace:Low-temperature processing preserves mechanical properties in high-performance fluoropolymer compounds. AS9100 quality system requirements narrow vendor qualification to established suppliers with aerospace program histories.
- Packaging Solutions:High-throughput lines serve film and sheet producers with standardized screw designs and rapid changeover protocols.
- Consumer Goods:Mid-tier equipment serves appliance and electronics housing compounders with balanced performance and capital efficiency.
Automotive Components anchors current procurement volume. Aerospace represents the steepest margin expansion opportunity.
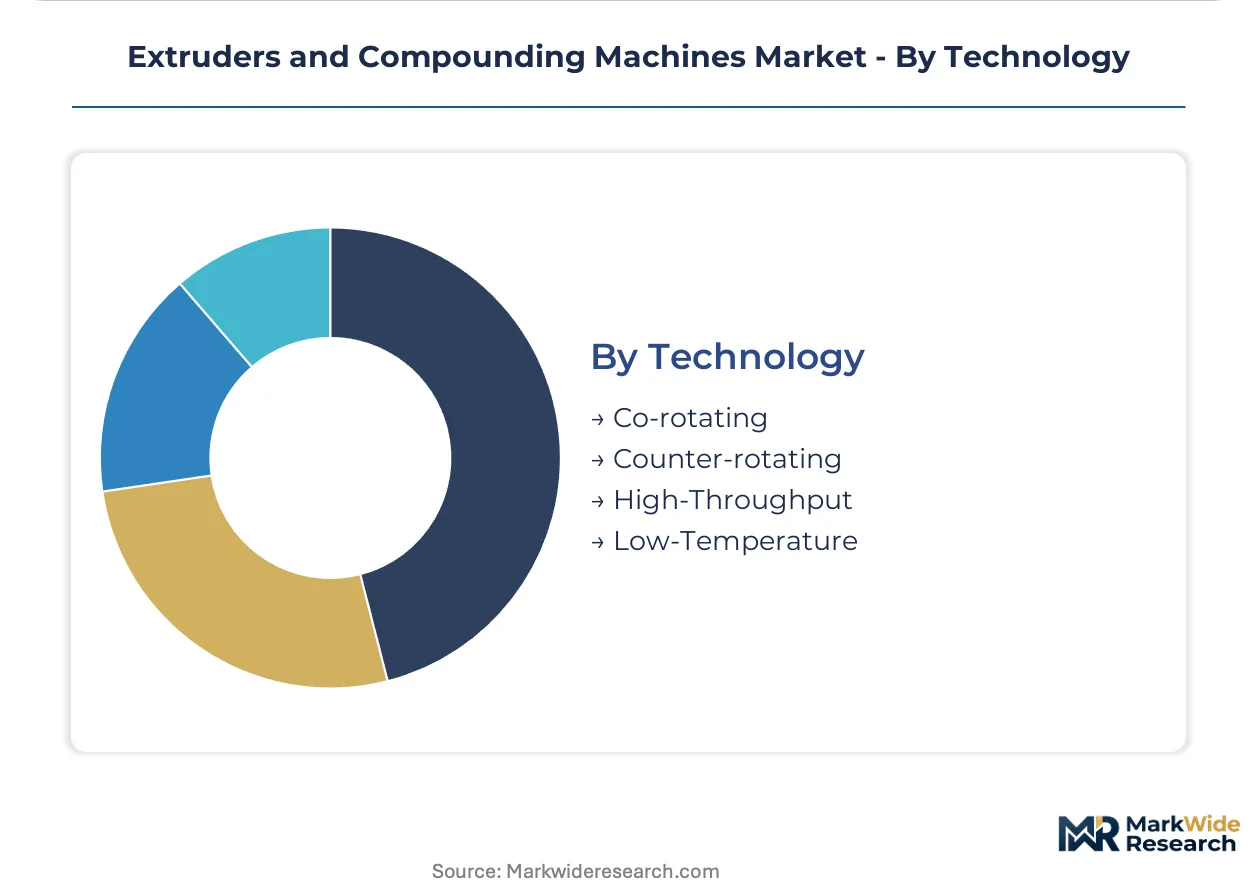
Technology:
Maturity gradients separate proven co-rotating architectures from emerging low-temperature systems still navigating qualification timelines.
- Co-rotating:Dominant twin-screw configuration for high-performance polymer compounding. Self-wiping screw geometry enables continuous pharmaceutical formulation with minimal residence time variation.
- Low-Temperature:Shear-sensitive processing preserves bio-polymer molecular weight for medical and packaging applications. Nitrogen blanketing and cooled barrel sections extend processing windows for PLA and starch-based compounds.
- Counter-rotating:Calendering and profile extrusion applications leverage positive material transport for PVC and wood-plastic composites.
- High-Throughput:Extended L/D ratios and optimized feed sections maximize output for commodity resin processors.
Co-rotating technology holds installed base dominance. Low-Temperature systems are climbing the fastest as biopolymer formulation expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process control engineers and polymer technologists concentrate in Germany's industrial belt, China's Yangtze manufacturing corridor, and the US Great Lakes automotive zone. These talent pools anchor equipment specification authority and drive procurement decisions for high-torque systems.
Germany
Automotive lightweighting mandates from KBA pull compounders toward direct-drive torque motors with regenerative braking. REACH chemical restrictions enforced by ECHA force sealed venting upgrades across polymer processing facilities. Stuttgart and Munich anchor high-performance compounding demand from tier-one automotive suppliers.
China
SAMR-enforced GB energy efficiency standards reshape import requirements for polymer machinery. The Yangtze River Delta cluster concentrates mid-tier plastic processing procurement with rapid delivery expectations. Shanghai and Suzhou house the densest concentration of packaging and automotive compounders specifying co-rotating twin-screw platforms.
United States
FDA material-contact surface standards limit pharmaceutical compounding equipment to vendors with documented compliance histories. EPA emissions rules mandate sealed venting and VOC capture on new extrusion lines. Medical tubing producers in Minnesota and automotive compounders in Michigan drive specification toward pre-validated environmental control packages.
India
The PLI scheme for specialty chemicals expands domestic pharmaceutical formulation capacity. CDSCO alignment with FDA standards accelerates demand for ASME BPE-certified compounding systems. Gujarat and Maharashtra host emerging clusters of active pharmaceutical ingredient producers replacing batch operations with continuous processing lines.
Japan
METI industrial policy supports advanced materials processing for aerospace fluoropolymer compounds. JIS standards and AS9100 quality requirements narrow vendor qualification to established suppliers. Nagoya and Osaka concentrate precision compounding demand from electronics and automotive supply chains.
Extruders and Compounding Machines Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent specification tiers. The vendor base splits between integrated drivetrain manufacturers and modular assembly specialists. Three archetypes dominate: captive gearbox producers with torque density leadership, authorized rebuild networks capturing aftermarket service revenue, and rapid-delivery fabricators serving mid-tier Asian processors. Competitive moves concentrate on M&A for metallurgical supply security and strategic partnerships for Industry 4.0 control system integration.
Within the premium integrated-systems tier, Coperion GmbH and Davis-Standard LLC occupy positions defined by rebuild infrastructure and service network density. Nanjing KY Chemical Machinery Co Ltd exemplifies the speed-focused fabrication archetype competing on delivery timelines for standardized plastic processing lines. Leistritz AG and Japan Steel Works Ltd sit within specialized drivetrain engineering segments where power density requirements above 16 Nm/cm³ create technical qualification barriers. These named entities anchor competitive positioning without implying specific strategic actions or financial performance claims.
| Leading Market Players |
|---|
| Coperion GmbH |
| Leistritz AG |
| Bausano SpA |
| Davis-Standard LLC |
| Milacron Holdings Corp |
| Kabra Extrusiontechnik Ltd |
| Japan Steel Works Ltd |
| Reifenhäuser GmbH & Co KG |
| Nanjing KY Chemical Machinery Co Ltd |
| Others |
Supply Flow & Price Mechanics
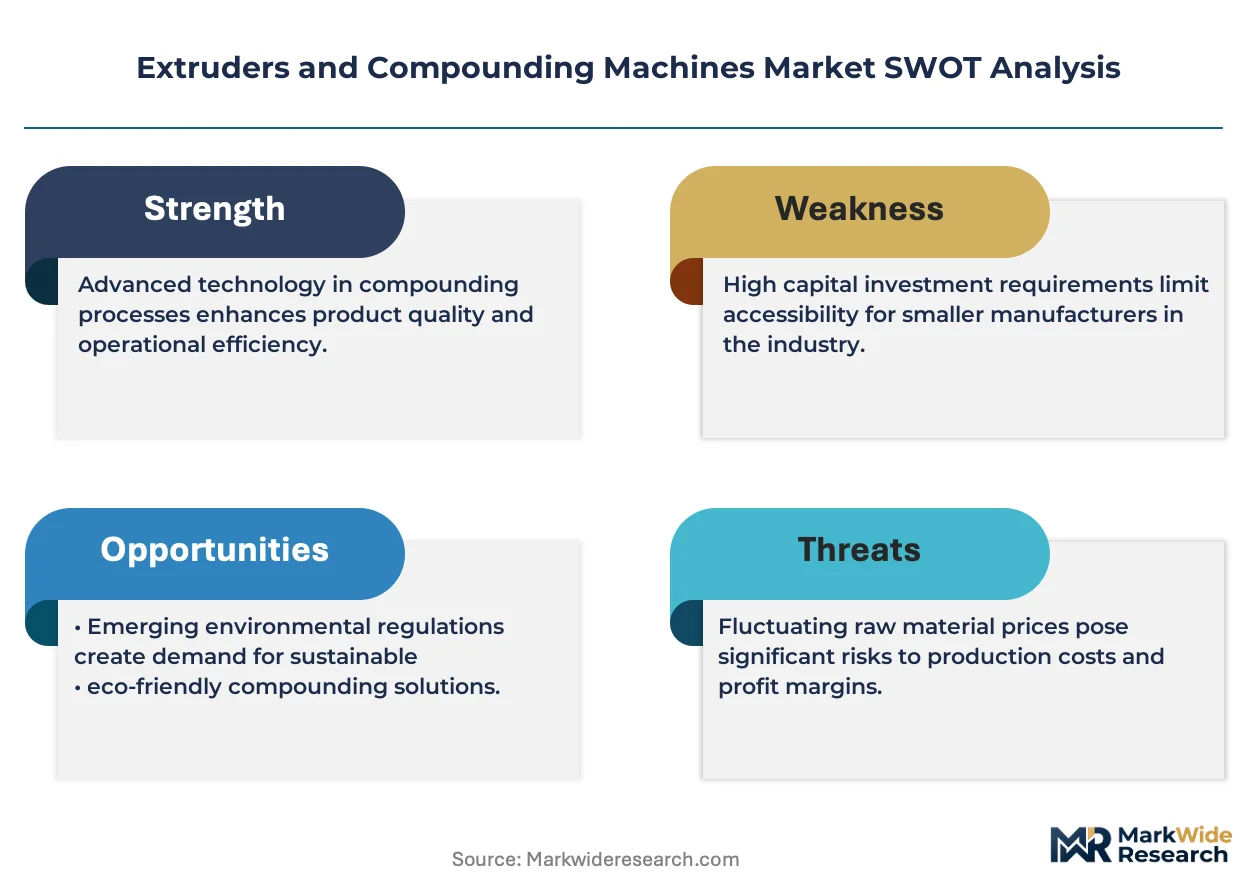
Nickel alloy price indices cascade through bimetallic barrel and corrosion-resistant screw manufacturing, compressing margins at specialty extruder tiers while commodity single-screw lines absorb volatility through standardized metallurgy. REACH-mandated sealed venting and FDA surface certification requirements widen the cost gap between validated pharmaceutical systems and standard plastic processing equipment.
Pricing Analysis
Bundled after-sales contracts versus unbundled third-party rebuild sourcing now defines the dominant pricing model across North American automotive supply chains. Certification-grade differentiation separates FDA-validated pharmaceutical systems from mid-tier packaging lines, with compliance documentation driving substantial price premiums. Cost compression intensifies in commodity plastic processing as Chinese fabricators compete on delivery speed for Yangtze River Delta procurement. Tier-one automotive compounders exhibit lowest price sensitivity due to lightweighting mandate urgency, while mid-tier packaging processors prioritize capital efficiency over performance specifications.
Supply Chain Analysis
Dual-sourcing requirements for high-torque gearboxes and bimetallic barrel liners mandate multi-supplier qualification across German, Japanese, and Austrian metallurgical specialists. Specialty alloy feedstock draws from concentrated European and Japanese suppliers, creating input cost volatility for corrosion-resistant screw materials. Single-source vulnerability in power-dense drivetrain components above 16 Nm/cm³ strains automotive compounder qualification timelines. Distribution runs through OEM-authorized service networks and third-party rebuild specialists, with procurement fragmentation compressing traditional manufacturer spare parts margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH chemical restrictions and FDA material-contact standards continuously force equipment replacement cycles across polymer processing facilities.
For Market Incumbents: Anticipate margin compression from unbundled service procurement by securing captive metallurgical supply through backward integration into specialty alloy feedstock. Reinforce qualification barriers through Industry 4.0 control system integration and documented compliance histories for pharmaceutical manufacturing. Counter emerging rapid-delivery fabricators by embedding energy recovery systems as standard rather than optional configurations. For New Entrants and Emerging Players: Enter via India's PLI-driven specialty chemicals expansion, where domestic pharmaceutical formulation capacity creates demand for ASME BPE-certified compounding systems with rapid installation capabilities. Target biopolymer processing white-space through low-shear screw geometries combined with nitrogen blanketing systems for heat-sensitive PLA compounds. Pursue OEM-authorized rebuild network partnerships rather than capital equipment manufacturing to capture recurring service revenue with lower capital intensity. For Investors and Strategic Acquirers: Consolidation pressure builds where gearbox manufacturing capability concentrates among vendors with captive drivetrain production exceeding 16 Nm/cm³ power density thresholds. Long-term viability favors integrated-systems producers with rebuild infrastructure density and service network coverage across automotive and pharmaceutical clusters. Monitor carbon-border adjustment mechanism enforcement as the critical signal for import cost structure inflection in Asian-manufactured equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloys | Captive supply of bimetallic barrel liners reduces input cost volatility from Japanese and European metallurgical suppliers. |
| Energy Recovery System Standardization | Regenerative braking integration aligns with KBA automotive lightweighting mandates and SAMR energy efficiency standards. |
| FDA Compliance Documentation Investment | ASME BPE certification histories unlock pharmaceutical manufacturing procurement with substantial price premiums over commodity tiers. |
| OEM-Authorized Rebuild Network Expansion | Service revenue capture counters unbundled procurement fragmentation in North American automotive supply chains. |
| Industry 4.0 Control System Partnerships | Model-predictive temperature integration addresses process control engineering skill gaps constraining machinery suppliers. |
Methodological Framework
Direct dialogue with plant engineers at polymer processing facilities, procurement leads at tier-one automotive compounders, aftermarket service heads, and technical R&D directors at drivetrain manufacturers grounded qualitative insights. Secondary validation drew from customs and trade data, SAMR GB standard filings, EPA emissions rule dockets, FDA material-contact guidance documents, and SEC 10-K disclosures from capital equipment manufacturers. Bottom-up demand modeling across screw configurations and top-down macroeconomic triangulation ensured cross-verification of market sizing estimates.
Installed base projections and replacement cycle analysis across the analysis window reflect segmentation by torque density tier, regulatory compliance grade, end-use vertical, and regional manufacturing cluster. CAGRs were derived from regression analysis of historical capital expenditure patterns weighted by announced automotive lightweighting program timelines and pharmaceutical continuous manufacturing adoption curves. Forecast inputs incorporated REACH enforcement intensity projections, carbon-border adjustment documentation requirements, and biopolymer formulation capacity buildout announcements.
Inputs from ECHA regulatory filings and CDSCO alignment notifications were available through the study window; gaps in real-time alloy price index reporting introduce uncertainty bands around specialty extruder cost structure assumptions. Deviation in EU CBAM implementation timelines or SAMR energy efficiency enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Welding Consumables Market
Industrial Materials
Tension Spring Market
Industrial Materials
Paint Knife Market
Industrial Materials
Pultrusion Products Market
Industrial Materials
Air Classifiers Market
Industrial Materials
High Speed Dispersers (HSD) Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Natural Industrial Absorbents Market
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Diamond Wire Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
High Speed Steels Market
Industrial Materials
Heat-Insulation Boards for Industrial Equipment Market
Industrial Materials
Shock Mat Market