
 Global Glass Wool Board Sales Market | 2026-2036
Global Glass Wool Board Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glass Wool Board Sales Market Analysis
Mineral wool is rebalancing competitive economics as specifiers weigh thermal performance against installed cost in mid-rise commercial envelopes. Owens Corning leverages its North American manufacturing scale to anchor supply contracts with national homebuilders. Saint-Gobain competes through integrated glass-to-fiber operations that sustain margin control across volatile silica markets. Knauf Insulation specializes in high-density acoustic formats that occupy premium positions in European cinema and studio construction.
Glass wool board consists of bonded glass fibers formed into rigid or semi-rigid sheets, typically manufactured via rotary process spinning of molten glass at 1,400°C and bound with phenolic resin to achieve densities from 10kg/m³ to 25kg/m³ and thicknesses ranging from 25mm to 100mm, serving primarily as thermal insulation, acoustic absorption, and fire-containment barriers in built environments. The rigid boards segment leads value contribution due to specification lock-in within commercial roofing and curtain-wall assemblies, while acoustic tiles represent the fastest-growing category as open-plan office retrofits accelerate across developed markets. Flexible panels retain mature demand profiles in residential attic applications where price sensitivity limits margin expansion.
The EU Green Deal and REACH frameworks in Europe, alongside EPA energy-efficiency guidelines in the United States and China's GB standards for building energy conservation, collectively tighten permissible thermal transmittance thresholds and restrict formaldehyde-based binder chemistries, forcing reformulation investments and reshaping competitive access. Japan's METI building codes and India's BIS insulation standards are converging toward stricter fire-reaction classifications that favor non-combustible glass wool over polymer foam alternatives in high-occupancy structures. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where product certification costs will concentrate and where harmonized standards will unlock cross-border scale.
Market Dynamics
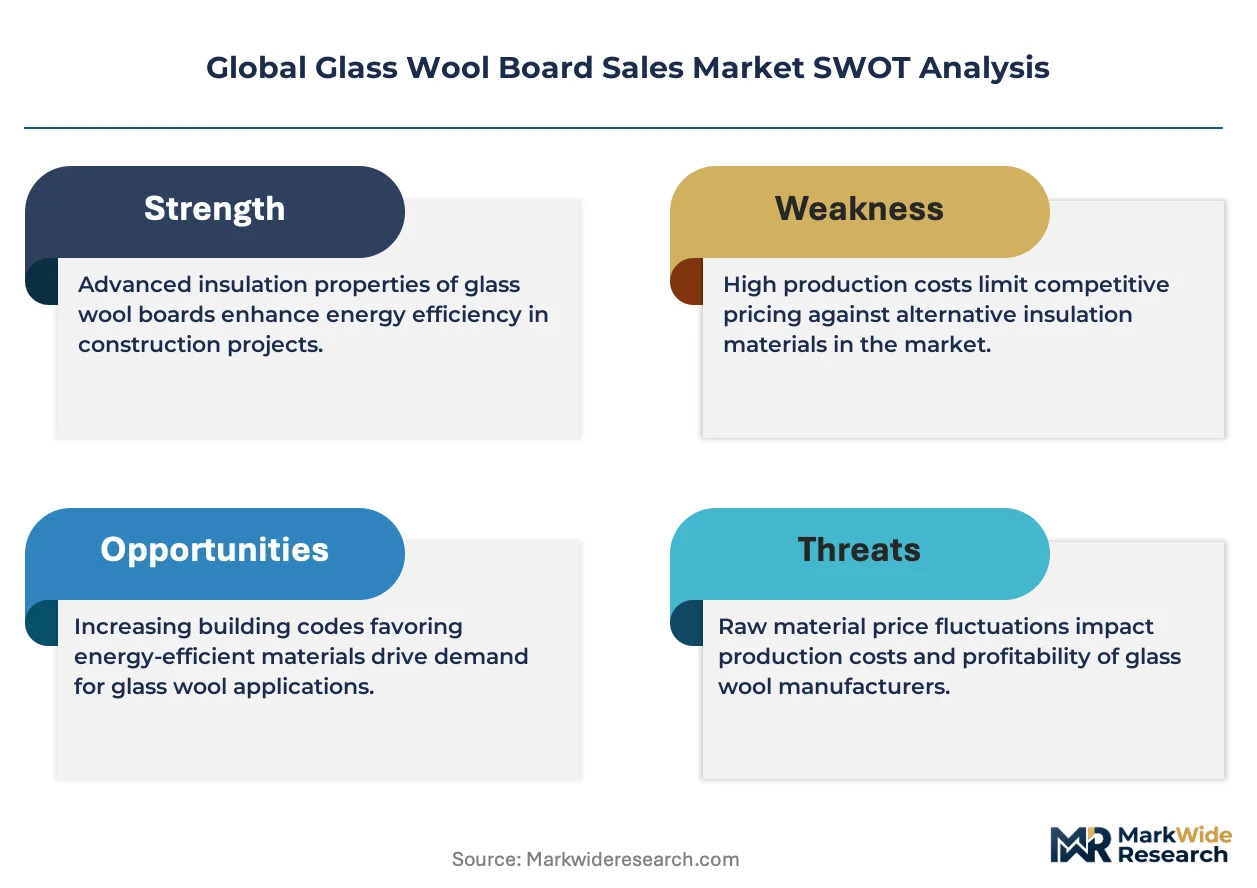
The EU Green Deal's compression of allowable U-values for building envelopes is forcing reformulation investments across the glass wool board supply base, concentrating competitive advantage among manufacturers with captive silica sourcing and integrated fiber-spinning capabilities.
Growth Catalysts
- Retrofit code tightening in China:Tier-one cities including Shanghai and Beijing are accelerating building energy audits, pulling rigid board volumes into facade renovation projects that previously used loose-fill alternatives.
- REACH framework binder restrictions:ECHA's formaldehyde emission limits are disqualifying legacy phenolic chemistries, creating specification openings for bio-based resin systems that command premium positioning in Nordic markets.
- Rotary spinning process advances:Newer fiber-diameter control technologies are improving thermal resistance consistency, enabling glass wool boards to meet stricter lambda-value requirements in German commercial roofing assemblies.
Market Restraints
- Silica sand supply concentration:High-purity silica sourcing clusters in select Chinese provinces and Egyptian desert deposits, exposing converters to freight-cost volatility and geopolitical interruption risk.
- Polymer foam substitution in residential attics:Expanded polystyrene and spray polyurethane systems compete on installed cost-per-R-value in single-family construction, capping glass wool board penetration in price-sensitive segments.
- Curing energy intensity:Phenolic resin polymerization requires sustained thermal input, embedding natural gas price exposure into manufacturing cost structures that resist short-term hedging.
Strategic Opportunities
- India's BIS fire-reaction convergence:Stricter non-combustibility classifications in high-occupancy structures favor glass wool over polymer alternatives, opening specification pathways in Mumbai and Delhi commercial towers.
- Acoustic tile retrofit channels:Open-plan office conversions across London and Paris are accelerating demand for high-density ceiling systems that integrate thermal and sound-absorption functions.
- Digital specification platforms:Building information modeling libraries are compressing architect decision cycles, rewarding suppliers with parametrically accurate thermal performance datasets embedded in Revit and ArchiCAD modules.
Industry Challenges
- Bio-based resin formulation expertise:The shift from formaldehyde binders requires polymer chemistry capabilities scarce among traditional glass wool engineering teams, lengthening product validation timelines.
- Multi-jurisdiction certification stacking:Simultaneous pursuit of CE marking, EPA-compliant labeling, and China's GB standard testing extends commercialization cycles by twelve to eighteen months for new board densities.
- Capex intensity for rotary line upgrades:Fiber-diameter uniformity improvements demand furnace rebuilds and spinner disc replacements that strain mid-capitalization producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glass Wool Board Sales Market |
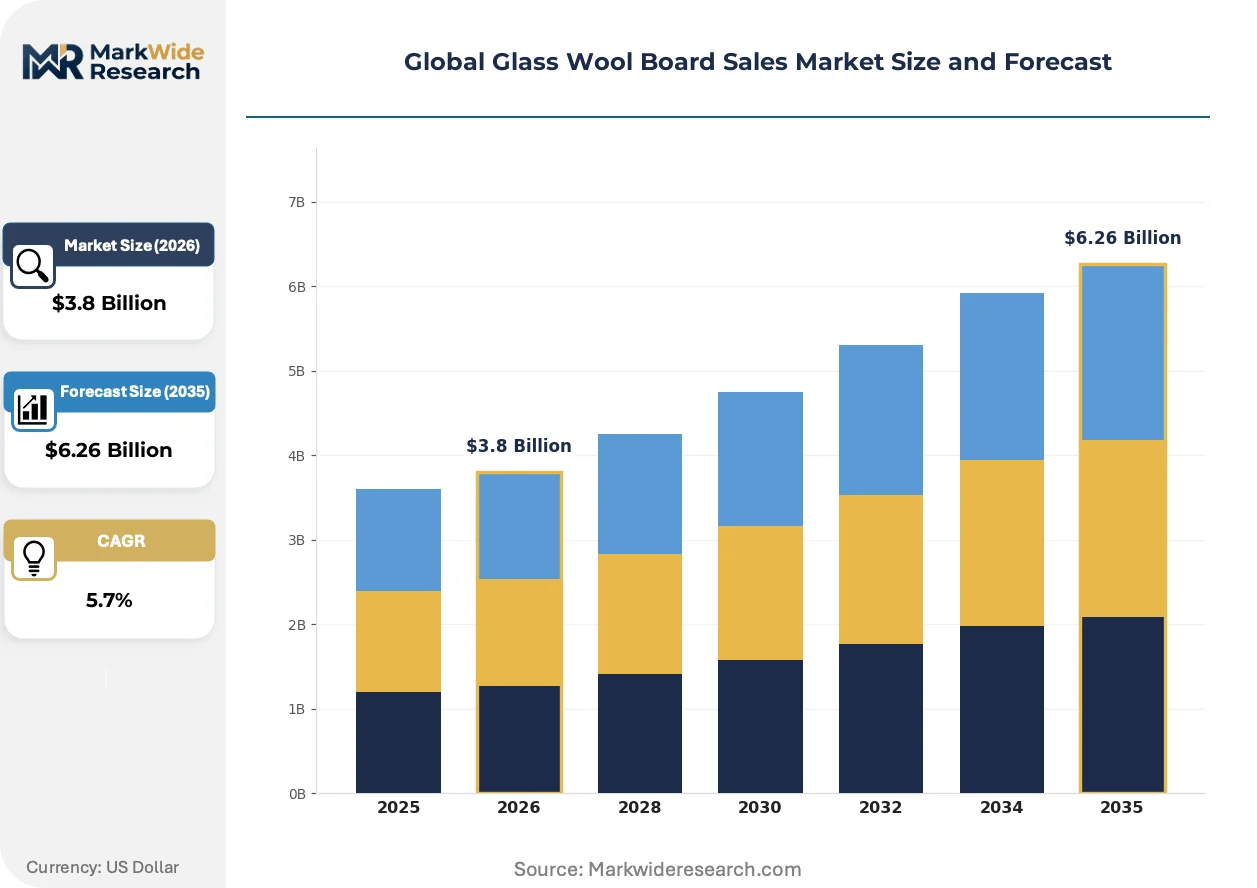
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Boards, Flexible Panels, Acoustic Tiles, Fireproof Sheets End Use Industry: Construction, HVAC, Automotive, Marine Thickness: 25mm, 50mm, 75mm, 100mm Density: 10kg/m³, 15kg/m³, 20kg/m³, 25kg/m³ |
| Companies Covered | Owens Corning, Saint-Gobain, Knauf Insulation, Johns Manville, Rockwool International, CertainTeed, Atlas Roofing, PPG Industries, DBW Advanced Fiber Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glass Wool Board Sales Market Emerging Trajectories
Automation of fiber-forming and binder application processes is compressing unit economics while regulatory chemistry restrictions are rewriting material specifications. Demand-side digitization is shortening specification cycles and concentrating purchasing power.
Closed-loop rotary spinning control systems is automating fiber-diameter consistency to within two microns across production runs. Commercial roofing contractors in Germany and the Netherlands are specifying these tighter-tolerance boards for curtain-wall assemblies where thermal bridging liability drives insurance premiums. The technology is automating quality-assurance labor out of mid-tier manufacturing, compressing margin structures for producers without sensor-integrated lines.
REACH Annex XVII restrictions on formaldehyde-releasing substances are forcing binder reformulation across European supply chains. Manufacturers face eighteen-month validation cycles for phenolic resin replacements while maintaining fire-reaction classifications under EN 13501. High-density acoustic boards for cinema and studio construction face the steepest compliance cost concentration due to stricter indoor air quality mandates in France and Belgium.
Architects and quantity surveyors are consolidating specification decisions through centralized procurement platforms that rank suppliers by embedded carbon and cost-per-thermal-unit metrics. National homebuilders in the United States are shifting from distributor-mediated purchasing to direct mill contracts that lock volume commitments against index-linked silica pricing. This concentration is most visible in Texas and Florida residential construction, where national builders command sufficient scale to disintermediate regional insulation distributors.
Global Glass Wool Board Sales Market Segmentation
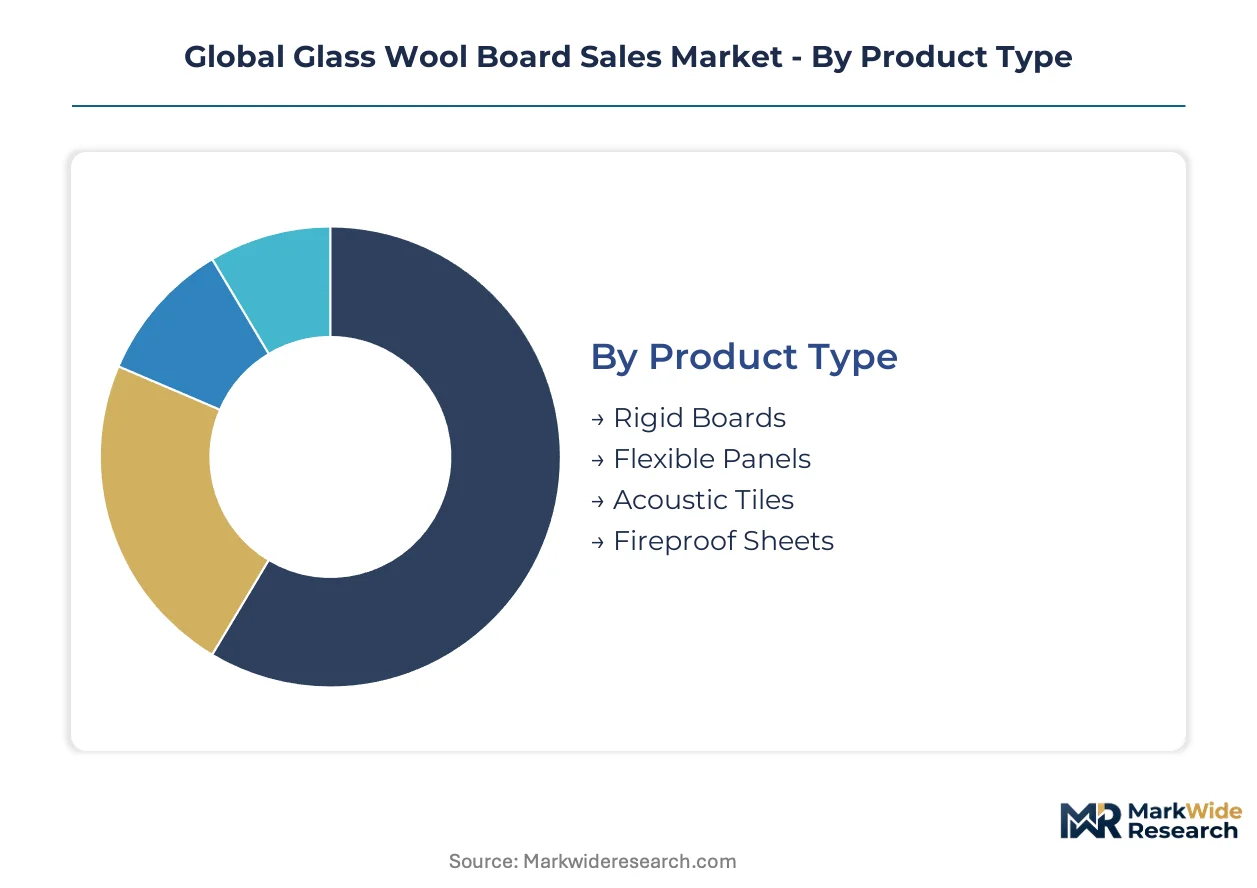
Glass wool board specifications diverge sharply across thermal, acoustic, and fire-containment applications, with product architecture and dimensional attributes determining access to premium specification channels versus commodity construction markets.
Product Type:
Structural rigidity and binder chemistry differentiate performance tiers and installation economics across built environment applications.
- Rigid Boards:Bonded glass fiber sheets with phenolic resin binders achieve compressive strength for load-bearing roofing assemblies. German commercial contractors specify these for curtain-wall spandrel panels where dimensional stability under mechanical fastening prevents thermal bridging liability.
- Acoustic Tiles:High-density formulations with optimized fiber orientation target sound absorption coefficients in open-plan office retrofits. Paris and London fit-out contractors are pulling these volumes into ceiling grid replacements that integrate thermal and acoustic functions.
- Flexible Panels:Lower-density blankets conform to irregular attic framing in residential construction. Price competition from polymer foams limits margin expansion in single-family applications across Texas and Florida.
- Fireproof Sheets:Engineered non-combustible grades meet EN 13501 A1 classifications for high-occupancy structures. Mumbai and Delhi commercial tower specifications are accelerating adoption as India's BIS standards converge toward stricter fire-reaction classes.
Rigid boards lead on scale; acoustic tiles lead on momentum.
End Use Industry:
Application-specific performance certification requirements reshape competitive access and pricing power across vertical demand pools.
- Construction:Building envelope and interior partition specifications dominate volume, with EU Green Deal U-value mandates compressing allowable thermal transmittance in German and Dutch commercial facades.
- HVAC:Duct lining and equipment insulation demand moisture-resistant facings. REACH formaldehyde restrictions are disqualifying legacy phenolic binders in Nordic specification channels.
- Automotive:Lightweight thermal and acoustic management for electric vehicle battery enclosures. Japanese OEMs through METI-guided supply chains favor thin-profile high-density formats.
- Marine:Fire-containment and thermal insulation for ship compartmentation. IMO SOLAS regulations drive non-combustible material substitution in South Korean and Chinese shipyard output.
Construction commands absolute volume; HVAC specifications are climbing fastest on regulatory chemistry reformulation.
Thickness:
Dimensional standardization aligns with modular framing systems and thermal resistance targets across regional building codes.
- 50mm:The specification workhorse for commercial roofing and curtain-wall cavities, balancing R-value delivery with structural dead load limits in German and Dutch assemblies.
- 100mm:Maximum standard thickness for high-performance envelopes meeting passive house thermal bridges. Tier-one Chinese cities specify these for facade retrofit projects replacing legacy loose-fill systems.
- 25mm:Thin-profile applications for HVAC duct lining and constrained cavity depths. Japanese commercial HVAC retrofits favor this dimension for space-constrained mechanical rooms.
- 75mm:Intermediate specification for residential attic upgrades where rafter depth permits incremental R-value stacking. US national homebuilder direct contracts concentrate volume here.
50mm thickness anchors installed base; 100mm specifications are expanding most quickly on code tightening.
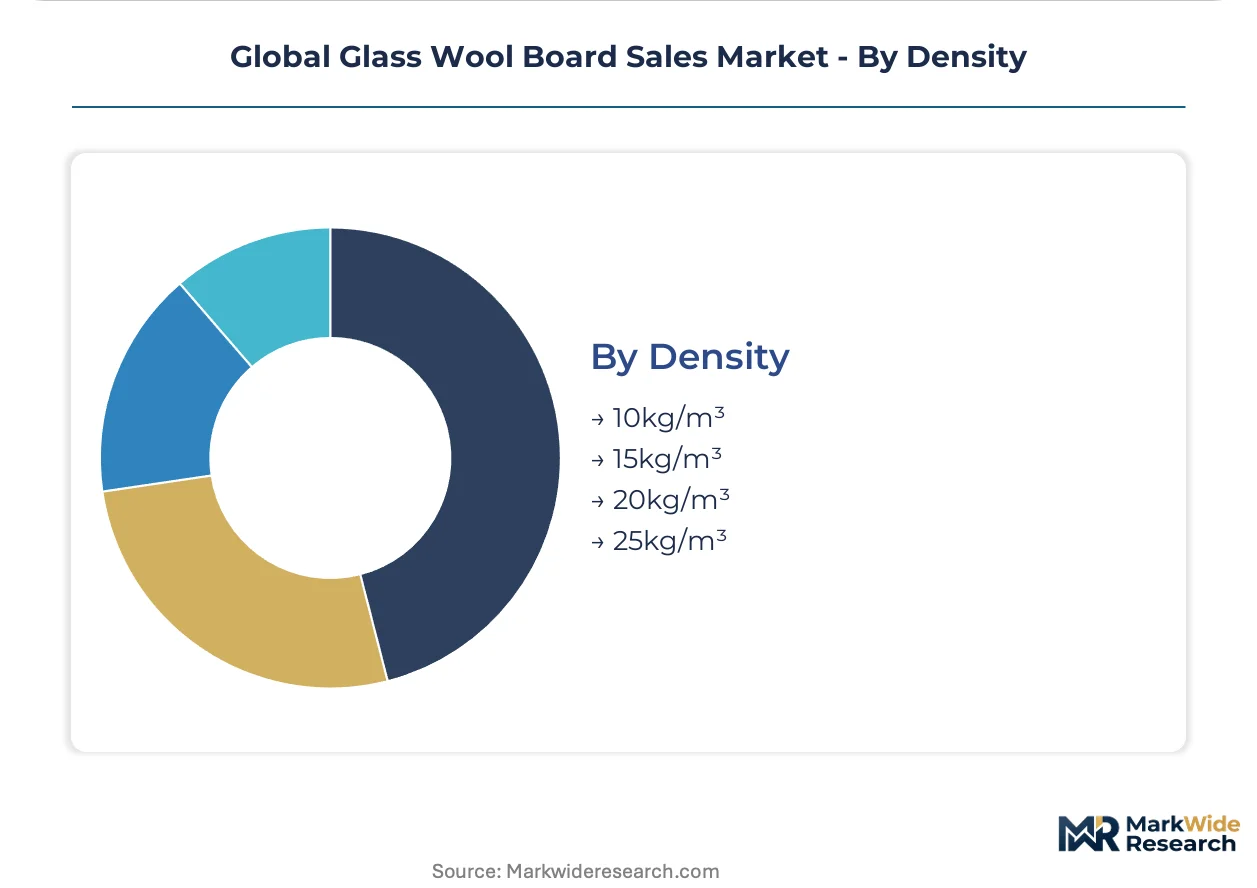
Density:
Fiber packing and binder loading determine mechanical properties, acoustic performance, and fire-reaction classification economics.
- 25kg/m³:High-density acoustic formats for cinema and studio construction where sound absorption coefficients must meet precise NRC targets. Knauf Insulation specializes here.
- 15kg/m³:The commercial roofing standard balancing thermal lambda consistency with installed weight. German contractors specify this density for flat roof assemblies under EPD membrane systems.
- 10kg/m³:Lowest-density commodity grade for residential attic loose-fill alternatives. Price pressure from expanded polystyrene caps specification in US single-family construction.
- 20kg/m³:Mid-density bridging applications where moderate compressive strength meets thermal performance. Chinese tier-one city retrofits are absorbing volumes here for facade board replacement.
15kg/m³ density dominates specification volume; 25kg/m³ acoustic grades command steepest expansion trajectory on premium fit-out demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German commercial construction clusters anchor glass wool board specification intensity, with EU Green Deal mandates compressing U-values across building envelopes and pulling rigid board volumes into facade renovation channels.
United States
National homebuilders in Texas and Florida are consolidating procurement through direct mill contracts that lock volume commitments against index-linked silica pricing. EPA energy-efficiency guidelines tighten thermal transmittance thresholds for residential envelopes. The Southeast construction corridor absorbs flexible panel volumes for attic applications where price competition from polymer foams remains acute.
Germany
Commercial roofing contractors specify 15kg/m³ density rigid boards for flat roof assemblies under EPD membrane systems. REACH Annex XVII formaldehyde restrictions disqualify legacy phenolic binders, forcing eighteen-month validation cycles for bio-based resin replacements. The Rhine-Ruhr industrial belt concentrates specification decisions for curtain-wall spandrel panels where dimensional stability prevents thermal bridging liability.
China
Tier-one cities including Shanghai and Beijing accelerate building energy audits, pulling rigid board volumes into facade renovation projects that previously relied on loose-fill alternatives. GB standards for building energy conservation tighten permissible thermal transmittance thresholds. The Yangtze River Delta manufacturing base supplies rotary-spun fiber to domestic converters facing silica sand sourcing concentration in select inland provinces.
India
Mumbai and Delhi commercial tower specifications accelerate adoption of fireproof sheet grades as BIS standards converge toward stricter non-combustibility classifications. High-occupancy structure mandates favor glass wool over polymer foam alternatives. The National Capital Region construction cluster drives demand for 100mm thickness boards in facade retrofit projects replacing legacy insulation systems.
Japan
METI building codes guide Japanese OEM supply chains toward thin-profile high-density formats for electric vehicle battery enclosure thermal management. Commercial HVAC retrofits in Tokyo favor 25mm thickness for space-constrained mechanical rooms. The Kanto industrial corridor integrates glass wool specifications into METI-guided procurement frameworks for high-occupancy structures.
Global Glass Wool Board Sales Market Vendor Landscape
Global majors compete with regional champions across manufacturing scale and specification channel access, producing a tiered structure where integrated fiber-spinning capabilities determine margin resilience. Consolidation concentrates among manufacturers with captive silica sourcing and phenolic resin reformulation expertise. Three archetypes dominate: North American scale players anchoring national homebuilder contracts, European integrated glass-to-fiber operators sustaining margin control, and Asian converters serving retrofit-driven tier-one city demand. Capacity expansion and bio-based binder chemistry partnerships represent the dominant competitive vectors.
Within the integrated manufacturing tier, Owens Corning and Saint-Gobain exemplify divergent strategic positions. Owens Corning occupies a scale-driven archetype leveraging North American production footprint to anchor supply contracts with volume purchasers. Saint-Gobain represents the vertically integrated European model with glass-to-fiber operations that buffer margin exposure across volatile input markets. Knauf Insulation sits within the specialization archetype, anchoring premium positioning through high-density acoustic format expertise that commands specification in cinema and studio construction channels.
| Leading Market Players |
|---|
| Owens Corning |
| Saint-Gobain |
| Knauf Insulation |
| Johns Manville |
| Rockwool International |
| CertainTeed |
| Atlas Roofing |
| PPG Industries |
| DBW Advanced Fiber Technologies |
| Others |
Supply Flow & Price Mechanics
EU Green Deal U-value mandates compressing thermal transmittance thresholds are forcing glass wool board converters toward higher-density rigid formats, compelling supply base consolidation around integrated fiber-spinning capabilities and reshaping pricing power toward manufacturers with captive silica sourcing.
Pricing Analysis
Silica sand freight-cost volatility passes through to board pricing within one to two quarters, compressing margins for converters without long-term offtake agreements with Egyptian or Chinese deposit operators. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with CE-marked acoustic boards commanding substantial premiums over commodity attic panels. Price erosion runs through flexible panel segments as expanded polystyrene substitutes capture single-family residential volume in Texas and Florida. National homebuilders exhibit lowest price sensitivity due to direct mill contracting power, while regional distributors face acute margin pressure from polymer foam competition.
Supply Chain Analysis
Skilled furnace operators and polymer chemists concentrate in Germany's Rhine-Ruhr belt and China's Yangtze River Delta, constraining rotary line expansion for mid-capitalization producers lacking apprenticeship pipeline access. Manufacturing gravity centers on China, Germany, and the United States, with high-purity silica sourcing anchored in select Chinese provinces and Egyptian desert deposits. The supply chain draws from phenolic resin systems, bio-based binder alternatives, and spinner disc alloys, with single-source vulnerability concentrated in formaldehyde-free resin formulation expertise. Distribution runs through national homebuilder direct contracts and specification-channel architects, bypassing traditional regional insulation distributors in high-volume corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass wool board markets reward geographic arbitrage between EU REACH-mandated bio-based binder premiums and China's tier-one city retrofit code acceleration, with regulatory cost differentials exceeding manufacturing labor advantages.
For Market Incumbents: Deploy captive silica sourcing to lock supply contracts against index-linked pricing volatility. Owens Corning and Saint-Gobain should accelerate phenolic resin reformulation partnerships to preempt REACH Annex XVII disqualification of legacy chemistries. Capacity addition in India's National Capital Region captures BIS fire-reaction convergence before specification channels crystallize around established suppliers. For New Entrants and Emerging Players: Bio-based binder chemistry expertise offers the most penetrable wedge for Nordic specification channels where ECHA formaldehyde limits have already disqualified incumbent formulations. White-space targets include Mumbai commercial tower fireproof sheet demand and Paris acoustic tile retrofit channels. A technology-first go-to-market angle embedding parametric thermal datasets in Revit libraries compresses architect decision cycles against established distributors. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing integrated glass-to-fiber operations and validated bio-based resin systems. Long-term viability over the next decade hinges on regulatory chemistry convergence rather than manufacturing scale alone. Acquisition targets should demonstrate spinner disc replacement capability and multi-jurisdiction certification stacking experience. Watch India's BIS standard harmonization with EN 13501 as the inflection signal for fire-containment grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Sourcing | Captive Egyptian or Chinese deposit access insulates margin from freight-cost volatility and geopolitical interruption. |
| Bio-Based Resin Partnership | Eighteen-month REACH validation cycles favor early movers in phenolic replacement chemistry for Nordic premium channels. |
| Rotary Line Automation Upgrade | Closed-loop fiber-diameter control within two microns qualifies German commercial roofing contractors for curtain-wall specifications. |
| Digital Specification Platform Embedding | Revit and ArchiCAD thermal performance datasets compress architect decision cycles and concentrate purchasing power. |
| India Fireproof Sheet Capacity Buildout | BIS non-combustibility convergence in Mumbai and Delhi commercial towers opens specification pathways before channels lock. |
Methodological Framework
Direct dialogue with plant managers at rotary spinning facilities, procurement leads at national homebuilders, specification architects in German commercial construction, and ECHA regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from EU REACH Annex XVII filings, Chinese GB standard energy conservation disclosures, SEC 10-K raw material cost disclosures, and customs trade data tracking silica sand import flows. Bottom-up volume estimates from individual production facility throughput triangulated against top-down construction spending elasticity models.
Segment-level value outputs across the projection horizon reflect disaggregated modeling by product architecture, end-use certification requirements, thickness standardization, and density-grade positioning. The analytical framework incorporated rotary process energy intensity curves, binder chemistry cost transitions, and regional code-tightening schedules without year-specific anchoring. CAGRs emerged from logistic diffusion curves fitted to retrofit penetration rates and new-build specification velocity across tier-one Chinese cities and German commercial clusters.
The model holds under continued regulatory tightening trajectories; deviation in natural gas price stability or silica sand export restrictions would shift margin concentration toward integrated manufacturers. Forecasts reflect assumptions about REACH implementation pacing and BIS standard convergence velocity. Material deviation in bio-based resin validation timelines or polymer foam substitution elasticity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Magnet Rings Market
Industrial Materials
Welding Consumables Market
Industrial Materials
High Purity Quartz Market
Industrial Materials
Static Mixer Market
Industrial Materials
High Performance Random Packing Market
Industrial Materials
Bamboo Products Market
Industrial Materials
Mineral Processing Equipment Market
Industrial Materials
Extruders Market
Industrial Materials
Polycarbonate Panels Market
Industrial Materials
Grouting Materials Market
Industrial Materials
Industrial Absorbents Market
Industrial Materials
Industrial Wax Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Self Locking Nuts Market
Industrial Materials
GCC Heat Treating Market