
 Global High Temperature Gaskets Market | 2026-2036
Global High Temperature Gaskets Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Temperature Gaskets Market Foresight
Specialized industrial distributors is reshaping how high-temperature gasket specifications reach end-users, with technical sales engineers now embedding directly at plant procurement offices. KLINGER Holding GmbH leverages its European manufacturing base to sustain long-term supply contracts with refinery operators. Flexitallic Group anchors its position through deep specialization in spiral-wound and kammprofile designs for critical pressure boundaries. Parker-Hannifin Corporation competes by extending its fluid power distribution network into sealing system bundling.
High temperature gaskets are engineered sealing elements manufactured from graphite, metal, ceramic fiber, or PTFE composites, designed to maintain mechanical integrity and leak-free performance at sustained temperatures exceeding 300°C in flanged joints and pressure vessels. Their primary purpose is to prevent fugitive emissions, thermal cycling failure, and process fluid loss in energy infrastructure, chemical reactors, and aerospace propulsion systems. Graphite and metal segments dominate current procurement volumes due to proven performance in steam and hydrocarbon service, while ceramic fiber formulations represent the fastest-growing material class as operators push past 800°C thresholds in gas turbines and solid oxide fuel cell assemblies. Spiral wound and kammprofile product types capture the deepest margin pools because they command engineering-intensive customization for ASME pressure classes and require certified welding of winding metals.
EPA emissions enforcement under the Clean Air Act and REACH chemical restrictions through ECHA constrain elastomer and PTFE formulation choices, compelling reformulation toward halogen-free and low-VOC binder systems. China's SAMR enforces GB standards for pressure equipment sealing that effectively block uncertified imports from power sector tenders. India's CEA mandates boiler gasket replacement intervals that sustain aftermarket demand cycles. Stakeholders must monitor how evolving carbon border adjustments and material passport requirements alter supplier qualification timelines across jurisdictions.
Market Dynamics
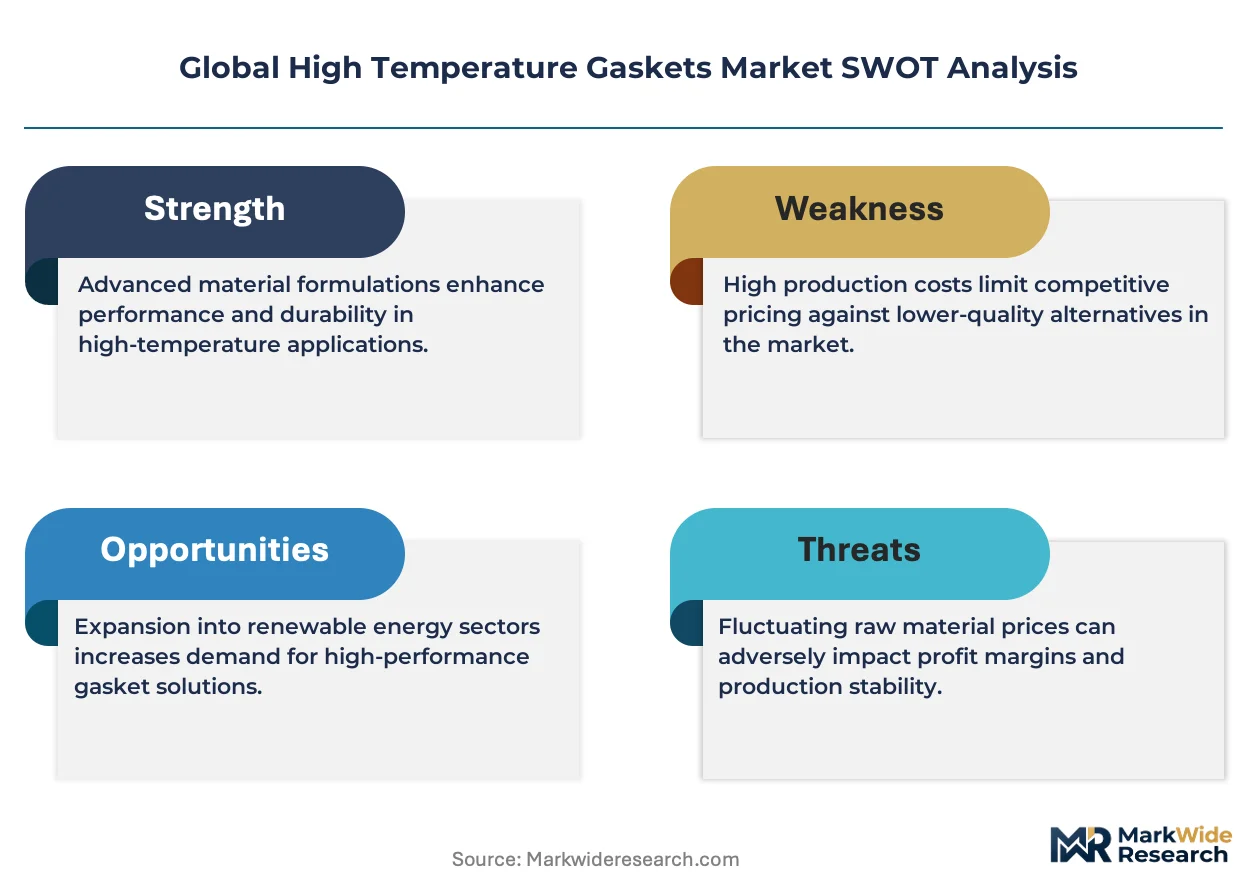
Coal-to-gas turbine conversions across Asia-Pacific power infrastructure are compressing replacement cycles and forcing material upgrades from compressed asbestos to graphite-ceramic composites, restructuring procurement specifications at the engineering level.
Growth Catalysts
- EPA Clean Air Act enforcement:Fugitive emissions monitoring mandates at US refineries accelerate graphite gasket replacement schedules in flanged hydrocarbon service.
- China's industrial corridor expansion:Petrochemical cluster buildouts in Shandong and Jiangsu provinces sustain bulk procurement volumes for spiral-wound pressure seals.
- Solid oxide fuel cell commercialization:Ceramic fiber gasket architectures rated above 800°C capture design wins in distributed hydrogen power systems.
Market Restraints
- Graphite price volatility:Synthetic graphite electrode competition from electric vehicle battery anode production constrains industrial seal feedstock allocation.
- REACH chemical restrictions:ECHA halogenated compound limitations block legacy PTFE binder formulations from EU power sector tenders.
- Specialized welding capacity scarcity:Certified 316L stainless winding wire joining for ASME Class 900+ ratings concentrates among German and Japanese metalworkers.
Strategic Opportunities
- India's CEA boiler maintenance mandates:Mandatory gasket replacement intervals create predictable aftermarket demand cycles for domestic distributors.
- Hydrogen pipeline infrastructure:High-purity hydrogen embrittlement-resistant metal gasket designs open specification windows in Netherlands and Germany transport projects.
- Technical sales engineer embedding:Specialized industrial distributors place application engineers directly at Saudi Aramco and ADNOC procurement offices to influence specification standards.
Industry Challenges
- ASME BPVC Section VIII certification timelines:Pressure vessel gasket qualification cycles extend 14-18 months, delaying new material commercialization.
- Multi-material stack integration:Ceramic fiber-graphite hybrid gaskets require thermal expansion coefficient matching that complicates field installation protocols.
- Welding metallurgist shortage:Inconel 625 winding wire joining expertise concentrates among aging specialist workforces in Pittsburgh and Dusseldorf industrial basins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Temperature Gaskets Market |
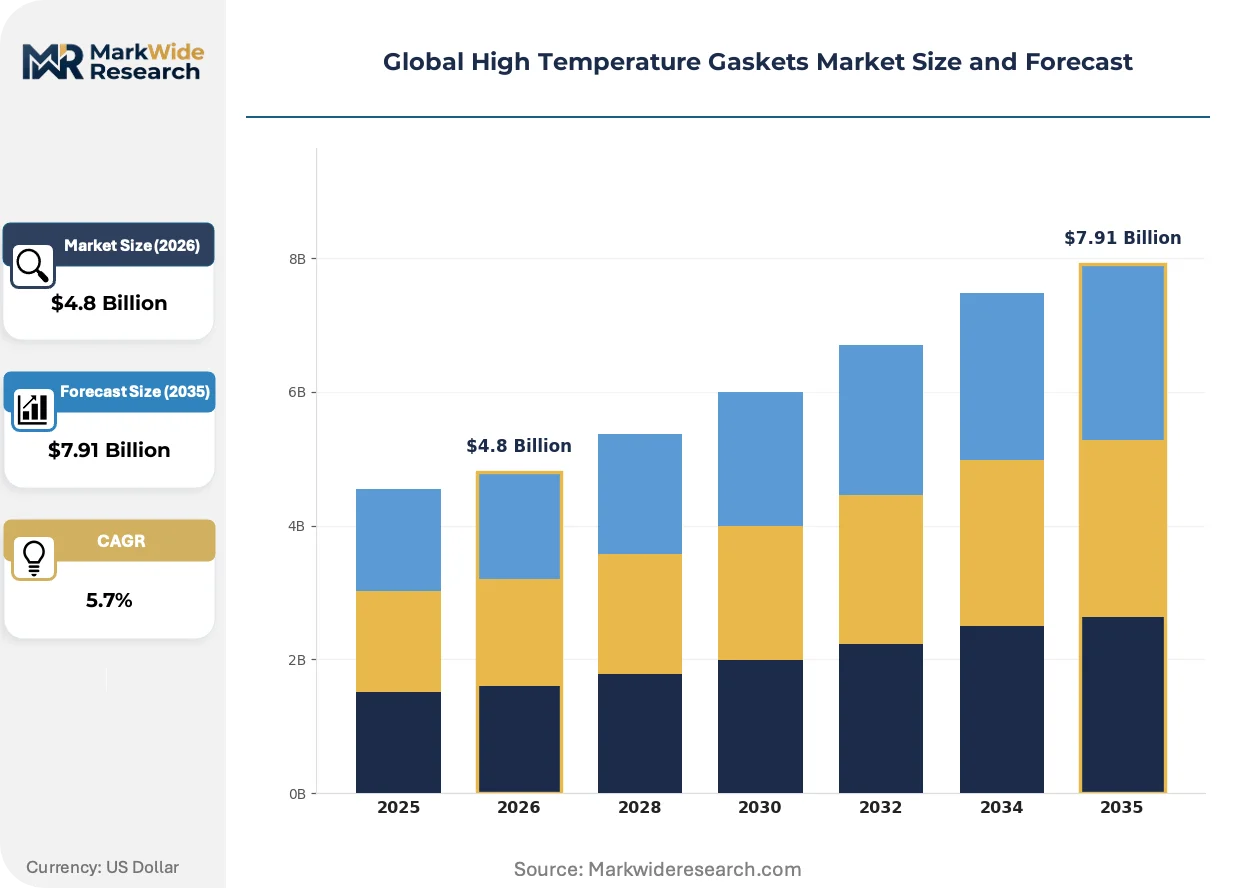
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Graphite, Elastomers, PTFE, Metal, Ceramic Fiber, Aramid Application: Power Generation, Chemical Processing, Aerospace, Oil Refining, Marine, HVAC Industry Vertical: Energy Production, Petrochemical, Aviation, Shipbuilding, HVAC Manufacturing, Industrial Equipment Product Type: Ring Gaskets, Spiral Wound, Jacketed, Kammprofile, Sheet, Metallic |
| Companies Covered | KLINGER Holding GmbH, Advanced Sealing Inc., Flexitallic Group, Parker-Hannifin Corporation, Auburn Manufacturing, Inc., TEADIT International Produktions GmbH, 3M Company, Teadit Group, Garlock Sealing Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Temperature Gaskets Market Shifts & Advancements
Digital specification tools and predictive maintenance analytics are compressing traditional distributor-buyer relationships, while material science advances push thermal performance boundaries past conventional graphite limits.
Multi-layer graphene-reinforced graphite composites are virtualizing conventional flexible graphite sheet architectures in gas turbine combustion seal applications. Siemens Energy and Mitsubishi Heavy Industries specify these materials for 650°C+ continuous duty in combined-cycle plants. The technology is virtualizing legacy compressed graphite procurement patterns by enabling thinner, higher-pressure designs that reduce flange load requirements.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force reformulation of PTFE-based gasket binders across EU chemical processing installations. ECHA enforcement timelines compress supplier qualification windows to 24 months. German and French petrochemical operators now require halogen-free certification documentation for all new seal procurement.
Plant reliability engineering teams now specify outcome-based gasket performance contracts rather than unit-price purchasing. Saudi Aramco's Jazan refinery and Reliance Industries' Jamnagar complex bundle seal supply with leakage-rate guarantees and predictive replacement scheduling. This model concentrates volume with technically integrated suppliers capable of thermal cycling failure modeling.
Global High Temperature Gaskets Market Segmentation
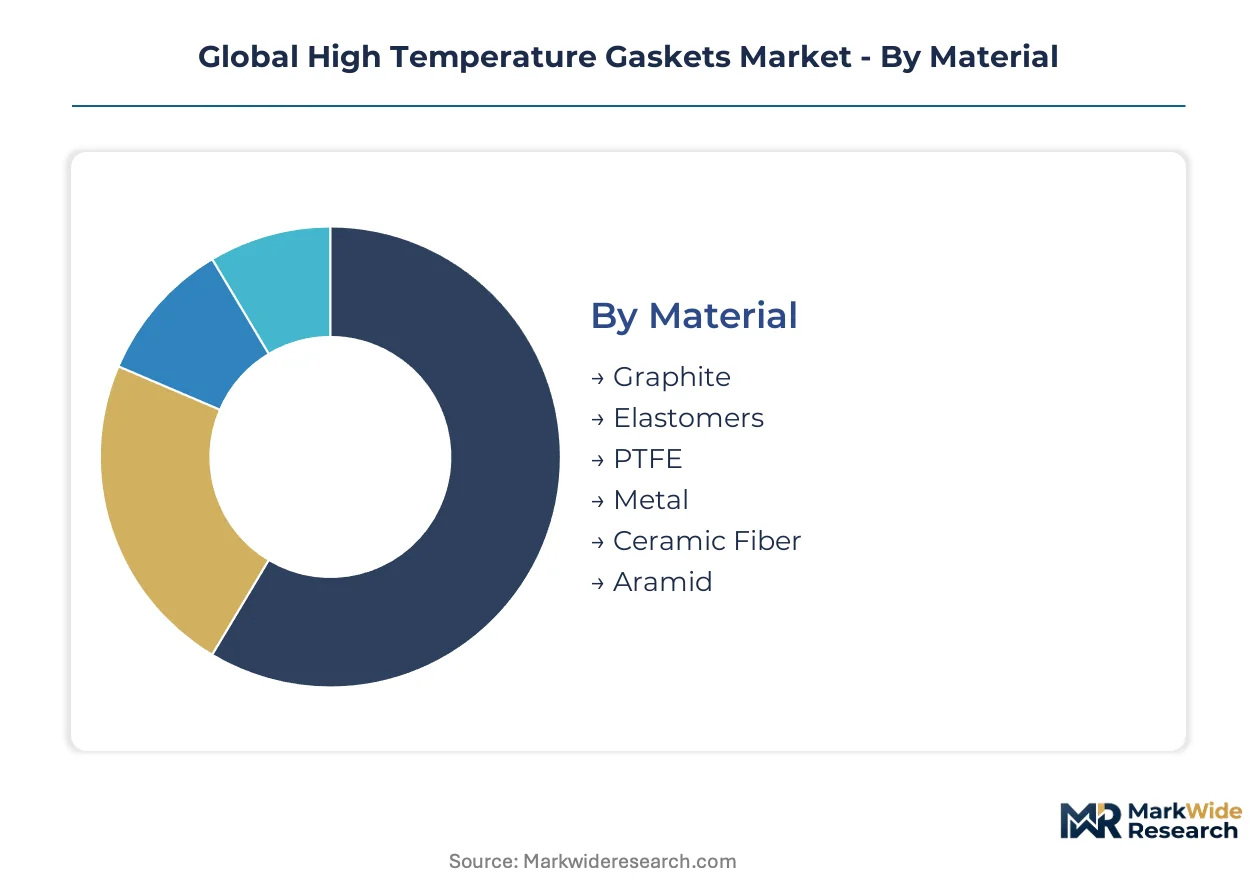
High temperature gasket procurement splits across material chemistry, pressure-boundary geometry, and end-use thermal severity. Specification engineers weight ASME pressure ratings against sustained operating temperatures when matching product types to application demands.
Material:
Cost tier stratification in raw material inputs directly shapes procurement budgets and replacement cycles across industrial sectors.
- Graphite:Flexible graphite sheet and laminated composites dominate steam and hydrocarbon service through 550°C continuous duty. China's petrochemical clusters in Shandong and Jiangsu provinces drive bulk procurement volumes for refinery flange assemblies.
- Metal:316L stainless steel and Inconel 625 wound or solid metal designs withstand pressure cycling in ASME Class 600+ ratings. German and Japanese certified welding shops concentrate supply capacity for critical nuclear and chemical pressure boundaries.
- Ceramic Fiber:Alumina-silica and alkaline earth silicate formulations rated above 800°C serve gas turbine combustion seals and solid oxide fuel cell stacks.
- PTFE:Virgin and filled polytetrafluoroethylene sheets handle corrosive chemical service below 260°C threshold.
- Elastomers:Fluoroelastomer and silicone compounds fill low-pressure, moderate-temperature HVAC and marine applications.
- Aramid:Synthetic fiber-reinforced compressed sheets substitute for legacy asbestos in pulp and paper processing equipment.
Graphite holds installed capacity. Ceramic fiber is rotating up the share rankings.
Application:
Volume concentrates where thermal cycling severity and emissions compliance intersect to compress replacement intervals.
- Power Generation:Coal-to-gas turbine conversions across Asia-Pacific force material upgrades from compressed asbestos to graphite-ceramic hybrids. India's CEA mandates boiler gasket replacement cycles that sustain predictable aftermarket demand.
- Chemical Processing:REACH Annex XVII halogen restrictions block legacy PTFE formulations from EU tenders. German and French operators now require halogen-free certification documentation for all new seal procurement.
- Oil Refining:EPA Clean Air Act fugitive emissions monitoring accelerates graphite gasket replacement schedules in US flanged hydrocarbon service.
- Aerospace:Propulsion system seals for turbofan and rocket motor applications demand Inconel or ceramic fiber architectures.
- Marine:Classification society rules for LNG carrier cargo containment systems specify cryogenic-to-ambient thermal cycling resistance.
- HVAC:Commercial and industrial heating equipment specifies compressed fiber and elastomer gaskets for sub-300°C duct and heat exchanger joints.
Power generation commands replacement frequency. Chemical processing is climbing the fastest on regulatory-driven material turnover.
Industry Vertical:
Customer type differentiation separates specification-influencing OEMs from price-sensitive maintenance contractors.
- Energy Production:Utility and independent power producers bundle seal supply with leakage-rate guarantees. Saudi Aramco's Jazan refinery and Reliance Industries' Jamnagar complex specify outcome-based performance contracts.
- Petrochemical:Integrated refinery-chemical complexes in China's industrial corridor sustain engineering-intensive customization demand for spiral-wound and kammprofile designs.
- Aviation:OEM propulsion system manufacturers specify certified materials for turbine hot section seals.
- Shipbuilding:Korean and Chinese yards specify marine classification society-approved materials for engine room and cargo system sealing.
- HVAC Manufacturing:Original equipment producers source commodity compressed fiber and elastomer sheets in high volume.
- Industrial Equipment:General machinery builders specify standard ring and sheet gaskets for pumps, valves, and pressure vessel flanges.
Energy production concentrates technical sales engineer embedding. Petrochemical is gaining share fastest on cluster expansion.
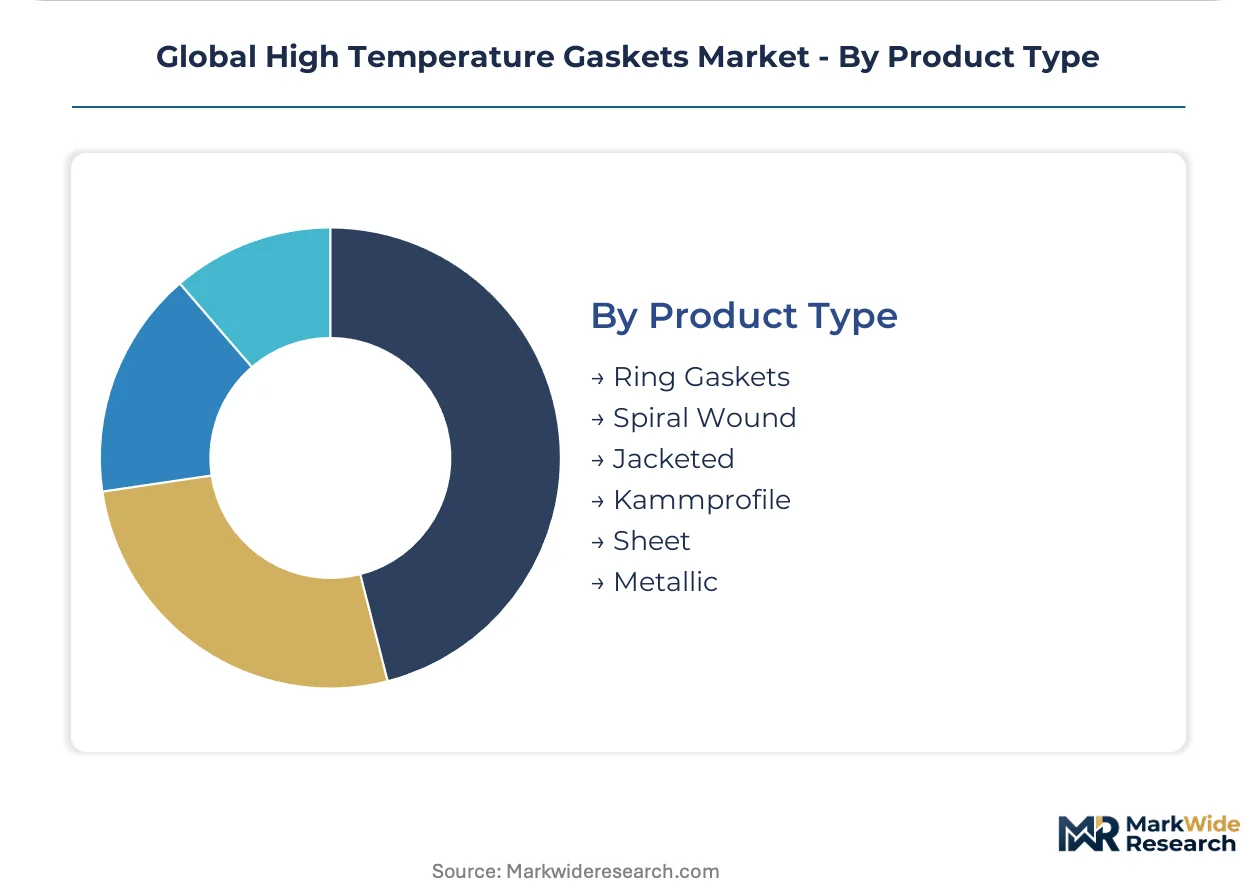
Product Type:
Margin structure varies with engineering intensity and certification burden in pressure-boundary design.
- Spiral Wound:V-shaped metal winding with graphite or PTFE filler combines resilience and recovery for thermal cycling service. Flexitallic Group anchors market position through deep specialization in critical pressure boundary applications.
- Kammprofile:Serrated metal core with soft facing layers delivers high bolt load distribution in heat exchanger and vessel flanges. ASME Class 900+ ratings require certified welding of winding metals that concentrates among German and Japanese suppliers.
- Ring Gaskets:Solid metal oval and octagonal designs seal high-pressure wellhead and valve bonnet applications.
- Jacketed:Metal-encased compressible filler suits chemical and food processing where corrosion resistance is paramount.
- Sheet:Compressed fiber, graphite, and PTFE sheets enable field fabrication of custom shapes for maintenance repair.
- Metallic:Solid metal gaskets including lens and weld ring designs serve extreme pressure-temperature combinations.
Spiral wound holds installed capacity. Kammprofile is rotating up the share rankings on heat exchanger specification wins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The TurkStream pipeline corridor underwrites Russia's energy bridge to Turkey and Southeast Europe, while China's West-East Gas Pipeline network anchors Asia-Pacific infrastructure demand for high-temperature sealing systems.
United States
EPA Clean Air Act fugitive emissions monitoring accelerates graphite gasket replacement at Gulf Coast refineries. The Department of Energy's hydrogen hub program funds pipeline sealing research. Houston's petrochemical corridor sustains bulk procurement for ASME Class 600+ pressure boundaries.
Germany
ECHA REACH Annex XVII halogen restrictions block legacy PTFE formulations from chemical sector tenders. The National Hydrogen Strategy funds high-purity hydrogen transport infrastructure. Ruhr industrial basin operators now require halogen-free certification for all new seal procurement.
China
SAMR GB standards for pressure equipment sealing exclude uncertified imports from power sector tenders. Dual carbon goals accelerate coal-to-gas turbine conversions. Shandong and Jiangsu petrochemical clusters drive engineering-intensive customization demand for spiral-wound designs.
India
CEA mandates boiler gasket replacement intervals that sustain predictable aftermarket demand cycles. PLI scheme incentives support domestic manufacturing scale-up. Gujarat's Jamnagar refining complex bundles seal supply with leakage-rate guarantees and predictive maintenance scheduling.
Saudi Arabia
SFDA chemical safety standards constrain elastomer formulation choices in downstream processing. Vision 2030 industrial cluster development expands refinery-chemical integration. Jazan refinery operators embed technical sales engineers directly at procurement offices to influence specification standards.
Global High Temperature Gaskets Market Competitive Landscape
On the supply side, the industry is moderately consolidated around specialized industrial distributors and material-specific fabricators. European and North American metalworkers concentrate certified welding capacity for critical pressure ratings. Strategic archetypes include spiral-wound specialists, graphite composite formulators, and fluid power distributors extending into sealing system bundling. Dominant competitive moves involve technical sales engineer embedding at major procurement offices and outcome-based performance contracting that bundles supply with leakage guarantees.
Within the European manufacturing tier, KLINGER Holding GmbH and Flexitallic Group occupy positions anchored by long-term supply relationships with refinery operators. Parker-Hannifin Corporation exemplifies the distribution-network extension archetype, leveraging fluid power infrastructure to bundle sealing systems. These three represent distinct strategic vectors: specialized fabrication, pressure-boundary engineering, and integrated distribution.
| Leading Market Players |
|---|
| KLINGER Holding GmbH |
| Advanced Sealing Inc. |
| Flexitallic Group |
| Parker-Hannifin Corporation |
| Auburn Manufacturing, Inc. |
| TEADIT International Produktions GmbH |
| 3M Company |
| Teadit Group |
| Garlock Sealing Technologies |
| Others |
Supply & Pricing Matrix
Ruhr industrial basin metalworkers anchor graphite sheet and spiral-wound fabrication capacity, concentrating pricing power among German and Japanese certified welding shops serving ASME Class 900+ pressure boundaries. Their dominance in Inconel 625 winding wire joining creates tiered procurement economics where buyers trade lead time certainty against unit cost premiums.
Pricing Analysis
Volume-discount tiering structures separate spot purchasers from long-term offtake contractors in refinery and power generation procurement. Price differentiation hinges on ASME BPVC Section VIII certification grade and technical sales engineer embedding depth. Cost compression in standard graphite sheet grades is intensifying because Chinese petrochemical clusters in Shandong and Jiangsu negotiate consolidated annual volumes. Maintenance contractors prove most price-sensitive; integrated refinery-chemical complexes least so due to outcome-based performance contracting with leakage-rate guarantees.
Supply Chain Analysis
Tariff exposure between China and the United States disrupts flexible graphite feedstock flows for battery anode competition. Supply concentrates in Germany, Japan, and China for certified winding wire and ceramic fiber mat production. Raw material dependencies rest on synthetic graphite electrodes, alumina-silica ceramic fiber, and 316L stainless steel wire. Single-source vulnerability concentrates in Pittsburgh and Dusseldorf industrial basins where aging welding metallurgist workforces constrain capacity expansion. Distribution runs through specialized industrial distributors placing application engineers directly at procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates structural barriers. ASME certification timelines and REACH chemical compliance requirements cement incumbent positions through 14-18 month qualification cycles that block rapid competitive entry.
For Market Incumbents: Pre-empt ceramic fiber-graphite hybrid displacement by securing captive synthetic graphite feedstock arrangements before battery anode competition tightens industrial seal allocation. Accelerate technical sales engineer embedding at Saudi Aramco and ADNOC procurement offices to lock specification standards. Backward integration into multi-layer graphene-reinforced composite production in Ruhr or Pittsburgh industrial basins defends margin position against emerging Asian formulators. For New Entrants and Emerging Players: Pursue India's CEA-mandated boiler replacement aftermarket where predictable demand cycles and PLI scheme incentives support domestic manufacturing scale-up. Target solid oxide fuel cell gasket architectures rated above 800°C as the most penetrable segment, given nascent supplier concentration and hydrogen infrastructure buildout in Netherlands and Germany. Lead with halogen-free certification documentation to capture EU chemical processing tenders blocked from legacy PTFE formulations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized industrial distributors with technical sales engineer embedding and outcome-based performance contracting. Long-term viability over the projection horizon favors acquisition targets with certified welding capacity for nuclear and chemical pressure boundaries. Watch hydrogen pipeline infrastructure procurement windows in Germany and the Netherlands as the signal indicating inflection toward embrittlement-resistant metal gasket demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Graphite Feedstock | Battery anode competition from electric vehicle production constrains industrial seal material allocation. |
| Technical Sales Engineer Embedding at Procurement Offices | Saudi Aramco and ADNOC specification standards favor suppliers with direct engineering influence. |
| Halogen-Free Certification Investment | ECHA REACH Annex XVII restrictions block legacy PTFE binders from EU power sector tenders. |
| Ceramic Fiber-Graphene Composite R&D Scale-Up | Siemens Energy and Mitsubishi Heavy Industries specify 650°C+ materials for combined-cycle plants. |
| Long-Term Supply Agreement with Refinery Operators | KLINGER Holding GmbH sustains position through European manufacturing base relationships. |
Research Methodology
Initial hypotheses were tested against primary input from plant reliability engineers, refinery procurement managers, gasket fabrication technical directors, and aftermarket distribution channel heads and refined through secondary validation. Primary fieldwork combined structured interviews with maintenance directors at power generation facilities and chemical processing plants with technical discussions at specialized industrial distributors. Secondary sources included customs and trade data for graphite and ceramic fiber imports, ASME BPVC certification registry filings, EPA Clean Air Act enforcement documentation, and ECHA REACH restriction timelines. Bottom-up demand modeling from end-use procurement volumes triangulated against top-down supply capacity assessments across German, Japanese, and Chinese manufacturing bases.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled included material chemistry tier, pressure-boundary geometry type, end-use thermal severity class, and regional regulatory cluster. CAGRs were derived from installation base growth, replacement cycle compression, and material upgrade velocity. Industry-specific forecast inputs incorporated coal-to-gas turbine conversion timelines in Asia-Pacific and solid oxide fuel cell commercialization trajectories in distributed hydrogen systems.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, graphite electrode pricing, or carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline stability and welding metallurgist workforce availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Precipitated Silica Market
Industrial Materials
Wood Shavings Market
Industrial Materials
Elastomeric Couplings Market
Industrial Materials
High Performance Random Packing Market
Industrial Materials
United States Graphite Electrodes Market
Industrial Materials
Cork Material Market
Industrial Materials
Global Glass Wool Board Sales Market
Industrial Materials
Industrial Anti-Fatigue Mat Market
Industrial Materials
Silica Fume Market
Industrial Materials
Hose Reinforcement Wire Market
Industrial Materials
Fly Ash Market
Industrial Materials
Polycarbonate Panels Market
Industrial Materials
United States Ceramic Roller Bearings Market
Industrial Materials
Wire Drawing Dies Market
Industrial Materials
Warehouse Drums and Barrels Market
Industrial Materials
Twin Screw Extruders Market