
 Neoprene Foam Market | 2026-2036
Neoprene Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Neoprene Foam Market Intelligence
High-performance, low-VOC neoprene foam formulations are rotating the market toward specialized applications in automotive and electronics. This shift favors manufacturers with strong chemical engineering capabilities. DuPont de Nemours leverages its historical leadership in polymer science to offer premium grades for demanding environments. Arkema competes through its portfolio of specialty polymers, targeting niche industrial segments. Denka Company Limited anchors a significant portion of the supply chain in Asia, focusing on consistent quality for large-scale industrial buyers.
Neoprene foam is a synthetic rubber, polychloroprene, expanded into a cellular structure, creating a flexible and durable material. Its closed-cell variant is particularly valued for its inherent resistance to water, oil, ozone, and weathering, making it an excellent material for insulation and gasketing. The material's primary purpose is to provide reliable sealing, cushioning, and thermal insulation in harsh operational conditions. Closed Cell foam dominates the product landscape, underpinning its use in critical Sealing Solutions and Gasket Manufacturing, while open cell types find use in specific cushioning applications.
Regulatory frameworks significantly influence product development and market access. The European Chemicals Agency (ECHA) enforces REACH, which governs the use of chemical substances, impacting blowing agents and additives. In the United States, the EPA sets standards for emissions from polymer manufacturing facilities. Concurrently, China's GB standards dictate material safety and performance criteria for products sold domestically. Material suppliers must therefore innovate on formulations that meet these diverse compliance requirements without compromising performance.
Market Dynamics
The neoprene foam market is shaped by the fundamental tension between stringent environmental regulations governing chemical inputs and the persistent industrial demand for high-performance, durable materials. This dynamic forces innovation in polymer chemistry and manufacturing processes across the supply chain.
Growth Catalysts
- Marine Equipment Expansion:The need for materials with superior resistance to saltwater, UV radiation, and oil in marine applications, including wetsuits, buoyancy aids, and vessel seals, drives consistent consumption of closed-cell neoprene foam.
- Building Energy Codes:Stricter building energy efficiency standards in North America and Europe promote the use of high-performance insulation and sealing materials, including neoprene foam gaskets for window and door assemblies to minimize air leakage.
- Automotive Production in Germany:Germany's automotive industry specifies high-grade neoprene foam for engine bay insulation, gaskets, and seals to meet demanding thermal management and noise, vibration, and harshness (NVH) reduction requirements.
Market Restraints
- Raw Material Volatility:Prices for key feedstocks like butadiene, a petroleum derivative, are subject to fluctuations in the global oil market, creating cost instability for polychloroprene production and pressuring manufacturer margins.
- Substitution from EPDM and Silicone:In certain high-temperature or specialized sealing applications, ethylene propylene diene monomer (EPDM) and silicone foams present a substitution threat due to their distinct performance characteristics and sometimes lower cost profiles.
- REACH Compliance Burden:The European Union's REACH framework restricts the use of certain blowing agents, plasticizers, and flame retardants, compelling costly reformulation and certification cycles for products sold within the EU market.
Strategic Opportunities
- Electric Vehicle Battery Systems:The growing EV market creates an opportunity for neoprene foam as a material for battery pack seals, thermal runaway barriers, and vibration damping pads, where its sealing and fire-retardant properties are critical.
- Industrialization in Brazil:Brazil's expanding automotive and industrial manufacturing sectors represent an underpenetrated market for specialized sealing and insulation solutions, offering a new growth axis for neoprene foam suppliers.
- Bio-Based Formulations:Developing and commercializing neoprene foam derived from non-petroleum sources, such as limestone-based polychloroprene, opens access to customers prioritizing sustainability and a reduced carbon footprint in their supply chains.
Industry Challenges
- Divergent Global Standards:Manufacturers face significant complexity in ensuring a single product formulation complies with the distinct chemical safety and performance requirements of EU REACH, US EPA rules, and China's GB standards.
- Capital Investment for Greener Processes:Transitioning to low-VOC formulations and environmentally benign blowing agents requires substantial capital expenditure in new manufacturing equipment and process controls, posing a barrier for smaller producers.
- Chemical Engineering Talent Scarcity:A shortage of polymer scientists and chemical engineers skilled in developing formulations that balance performance, cost, and regulatory compliance constrains the pace of product innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neoprene Foam Market |
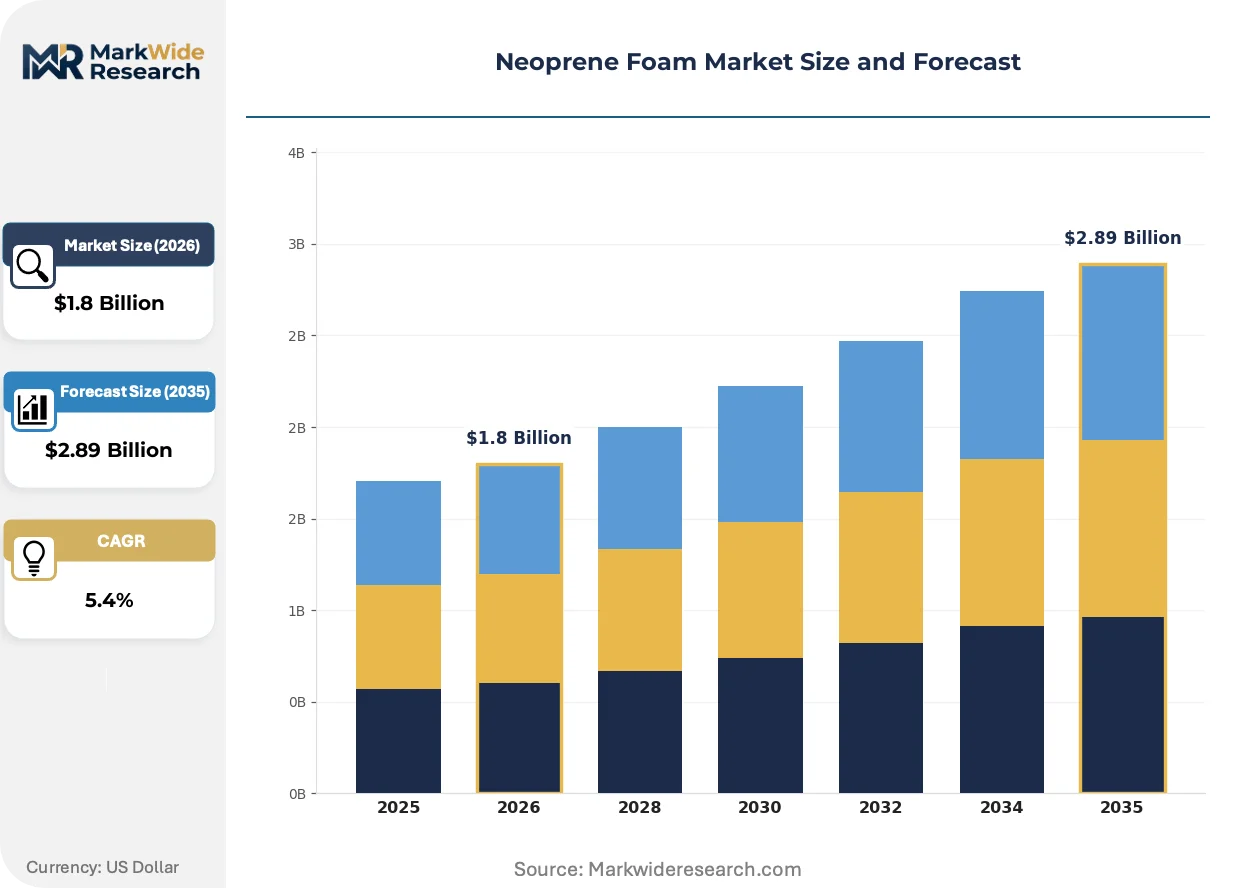
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Cell, Open Cell, Sheet, Block, Rolled Application: Sealing Solutions, Thermal Insulation, Cushioning Pads, Protective Gear, Gasket Manufacturing End User Industry: Construction, Marine Equipment, Furniture Manufacturing, Packaging Solutions, Electronics Form: Sheets, Rolls, Blocks, Molded Shapes, Custom Cut |
| Companies Covered | DuPont de Nemours, BASF, ChemChina, Arkema, LG Chem, DOW, Huntsman Corporation, Trelleborg, Denka Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neoprene Foam Market Strategic Shifts & Innovations
Material science advancements are steering the neoprene foam market toward formulations that satisfy both environmental mandates and extreme performance criteria. This evolution is most pronounced in the development of materials with lower volatile organic compound (VOC) profiles and reduced environmental impact.
Bio-based neoprene foam, derived from sources like limestone instead of petroleum, offers a functionally equivalent material with a more sustainable lifecycle. Automotive and consumer goods manufacturers are adopting these materials to meet corporate sustainability goals and appeal to environmentally conscious consumers. This trend is supplanting traditional petroleum-derived polychloroprene in market segments where a green brand identity provides a distinct competitive advantage.
Regulations such as the EPA's National Emission Standards for Hazardous Air Pollutants (NESHAP) are reshaping manufacturing processes in the United States. These rules mandate stricter controls on emissions from polymer production, compelling investment in alternative blowing agents and solvent-free lamination techniques. Manufacturers supplying the US construction and automotive sectors are most directly impacted, needing to re-engineer products to achieve compliance.
Industrial buyers are altering their procurement patterns, moving away from sourcing raw foam and toward specifying pre-certified, integrated systems. This shift disrupts the traditional component supplier model, creating an advantage for fabricators that can deliver a complete, tested sealing or insulation assembly. The trend is most advanced in the European building sector, where CE marking for assemblies is mandatory, and in North American aerospace supply chains.
Neoprene Foam Market Segmentation
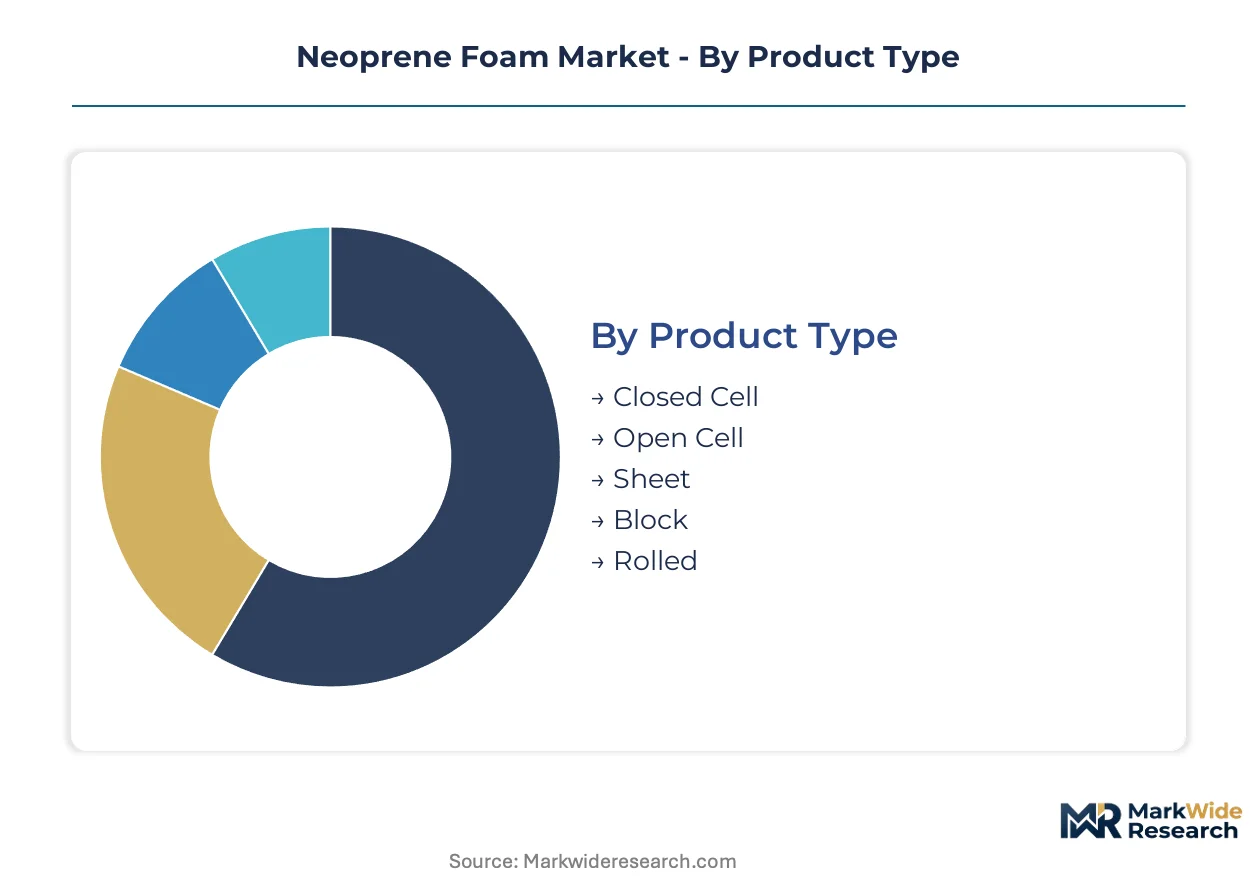
Understanding the segmentation of the neoprene foam market reveals the diverse requirements across various industrial and consumer applications. Distinct product types, applications, end-user industries, and forms dictate material specifications and supply chain configurations. This granular view helps manufacturers align their product development with specific market needs and regulatory demands.
Product Type:
Margin pools within the neoprene foam market often concentrate around specialized formulations and higher-performance product types.
- Closed Cell:This variant features a dense, impermeable structure, offering superior resistance to water absorption, chemicals, and weathering. Demand is significant in marine equipment and construction for critical sealing and insulation, particularly in Germany's automotive sector.
- Open Cell:Characterized by interconnected pores, open cell neoprene foam provides excellent cushioning, sound absorption, and flexibility. Its primary purpose is found in specific protective gear and comfort applications where breathability is beneficial.
- Sheet:Neoprene foam sheets serve as a fundamental raw material for subsequent fabrication into gaskets, seals, and insulation panels.
- Block:Large blocks of neoprene foam are processed by converters into various forms, enabling cost-effective production for bulk industrial applications.
- Rolled:Rolled neoprene foam is preferred for continuous production lines, particularly in textile lamination for wetsuits and protective apparel.
The dominant share belongs to Closed Cell, while Open Cell is expanding most quickly.
Application:
Volume concentration dictates the primary focus for manufacturers, with high-volume applications driving production scale and material innovation.
- Sealing Solutions:Neoprene foam provides reliable sealing against liquids, gases, and dust in harsh operational conditions, crucial for industrial machinery and infrastructure projects. Manufacturers in Germany leverage these properties for critical engine bay seals.
- Gasket Manufacturing:Precision-cut neoprene gaskets offer durable and chemical-resistant seals in a multitude of industrial assemblies, meeting stringent performance criteria in sectors like electronics and automotive.
- Thermal Insulation:The material's closed-cell structure offers effective thermal barriers, minimizing heat transfer in HVAC systems and cold storage units.
- Cushioning Pads:Neoprene foam's resilience and shock absorption properties make it suitable for impact protection in packaging and sports equipment.
- Protective Gear:The material's flexibility and insulation capabilities are essential for wetsuits, medical braces, and industrial safety apparel.
Volume concentration remains highest in Sealing Solutions, with Gasket Manufacturing experiencing significant expansion.
End User Industry:
Customer types and their specific regulatory and performance needs shape product development and market access for neoprene foam suppliers.
- Marine Equipment:This sector requires neoprene foam for wetsuits, buoyancy aids, and vessel seals, demanding superior saltwater and UV resistance. The EU's REACH framework influences material composition for these products.
- Construction:Neoprene foam finds use in building envelopes for window and door gaskets, expansion joints, and pipe insulation, adhering to stricter energy efficiency standards in North America.
- Electronics:Neoprene foam provides sealing, vibration damping, and thermal management within electronic devices, protecting sensitive components from environmental factors.
- Furniture Manufacturing:The material is used for cushioning and padding in high-performance outdoor and commercial furniture applications.
- Packaging Solutions:Neoprene foam offers protective cushioning for delicate or sensitive items during transit, preventing damage from impact and vibration.
Industrial buyers in Marine Equipment drive substantial demand, as Construction sectors expand their material specifications.
Form:
Supply concentration for neoprene foam is often determined by the ease of processing and the versatility of the material's physical form.
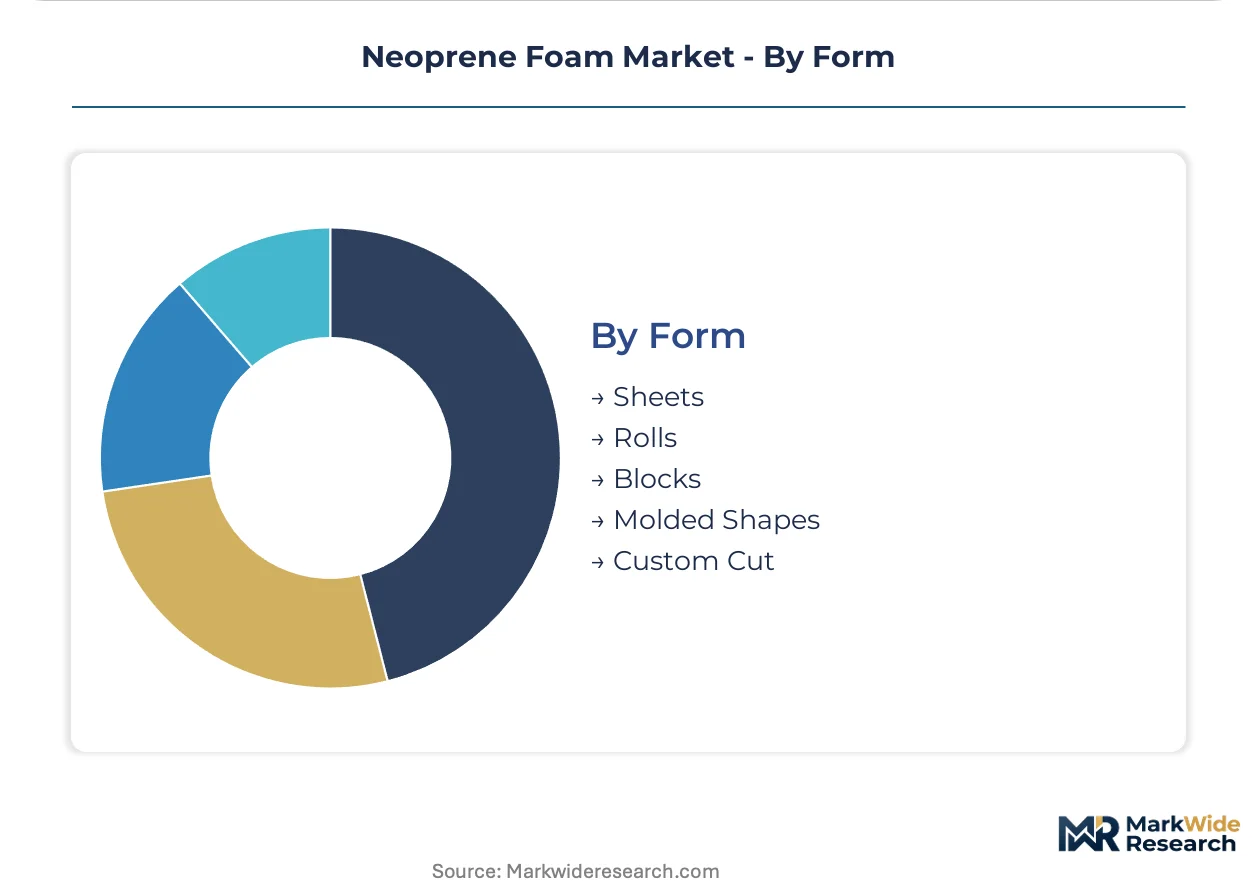
- Sheets:Neoprene foam sheets are a versatile format, widely used as base material for cutting, laminating, and fabricating into various components. These sheets are essential for gasket manufacturers.
- Rolls:Large rolls of neoprene foam facilitate efficient, continuous production processes, particularly for applications requiring long lengths or automated cutting.
- Blocks:Neoprene foam blocks allow for custom shaping and larger component fabrication, catering to specialized industrial needs.
- Molded Shapes:Custom molded neoprene foam parts offer precise fits and complex geometries for specific applications like automotive seals or electronic enclosures.
- Custom Cut:Fabricators provide custom-cut neoprene foam solutions tailored to exact client specifications, serving niche industrial requirements.
Supply chain efficiency is maximized for Sheets, while Molded Shapes offers tailored solutions for high-value applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration in neoprene foam production and consumption often aligns with regions having developed industrial bases and stringent regulatory environments. These areas demand high-performance materials for diverse applications. Such concentration drives localized innovation and manufacturing capabilities.
Germany
Germany's automotive and machinery sectors drive significant demand for high-grade neoprene foam. The EU's REACH framework influences material composition and manufacturing processes across the region. Bavarian industrial clusters specify neoprene foam for critical engine bay insulation and sealing solutions.
United States
The United States market requires neoprene foam for building energy efficiency and electronics applications. EPA standards regulate emissions from polymer manufacturing facilities, impacting product formulations. Manufacturing hubs in Michigan and Ohio utilize neoprene foam for automotive gaskets and construction seals.
China
China's expanding industrial base consumes substantial volumes of neoprene foam for various applications. The nation's GB standards dictate material safety and performance criteria for domestic products. Industrial zones like the Yangtze River Delta integrate neoprene foam into electronics and machinery production.
Brazil
Brazil's industrialization in automotive and manufacturing sectors creates new demand for specialized neoprene foam solutions. ANVISA regulations influence the chemical composition of industrial materials imported and used within the country. São Paulo's automotive industry procures neoprene foam for seals and insulation components.
Japan
Japanese advanced manufacturing and electronics industries require high-performance neoprene foam for precision applications. JIS standards set rigorous quality and performance benchmarks for industrial materials. The Kanto region's technology clusters integrate neoprene foam into advanced electronic devices and automotive parts.
Neoprene Foam Market Key Industry Players
Concentration sits with large chemical conglomerates, which leverage extensive R&D capabilities for advanced polymer science. The market structure exhibits a tiered approach, featuring these global leaders alongside specialized polymer producers and numerous regional fabricators. Companies pursue portfolio diversification and geographic expansion to capture market share across diverse end-use sectors. Strategic partnerships and technology licensing agreements also play a role in disseminating specialized formulations and accessing new markets.
Within the premium segment, companies like DuPont de Nemours exemplify manufacturers with historical leadership in polymer science, providing advanced formulations for demanding environments. Arkema, a European-based specialty polymer producer, occupies a position targeting niche industrial segments, offering a diverse portfolio of specialty polymers. Denka Company Limited, a Japan-headquartered chemical firm, anchors a significant portion of the supply chain in Asia, focusing on consistent quality for large-scale industrial buyers. These entities collectively demonstrate the varied approaches to market penetration, from high-performance material development to broad industrial supply, shaping the competitive dynamics across different regions and application areas.
| Leading Market Players |
|---|
| DuPont de Nemours |
| BASF |
| ChemChina |
| Arkema |
| LG Chem |
| DOW |
| Huntsman Corporation |
| Trelleborg |
| Denka Company Limited |
| Others |
Cost & Logistics Intelligence
Large-scale polychloroprene production capacity underpins the neoprene foam market, driving supply concentration among a few global chemical giants. This industrial scale directly influences market price floors and the competitive dynamics for downstream fabricators.
Pricing Analysis
EU REACH dictates the pricing tier structure for neoprene foam sold within Europe, influencing formulation costs and market access. The dominant pricing model involves contract-based long-term offtake agreements, with price differentiation stemming from certification levels and specialized performance characteristics. Raw material volatility for butadiene creates pricing pressure across all segments. Industrial buyers in demanding applications like automotive and marine equipment exhibit lower price sensitivity for high-performance grades, while commodity segments remain highly price-sensitive.
Supply Chain Analysis
Managing just-in-time inventory for specialty neoprene foam grades presents a challenge due to complex manufacturing processes and global logistics. Supply concentration centers on major chemical producers in Asia, particularly Japan and China, alongside European hubs like Germany. The supply chain draws from butadiene, a petroleum derivative, creating commodity price volatility risk. Distribution runs through a network of converters and fabricators, increasingly shifting towards pre-certified, integrated assembly solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neoprene foam market experiences a significant buyer-power shift as industrial customers increasingly demand pre-certified, integrated sealing and insulation assemblies. This trend, particularly in the European building sector, consolidates procurement towards fabricators offering complete solutions.
For Market Incumbents: Compound chemical engineering capabilities to develop advanced low-VOC neoprene foam formulations meeting diverse global regulatory standards like EU REACH and China's GB standards. Invest in certification processes for integrated sealing assemblies to counter substitution threats from EPDM and silicone foams. Secure long-term feedstock contracts to mitigate raw material volatility. Establish regional manufacturing hubs to serve key industrial clusters like Germany's automotive sector effectively.
For New Entrants and Emerging Players: Anchor in niche, high-growth applications such as electric vehicle battery systems where specialized sealing and fire-retardant properties are critical. Target underpenetrated industrial markets like Brazil's expanding automotive sector with tailored insulation solutions. Develop bio-based neoprene foam formulations derived from non-petroleum sources to access customers prioritizing sustainability. Offer specialized engineering support to integrate these advanced materials into complex end-user designs.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized fabricators offering integrated neoprene foam assemblies with pre-certified performance. The long-term viability of this market hinges on continuous innovation in polymer chemistry to balance performance with environmental compliance. Target acquisition profiles include mid-sized firms with proprietary low-VOC formulations and strong technical support for demanding industrial applications. The signal to watch is the accelerating adoption rate of bio-based neoprene foam across automotive and consumer goods sectors.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Low-VOC Formulations | Ensures compliance with EU REACH and US EPA standards, maintaining market access for manufacturers. |
| Acquire Specialized Fabricators | Integrates downstream capabilities, enabling delivery of pre-certified, integrated sealing solutions to industrial buyers. |
| Develop Bio-Based Polychloroprene | Addresses customer demand for sustainability, opening new market segments like eco-conscious consumer goods. |
| Expand Production in Brazil | Captures new demand from Brazil's industrialization, particularly in its expanding automotive manufacturing sector. |
| Enhance Chemical Engineering R&D | Drives innovation for high-performance materials required in electric vehicle battery systems and marine equipment. |
Research Approach
Operator-level perspectives from R&D directors, procurement managers, plant engineers, and regulatory affairs specialists anchored the qualitative base for this analysis. Primary interviews were triangulated with extensive secondary research from ECHA reports, EPA publications, and China GB standards documents. This approach ensured a robust understanding of market dynamics, cross-validating insights from both bottom-up and top-down data aggregation methods.
Sensitivity analysis was applied to key variables, allowing for a comprehensive understanding of potential market trajectories across the analysis window. The quantitative model segmented the market by product type, application, end-user industry, and geographic region. Compound Annual Growth Rates were derived from historical data analysis combined with future growth projections. Key industry-specific inputs included butadiene price forecasts and electric vehicle production targets.
Decision-makers should treat outputs as directional under assumptions of a stable regulatory environment and consistent raw material supply; material deviation would warrant model refresh. Forecasts reflect these documented assumptions, acknowledging risks from significant shifts in global trade policies or unforeseen technological disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Mesh Nozzle Plates Market
Industrial Materials
Industrial Wax Market
Industrial Materials
Soil Stabilization Materials Market
Industrial Materials
High Pressure Braided Tubing (HPBT) Market
Industrial Materials
Industrial Films Market
Industrial Materials
Heat Shrink Tubing and Sleeves Market
Industrial Materials
Industrial Gaskets Market
Industrial Materials
Hardfacing Rods Market
Industrial Materials
High Modulus Polyethylene Rope Market
Industrial Materials
Wire Mesh Market
Industrial Materials
Stainless Steel Cable Ties Market
Industrial Materials
Industrial Heaters Market
Industrial Materials
Grouting Materials Market
Industrial Materials
Global Graphite Electrode Rod Market
Industrial Materials
Global Industrial Fastener Seal Market
Industrial Materials
Crimped Wire Brushes Market