
 Aluminum Tubes Market | 2026-2036
Aluminum Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Tubes Market Outlook
ISO 9001 quality management certification is rotating as the baseline gate for aluminum tube suppliers bidding on automotive and aerospace contracts. Norsk Hydro leverages its integrated bauxite-to-tube value chain to sustain cost advantages across European automotive programs. Albéa Group anchors its position through specialized laminate and pure aluminum tube lines for pharmaceutical and cosmetic packaging. Constellium competes on high-strength alloy formulations for aerospace structural applications.
Aluminum tubes are hollow cylindrical products manufactured from aluminum alloys through extrusion, drawing, or welding processes, typically specified by outer diameter, wall thickness, and temper grade (e.g., 6061-T6, 3003-H14), serving primarily as conduits for fluids, gases, and heat transfer media or as load-bearing structural elements. Extruded tubes dominate volume production for construction and general industrial use due to lower per-unit manufacturing cost and geometric flexibility, while seamless tubes command premium positioning in aerospace and high-pressure fluid systems where fatigue resistance and leak integrity justify material and processing overhead. Heat exchanger applications represent the fastest-growing end-use cluster as electric vehicle thermal management systems expand coolant circuit complexity.
FDA regulations govern pharmaceutical tube contact surfaces and extractable testing protocols in the United States, while REACH and the EU Green Deal carbon border adjustments tighten traceability and embodied emissions requirements for aluminum sourced into European packaging and automotive supply chains. China's GB standards and SAMR market surveillance protocols enforce alloy composition and dimensional tolerances for tubes used in domestic infrastructure and export manufacturing. Stakeholders must monitor evolving alloy carbon intensity disclosures as procurement criteria across regulated end-use sectors.
Market Dynamics
REACH compliance and the EU Green Deal carbon border adjustment mechanism are compressing supplier margins while rewarding low-carbon primary aluminum sources, reshaping competitive positioning across European automotive and packaging supply chains.
Growth Catalysts
- Electric vehicle thermal management expansion:Battery pack cooling circuits require 40-60% more aluminum tubing per vehicle than internal combustion architectures, pulling extruded 6061 and 3003 alloys into new volume tiers.
- India's PLI scheme for pharmaceuticals:Domestic tube production incentives are capturing contract manufacturing flows from European and North American packaging buyers seeking cost-advantaged, FDA-inspected supply.
- ISO 9001 certification baseline:Automotive and aerospace OEMs now mandate quality management system verification as a non-negotiable bidding threshold, filtering out uncertified regional suppliers.
Market Restraints
- Primary aluminum price volatility:LME aluminum fluctuations and smelter energy cost spikes in China and Russia transmit directly to tube mill input costs, compressing margin predictability.
- Seamless tube supply concentration:Aerospace-grade seamless capacity clusters among a handful of European and Japanese mills, creating single-source vulnerability for fatigue-critical applications.
- Polymer laminate substitution in cosmetics:Multi-layer plastic and bio-based barrier tubes are capturing mid-market personal care volumes where aluminum's recyclability premium does not justify cost.
Strategic Opportunities
- India domestic demand underpenetration:Per-capita aluminum tube consumption in Indian pharmaceutical and cosmetics packaging trails Southeast Asian benchmarks by 35-40%, offering expansion runway.
- Hydrogen infrastructure tubing:High-pressure 700-bar aluminum-lined composite cylinders for fuel cell vehicles represent an emerging specification cluster requiring new alloy and joining qualifications.
- EU Green Deal carbon intensity disclosure:Embodied emissions reporting mandates are creating first-mover advantage for mills with verified low-carbon bauxite-to-tube value chains.
Industry Challenges
- Alloy temper certification timelines:New aerospace and automotive specifications require 18-24 month qualification cycles with OEMs, freezing product development capital and engineering resources.
- Extrusion die reconfiguration costs:Heat exchanger micro-channel geometries demand precision die investments exceeding $2 million per profile family, concentrating capability among capitalized tier-one mills.
- Legacy ERP integration with traceability systems:Carbon accounting and alloy pedigree tracking requirements are forcing mid-cap producers to replace decades-old production control software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Tubes Market |
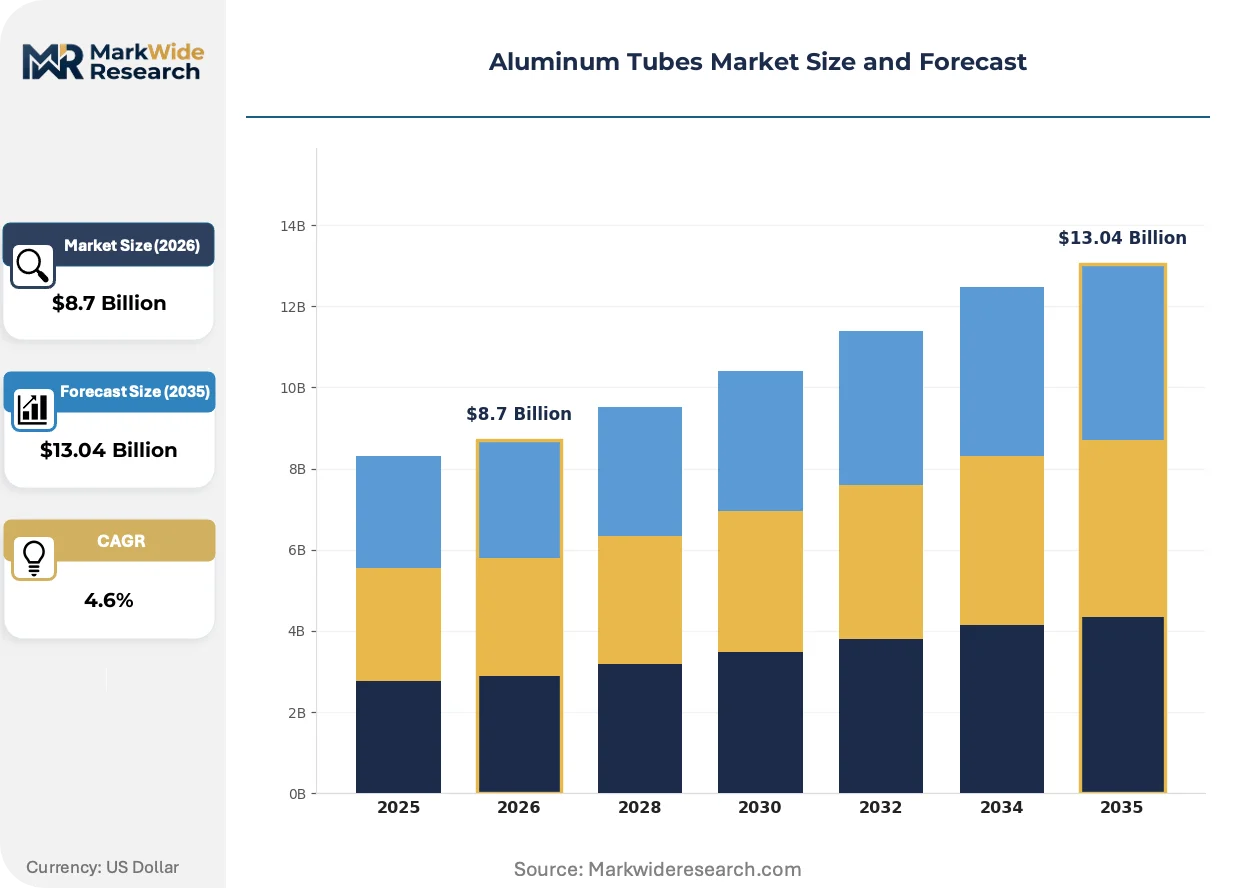
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless Tubes, Welded Tubes, Extruded Tubes, Drawn Tubes End User: Automotive, Aerospace, Construction, Packaging Application: Heat Exchangers, Structural Components, Fluid Transportation, Electrical Conductors Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Tubex Aluminium Tubes, Albéa Group, Norsk Hydro, Constellium, ALPLA, Zhongwang Aluminum, Chalco, Kaiser Aluminum, UACJ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Tubes Market Strategic Shifts
Extrusion die simulation software and inline quality sensing are compressing development cycles and defect rates simultaneously, while regulatory carbon accounting is becoming a procurement gate rather than a voluntary disclosure.
Continuous rotary extrusion (CRE) is displacing conventional direct extrusion for small-diameter heat exchanger tubing. HVAC and battery thermal management suppliers in Germany and South Korea are adopting CRE lines at 15-20% annual capacity expansion rates. The process is displacing higher-scrap, batch-oriented production methods by enabling seamless coil-to-coil output with sub-5% dimensional variance.
REACH Article 33 substance disclosure and the EU Carbon Border Adjustment Mechanism are tightening aluminum sourcing documentation requirements. Tube mills serving European automotive and pharmaceutical packaging must now provide smelter-level carbon intensity certificates and alloy pedigree traceability. Suppliers with captive low-carbon primary aluminum or verified recycling streams are capturing specification-driven contract renewals from carbon-intensive competitors.
Pharmaceutical contract manufacturers are consolidating tube supplier bases from 8-12 vendors to 3-4 strategic partners with integrated laminate, pure aluminum, and regulatory filing support capabilities. This concentration is displacing spot-buying relationships and fragmenting regional tube distributors. The shift is most visible in India, where domestic packaging leaders are absorbing export-oriented contract manufacturing volumes previously sourced from European mills.
Aluminum Tubes Market Segmentation
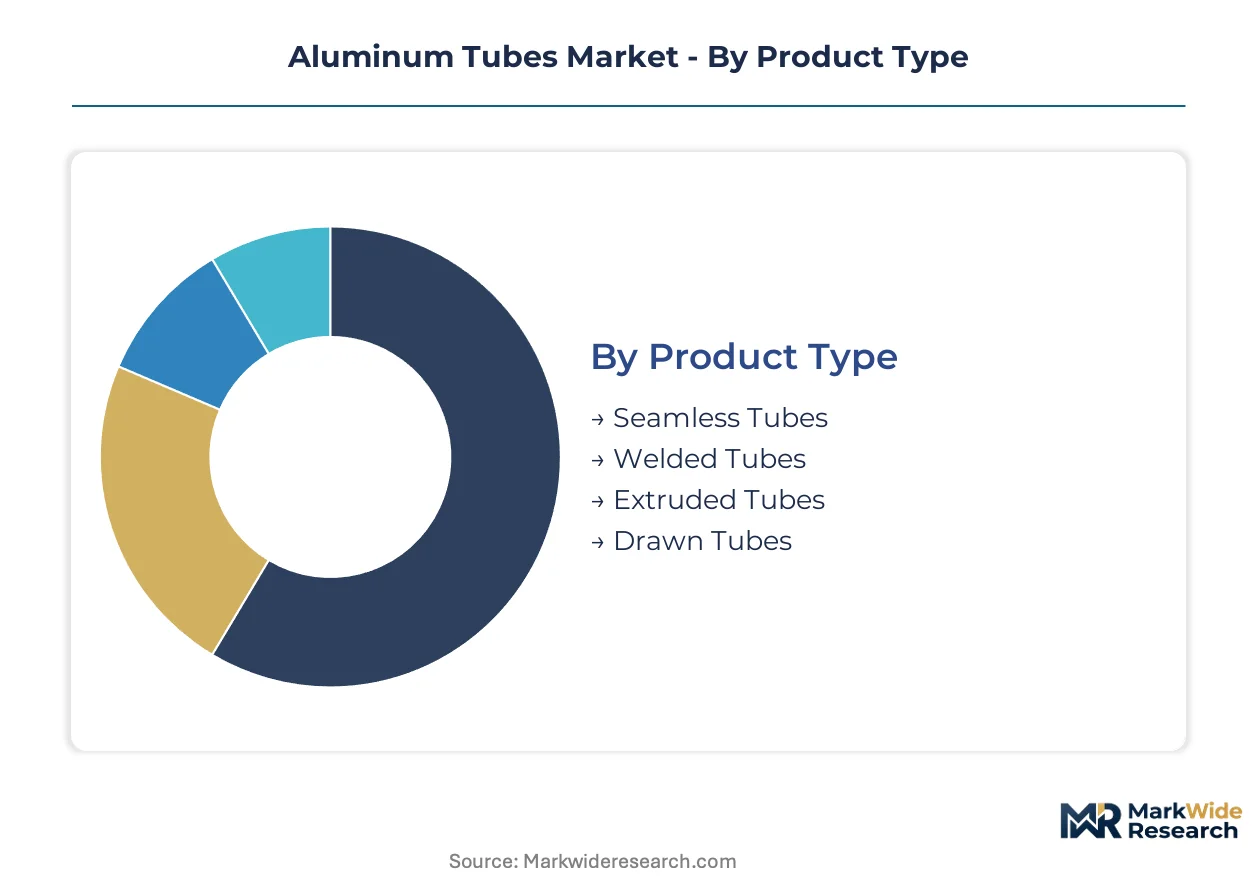
Aluminum tube specifications diverge sharply across end-use sectors, with aerospace and pharmaceutical packaging imposing alloy purity and traceability requirements that general industrial applications do not. Segmentation clarity enables procurement teams to match temper grades and forming methods against regulatory load and performance thresholds.
Product Type:
REACH and FDA contact-surface rules differentiate tube categories by forming method and defect tolerance, with seamless and drawn variants commanding premium positioning in regulated channels.
- Seamless Tubes:Manufactured through rotary piercing or extrusion without longitudinal welds, achieving uniform grain structure critical for fatigue resistance. Aerospace hydraulic systems and high-pressure hydrogen storage in Germany and Japan specify seamless 6061-T6 and 7075-T73 grades for leak integrity under cyclic loading.
- Extruded Tubes:Formed by forcing aluminum billets through shaped dies, enabling complex cross-sections at lower unit cost. Battery thermal management circuits in South Korea and Germany pull extruded 3003-H14 and 6061-T6 into micro-channel geometries for electric vehicle coolant distribution.
- Welded Tubes:Produced from rolled strip joined by ERW or laser welding, suitable for low-pressure fluid transport and structural frames where seam integrity requirements are moderate.
- Drawn Tubes:Cold-drawn over mandrels to achieve tight dimensional tolerances and work-hardened surfaces, serving precision instrumentation and medical device applications.
Established volume favors extruded tubes; emerging adoption favors seamless tubes.
End User:
Customer procurement power and qualification timelines segment the market, with automotive and aerospace OEMs mandating 18-24 month certification cycles that filter supplier bases.
- Automotive:OEM thermal management programs specify extruded aluminum tubing for battery pack cooling circuits, with 40-60% higher aluminum content per vehicle than internal combustion architectures. Tier-one suppliers in Germany and South Korea are expanding CRE line capacity to serve this demand cluster.
- Aerospace:Airframe and propulsion systems require seamless high-strength alloys with full pedigree traceability. European and Japanese mills dominate fatigue-critical specifications, creating single-source vulnerability for downstream manufacturers.
- Construction:Building envelope and structural applications consume standard extruded profiles where cost efficiency outweighs alloy sophistication.
- Packaging:Pharmaceutical and cosmetic tube demand concentrates in India, where domestic production serves both local brands and export-oriented contract manufacturers seeking FDA-inspected, cost-advantaged supply.
Procurement scale concentrates in automotive; margin capture concentrates in aerospace.
Application:
Functional performance requirements determine alloy selection and forming investment, with heat transfer and pressure containment applications driving technical differentiation.
- Heat Exchangers:Micro-channel aluminum tubing enables compact thermal management in electric vehicle battery packs and HVAC systems. Continuous rotary extrusion lines in Germany achieve sub-5% dimensional variance for coil-to-coil production of these precision geometries.
- Structural Components:Load-bearing frames and support elements utilize 6061-T6 and 6082-T6 extrusions where strength-to-weight ratio and corrosion resistance justify material selection.
- Fluid Transportation:Conduit systems for automotive, aerospace, and industrial fluids specify temper grades based on pressure rating and chemical compatibility requirements.
- Electrical Conductors:Busbar and cable shielding applications leverage aluminum's conductivity and lightweight properties in power distribution and renewable energy installations.
Technology investment clusters in heat exchangers; commoditization risk sits with fluid transportation.
Distribution Channel:
Contract value and technical service intensity shape channel selection, with direct relationships dominating specification-driven segments and intermediaries serving spot-demand markets.
- Direct Sales:Automotive and aerospace OEMs engage mills and tier-one converters directly for long-term supply agreements with embedded quality system audits and carbon intensity disclosure requirements.
- Distributors:Regional stockists serve construction and general industrial customers with standard extruded profiles, offering cut-to-length and short-lead-time fulfillment.
- Online Retail:E-commerce platforms capture small-lot demand from maintenance, repair, and prototyping operations where specification complexity is low.
- Wholesalers:Volume aggregators supply downstream fabricators and installers with commodity-grade tubing for non-critical applications.
Relationship stickiness strengthens in direct sales; price transparency pressures wholesalers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and pharmaceutical contract manufacturers concentrate procurement power across distinct regional clusters, each shaped by local regulatory regimes and industrial specialization.
Germany
Electric vehicle thermal management programs at BMW and Mercedes-Benz pull extruded aluminum tubing into battery cooling circuits. The EU Green Deal carbon border adjustment mechanism forces mills to provide smelter-level emissions certificates. Continuous rotary extrusion lines in Baden-Württemberg achieve sub-5% dimensional variance for micro-channel heat exchanger coils.
India
Domestic pharmaceutical packaging demand serves both local cosmetics brands and export-oriented contract manufacturers seeking FDA-inspected supply. The PLI scheme for pharmaceuticals incentivizes domestic tube production capacity. Ahmedabad and Mumbai host concentrated tube fabrication clusters capturing flows previously sourced from European mills.
China
Infrastructure investment and export manufacturing sustain volume demand for standard extruded profiles. GB standards and SAMR market surveillance protocols enforce alloy composition and dimensional tolerances. Shandong and Henan provinces concentrate primary aluminum smelting and downstream tube extrusion capacity.
United States
Aerospace hydraulic systems and defense applications specify seamless high-strength alloys with full pedigree traceability. FDA regulations govern pharmaceutical tube contact surfaces and extractable testing protocols. Kaiser Aluminum and specialty mills in the Pacific Northwest serve fatigue-critical specifications for Boeing and defense primes.
Japan
Precision drawn tubing for instrumentation and medical devices leverages cold-drawn mandrel processes. METI industrial policy supports advanced materials development for hydrogen infrastructure applications. Nagoya and Osaka industrial corridors concentrate seamless tube capacity for automotive and aerospace supply chains.
Aluminum Tubes Market Competitive Environment
Player mix skews toward integrated primary aluminum producers and specialized packaging converters. Consolidation pressure runs high in aerospace-grade seamless tubing, where European and Japanese mills dominate fatigue-critical specifications. Three strategic archetypes define competitive positioning: captive bauxite-to-tube value chains, specialized laminate and pure aluminum packaging specialists, and high-strength alloy formulators for structural applications. Dominant competitive moves include strategic partnerships for carbon intensity verification and capacity expansion in continuous rotary extrusion lines.
Among European integrated producers, Norsk Hydro exemplifies the captive value chain archetype through its bauxite-to-tube vertical control. Albéa Group and Constellium occupy distinct specialization tiers—Albéa anchoring pharmaceutical and cosmetic packaging through laminate and pure aluminum lines, while Constellium represents high-strength alloy formulation for aerospace structural applications. These three entities illustrate how geographic integration, regulatory compliance depth, and alloy sophistication stratify competitive position.
| Leading Market Players |
|---|
| Tubex Aluminium Tubes |
| Albéa Group |
| Norsk Hydro |
| Constellium |
| ALPLA |
| Zhongwang Aluminum |
| Chalco |
| Kaiser Aluminum |
| UACJ |
| Others |
Value Chain & Pricing Dynamics
REACH Article 33 substance disclosure and the EU Carbon Border Adjustment Mechanism gate both supplier qualification and price differentiation simultaneously, forcing mills to absorb certification costs or surrender margin while buyers sort on verified low-carbon pedigree. Tube procurement now splits between carbon-intensive spot supply and premium contracted streams with full smelter-level emissions documentation.
Pricing Analysis
Cost-plus contracts with LME aluminum indexation dominate long-term automotive and aerospace agreements, insulating mills from raw material spikes while exposing them to energy cost pass-through disputes. Price differentiation rests on ISO 9001 certification tier and carbon intensity disclosure grade, with uncertified regional suppliers facing 15-20 point discounts. Cost compression in standard extruded profiles intensifies as Chinese capacity exports into Southeast Asian spot markets. Pharmaceutical packaging buyers show lowest price sensitivity, prioritizing FDA contact-surface compliance and extractable testing protocols over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German and South Korean automotive thermal management suppliers, while Indian pharmaceutical contract manufacturers maintain strategic stockpiles of FDA-inspected tube grades to buffer qualification timelines. Primary aluminum supply concentrates in China, Russia, and Canada, with bauxite processing clustered in Guinea and Australia. Raw material dependencies center on alumina refining capacity, extrusion die tooling, and precision mandrel stock for drawn tubes. Single-source vulnerability runs through European and Japanese seamless tube mills serving fatigue-critical aerospace specifications. Distribution runs through direct mill relationships for specification-driven segments and regional distributors for construction-grade spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified seamless tube capacity for aerospace and hydrogen infrastructure applications remains structurally scarce, with 18-24 month OEM qualification cycles freezing engineering resources and capital deployment for new entrants. Mills that secure carbon intensity verification early capture specification-driven renewals from carbon-intensive competitors.
For Market Incumbents: Compound defensive positioning by securing captive low-carbon primary aluminum supply through backward integration or long-term offtake, and expand continuous rotary extrusion capacity in Baden-Württemberg or South Korea to serve electric vehicle thermal management demand. Polymer laminate substitution in mid-market cosmetics threatens aluminum tube volumes; counter with recyclability certification and closed-loop collection programs. For New Entrants and Emerging Players: ISO 9001 certification fast-track through accredited third-party auditors opens bidding eligibility for automotive and aerospace contracts previously blocked to uncertified regional mills. Target India's underpenetrated pharmaceutical packaging segment, where per-capita consumption trails Southeast Asian benchmarks. Lead with integrated regulatory filing support and laminate-to-pure-aluminum product breadth to displace fragmented distributor relationships. For Investors and Strategic Acquirers: EU Green Deal carbon border adjustment implementation reshapes the acquisition landscape toward mills with verified low-carbon bauxite-to-tube value chains or established recycling streams. Long-term viability favors integrated producers with upstream alumina access and downstream extrusion capability. Watch for LME aluminum volatility exceeding historical bands as a signal to reassess margin sustainability across the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Intensity Verification | EU Green Deal compliance gates contract renewals for European automotive and pharmaceutical packaging supply. |
| Continuous Rotary Extrusion Capacity Expansion | German and South Korean CRE lines achieve sub-5% dimensional variance for micro-channel heat exchanger coils. |
| Backward Integration into Low-Carbon Primary Aluminum | Captive smelter access insulates margins from carbon border adjustment exposure and LME volatility. |
| ISO 9001 Certification Investment | Quality management verification filters uncertified regional suppliers from automotive and aerospace bidding. |
| India Domestic Production Scale-Up | PLI scheme incentives capture export-oriented pharmaceutical contract manufacturing flows from European mills. |
Study Parameters
Operator-level perspectives from extrusion plant managers, Tier 1 automotive procurement leads, pharmaceutical packaging converters, and aerospace quality engineers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC filings, customs trade databases, ECHA REACH registration data, and OEM supplier qualification documents. Bottom-up volume estimates by product type and end-use segment triangulated against top-down aluminum consumption forecasts from national industry associations.
Sensitivity analysis tested forecast robustness across LME price bands, carbon border adjustment implementation timelines, and electric vehicle penetration scenarios. The analytical framework modeled volume and value across product type, end-use sector, alloy grade tier, and regional production hub throughout the projection horizon. CAGRs derived from segment-level growth drivers including battery thermal management content per vehicle, pharmaceutical packaging contract manufacturing migration, and hydrogen infrastructure qualification timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained electric vehicle adoption and incremental EU carbon border adjustment enforcement; material deviation in primary aluminum energy costs or regulatory implementation pace would warrant model refresh. Revision becomes warranted when seamless tube capacity utilization crosses thresholds that trigger qualification queue extensions beyond standard OEM timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Pump Casing Materials Market
Metals
Stainless Steel Foil Market
Metals
Lanthanum Market
Metals
GCC Metal Forging Market
Metals
Global Aluminum Market
Metals
TMCP Steel Market
Metals
Osmium Market
Metals
Transition Metals Market
Metals
Monel Alloy Market
Metals
Europe Welding Consumables Market
Metals
Steel Wire Market
Metals
Metal Forging Parts Market
Metals
North America Metal Casting Market
Metals
Global Superconducting Wire Market
Metals
Stainless Steel Round Bar Market
Metals
Rhodium Market