
 Recycled Metal Market | 2026-2036
Recycled Metal Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Metal Market Analysis
Buyer concentration across North American and European automotive OEMs is rebalancing as tier-one suppliers diversify feedstock contracts toward independent recyclers. Nucor Corporation anchors electric arc furnace output across the United States with captive scrap networks. ArcelorMittal competes through integrated blast furnace and EAF routes spanning multiple continents. Sims Metal Management controls collection density in urban port corridors, leveraging scale advantages in ocean freight logistics.
Recycled metal comprises post-consumer and post-industrial metallic feedstock that undergoes sorting, shredding, melting, and refining to restore metallurgical properties equivalent to primary production. Steel scrap typically contains residual copper below 0.20 percent by weight to meet rebar and flat-rolled specifications, while recycled aluminum achieves 95 percent energy savings versus bauxite electrolysis. Aluminum and steel product types carry the highest volume throughput, with aluminum margins expanding fastest due to automotive lightweighting specifications. Construction and automotive end use industries absorb the majority of sheet and ingot form output, though electronics demand for high-purity copper concentrates value in refining-intensive processing methods.
The EPA regulates hazardous waste classification for metal-containing slag and dust under RCRASubtitle C, while the EU Green Deal and REACH constrain heavy metal content in finished products destined for European markets. China's MEE enforces import purity thresholds on ferrous and non-ferrous scrap through GB standards, redirecting regional trade flows toward Southeast Asian sorting hubs. Stakeholders must monitor evolving carbon border adjustment mechanisms and scrap export restriction cascades to secure compliant feedstock positioning.
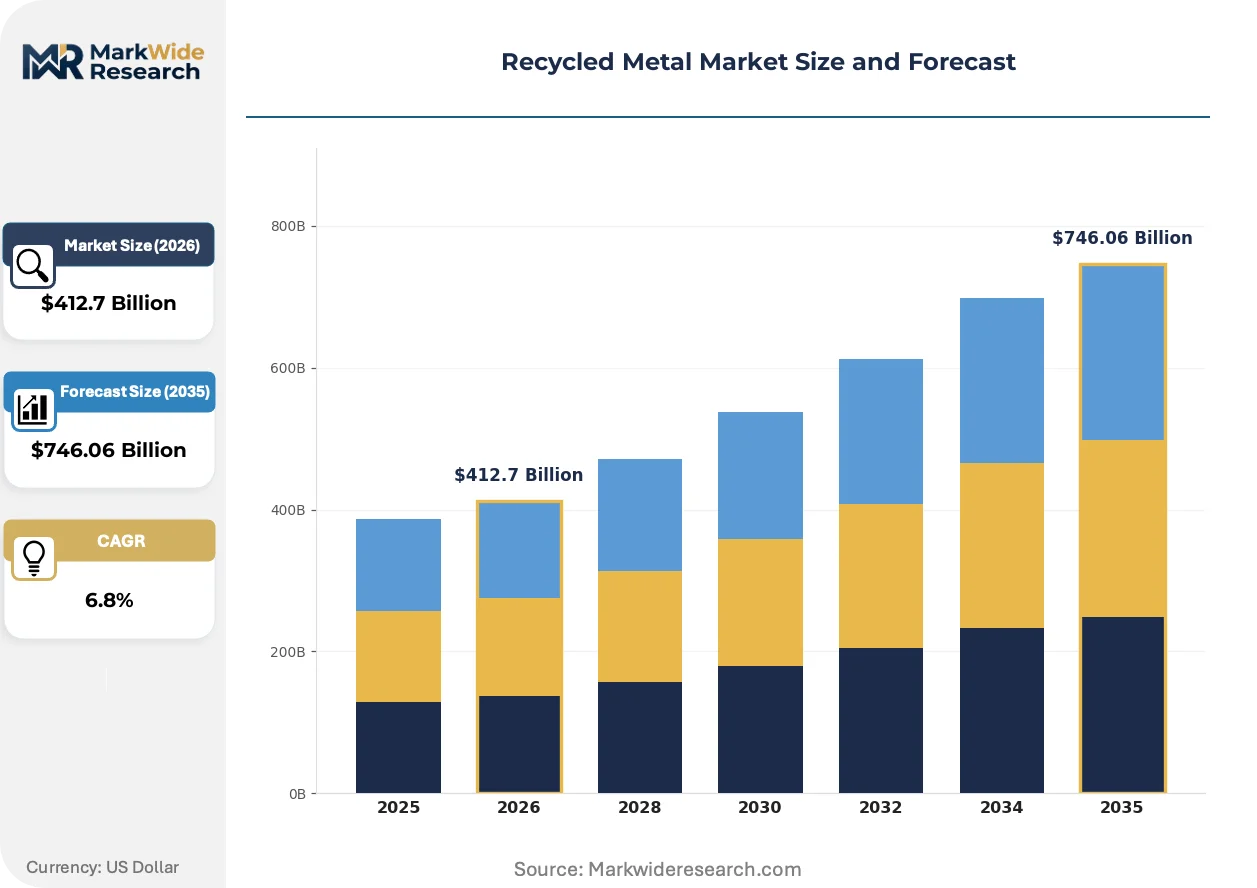
Market Dynamics
Carbon border adjustment mechanisms are restructuring scrap metal trade flows by imposing embodied-emission tariffs on primary metal imports, forcing European and North American fabricators to secure certified recycled feedstock with verified lifecycle documentation.
Growth Catalysts
- EU Green Deal carbon border adjustments:Importers into the European Union must now document recycled content percentages to avoid tariffs on steel and aluminum, redirecting procurement toward certified scrap suppliers.
- Automotive lightweighting mandates:OEMs in Germany, Japan, and the United States specify secondary aluminum for body-in-white components to meet fleet emission targets without sacrificing crash performance.
- Shredder technology diffusion:Advanced sensor-based sorting systems deployed in Turkish and Vietnamese processing hubs enable mixed-grade scrap to meet China's GB purity thresholds through pre-export beneficiation.
Market Restraints
- Ferrous scrap supply concentration:Collection networks cluster in industrialized urban corridors, leaving rural and developing regions with structurally higher logistics costs per ton processed.
- Residual copper contamination:Steel scrap exceeding 0.20 percent copper by weight fails rebar and flat-rolled specifications, requiring costly dilution with primary iron units or downstream refining.
- Export restriction cascades:China's MEE import bans and subsequent ASEAN sorting hub bottlenecks fragment global scrap arbitrage, trapping material in origin markets during price dislocations.
Strategic Opportunities
- India's secondary aluminum deficit:Domestic automotive and construction demand outpaces organized recycling capacity, creating openings for technology-transfer partnerships with established shredding operators.
- Blockchain-enabled provenance tracking:Distributed ledger systems certifying scrap origin and carbon intensity command premium pricing from EU and California buyers facing disclosure mandates.
- Building-integrated photovoltaic recovery:End-of-life solar installations in Germany and Japan yield specialized aluminum frames and silver-bearing conductors requiring dedicated collection infrastructure.
Industry Challenges
- Metallurgical assay talent scarcity:Rapidly evolving scrap grade specifications outpace training pipelines for handheld XRF operators and melt-shop chemists, delaying batch release times.
- Emissions verification infrastructure:Lifecycle assessment modeling for recycled content claims requires capital-intensive third-party certification against ISO 14040 standards, squeezing mid-tier processor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Metal Market |
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $746.06 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Copper, Steel, Zinc End Use Industry: Construction, Automotive, Electronics, Packaging Form: Scrap, Shredded, Ingots, Sheet Processing Method: Melted, Smelting, Recycling, Refining |
| Companies Covered | Nucor Corporation, ArcelorMittal, Sims Metal Management, Aurubis, Schnitzer Steel Industries, Steel Dynamics, Commercial Metals Company, Tata Steel, Novelis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Metal Market Emerging Trajectories
Digital traceability systems and pyrometallurgical efficiency gains are compressing the cost gap between secondary and primary metal production, while regulatory pressure on embodied carbon accelerates specification changes across construction and mobility supply chains.
Plasma arc smelting retrofits are electrifying traditional reverberatory furnace operations by substituting renewable-powered electrode heating for fossil fuel combustion. Aluminum casthouses in Norway and Iceland deploy these systems to produce near-zero-emission secondary ingots for automotive die-casting contracts. The technology is electrifying competitive positioning in premium automotive supply tiers where OEMs mandate supplier-specific carbon intensity disclosures.
REACH Annex XVII restrictions on heavy metal content in finished goods are compelling European electronics and construction manufacturers to document scrap feedstock provenance back to collection point. Enforcement by ECHA member state authorities intensified following the 2024 delegated act on recycled content thresholds for steel and aluminum placed on the EU market. Battery casing and architectural cladding producers now require segregated copper streams with certified lead and cadmium limits below 50 parts per million.
Automotive OEMs are consolidating secondary aluminum purchasing through direct offtake agreements with integrated scrap-to-ingot processors, bypassing traditional merchant metal distributors. BMW, Ford, and Volvo have established multi-year supply contracts specifying maximum carbon intensity per kilogram of A356 alloy delivered to foundry operations. This concentration is most visible in the Great Lakes industrial corridor where shredder operators co-locate melt shops to capture margin from sorted automotive scrap generated by Detroit-area vehicle retirement cycles.
Recycled Metal Market Segmentation
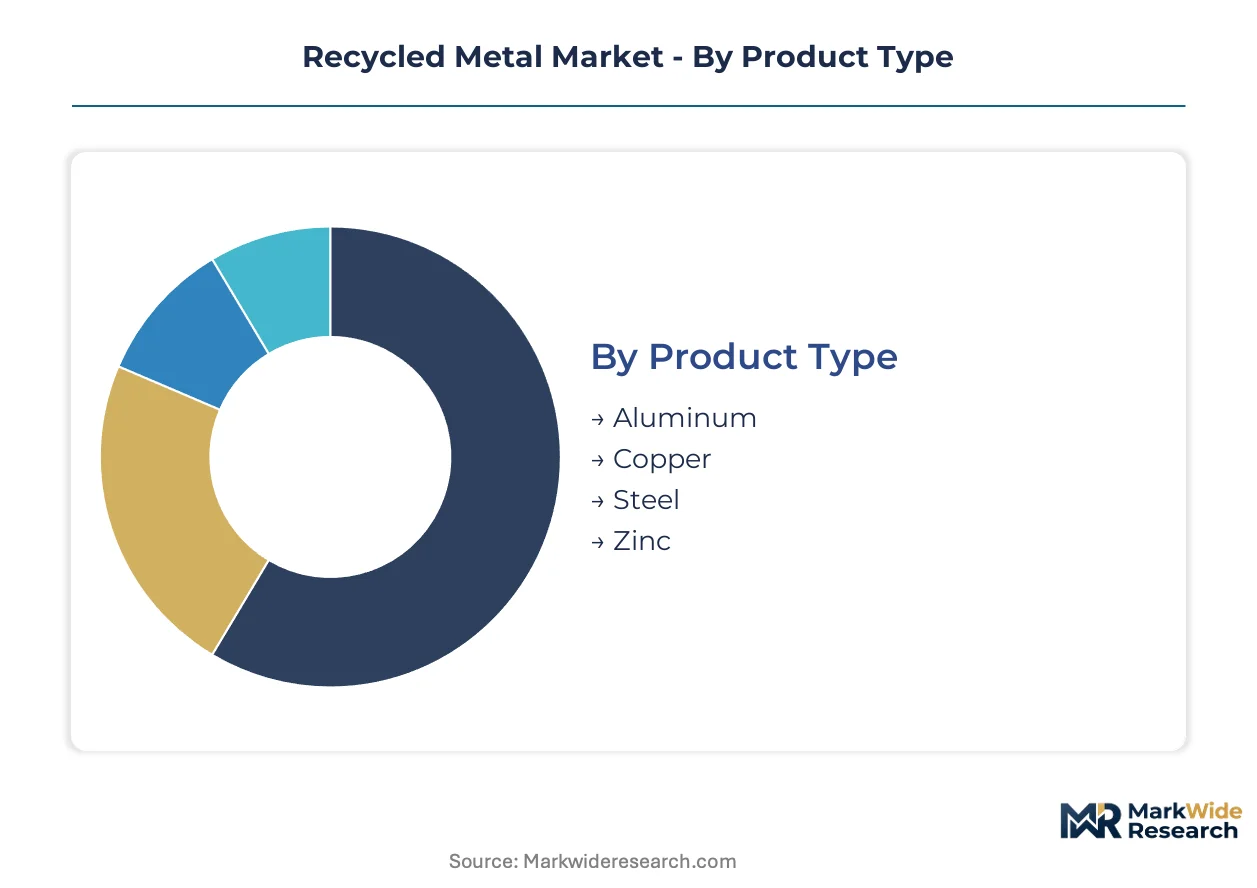
Segmentation in recycled metals determines compliance pathways, margin structures, and logistics requirements. Certification burdens vary sharply across product grades and processing intensities, shaping procurement strategies for automotive and construction buyers.
Product Type:
Steel and aluminum carry distinct certification requirements under EU Green Deal carbon border adjustments and China's GB standards, while copper and zinc face REACH Annex XVII heavy metal thresholds.
- Aluminum:Post-consumer automotive scrap and used beverage cans re-melted to 99.7% purity achieve 95% energy savings versus primary electrolysis. German and Japanese OEMs mandate certified secondary A356 alloy for body-in-white castings under fleet emission regulations.
- Steel:Ferrous scrap graded by residual copper content—below 0.20% for rebar and flat-rolled specifications—requires careful sorting to avoid costly dilution with pig iron. Electric arc furnace operators in the United States and Turkey dominate procurement of shredded auto bodies and structural demolition scrap.
- Copper:Electronics and wire scrap refined to cathode purity faces REACH cadmium and lead limits below 50 parts per million for EU market access.
- Zinc:Galvanized steel residue and die-cast scrap recovered through pyrometallurgical routes serves corrosion-coating applications with lower purity tolerance than battery-grade requirements.
Steel sits at the top of the volume ranking, with aluminum climbing the fastest.
End Use Industry:
Application-driven demand splits between embodied-carbon-sensitive mobility sectors and cost-weighted construction procurement, with electronics commanding premium purity premiums.
- Construction:Structural rebar and sheet piling absorb bulk ferrous scrap volumes, with LEED and BREEAM certification schemes rewarding recycled content documentation. German and French infrastructure tenders increasingly specify minimum secondary steel percentages.
- Automotive:Secondary aluminum castings for engine blocks, transmission housings, and structural nodes carry stringent OEM carbon intensity disclosures. BMW, Ford, and Volvo enforce supplier-specific lifecycle assessment thresholds through direct offtake contracts.
- Electronics:High-purity copper and precious metal concentrates from printed circuit boards require refining-intensive processing with ISO 14040-certified emissions verification.
- Packaging:Used beverage can loops operate on tight logistics radii, with novelis and constellium integrating collection directly with rolling mill feedstock.
Construction holds the largest tonnage position, though automotive commands the steepest expansion trajectory.
Form:
Physical state determines transportation economics, melting yield, and contamination risk, with shredded and ingot forms attracting premium pricing for furnace-ready consistency.
- Scrap:Unprocessed demolition and industrial residue requires manual sorting and density reduction before furnace charging, concentrating supply in urban collection corridors with shredder access.
- Shredded:Auto shredder residue processed through sensor-based separation achieves China's GB purity thresholds for copper and aluminum fractions, enabling export from Vietnamese and Turkish hubs.
- Ingots:Remelted secondary aluminum and copper pigs ship directly to foundries and casthouses, bypassing merchant distribution with certified carbon intensity documentation.
- Sheet:Continuously cast and rolled flat products serve automotive and construction fabricators demanding dimensional precision without primary metal carbon footprints.
Scrap dominates raw feedstock flows, while ingots gain share fastest through integrated scrap-to-metal processor expansion.
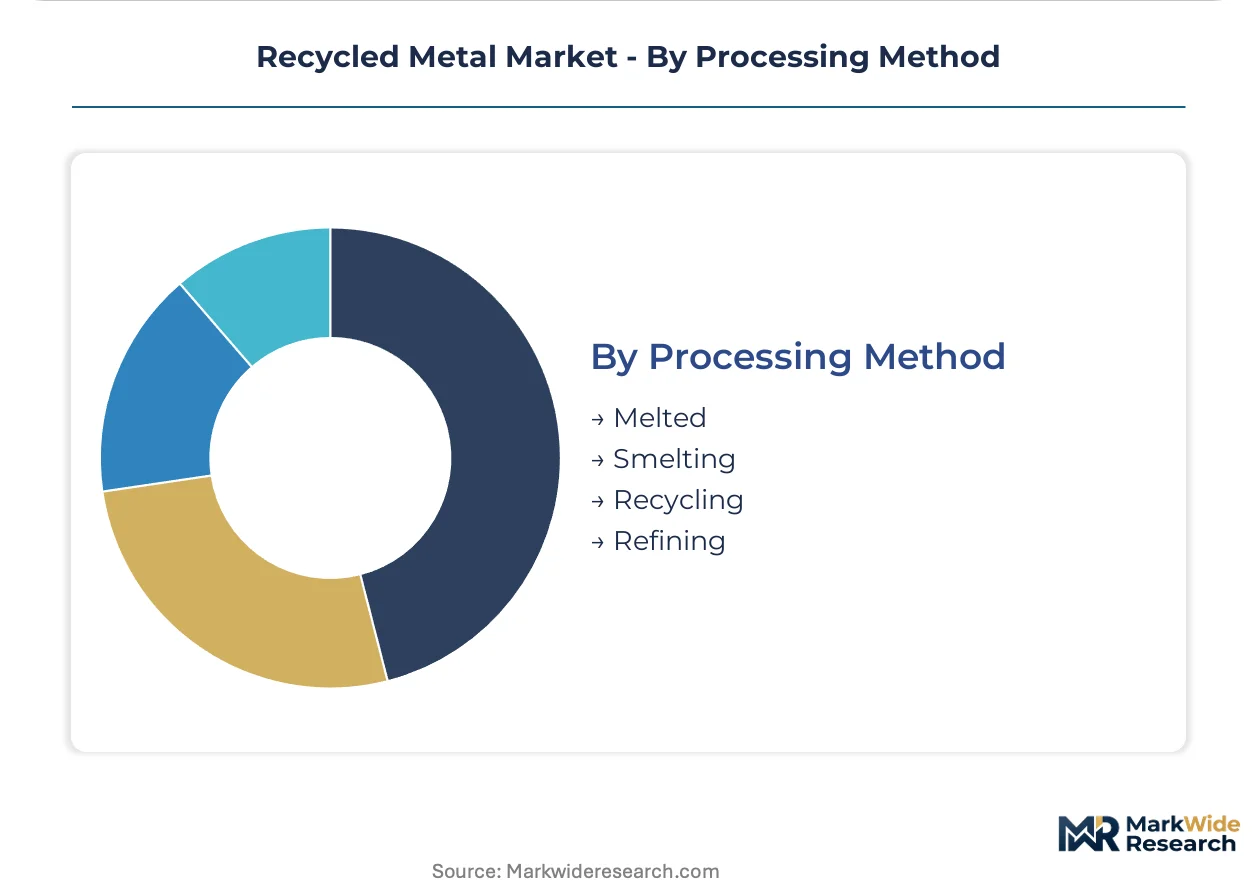
Processing Method:
Technology intensity separates commodity recyclers from premium alloy producers, with plasma arc and hydrometallurgical routes capturing automotive and electronics margins.
- Melted:Reverberatory and rotary furnace remelting of sorted scrap produces standardized ingots for construction and packaging, representing baseline secondary production economics.
- Smelting:Pyrometallurgical reduction of complex concentrates—including zinc residues and copper matte—recovers metal values from lower-grade feedstock with higher energy and emissions profiles.
- Recycling:Mechanical shredding, eddy current separation, and density sorting prepares mixed scrap for furnace charging without chemical transformation, dominating volume throughput.
- Refining:Electrolytic and fire refining of copper and precious metals achieves 99.99%+ purity for electronics and electrical applications, commanding the widest margin spreads.
Recycling handles the greatest tonnage, with refining expanding most quickly on electronics demand concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scrap metal processing talent clusters around Detroit, Duisburg, and Guangzhou, anchoring capacity expansion decisions for integrated recyclers.
United States
Automotive shredder operators in Michigan and Ohio feed electric arc furnaces with retired vehicle hulks under EPA RCRA hazardous waste protocols. The Inflation Reduction Act's domestic content bonuses redirect secondary aluminum procurement toward Great Lakes casthouses. Detroit-area processors co-locate melt shops to capture margin from sorted automotive scrap generated by regional vehicle retirement cycles.
Germany
REACH Annex XVII enforcement compels electronics and construction manufacturers to document scrap feedstock provenance back to collection point. The EU Green Deal carbon border adjustment forces fabricators to secure certified recycled steel with verified lifecycle documentation. The Ruhr industrial corridor hosts dense shredder-to-rolling-mill networks serving automotive OEMs in Bavaria and Baden-Württemberg.
China
Domestic automotive and construction demand outpaces organized recycling capacity in secondary aluminum. The Ministry of Ecology and Environment enforces import purity thresholds on ferrous and non-ferrous scrap through GB standards, redirecting regional trade flows toward Southeast Asian sorting hubs. Guangzhou and Tianjin processors deploy sensor-based sorting to meet domestic quality benchmarks for shredded feedstock.
India
Secondary aluminum deficit widens as automotive and construction demand accelerates beyond domestic melting capacity. The Bureau of Indian Standards and DGFT regulate scrap import classifications, creating compliance complexity for port-based processors. Gujarat and Maharashtra host emerging shredding operations seeking technology-transfer partnerships with established operators.
Turkey
Electric arc furnace operators dominate procurement of shredded auto bodies and structural demolition scrap from European export streams. Advanced sensor-based sorting systems deployed in Izmir and Istanbul processing hubs enable mixed-grade scrap to meet China's GB purity thresholds through pre-export beneficiation. The country's central bank monitors scrap import financing as lira volatility affects working capital for port processors.
Recycled Metal Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across feedstock collection, processing intensity, and end-market certification tiers. The vendor base separates into three strategic archetypes: integrated steelmakers with captive scrap networks, independent merchant processors controlling urban collection density, and aluminum casthouses securing automotive offtake through direct contracts. Consolidation pressure concentrates among shredder operators seeking melt-shop integration, while technology licensing agreements spread sensor-based sorting capabilities across emerging hubs.
Within the integrated steelmaker archetype, Nucor Corporation and ArcelorMittal exemplify divergent route strategies spanning electric arc furnace and blast furnace configurations. Sims Metal Management occupies a position among merchant processors leveraging scale advantages in ocean freight logistics across urban port corridors. These three anchors represent distinct competitive positioning: captive vertical control, global trading density, and regional collection dominance respectively.
| Leading Market Players |
|---|
| Nucor Corporation |
| ArcelorMittal |
| Sims Metal Management |
| Aurubis |
| Schnitzer Steel Industries |
| Steel Dynamics |
| Commercial Metals Company |
| Tata Steel |
| Novelis |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up shredder operators in the United States and Germany have consolidated urban collection networks, tightening supply discipline and enabling premium pricing for ISO 14040-certified secondary aluminum ingots sold to automotive OEMs under direct offtake contracts.
Pricing Analysis
Bundle-unbundle splits separate furnace-ready ingot premiums from unprocessed scrap commodity quotes. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and carbon intensity disclosure depth. Pricing pressure stems from China's MEE import purity thresholds redirecting mixed-grade material through Southeast Asian beneficiation hubs with added logistics costs. Merchant processors show highest price sensitivity, while integrated automotive casthouses absorb premiums for verified lifecycle documentation.
Supply Chain Analysis
Certification gating under EU Green Deal carbon border adjustments and REACH Annex XVII heavy metal limits fragments supplier qualification tiers. Supply concentrates in China, the United States, and Germany, with raw material flows drawing from automotive shredder residue, structural demolition scrap, and electronics wire feedstock. Single-source vulnerability runs through China's dominance of sensor-based sorting equipment manufacturing. Distribution runs through co-located shredder-melt shop corridors in Michigan, Duisburg, and Guangzhou.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in recycled metals rests on plasma arc furnace electrification cutting energy costs and automotive OEMs paying premiums for near-zero-emission secondary aluminum under fleet emission compliance deadlines.
For Market Incumbents: To counter independent merchant processors capturing automotive offtake through direct contracts, Nucor Corporation and ArcelorMittal should deepen backward integration into shredder collection networks in the Great Lakes and Ruhr corridors. Certification investment in ISO 14040 lifecycle assessment infrastructure captures EU Green Deal premium tiers. For New Entrants and Emerging Players: The EU Green Deal carbon border adjustment in Germany and France opens a window for blockchain-enabled provenance tracking specialists to capture automotive procurement mandates. India's secondary aluminum deficit presents the most penetrable geography, with technology-transfer partnerships offering the clearest go-to-market angle against organized recycling capacity shortfalls. For Investors and Strategic Acquirers: Valuations sit cheapest among independent merchant processors lacking melt-shop integration, as consolidation premiums concentrate in shredder-to-ingot vertical control. Long-term viability favors assets with renewable power purchase agreements backing plasma arc retrofits. The signal to watch is EU carbon border adjustment enforcement intensity against primary metal imports.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Arc Furnace Retrofit | Norwegian and Icelandic casthouses electrify reverberatory operations to supply BMW and Volvo with near-zero-emission A356 alloy. |
| Blockchain Provenance Tracking | Distributed ledger systems certifying scrap origin command premium pricing from EU buyers facing recycled content disclosure mandates. |
| Shredder-Melt Shop Co-location | Detroit-area processors capture margin from sorted automotive scrap generated by regional vehicle retirement cycles. |
| Sensor-Based Sorting Technology Transfer | Turkish and Vietnamese hubs deploy advanced separation to meet China's GB purity thresholds through pre-export beneficiation. |
| Direct Automotive Offtake Contracting | BMW, Ford, and Volvo consolidate secondary aluminum purchasing through multi-year supply agreements specifying maximum carbon intensity. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down scrap generation tracking forms the analytical core of this study. Primary interviews with shredder operators, electric arc furnace melt-shop managers, automotive Tier 1 procurement leads, and EPA hazardous waste compliance officers combined with secondary validation against SEC 10-K filings, EU ETS emissions registry data, Chinese customs trade statistics, and GB standards documentation. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Historical trendline analysis of scrap-to-metal conversion yields and automotive lightweighting aluminum content per vehicle informed the projection framework. Segmentation dimensions span product type, end-use industry, physical form, and processing method intensity, with regional regulatory cluster effects layered across the modeling period. CAGRs derive from fitted trend extrapolation adjusted for EU Green Deal implementation pace and China's MEE enforcement trajectory.
Revisions become necessary when carbon border adjustment mechanisms expand beyond steel and aluminum to copper and zinc, or when ASEAN sorting hub capacity constraints trigger export restriction cascades. A model refresh is warranted upon material change in automotive OEM carbon intensity disclosure thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Ferrosilicon Market
Metals
Global High Purity Titanium Powder Market
Metals
Stainless Steel 400 Series Market
Metals
Ultrafine Tungsten Wire for Medical Applications Market
Metals
Global Welding Powder Market
Metals
316 Stainless Steel Container Market
Metals
Neodymium Market
Metals
Aluminum Ingots Market
Metals
Flat-Rolled Stainless Steel Market
Metals
HSLA Steel Plate Market
Metals
Aluminum Tubes Market
Metals
Monel Alloy Market
Metals
Molybdenum Market
Metals
Cerium Market
Metals
Silico Manganese Market
Metals
Industrial Metal Strips Market