
 Rare Earth Metals Market | 2026-2036
Rare Earth Metals Market Size, Share, and Industry Trends Forecast 2026-2036
Rare Earth Metals Market Intelligence
Chinese state-owned mining consolidation is hardening supply-side discipline across the rare earth value chain. MP Materials controls the only integrated rare earth operation in the United States, leveraging its Mountain Pass deposit to anchor domestic magnet feedstock security. Lynas Rare Earths operates the largest non-Chinese separation facility, sustaining output from its Mount Weld concentrate through Malaysian processing. Albemarle competes in lithium and specialty minerals, extending its chemical extraction expertise toward rare earth recovery streams.
Rare earth metals comprise seventeen chemically similar elements, with atomic numbers spanning lanthanum through lutetium plus scandium and yttrium, typically occurring in mixed oxide ores requiring multi-stage solvent extraction to achieve 99.9% purity grades. These elements enable high-coercivity permanent magnets, phosphor illumination, and petroleum cracking catalysts. Neodymium and praseodymium dominate value pools within the type segment, as magnet alloys command premium pricing over lighter cerium-lanthanum fractions. Permanent magnets and electric vehicle applications are absorbing the fastest-growing share of refined output, while catalysts and polishing powders represent mature demand basins with lower growth elasticity.
China's Ministry of Industry and Information Technology governs production quotas and export licensing, while the EU Critical Raw Materials Act establishes domestic processing targets and strategic stockpile mandates. Japan's METI coordinates bilateral offtake agreements with Australian miners to reduce single-source dependency. Stakeholders must monitor quota announcements from Beijing and processing subsidies from Brussels to time capacity commitments and offtake negotiations.
Market Dynamics
China's MIIT export licensing system is hardening outbound flows of heavy rare earth elements, forcing motor manufacturers and magnet fabricators to accelerate non-Chinese feedstock qualification programs and dual-source contracting strategies.
Growth Catalysts
- EU Critical Raw Materials Act:Brussels has established domestic processing targets and strategic stockpile mandates, compelling European automakers to secure magnet-grade oxide supply chains outside China.
- Electric vehicle traction motors:Neodymium-iron-boron magnet orders from EV powertrain manufacturers are scaling rapidly as 800-volt architectures proliferate across premium and mass-market vehicle platforms.
- Japanese METI bilateral coordination:Tokyo's offtake agreements with Australian miners are reducing single-source dependency and creating alternative concentrate pathways for magnet alloy production.
Market Restraints
- Chinese state-owned mining consolidation:Beijing's production quota system and export licensing regime concentrates separation capacity within a handful of SOEs, constraining spot market liquidity.
- Multi-stage solvent extraction capex:Achieving 99.9% purity grades requires capital-intensive cracking and separation circuits with lengthy commissioning timelines.
- Ferrite magnet substitution in low-torque applications:Strontium ferrite formulations are capturing cost-sensitive automotive auxiliary motor segments where peak energy density is non-critical.
Strategic Opportunities
- US magnet manufacturing reshoring:The Inflation Reduction Act's domestic content credits are incentivizing sintered magnet production facilities in Texas and the Mountain West.
- Recycling feedstock streams:End-of-life hard disk drives and wind turbine generators represent emerging concentrate sources for hydrometallurgical rare earth recovery.
- Heavy rare earth diversification:Myanmar and Burmese border zone ionic clay deposits offer alternative dysprosium and terbium pathways outside Chinese jurisdiction.
Industry Challenges
- Separation chemistry talent scarcity:Solvent extraction process engineering expertise resides predominantly within Chinese and Japanese technical institutes, constraining Western facility staffing.
- Offtake contract tenor compression:Automakers are demanding shorter pricing reopener clauses and volume flexibility, complicating project finance for greenfield mine-to-magnet developments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rare Earth Metals Market |
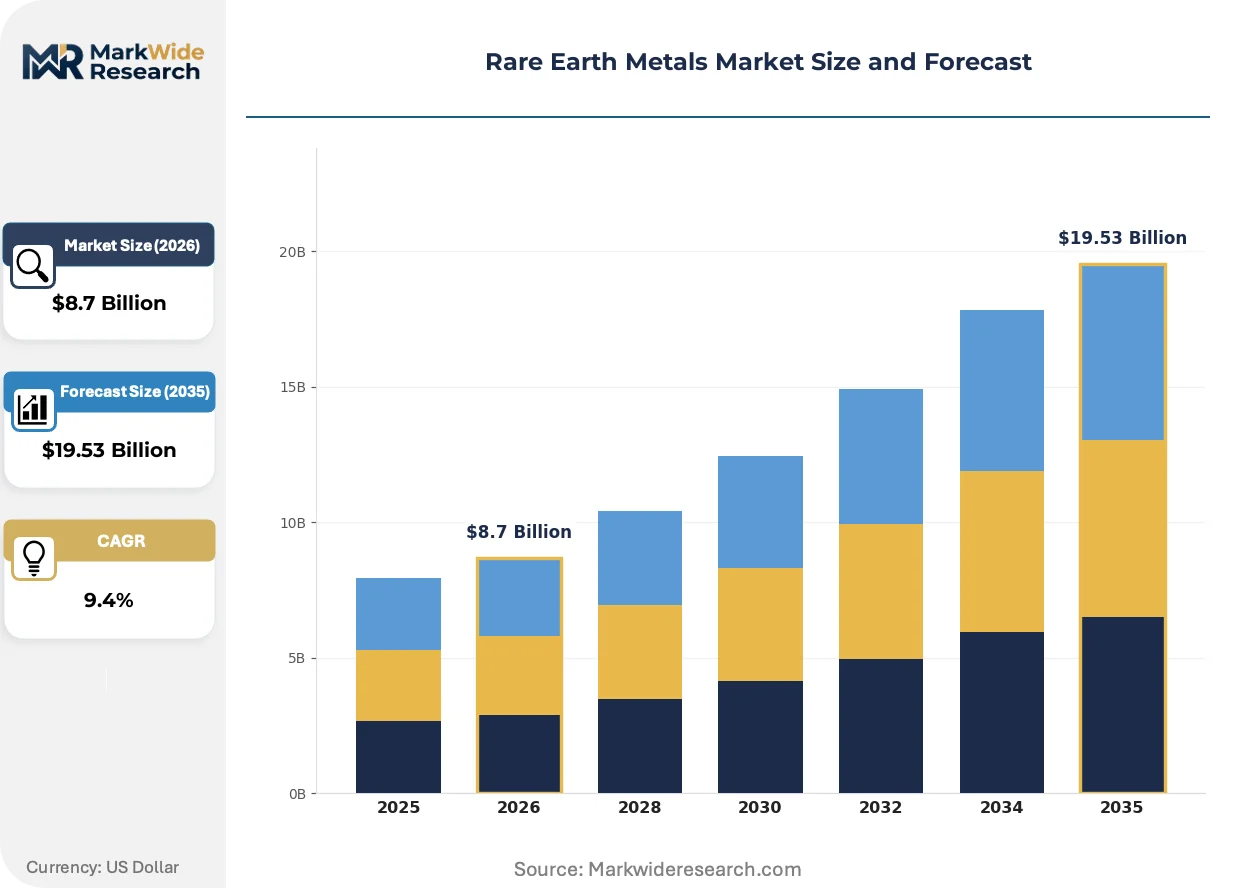
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Neodymium, Praseodymium, Dysprosium, Terbium, Europium, Yttrium Application: Electric Vehicles, Permanent Magnets, Catalysts, Phosphors, Polishing Powders, Fiber Optics End User Industry: Electronics Manufacturing, Renewable Energy, Defense & Aerospace, Chemical Production, Telecommunications Extraction Method: Open Pit Mining, Underground Mining, Solvent Extraction, Ion Exchange, Hydrothermal Processing, Magnetic Separation |
| Companies Covered | Arafura Rare Earths, St George Mining, Lynas Rare Earths, Albemarle, Brazilian Rare Earths, MP Materials, Critical Metals Corp, IperionX, Iluka Resources, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rare Earth Metals Market Strategic Shifts & Innovations
Permanent magnet alloy formulations and separation process intensification are reshaping how refined rare earths reach end-use specifications. Technology licensing patterns and procurement contract structures are shifting in parallel.
Grain-boundary diffusion technology is expanding into high-temperature automotive traction applications. This metallurgical process deposits heavy rare earth elements along neodymium-iron-boron grain boundaries rather than throughout the alloy matrix. BMW and Hyundai Motor Group powertrain divisions are qualifying diffusion-treated magnets for 180°C continuous operating environments. The approach is expanding into cost-sensitive segments by reducing dysprosium and terbium unit consumption per kilogram of finished magnet.
REACH authorization requirements for nickel and cobalt compounds are tightening feedstock disclosure obligations across EU magnet supply chains. ECHA's candidate list expansion is forcing Japanese and South Korean magnet fabricators to document rare earth co-product traceability. Magnet-grade oxide shipments into Rotterdam and Hamburg are now requiring certified separation origin statements, with automotive Tier-1 suppliers conducting third-party audits.
Long-term offtake contracting is displacing spot market purchasing for magnet-grade neodymium-praseodymium oxide. European and North American automakers are negotiating five-to-seven-year supply agreements directly with Australian and US concentrate producers, bypassing traditional trading house intermediaries. This pattern is most visible in German OEM procurement offices, where dual-source mandates now specify minimum non-Chinese origin percentages for strategic motor programs.
Rare Earth Metals Market Segmentation
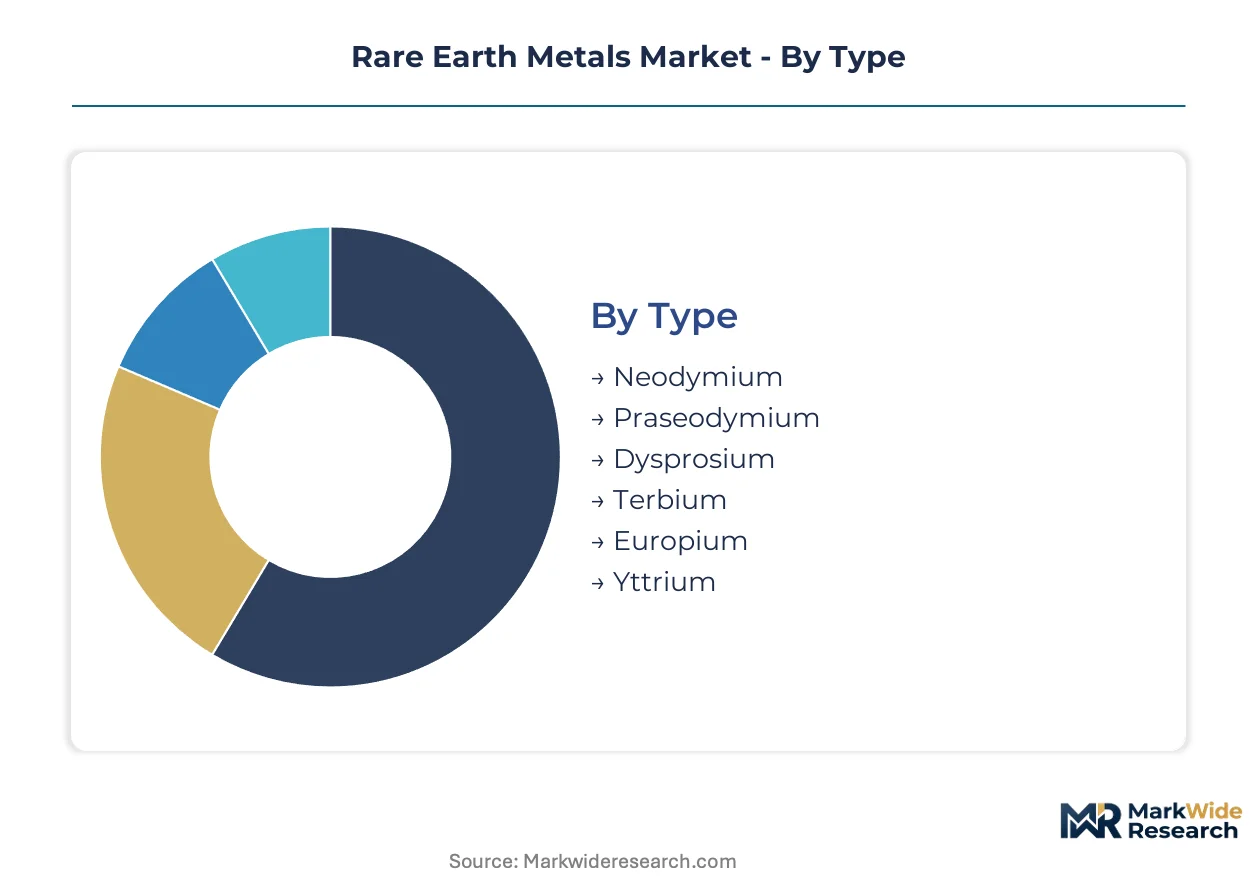
Rare earth supply chains fragment across elemental chemistry, downstream application, and extraction technology. Each segmentation layer determines pricing power, capital requirements, and geopolitical exposure for market participants.
Type:
Capital intensity peaks in heavy rare earth separation, where multi-stage solvent extraction circuits demand specialized infrastructure. Light rare earths require lower upfront investment but face oversupply pressure.
- Neodymium:This light rare earth constitutes the primary magnetic phase in neodymium-iron-boron alloys, typically comprising 12-14% by weight in sintered magnet formulations. Japanese and South Korean electronics manufacturers are scaling procurement of neodymium-praseodymium oxide blends for traction motor programs.
- Praseodymium:Alloyed with neodymium in a 1:4 ratio, this element enhances magnetic coercivity and corrosion resistance in high-temperature motor environments. German automakers are specifying minimum praseodymium content in dual-source magnet supply agreements.
- Dysprosium:Heavy rare earth deposited at grain boundaries to maintain magnetic performance above 150°C.
- Terbium:Critical for high-temperature stability in aerospace and defense magnet applications.
- Europium:Phosphor-activated red emission in display backlighting systems.
- Yttrium:Ceramic stabilizer and LED phosphor matrix component.
Most installed capacity flows through neodymium-praseodymium production. Expansion is steepest in dysprosium-terbium heavy rare earth circuits.
Application:
Application segmentation reveals divergent margin profiles, with magnet-grade materials commanding premium pricing over industrial chemical feedstocks.
- Electric Vehicles:Traction motors in 800-volt architectures require 1-2 kilograms of rare earth magnets per vehicle, with neodymium-iron-boron formulations specified for torque density targets. European OEM procurement offices are negotiating direct offtake agreements with Australian concentrate producers.
- Permanent Magnets:Beyond automotive, these alloys power wind turbine generators, hard disk drive voice coil motors, and industrial servo systems. Japanese magnet fabricators are qualifying grain-boundary diffusion treatments to reduce heavy rare earth unit consumption.
- Catalysts:Fluid catalytic cracking in petroleum refining consumes lanthanum-cerium fractions.
- Phosphors:Europium and terbium activated compounds enable LED and display illumination.
- Polishing Powders:Cerium oxide dominates optical glass and semiconductor wafer finishing.
- Fiber Optics:Erbium-doped amplifiers require specialized doping precursors.
Magnet applications absorb the majority of value creation. Electric vehicle traction motors are gaining share fastest among end-use categories.
End User Industry:
End user segmentation tracks regulatory exposure, with defense and aerospace programs subject to strict domestic content mandates.
- Electronics Manufacturing:Japanese and South Korean supply chains concentrate demand for magnet-grade oxides in precision motor and sensor applications. METI-coordinated bilateral agreements with Australian miners are reducing single-source dependency.
- Renewable Energy:Direct-drive wind turbines specify 600+ kilograms of rare earth magnets per megawatt of installed capacity. Offshore wind developers in the North Sea are requiring certified non-Chinese origin documentation.
- Defense & Aerospace:Guidance systems and radar components require heavy rare earth stabilized magnets with full supply chain traceability.
- Chemical Production:Refinery catalysts and industrial process chemicals consume light rare earth fractions.
- Telecommunications:Fiber optic infrastructure and satellite communication systems drive specialty doping demand.
Electronics manufacturing channels the largest volume. Renewable energy procurement is climbing the fastest among industrial verticals.
Extraction Method:
Extraction method determines project economics, with ionic clay deposits offering lower capital barriers than hard rock mining but concentrated geographic availability.
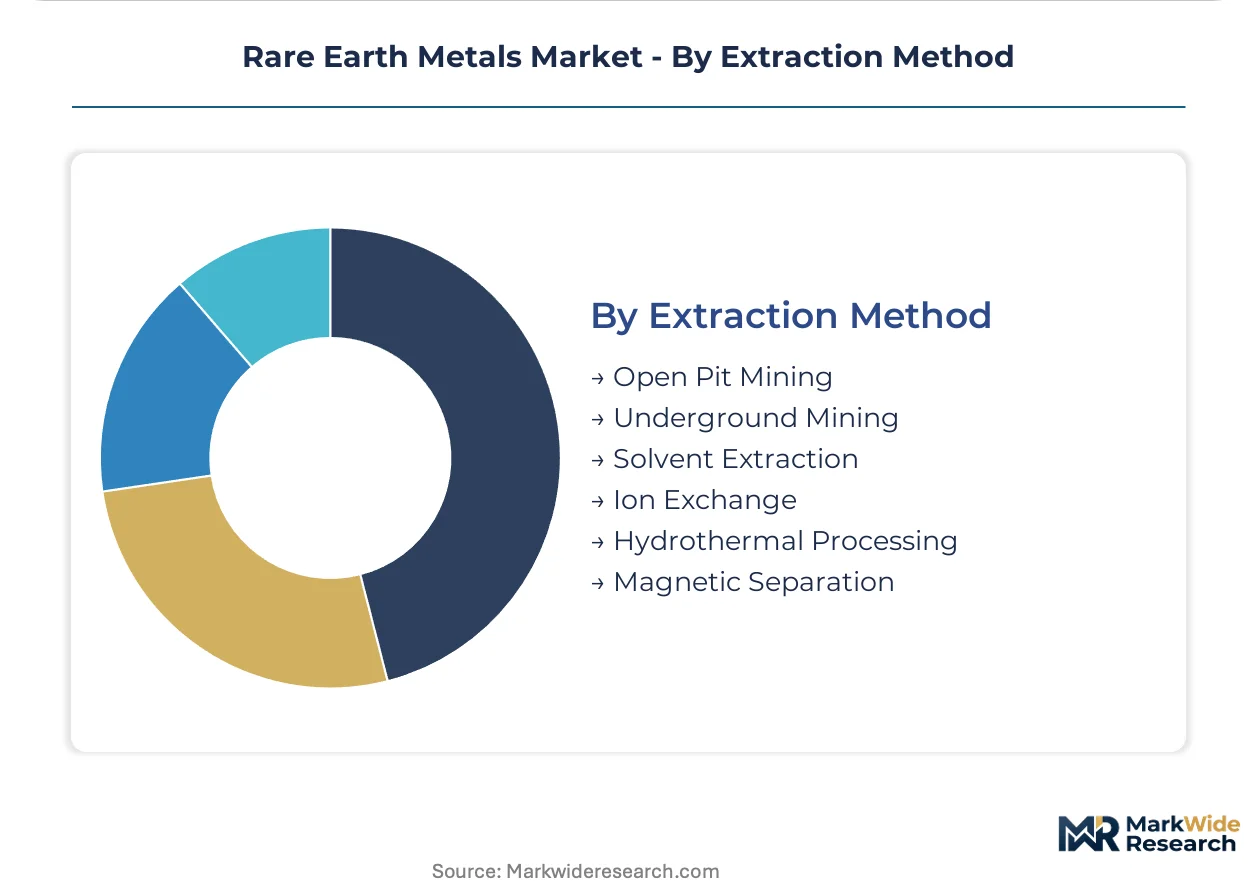
- Open Pit Mining:Hard rock deposits at Mountain Pass and Mount Weld employ conventional drilling and blasting followed by crushing and flotation concentration. MP Materials operates the only integrated rare earth mining and separation facility in the United States.
- Underground Mining:Higher-grade narrow vein deposits in China and Russia utilize shaft and drift extraction methods.
- Solvent Extraction:Multi-stage counter-current circuits achieve 99.9% purity separation of individual rare earth elements.
- Ion Exchange:Selective resin-based separation complements solvent extraction for high-value heavy rare earth recovery.
- Hydrothermal Processing:Alkaline cracking and acid leaching of refractory ore minerals.
- Magnetic Separation:Pre-concentration and monazite-xenotime separation in beach sand placer deposits.
Open pit and solvent extraction combinations dominate current supply. Ion exchange capacity is expanding most quickly for heavy rare earth recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting rare earth investment toward jurisdictions with lower compliance costs and explicit processing subsidies. Capital is migrating from quota-constrained environments toward regions offering domestic content credits and streamlined permitting.
United States
MP Materials operates the sole integrated mining and separation facility at Mountain Pass, California, supplying domestic magnet feedstock. The Inflation Reduction Act's domestic content credits are incentivizing sintered magnet production in Texas and the Mountain West. Defense procurement mandates from the Department of Defense are accelerating qualification of non-Chinese heavy rare earth sources for guidance systems.
China
MIIT production quotas and export licensing concentrate separation capacity within state-owned enterprises, constraining spot market liquidity for dysprosium and terbium. Beijing's consolidation of mining assets under SOE control is hardening supply-side discipline across the value chain. Inner Mongolia and Jiangxi province host the bulk of ionic clay processing infrastructure for heavy rare earth recovery.
Australia
Lynas Rare Earths sustains output from Mount Weld concentrate through Malaysian processing, representing the largest non-Chinese separation operation. METI-coordinated bilateral offtake agreements with Tokyo are reducing Japanese single-source dependency. Western Australia's mining jurisdiction is attracting greenfield development for dysprosium-terbium diversification outside Chinese jurisdiction.
Japan
Electronics manufacturers in Osaka and Nagoya are scaling procurement of neodymium-praseodymium oxide blends for traction motor programs. METI coordinates direct offtake agreements with Australian miners to secure magnet-grade concentrate pathways. Toyota and Honda powertrain divisions are qualifying grain-boundary diffusion treatments to reduce heavy rare earth unit consumption.
Germany
EU Critical Raw Materials Act processing targets and strategic stockpile mandates are compelling BMW and Volkswagen to secure magnet-grade oxide supply chains outside China. ECHA REACH authorization requirements are tightening feedstock disclosure obligations across magnet supply chains. Bavarian OEM procurement offices are negotiating five-to-seven-year supply agreements directly with Australian concentrate producers.
Rare Earth Metals Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue heavy rare earth diversification and recycling feedstock streams. The market structures around a handful of integrated miners with captive separation capacity and a longer tail of development-stage projects seeking offtake validation. Three archetypes dominate: quota-backed Chinese SOEs with downstream magnet integration, Western integrated miners with government offtake support, and Australian concentrate exporters with Asian processing partnerships. Capacity expansion and dual-source contracting represent the dominant competitive moves as automakers qualify alternative supply chains.
Among Australian-listed developers, Arafura Rare Earths and Brazilian Rare Earths exemplify the project-development archetype targeting heavy rare earth diversification outside Chinese jurisdiction. MP Materials occupies a position as the sole US-integrated operator, anchoring domestic magnet feedstock security. Lynas Rare Earths represents the non-Chinese separation specialist model, sustaining output through Malaysian processing of Mount Weld concentrate.
| Leading Market Players |
|---|
| Arafura Rare Earths |
| St George Mining |
| Lynas Rare Earths |
| Albemarle |
| Brazilian Rare Earths |
| MP Materials |
| Critical Metals Corp |
| IperionX |
| Iluka Resources |
| Others |
Cost & Logistics Intelligence
Neodymium-praseodymium oxide spot price indices cascade through magnet-grade oxide premiums into long-term offtake contract tiers, with Chinese MIIT export licensing constraints amplifying price spreads between spot and contracted volumes across Japanese and South Korean electronics supply chains.
Pricing Analysis
Distributor margins on magnet-grade oxides compress under direct-to-OEM contracting trends, with five-to-seven-year supply agreements displacing trading house intermediaries. Pricing stratifies across magnet-grade certification tiers, with automotive dual-source mandates commanding premiums over uncertified industrial feedstocks. Cost compression in light rare earth fractions intensifies as Chinese state-owned mining consolidation hardens supply-side discipline. Catalyst and polishing powder buyers exhibit highest price sensitivity, while defense procurement offices accept premium pricing for full traceability documentation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German and Japanese automakers, bypassing traditional concentrate traders. Supply concentrates in China, Australia, and Myanmar, with heavy rare earth recovery drawing from ionic clay deposits along Burmese border zones. Feedstock dependencies center on monazite-xenotime concentrates, solvent extraction reagents, and grain-boundary diffusion processing chemicals. Single-source vulnerability in dysprosium-terbium separation circuits exposes magnet fabricators to Beijing's export licensing disruptions. Distribution runs through Rotterdam and Hamburg for EU REACH compliance, with certified origin statements now mandatory for automotive Tier-1 qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with magnet-grade oxide specifications tightening as 800-volt EV architectures proliferate and grain-boundary diffusion treatments reduce heavy rare earth unit consumption.
For Market Incumbents: Cement dual-source contracting relationships with Australian concentrate producers before greenfield heavy rare earth capacity reaches commissioning. Lock in solvent extraction engineering talent pools through partnerships with Japanese technical institutes, as Western facility staffing constraints deepen. Defend against ferrite magnet substitution in auxiliary motor segments by qualifying higher-temperature neodymium-iron-boron formulations for cost-sensitive automotive tiers.
For New Entrants and Emerging Players: The EU Critical Raw Materials Act in Europe opens a window for heavy rare earth diversification projects in Western Australia and North American jurisdictions. Target recycling feedstock streams from end-of-life wind turbines and hard disk drives as the most penetrable concentrate source outside Chinese jurisdiction. Pursue hydrometallurgical recovery partnerships with German OEM procurement offices seeking circular supply chain credentials.
For Investors and Strategic Acquirers: Consolidation pressure builds where separation chemistry expertise concentrates within Chinese and Japanese technical institutes, constraining Western facility development timelines. Five-to-ten-year viability hinges on offtake contract tenor and strategic stockpile mandate alignment. Acquire developers with advanced Malaysian or Texas processing partnerships and MIIT-independent concentrate pathways. Watch Beijing's production quota announcements as the primary inflection signal for spot market liquidity and pricing volatility.
| Strategic Initiative | Industry Significance |
|---|---|
| Heavy Rare Earth Circuit Expansion | Western Australian ionic clay projects diversify dysprosium-terbium supply outside Chinese MIIT jurisdiction. |
| Grain-Boundary Diffusion Licensing | Toyota and Hyundai Motor Group adoption reduces heavy rare earth unit consumption per kilogram of finished magnet. |
| Recycling Feedstock Partnerships | End-of-life hard disk drives and wind turbines emerge as hydrometallurgical concentrate sources for European automakers. |
| Direct-to-OEM Contracting | BMW and Volkswagen procurement offices bypass trading houses through five-to-seven-year Australian concentrate agreements. |
| Solvent Extraction Talent Acquisition | Japanese technical institute partnerships address Western facility staffing constraints in multi-stage purification circuits. |
Research Approach
Bottom-up electric vehicle traction motor modeling reconciled against top-down rare earth concentrate production tracking forms the analytical core of this study. Primary interviews with magnet fabricator procurement directors, solvent extraction process engineers, OEM platform specification leads, and MIIT quota monitoring specialists combine with secondary validation from customs trade data, SEC mining company filings, ECHA REACH authorization databases, and METI bilateral offtake disclosure records. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Input-output matrices map neodymium-praseodymium oxide demand across magnet-grade purity tiers, electric vehicle motor architectures, and regional regulatory clusters throughout the projection horizon. CAGRs derive from segment-level volume build-ups reconciled against concentrate supply capacity announcements. Forecast inputs incorporate grain-boundary diffusion adoption curves, EU Critical Raw Materials Act processing target compliance timelines, and Chinese export licensing issuance patterns.
Revisions become necessary when Beijing's MIIT quota announcements, Brussels processing subsidy disbursements, or grain-boundary diffusion metallurgy breakthroughs materially alter supply-demand balances. Forecasts reflect documented assumptions regarding concentrate commissioning schedules and offtake contract closure rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Steel Market
Metals
Platinum Market
Metals
Steel Drums and Ibcs Market
Metals
Shipbuilding Steel Plate Market
Metals
Neodymium Market
Metals
Global Precious Metal Market
Metals
Steel Drums Market
Metals
Tungsten Metal Powder Market
Metals
Cerium Market
Metals
Iron and Steel Market
Metals
Nickel Foam Market
Metals
Global Flat Carbon Steel Market
Metals
Beryllium Copper Plate Market
Metals
Global Aluminum Market
Metals
Steel Salvage Drums Market
Metals
Global Brass Rods Market