
 Pesticide Inert Ingredients Market | 2026-2036
Pesticide Inert Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Pesticide Inert Ingredients Market Outlook
The EU Green Deal is realigning formulation priorities across the European crop protection sector. BASF SE leverages its integrated surfactant pipeline to sustain supply security for glyphosate adjuvants. Dow Inc. anchors North American solvent supply through its propylene oxide derivatives network. Clariant AG specializes in emulsifier systems that navigate tightening aquatic toxicity standards.
Pesticide inert ingredients encompass non-active formulation components—surfactants, solvents, emulsifiers, and fillers—that enable active ingredient dispersion, stability, and application efficacy, typically comprising 50–90% of formulated product mass by weight. These materials determine droplet spread on leaf surfaces, tank-mix compatibility, and drift reduction during aerial spraying. Solvent and surfactant ingredient types command the deepest margin pools due to patent-protected molecular architectures and toll-manufacturing relationships with agrochemical majors. Liquid formulations dominate agricultural channels, while granular formats retain strength in turf and ornamental applications where dust exposure must be minimized.
EPA registration requirements mandate full inert ingredient disclosure for new pesticide approvals, compelling suppliers to reformulate with EPA List 4A materials. REACH restricts certain petroleum-derived solvents, accelerating European demand for bio-based alternatives that comply with ECHA hazard classifications. India's Central Insecticides Board requires separate inert toxicity data for import registrations, adding compliance layers for multinational formulators. Stakeholders must monitor evolving substance bans and pre-approve replacement chemistries before pipeline disruptions materialize.
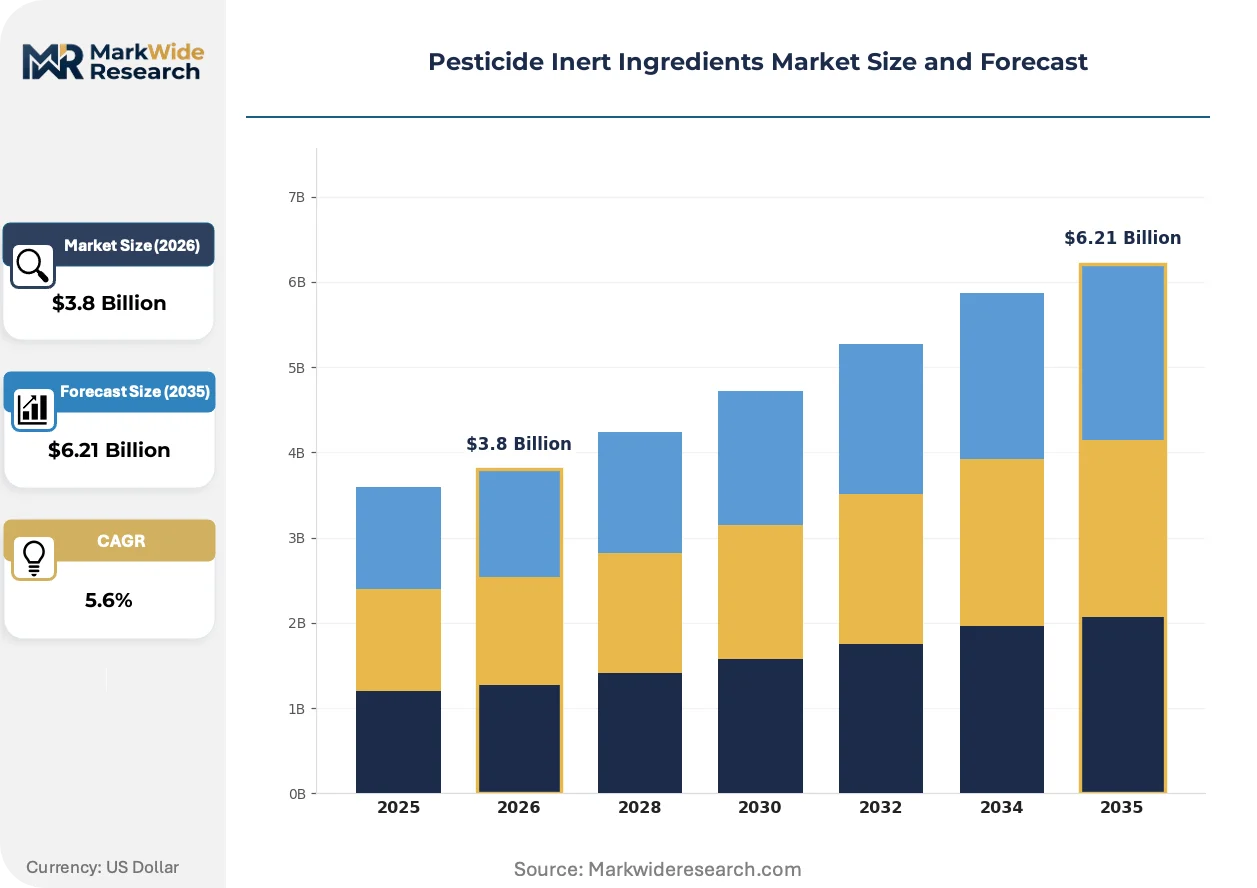
Market Dynamics
Formulation disclosure mandates from EPA and ECHA are compressing the supplier base, forcing agrochemical majors to pre-qualify alternative chemistries before pipeline disruptions materialize.
Growth Catalysts
- Bio-based surfactant procurement:Agricultural end users in Brazil's soybean belt are expanding orders for plant-derived adjuvants that meet ECHA aquatic toxicity thresholds.
- REACH solvent restrictions:The regulation's tightening hazard classifications are accelerating European demand for bio-based alternatives in crop protection formulations.
- India's import registration layers:The Central Insecticides Board's separate inert toxicity data requirements are creating captive formulation capacity for domestic suppliers.
Market Restraints
- Petroleum-derived solvent volatility:Propylene oxide feedstock costs swing with refinery crack spreads, compressing margin pools for North American solvent suppliers.
- List 4A material scarcity:EPA's approved inert inventory concentrates supply among toll-manufacturers with existing registration dossiers.
- Aquatic toxicity standard escalation:ECHA's chronic hazard reclassifications are retiring emulsifier chemistries faster than replacement pipelines can validate.
Strategic Opportunities
- Granular format conversion:Turf and ornamental channels in the United States are absorbing dust-minimized carriers that command formulation premiums over liquid equivalents.
- EU Green Deal alignment:The framework's biocidal product review timelines are creating first-mover windows for suppliers with pre-validated sustainable chemistries.
- Tank-mix compatibility services:Drift reduction adjuvant bundles are penetrating aerial spraying contractors in Australia's wheat belt through application-efficacy guarantees.
Industry Challenges
- Registration dossier preparation:EPA's full inert disclosure requirements demand 18-24 month pre-approval timelines that freeze formulation pipelines.
- Cross-border formulation reconciliation:India's separate toxicity data requirements force multinationals to maintain parallel product specifications for export versus domestic sale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pesticide Inert Ingredients Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Surfactants, Solvents, Emulsifiers, Fillers Application: Agricultural, Horticultural, Industrial, Residential Formulation: Liquid, Granular, Powder, Aerosol End User: Agriculture, Pest Control, Landscaping, Home Gardeners |
| Companies Covered | BASF SE, Dow Inc., Solvay SA, Clariant AG, Croda International, Stepan Company, Huntsman Corporation, Evonik Industries, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pesticide Inert Ingredients Market Strategic Shifts
Active ingredient delivery architectures are fragmenting as biologicals and precision application systems demand co-formulants with narrower compatibility windows.
Microemulsion concentrate technology is electrifying droplet spread dynamics on hydrophobic leaf surfaces. Specialty formulators in Brazil's Cerrado region are adopting these systems at pace to replace solvent-heavy emulsifiable concentrates. The shift is compressing demand for traditional aromatic hydrocarbon carriers while expanding patent-protected surfactant architectures.
EPA's 2024 inert ingredient disclosure expansion is forcing agrochemical registrants to submit full composition data for new product approvals. The industrial consequence is a supplier pre-qualification bottleneck that delays pipeline launches by 12-18 months. North American glyphosate adjuvant suppliers are responding by consolidating toll-manufacturing relationships with List 4A-approved material providers.
Application-efficacy guarantees are displacing commodity surfactant procurement in aerial spraying channels. Brazilian soybean cooperatives are bundling drift-reduction adjuvants with satellite-guided application services, unbundling the chemical purchase from the outcome contract. The model is most visible in Mato Grosso's 2024 planting season contracts.
Pesticide Inert Ingredients Market Segmentation
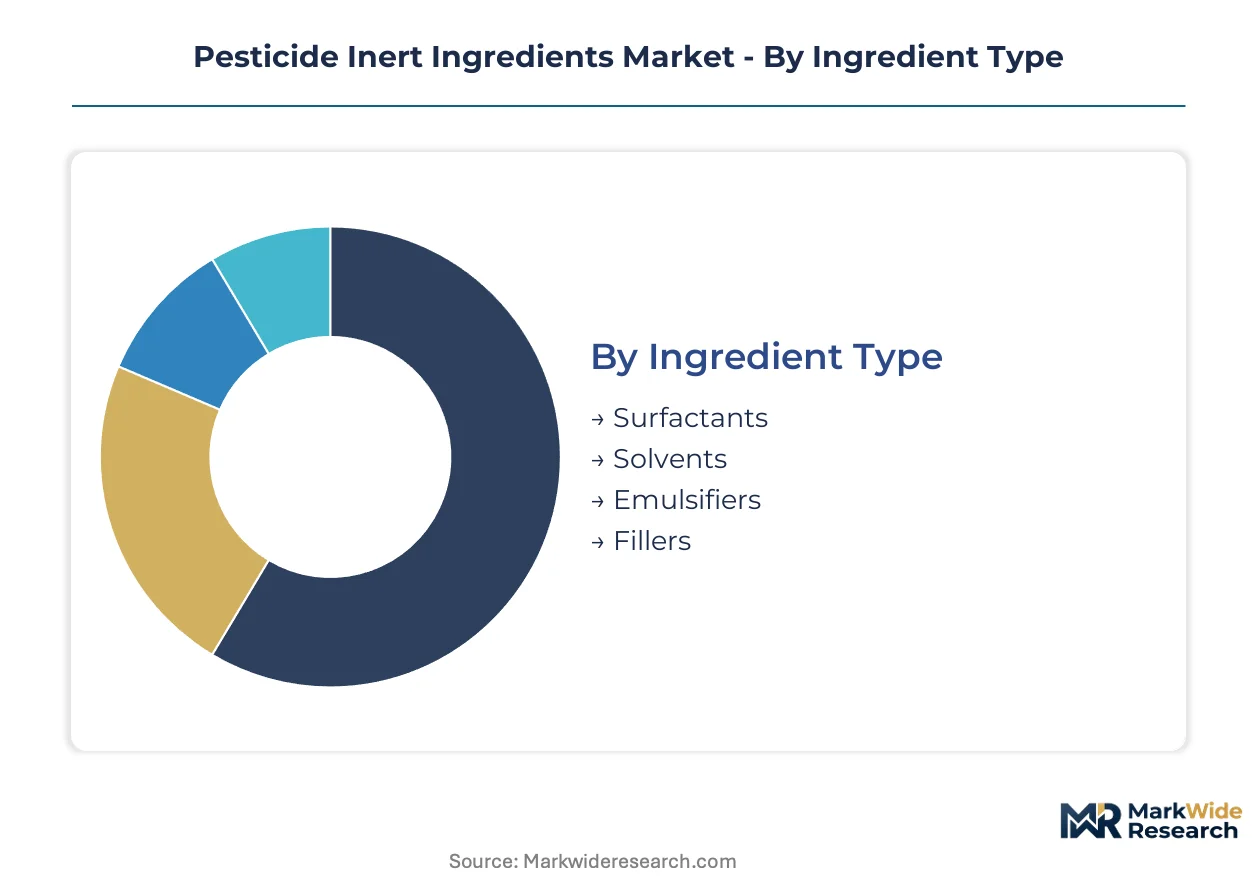
Ingredient type and formulation architecture determine margin capture and regulatory exposure across pesticide inert supply chains. Application channels diverge sharply between high-volume agricultural procurement and specification-driven horticultural contracting.
Ingredient Type:
Surfactants and solvents command premium positioning through patent-protected molecular architectures, while emulsifiers and fillers compete on volume scale.
- Surfactants:These surface-active agents reduce interfacial tension between hydrophobic leaf cuticles and aqueous spray solutions. Brazilian soybean cooperatives in Mato Grosso are expanding procurement of bio-based alkyl polyglucoside formulations that satisfy ECHA aquatic toxicity thresholds.
- Solvents:Petroleum-derived and bio-based carriers dissolve lipophilic active ingredients for uniform dispersion. REACH restrictions on aromatic hydrocarbons are accelerating European demand for terpene-based alternatives in glyphosate formulations.
- Emulsifiers:Stabilize oil-in-water dispersions for emulsifiable concentrate formulations.
- Fillers:Inert carriers like clay and cellulose provide bulk in granular and powder formulations.
Mature deployment sits with solvent systems in North American glyphosate supply chains. Newer deployment is concentrated in surfactant architectures compliant with tightening ECHA hazard classifications.
Application:
Agricultural channels absorb volume at commodity margins, while horticultural and industrial segments reward specification compliance with price premiums.
- Agricultural:Crop protection formulations for field-scale deployment dominate tonnage demand. India's cotton-growing states in Maharashtra and Gujarat are expanding procurement of tank-mix compatible adjuvant bundles for aerial spraying operations.
- Horticultural:Specialty fruit and vegetable production requires drift-minimized application systems. California's Central Valley nut orchards are specifying low-volatility solvent systems that comply with EPA regional air quality management district rules.
- Industrial:Right-of-way and structural pest control applications.
- Residential:Consumer lawn and garden products with simplified handling requirements.
Volume concentration rests with agricultural procurement. Margin expansion is climbing the fastest in horticultural channels where residue limits and application timing constraints command formulation premiums.
Formulation:
Liquid formats dominate agricultural throughput, while granular systems capture turf and ornamental premiums through dust exposure mitigation.
- Liquid:Emulsifiable concentrates and suspension concentrates enable rapid tank-mix preparation. Australia's wheat belt aerial spraying contractors are adopting microemulsion concentrates to replace solvent-heavy legacy formulations.
- Granular:Controlled-release carriers minimize applicator dust exposure. United States golf course superintendents are converting to dust-minimized granular carriers that command formulation premiums over liquid equivalents.
- Powder:Wettable powders for dry handling and extended shelf stability.
- Aerosol:Pressurized dispensers for residential and industrial spot treatment.
Established infrastructure supports liquid formulation deployment. Emerging conversion is visible in granular formats for occupational exposure-sensitive applications.
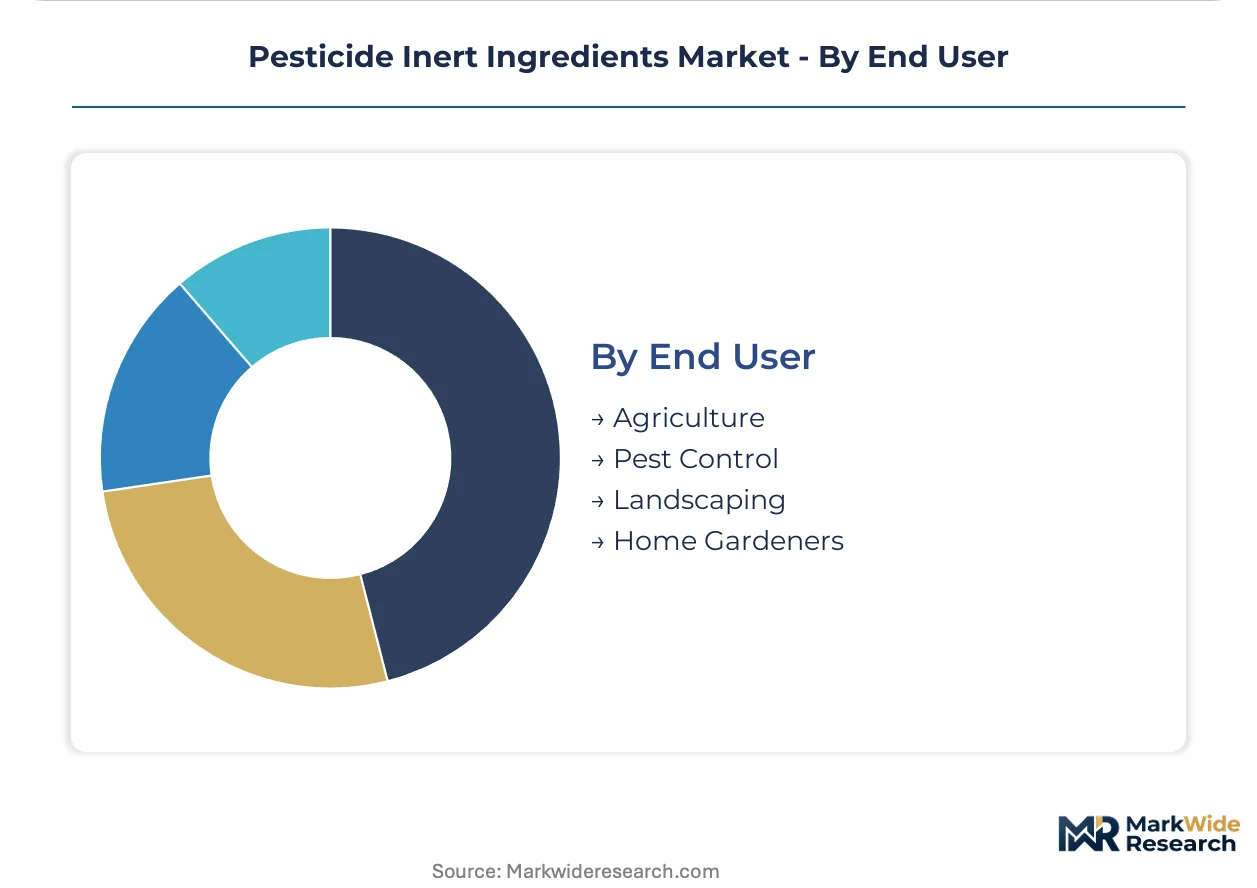
End User:
Professional agriculture drives specification complexity, while residential channels prioritize handling simplicity and retail shelf presence.
- Agriculture:Large-scale farming operations and cooperative procurement networks. Brazil's Cerrado region soybean producers are bundling drift-reduction adjuvants with satellite-guided application services under outcome-based contracting models.
- Pest Control:Licensed applicators serving structural and commercial accounts.
- Landscaping:Commercial turf maintenance and ornamental plant management.
- Home Gardeners:Consumer retail channels with pre-mixed, ready-to-use packaging formats.
Procurement sophistication concentrates with agricultural end users. Simplified deployment dominates home gardener segments where pre-formulated convenience overrides technical specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mato Grosso's soybean belt concentrates bio-based surfactant procurement for glyphosate adjuvants, with cooperatives bundling drift-reduction formulations into satellite-guided application contracts. EPA registration requirements in the United States and REACH restrictions in Europe are diverting formulation investment toward compliant chemistry pipelines.
United States
California's Central Valley nut orchards drive demand for low-volatility solvent systems that satisfy EPA regional air quality management district rules. The EPA's 2024 inert ingredient disclosure expansion mandates full composition data for new pesticide approvals, compressing supplier pre-qualification timelines. North American glyphosate adjuvant suppliers are consolidating toll-manufacturing relationships with List 4A-approved material providers.
Brazil
Soybean cooperatives in Mato Grosso and the broader Cerrado region are expanding orders for plant-derived adjuvants that meet ECHA aquatic toxicity thresholds. ANVISA alignment with international hazard classification standards is accelerating domestic reformulation of emulsifiable concentrates. Specialty formulators in Brazil's agricultural interior are adopting microemulsion concentrate technology to replace solvent-heavy legacy systems.
India
Maharashtra and Gujarat cotton-growing states are expanding procurement of tank-mix compatible adjuvant bundles for aerial spraying operations. The Central Insecticides Board requires separate inert toxicity data for import registrations, creating captive formulation capacity for domestic suppliers. Indian formulators are building parallel product specifications to serve export versus domestic sale channels.
Germany
BASF SE's integrated surfactant pipeline in Ludwigshafen sustains supply security for European glyphosate adjuvant production. REACH restrictions on aromatic hydrocarbon solvents are accelerating demand for terpene-based alternatives in crop protection formulations. German chemical clusters are pre-validating sustainable chemistries to capture EU Green Deal biocidal product review first-mover windows.
Australia
Wheat belt aerial spraying contractors are adopting microemulsion concentrates to replace solvent-heavy legacy formulations. The TGA and APVMA alignment with OECD hazard testing guidelines is streamlining registration pathways for imported adjuvant chemistries. Application-efficacy guarantees are penetrating contractor channels through drift-reduction adjuvant bundles with outcome-based contracting.
Pesticide Inert Ingredients Market Competitive Environment
Premium-margin players sit above commodity-margin players across patent-protected molecular architectures and toll-manufacturing relationships. The supplier base compresses around List 4A-approved material providers as EPA disclosure mandates freeze formulation pipelines. Three archetypes dominate: integrated chemical majors with captive surfactant pipelines, specialty surfactant houses with ECHA-compliant bio-based portfolios, and toll-manufacturers with existing registration dossiers. Competitive moves concentrate on pre-qualification partnerships with agrochemical majors and geographic expansion into Brazil's soybean belt and India's cotton-growing states.
Among European integrated majors, BASF SE and Solvay SA exemplify the premium-tier archetype through captive supply chain control over surfactant and solvent intermediates. Dow Inc. anchors North American positioning through propylene oxide derivatives networks. Clariant AG occupies a specialist position within the emulsifier tier, navigating tightening aquatic toxicity standards through molecular architecture differentiation. Croda International represents the bio-based transition archetype, with formulation portfolios aligned to REACH solvent restrictions and EU Green Deal compliance windows.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Solvay SA |
| Clariant AG |
| Croda International |
| Stepan Company |
| Huntsman Corporation |
| Evonik Industries |
| Eastman Chemical Company |
| Others |
Value Chain & Pricing Dynamics
Microemulsion concentrate technology is compressing cost economics for solvent-heavy emulsifiable concentrates while concentrating supply among patent-protected surfactant architects. This production-method transition simultaneously elevates formulation premiums for compliant chemistries and consolidates toll-manufacturing relationships around List 4A-approved material providers.
Pricing Analysis
Outcome-based contracting anchored to application efficacy guarantees commands premium positioning in Brazilian soybean cooperatives. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-compliant bio-based surfactants from petroleum-derived alternatives and commodity fillers. Pricing pressure stems from propylene oxide feedstock volatility compressing North American solvent margins. Agricultural cooperatives in Brazil and India exhibit highest price sensitivity, while California nut orchard operators accept formulation premiums for low-volatility compliance.
Supply Chain Analysis
Freight cost differentials between Ludwigshafen chemical clusters and Mato Grosso formulation facilities favor regional toll-manufacturing partnerships over transatlantic solvent shipments. Supply concentrates in Germany, Brazil, and India, with raw material dependencies on propylene oxide derivatives, terpene-based carriers, and plant-derived alkyl polyglucosides. Single-source vulnerability sits with EPA List 4A-approved inventory concentration. Distribution runs through agrochemical majors' captive formulation networks and cooperative procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EPA's full inert disclosure requirements erect 18-24 month registration barriers that freeze out undercapitalized competitors.
For Market Incumbents: Deploy backward integration into bio-based surfactant feedstocks to secure supply continuity as REACH aromatic hydrocarbon restrictions accelerate. Consolidate toll-manufacturing relationships with List 4A-approved providers before EPA disclosure mandates compress viable supplier pools. BASF SE's integrated Ludwigshafen pipeline exemplifies the defensive architecture required against formulation pipeline freezes. For New Entrants and Emerging Players: Australian wheat belt aerial spraying contractors represent an underserved buyer archetype seeking drift-reduction adjuvant bundles with application-efficacy guarantees. Penetrate through tank-mix compatibility services that unbundle chemical purchase from outcome contracts. Target microemulsion concentrate technology adoption gaps in Brazil's Cerrado region where specialty formulators lag multinational deployment timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty surfactant houses with ECHA-compliant bio-based portfolios and existing EPA registration dossiers. Long-term viability favors toll-manufacturers with validated chemistry pipelines over commodity solvent suppliers exposed to petroleum feedstock volatility. Watch for EU Green Deal biocidal product review timeline accelerations as inflection signals for first-mover premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Captive supply of plant-derived alkyl polyglucosides secures ECHA compliance ahead of REACH solvent restrictions. |
| List 4A Registration Dossier Acquisition | Pre-qualified chemistry pipelines eliminate 18-24 month EPA approval delays for agrochemical majors. |
| Regional Toll-manufacturing Partnerships | Mato Grosso and Maharashtra facilities reduce freight exposure to propylene oxide derivative supply chains. |
| Microemulsion Concentrate Technology Licensing | Patent-protected architectures replace solvent-heavy emulsifiable concentrates in Brazil's Cerrado region. |
| Outcome-based Contracting Model Expansion | Satellite-guided application bundles in Australian wheat belt penetrate aerial spraying contractor channels. |
Study Parameters
Independent corroboration across agrochemical formulator executives, EPA registration consultants, and Brazilian cooperative procurement managers underwrites the qualitative findings. Primary interviews with surfactant R&D directors, toll-manufacturing plant managers, and Indian Central Insecticides Board compliance officers combined with secondary validation from EPA registration databases, ECHA substance dossiers, REACH restriction timelines, and customs trade data. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across ingredient type, formulation architecture, and application channel dimensions.
Historical reference periods anchored the forecast window to pre-pandemic baseline demand patterns and post-2022 regulatory acceleration phases. The analytical framework models surfactant, solvent, emulsifier, and filler segments across liquid, granular, powder, and aerosol formulations, with end-use splits between agricultural, horticultural, industrial, and residential channels. CAGRs derive from regression analysis against active ingredient deployment trajectories and regulatory compliance cost curves. Industry-specific inputs include glyphosate adjuvant demand elasticity and ECHA aquatic toxicity reclassification schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA disclosure mandate enforcement intensity and REACH solvent restriction expansion timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
2,3-Butanediol Market
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
Singapore Sealants Market
Industrial Chemicals
Screw Separators Market
Industrial Chemicals
Kraft Lignin Products Market
Industrial Chemicals
Machine Tool Oils Market
Industrial Chemicals
Blown Oils Market
Industrial Chemicals
Sulphur Recovery Technologies Market
Industrial Chemicals
Fischer-Tropsch (FT) Wax Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Hydrofluoric Acid (HF) for Semiconductor Market
Industrial Chemicals
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market
Industrial Chemicals
Rust Preventive Oil Market
Industrial Chemicals
Food Grade Grease Market