
 Removable Adhesive Market | 2026-2036
Removable Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Removable Adhesive Market Analytics
Multi-source procurement for acrylic resin feedstocks is rebalancing supply risk across the removable adhesive value chain. Henkel AG & Co. KGaA leverages its European manufacturing footprint to sustain formulation consistency for automotive and electronics clients. Tesa SE anchors its position through precision tape manufacturing for surface protection applications. 3M Company dominates the high-performance segment with proprietary polymer platforms that command premium positioning in industrial channels.
Removable adhesive denotes a bonding agent engineered for temporary attachment with clean release from substrates such as glass, metal, polymer, or painted surfaces, typically formulated with tackified styrene block copolymers or UV-curable acrylics exhibiting peel adhesion below 50 ounces per inch. The primary commercial purpose centers on protecting surfaces during manufacturing, enabling repositionable labels, and supporting temporary assembly in electronics and automotive production. Pressure-sensitive formulations occupy the largest volume share due to their instant tack and room-temperature applicability across packaging and labeling workflows. Water-soluble variants represent the fastest-growing chemistry as sustainability mandates in Europe and East Asia push brands toward wash-away label adhesives for recyclable containers. The dots and tapes forms capture disproportionate margin pools in precision electronics assembly, where dimensional consistency and residue-free removal justify unit price premiums over rolls and sheets.
The EPA regulates volatile organic compound emissions from adhesive manufacturing facilities in the United States, constraining solvent-based formulation choices and accelerating waterborne and hot-melt technology transitions. REACH compliance in Europe mandates substance registration and restriction protocols that elevate R&D costs for non-EU suppliers seeking market access. OSHA workplace exposure limits for isocyanates and solvent vapors shape plant-level process design and personal protective equipment requirements across domestic production sites. Stakeholders must monitor evolving extended producer responsibility frameworks in major economies, as packaging recyclability regulations will increasingly dictate adhesive selection criteria for brand owners and contract packagers.
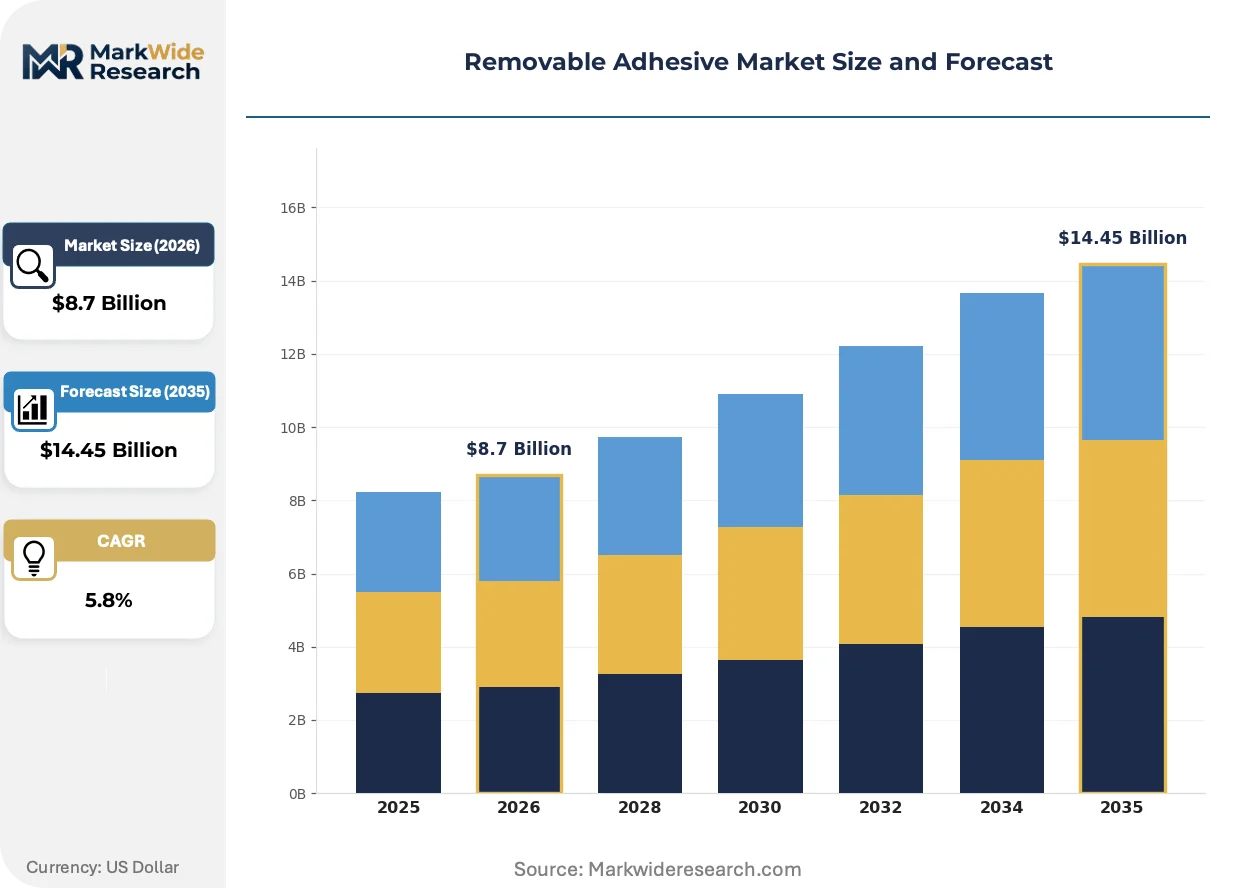
Market Dynamics
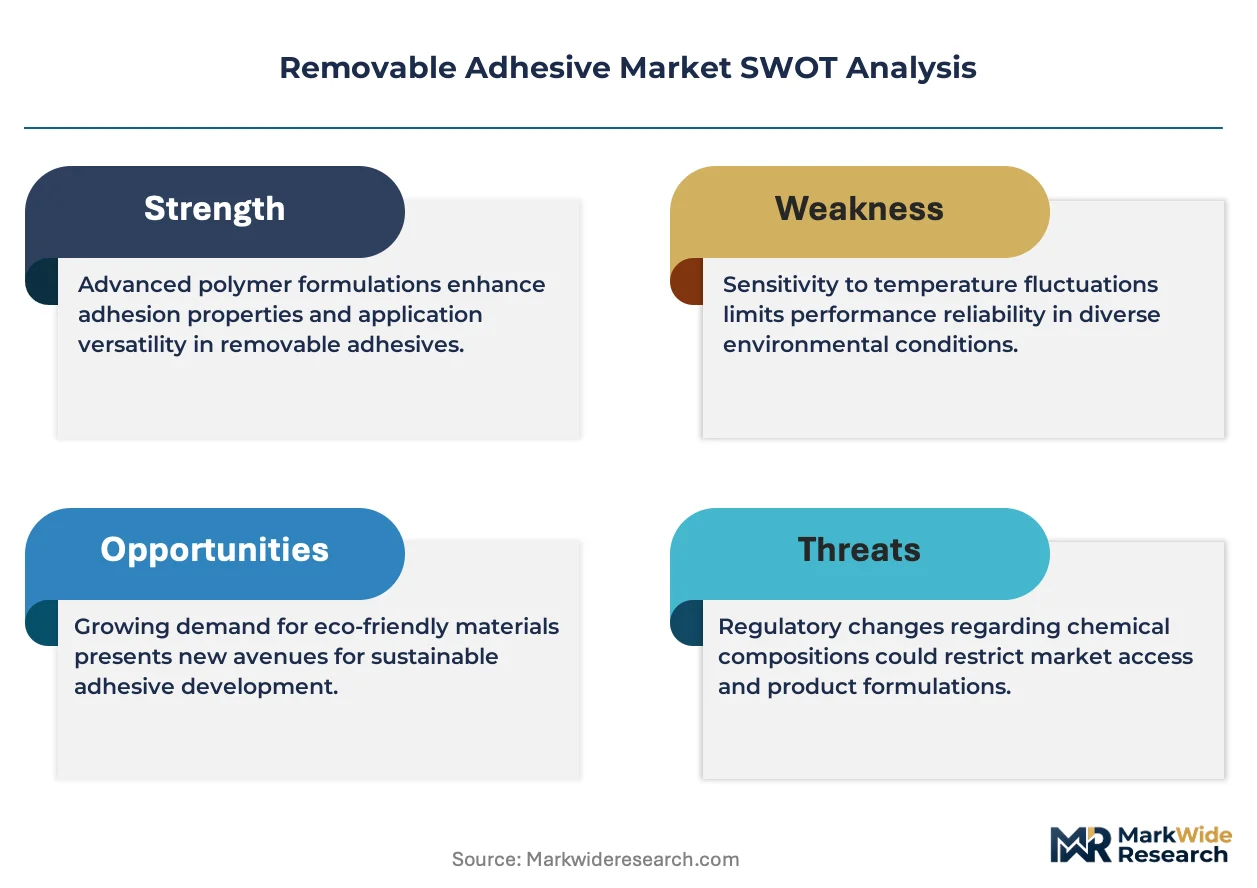
Pressure-sensitive adhesive formulations face mounting formulation complexity as REACH substance restrictions and EPA volatile organic compound limits simultaneously constrain solvent-based chemistries while electronics manufacturers demand residue-free temporary bonding for ever-smaller device assemblies.
Growth Catalysts
- EU Green Deal packaging recyclability mandates:Wash-away label adhesives gain procurement priority among European beverage brands seeking circular economy compliance without compromising label repositionability during filling operations.
- Consumer electronics miniaturization:Temporary bonding dots and tapes replace mechanical fasteners in smartphone and tablet assembly lines, where clean release protects delicate glass and polymer substrates during component placement.
- China dual carbon goals:Domestic packaging converters accelerate waterborne removable adhesive adoption to meet provincial emissions reduction targets while serving export markets with tightening environmental specifications.
Market Restraints
- Acrylic resin feedstock concentration:Asian petrochemical complexes supply over seventy percent of specialty tackifier resins, exposing formulators to shipping disruption and currency fluctuation risks.
- UV-curable chemistry cost premiums:Photoinitiator and oligomer inputs command three-to-four-fold pricing over conventional hot-melt formulations, limiting penetration in price-sensitive industrial labeling segments.
- Silicone adhesive substitution:Platinum-catalyzed silicone pressure-sensitive adhesives offer superior thermal stability for automotive electronics, displacing acrylic removable formulations in under-hood applications above 120 degrees Celsius.
Strategic Opportunities
- India PLI scheme electronics manufacturing:Contract assemblers in Tamil Nadu and Karnataka seek localized removable adhesive supply for smartphone and component production under production-linked incentive contracts.
- Biodegradable starch-based formulations:Fermentation-derived polysaccharide adhesives paired with compostable paper facestocks address emerging extended producer responsibility frameworks for single-use packaging in France and Italy.
- Direct-to-converter digital platforms:Specialty tape manufacturers bypass traditional distribution tiers by offering customized slit-width configurations through online portals serving mid-sized electronics contract manufacturers.
Industry Challenges
- Formulation chemist talent scarcity:Retirement waves among adhesive polymer scientists with styrene block copolymer expertise constrain R&D throughput at mid-sized European specialty chemical firms.
- Multi-jurisdiction substance notification:Parallel REACH, TSCA, and China MEE new chemical registration requirements extend product launch timelines by eighteen to twenty-four months for novel bio-based removable adhesive platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Removable Adhesive Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensitive, Water Soluble, Heat Activated, Double-Sided Application: Packaging, Labeling, Surface Protection, Automotive End User: Construction, Retail, Consumer Goods, Electronics Form: Rolls, Sheets, Tapes, Dots |
| Companies Covered | 3M Company, Henkel AG & Co. KGaA, Tesa SE, Avery Dennison Corporation, Nitto Denko Corporation, H.B. Fuller Company, Sika AG, Shurtape Technologies, Intertape Polymer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Removable Adhesive Market Evolving Landscape
Removable adhesive technology trajectories center on clean-release chemistry advancement, regulatory-driven sustainability transitions, and procurement model digitization that collectively compress traditional specification-to-supply cycles.
UV-LED curable acrylic removable adhesives are converging with precision electronics assembly workflows. Smartphone and display manufacturers in South Korea and Taiwan adopt these formulations for temporary protective film bonding. The technology enables instant cure at reduced energy intensity while eliminating thermal damage to heat-sensitive OLED substrates, compressing capital requirements for cleanroom adhesive application stations.
REACH Annex XIV authorization requirements for certain phthalate plasticizers force reformulation of legacy tackified styrene block copolymer adhesives. European tape converters face supply continuity decisions as substances of very high concern sunset dates approach. Automotive interior trim protection film suppliers accelerate migration to hydrogenated hydrocarbon resin alternatives despite requalification costs and peel adhesion performance verification.
Specification-driven procurement now dominates removable adhesive selection for multinational electronics original equipment manufacturers. Centralized technical teams in Shenzhen and San Jose consolidate approved vendor lists around residue-free performance certifications. Tier-one contract manufacturers in Vietnam and Mexico face compressed qualification windows as brand owners push supply base consolidation to simplify audit and compliance documentation.
Removable Adhesive Market Segmentation
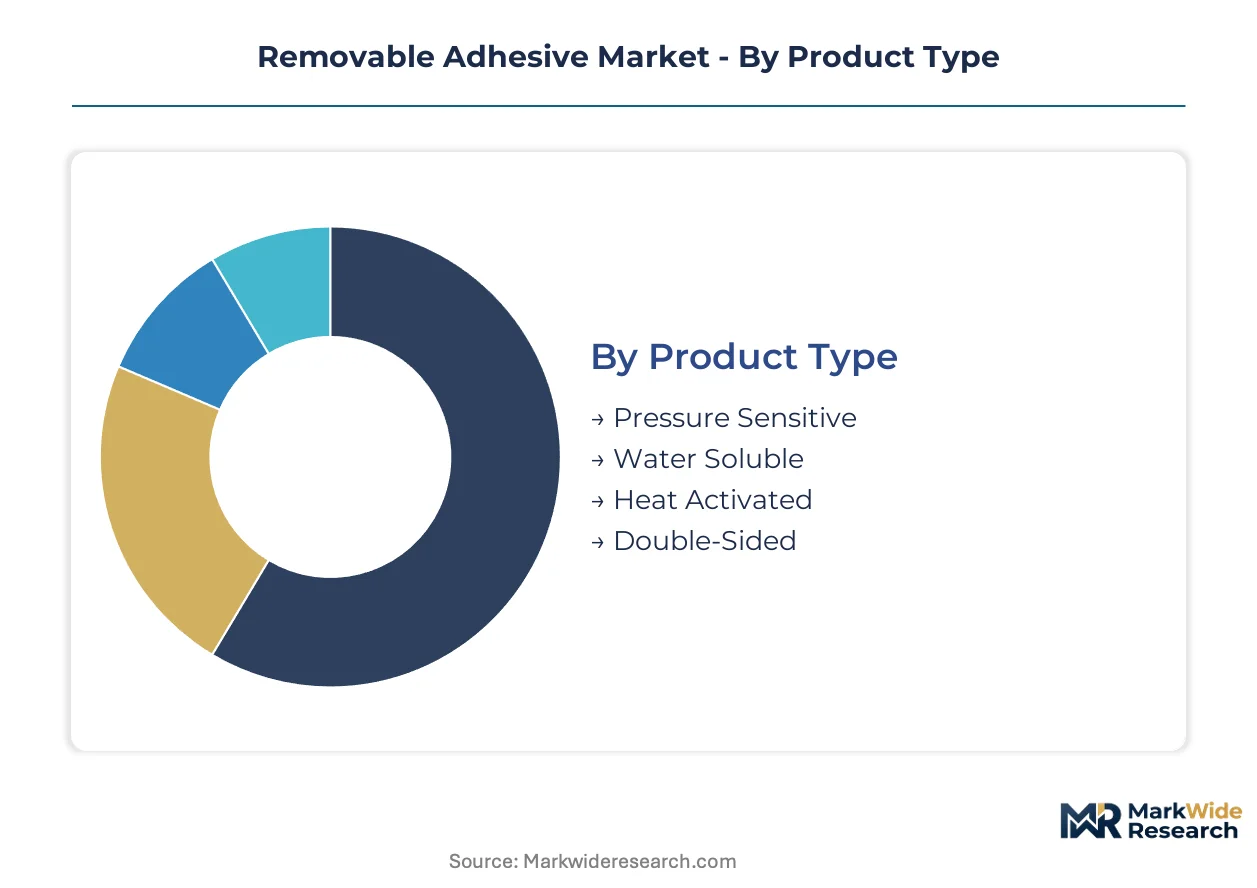
Removable adhesive procurement decisions pivot on chemistry-performance tradeoffs and application-specific release requirements. Electronics manufacturers and packaging converters drive specification fragmentation as temporary bonding needs diverge across device assembly and circular economy compliance.
Product Type:
Upgrade cycles in electronics assembly and sustainability mandates in beverage packaging are rebalancing chemistry preferences across formulator portfolios.
- Pressure Sensitive:Formulated with tackified styrene block copolymers or UV-curable acrylics exhibiting instant tack at room temperature. Electronics contract manufacturers in Vietnam and Mexico specify these for temporary protective films during smartphone assembly where clean release protects glass substrates.
- Water Soluble:Polyvinyl alcohol or starch-based polymers engineered for complete dissolution in aqueous wash systems. European beverage brands under EU Green Deal packaging mandates prioritize these for recyclable container labels requiring repositionability during filling operations.
- Heat Activated:Thermoplastic formulations requiring thermal energy to achieve tack and release characteristics.
- Double-Sided:Carrier-supported constructions enabling temporary bonding between two substrates with differential release properties.
Volume sits with Pressure Sensitive; growth tilts toward Water Soluble.
Application:
Cost tier differentiation separates commodity packaging procurement from precision electronics specification where residue-free performance commands price premiums.
- Packaging:Repositionable carton sealing and temporary closure applications dominate procurement volumes among Asian export-oriented converters.
- Labeling:Wash-away adhesives for recyclable containers and removable price labels represent the steepest expansion trajectory as extended producer responsibility frameworks tighten across France and Italy.
- Surface Protection:Precision-cut films for automotive interior trim and electronic display glass during manufacturing and transit.
- Automotive:Temporary bonding for interior assembly and paint protection films requiring clean release from painted metal and polymer substrates.
Packaging commands procurement scale; Labeling captures specification-driven margin expansion.
End User:
Customer type fragmentation reflects divergent technical requirements between project-based construction procurement and continuous manufacturing in electronics.
- Construction:Temporary flooring protection and surface masking during finishing operations with emphasis on residue-free removal from cured concrete and painted drywall.
- Retail:Point-of-sale display mounting and promotional signage requiring clean removal from fixture surfaces without substrate damage.
- Consumer Goods:Appliance manufacturers specify removable protective films for stainless steel and glass surfaces during distribution.
- Electronics:Smartphone, tablet, and display manufacturers in South Korea and Taiwan drive precision tape and dot specifications for component placement and temporary bonding.
Electronics concentrates R&D attention; Construction anchors project-based procurement volumes.
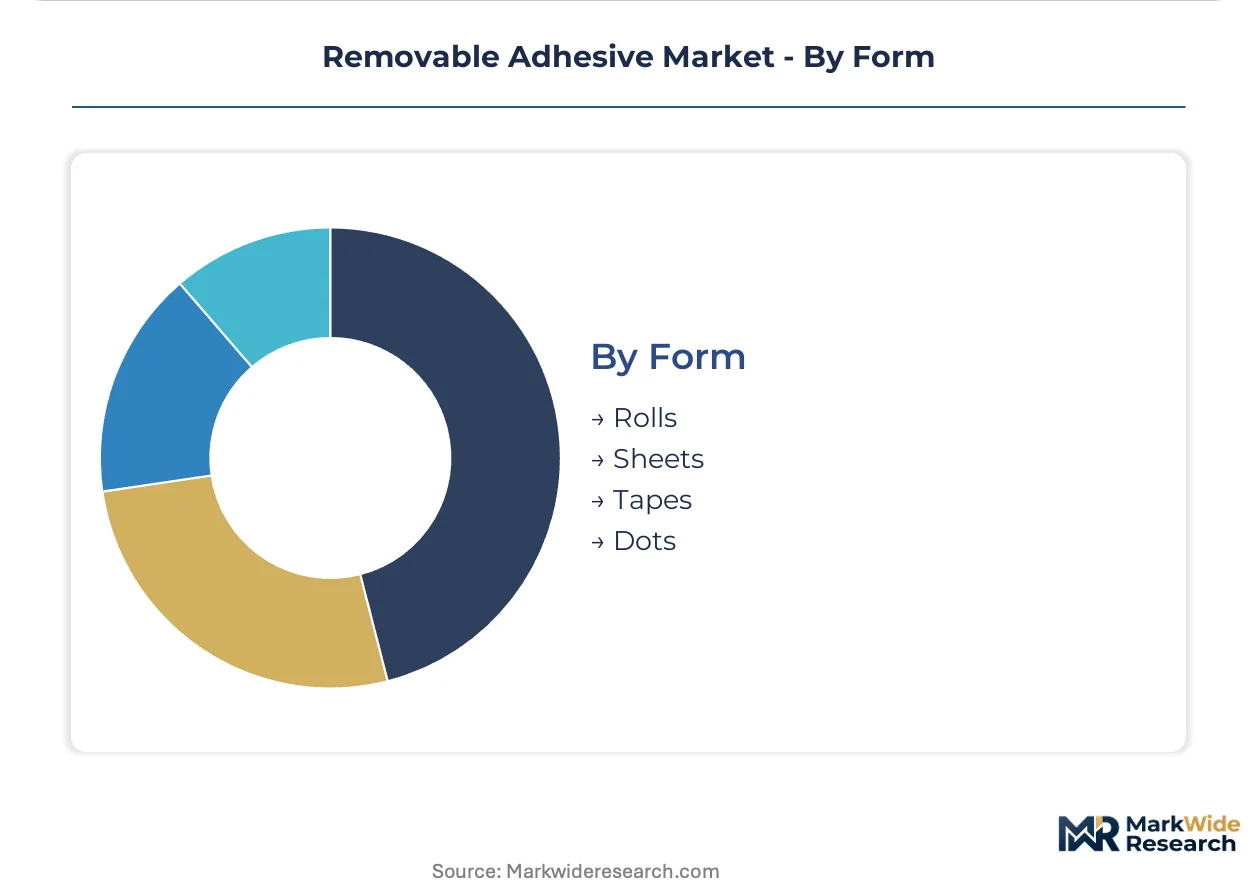
Form:
Supply concentration in precision slitting capabilities separates tape and dot manufacturers from commodity roll converters.
- Rolls:Standard-width master rolls serving downstream converters with basic slitting and die-cutting requirements.
- Sheets:Pre-cut dimensions for manual application in construction surface protection and retail display mounting.
- Tapes:Precision-slit configurations for automated electronics assembly lines where dimensional consistency enables high-speed application.
- Dots:Miniaturized circular formats for temporary component bonding in miniaturized device assemblies where mechanical fasteners prove impractical.
Rolls dominate converter feedstock procurement; Dots expand fastest in precision electronics workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics manufacturing clusters in China, South Korea, and Taiwan concentrate procurement of precision removable adhesives for temporary bonding applications. Packaging converters across Germany, the United States, and Japan drive demand for wash-away and repositionable label formulations. Regulatory divergence between REACH substance restrictions, EPA volatile organic compound limits, and China's dual carbon goals fragments formulation requirements across major production hubs.
China
Consumer electronics contract manufacturers in Shenzhen and Dongguan specify pressure-sensitive removable tapes for smartphone assembly workflows. Provincial emissions reduction targets under the dual carbon policy accelerate waterborne adhesive adoption among packaging converters in Guangdong and Jiangsu. The Yangtze River Delta cluster hosts specialty chemical formulators serving both domestic brands and export-oriented electronics assemblers.
United States
Automotive interior trim suppliers in Michigan and Ohio procure surface protection films requiring clean release from painted polymer substrates. EPA volatile organic compound emission limits constrain solvent-based formulation choices at manufacturing facilities in the industrial Midwest. Electronics assembly operations in Austin and Silicon Valley drive specification of precision-cut removable dots for semiconductor packaging workflows.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg mandate residue-free protective films for paint and interior surfaces during assembly and transit. REACH Annex XIV authorization timelines force reformulation of legacy tackified styrene block copolymer adhesives used in tape manufacturing. The Rhine-Ruhr industrial corridor anchors European production of hydrogenated hydrocarbon resin alternatives for automotive applications.
South Korea
Display manufacturers in Gyeonggi Province adopt UV-LED curable removable adhesives for temporary protective film bonding on OLED panels. MFDS chemical substance notification requirements extend product registration timelines for imported bio-based adhesive platforms. The Suwon-Siheung cluster concentrates precision electronics assembly driving miniaturized dot and tape specifications.
Japan
Precision equipment manufacturers in the Nagoya and Osaka regions specify removable adhesives for temporary component fixation during optical and semiconductor device assembly. METI circular economy guidelines push packaging converters toward water-soluble label formulations for recyclable container applications. The Kanto region hosts formulation R&D operations serving both domestic electronics brands and regional export markets.
Removable Adhesive Market Competitive Landscape
Portfolio diversification dominates the current landscape as established chemical conglomerates and precision tape specialists reposition around regulatory-driven formulation shifts. The market exhibits tiered concentration: multinational adhesive platforms with polymer science capabilities occupy premium specification channels, while regional converters serve commodity packaging procurement with standardized hot-melt and waterborne formulations. Three archetypes define competitive positioning: diversified chemical conglomerates leveraging cross-sector polymer expertise, precision tape specialists with slitting and die-cutting capabilities, and regional formulators optimizing for local regulatory compliance. Dominant moves include backward integration into tackifier resin supply and geographic expansion through distributor acquisition in Southeast Asian electronics hubs.
Among diversified chemical platforms, 3M Company and Henkel AG & Co. KGaA exemplify the polymer science-driven tier serving precision electronics and automotive specification channels. Tesa SE occupies a position within the precision tape specialist archetype, anchoring European supply for surface protection applications. These three entities represent contrasting strategic postures: the diversified conglomerate model spanning multiple adhesive chemistries and end-use segments, versus the focused specialist approach concentrating dimensional precision and clean-release performance verification.
| Leading Market Players |
|---|
| 3M Company |
| Henkel AG & Co. KGaA |
| Tesa SE |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| H.B. Fuller Company |
| Sika AG |
| Shurtape Technologies |
| Intertape Polymer Group |
| Others |
Value Network & Pricing Analysis
Performance-grade certification divergence between residue-free electronics specifications and commodity packaging grades generates parallel pricing architectures and sourcing configurations. Electronics manufacturers in South Korea and Taiwan pay substantial premiums for MFDS-registered precision dots and tapes, while Asian packaging converters source unregistered waterborne formulations through distributor networks at substantially lower unit economics.
Pricing Analysis
Volume concentrates in commodity-grade pressure-sensitive rolls serving Asian packaging converters, while margin pools accrue to precision-cut dots and tapes for electronics assembly. Price differentiation hinges on clean-release certification tier and automated application compatibility, with UV-curable acrylics commanding substantial premiums over hot-melt styrene block copolymers. Pricing pressure stems from silicone adhesive substitution in automotive electronics above 120 degrees Celsius, compressing acrylic formulation margins in under-hood applications. Packaging converters exhibit highest price sensitivity, whereas smartphone OEMs prioritize residue-free performance over unit cost.
Supply Chain Analysis
Freight cost volatility from Asian petrochemical complexes to European tape converters has elevated regional formulation investments as a risk-mitigation priority. Specialty tackifier resin production concentrates in China, South Korea, and Japan, with formulators drawing from these feedstock hubs for styrene block copolymer and acrylic polymer inputs. Single-source vulnerability in photoinitiator supply for UV-curable platforms exposes electronics adhesive manufacturers to semiconductor-industry demand shocks. Distribution runs through authorized distributor networks for precision electronics grades, while commodity packaging adhesives flow through direct-to-converter digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance cost escalation is forcing consolidation among mid-sized European specialty chemical firms unable to absorb parallel REACH, TSCA, and China MEE registration expenses. Surviving players will capture specification-driven margin pools as multinational electronics OEMs consolidate approved vendor lists.
For Market Incumbents: Anticipate silicone adhesive encroachment in automotive electronics by accelerating hydrogenated hydrocarbon resin qualification for thermal stability applications. Backward integration into captive tackifier production in the Yangtze River Delta reduces currency exposure and secures supply continuity for pressure-sensitive formulations. Prioritize MFDS pre-registration in South Korea to defend precision tape positioning against Japanese competitors. For New Entrants and Emerging Players: Launch via direct-to-converter digital platforms targeting mid-sized Vietnamese and Mexican electronics contract manufacturers facing compressed qualification windows from brand owners. White-space opportunity sits with biodegradable starch-based formulations for French and Italian extended producer responsibility frameworks, where incumbent R&D pipelines lag sustainability mandates. Partner with regional slitting specialists to bypass capital-intensive precision die-cutting investments. For Investors and Strategic Acquirers: Re-rating potential sits with precision tape specialists possessing validated clean-release certifications given OEM supply base consolidation trends. Long-term viability favors formulators with multi-jurisdiction regulatory dossiers and established electronics channel relationships. Watch for India PLI scheme contract awards to Tamil Nadu and Karnataka assemblers as inflection signal for localized adhesive demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tackifier Resins | Captive supply of styrene block copolymer feedstocks insulates margin from Asian petrochemical price volatility. |
| UV-LED Curable Platform Expansion | Instant cure capability at reduced energy intensity aligns with South Korean OLED substrate protection requirements. |
| Biodegradable Formulation Development | Fermentation-derived polysaccharide adhesives address emerging EU Green Deal packaging recyclability mandates. |
| Direct-to-Converter Digital Channel | Customized slit-width configurations bypass distribution tiers serving mid-sized electronics contract manufacturers. |
| Multi-Jurisdiction Regulatory Registration | Parallel REACH, TSCA, and China MEE compliance accelerates product launch timelines for novel bio-based platforms. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with adhesive formulation chemists, electronics contract manufacturer procurement leads, and automotive OEM surface protection engineers combined with secondary validation from ECHA substance registration databases, EPA emission compliance reports, and ACC industry statistics. Bottom-up volume modeling across chemistry types and application segments triangulated against top-down value estimates derived from customs trade flows and SEC 10-K segment disclosures.
Granularity-level modeling operated at chemistry-grade, application-function, and regional-production-cluster dimensions across the analysis window. Segmentation dimensions included pressure-sensitive versus water-soluble versus UV-curable chemistries; packaging, labeling, surface protection, and automotive applications; and electronics, automotive, construction, and retail end-user categories. CAGRs were derived from elasticity-adjusted demand projections incorporating electronics miniaturization trends and regulatory-driven formulation substitution patterns.
Feedstock price shocks, regulatory timeline delays, and silicone substitution acceleration are the dominant revision risks to forecast outputs. Forecasts reflect assumptions regarding dual carbon policy implementation consistency in China and EU Green Deal packaging mandate enforcement timelines. Stakeholders should weight assumptions against their own operating context and supply base exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Gasket and Seal Material Market
Adhesives & Sealants
Rubber-Based Adhesives Market
Adhesives & Sealants
Polyester Hot Melt Adhesives Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
UV Adhesives Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market
Adhesives & Sealants
Malaysia Sealants Market
Adhesives & Sealants
Animal Glue Market