
 Adhesive Dispensing Systems Market | 2026-2036
Adhesive Dispensing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Adhesive Dispensing Systems Market Analysis
Aftermarket service revenue for precision dispensing modules is reconfiguring margin pools away from initial equipment sales across the adhesive dispensing systems value chain. Nordson Corporation leverages its extensive global service network to capture recurring calibration and parts replacement income. Graco Inc. anchors its position through deep specialization in high-viscosity material handling systems for industrial coating applications. Henkel AG & Co. KGaA differentiates by integrating adhesive chemistry expertise with dispensing hardware design, creating bundled process solutions that competitors struggle to replicate.
Adhesive dispensing systems are engineered equipment that meter, mix, and deposit adhesives, sealants, or lubricants at controlled pressures, temperatures, and flow rates to achieve specified bond line thickness and cure profiles. Hot melt technology dominates volume shipments due to its elimination of solvent-based drying stages and compatibility with high-speed packaging lines. Automated systems command the largest installed base in automotive assembly and electronics manufacturing, where repeatability tolerances below 0.1 millimeters justify capital expenditure. UV curing represents the fastest-expanding technology segment, driven by electronics miniaturization requiring instant polymerization without thermal damage to sensitive components.
OSHA workplace exposure limits and EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-based adhesive formulations in US manufacturing facilities, pushing capital allocation toward closed-loop dispensing architectures. REACH registration requirements and the EU F-Gas Regulation govern chemical composition and thermal management components in European equipment deployments. Stakeholders must monitor regulatory divergence between jurisdictions when configuring platform architectures, as compliance investments in one geography may not transfer efficiently to markets with divergent chemical control frameworks.
Market Dynamics
Automotive electrification is forcing adhesive dispensing architectures to accommodate larger bond areas and thermally sensitive substrates, compressing equipment refresh cycles and expanding aftermarket service revenue pools.
Growth Catalysts
- EV Battery Pack Sealing:Electric vehicle manufacturers in Germany and the United States are expanding precision bonding operations to accommodate larger battery enclosures requiring hermetic seals.
- Solvent-Free UV Curing:REACH compliance in Europe and evolving EPA VOC standards in North America are accelerating capital allocation toward closed-loop dispensing platforms that eliminate solvent-based drying stages.
- Electronics Miniaturization:Shenzhen and Dongguan manufacturing corridors concentrate demand for sub-0.1 millimeter repeatability in semiconductor packaging and display assembly applications.
Market Restraints
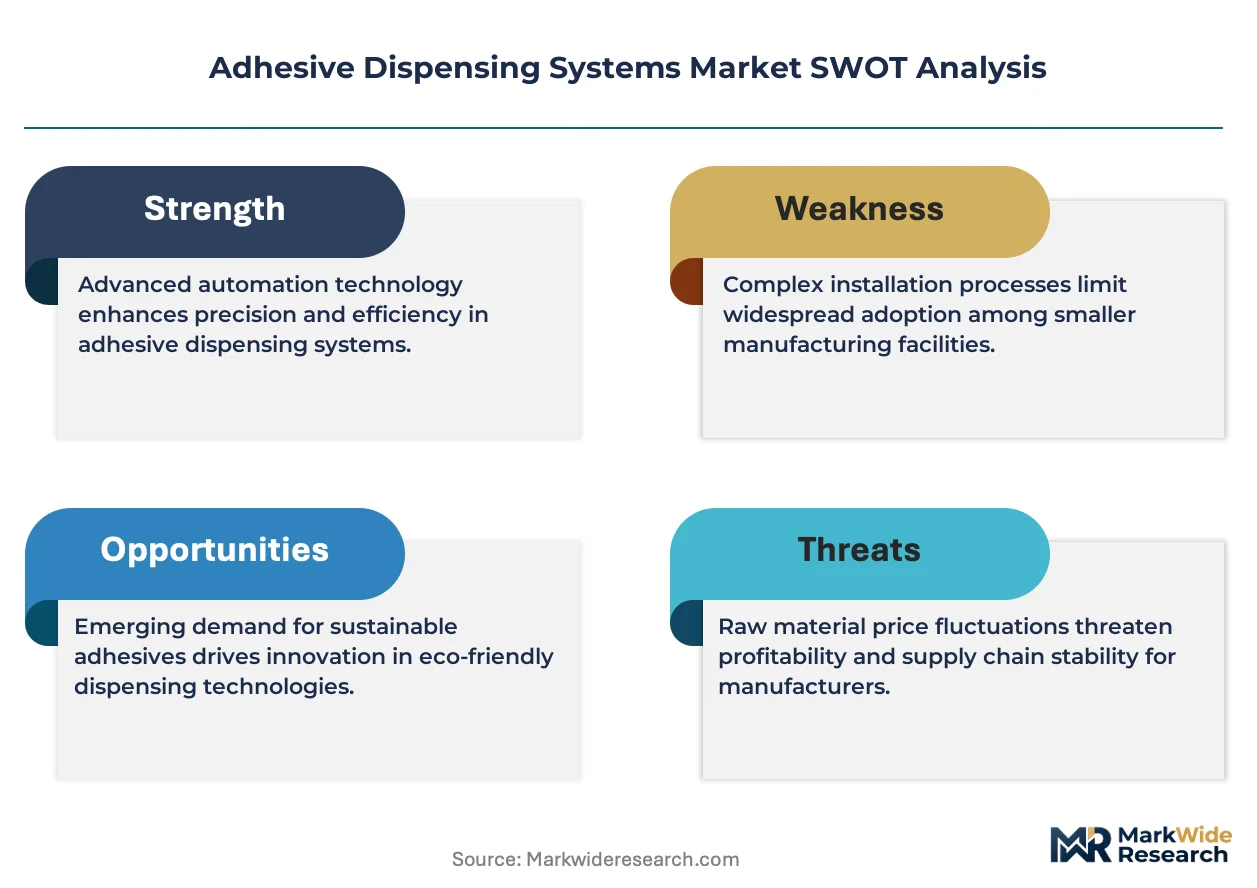
- Specialized Polymer Feedstock Volatility:Engineering-grade hot melt adhesives depend on petrochemical derivatives subject to input cost swings that compress equipment margin pools.
- Precision Component Supply Concentration:High-pressure pumps and servo-driven metering valves source predominantly from German and Japanese precision engineering suppliers, creating geographic concentration risk.
- Legacy Solvent Formulation Lock-In:Existing capital investment in solvent-based adhesive curing infrastructure creates switching friction despite OSHA workplace exposure limits constraining continued deployment.
Strategic Opportunities
- Medical Device Assembly:ISO 13485-certified dispensing systems remain underpenetrated in orthopedic implant and diagnostic cartridge manufacturing, where biocompatibility validation creates switching costs.
- Renewable Energy Manufacturing:Wind turbine blade bonding and solar panel encapsulation applications are expanding addressable equipment demand beyond traditional automotive and electronics verticals.
- EU F-Gas Regulation Compliance:Thermal management component redesigns to eliminate fluorinated gases create retrofit and replacement cycles for installed base equipment in European manufacturing facilities.
Industry Challenges
- Multi-Material Process Engineering Talent:Equipment vendors struggle to recruit specialists capable of integrating adhesive rheology, thermal dynamics, and robotic motion control into unified process solutions.
- Cross-Jurisdictional Certification Timelines:Divergent chemical control frameworks between EPA, ECHA, and China's MEE require redundant validation testing that extends product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adhesive Dispensing Systems Market |
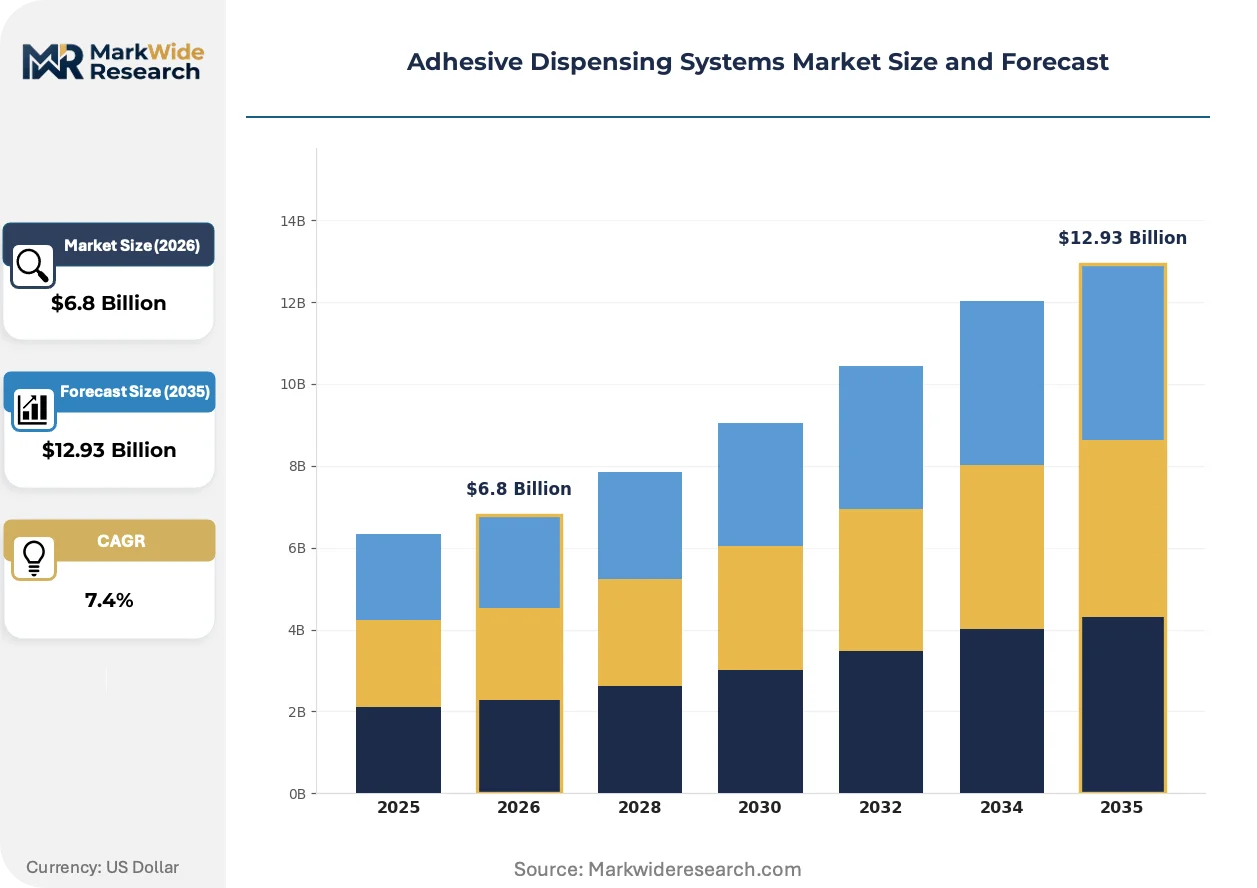
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Systems, Semi-Automated Systems, Portable Dispensers Application: Woodworking, Automotive Assembly, Electronics Manufacturing, Packaging Technology: Hot Melt, Cold Dispensing, UV Curing, Liquid Adhesive End User: Manufacturers, Contractors, DIY Enthusiasts, Retailers |
| Companies Covered | Nordson Corporation, Valco Melton, Graco Inc., Dopag Group, Henkel AG & Co. KGaA, Dymax Corporation, ITW Dynatec, EXACT Dispensing Systems, Hernon Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adhesive Dispensing Systems Market Emerging Trajectories
Adhesive dispensing technology is converging with in-line quality verification and predictive maintenance analytics, transforming capital equipment from standalone tools into connected production nodes.
Vision-guided dispensing is collapsing the boundary between deposition and inspection by embedding laser profilometry and machine vision directly into dispensing heads. Automotive tier-one suppliers in Stuttgart and Detroit are deploying these systems for real-time bead-width verification. The technology is collapsing rework rates and compressing quality assurance headcount in high-volume assembly environments.
REACH registration requirements and the EU F-Gas Regulation are governing chemical composition and thermal management components in European equipment deployments. Manufacturers must reformulate adhesive chemistries and redesign heating subsystems to maintain market access. German automotive OEMs are accelerating supplier qualification timelines to ensure continuity under evolving compliance frameworks.
Aftermarket service unbundling is fragmenting traditional equipment-sales revenue models. End-users in China's electronics corridors now procure calibration contracts and spare parts through independent channels rather than captive vendor programs. Japanese automotive assemblers are driving this shift by mandating open-architecture maintenance protocols that prevent vendor lock-in.
Adhesive Dispensing Systems Market Segmentation
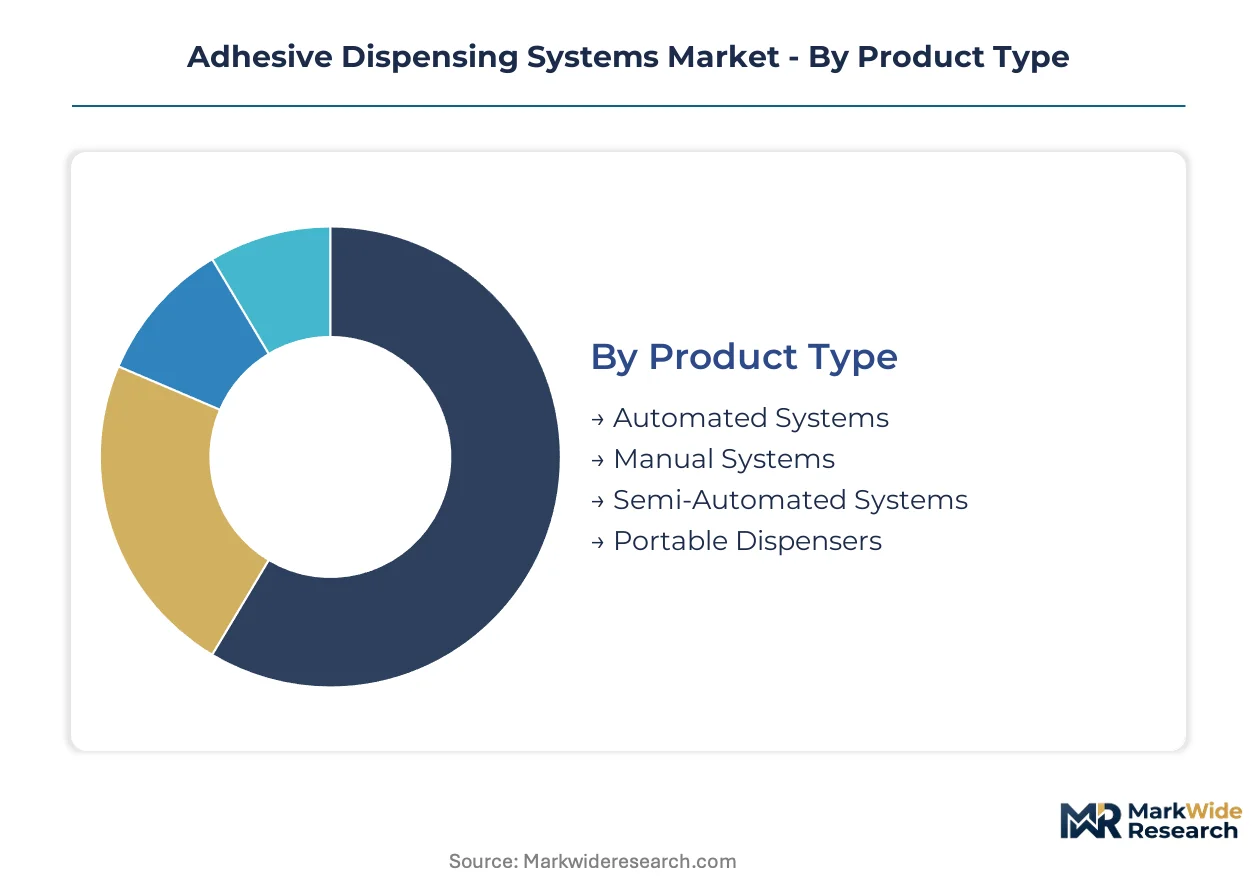
Segmentation in adhesive dispensing systems reflects divergent capital intensity requirements across end-use verticals. Equipment specifications vary dramatically between high-volume automotive assembly and precision electronics manufacturing, creating distinct margin pools and service revenue profiles.
Product Type:
Capital deployment intensity separates equipment tiers, with automation levels directly correlating to throughput requirements and quality tolerances.
- Automated Systems:Robotic dispensing cells integrate servo-driven metering valves and vision guidance for sub-0.1 millimeter repeatability. Automotive assembly lines in Germany and the United States deploy these systems for EV battery pack sealing where hermetic integrity is non-negotiable.
- Manual Systems:Handheld pneumatic dispensers and benchtop units serve low-volume prototyping and repair applications. Contractors in North American construction markets favor these systems for on-site flexibility where capital expenditure constraints dominate.
- Semi-Automated Systems:Operator-assisted stations with programmable dispensing paths bridge manual and fully automated workflows.
- Portable Dispensers:Battery-powered handheld units enable field service and maintenance bonding operations.
Automated Systems hold installed capacity. Semi-Automated Systems is rotating up the share rankings.
Application:
End-use specifications dictate adhesive chemistry compatibility, cure speed requirements, and dispensing precision thresholds.
- Automotive Assembly:Structural bonding of lightweight materials and battery enclosure sealing demand high-pressure dispensing of thermally conductive adhesives. OEMs in Stuttgart and Detroit are expanding precision bonding operations to accommodate electric vehicle architectures.
- Electronics Manufacturing:Semiconductor packaging and display assembly require micro-dispensing of UV-curable materials without thermal damage to sensitive components. Manufacturing corridors around Shenzhen and Dongguan concentrate demand for sub-0.1 millimeter repeatability.
- Packaging:High-speed carton sealing and labeling operations favor hot melt systems for instant bond formation.
- Woodworking:Panel lamination and furniture assembly utilize cold dispensing of PVA and polyurethane formulations.
Automotive Assembly holds installed capacity. Electronics Manufacturing is climbing the fastest.
Technology:
Cure mechanism selection determines energy consumption, throughput ceiling, and regulatory compliance posture.
- Hot Melt:Thermoplastic adhesives applied at 150-200°C eliminate solvent-based drying stages and enable high-speed packaging line integration. The technology dominates volume shipments due to compatibility with continuous production environments.
- UV Curing:Photoinitiator-activated polymerization delivers instant cure without thermal loading. Electronics miniaturization in Asian manufacturing corridors is accelerating capital allocation toward closed-loop UV dispensing platforms that satisfy REACH and EPA VOC constraints.
- Cold Dispensing:Room-temperature application of reactive and water-based formulations serves temperature-sensitive substrates.
- Liquid Adhesive:Low-viscosity systems for wicking and capillary bonding applications in medical device and optical assembly.
Hot Melt holds installed capacity. UV Curing is gaining share fastest.
End User:
Procurement authority and technical specification control vary dramatically across the customer base, shaping vendor sales motion and service contract structures.
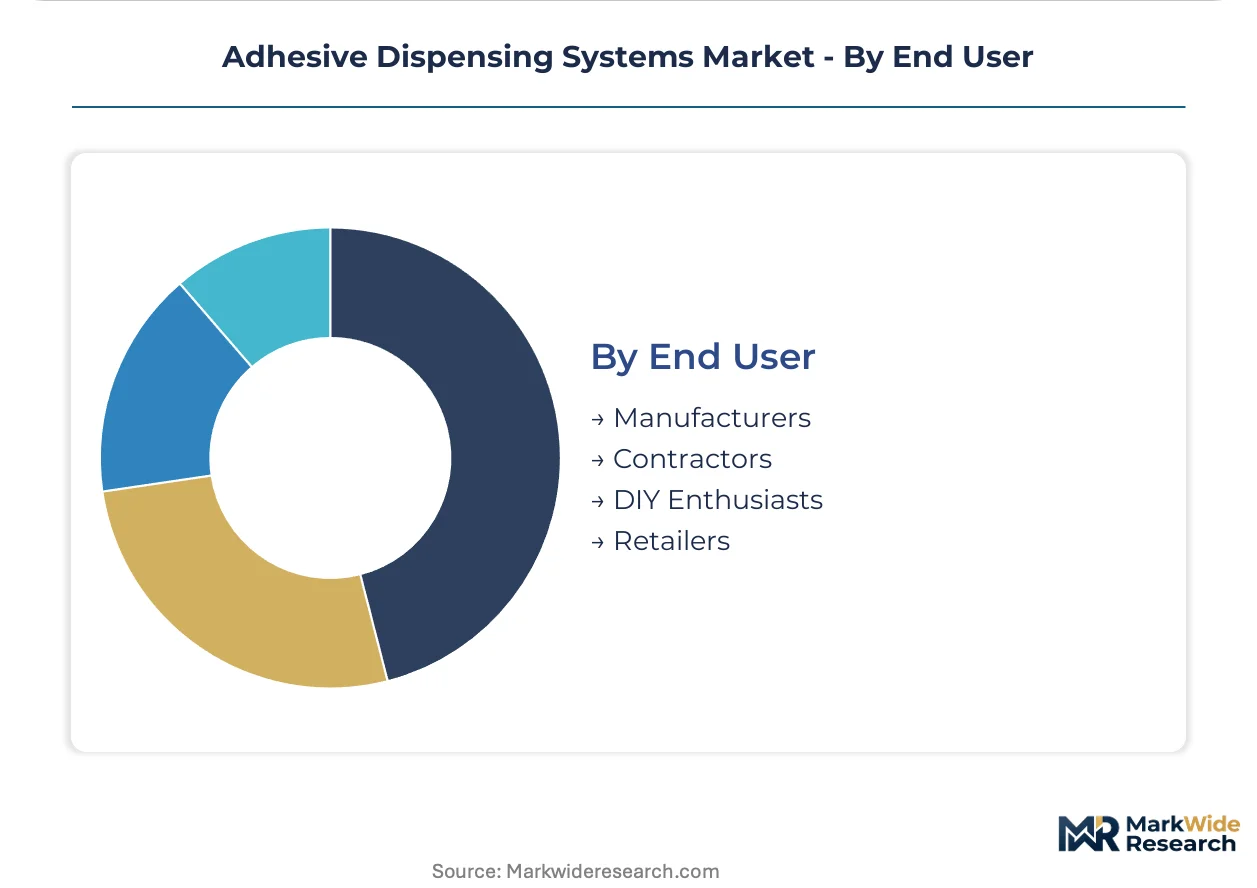
- Manufacturers:Tier-one automotive suppliers and electronics OEMs specify equipment performance parameters and mandate open-architecture maintenance protocols. These end-users drive demand for ISO-certified systems with predictive maintenance analytics integration.
- Contractors:Construction and installation specialists prioritize equipment portability and rapid setup over precision specifications. Service revenue pools from these customers concentrate on spare parts rather than calibration contracts.
- DIY Enthusiasts:Consumer-grade handheld dispensers for home repair and craft applications.
- Retailers:Distributors stocking entry-level equipment for small business and consumer segments.
Manufacturers hold installed capacity. Contractors is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German automotive OEMs prioritize hermetic sealing systems for battery enclosures, while Chinese electronics corridors demand sub-0.1 millimeter repeatability for semiconductor packaging. North American packaging lines favor hot melt throughput over precision specifications.
United States
Automotive electrification in Detroit and South Carolina is compressing equipment refresh cycles for battery pack sealing operations. EPA National Emission Standards for Hazardous Air Pollutants and OSHA workplace exposure limits are accelerating capital reallocation toward closed-loop dispensing architectures. Precision bonding corridors in Michigan and Tennessee are expanding capacity to accommodate EV platform transitions.
Germany
Stuttgart-based automotive OEMs are mandating supplier qualification timelines for hermetic seal integrity under expanded electric vehicle production schedules. REACH registration requirements and the EU F-Gas Regulation are forcing thermal management subsystem redesigns to eliminate fluorinated gases. Industrial clusters in Bavaria and Baden-Württemberg concentrate demand for ISO-certified automated dispensing cells.
China
Electronics miniaturization in Shenzhen and Dongguan manufacturing corridors is driving demand for UV-curable micro-dispensing platforms. MEE oversight of chemical composition and SAMR equipment certification requirements are constraining imported system deployments. Yangtze River Delta and Pearl River Delta clusters are localizing supply chains for high-pressure metering valve production.
Japan
Automotive tier-one suppliers in Nagoya and Tokyo are integrating vision-guided dispensing for real-time bead-width verification. METI industrial standards and JIS certification protocols are governing equipment interoperability specifications. Precision engineering suppliers in Chubu and Kansai regions dominate servo-driven valve component sourcing.
South Korea
Display panel manufacturers in Gyeonggi Province are deploying UV curing platforms for instant polymerization without thermal damage. MFDS equipment validation requirements and dual carbon goals are shaping procurement specifications for energy-efficient curing subsystems. Seoul Capital Area electronics clusters are expanding semiconductor packaging capacity with sub-micron dispensing tolerances.
Adhesive Dispensing Systems Market Vendor Landscape
Capability concentration sits with specialized precision engineering houses; scale advantage sits with diversified industrial equipment conglomerates. The vendor base stratifies into three tiers: integrated adhesive chemistry specialists, standalone dispensing hardware fabricators, and regional system integrators. Dominant competitive moves include backward integration into precision component manufacturing and geographic expansion through distribution partnerships in Asian electronics corridors.
Among North American industrial equipment conglomerates, Nordson Corporation and Graco Inc. exemplify divergent strategic positioning within the competitive structure. German chemical-industrial hybrids including Henkel AG & Co. KGaA occupy a distinctive tier by bundling adhesive formulation expertise with dispensing hardware design. These three anchors represent the primary competitive archetypes: diversified equipment scale, precision component specialization, and integrated chemistry-hardware solutions.
| Leading Market Players |
|---|
| Nordson Corporation |
| Valco Melton |
| Graco Inc. |
| Dopag Group |
| Henkel AG & Co. KGaA |
| Dymax Corporation |
| ITW Dynatec |
| EXACT Dispensing Systems |
| Hernon Manufacturing |
| Others |
Supply Flow & Price Mechanics
Shanghai-Ningbo port freight corridors impose cost volatility that ripples through German precision component suppliers and Chinese electronics assemblers alike, compressing margin pools for mid-tier equipment vendors while amplifying price differentiation between ISO-certified automated cells and entry-level manual dispensers.
Pricing Analysis
Long-term offtake contracts dominate procurement between Tier 1 automotive suppliers and precision dispensing vendors, insulating pricing from spot volatility in petrochemical feedstocks. Three-tier pricing structure across premium, standard, and economy levels separates vision-guided robotic cells with predictive maintenance analytics from semi-automated stations and handheld pneumatic units. Pricing pressure stems from aftermarket service unbundling in Chinese electronics corridors, where independent calibration channels erode captive vendor revenue. Contractors in North American construction markets exhibit highest price sensitivity, while German automotive OEMs prioritize hermetic seal certification over unit cost.
Supply Chain Analysis
Engineering-grade thermoplastic feedstocks draw from petrochemical complexes in Germany, the United States, and Saudi Arabia, tethering hot melt adhesive formulations to naphtha and propylene price swings. High-pressure metering valves and servo-driven dispensing heads source predominantly from precision engineering clusters in Germany and Japan, creating geographic concentration risk for equipment fabricators. Single-source vulnerability in ceramic piston pump manufacturing threatens production continuity for UV curing platform vendors. Distribution runs through authorized system integrators in Asian electronics corridors and direct OEM relationships in European automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UV curing platform displacement of solvent-based architectures represents a high-growth disruption, with EPA National Emission Standards and REACH compliance timelines forcing capital reallocation across installed base equipment.
For Market Incumbents: Build aftermarket service moats through predictive maintenance analytics integration and captive spare parts logistics. Incorporate laser profilometry directly into dispensing heads to collapse inspection boundaries and defend against vision-system specialists. Expand calibration contract penetration in Chinese electronics corridors before independent channels consolidate further. For New Entrants and Emerging Players: Medical device assembly corridors in Massachusetts and Minnesota present underpenetrated white space, where ISO 13485 certification requirements create switching costs that favor specialized entrants. Target orthopedic implant manufacturers with biocompatibility-validated micro-dispensing platforms. Pursue equipment-as-a-service financing to bypass capital expenditure constraints at mid-size diagnostic cartridge producers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core dispensing hardware units amid portfolio rationalization. Five-to-ten year viability favors vendors with integrated adhesive chemistry expertise and open-architecture maintenance protocols. Monitor EPA VOC enforcement actions as inflection indicator for accelerated solvent-to-UV platform replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Valve Manufacturing | German and Japanese component sourcing concentration creates margin vulnerability for hardware fabricators lacking captive supply. |
| UV Curing Platform Certification | REACH and EPA compliance timelines accelerate replacement demand for solvent-based installed base equipment. |
| Medical Device Assembly Market Entry | ISO 13485 validation requirements in orthopedic implant manufacturing create defendable switching costs for early entrants. |
| Predictive Maintenance Analytics Integration | Vision-guided dispensing systems with real-time bead-width verification collapse quality assurance headcount in automotive assembly. |
| Renewable Energy Manufacturing Expansion | Wind turbine blade bonding and solar panel encapsulation extend addressable demand beyond traditional automotive and electronics verticals. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing plant engineers at automotive OEMs in Stuttgart and Detroit, procurement leads at electronics contract manufacturers in Shenzhen, aftermarket service heads at precision dispensing vendors, and regulatory affairs specialists tracking REACH and EPA compliance timelines. Secondary validation drew from SEC 10-K filings, customs trade data for thermoplastic adhesive feedstocks, ECHA substance registration databases, and SAMR equipment certification records. Bottom-up equipment shipment tallies were triangulated against top-down capital expenditure estimates from automotive and electronics manufacturing clusters.
Calibration against historical refresh cycles in automotive assembly and electronics packaging anchored growth rate derivation across the projection horizon. Segmentation dimensions modeled include automation level, cure mechanism technology, end-use vertical, and regional regulatory cluster. CAGRs reflect weighted averages of equipment replacement timelines, capacity expansion announcements, and compliance-driven retrofit cycles. Forecast inputs incorporated EV battery pack sealing specifications from German and US OEMs, plus semiconductor packaging tolerance requirements from Asian manufacturing corridors.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by precision component suppliers or accelerated SAMR localization mandates in China would shift outcomes substantially. Cross-checking against customs data for high-pressure metering valve imports and ECHA substance volume registrations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
High Temperature Adhesives Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Global Construction Adhesive Tapes Market
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
Animal Glue Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market
Adhesives & Sealants
Spain Sealants Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
Adhesive Resin Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
Lead Encapsulants Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Global Underfill Material Market
Adhesives & Sealants
Global Silicone Adhesives Market