
 US Metal Fabrication Market | 2026-2036
US Metal Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
US Metal Fabrication Market Analytics
The direct-to-contractor channel is narrowing as large fabricators consolidate purchasing power and bypass traditional distributors. Nucor Corporation leverages its electric-arc furnace network to sustain cost leadership in structural steel across the Southeast. Reliance Steel & Aluminum Co. anchors a vast branch-based distribution model that competes on same-day availability in fragmented regional markets. ATI specializes in nickel-based superalloys and titanium products that differentiate its position in aerospace and defense supply chains.
US metal fabrication encompasses the cutting, forming, welding, and assembly of raw metal stock into finished components, typically operating with tolerances ranging from ±0.005 inches for precision machining to ±1/16 inch for structural steel. The output serves as critical input infrastructure for construction framing, vehicle chassis, aircraft fuselages, and industrial equipment housings. Sheet metal and structural components dominate current output volumes, though machined parts command premium margins due to tighter tolerances and longer qualification cycles in aerospace and medical device applications. Laser cutting and metal stamping represent the fastest-expanding fabrication technique categories, driven by automation investments that reduce per-part labor content and improve repeatability across high-mix, low-volume production environments.
OSHA governs worker exposure to welding fumes and metalworking fluids, while the EPA regulates air emissions from coating and finishing operations, both elevating capital requirements for compliant shop floors. The Buy America provisions embedded in federal infrastructure spending direct procurement toward domestic melt-and-pour sources, reshaping supplier qualification criteria for public project bidders. Stakeholders must monitor how NHTSA vehicle lightweighting standards and FAA airframe certification timelines simultaneously pull aluminum and advanced high-strength steel demand in competing directions.
Market Dynamics
Reshoring mandates embedded in federal infrastructure legislation are compressing supplier qualification timelines while elevating domestic melt-and-pour requirements across public project pipelines. This structural pull is redrawing competitive boundaries between integrated mills and independent fabricators.
Growth Catalysts
- Infrastructure Investment and Jobs Act:Federal bridge and highway appropriations channel demand toward domestic steel sources. Buy America compliance now gates eligibility for public sector awards.
- Aerospace titanium assemblies:OEM supply chain restructuring accelerates precision-machined component procurement from US-based Tier 1 fabricators. Qualification cycles favor incumbent domestic suppliers.
- Laser cutting automation:Capital deployment into fiber laser systems reduces per-part labor content in high-mix environments. Repeatability gains expand addressable contract manufacturing scope.
Market Restraints
- Scrap steel price volatility:Electric-arc furnace operators face margin compression when ferrous scrap inventories tighten. Input cost pass-through lags constrain pricing power.
- Great Lakes supplier concentration:Automotive stamping capacity clusters around Detroit and Cleveland corridors. Regional disruption risks propagate through just-in-sequence supply chains.
- Aluminum substitution ceiling:FAA airframe certification timelines slow material transitions in commercial aviation. Titanium retains structural load-bearing roles despite lightweighting pressure.
Strategic Opportunities
- Gulf Coast petrochemical expansion:LNG export terminal construction creates demand for pressure vessel fabrication and pipeline spooling. Modular construction methods favor shop-fabricated subassemblies.
- OSHA welding fume compliance:Mandated exposure limits drive replacement demand for local exhaust ventilation systems. Retrofit services represent recurring revenue attach.
- Hybrid additive-subtractive workflows:Directed energy deposition paired with CNC finishing compresses lead times for complex aerospace brackets. Process integration opens geometric freedom beyond conventional machining.
Industry Challenges
- CNC programming talent scarcity:Multi-axis machining and robotic welding cells require operators with combined mechanical and software competencies. Community college pipeline output lags employer demand.
- EPA coating emission compliance:VOC capture and thermal oxidizer investments strain mid-cap fabricator balance sheets. Permitting timelines extend project startup windows.
- FAA Part 21 certification burden:First-article inspection protocols and supplier audit requirements consume engineering bandwidth. Smaller shops exit aerospace tiering due to fixed compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Metal Fabrication Market |
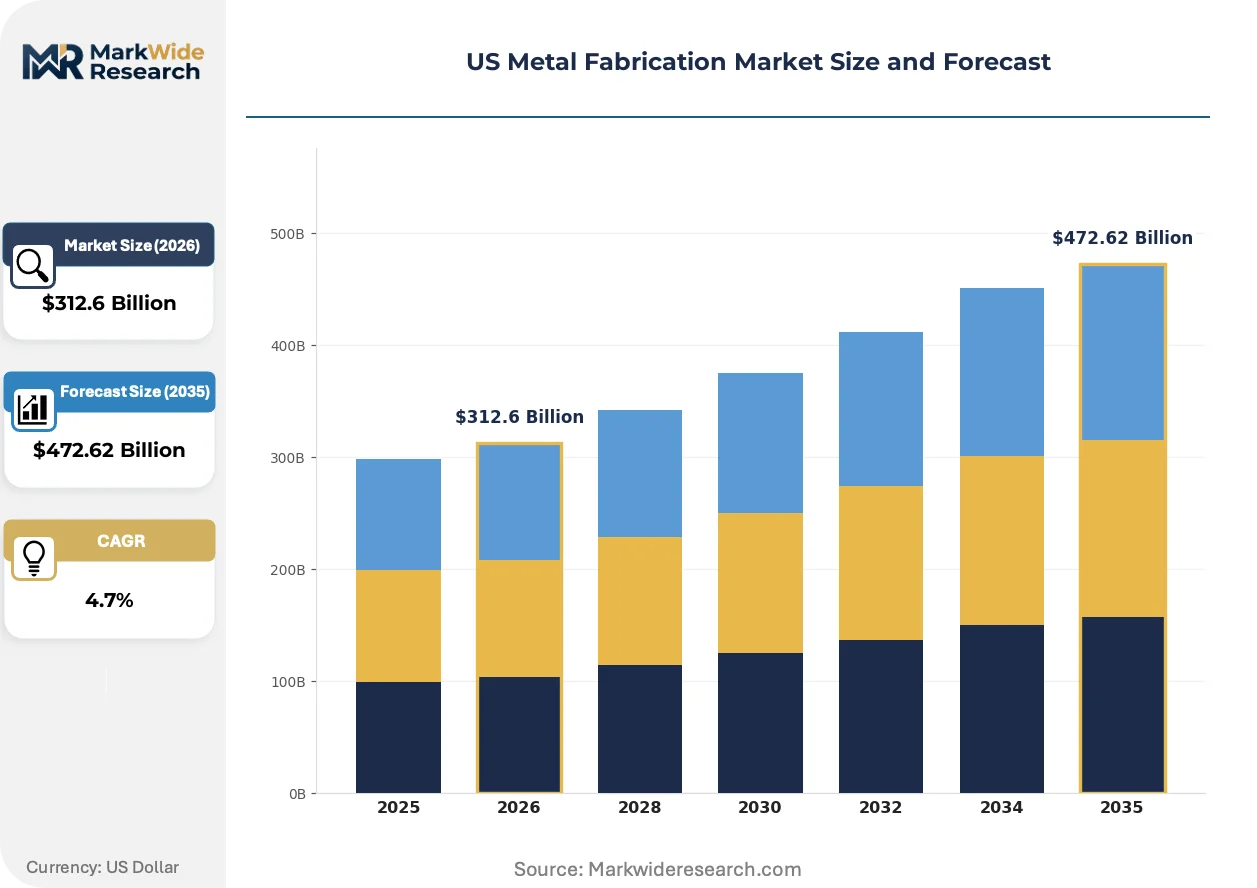
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $472.62 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet Metal, Structural Components, Machined Parts, Metal Forming Industry Vertical: Aerospace, Automotive OEMs, Electronics, Construction Fabrication Technique: Welding, Laser Cutting, Metal Stamping, Bending End User: Manufacturers, Contractors, Distributors, Fabricators |
| Companies Covered | Alcoa Corporation, Commercial Metals Company, Nucor Corporation, Schuff Steel Co., ATI (Allegheny Technologies Inc.), United States Steel Corporation, Reliance Steel & Aluminum Co., Maysteel Industries, Arconic Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Metal Fabrication Market Evolving Landscape
Automation investments are fragmenting competitive advantage sources away from pure scale toward process control precision and rapid qualification responsiveness. Technology convergence and regulatory stringency now determine margin capture more than raw throughput capacity.
Fiber laser cutting systems with automated material handling and nesting software are hybridizing batch production economics with mass-customization flexibility. Job shops serving construction and agricultural equipment OEMs adopt these cells to compress quoting-to-delivery cycles. The technology is hybridizing traditional make-to-order fabricators into responsive contract manufacturers capable of absorbing demand volatility without workforce expansion.
OSHA's enforcement emphasis on hexavalent chromium exposure during stainless steel welding elevates capital requirements for compliant ventilation infrastructure. Shops serving food processing and pharmaceutical equipment sectors face heightened inspection frequency. Texas and Louisiana fabricators report accelerated investment in downdraft tables and ambient air filtration to preempt enforcement action.
Consolidated purchasing power among national construction contractors is disintermediating traditional steel service centers. Direct mill relationships and consignment inventory arrangements replace spot buying through distributors. This channel compression is most visible in Southeast commercial building markets where Turner, DPR, and Brasfield & Gorrie negotiate structural steel packages at arm's length from regional fabricators.
US Metal Fabrication Market Segmentation
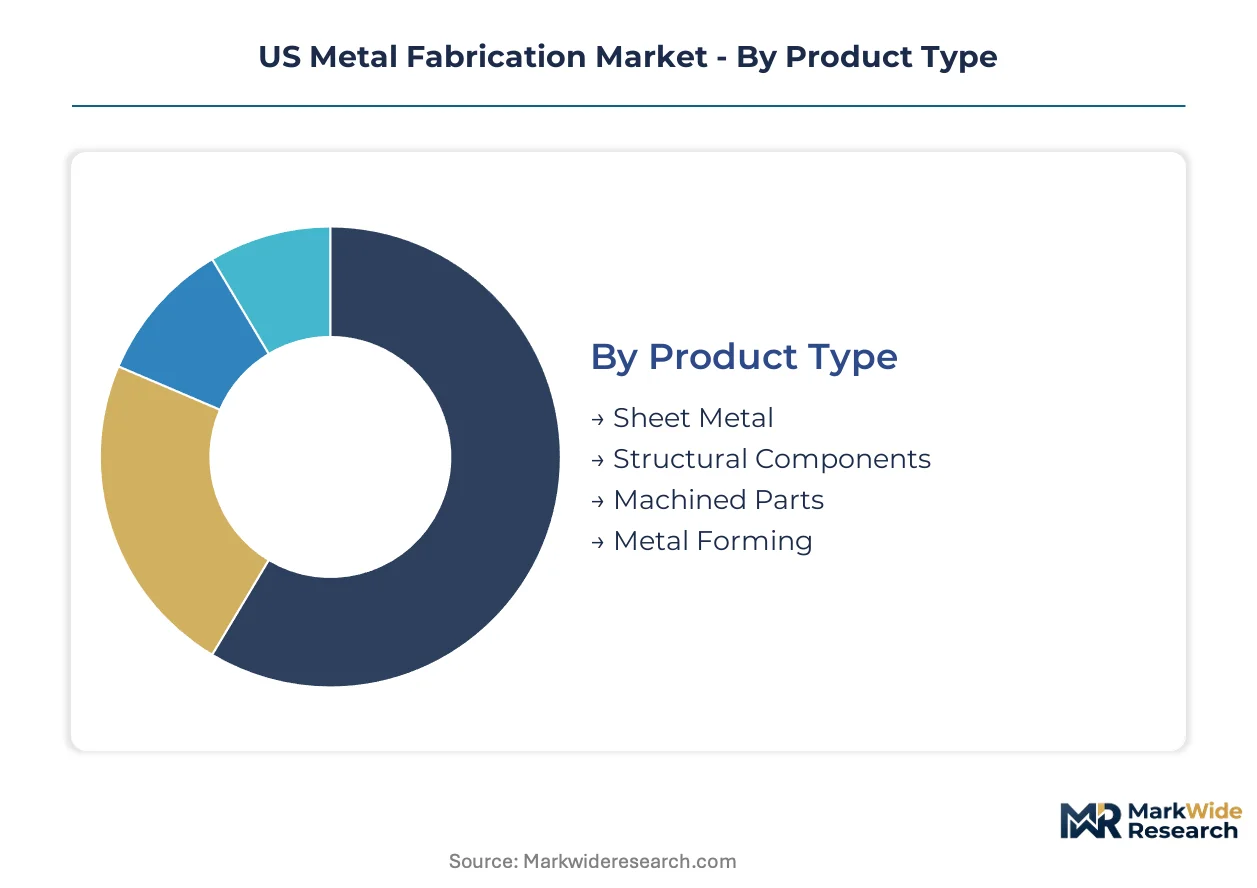
US metal fabrication segmentation reveals how capital intensity, certification requirements, and supply chain proximity fragment competitive positioning across distinct production modes. Each category maps to different margin structures and customer qualification barriers.
Product Type:
Structural applications span load-bearing infrastructure through precision medical devices, with tolerance requirements dictating equipment investment and labor skill premiums.
- Sheet Metal:Thin-gauge steel and aluminum formed into enclosures, ductwork, and equipment housings. HVAC and agricultural machinery OEMs in the Midwest corridor drive volume, with automated nesting software compressing material yield losses.
- Structural Components:Heavy steel shapes for bridges, buildings, and industrial frameworks. IIJA-funded highway projects across Texas and the Southeast concentrate demand, though Buy America melt-and-pour verification extends procurement cycles.
- Machined Parts:CNC-machined precision components with tight tolerances for aerospace and medical applications. Boeing and Lockheed Martin supplier qualification protocols favor incumbent domestic Tier 1 fabricators with existing AS9100 certification.
- Metal Forming:Roll forming, hydroforming, and deep drawing operations producing continuous profiles and complex geometries. Automotive chassis rails and appliance panels represent anchor demand segments.
The dominant share belongs to Structural Components, while Machined Parts is closing the gap fastest.
Industry Vertical:
Customer concentration varies sharply, from fragmented construction bidding to oligopsonistic aerospace procurement with multi-year qualification locks.
- Aerospace:Titanium and nickel superalloy fabrications for airframes and propulsion systems. OEM supply chain restructuring accelerates reshoring of precision-machined assemblies, with FAA Part 21 certification gating new supplier entry.
- Automotive OEMs:Stamping and welding of chassis, body-in-white, and powertrain housings. Detroit and Cleveland corridor capacity serves just-in-sequence delivery requirements, leaving limited flexibility for demand spikes.
- Electronics:Precision sheet metal for server racks, enclosures, and thermal management components. Data center construction in Northern Virginia and Phoenix pulls aluminum fabrication demand.
- Construction:Structural steel for commercial buildings, bridges, and industrial facilities. Direct-to-contractor channel compression disintermediates traditional service centers in Southeast markets.
Construction maintains the largest revenue footprint, though Aerospace is expanding most quickly.
Fabrication Technique:
Automation diffusion rates diverge by technique, with capital substitution proceeding fastest in processes where repeatability directly reduces rework costs.
- Welding:Fusion processes joining ferrous and non-ferrous metals across structural and pressure vessel applications. OSHA hexavalent chromium enforcement elevates ventilation capital requirements for stainless steel work.
- Laser Cutting:Fiber laser systems with automated material handling and nesting optimization. High-mix, low-volume job shops adopt these cells to absorb demand volatility without proportional workforce expansion.
- Metal Stamping:High-volume mechanical pressing of automotive and appliance components. Die investment thresholds favor long-run contracts, locking supplier-customer relationships across vehicle platform lifecycles.
- Bending:Press brake and roll forming operations producing angular and curved profiles. Lower automation penetration preserves manual setup skills for prototype and short-run production.
Laser Cutting is gaining share fastest, while Welding retains the broadest installed base.
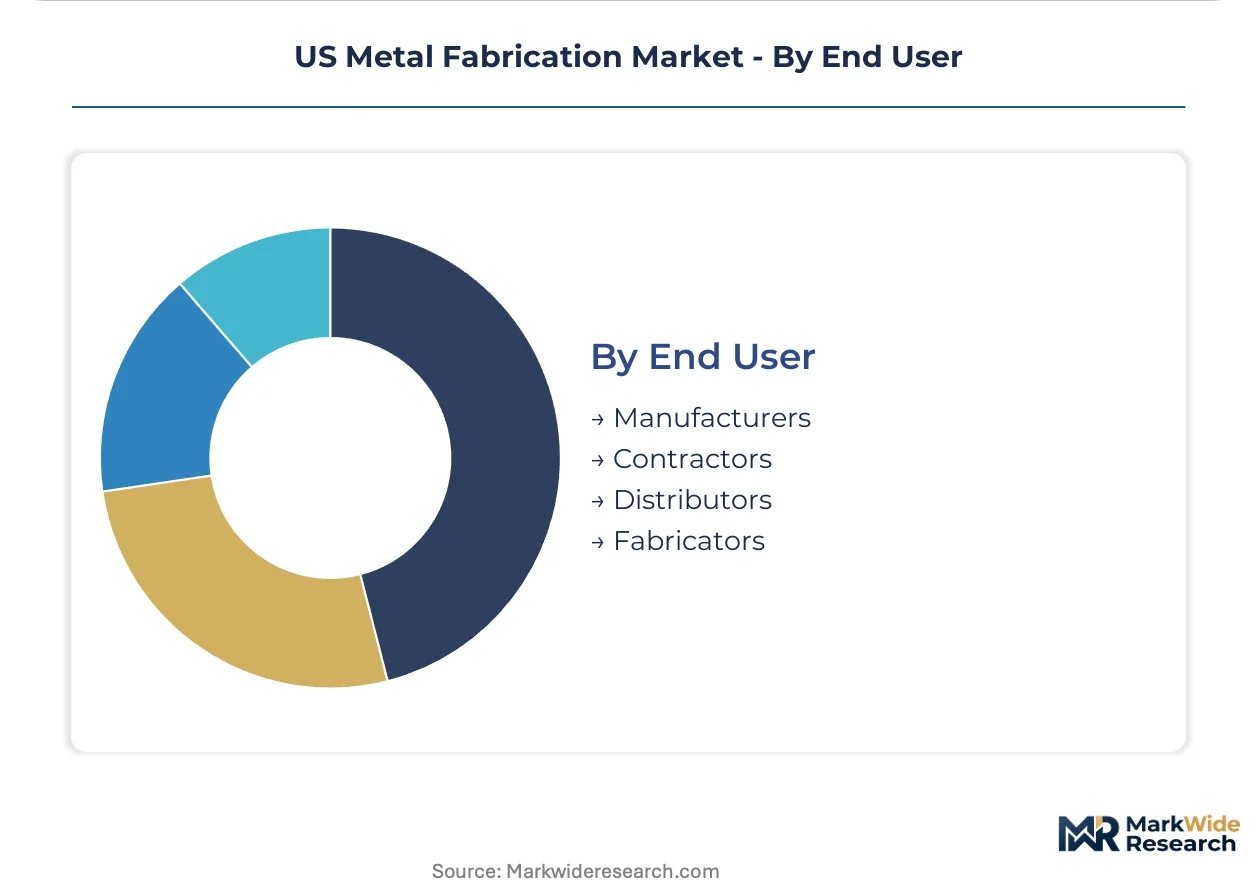
End User:
Procurement sophistication ranges from spot-market distributors to engineered specification buyers with captive supplier development programs.
- Manufacturers:OEMs and Tier 1 suppliers integrating fabricated components into finished goods. Boeing, Caterpillar, and Deere maintain approved vendor lists with audit-driven qualification maintenance.
- Contractors:Construction firms procuring structural steel packages for commercial and infrastructure projects. Turner and DPR negotiate direct mill relationships, bypassing regional service centers.
- Distributors:Steel service centers and metal wholesalers holding inventory for spot and contract sales. Reliance Steel's branch network competes on same-day availability in fragmented regional markets.
- Fabricators:Subcontract job shops performing specialized cutting, forming, or welding for upstream customers. Texas and Louisiana petrochemical corridor shops report pressure vessel demand surges from LNG terminal construction.
Manufacturers command the largest procurement volume, while Contractors are consolidating purchasing power fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Gulf Coast fabricators command 15-20% pricing premiums over Great Lakes competitors due to LNG-driven demand density, while Midwest automotive stamping belts absorb margin compression from just-in-sequence delivery mandates.
Southeast
Commercial building and highway bridge fabrication dominate regional output. IIJA Buy America compliance gates federal project eligibility, forcing melt-and-pour documentation. Atlanta and Charlotte service centers consolidate purchasing power through direct mill relationships.
Texas Gulf Coast
LNG export terminal construction and petrochemical expansion drive pressure vessel and pipeline spooling demand. OSHA welding fume enforcement accelerates ventilation retrofits. Houston and Beaumont fabrication clusters report 18-month order backlogs for modular subassemblies.
Great Lakes
Automotive stamping capacity concentrates around Detroit and Cleveland corridors. NHTSA lightweighting standards pull aluminum and advanced high-strength steel demand. Toledo and Flint suppliers face just-in-sequence delivery constraints with limited demand spike flexibility.
Pacific Northwest
Aerospace precision machining and titanium fabrication anchor regional specialization. FAA Part 21 certification requirements favor incumbent suppliers with existing AS9100 credentials. Seattle and Portland shops benefit from Boeing supply chain reshoring mandates.
Southwest
Data center construction in Phoenix and renewable energy infrastructure in New Mexico drive aluminum enclosure and structural steel demand. EPA coating emission compliance strains mid-cap balance sheets. Albuquerque fabricators report permitting timeline extensions for thermal oxidizer installations.
US Metal Fabrication Market Competitive Landscape
Integrated steel producers and independent fabricators split the market along capital intensity lines. Electric-arc furnace operators leverage scrap-based cost structures against traditional integrated mills. Three archetypes dominate: scale-driven structural steel suppliers, specialty alloy precision machiners, and regional distribution networks. Consolidation proceeds through M&A among mid-cap job shops and capacity expansion into Gulf Coast petrochemical corridors.
Among integrated producers, United States Steel Corporation and Nucor Corporation exemplify the scale-driven archetype through electric-arc furnace networks. ATI occupies a position within the specialty materials tier focused on nickel-based superalloys and titanium products for aerospace qualification chains. Reliance Steel & Aluminum Co. anchors the distribution network model competing on same-day availability across fragmented regional markets.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Commercial Metals Company |
| Nucor Corporation |
| Schuff Steel Co. |
| ATI (Allegheny Technologies Inc.) |
| United States Steel Corporation |
| Reliance Steel & Aluminum Co. |
| Maysteel Industries |
| Arconic Corporation |
| Others |
Value Network & Pricing Analysis
Tight capacity utilization across Texas Gulf Coast fabrication clusters is compressing lead times and emboldening suppliers to enforce stricter payment terms. This utilization dynamic simultaneously elevates spot pricing leverage for domestic melt-and-pour sources while pressuring mid-cap fabricators to absorb input volatility.
Pricing Analysis
Configured-to-order pricing commands 15-20% premiums over standard catalog offerings for pressure vessel and structural steel packages. Contract-based long-term offtake agreements dominate federal infrastructure awards, with Buy America compliance tiers creating price stratification across certification levels. Cost compression in automotive stamping runs through just-in-sequence delivery mandates that limit demand spike flexibility. Contractors procuring structural steel packages exhibit highest price sensitivity, while aerospace OEMs prioritize qualification security over unit economics.
Supply Chain Analysis
Extended payment terms from 45 to 75 days are proliferating through supply-chain finance facilities backed by national distributors. Domestic melt-and-pour capacity concentrates in Indiana, Ohio, and Alabama, with ferrous scrap flows drawing from industrial Midwest collection networks. Electric-arc furnace operations rest on ferrous scrap, graphite electrodes, and natural gas inputs. Single-source vulnerability concentrates in titanium sponge feedstock for aerospace superalloy fabricators. Distribution runs through branch-based steel service centers competing on same-day availability in fragmented regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal infrastructure appropriations are accelerating an early-cycle expansion in domestic structural steel demand. IIJA-funded project pipelines extend visibility for qualified melt-and-pour suppliers beyond typical construction cycles.
For Market Incumbents: Build qualification moats around AS9100 and AISC certification portfolios that gate aerospace and bridge fabrication awards. Consolidate regional job shop capacity in Gulf Coast corridors to capture LNG terminal construction demand. Defensive moves should prioritize backward integration into scrap processing to hedge ferrous input volatility. Channel control through direct mill relationships with Turner and DPR displaces traditional service center intermediation. For New Entrants and Emerging Players: Build out OSHA-compliant welding ventilation retrofit services as recurring revenue attach in Texas and Louisiana petrochemical markets. White-space targets include hybrid additive-subtractive workflows for complex aerospace brackets and modular subassembly fabrication for LNG export terminals. The most penetrable segment lies in mid-cap job shops exiting aerospace tiering due to FAA Part 21 compliance burdens. Go-to-market positioning should emphasize rapid qualification responsiveness against incumbent engineering bandwidth constraints. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across laser cutting automation and fiber laser system deployments. Long-term viability over a 5-10 year window favors fabricators with installed AS9100 credentials and Gulf Coast geographic positioning. Acquisition target archetypes include regional job shops with underutilized capacity in Beaumont and Houston corridors. The signal to watch is qualification timeline compression for reshoring aerospace assemblies as OEM supply chain restructuring accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Gulf Coast LNG terminal construction absorbs modular subassembly output from Houston fabrication clusters. |
| Backward Integration | Scrap processing investments hedge ferrous input volatility for electric-arc furnace operators. |
| Certification Investment | AS9100 and AISC credentials gate eligibility for Boeing supply chain reshoring mandates. |
| Channel Control | Direct mill relationships with national contractors disintermediate traditional steel service centers. |
| Joint Venture | Hybrid additive-subtractive partnerships compress lead times for complex titanium aerospace brackets. |
Research Methodology
A spread of perspectives from fabrication plant managers, OEM procurement leads at Boeing and Caterpillar, steel service center branch directors, and OSHA compliance officers converged on the working assumptions. Primary interview intelligence combined with secondary validation against SEC 10-K filings, AISC fabrication statistics, EPA air emission permits, and customs trade data. Bottom-up capacity assessments across Texas, Great Lakes, and Southeast corridors triangulated against top-down federal appropriation flow analysis.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation by product type, industry vertical, fabrication technique, and end user. CAGRs derived from capacity utilization trajectories, IIJA funding disbursement schedules, and aerospace OEM reshoring commitment timelines. Industry-specific forecast inputs incorporated NHTSA lightweighting standard stringency and FAA Part 21 certification burden evolution.
Stress conditions across ferrous scrap price volatility, IIJA appropriation timing, and aerospace qualification cycle compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on federal infrastructure spending continuity and reshoring policy durability. Macroeconomic recession, regulatory rollback of Buy America provisions, or breakthrough aluminum substitution in commercial aviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Flat-Rolled Products Market
Metals
Silico Manganese Market
Metals
Global Bronze Market
Metals
Aluminium Collars Market
Metals
Global Aluminum Market
Metals
Stainless Steel Foil Market
Metals
Europe Metal Service Centers Market
Metals
Liquid Metal Thermal Pad Market
Metals
Colloidal Metal Particles Market
Metals
Aluminum Scrap Recycling Market
Metals
Copper and Copper Alloy Powder Market
Metals
Silver Sulphate Market
Metals
Base Metals Market
Metals
High Purity Lead Market
Metals
Tin Chloride Market
Metals
North America Electrical Steel Market