
 High Purity Boron Market | 2026-2036
High Purity Boron Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Boron Market Analytics
Specialized boron purification expertise is collapsing across Western chemical engineering programs, creating acute bottlenecks for producers seeking to expand electronic-grade output. H.C. Starck GmbH leverages its decades of refractory metals processing to sustain captive purification capabilities in Germany. SB Boron anchors Chinese domestic supply through integrated boron ore-to-powder operations in Liaoning province. SkySpring Nanomaterials Inc. differentiates via nanoscale boron formulations serving research institutions and advanced materials developers.
High purity boron denotes elemental boron refined to impurity levels below ten parts per million, typically produced via halide reduction or molten salt electrolysis for applications demanding precise dopant control. The material functions primarily as a neutron absorber in nuclear control rods and as a p-type dopant in semiconductor wafer manufacturing. Boron nitride and boron carbide command premium pricing within the product type dimension due to their extreme hardness and thermal stability in aerospace and defense applications. Electronics and nuclear industry applications outpace glass manufacturing in growth velocity, though agriculture retains volume dominance through boron micronutrient distribution.
EPA oversight of boron effluent limits shapes US production economics, while REACH registration requirements in Europe elevate compliance costs for imported material. China's SAMR enforces GB standards on electronic-grade boron purity that effectively filter lower-tier domestic suppliers from semiconductor supply chains. Stakeholders must monitor evolving dual-use export controls affecting boron isotope separation capabilities and assess captive purification investments against long-term supply security requirements.
Market Dynamics
Semiconductor fabs are consolidating p-type dopant procurement around captive purification partnerships, compressing merchant spot markets for electronic-grade boron as process node transitions below 3nm demand impurity thresholds below 5 ppm.
Growth Catalysts
- Sub-3nm process nodes:Taiwan Semiconductor Manufacturing and Samsung Foundry are locking multi-year supply agreements for ultra-high purity boron to sustain transistor scaling roadmaps.
- China's GB 31371-2014 standards:Electronic-grade chemical mandates from SAMR are filtering out low-purity domestic suppliers and concentrating demand on certified producers.
- REACH Article 33 supply chain disclosure:European semiconductor equipment makers are prioritizing documented boron provenance to satisfy downstream due diligence requirements.
Market Restraints
- Fluorinated reagent cost volatility:Boron trichloride and trifluoride feedstock prices swing with chlor-alkali plant operating rates in the US Gulf Coast.
- Liaoning ore concentration:Over 60 percent of Chinese boron ore processing clusters in a single province creates weather and logistics disruption exposure.
- Isotope separation bottlenecks:Boron-10 enrichment for nuclear control rod applications requires gaseous diffusion capacity concentrated in Russian and US government facilities.
Strategic Opportunities
- India's semiconductor PLI scheme:Micron Technology's Gujarat assembly and test facility is creating first-mover demand for localized electronic-grade chemical supply.
- Solid-state battery electrolyte doping:Lithium-boron-sulfur formulations for next-generation EV cells are opening specification conversations outside traditional semiconductor channels.
- Direct-to-fab digital procurement:SkySpring Nanomaterials and specialty distributors are building API-integrated inventory management bypassing regional chemical wholesalers.
Industry Challenges
- Halide reduction engineering talent:University chemical engineering programs in Germany and the US have shuttered pyrometallurgy specializations, forcing producers to train in-house.
- Dual-use export licensing timelines:US Department of Commerce BIS reviews for isotope separation equipment stretch 14-18 months, delaying capacity expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Boron Market |
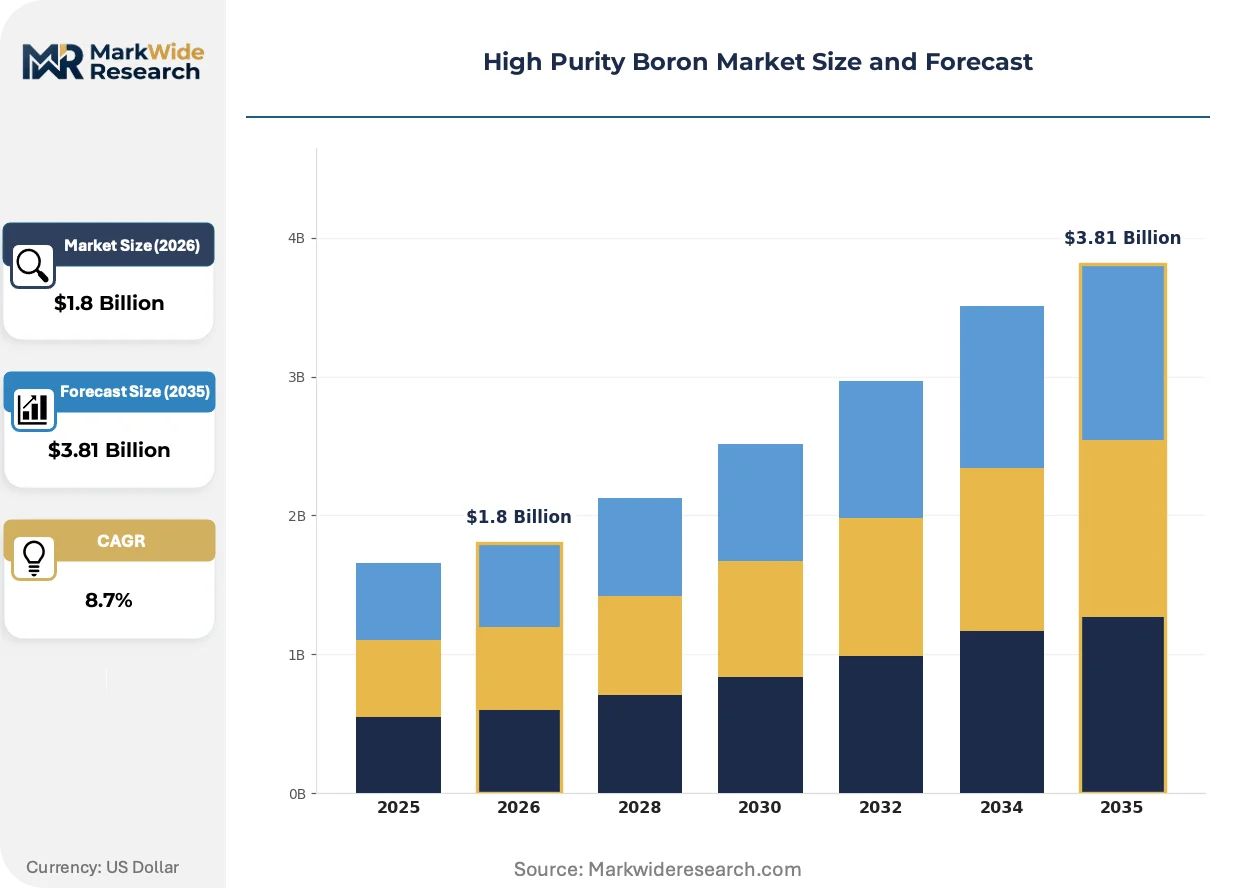
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boron Trioxide, Boron Carbide, Boron Nitride, Sodium Borohydride Application: Glass Manufacturing, Agriculture, Electronics, Nuclear Industry End User: Manufacturers, Research Institutions, Chemical Companies, Energy Sector Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | SB Boron, H.C. Starck GmbH, SkySpring Nanomaterials Inc., CRS Chemicals, Boading Zhongpuruituo Technology, New Metals and Chemicals Ltd., Noah Technologies Corporation, YingKou Liaobin Fine Chemicals, Dandong Chemicals Engineering Institute, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Boron Market Evolving Landscape
Process intensification in boron purification is compressing batch cycle times while plasma-based reduction methods are opening alternative feedstock pathways outside traditional ore dependencies.
Zone refining technology is bifurcating the high purity boron landscape. This method achieves 99.9999 percent purity through iterative solidification without halide intermediates. South Korean memory fabs are adopting zone-refined boron for 3D NAND channel doping to eliminate chlorine contamination risks. The technology is bifurcating supply relationships away from traditional chemical reduction suppliers toward vertically integrated metallurgical processors.
REACH SVHC candidate list expansion is tightening boron compound disclosure obligations. ECHA's 2024 update added specific boron derivatives to the authorization roadmap, forcing non-EU exporters to establish Only Representative legal structures. European semiconductor chemical distributors are responding by consolidating supplier audits and rejecting undocumented material from smaller Chinese traders.
Specification-driven procurement is displacing spot purchasing in advanced dopant categories. Taiwan and South Korean fabs are mandating two-year purity certification windows and locked formulation recipes, freezing out speculative traders. This consolidation is most visible in the Hsinchu Science Park cluster, where TSMC's supplier qualification timelines now exceed 24 months for new boron sources.
High Purity Boron Market Segmentation
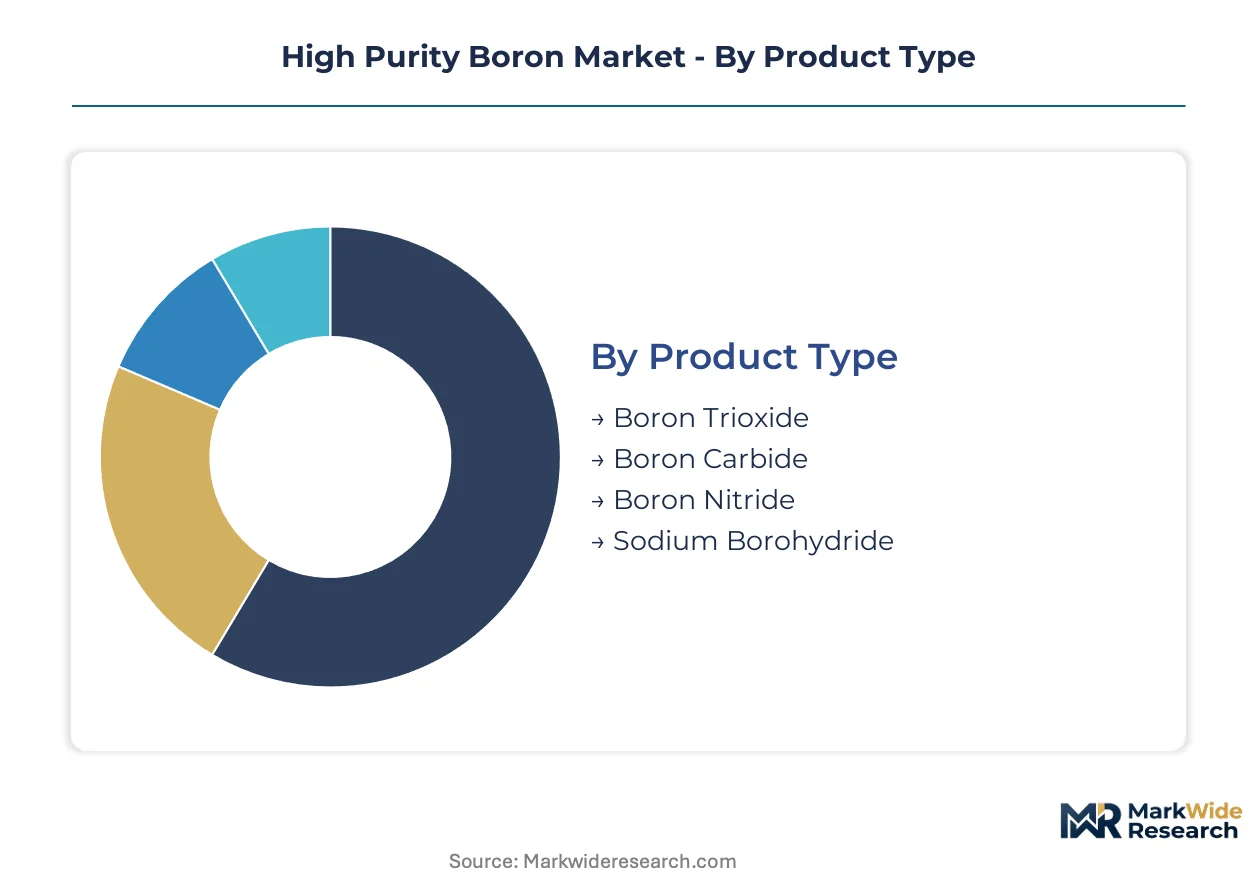
Segmentation in high purity boron reveals how substitution pressures and specification tiers fragment procurement patterns across nuclear, semiconductor, and materials science channels. Each dimension carries distinct margin profiles and qualification barriers that reshape competitive positioning.
Product Type:
Boron carbide and boron nitride face intensifying substitution risk from synthetic diamond and aluminum nitride in extreme-thermal applications, while boron trioxide maintains cost advantages in glass conditioning that resist displacement.
- Boron Trioxide:Amorphous oxide refined to electronic-grade specifications serves as the primary fluxing agent in borosilicate glass manufacturing and precursor for halide reduction processes. Demand concentrates in flat-panel display substrate plants in South Korea and Taiwan, constrained by chlor-alkali feedstock cost volatility.
- Boron Carbide:Third-hardest known material behind diamond and cubic boron nitride, synthesized via carbothermal reduction of boric acid for armor plating and abrasive applications. Defense procurement in the US and Germany sustains premium pricing despite ceramic matrix composite substitution in aerospace.
- Boron Nitride:Hexagonal crystal structure delivers exceptional thermal conductivity and electrical insulation for heat-spreading substrates in power electronics.
- Sodium Borohydride:Hydride reducing agent for pharmaceutical and fine chemical synthesis, with purity grades below 100 ppm metal content commanding specialty chemical premiums.
Boron trioxide retains volume leadership; boron nitride holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity micronutrient distribution from captive electronic-grade supply chains with divergent margin structures.
- Electronics:P-type dopant specifications below 5 ppm impurity thresholds drive zone refining adoption for 3nm process nodes. Taiwan Semiconductor Manufacturing and Samsung Foundry are consolidating procurement around multi-year purity certification agreements.
- Nuclear Industry:Boron-10 isotope enrichment for control rod neutron absorption requires gaseous diffusion capacity concentrated in Russian and US government facilities, creating supply security bottlenecks.
- Glass Manufacturing:Borosilicate and optical glass conditioning consumes volume boron trioxide with lower purity tolerances than semiconductor applications.
- Agriculture:Boron micronutrient distribution for soil correction and foliar feeding operates through commodity fertilizer channels with price sensitivity to South American soybean planting cycles.
Glass manufacturing retains volume leadership; electronics holds the steepest expansion curve.
End User:
Customer type fragmentation splits procurement between specification-driven fabs and volume-negotiating commodity buyers with incompatible qualification timelines.
- Manufacturers:Semiconductor fabs and specialty ceramics producers impose 24-month supplier qualification protocols with locked formulation recipes. Hsinchu Science Park cluster procurement now mandates two-year purity certification windows.
- Research Institutions:Nanoscale boron formulations for materials science investigation tolerate higher per-gram costs and smaller batch volumes than production-scale procurement.
- Chemical Companies:Merchant distributors and custom synthesis houses intermediate between refiners and downstream formulators.
- Energy Sector:Nuclear utilities and battery developers pursue long-term offtake agreements for isotopically enriched and battery-electrolyte grade material respectively.
Manufacturers retain volume leadership; research institutions hold the steepest expansion curve.
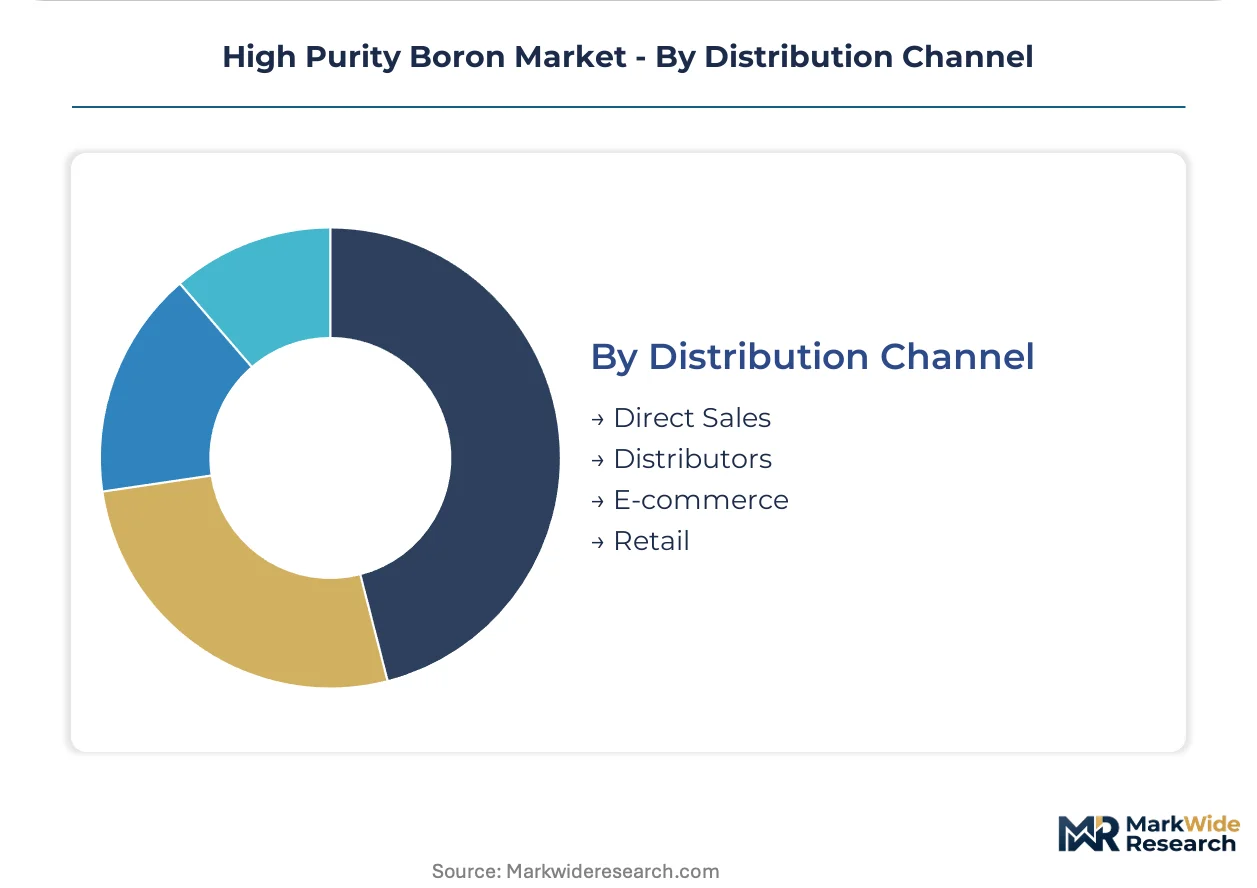
Distribution Channel:
Supply concentration in Liaoning ore processing and German captive purification creates geographic asymmetries that reshape channel economics.
- Direct Sales:Captive partnerships between TSMC and certified refiners bypass regional chemical wholesalers entirely. API-integrated inventory management systems are displacing spot purchasing in advanced dopant categories.
- Distributors:European semiconductor chemical distributors are consolidating supplier audits and rejecting undocumented material from smaller Chinese traders under REACH Article 33 pressure.
- E-commerce:SkySpring Nanomaterials and specialty distributors serve research institutions with nanoscale formulations through digital procurement platforms.
- Retail:Agricultural micronutrient distribution through farm supply cooperatives and garden center channels handles lowest-purity grades.
Direct sales retain volume leadership; e-commerce holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward German captive purification operations while Chinese ore-to-powder integrators compress margins through volume concentration. Semiconductor fabs in Taiwan and South Korea pay premiums for zone-refined material that Liaoning-based suppliers cannot yet match.
United States
Domestic demand centers on nuclear control rod fabrication and defense armor applications requiring boron-10 isotope enrichment. EPA effluent limits under the Clean Water Act constrain chlor-alkali feedstock economics for halide reduction plants. The US Gulf Coast chemical corridor hosts boron trifluoride processing tied to semiconductor equipment supply chains.
Germany
H.C. Starck GmbH sustains European electronic-grade supply through refractory metals processing expertise accumulated over decades. REACH Article 33 disclosure requirements and ECHA SVHC candidate list expansions elevate compliance costs for imported material. The Hesse industrial cluster anchors captive purification capabilities serving Dutch lithography equipment makers.
China
SB Boron controls domestic ore-to-powder integration from Liaoning province deposits that supply over sixty percent of national processing capacity. SAMR enforcement of GB 31371-2014 electronic-grade standards filters low-purity suppliers from semiconductor supply chains. Yangtze River Delta fabs in Shanghai and Wuxi concentrate demand for certified dopant material.
South Korea
Samsung Foundry and SK hynix drive zone-refined boron adoption for sub-3nm process node transistor scaling. METI-coordinated supply security dialogues with Japanese counterparts address isotope separation bottlenecks. The Yongin semiconductor cluster mandates two-year purity certification windows locking out speculative traders.
India
Micron Technology's Gujarat assembly and test facility creates first-mover demand for localized electronic-grade chemical supply under the semiconductor PLI scheme. BIS certification requirements for electronic-grade chemicals remain under development, creating temporary specification ambiguity. The Dholera Special Investment Region attracts boron distributor warehousing investments.
High Purity Boron Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with zone-refining specialists commanding premium pricing while ore-integrated Chinese producers dominate volume tiers. The market structure consolidates around three strategic camps: captive purification partnerships with semiconductor fabs, merchant chemical distributors managing REACH compliance complexity, and nanoscale formulation specialists serving research institutions. Dominant competitive moves include backward integration into boron ore mining and API-integrated digital procurement platforms displacing regional wholesalers.
Among German refractory metals processors, H.C. Starck GmbH occupies a position exemplifying captive purification sustainability through decades of accumulated pyrometallurgy expertise. SB Boron represents the ore-integrated archetype, anchoring Chinese domestic supply security through Liaoning province concentration. SkySpring Nanomaterials Inc. exemplifies the nanoscale specialization tier, serving research institutions with formulation capabilities outside production-scale procurement channels.
| Leading Market Players |
|---|
| SB Boron |
| H.C. Starck GmbH |
| SkySpring Nanomaterials Inc. |
| CRS Chemicals |
| Boading Zhongpuruituo Technology |
| New Metals and Chemicals Ltd. |
| Noah Technologies Corporation |
| YingKou Liaobin Fine Chemicals |
| Dandong Chemicals Engineering Institute |
| Others |
Value Network & Pricing Analysis
Multi-year purity certification agreements between semiconductor fabs and certified refiners lock in both supply access and price visibility, insulating buyers from spot volatility while anchoring premium tiers to qualification timelines that stretch beyond 24 months in the Hsinchu Science Park cluster.
Pricing Analysis
The customization-premium spread between zone-refined electronic-grade material and standard halide-reduced boron widens as sub-3nm process nodes demand impurity thresholds below 5 ppm. Pricing stratifies across premium, standard, and economy tiers driven by certification grade and volume scale. Cost compression in the standard tier intensifies because Liaoning-based ore-integrated producers expand output. Research institutions show least price sensitivity due to small-batch nanoscale procurement, while agricultural micronutrient distributors exhibit highest sensitivity to South American planting cycle fluctuations.
Supply Chain Analysis
Inventory cycles exceeding six months for electronic-grade material reflect the extended qualification protocols that semiconductor fabs impose on new boron sources. Supply concentrates in China, Germany, and South Korea, with raw material feedstocks drawing from Liaoning ore deposits, chlor-alkali plants on the US Gulf Coast, and Russian gaseous diffusion facilities for isotope enrichment. Single-source vulnerability around boron-10 enrichment capacity creates supply security bottlenecks for nuclear control rod fabricators. Distribution runs through direct captive partnerships for advanced dopant categories, bypassing regional chemical wholesalers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
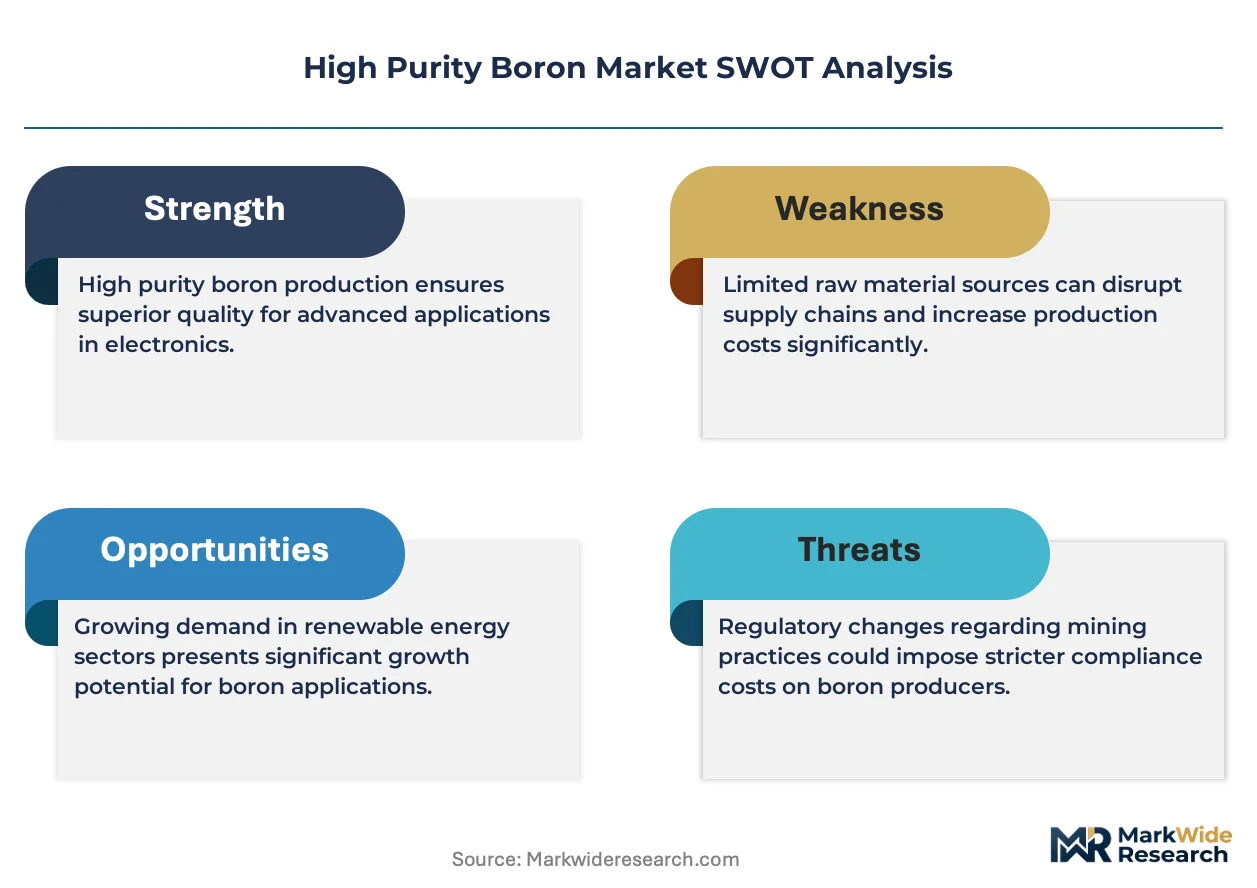
The high purity boron market functions as a defensive-moat story where regulatory entrenchment through REACH Article 33 disclosure requirements and SAMR GB standards creates switching costs that freeze out uncertified competitors.
For Market Incumbents: Shield market position by deepening backward integration into Liaoning ore mining to secure feedstock autonomy against weather disruption exposure. Prioritize zone-refining capacity additions in South Korea to capture Samsung Foundry and SK hynix demand for sub-3nm doping applications. Certification investment in ECHA Only Representative structures defends European distributor relationships against SVHC candidate list expansion threats. For New Entrants and Emerging Players: BIS dual-use export licensing fast-tracks for isotope separation equipment represent the most penetrable entry pathway for nuclear-grade material supply. Target India's Dholera Special Investment Region warehousing under the semiconductor PLI scheme before BIS certification requirements crystallize. Solid-state battery electrolyte doping specifications offer a go-to-market angle outside established semiconductor procurement channels. For Investors and Strategic Acquirers: Captive purification specialists with decades of pyrometallurgy expertise anchor acquisition target archetypes offering irreplaceable technical talent pipelines. Five-to-ten year viability hinges on zone-refining technology diffusion beyond South Korean memory fabs. The signal to watch is TSMC supplier qualification timeline compression below 18 months, indicating capacity shortage inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Ore Mining | SB Boron's Liaheng province control secures feedstock against logistics disruption exposure. |
| Zone-Refining Capacity Expansion | South Korean adoption for 3D NAND channel doping eliminates chlorine contamination risks. |
| API-Integrated Digital Procurement Platforms | SkySpring Nanomaterials bypasses regional chemical wholesalers serving research institutions. |
| ECHA Only Representative Establishment | Non-EU exporters satisfy REACH Article 33 disclosure obligations for semiconductor equipment makers. |
| Solid-State Battery Electrolyte Qualification | Lithium-boron-sulfur formulations open specification conversations outside traditional dopant channels. |
Research Methodology
A spread of perspectives from semiconductor procurement managers, nuclear fuel fabrication engineers, chemical distribution channel heads, and pyrometallurgy R&D directors converged on the working assumptions driving this analysis. Primary field engagement combined with secondary validation from customs trade databases, SEC chemical company filings, and ECHA registration dossiers. Bottom-up demand modeling across end-use applications triangulated against top-down value chain assessments.
Segmentation dimensions modeled include purity grade tier, end-use industry, synthesis method, and regional production hub across the analysis window. CAGRs emerged from iterative reconciliation of shipment volume data and value-based procurement records. Forecast inputs incorporated chlor-alkali plant operating rate sensitivity and semiconductor fab capacity expansion pipelines without year-specific milestones.
The analysis sits within stated boundaries; outcomes outside sustained sub-3nm process node transitions or relaxed dual-use export licensing timelines would require recalibration. Forecasts reflect documented assumptions regarding qualification protocol stability and ore deposit concentration persistence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Steel Drums Market
Metals
Aluminum Tubes Market
Metals
Russia Metal Fabrication Market
Metals
Beryllium Market
Metals
Silver Cyanide Market
Metals
India Steel Market
Metals
Metallurgical Silicon Market
Metals
Carbon Steel Market
Metals
Heat-Treated Steel Plates Market
Metals
North America and Europe Metal Powder Market
Metals
Anodized Titanium Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
Trivalent Chromium Finishing Market
Metals
Ruthenium Market
Metals
Europe Metal Casting Market
Metals
High-End Copper Foil Market