
 Bulgaria Passenger Vehicles Lubricants Market | 2026-2036
Bulgaria Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Bulgaria Passenger Vehicles Lubricants Market Outlook
Automotive service shops is tilting toward bundled oil-change packages that lock in recurring fleet contracts. Shell leverages its retail network to control high-traffic corridors between Sofia and Burgas. Castrol sustains brand pull among individual consumers through OEM approval tie-ins with Volkswagen and Renault service centers. Prista Oil anchors the mid-tier segment with localized blending operations near Ruse.
Bulgaria passenger vehicles lubricants are formulated hydrocarbon-based or synthetic fluid systems engineered to reduce friction, dissipate heat, and prevent wear in internal combustion and transmission assemblies, typically meeting viscosity grades from SAE 0W-16 through 20W-50 and additive packages governed by API SP or ACEA C sequences. Engine Oil dominates volume throughput due to mandatory drain intervals, while Synthetic formulations command expanding margin pools as turbocharged direct-injection engines proliferate in the Light Duty Vehicles fleet. Fleet Operators represent the fastest-growing end user category as logistics firms centralize procurement through contracted Automotive Service Shops.
Bulgaria's lubricant quality framework aligns with EU REACH chemical registration and the F-Gas Regulation on fluorinated greenhouse gases, while the Bulgarian Executive Agency for Environment enforces waste-oil collection quotas that shape reverse logistics costs for distributors. The country's national standards body applies BDS EN norms that transpose ACEA and API performance benchmarks into legally binding market access requirements. Stakeholders must monitor whether upcoming EU battery-electric vehicle mandates compress the addressable internal-combustion lubricant pool faster than hybrid powertrain complexity can offset volume erosion.
Market Dynamics
The Bulgaria passenger vehicles lubricants market is being fundamentally restructured by the EU Green Deal's tightening emission mandates, which are compressing drain intervals while simultaneously elevating specification requirements for turbocharged direct-injection powertrains.
Growth Catalysts
- ACEA C Sequences:The EU's ACEA C3 and C5 oil specifications mandate lower SAPS formulations that extend catalyst life, forcing fleet operators into higher-margin synthetic purchases during every service cycle.
- Fleet Operator Procurement Centralization:Logistics firms across Sofia and Plovdiv are consolidating lubricant purchasing through contracted automotive service shops, creating volume commitments that stabilize distributor throughput.
- Turbocharger Penetration:Light duty vehicles with gasoline direct-injection turbochargers require synthetic 0W-20 and 0W-30 grades that command premium pricing over mineral-based alternatives.
Market Restraints
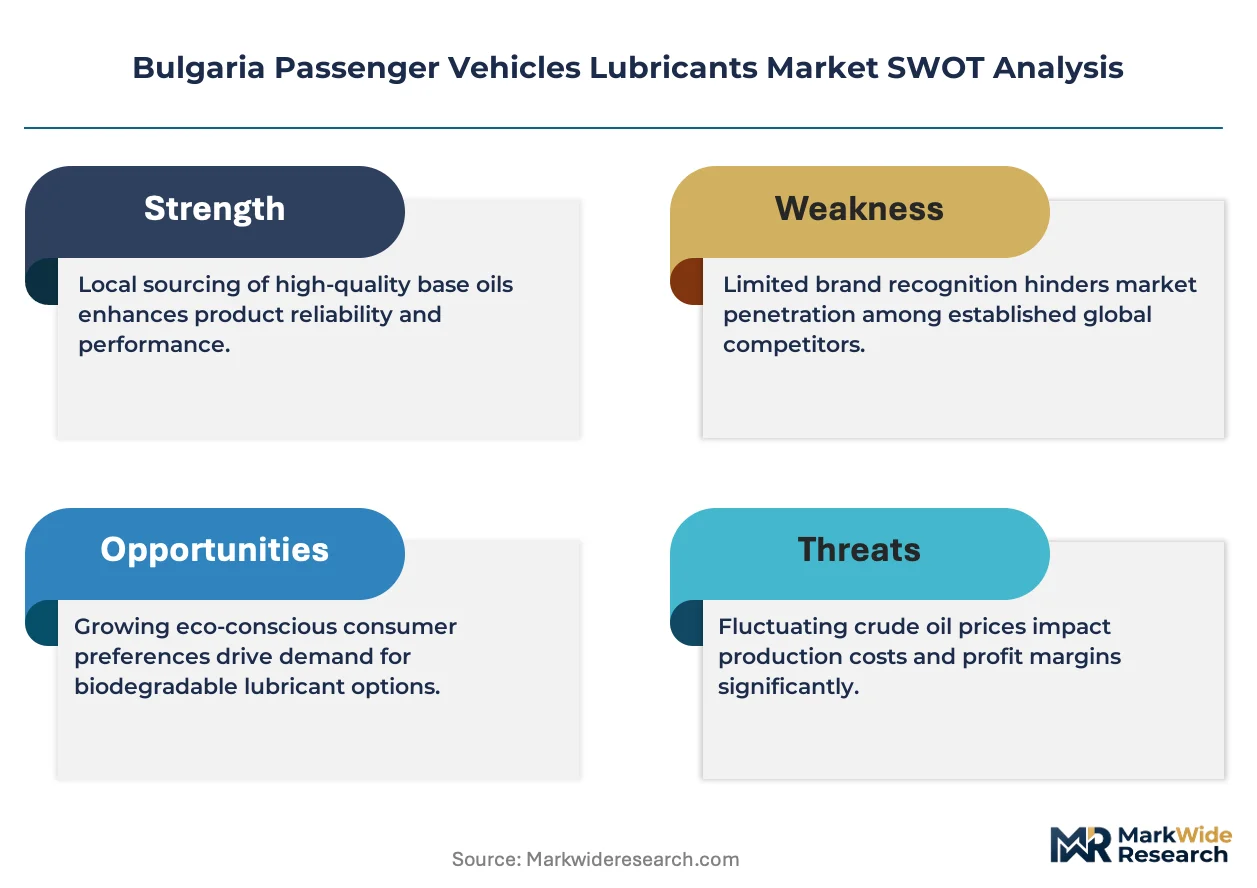
- Base Oil Supply Concentration:Bulgaria relies on imported Group II and III base stocks from refineries in Romania and Greece, exposing blenders to feedstock cost volatility and currency fluctuation risk.
- Waste Oil Collection Quotas:The Bulgarian Executive Agency for Environment enforces mandatory reverse logistics requirements that add fixed cost layers to distributor operations regardless of volume.
- Battery-Electric Vehicle Substitution:Sofia's municipal fleet electrification pilot and rising BEV registrations among urban consumers threaten to erode the addressable engine oil pool faster than hybrid complexity can offset volume declines.
Strategic Opportunities
- Burgas Corridor Service Infrastructure:The Black Sea port city's expanding logistics hub remains underserved by premium lubricant distribution, creating whitespace for synthetic product penetration among cross-border freight operators.
- EU F-Gas Regulation Compliance Services:Refrigerant lubricant demand from vehicle HVAC system servicing presents a technical add-on opportunity for shops already handling engine oil changes.
- Hybrid Powertrain Fluid Complexity:Dual-clutch and e-CVT transmissions in PHEV models require specialized lubricants with electrical conductivity properties, opening formulation differentiation beyond conventional engine oils.
Industry Challenges
- REACH Chemical Registration Burden:The EU REACH framework demands extensive additive substance documentation that stretches compliance timelines and requires dedicated regulatory staffing for smaller Bulgarian blenders.
- API SP Certification Costs:Third-party testing for API SP and ILSAC GF-6 performance claims imposes five-figure euro certification expenses that disadvantage mid-tier brands competing against multinational-backed portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulgaria Passenger Vehicles Lubricants Market |
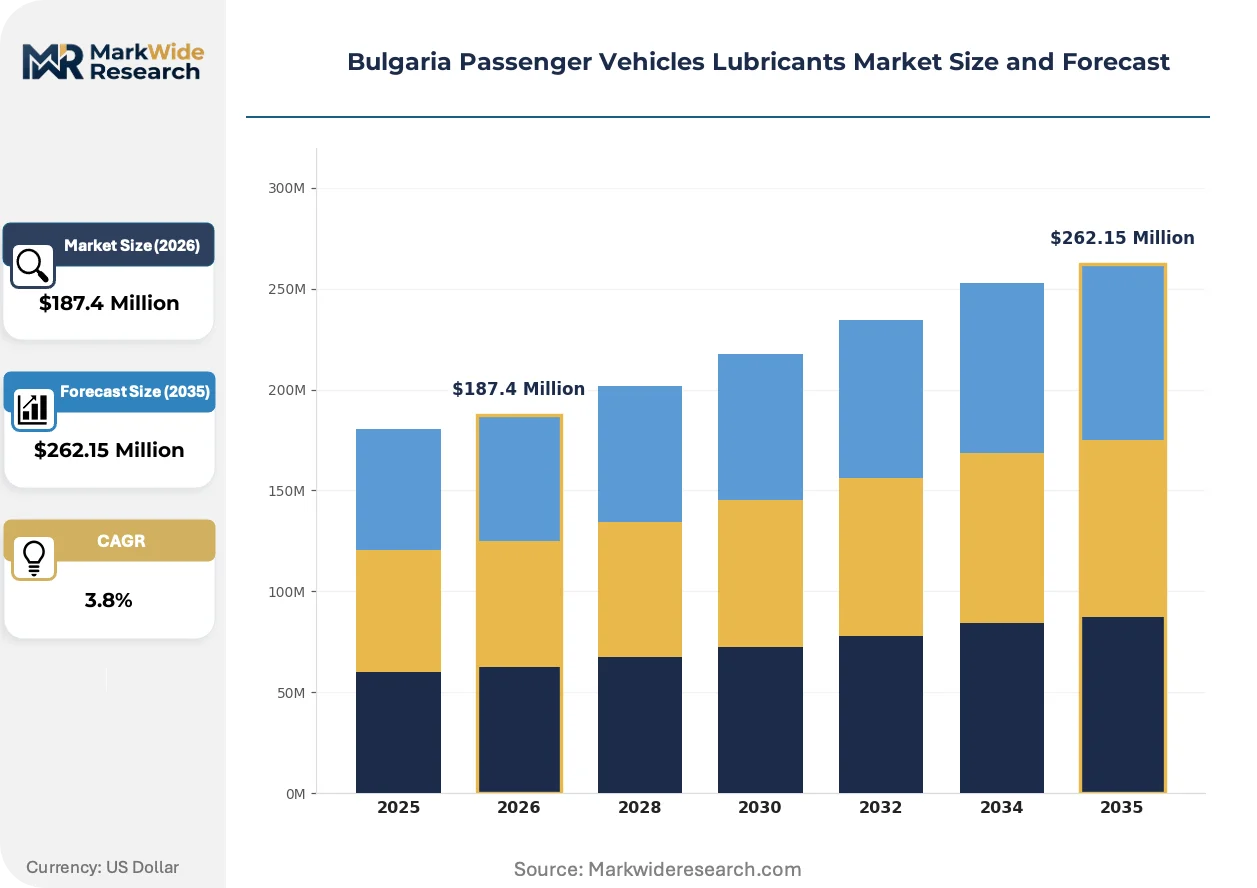
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Grease End User: Light Duty Vehicles, Fleet Operators, Repair Shops, Individual Consumers Performance Level: API Certified, OEM Approved, Synthetic, Conventional Distribution Channel: Retail Outlets, Online Platforms, Wholesalers, Automotive Service Shops |
| Companies Covered | Shell, Castrol, TotalEnergies, ExxonMobil Corporation, Prista Oil, Royal Dutch Shell Plc, Chevron Corporation, AVIA International, Liqui Moly, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulgaria Passenger Vehicles Lubricants Market Strategic Shifts
Formulation chemistry and procurement architecture are undergoing parallel transformation as emission hardware protection requirements collide with fleet purchasing rationalization across Bulgaria's automotive service sector.
Low-viscosity synthetic engine oils are collapsing the historical volume advantage of mineral-based products in the Bulgarian market. Fleet maintenance departments in Sofia's commercial vehicle clusters are mandating 0W-20 and 0W-30 grades for new turbocharged acquisitions. This specification compression is eliminating the price-floor protection that mid-tier mineral brands previously enjoyed in high-mileage segments.
The EU F-Gas Regulation is reshaping refrigerant lubricant specifications across Bulgaria's automotive service network. The phasedown of HFC refrigerants is driving demand for polyolester and PAG lubricants compatible with R-1234yf systems. Shops in Plovdiv's industrial zone are retrofitting equipment and training technicians to handle these low-global-warming-potential alternatives, creating service revenue offsetting declining engine oil margins.
Long-term fluid analysis contracts are displacing fixed-interval oil changes among Bulgarian fleet operators. Logistics firms along the Sofia-Burgas corridor are adopting condition-based monitoring that extends drain intervals by 30-50% while locking in exclusive supplier relationships. This procurement consolidation concentrates purchasing power with distributors capable of delivering laboratory analysis and consolidated billing.
Bulgaria Passenger Vehicles Lubricants Market Segmentation
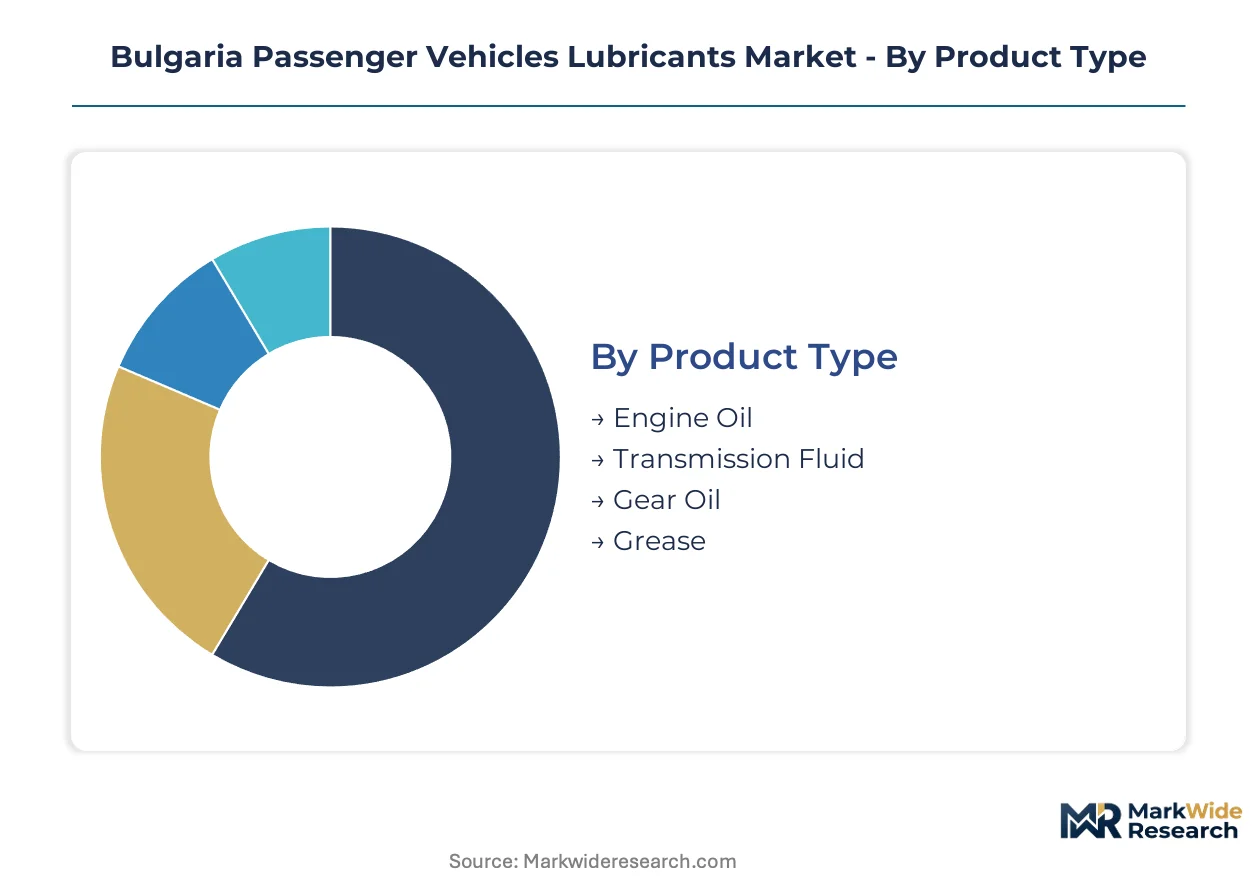
Segmentation in Bulgaria's passenger vehicles lubricants market reveals how service intensity, procurement centralization, and specification pressure fragment demand across distinct value pools. Each dimension exposes different margin structures and competitive access points for suppliers targeting Sofia's fleet clusters versus Plovdiv's retail corridors.
Product Type:
After-sales service intensity varies sharply by lubricant category, with drain intervals and system accessibility determining how frequently vehicles enter service bays.
- Engine Oil:Formulated hydrocarbon-based or synthetic fluid systems meeting SAE viscosity grades from 0W-16 through 20W-50 and additive packages governed by API SP or ACEA C sequences. Mandatory drain intervals under EU emission norms force recurring purchases across Sofia's commercial vehicle density and Plovdiv's service infrastructure clusters.
- Transmission Fluid:Specialized formulations for automatic, manual, and dual-clutch transmissions with friction modification and thermal stability requirements. Demand concentrates in fleet maintenance departments as logistics firms extend vehicle lifecycles through preventive servicing along the Sofia-Burgas freight corridor.
- Gear Oil:High-viscosity lubricants for differential and axle assemblies with extreme-pressure additive packages.
- Grease:Semi-solid lubricants for chassis points, wheel bearings, and ancillary components with NLGI consistency grades.
By volume, Engine Oil leads. By growth pace, Transmission Fluid is ahead as dual-clutch and e-CVT complexity proliferates.
End User:
Procurement rationalization separates volume-stable fleet contracts from price-sensitive individual purchasing across Bulgaria's urban centers.
- Fleet Operators:Centralized procurement through contracted automotive service shops with consolidated billing and long-term fluid analysis programs. Sofia's logistics firms and cross-border freight operators along the Black Sea corridor anchor this segment's expansion as emission compliance tightens maintenance schedules.
- Light Duty Vehicles:Passenger car and light commercial vehicle owners following manufacturer service intervals. Turbocharged direct-injection penetration in Sofia and Plovdiv drives specification upgrades toward synthetic 0W-20 and 0W-30 grades.
- Repair Shops:Independent and franchised service providers purchasing bulk lubricants for retail resale with markup.
- Individual Consumers:DIY purchasers through retail and online channels, predominantly price-driven with limited brand loyalty.
By volume, Light Duty Vehicles leads. By margin expansion, Fleet Operators is climbing the fastest through locked-in contractual structures.
Performance Level:
Specification tiering aligns with emission hardware protection requirements under EU Green Deal obligations, compressing the viable market for lower-grade formulations.
- Synthetic:Chemically engineered base stocks with uniform molecular structures enabling low-viscosity grades and extended drain intervals. ACEA C3 and C5 specifications for catalyst protection command premium positioning across Sofia's fleet procurement.
- API Certified:Third-party tested formulations meeting American Petroleum Institute SP and ILSAC GF-6 performance benchmarks. Certification costs create barrier-to-entry advantages for multinational portfolios against mid-tier Bulgarian blenders.
- OEM Approved:Factory-endorsed lubricants meeting Volkswagen, Renault, and other manufacturer-specific requirements for warranty compliance.
- Conventional:Mineral-based formulations derived from refined crude with higher viscosity indices and shorter service intervals.
By volume, API Certified leads. By specification trajectory, Synthetic is gaining share fastest as turbocharger penetration accelerates.
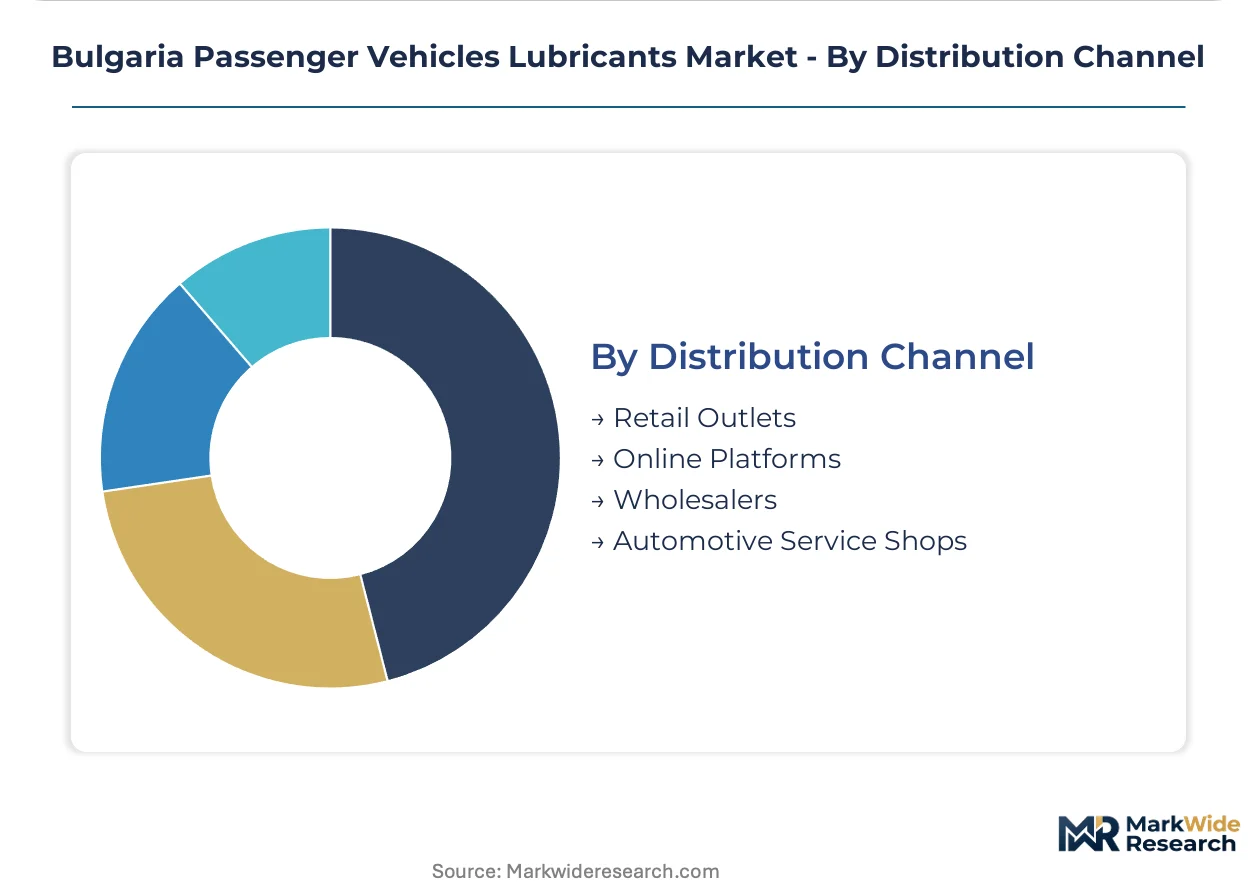
Distribution Channel:
Channel control determines access to high-frequency service touchpoints versus dispersed retail catchments across Bulgaria's geography.
- Automotive Service Shops:Bundled oil-change packages with recurring fleet contracts and technical service capabilities. Shell's corridor control between Sofia and Burgas and Castrol's OEM approval tie-ins concentrate competitive positioning here.
- Wholesalers:Bulk distributors supplying independent repair networks and regional retailers with inventory financing and logistics support. Prista Oil's localized blending near Ruse anchors mid-tier penetration through this channel.
- Retail Outlets:Hypermarkets, auto parts stores, and petrol stations serving individual consumers with immediate availability.
- Online Platforms:E-commerce channels with price transparency and delivery convenience for specification-savvy purchasers.
By volume, Wholesalers leads. By strategic control, Automotive Service Shops shows the steepest expansion trajectory as procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Sofia and Plovdiv where fleet density justifies premium synthetic formulations, while peripheral regions absorb cost volatility through mineral-grade substitution. This asymmetry fragments distributor margins across Bulgaria's urban-rural divide.
Sofia
Centralized fleet procurement dominates lubricant throughput as logistics firms mandate ACEA C5 specifications for turbocharged acquisitions. The Bulgarian Executive Agency for Environment enforces waste-oil collection quotas that elevate fixed costs for service operators. Sofia's commercial vehicle clusters along the Trakia corridor anchor synthetic product penetration among cross-border freight operators.
Plovdiv
Industrial zone density drives transmission fluid demand as manufacturing fleets extend vehicle lifecycles through preventive maintenance. EU F-Gas Regulation compliance requirements reshape HVAC service revenue streams for local automotive shops. Plovdiv's service infrastructure concentrates mid-tier blending distribution through regional wholesaler networks.
Burgas
Black Sea port logistics create whitespace for premium lubricant penetration among maritime-linked freight operators. REACH chemical registration burdens stretch compliance timelines for smaller blenders serving this corridor. Burgas corridor service infrastructure remains underserved relative to synthetic product demand from expanding logistics hubs.
Ruse
Localized blending operations anchor mid-tier segment supply through proximity to Romanian Group II and III base oil import routes. BDS EN norm transpositions of ACEA and API benchmarks create legally binding market access requirements. Ruse's Danube river logistics position supports cross-border distribution into northern Bulgarian catchments.
Bulgaria Passenger Vehicles Lubricants Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with formulation differentiation. The Bulgarian passenger vehicles lubricants market structures around multinational portfolio breadth against regional blending agility. Three archetypes dominate: integrated energy majors with retail network control, mid-tier regional blenders with localized supply chains, and specialty synthetic formulators with OEM approval positioning. Capacity consolidation and procurement centralization represent the dominant competitive vectors reshaping distributor relationships.
Within the integrated major tier, Shell and Castrol exemplify divergent corridor control strategies. Shell leverages retail network density across high-traffic Sofia-Burgas corridors. Castrol sustains brand pull through OEM approval positioning within Volkswagen and Renault service centers. Prista Oil occupies the mid-tier regional blender position with localized operations near Ruse.
| Leading Market Players |
|---|
| Shell |
| Castrol |
| TotalEnergies |
| ExxonMobil Corporation |
| Prista Oil |
| Royal Dutch Shell Plc |
| Chevron Corporation |
| AVIA International |
| Liqui Moly |
| Others |
Value Chain & Pricing Dynamics
The Sofia-Burgas freight corridor channels cost volatility from Romanian and Greek Group II and III base oil imports into downstream price differentiation between synthetic formulations and mineral-based alternatives across Bulgaria's fleet procurement clusters.
Pricing Analysis
Customization-premium spreads separate ACEA C5 synthetic formulations from API-certified mineral grades across Bulgarian automotive service shops. Three-tier pricing structure across premium, standard, and economy levels reflects certification investment, volume scale, and after-sales bundling intensity. Cost compression in mid-tier mineral segments is intensifying because turbocharger penetration collapses price-floor protection previously enjoyed in high-mileage applications. Individual consumers through retail outlets exhibit highest price sensitivity, while fleet operators locked into fluid analysis contracts show lowest sensitivity due to consolidated billing structures.
Supply Chain Analysis
Extended payment terms from Romanian and Greek refineries anchor supplier-financing arrangements that buffer Bulgarian blenders against feedstock cost volatility. Geographic supply concentration centers on Romania, Greece, and regional EU Group III producers for base stock inputs. Raw material dependencies rest on polyalphaolefin synthetic bases, viscosity index improvers, and detergent-dispersant additive packages. Single-source vulnerability from Black Sea logistics chokepoints threatens just-in-time blending operations near Ruse. Distribution runs through wholesaler networks feeding automotive service shops with bundled fleet contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bulgaria's passenger vehicles lubricants market approaches a platform-economics inflection as fleet procurement centralization and OEM approval interoperability reshape competitive control points.
For Market Incumbents: Harden corridor control along the Sofia-Burgas logistics axis through exclusive fluid analysis contracts that lock in cross-border freight operators. Deepen backward integration into additive blending capabilities to offset REACH registration burdens stretching compliance timelines for smaller competitors. Channel control represents the critical defensive lever against mid-tier regional blenders exploiting localized supply chain agility. For New Entrants and Emerging Players: The Burgas Black Sea port corridor's expanding logistics hub represents the most penetrable entry point for premium synthetic penetration among underserved maritime-linked freight operators. Plovdiv's industrial zone transmission fluid demand offers secondary whitespace as manufacturing fleets extend vehicle lifecycles through preventive maintenance programs. A technical service partnership model with established automotive service shops provides the most viable go-to-market angle against entrenched multinational retail networks. For Investors and Strategic Acquirers: EU battery-electric vehicle mandates reshaping the acquisition landscape compress internal-combustion lubricant pools faster than hybrid complexity can offset volume erosion. Long-term viability across the next decade hinges on formulation diversification into PHEV transmission fluids and refrigerant lubricants compliant with F-Gas Regulation phasedown schedules. Acquisition targets should prioritize mid-tier blenders with localized Ruse operations and existing BDS EN norm compliance infrastructure. The signal to track is Sofia municipal fleet electrification pilot expansion rates as early volume erosion indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Blending | REACH compliance cost absorption protects margin structure against mid-tier competitors near Ruse. |
| Long-term Fleet Service Contracts | Fluid analysis bundling locks in Sofia logistics operators through exclusive procurement relationships. |
| Hybrid Powertrain Fluid Development | Electrical conductivity formulations for PHEV e-CVT systems open specification differentiation beyond engine oils. |
| F-Gas Regulation Compliance Services | R-1234yf refrigerant lubricant servicing creates technical add-on revenue for Plovdiv automotive shops. |
| Corridor Distribution Infrastructure | Burgas port logistics penetration captures cross-border freight operator synthetic demand growth. |
Study Parameters
Desk research of EU regulatory filings, base oil trade databases, and ACEA technical bulletins preceded structured interviews with automotive service shop operators, fleet procurement managers, and lubricant blender technical directors across Sofia, Plovdiv, and Burgas. Primary fieldwork with Bulgarian Executive Agency for Environment officials and BDS standards body representatives validated waste-oil collection quota enforcement patterns. Secondary sources included customs import records for Group II and III base stocks, OEM service manual specifications, and automotive aftermarket distributor financial disclosures. Bottom-up volume modeling triangulated against top-down EU lubricant consumption benchmarks anchored forecast integrity.
Assumptions held fixed across the analysis window include EU Green Deal emission mandate trajectory, ACEA C sequence specification adoption rates, and Bulgarian BEV fleet penetration curves derived from municipal pilot programs. Segmentation dimensions modeled encompass product type, end-user procurement architecture, performance certification tier, and distribution channel control intensity. CAGRs were computed from annual volume and value progression across synthetic and mineral formulation splits. Industry-specific inputs integrated turbocharger penetration rates in Light Duty Vehicles and fleet operator centralization indices along the Sofia-Burgas corridor.
Practitioners should monitor EU battery-electric vehicle mandate acceleration, REACH additive substance restriction expansions, and Black Sea logistics disruption events for early signals requiring forecast adjustment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Process Oil Market
Lubricants
Angola Lubricants Market
Lubricants
Aviation Lubricants Market
Lubricants
Russia Lubricants Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Cutting Fluid Market
Lubricants
Global Compressor Oil Market
Lubricants
Neat Cutting Oil Market
Lubricants
Malaysia Automotive Engine Oils Market
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
Middle East Commercial Vehicles Lubricants Market
Lubricants
United States Commercial Vehicles Lubricants Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
EDM Oils/Fluids Market
Lubricants
Germany Automotive Engine Oils Market
Lubricants
America Lubricants Market