

Copper and Brass Flat Products Market Size, Share, and Industry Trends Forecast 2026-2036
Copper and Brass Flat Products Market Insights
Aluminum busbar and composite conductor materials is realigning procurement economics in medium-voltage electrical applications, pressuring brass flat product specifications toward higher conductivity grades. Aurubis AG leverages integrated smelter-to-rolling capacity to sustain premium alloy consistency across European electrical component supply chains. Wieland-Werke AG anchors its position through specialized high-performance copper alloys for semiconductor lead frames and thermal management substrates.
Copper and brass flat products denote rolled, cast, or extruded non-ferrous metal forms with thickness typically ranging from 0.05 mm foils to 25 mm plates, manufactured through hot and cold rolling mills with precise control over grain structure and surface finish for electrical, thermal, or corrosion-resistant applications. Copper strips dominate volume flows into electrical components and heat exchanger manufacturing, where conductivity and formability specifications command margin premiums over commodity construction grades. Brass plates and foils occupy specialized niches in decorative architectural elements and precision electronics, with tighter dimensional tolerances supporting differentiated pricing against standard sheet offerings.
REACH and RoHS frameworks in Europe restrict lead content in free-machining brass alloys, redirecting formulation R&D toward bismuth and silicon substitutes that maintain machinability without hazardous substance classification. China's GB standards for building materials and the US EPA lead-safe certification requirements shape product access thresholds for roofing, cladding, and plumbing applications across their respective jurisdictions. Stakeholders must monitor evolving alloy substitution timelines and certification reciprocity agreements between regulatory regimes to anticipate which product specifications will carry cross-border market access advantages.
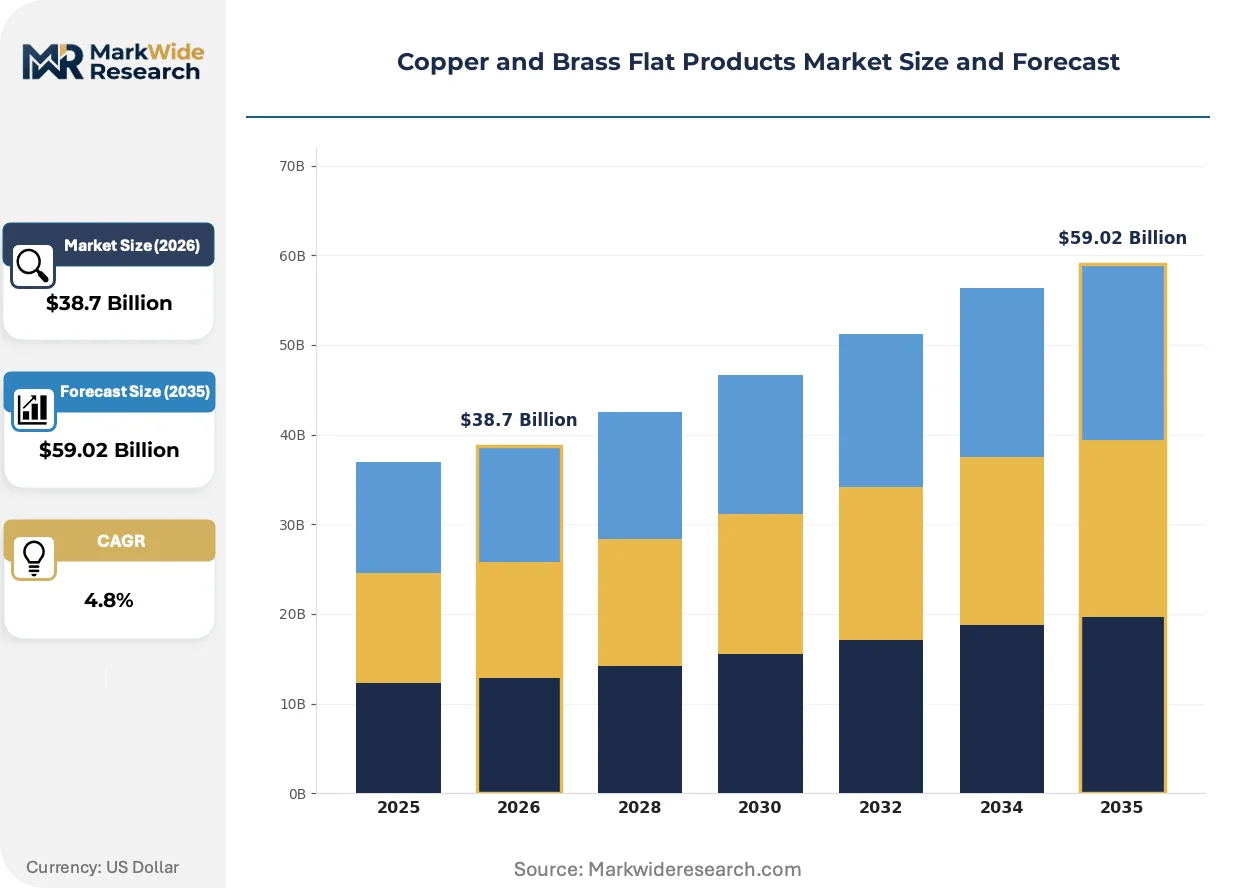
Market Dynamics
Aluminum busbar and composite conductor materials are pressuring brass flat product specifications toward higher conductivity grades, forcing alloy reformulation across electrical component supply chains.
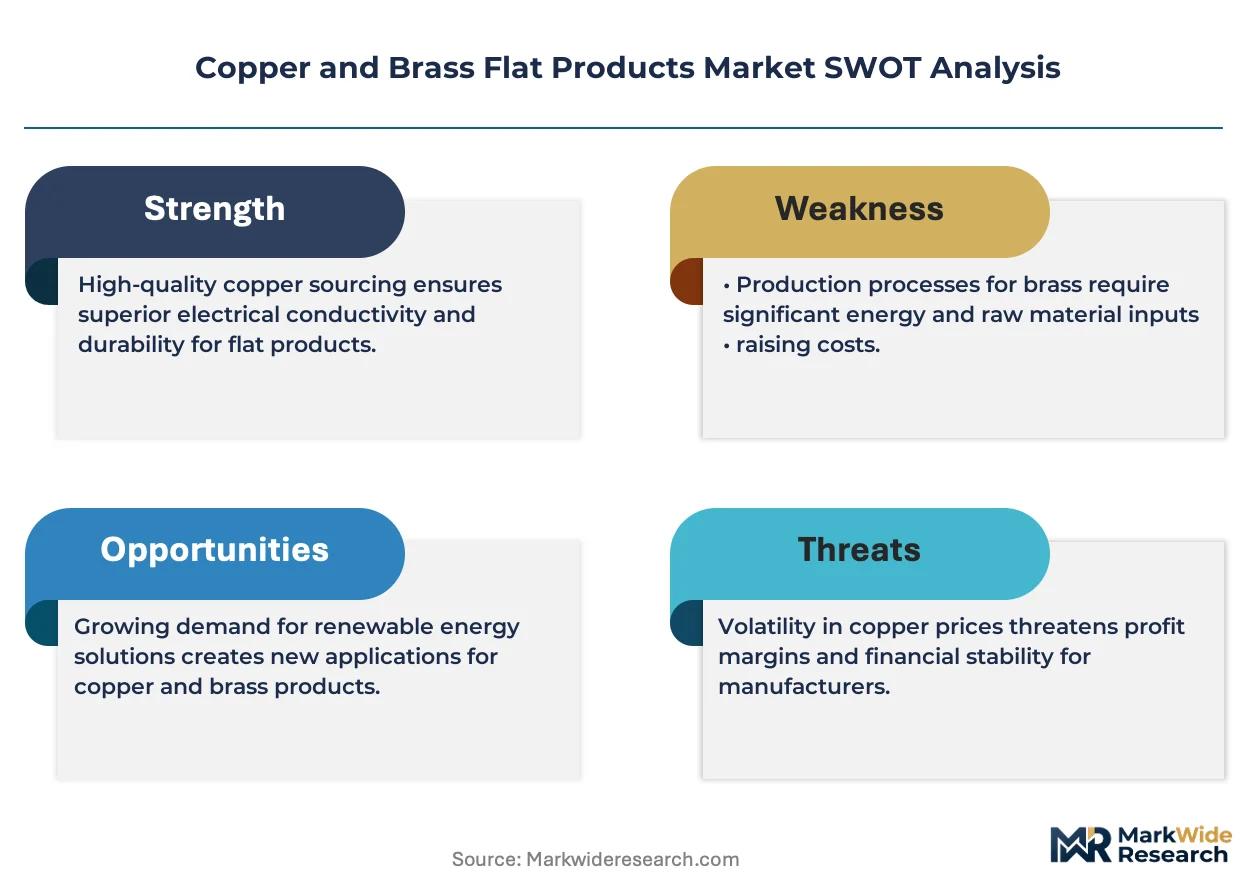
Growth Catalysts
- EV Powertrain Procurement:Electrical component manufacturers are expanding orders for high-conductivity copper strips to serve electric vehicle motor windings and battery interconnects.
- REACH Compliance:Europe's chemical registration framework is tightening traceability requirements, creating competitive advantage for certified suppliers with documented alloy provenance.
- India's PLI Scheme:Production-linked incentives for electronics manufacturing are drawing brass strip imports for connector and terminal fabrication.
Market Restraints
- Copper Price Volatility:London Metal Exchange copper pricing swings compress rolling mill margins and destabilize long-term contract negotiations.
- Lead Substitution Costs:REACH and RoHS restrictions on free-machining brass alloys force expensive R&D into bismuth and silicon substitutes without hazardous substance classification.
- Aluminum Substitution Threat:Composite conductor materials displace copper in medium-voltage distribution where conductivity-to-weight ratios favor lighter alternatives.
Strategic Opportunities
- Semiconductor Thermal Management:High-performance copper alloys for lead frames and heat spreaders serve chip packaging demand from Taiwan and South Korea fabrication facilities.
- Grid Infrastructure Modernization:FERC interconnection queue reforms and IRA transmission investment tax credits expand procurement of high-conductivity busbar materials.
- Recycled Content Certification:ECHA SCIP database requirements and EU Green Deal circular economy mandates create premium positioning for closed-loop copper suppliers.
Industry Challenges
- Alloy Metallurgy Expertise Gap:Formulation chemists capable of balancing machinability, conductivity, and regulatory compliance remain scarce across European rolling mills.
- Multi-Jurisdiction Certification Timelines:Simultaneous compliance with REACH, China's GB standards, and US EPA lead-safe requirements extends product launch cycles by 12-18 months.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper and Brass Flat Products Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to reshape alloy development priorities, with conductivity performance and environmental compliance becoming inseparable design constraints.
Copper-chromium-zirconium alloys engineered for high-temperature strength retention are converging with silicon carbide power module packaging requirements. Automotive Tier 1 suppliers in Germany and Japan are qualifying these materials for 800V EV architectures. The technology is converging with traditional brass specifications, compressing the addressable market for standard conductivity grades in premium electrical applications.
China's GB standards for building materials are tightening heavy metal content thresholds for roofing and cladding applications. MIIT enforcement actions against non-compliant producers are accelerating consolidation among smaller rolling mills. Architectural brass suppliers are redirecting export volumes toward Middle Eastern markets with less stringent certification reciprocity.
Buyers are consolidating supplier relationships around integrated smelter-to-rolling operations with captive scrap recycling and certified carbon accounting. Large electrical OEMs in India and Southeast Asia are disintermediating traders to secure alloy consistency and documentation for ESG reporting. This pattern is most visible in procurement for data center busbar and renewable energy interconnection projects.
Copper and Brass Flat Products Market Segmentation
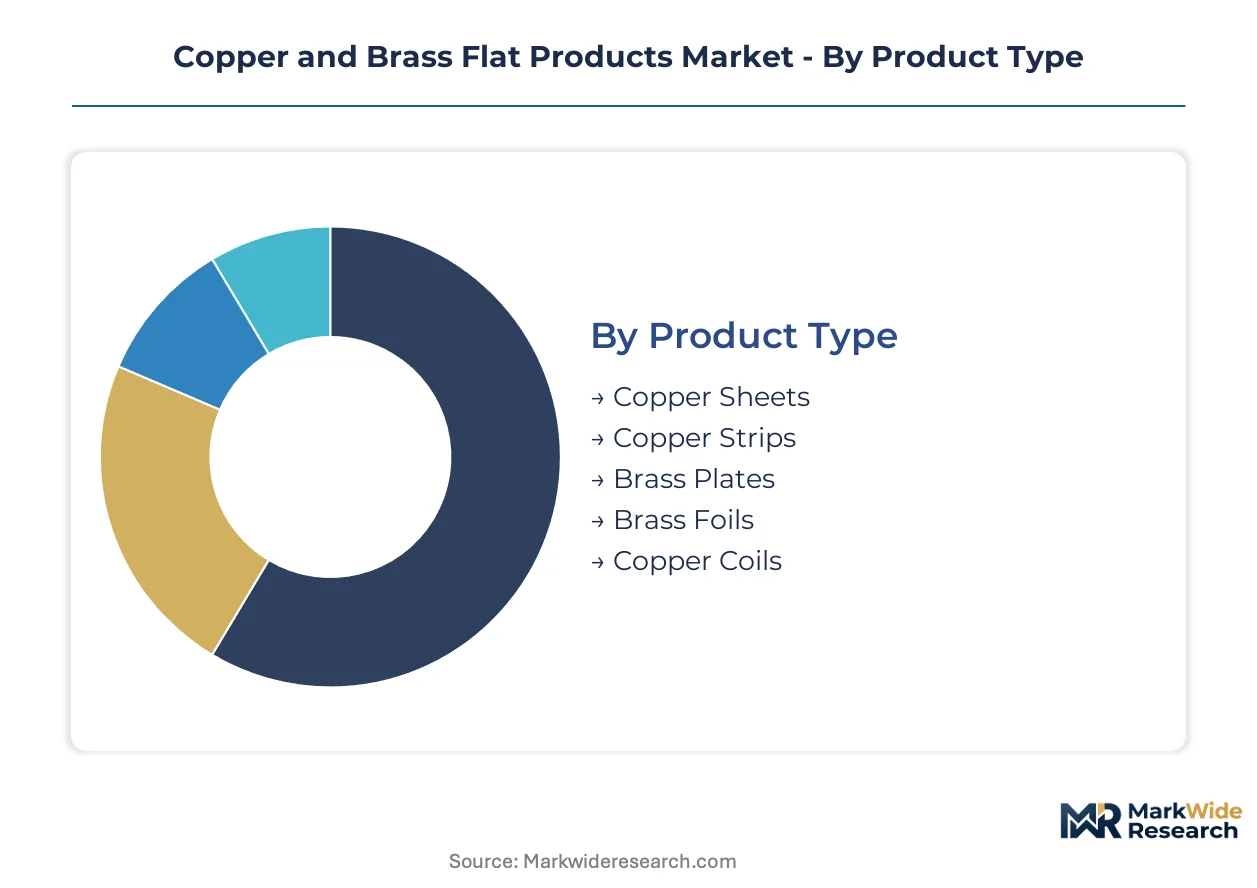
Copper and brass flat products serve radically different value pools across electrical conductivity versus architectural corrosion resistance specifications. Procurement patterns diverge sharply between high-volume commodity grades and precision-tolerance alloys commanding substantial margin premiums.
Product Type:
Volume concentrates in commodity sheet and strip formats while foils and specialized coils capture disproportionate value through technical specifications.
- Copper Strips:Rolled copper with precise thickness control serves motor windings, transformer cores, and battery interconnects where IACS conductivity ratings determine supplier qualification. EV powertrain manufacturers in Germany and Japan are expanding orders for high-conductivity grades that exceed standard electrical specifications.
- Copper Sheets:Broader dimensional formats support busbar fabrication, roofing systems, and industrial equipment housings. Demand clusters in Indian grid infrastructure projects and US data center power distribution where formability and thermal performance balance against installed cost.
- Brass Plates:Copper-zinc alloys with decorative surface finishes supply architectural cladding and precision machining stock. REACH lead restrictions are forcing rapid alloy reformulation toward bismuth-substituted machinability grades.
- Copper Coils:Continuous rolled formats enable high-speed stamping operations for electrical connector production. Japanese automotive Tier 1 suppliers specify grain-controlled annealing for 800V EV terminal consistency.
- Brass Foils:Ultra-thin rolled products below 0.1mm thickness serve EMI shielding and precision spring applications. Taiwanese semiconductor packaging facilities drive qualification of high-strength copper-beryllium alternatives.
Today's leader: Copper Strips. Tomorrow's challenger: Copper Coils.
Application:
Electrical conductivity applications command specification premiums while construction volumes provide baseline capacity utilization.
- Electrical Components:Busbar, terminal, and connector fabrication demands conductivity-certification with full alloy traceability. India's PLI scheme for electronics manufacturing is accelerating brass strip imports for domestic connector production.
- Heat Exchangers:Thermal transfer applications require corrosion-resistant alloys with controlled grain structure for brazing compatibility. HVAC equipment manufacturers specify tin-bearing brass grades for condenser and evaporator coil longevity.
- Roofing & Cladding:Architectural copper systems leverage natural patina formation for aesthetic durability. China's GB standards tightening heavy metal thresholds are redirecting non-compliant export volumes toward Middle Eastern markets.
- Plumbing:Water distribution applications specify lead-free alloys under US EPA lead-safe certification and equivalent European potable water directives. California and New York municipal procurement mandates drive low-lead brass specification adoption.
- Decorative Elements:Interior and exterior ornamental applications prioritize surface finish consistency and tarnish resistance over mechanical properties. Heritage restoration projects in France and Italy specify traditional alloy compositions with documented provenance.
Electrical Components dominates current procurement value. Heat Exchangers shows steepest expansion trajectory through HVAC electrification and industrial decarbonization retrofits.
End Use Industry:
Electronics manufacturing and transportation equipment concentrate premium alloy demand while construction provides volume stability.
- Electronics Manufacturing:Semiconductor lead frames, thermal management substrates, and high-frequency connector systems require ultra-pure copper with oxygen content below 5ppm. South Korean and Taiwanese fabrication facilities are qualifying copper-chromium-zirconium alloys for advanced packaging.
- Transportation Equipment:EV powertrain and charging infrastructure specifications are displacing traditional automotive brass applications. 800V architectures demand conductivity grades that exceed legacy internal combustion engine specifications.
- Construction:Building envelope and structural applications consume commodity-grade sheet and coil for roofing, flashing, and architectural metalwork. US IRA commercial building efficiency incentives are expanding heat pump HVAC specification rates.
- HVAC Systems:Refrigeration and climate control equipment relies on brazable copper tubing and corrosion-resistant brass fittings. European F-Gas Regulation phase-down schedules are accelerating heat pump deployment and associated coil demand.
- Aerospace:Airframe and avionics applications specify high-strength copper-beryllium and copper-nickel alloys with fatigue resistance and thermal stability. FAA certification timelines extend qualification cycles for new alloy introductions.
Electronics Manufacturing captures the highest value per kilogram. Transportation Equipment is gaining share fastest through EV production scale-up.
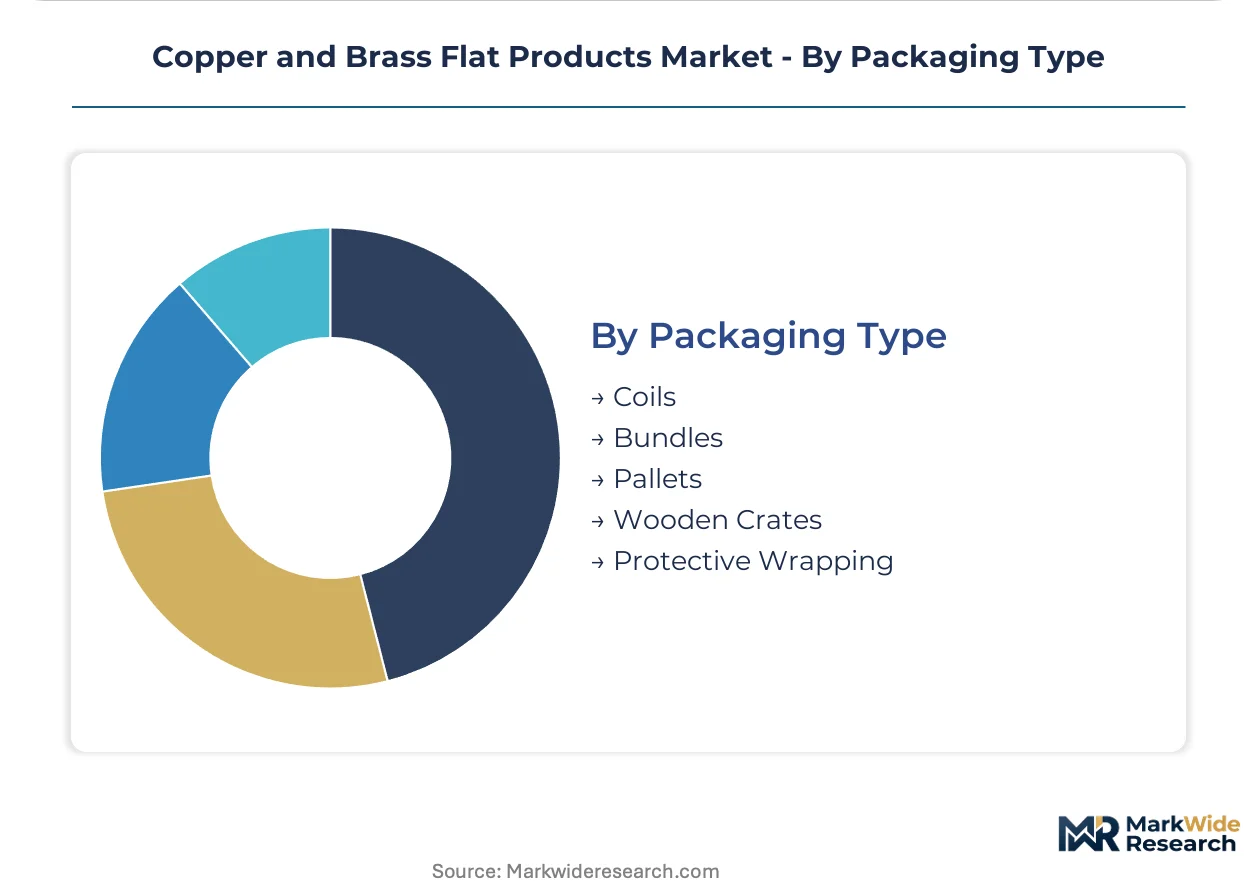
Packaging Type:
Coil and bundle formats dominate electrical component supply chains while protective wrapping specifications rise with ESG documentation requirements.
- Coils:Continuous wound formats enable automated decoiling and stamping operations for high-volume electrical component production. European rolling mills are certifying carbon-accounted packaging for ECHA SCIP database compliance.
- Bundles:Strapped flat product collections serve construction and general fabrication with forklift-accessible handling. Indian importers specify bundle weights optimized for container loading efficiency.
- Protective Wrapping:VCI film and paper interleaving prevents surface oxidation during ocean freight and extended storage. Japanese just-in-time suppliers mandate wrapping specifications that eliminate pre-processing cleaning steps.
- Wooden Crates:Rigid containment for precision foil and thin strip products prevents edge damage and dimensional distortion. Aerospace suppliers require ISPM-15 certified heat-treated crating for international shipments.
- Pallets:Standardized platform loading supports warehouse automation and cross-docking efficiency for distributor networks. Large electrical OEMs in Southeast Asia are consolidating procurement around palletized unit loads with RFID tracking.
Coils maintain incumbent position in electrical supply chains. Protective Wrapping specifications are climbing fastest with traceability and carbon accounting mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial cluster anchors European copper and brass flat products demand through integrated smelter-to-rolling operations serving automotive and electrical component supply chains.
Germany
EV powertrain manufacturers in Stuttgart and Munich are expanding procurement of high-conductivity copper strips for 800V motor windings and battery interconnects. REACH compliance documentation requirements under ECHA frameworks create competitive filtering for certified suppliers with full alloy provenance. The Ruhr Valley concentration of rolling mills maintains captive scrap recycling and carbon-accounted production for ESG-reporting electrical OEMs.
China
Grid infrastructure modernization and data center power distribution are accelerating orders for copper busbar materials across state-owned utility procurement channels. MIIT enforcement of GB standards for building materials is consolidating non-compliant producers and redirecting architectural brass export volumes. The Yangtze River Delta cluster around Shanghai houses precision rolling capacity for semiconductor packaging substrates serving Taiwanese and South Korean fabrication facilities.
India
Electronics manufacturing incentives under the PLI scheme are drawing brass strip imports for domestic connector and terminal production. Bureau of Indian Standards certification timelines for electrical-grade copper are compressing procurement cycles for grid infrastructure contractors. Gujarat's Mundra port corridor is emerging as the primary entry point for Southeast Asian rolled copper serving western Indian automotive clusters.
United States
IRA transmission investment tax credits and FERC interconnection queue reforms are expanding procurement of high-conductivity busbar for renewable energy projects. EPA lead-safe certification requirements for potable water applications are displacing legacy brass alloys in California and New York municipal procurement. The Southeast manufacturing belt from Georgia to Tennessee is concentrating stamping operations for EV electrical component supply chains.
Japan
Automotive Tier 1 suppliers in Nagoya and Osaka are qualifying copper-chromium-zirconium alloys for 800V EV architectures and silicon carbide power module packaging. METI industrial decarbonization roadmaps are tightening carbon intensity thresholds for imported copper materials. The Chubu region's precision rolling mills maintain grain-controlled annealing specifications for semiconductor lead frame consistency.
Copper and Brass Flat Products Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated producers scale smelter-to-rolling operations to capture EV and grid infrastructure procurement growth. The vendor base stratifies between multinational integrated metals groups with captive mining and refining, regional rolling specialists serving construction and general fabrication, and precision alloy developers for semiconductor and aerospace applications. Strategic archetypes include backward-integrated primary producers, specialized high-performance alloy formulators, and distributor-fabricators with regional stocking positions. Competitive moves center on captive scrap recycling certification for EU Green Deal compliance and alloy formulation R&D for lead-free machinability grades.
Within the integrated producer tier, Aurubis AG exemplifies European smelter-to-rolling consolidation with Ruhr Valley production gravity, while Wieland-Werke AG occupies a specialized position in high-performance copper alloys for thermal management substrates. Among Asia-Pacific-based fabricators, Mitsubishi Materials Corporation and JX Nippon Mining & Metals Corporation represent Japanese precision rolling expertise serving automotive and semiconductor packaging demand. These anchors illustrate how geographic proximity to end-use clusters and regulatory compliance documentation capabilities are separating qualified suppliers from commodity-grade competitors.
| Leading Market Players |
|---|
| Aurubis AG |
| Wieland-Werke AG |
| KME Group |
| Mitsubishi Materials Corporation |
| JX Nippon Mining & Metals Corporation |
| Hindalco Industries |
| Jiangxi Copper |
| Mueller Industries |
| PMX Industries |
| Others |
Pricing and Supply Chain Analysis
Formulation chemists with REACH alloy certification expertise in Germany's Ruhr Valley command wage premiums that compress rolling mill margins and widen spreads between certified premium grades and commodity construction sheet. Labor-cost differentials between European certified producers and Indian import-dependent fabricators stratify pricing tiers across electrical component supply chains.
Pricing Analysis
London Metal Exchange copper pricing passes through directly to strip and sheet quotations, with rolling margins absorbing volatility in contract negotiations. Three-tier pricing structure across premium, standard, and economy levels separates IACS-certified electrical grades from architectural brass and commodity construction sheet. Cost compression in standard grades intensifies because aluminum busbar substitution erodes volume leverage. Commodity construction buyers exhibit highest price sensitivity, while semiconductor packaging facilities accept substantial premiums for oxygen-free copper with full provenance documentation.
Supply Chain Analysis
REACH and RoHS certification gating restricts qualified supplier pools to integrated smelter-to-rolling operations with documented alloy provenance and ECHA SCIP database compliance. Production concentrates in Germany, China, and Japan, with raw material supply drawing from Chilean mining concentrate, Zambian cathode, and domestic scrap recycling streams. Single-source vulnerability runs through Chilean concentrate supply contracted under annual offtake agreements. Distribution runs through direct mill relationships with large electrical OEMs, disintermediating trader networks for ESG-reporting procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Green Deal circular economy mandates and ECHA SCIP database requirements are accelerating premium positioning for certified closed-loop suppliers.
For Market Incumbents: Acquire captive scrap recycling assets in Germany and Southeast Asia to secure EU Green Deal compliance documentation and carbon-accounted production. Integrate backward into Zambian or Chilean concentrate offtake to insulate rolling margins from LME volatility. Aluminum substitution in medium-voltage distribution threatens volume leverage in standard grades. For New Entrants and Emerging Players: Electrical OEM procurement teams in India and Southeast Asia represent the most accessible channel entry point for certified strip suppliers with PLI scheme documentation capabilities. Target brass strip qualification for domestic connector production under India's electronics manufacturing incentives. White-space exists in high-conductivity copper-chromium-zirconium alloys for 800V EV architectures where incumbent capacity is constrained. For Investors and Strategic Acquirers: Valuations sit cheapest among regional rolling specialists with construction-grade exposure and limited certification infrastructure. Long-term viability hinges on regulatory compliance documentation capabilities and proximity to EV powertrain manufacturing clusters. Watch FERC interconnection queue clearance rates as inflection signal for grid infrastructure procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Concentrate Supply | Secures rolling margin stability against LME copper volatility for European producers. |
| REACH Certification Investment | Unlocks premium positioning in ECHA SCIP database-compliant electrical component supply chains. |
| Captive Scrap Recycling Buildout | Delivers EU Green Deal circular economy credentials for carbon-accounted procurement mandates. |
| High-Performance Alloy R&D Partnership | Qualifies copper-chromium-zirconium materials for 800V EV silicon carbide packaging applications. |
| Direct Mill Relationship Expansion | Disintermediates trader networks for Indian and Southeast Asian electrical OEM procurement consolidation. |
Research Methodology
Bottom-up electrical component demand modeling reconciled against top-down smelter and rolling capacity tracking forms the analytical core of this study. Primary interviews with rolling mill technical directors, electrical OEM procurement managers, semiconductor packaging engineers, and alloy formulation chemists combined with secondary validation from ECHA registration databases, LME warehouse stock reports, customs trade flow data, and SEC filings from integrated metals groups. Triangulation between consumption-side qualification requirements and supply-side certification capabilities produced volume and value estimates.
Input-output matrices map copper concentrate availability through smelting, refining, and rolling stages across product type, application, end-use industry, and packaging format dimensions. Segment-level CAGRs derive from rolling capacity expansion announcements, EV powertrain procurement timelines, and grid infrastructure investment trajectories. Forecast inputs include FERC interconnection queue data, IRA transmission tax credit utilization rates, and PLI scheme disbursement patterns for electronics manufacturing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum substitution rates in medium-voltage distribution and Chilean concentrate supply disruptions. Model assumptions reflect documented alloy qualification timelines and regulatory reciprocity agreements between REACH, China's GB standards, and US EPA frameworks. A model refresh is warranted upon material change in FERC interconnection reform implementation or EU Green Deal circular economy mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.