
 Copper and Copper Alloy Powder Market | 2026-2036
Copper and Copper Alloy Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Copper and Copper Alloy Powder Market Outlook
Direct supply relationships between atomization houses and additive manufacturing end-users is narrowing, bypassing traditional distributor networks. Kymera International leverages captive gas atomization capacity to serve North American aerospace powder bed fusion operators. Mitsui Mining & Smelting Co., Ltd anchors Asian supply through electrolytic refinement integrated with water atomization. Pometon S.p.A. specializes in brass and bronze powder grades for European friction material and sintered component producers.
Copper and copper alloy powders comprise discrete metallic particles produced via atomization, electrolysis, or chemical reduction, typically spanning 1 to 150 micrometers with purity grades from 99.0% to 99.9%+ depending on end-use electrical or thermal conductivity requirements. These powders serve as feedstock for powder metallurgy compaction, metal injection molding, thermal spray coatings, and additive manufacturing where net-shape forming and material efficiency outperform wrought processing. Bronze powder dominates volume consumption in self-lubricating bearings and structural sintered parts where tin addition improves hardness and wear resistance. 3D printing represents the fastest-expanding application segment as spherical copper and copper-nickel-chrome formulations gain qualification for rocket engine combustion chambers and conformal cooling molds. Electrical components remain the deepest margin pool, with micron-size high-purity copper powder commanding premium pricing for multilayer ceramic capacitor terminations and semiconductor packaging.
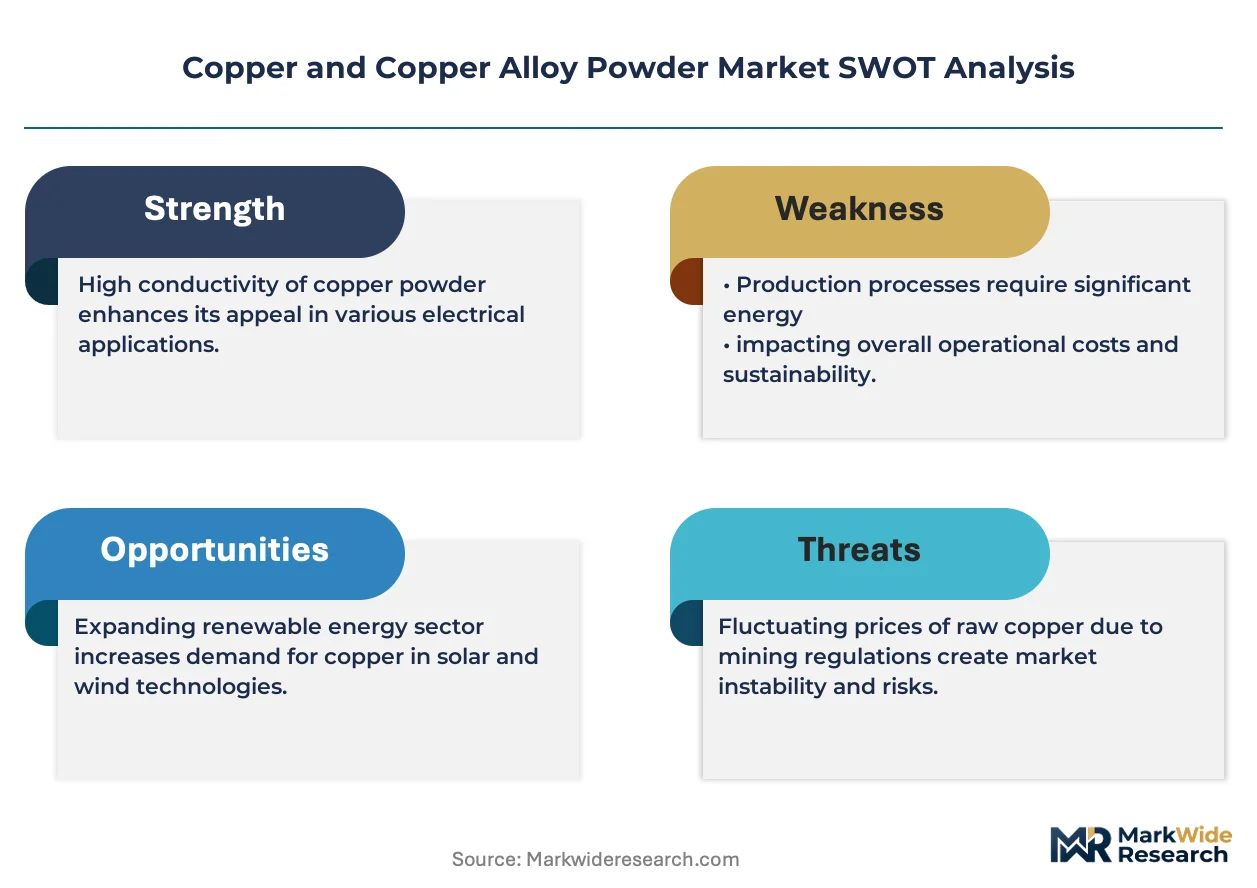
REACH registration and RoHS substance restrictions in Europe compel powder producers to document full material composition and restrict lead content in brass formulations below 0.1% threshold limits. China's GB standards and dual carbon goals enforced by MEE pressure smelters to reduce energy intensity in electrolytic powder production and shift toward hydrogen-reduced or recycled feedstock routes. Stakeholders must monitor evolving powder qualification protocols from FDA and EMA for antimicrobial copper coatings in medical devices, as regulatory clearance timelines will determine which alloy compositions achieve first-mover advantage in healthcare surface applications.
Market Dynamics
Spherical copper powder qualification for laser powder bed fusion is concentrating procurement power among aerospace primes, forcing atomization houses to invest in plasma rotating electrode capacity and bypass traditional powder distributors.
Growth Catalysts
- REACH purity mandates:ECHA enforcement tightens trace metal thresholds for European friction material producers, accelerating electrolytic powder substitution of water-atomized grades in brake pad formulations.
- EV motor winding densification:Hairpin stator designs in traction motors consume ultra-fine high-conductivity copper powder for compaction-formed slot liners, pulling volume from traditional wire winding supply chains.
- Conformal cooling mold adoption:Tooling manufacturers in Germany and Japan integrate additively manufactured copper-alloy heat sinks into injection mold cores, replacing gun-drilled beryllium copper inserts.
Market Restraints
- Argon supply volatility:Gas atomization operations face input cost pressure from industrial gas supply concentration in Gulf Coast pipeline networks and Ukrainian helium displacement effects.
- Electrolytic capacity concentration:High-purity powder production clusters in Chinese smelter complexes, exposing non-Chinese buyers to export license unpredictability and carbon intensity scrutiny.
- Plasma spray substitution:HVOF-applied cermet coatings displace bronze powder in certain bearing surface applications where hardness requirements exceed sintered bronze limits.
Strategic Opportunities
- Antimicrobial medical device coatings:FDA and EMA pathway clarity for copper-nickel surface treatments in implantable hardware creates first-mover qualification advantages for alloy powder suppliers.
- Hydrogen-reduced copper routes:China's dual carbon goals and MEE enforcement incentivize smelters to shift from electrolytic to hydrogen-direct reduction, lowering Scope 3 emissions for European automotive buyers.
- Direct-to-printer distribution:Powder bed fusion operators in aerospace establish toll-processing relationships with atomization houses, disintermediating regional distributors and capturing lot-traceability value.
Industry Challenges
- Spheroidization technician scarcity:Plasma rotating electrode and plasma atomization operations require specialized metallurgists capable of optimizing electrode feed rates and plasma gas mixtures, with training pipelines lagging capacity expansion.
- Multi-certification burden:Suppliers serving aerospace, medical, and automotive verticals simultaneously must maintain AS9100, ISO 13485, and IATF 16949 quality systems, duplicating audit costs without volume scale.
- Lot-to-lot rheology control:Powder bed fusion users demand sub-2% tap density variation across shipments, requiring atomization houses to implement in-line laser diffraction and reject streams that compress margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper and Copper Alloy Powder Market |
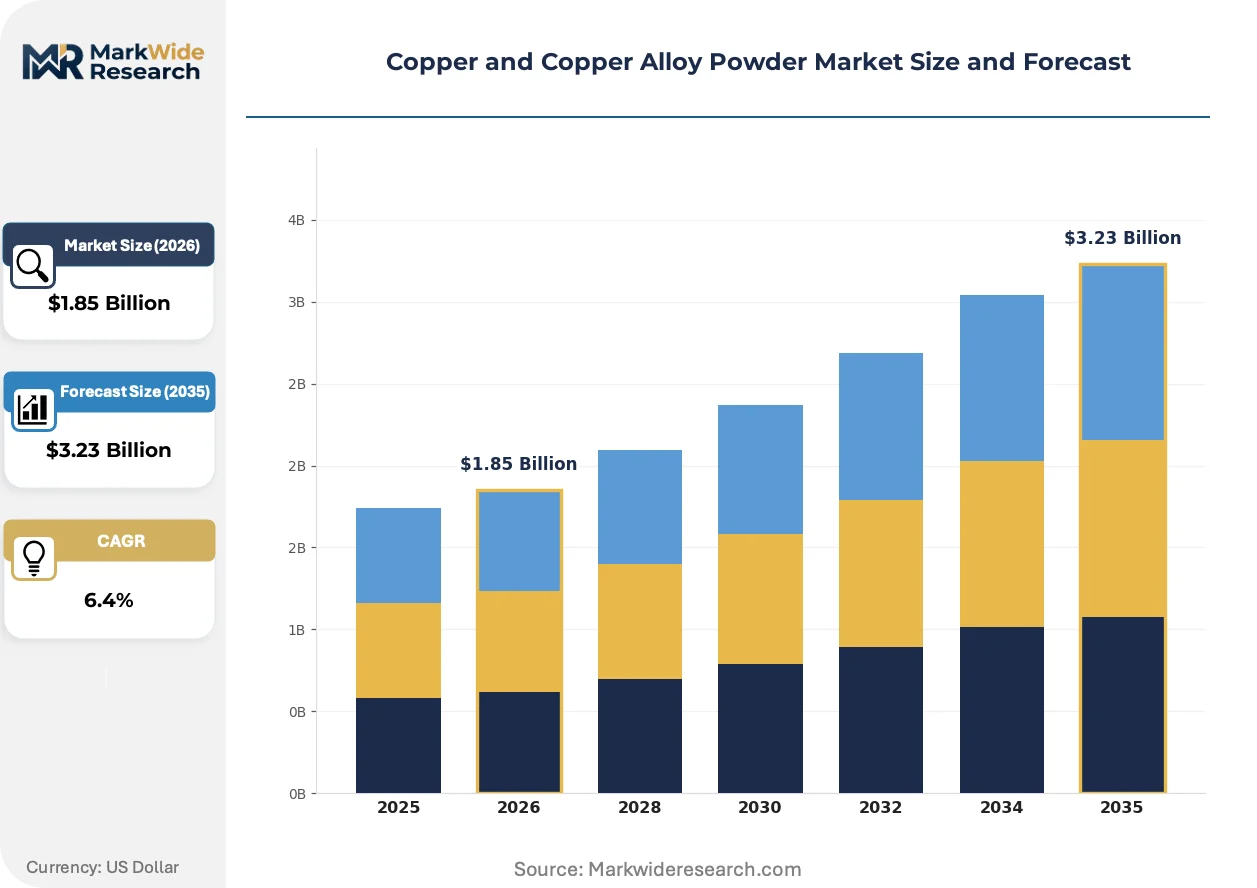
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Powder, Bronze Powder, Brass Powder, Copper-Coated Powder Application: 3D Printing, Electrical Components, Automotive Parts, Aerospace Components Particle Size: Micron Size, Nano Size, Millimeter Size, Coarse Size End User: Manufacturing, Electronics, Aerospace, Automotive |
| Companies Covered | Kymera International, Mitsui Mining & Smelting Co., Ltd, GGP Metalpowder AG, Makin Metal Powders, American Elements, Fukuda Metal Foil & Powder Co., Ltd, Pometon S.p.A., The Metal Powder Company Limited, American Chemet Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper and Copper Alloy Powder Market Strategic Shifts
Process analytical technology and closed-loop atomization control are compressing powder qualification timelines, while regulatory pressure on carbon intensity reshapes feedstock sourcing strategies across major consuming regions.
Plasma rotating electrode process (PREP) equipment is digitizing quality assurance workflows in spherical copper powder production. Aerospace powder bed fusion operators in Germany and the United States specify PREP-derived powders for rocket engine combustion chambers, rejecting traditional gas-atomized material due to satellite particle contamination. Real-time melt pool monitoring and machine learning classification of particle morphology is digitizing the link between atomization parameters and final part mechanical properties.
China's GB standards enforcement and MEE dual carbon implementation are tightening energy intensity benchmarks for electrolytic powder production. Smelters in Jiangxi and Anhui provinces face mandatory carbon emissions trading compliance, accelerating capital allocation toward hydrogen-reduced copper oxide feedstock routes. European automotive Tier-1 suppliers now require documented Scope 3 emissions for copper powder in motor laminations, privileging producers with verified low-carbon process routes.
Direct toll-processing contracts between atomization houses and aerospace primes are displacing distributor-held inventory models. Powder bed fusion operators in the United States and Germany negotiate multi-year take-or-pay agreements with captive atomization capacity, securing lot traceability and custom chemistry specifications. This channel compression is most visible in North American rocket propulsion supply chains, where SpaceX and Blue Origin subsidiaries source copper-nickel-chrome powders directly from Kymera International gas atomization lines.
Copper and Copper Alloy Powder Market Segmentation
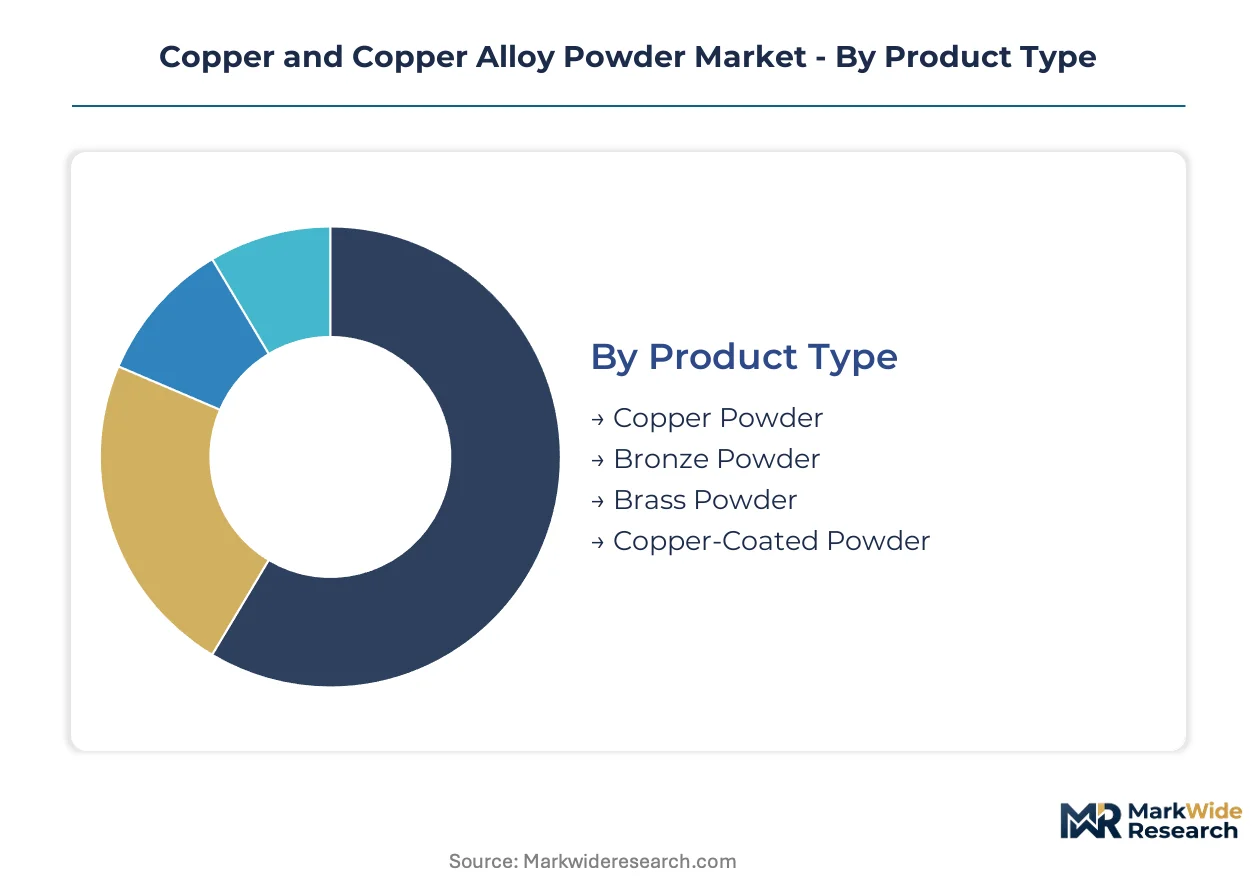
Copper and copper alloy powder markets fragment across technical specifications that dictate atomization method selection and end-use qualification pathways. Product chemistry, particle geometry, and application requirements create distinct supply chains with divergent margin structures and certification burdens.
Product Type:
After-sales service intensity varies sharply across alloy chemistries, with high-purity electrolytic grades demanding lot-traceability support and custom blending services that commodity bronze formulations rarely require.
- Copper Powder:Electrolytic and atomized grades span 99.0% to 99.9%+ purity, with spherical morphology commanding premium positioning for laser powder bed fusion feedstock. Demand concentrates in German and US aerospace supply chains where rocket engine combustion chamber manufacturers specify PREP-derived material with sub-50 ppm oxygen content, constrained by plasma rotating electrode capacity scarcity and argon supply volatility.
- Bronze Powder:Copper-tin alloys typically containing 10-12% tin by weight deliver enhanced hardness and wear resistance for self-lubricating bearing applications. Volume concentrates in European friction material producers facing REACH-mandated trace metal threshold tightening, pulling electrolytic substitution of legacy water-atomized grades in brake pad formulations.
- Brass Powder:Copper-zinc formulations serve decorative coatings and low-load structural sintered parts where color consistency and machinability outweigh conductivity requirements. RoHS lead content restrictions below 0.1% threshold limits reshape European supplier qualification.
- Copper-Coated Powder:Surface-modified particles enable dispersion-strengthened composites and specialized thermal spray applications. Chinese domestic EV motor production scales drive interconnect coating demand.
By volume, bronze powder leads through established bearing and friction material consumption. By growth pace, high-purity copper powder for additive manufacturing is ahead.
Application:
Application selection determines atomization capital requirements, with aerospace and 3D printing specifications demanding spherical morphology that water atomization cannot achieve.
- 3D Printing:Spherical copper and copper-nickel-chrome powders gain qualification for rocket engine combustion chambers and conformal cooling molds where net-shape forming outperforms wrought processing. German and Japanese tooling manufacturers integrate additively manufactured copper-alloy heat sinks into injection mold cores, displacing gun-drilled beryllium copper inserts.
- Electrical Components:Micron-size high-purity copper powder commands premium positioning for multilayer ceramic capacitor terminations and semiconductor packaging, representing the deepest margin pool. Hairpin stator designs in traction motors consume ultra-fine high-conductivity material for compaction-formed slot liners.
- Automotive Parts:Sintered structural components and friction materials dominate volume, with REACH compliance tightening purity benchmarks for European brake pad producers.
- Aerospace Components:Direct toll-processing contracts between atomization houses and primes displace distributor-held inventory models, securing lot traceability and custom chemistry specifications.
Electrical components generate the highest margins per kilogram. 3D printing applications are climbing the fastest as qualification timelines compress.
Particle Size:
Size classification dictates atomization technology selection and downstream process compatibility, with sub-45 micron fractions commanding disproportionate value capture.
- Micron Size:Particles spanning 1-150 micrometers serve powder metallurgy compaction, metal injection molding, and thermal spray coatings. Powder bed fusion users demand sub-2% tap density variation across shipments, requiring in-line laser diffraction and reject stream management.
- Nano Size:Sub-100 nanometer particles enable conductive inks, antimicrobial coatings, and catalyst applications. FDA and EMA pathway clarity for copper-nickel surface treatments in implantable hardware creates first-mover qualification advantages.
- Millimeter Size:Coarse fractions support filtration media and specialized chemical process applications with lower purity requirements.
- Coarse Size:Oversize material typically reprocessed or diverted to metallurgical feedstock rather than powder applications.
Micron size fractions dominate tonnage shipments. Nano size materials are gaining share fastest through electronics and medical surface treatment adoption.
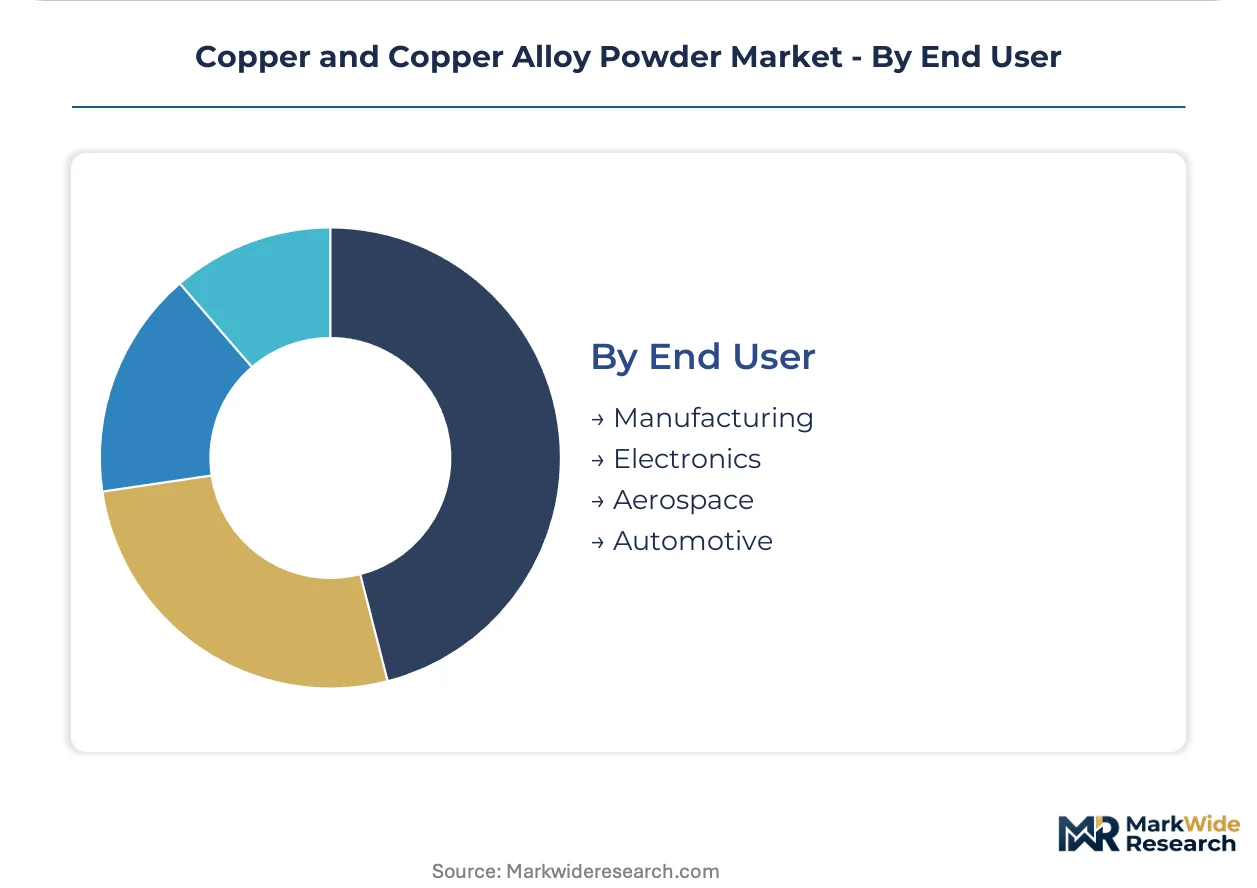
End User:
End-user concentration shapes geographic production footprints, with Chinese domestic scaling in EV manufacturing redirecting electrolytic capacity toward battery interconnect and motor winding applications.
- Manufacturing:Powder metallurgy compaction and metal injection molding operations consume bronze and brass grades for structural components and self-lubricating bearings. REACH enforcement accelerates electrolytic substitution in European friction material supply chains.
- Electronics:Multilayer ceramic capacitor terminations and semiconductor packaging demand 99.9%+ purity with controlled particle morphology. China's GB standards and MEE dual carbon goals pressure smelters toward hydrogen-reduced feedstock routes.
- Aerospace:Rocket propulsion and thermal management applications specify PREP-derived spherical powders with documented lot traceability. SpaceX and Blue Origin subsidiaries source copper-nickel-chrome powders directly from captive North American atomization capacity.
- Automotive:Hairpin stator densification and friction materials drive volume, with European Tier-1 suppliers requiring documented Scope 3 emissions for motor lamination materials.
Manufacturing absorbs the greatest tonnage. Aerospace end-use is expanding most quickly through direct supply chain compression and qualification-driven premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in copper and copper alloy powders tilts toward Chinese electrolytic producers serving domestic EV supply chains, while European buyers absorb REACH compliance premiums without equivalent supply leverage.
United States
Aerospace powder bed fusion operators drive spherical copper demand for rocket engine combustion chambers. FAA certification pathways for additively manufactured propulsion components accelerate qualification timelines. Direct toll-processing contracts concentrate procurement power among primes in Texas and California, bypassing traditional distributor networks.
Germany
Conformal cooling mold adoption pulls copper-nickel-chrome powders into injection tooling applications. ECHA REACH enforcement tightens trace metal thresholds for friction material producers. Industrial clusters in Bavaria and Baden-Württemberg integrate additively manufactured heat sinks into automotive supplier tooling.
China
Domestic EV motor and battery interconnect production scales electrolytic powder consumption for hairpin stator slot liners. MEE dual carbon goals and GB standards enforcement pressure Jiangxi and Anhui smelters toward hydrogen-reduced feedstock routes. Yangtze River Delta battery manufacturers redirect high-purity capacity from export to captive motor winding supply.
Japan
Tooling manufacturers advance copper-alloy additive manufacturing for thermal management in semiconductor packaging equipment. METI industrial decarbonization incentives favor low-carbon powder routes for automotive Tier-1 suppliers. Nagoya-area precision mold producers displace gun-drilled beryllium copper with printed conformal cooling inserts.
South Korea
Semiconductor packaging demand concentrates micron-size high-purity copper powder for multilayer ceramic capacitor terminations. K-environmental regulations align with EU carbon border adjustments, privileging documented low-carbon supply chains. Seoul Capital Area electronics manufacturers secure long-term electrolytic contracts with carbon intensity verification.
Copper and Copper Alloy Powder Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream where atomization technology and lot-traceability systems determine qualification access. Market structure concentrates around captive gas atomization capacity serving aerospace primes, with electrolytic refinement operations clustering in Asian smelter complexes. Three archetypes dominate: vertically integrated mining-to-powder houses, toll-processing atomization specialists, and regional blending operations serving friction materials. Competitive dynamics center on plasma rotating electrode capacity expansion and direct-to-printer distribution channel compression.
Among North American atomization houses, Kymera International exemplifies the captive-capacity archetype serving aerospace powder bed fusion operators. Mitsui Mining & Smelting Co., Ltd anchors Asian supply through integrated electrolytic refinement. Pometon S.p.A. occupies a position within European specialty alloys, representing the regional formulation-focused tier serving friction material and sintered component producers.
| Leading Market Players |
|---|
| Kymera International |
| Mitsui Mining & Smelting Co., Ltd |
| GGP Metalpowder AG |
| Makin Metal Powders |
| American Elements |
| Fukuda Metal Foil & Powder Co., Ltd |
| Pometon S.p.A. |
| The Metal Powder Company Limited |
| American Chemet Corporation |
| Others |
Value Chain & Pricing Dynamics
Chinese electrolytic capacity concentration in Jiangxi and Anhui provinces anchors downstream margin capture in battery interconnect and motor winding supply chains. Aerospace primes in Texas and California absorb configured-to-order premiums for PREP-derived spherical grades while friction material producers face REACH-mandated cost pass-throughs without equivalent procurement leverage.
Pricing Analysis
Configured-to-order PREP-derived spherical copper powder commands substantial premiums over standard water-atomized bronze grades for friction applications. Pricing stratifies across aerospace qualification tiers, automotive motor lamination specifications, and commodity bearing formulations, with oxygen content thresholds and lot-traceability documentation as primary differentiation drivers. Cost compression in standard bronze grades intensifies as European REACH enforcement accelerates electrolytic substitution. Automotive Tier-1 suppliers exhibit highest price sensitivity due to Scope 3 emissions documentation requirements, while aerospace powder bed fusion operators prioritize supply security over unit cost.
Supply Chain Analysis
Export control regimes on plasma rotating electrode process equipment limit spherical powder capacity expansion outside North America and Germany. Production draws from Chinese electrolytic smelter complexes, Japanese precision atomization houses, and German PREP specialists. Argon supply concentration in Gulf Coast pipeline networks and Ukrainian helium displacement effects create single-source vulnerability for gas atomization operations. Distribution runs through direct toll-processing contracts between atomization houses and aerospace primes, displacing regional distributor-held inventory models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Copper and copper alloy powder markets reward service-attach strategies as lot-traceability documentation and custom blending services expand faster than commodity powder tonnage. After-sales qualification support for aerospace powder bed fusion operators now generates margin premiums exceeding base material value.
For Market Incumbents: Harden plasma rotating electrode capacity positions through captive technician training pipelines and multi-year take-or-pay agreements with aerospace primes. Kymera International's direct-to-printer distribution model demonstrates how channel control defends margin pools against distributor disintermediation. AS9100, ISO 13485, and IATF 16949 quality system maintenance represents a necessary cost burden that smaller competitors cannot replicate at equivalent scale. For New Entrants and Emerging Players: Establish a beachhead in hydrogen-reduced copper oxide feedstock routes serving European automotive Tier-1 suppliers with documented Scope 3 emissions requirements. China's MEE dual carbon enforcement creates white-space for low-carbon process specialists outside electrolytic capacity clusters. FDA and EMA antimicrobial coating qualification pathways for medical device applications offer regulatory-first-mover positioning with limited incumbent penetration. For Investors and Strategic Acquirers: Capital is best deployed toward toll-processing atomization specialists with captive aerospace qualification and direct prime relationships rather than commodity electrolytic operations exposed to Chinese export license unpredictability. Long-term viability across the projection horizon hinges on spherical morphology capability and regulatory certification depth. Watch for plasma rotating electrode equipment license availability as inflection indicator for Western capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Rotating Electrode Capacity Expansion | PREP equipment deployment secures aerospace powder bed fusion qualification access for rocket engine combustion chambers. |
| Hydrogen-Reduced Feedstock Transition | Low-carbon process routes satisfy European automotive Scope 3 emissions documentation requirements under ECHA frameworks. |
| Direct Toll-Processing Contracts | Long-term take-or-pay agreements with SpaceX and Blue Origin subsidiaries disintermediate distributor networks and capture lot-traceability value. |
| Antimicrobial Coating Regulatory Pathway | FDA and EMA qualification for copper-nickel surface treatments in implantable hardware creates first-mover medical device market access. |
| Captive Gas Atomization Investment | In-house argon recovery systems mitigate Gulf Coast supply concentration risk for North American spherical powder production. |
Study Parameters
A spread of perspectives from atomization house operations directors, aerospace powder bed fusion procurement leads, automotive Tier-1 supplier materials engineers, and friction material formulation chemists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, ECHA REACH registration databases, Chinese MEE environmental compliance disclosures, and customs trade flow records. Bottom-up capacity assessments and top-down demand segmentation were triangulated against electrolytic production statistics and additive manufacturing equipment installation data.
Demand-supply balance modeling across the analysis window integrated powder metallurgy compaction rates, metal injection molding throughput, thermal spray coating consumption, and additive manufacturing build volume expansion. Segmentation dimensions included alloy chemistry tiers, particle morphology specifications, end-use qualification pathways, and regional regulatory clusters. CAGRs were derived from fitted growth curves calibrated to EV motor production scaling, aerospace rocket engine program cadence, and conformal cooling mold adoption patterns in German and Japanese tooling markets.
Stress conditions across argon supply disruption scenarios, Chinese export license restriction probabilities, and REACH trace metal threshold tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding plasma rotating electrode capacity expansion timelines and hydrogen-reduction process route commercialization. Material shifts in FAA certification pathways for additively manufactured propulsion components or EMA antimicrobial coating approval timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Beryllium Copper Billet Market
Metals
Steel Drums Market
Metals
Zinc Ingots Market
Metals
Iron and Steel Market
Metals
Metal Injection Molding (Mim) Powders Market
Metals
Grain Oriented Electrical Steel Market
Metals
Hafnium Foil Market
Metals
North America Electrical Steel Market
Metals
US and Mexico Stainless Steel Market
Metals
Tungsten Metal Powder Market
Metals
Niobium Oxide Market
Metals
Bismuth Oxide Market
Metals
GCC Aluminium Cans Market
Metals
Carbon Steel Market
Metals
Crude Steel Market
Metals
High Purity Boron Market