
 Chromium Polynicotinate Market | 2026-2036
Chromium Polynicotinate Market Size, Share, and Industry Trends Forecast 2026-2036
Chromium Polynicotinate Market Outlook
The gap between pharmaceutical-grade and bulk commodity chromium polynicotinate is expanding. NOW Foods leverages vertically integrated botanical extraction capabilities to secure upstream niacin supply chains. Thorne Research differentiates through third-party purity certifications and practitioner-exclusive distribution. Sabinsa Corporation anchors South Asian raw material sourcing with in-house chromatographic standardization.
Chromium polynicotinate denotes a coordination complex where trivalent chromium binds to nicotinic acid (niacin), typically yielding 200–600 mcg elemental chromium per unit dose via chelation synthesis; manufacturers employ spray-drying or fluid-bed granulation to enhance bioavailability in finished dosage forms. The ingredient serves primarily as a glucose tolerance factor in dietary supplements targeting insulin sensitivity and lipid metabolism. Capsules and tablets command the largest share of finished product value, while powders capture accelerating demand from functional food fortification and personalized nutrition compounding. Dietary supplements remain the dominant application channel, though animal nutrition formulations for metabolic disorders in livestock represent an emerging margin pool.
The FDA regulates chromium polynicotinate as a dietary ingredient under DSHEA, requiring New Dietary Ingredient notifications for novel delivery formats or modified complexes. The EPA oversees chromium waste discharge from chemical synthesis facilities, elevating compliance costs for domestic manufacturers. India's CDSCO and BIS frameworks govern import quality standards for mineral complexes entering pharmaceutical and nutraceutical channels. Stakeholders must track evolving maximum permissible limits for hexavalent chromium contamination across jurisdictions and assess backward integration into niacin precursor supply as a risk-mitigation priority.
Market Dynamics
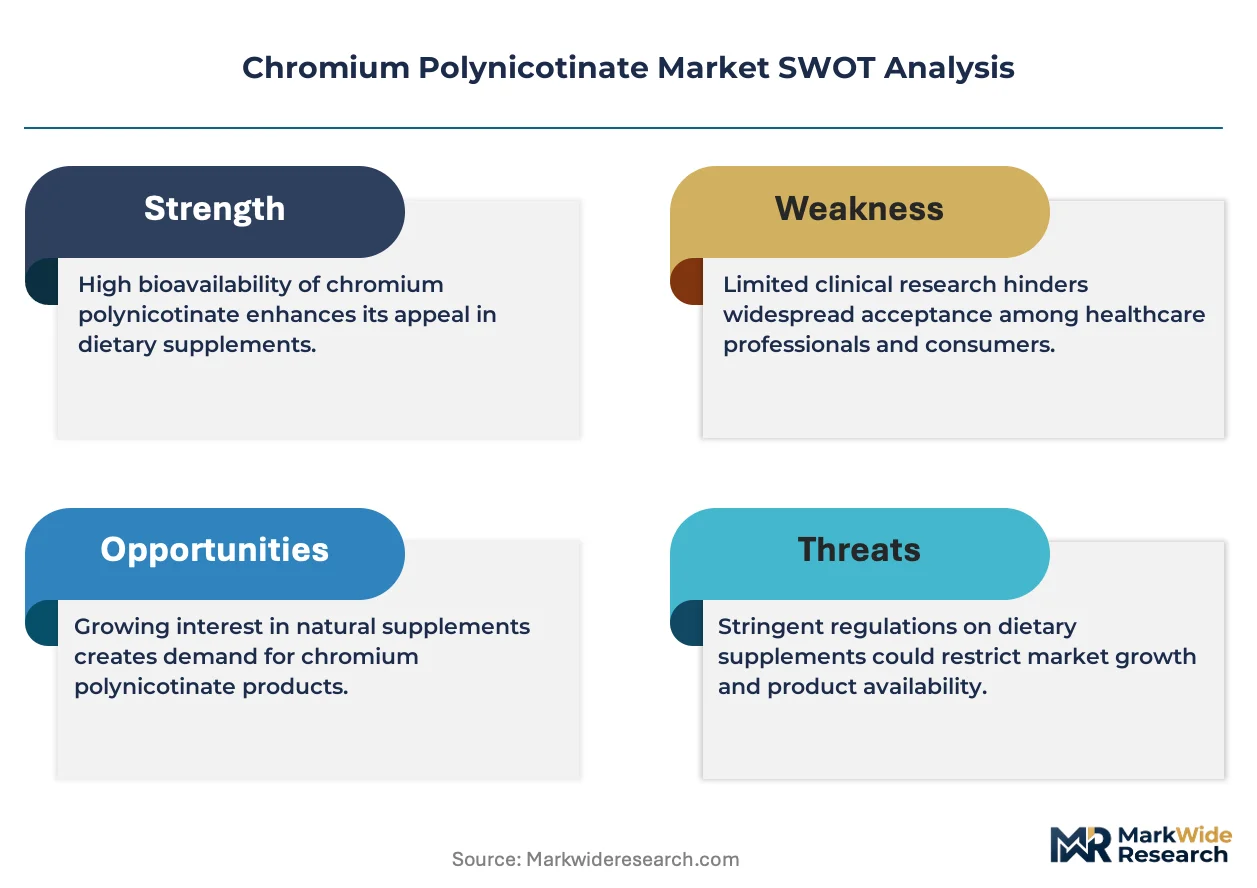
The chromium polynicotinate market is bifurcating around purity grades as sports nutrition formulators and metabolic health clinics diverge from bulk animal feed buyers, with FDA's New Dietary Ingredient notification pathway creating a compliance moat that rewards upstream niacin integration.
Growth Catalysts
- Metabolic health clinic expansion:Functional medicine networks in the United States are standardizing chromium polynicotinate protocols for insulin resistance management, driving pharmaceutical-grade demand.
- FSSAI mineral fortification guidelines:India's food safety regulator has expanded permissible chromium forms in processed foods, opening functional food channels previously restricted to supplements.
- Spray-drying equipment upgrades:Contract manufacturers in China are deploying fluid-bed granulation systems that improve bioavailability metrics for export-grade complexes.
Market Restraints
- Niacin price volatility:Crude oil fluctuations directly impact synthetic niacin precursor costs, compressing margins for non-integrated formulators.
- Hexavalent chromium contamination limits:EPA discharge standards for chemical synthesis facilities have elevated domestic US production costs versus Asian imports.
- Yeast-bound chromium substitution:Brewer's yeast extracts compete in the glucose tolerance factor positioning, particularly in European natural products channels.
Strategic Opportunities
- Veterinary metabolic disorder protocols:Livestock nutritionists are piloting chromium polynicotinate for dairy cow ketosis prevention, creating a margin pool outside human supplements.
- Personalized nutrition compounding:Direct-to-consumer powder formats are bypassing retail supplement channels through practitioner-led subscription models.
- CDSCO pharmaceutical-grade pathway:India's drug regulator is clarifying mineral complex standards that would enable Rx-adjacent positioning in metabolic syndrome management.
Industry Challenges
- Chromatographic standardization expertise:In-house HPLC capability gaps at mid-tier manufacturers delay batch release timelines.
- Dual-jurisdiction compliance:Simultaneous DSHEA notification and REACH registration requirements fragment regulatory affairs resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromium Polynicotinate Market |
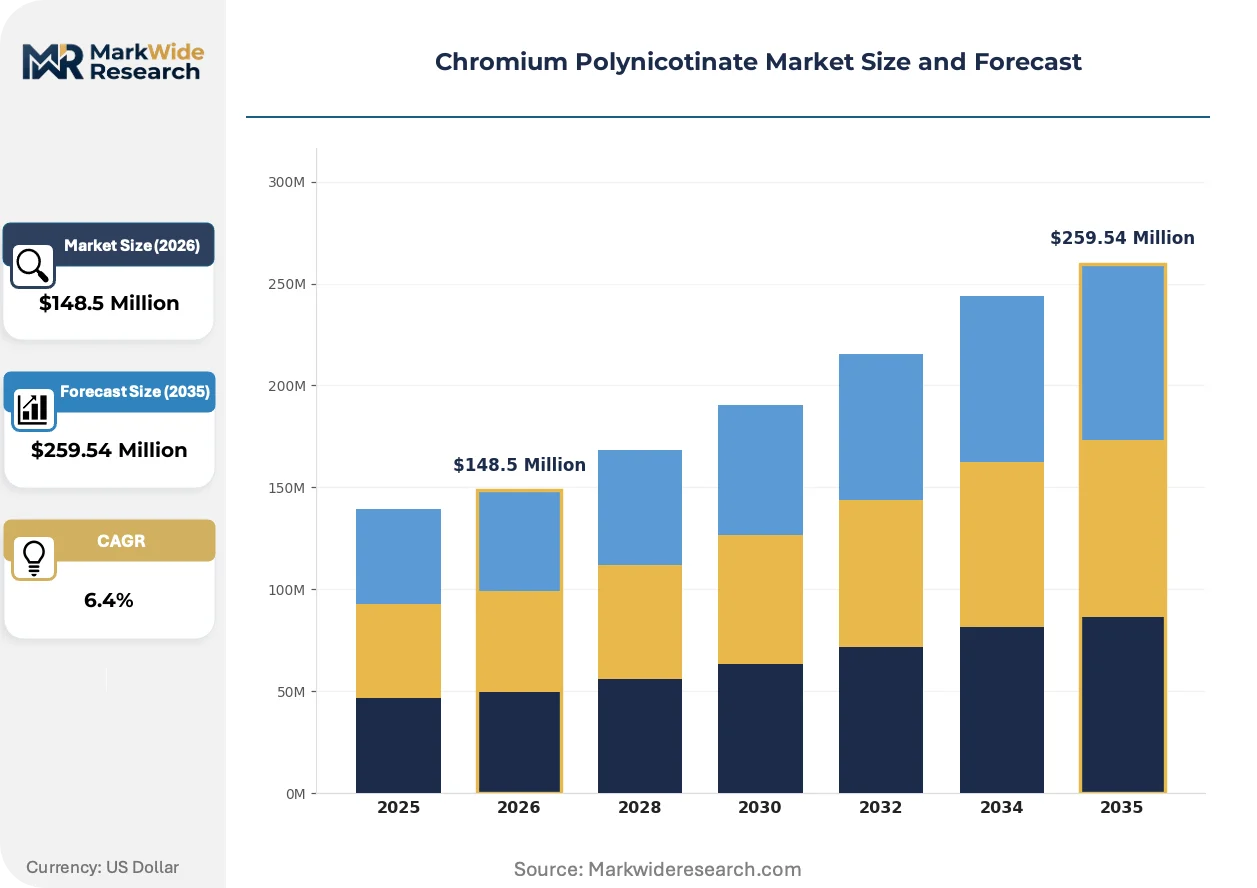
| Market Size in 2026 | $148.5 Million |
| Market Size in 2035 | $259.54 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Powders, Liquids Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Animal Nutrition Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies End User: Consumers, Health Care Providers, Fitness Centers, Nutritional Labs |
| Companies Covered | Sabinsa Corporation, NOW Foods, Thorne Research, Swanson Health Products, Solgar, Nature's Way, Pure Encapsulations, NutraBio Labs, Bio-Tech Pharmacal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromium Polynicotinate Market Strategic Shifts
Formulation science and regulatory segmentation are reshaping competitive positioning in chromium complexes, with bioavailability measurement standards and delivery format diversification emerging as primary vectors of differentiation.
Microencapsulation technology is unifying lipid-based coating systems with mineral chelates to protect chromium polynicotinate from gastric degradation. Sports nutrition brands in North America are adopting these formats for pre-workout matrices. The technology is unifying pharmaceutical-grade specifications with consumer palatability requirements, compressing the gap between clinical and retail positioning.
REACH authorization timelines for chromium compounds are extending registration burdens for EU-market suppliers. ECHA's evolving classification of trivalent chromium salts is forcing reformulation reviews across legacy product lines. Dietary supplement distributors are responding by diverting volume to Middle Eastern and Southeast Asian markets with less restrictive chemical frameworks.
Buyer concentration among metabolic health clinics is consolidating procurement power against fragmented raw material suppliers. Practitioner-exclusive distribution networks are displacing mass-market retail for high-purity grades. This concentration is most visible in the United States, where integrated functional medicine platforms now negotiate direct manufacturer relationships.
Chromium Polynicotinate Market Segmentation
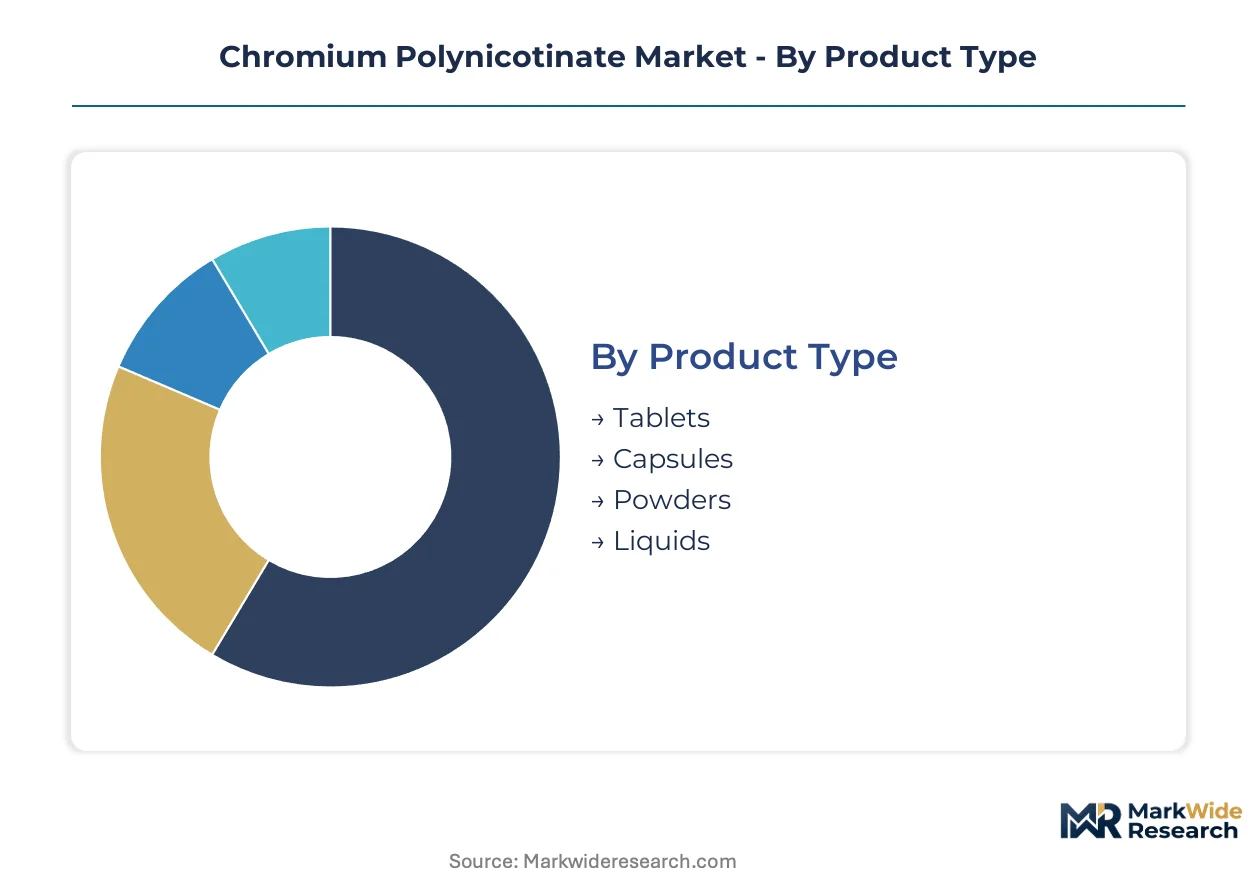
Chromium polynicotinate formulations diverge sharply across delivery formats and purity grades. Supply-side capabilities dictate which segments manufacturers can serve profitably.
Product Type:
Upstream spray-drying and fluid-bed granulation capacity concentrates among contract manufacturers in China and India, directly shaping finished dosage availability.
- Tablets:Compressed dosage forms containing 200–600 mcg elemental chromium with standardized disintegration profiles. United States metabolic health clinics drive pharmaceutical-grade tablet procurement through practitioner-exclusive networks.
- Capsules:Gelatin or vegetable-based shells encapsulating spray-dried chromium-niacin complexes. NOW Foods and Thorne Research dominate North American capsule supply through vertically integrated botanical extraction.
- Powders:Bulk compounding formats for personalized nutrition protocols. Direct-to-consumer subscription models in the United States bypass traditional retail channels.
- Liquids:Aqueous suspensions targeting pediatric and geriatric compliance segments. Limited domestic manufacturing due to stability testing burdens.
Tablets absorb the bulk of installed capacity; powders are expanding most quickly.
Application:
Cost tier stratification separates clinical-grade positioning from commodity bulk sales, with regulatory compliance costs widening the gap.
- Dietary Supplements:DSHEA-regulated products targeting glucose tolerance and lipid metabolism. FDA New Dietary Ingredient notifications create compliance moats for novel delivery formats.
- Functional Foods:FSSAI guidelines in India now permit chromium fortification in processed foods, opening channels previously restricted to supplements. Bakery and dairy applications lead adoption.
- Pharmaceuticals:CDSCO in India is clarifying mineral complex standards for potential Rx-adjacent metabolic syndrome positioning. Chromatographic purity requirements exceed supplement-grade specifications.
- Animal Nutrition:Livestock ketosis prevention protocols in dairy operations. Veterinary formulators pilot chromium polynicotinate as a margin pool outside human applications.
Dietary supplements command the deepest manufacturing investment; animal nutrition is gaining share fastest.
Distribution Channel:
Customer procurement patterns are displacing mass-market retail for high-purity grades, concentrating buyer power among integrated platforms.
- Online Retail:Direct-to-consumer platforms capture personalized nutrition and subscription compounding demand. Amazon and specialized nutraceutical portals dominate United States volume.
- Supermarkets:Mass-market shelf space for standard-grade tablets and capsules. Limited penetration of pharmaceutical-grade inventory due to margin compression.
- Health Stores:Practitioner-adjacent retail positioning for third-party certified products. GNC and Vitamin Shoppe carry Thorne Research and NOW Foods lines.
- Pharmacies:CDSCO-regulated channels in India and potential future Rx-adjacent positioning. Requires batch-specific certificates of analysis.
Online retail captures the steepest expansion trajectory; pharmacies retain the tightest supply qualifications.
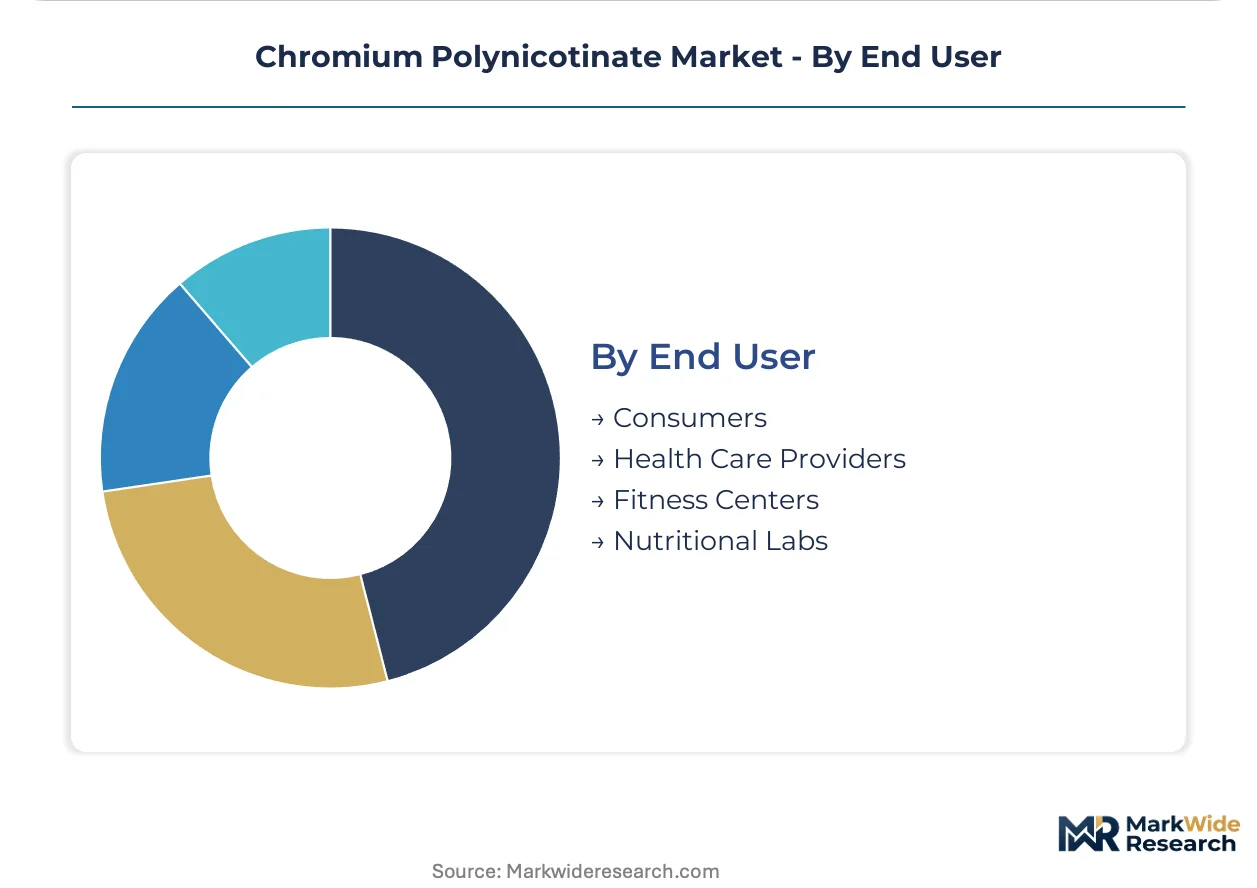
End User:
Volume concentration among metabolic health clinics is consolidating procurement power against fragmented raw material suppliers.
- Consumers:Self-directed purchasers through retail and online channels. Price sensitivity drives standard-grade tablet and capsule selection.
- Health Care Providers:Functional medicine networks standardizing chromium polynicotinate protocols for insulin resistance management. United States clinics negotiate direct manufacturer relationships.
- Fitness Centers:Sports nutrition dispensing for body composition and glucose management protocols. Pre-workout matrix integration drives microencapsulated format demand.
- Nutritional Labs:Compounding pharmacies and personalized nutrition formulators. Powder format procurement for custom dosing protocols.
Health care providers absorb the bulk of pharmaceutical-grade output; nutritional labs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors contract manufacturing capacity for chromium polynicotinate, with India's Deccan plateau hosting spray-drying facilities that supply North American supplement brands. Raw material refining clusters in Shandong Province and Gujarat State feed these operations.
United States
Metabolic health clinics in Arizona and California standardize chromium polynicotinate protocols for insulin resistance management. FDA's New Dietary Ingredient notification pathway creates compliance barriers for novel delivery formats. Utah's Wasatch Front concentrates vertically integrated botanical extraction operations serving practitioner-exclusive networks.
India
FSSAI mineral fortification guidelines expanded permissible chromium forms in processed foods, opening bakery and dairy channels. CDSCO is clarifying pharmaceutical-grade standards for potential Rx-adjacent metabolic syndrome positioning. Hyderabad and Ahmedabad host contract manufacturers with fluid-bed granulation capacity for export-grade complexes.
China
Synthetic niacin precursor supply chains in Shandong Province face crude oil price volatility that compresses formulator margins. MEE discharge standards for chromium waste elevate compliance costs versus Indian competitors. Zhejiang and Jiangsu provinces concentrate spray-drying equipment upgrades improving bioavailability metrics.
Germany
REACH authorization timelines for chromium compounds extend registration burdens for mineral complex suppliers. ECHA's evolving trivalent chromium classification forces reformulation reviews across legacy supplement lines. Bavaria's nutraceutical distributors divert volume to Middle Eastern markets with less restrictive chemical frameworks.
Canada
Health Canada regulates chromium polynicotinate under Natural Health Product regulations requiring site licenses and product approvals. Practitioner networks in Ontario and British Columbia pilot personalized nutrition compounding with direct-to-consumer powder formats. Vancouver's functional medicine platforms negotiate direct manufacturer relationships bypassing retail channels.
Chromium Polynicotinate Market Competitive Environment
Premium-margin players sit above commodity-margin players across purity certification and distribution exclusivity dimensions. The vendor base stratifies into three tiers: vertically integrated botanical extractors, third-party certified specialists, and contract manufacturing aggregators. Consolidation pressure concentrates among metabolic health clinic procurement networks. Dominant competitive moves include backward integration into niacin precursor supply and chromatographic standardization capability acquisition.
Within the vertically integrated tier, NOW Foods and Thorne Research exemplify upstream control strategies. Sabinsa Corporation anchors South Asian raw material sourcing archetypes. These three occupy positions that reflect divergent responses to FDA notification requirements and EPA discharge compliance costs.
| Leading Market Players |
|---|
| Sabinsa Corporation |
| NOW Foods |
| Thorne Research |
| Swanson Health Products |
| Solgar |
| Nature's Way |
| Pure Encapsulations |
| NutraBio Labs |
| Bio-Tech Pharmacal |
| Others |
Value Chain & Pricing Dynamics
Metabolic health clinic networks in the United States negotiate direct manufacturer relationships, compressing margins for non-integrated suppliers while rewarding chromatographic certification investments with premium positioning.
Pricing Analysis
Value-based pricing anchored to bioavailability outcomes dominates pharmaceutical-grade chromium polynicotinate procurement. Three-tier pricing structure across pharmaceutical-grade, supplement-grade, and feed-grade levels separates certified clinical protocols from commodity bulk sales. Pricing pressure stems from niacin precursor cost volatility tied to crude oil fluctuations, with Indian contract manufacturers capturing margin from integrated niacin supply. Standard-grade tablet buyers exhibit highest price sensitivity; metabolic health clinics demonstrate lowest sensitivity due to protocol standardization requirements.
Supply Chain Analysis
Chromatographic expertise shortages in Shandong Province and Gujarat State constrain batch release velocity for export-grade complexes. Raw material refining draws from Shandong synthetic niacin clusters, Gujarat mineral processing facilities, and Deccan plateau spray-drying operations. Single-source vulnerability concentrates in Shandong niacin precursor supply, with MEE discharge standards elevating domestic Chinese costs versus Indian competitors. Distribution runs through practitioner-exclusive networks for pharmaceutical grades, mass retail for standard supplements, and direct-to-consumer platforms for personalized nutrition compounding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's New Dietary Ingredient notification pathway erects a cost-of-compliance barrier that rewards incumbent players with established regulatory affairs infrastructure while filtering speculative entrants.
For Market Incumbents: Extend chromatographic standardization capabilities to capture metabolic health clinic procurement consolidation. Acquire fluid-bed granulation capacity in Hyderabad or Ahmedabad to secure export-grade complex supply. Brewer's yeast substitution threats in European natural products channels demand differentiated bioavailability positioning through microencapsulation investments. For New Entrants and Emerging Players: CDSCO pharmaceutical-grade pathway clarifications in India open a window for Rx-adjacent metabolic syndrome positioning ahead of competitor saturation. Target veterinary metabolic disorder protocols for dairy cow ketosis prevention as the most penetrable margin pool outside human supplements. Pursue direct-to-consumer powder format subscriptions through practitioner-led channels to bypass retail shelf access barriers. For Investors and Strategic Acquirers: The window for entry favors vertically integrated botanical extractors with captive niacin supply and in-house HPLC capability. Long-term viability hinges on backward integration into niacin precursor production and regulatory affairs scale. Watch FSSAI functional food fortification enforcement intensity as the signal for channel expansion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Niacin Precursor Supply | Captive niacin sourcing from Shandong or Gujarat refineries insulates margin from crude oil volatility. |
| Chromatographic Standardization Capability Acquisition | In-house HPLC batch release reduces dependence on third-party testing laboratories in Hyderabad clusters. |
| Veterinary Metabolic Disorder Protocol Development | Dairy cow ketosis prevention pilots with livestock nutritionists unlock margin pools outside human supplement saturation. |
| Microencapsulation Technology Deployment | Lipid-based coating systems protect gastric degradation for sports nutrition pre-workout matrix integration. |
| Practitioner-Exclusive Distribution Network Expansion | Direct manufacturer relationships with Arizona and California metabolic health clinics displace mass retail intermediation. |
Study Parameters
Trade databases, CDSCO regulatory filings, and FSSAI fortification guidelines formed the secondary backbone, cross-referenced with primary interviews involving contract manufacturing plant managers in Hyderabad, regulatory affairs leads at US supplement brands, metabolic health clinic procurement directors, and veterinary nutrition specialists. Bottom-up and top-down triangulation validated volume estimates across spray-drying capacity utilization and finished dosage export manifests.
Bottom-up modeling anchored forecasts to installed fluid-bed granulation capacity, niacin precursor supply elasticity, and metabolic health clinic protocol adoption rates across the projection horizon. Segmentation dimensions included delivery format, purity grade tier, application channel, and geographic regulatory cluster. CAGRs derived from capacity expansion announcements, clinic network growth trajectories, and substitution elasticity estimates for yeast-bound chromium alternatives.
The model assumes a particular technology adoption path; alternative pathways for microencapsulation cost reduction would alter the outlook for sports nutrition format penetration. Forecasts reflect assumptions regarding FSSAI enforcement consistency, EPA discharge standard stability, and niacin precursor supply continuity. Material deviation in hexavalent chromium contamination limits, REACH authorization timelines, or metabolic health clinic reimbursement patterns warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Gallic Acid Market
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Carbocernaite Market
Specialty Chemicals
UK Insect Repellent Market
Specialty Chemicals
Sodium Ascorbyl Phosphate (SAP) Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Global Curing Agents Market
Specialty Chemicals
Phenylbenzimidazole Sulfonic Acid Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
Multichannel Reagent Reservoir Market
Specialty Chemicals
Bio Polyol and Green Polyol Market
Specialty Chemicals
Eco-Friendly Plasticizers Market