
 Indonesia Construction Chemicals Market | 2026-2036
Indonesia Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Construction Chemicals Market Foresight
Residential high-rise development is expanding its share of construction chemical consumption as urban density rises across Indonesian megacities. PT FOSROC Indonesia leverages its technical service network to anchor specification decisions on major infrastructure bids. Sika AG competes through localized manufacturing and waterproofing system specialization. PT MBS Indonesia sustains its position via Master Builder Solutions' global formulation heritage adapted to tropical climate performance requirements.
Construction chemicals encompass admixtures, sealants, adhesives, and flooring compounds formulated to modify concrete properties, bond substrates, and protect structural elements against environmental degradation. These formulations typically incorporate polymers, surfactants, and specialty additives that enhance compressive strength, reduce permeability, or accelerate curing in humid tropical conditions. Admixtures command the largest volume share given their integration into nearly every concrete pour across residential and infrastructure applications. Flooring compounds represent the fastest-growing product category as commercial and industrial end-users prioritize abrasion-resistant, rapid-installation surface systems. Application segmentation shows infrastructure projects generating the most specification-intensive demand, while residential volume spreads across numerous mid-rise developments with thinner margin pools.
BIS equivalency through Indonesia's SNI standards, enforced by the National Standardization Agency, mandates compliance testing for imported and domestically produced construction chemicals before market distribution. The Ministry of Public Works and Housing issues technical specifications that directly shape admissible product categories for state-funded projects. Contractors and developers must monitor regulatory alignment between SNI revisions and project tender requirements to avoid specification disqualification on upcoming builds.
Market Dynamics
Indonesia's SNI mandatory certification standards are compressing product qualification timelines while simultaneously raising technical barriers for market entry, forcing both domestic producers and importers to restructure compliance workflows around BIS equivalency testing protocols.
Growth Catalysts
- Residential High-Rise Density:Urban verticalization across Greater Jakarta and Surabaya is concentrating concrete pour volumes into fewer, larger projects that maximize admixture specification efficiency.
- SNI Standards Tightening:The National Standardization Agency's expanded testing requirements for waterproofing membranes and structural adhesives is filtering out substandard imports and elevating average product performance baselines.
- Polymer-Modified Formulations:Acrylic and styrene-butadiene latex systems adapted to tropical humidity cycles are extending service life guarantees on infrastructure bids, anchoring specification decisions.
Market Restraints
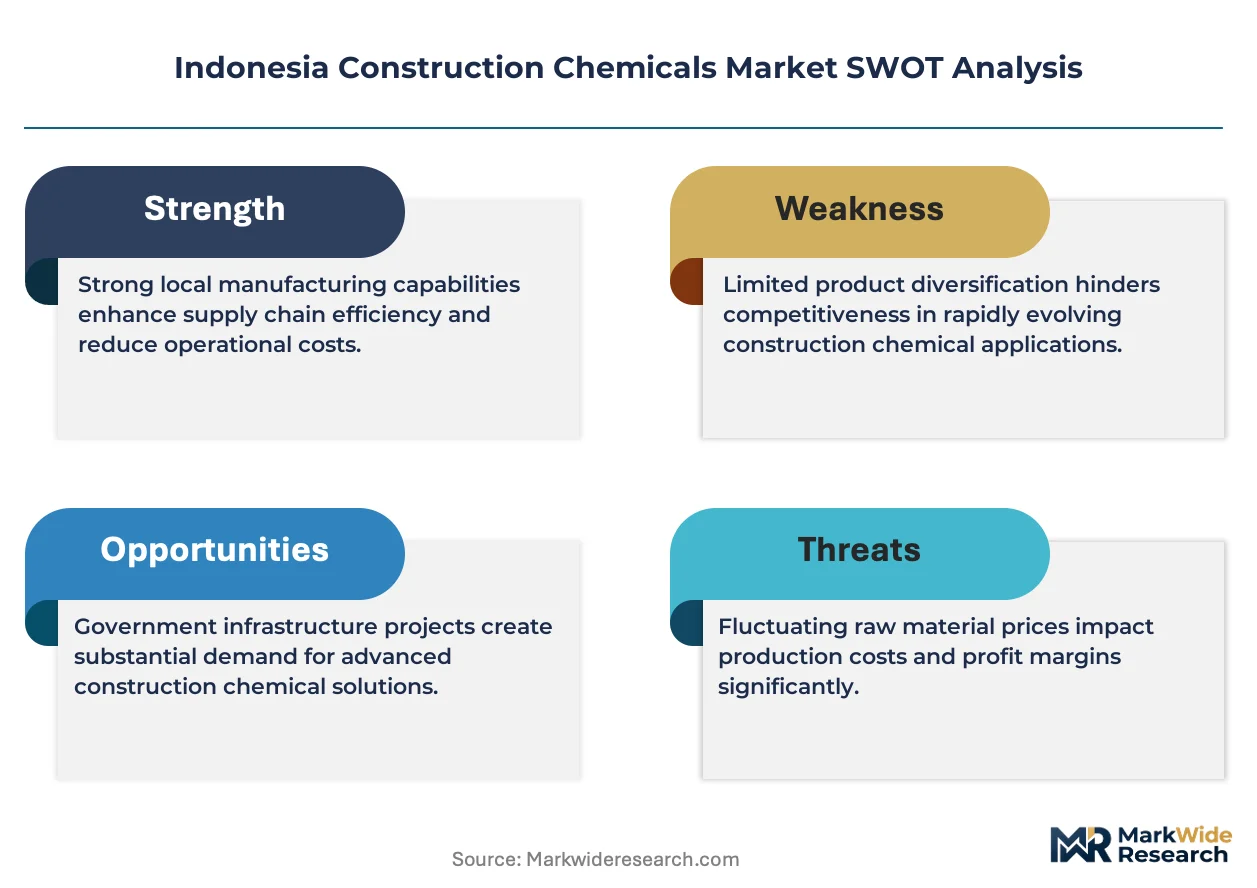
- Petrochemical Feedstock Volatility:Ethylene and propylene derivative costs for polymer binders fluctuate with regional refinery output, compressing formulation margins unpredictably.
- Import Dependency for Specialty Additives:High-performance superplasticizers and corrosion inhibitors concentrate supply among Southeast Asian chemical hubs, exposing buyers to shipping disruption risk.
- Substitution by Conventional Methods:Labor-intensive manual waterproofing with bituminous sheets persists in cost-sensitive residential segments, limiting chemical system penetration.
Strategic Opportunities
- Eastern Indonesia Expansion:Sulawesi and Papua infrastructure corridors remain underpenetrated relative to Java, offering first-mover positioning for contractors with localized technical service networks.
- Green Building Certification Alignment:Indonesia's nascent GREENSHIP rating system is creating specification pull for low-VOC sealants and recycled-content flooring compounds in premium commercial developments.
- Prefabrication Integration:Off-site concrete component manufacturing is unifying admixture dosing precision with just-in-time delivery, compressing waste and rework costs.
Industry Challenges
- Certification Timeline Compression:SNI laboratory queue backlogs extend product registration from six to fourteen months, delaying revenue recognition on new formulations.
- Technical Field Force Scarcity:Qualified application engineers who understand tropical concrete curing kinetics remain concentrated in Java, constraining specification support in outer islands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Construction Chemicals Market |
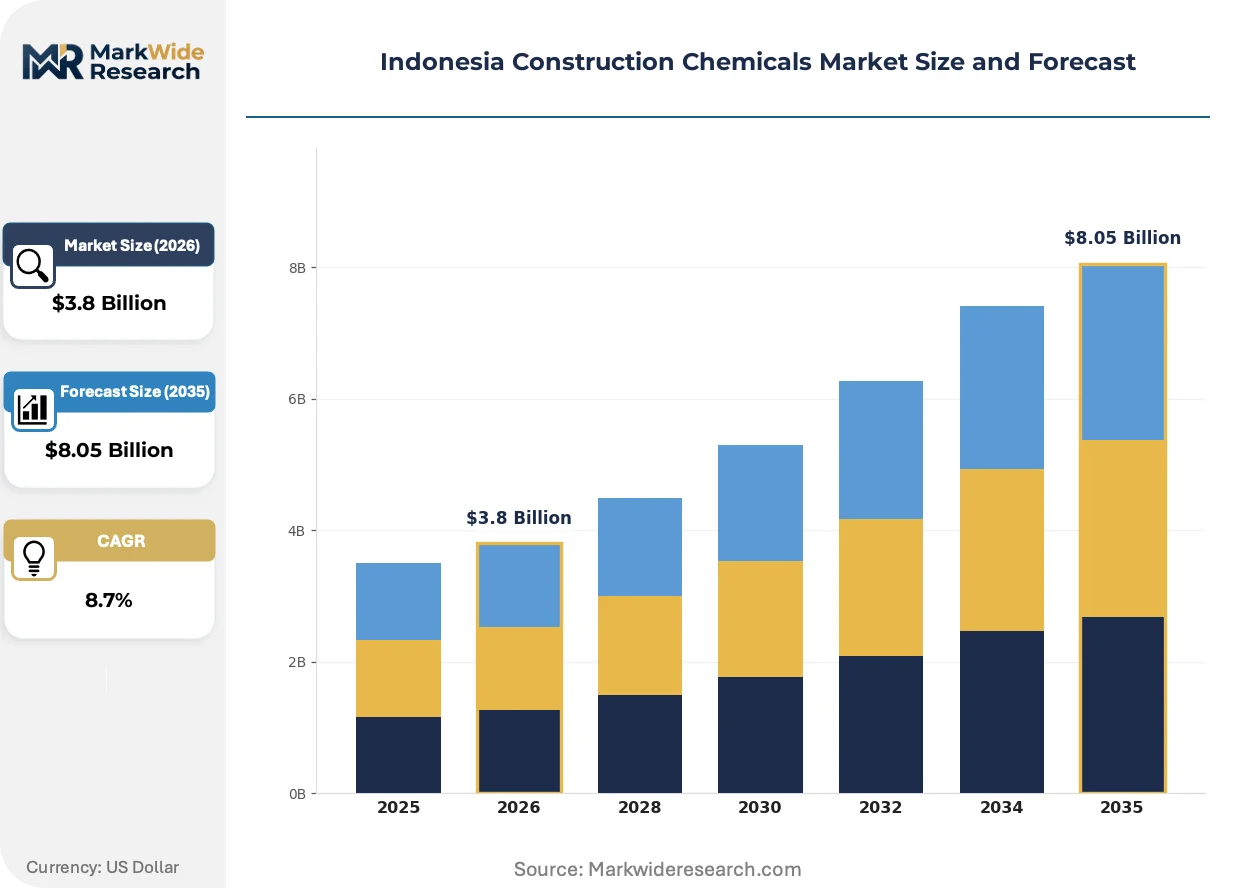
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Sealants, Adhesives, Flooring Compounds Application: Residential, Commercial, Infrastructure, Industrial End User: Contractors, Developers, Architects, Engineers Delivery Mode: Bulk, Pre-packaged, On-site Mixing, Online Services |
| Companies Covered | Saint-Gobain, PT FOSROC Indonesia, Sika AG, PT Dow Chemical Indonesia, PT Miranila Abadi (Ultrachem), MAPEI S.p.A., PT MBS (Master Builder Solutions) Indonesia, PT Propan Indonesia, Arkema (Bostik), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Construction Chemicals Market Shifts & Advancements
Formulation chemistry and compliance architecture are converging to reshape competitive positioning in Indonesia's construction chemicals sector. Three distinct vectors are compressing traditional supply relationships and elevating technical service intensity.
Hybrid polymer-cementitious systems is unifying waterproofing and structural bonding functions into single-application products. Major infrastructure contractors in the Trans-Java toll road expansion are specifying these dual-purpose formulations to compress construction schedules. The technology is unifying previously separate procurement categories, reducing supplier count per project and elevating technical support requirements.
Indonesia's Ministry of Public Works and Housing is tightening technical specifications for state-funded projects through revised SNI equivalency protocols. Imported construction chemicals now face extended laboratory validation before tender eligibility. Waterproofing membrane suppliers with existing BIS test reports are accelerating re-submission to maintain specification status on upcoming bids.
Buyer concentration among top-tier property developers is compressing supplier negotiation cycles and unbundling after-sales technical service from material pricing. Centralized procurement teams at Lippo Group and Agung Podomoro Land are negotiating multi-project framework agreements that lock in volume commitments against fixed pricing tiers. This pattern is most visible in Greater Jakarta's premium residential tower pipeline, where specification consistency across phased developments outweighs spot-market savings.
Indonesia Construction Chemicals Market Segmentation
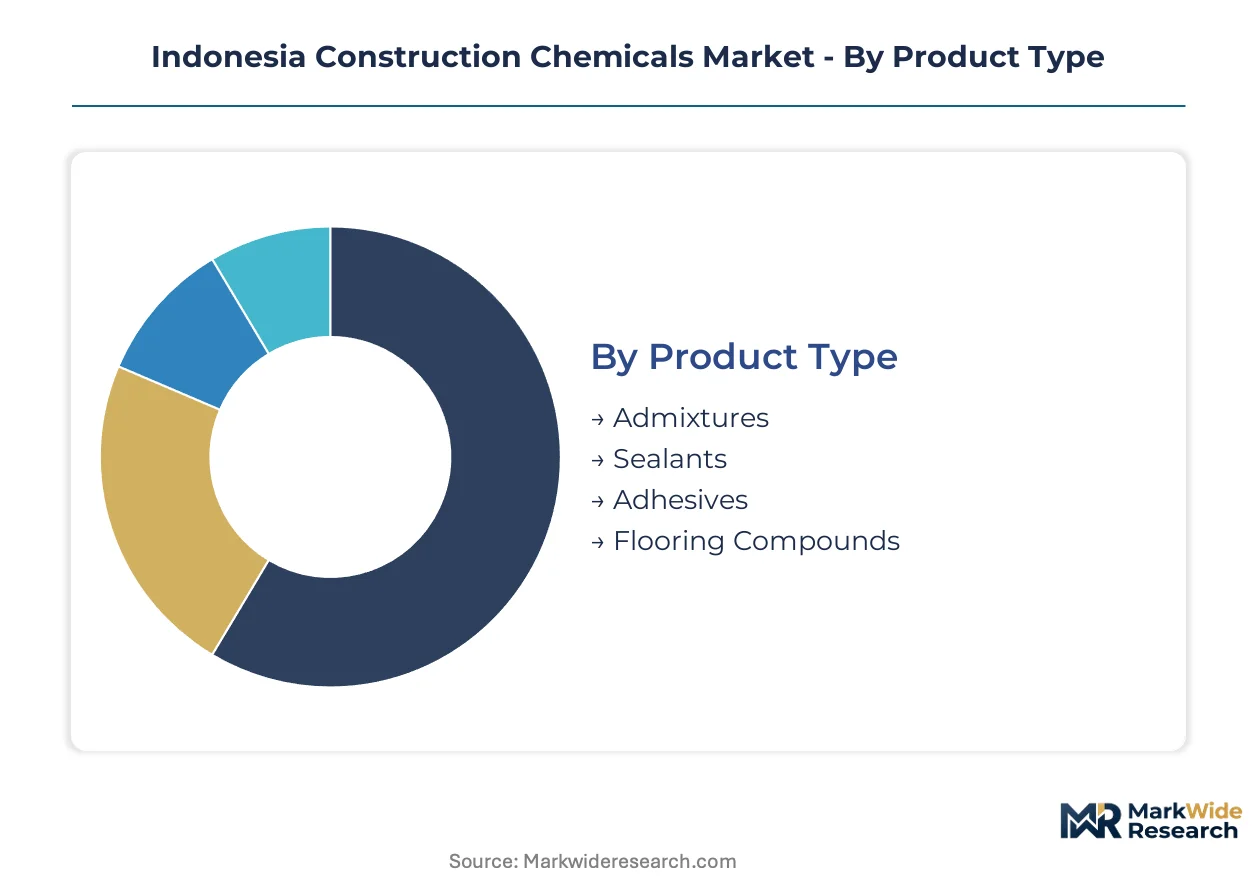
Segmentation in Indonesia's construction chemicals market reveals how specification power, procurement scale, and technical complexity concentrate differently across buyer types and delivery channels. Understanding these fault lines exposes where margin pools thicken and where volume commoditizes.
Product Type:
Buyers differentiate primarily by performance guarantee requirements and integration depth into concrete chemistry rather than surface application alone.
- Admixtures:Polymer-modified and superplasticizer formulations modify hydration kinetics and compressive strength in tropical humidity. Demand concentrates in Greater Jakarta's high-rise residential towers where concrete pour volumes per project justify bulk dosing systems and on-site technical support.
- Flooring Compounds:Self-leveling epoxy and polyurethane systems deliver abrasion-resistant surfaces with rapid return-to-service. Commercial developments in Surabaya and Bandung specify these for retail and logistics facilities where downtime costs exceed material premiums.
- Sealants:Silicone and polyurethane joint sealants accommodate structural movement in seismic zones. Infrastructure contractors specify movement-capable grades for bridge expansion joints.
- Adhesives:Tile adhesives and structural bonding agents anchor cladding and precast elements. Residential mid-rise developments in secondary Java cities drive volume through standardized mortar replacement.
Volume sits with Admixtures; growth tilts toward Flooring Compounds.
Application:
Project scale and specification intensity create divergent procurement patterns across construction verticals.
- Infrastructure:State-funded toll roads, ports, and dams demand SNI-certified waterproofing and structural repair systems with decade-plus service guarantees. The Ministry of Public Works and Housing mandates pre-qualification testing that filters supplier pools.
- Residential:Vertical high-rise construction concentrates admixture demand into fewer, larger pours. Developer consolidation in Greater Jakarta enables framework pricing agreements across phased tower developments.
- Commercial:Office and retail projects prioritize rapid-installation flooring and aesthetic finishes. GREENSHIP certification requirements in premium developments pull low-VOC sealant specifications.
- Industrial:Manufacturing facilities and warehouses specify chemical-resistant coatings and heavy-duty flooring. Sulawesi's nickel processing corridors generate emerging demand for corrosion protection systems.
Infrastructure commands specification premiums; Residential delivers volume scale.
End User:
Technical knowledge depth and procurement authority separate stakeholders who influence product selection from those who execute purchase orders.
- Contractors:Execute material procurement against tender specifications. Large infrastructure contractors in Java maintain preferred supplier relationships with technical service capabilities.
- Developers:Centralized procurement teams at major property groups negotiate multi-project framework agreements. Specification consistency across portfolios outweighs spot-market savings.
- Architects:Shape early-stage material selection through performance specifications. Green building consultants increasingly influence low-VOC and recycled-content requirements.
- Engineers:Structural and geotechnical specialists mandate admixture dosages and waterproofing membrane grades. Their calculations determine compliance margins on state-funded bids.
Contractors control purchase volume; Developers and Engineers split specification influence.
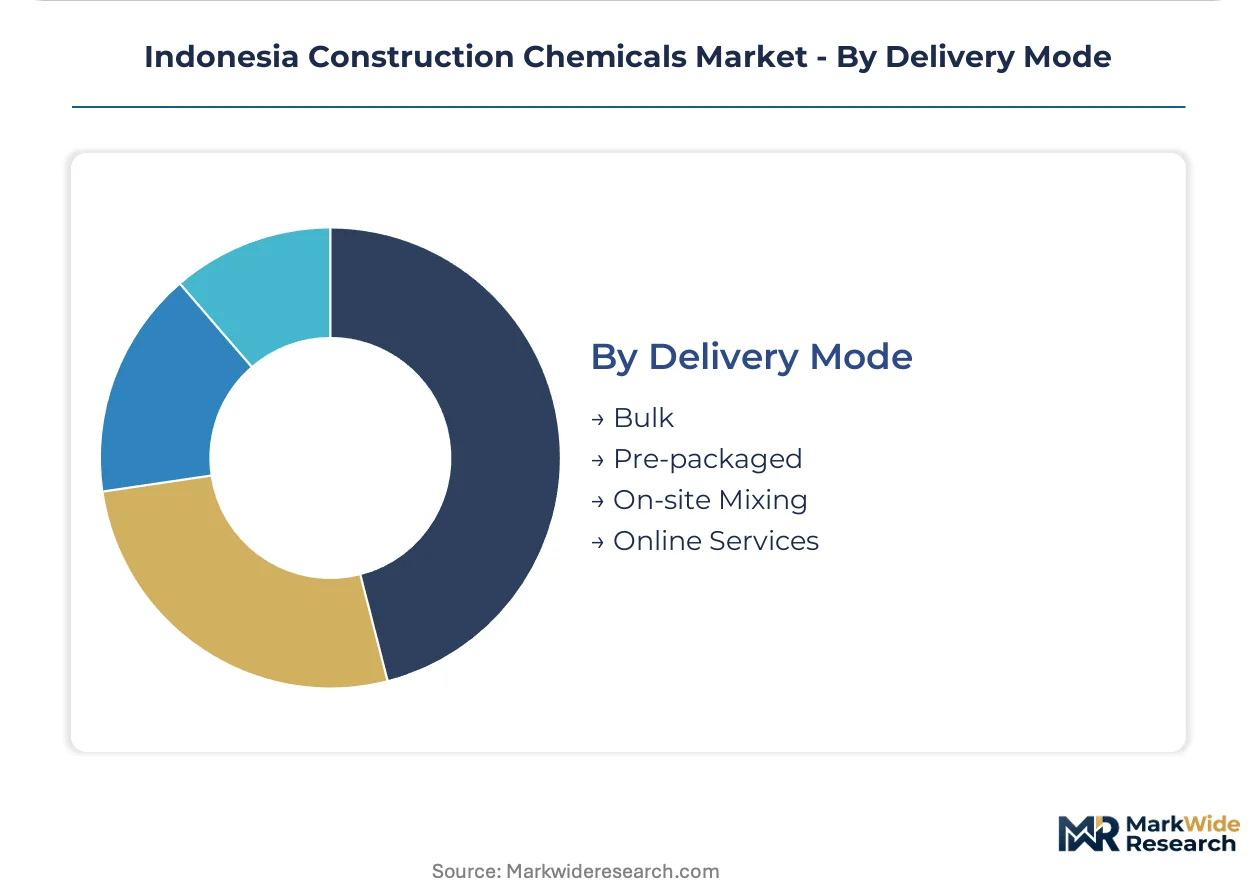
Delivery Mode:
Logistics configuration and inventory risk allocation determine channel economics for different product categories.
- Bulk:Tanker-delivered liquid admixtures serve high-volume concrete plants in Greater Jakarta and Surabaya. Just-in-time dosing integration with batching systems minimizes waste and labor.
- Pre-packaged:Bagged tile adhesives, repair mortars, and sealants stock hardware distribution networks. Provincial contractors in Eastern Indonesia rely on this channel given sporadic demand patterns.
- On-site Mixing:Mobile blending units produce custom formulations for remote infrastructure sites. Papua and Sulawesi projects use this mode to bypass shipping constraints on finished goods.
- Online Services:Digital platforms aggregate small-order fulfillment for residential renovation contractors. Penetration remains limited to Java's urban centers with reliable logistics infrastructure.
Bulk dominates admixture economics; Pre-packaged extends reach to fragmented demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Batam Free Trade Zone and SEZ incentives concentrate chemical manufacturing investment near Singapore logistics corridors. Java maintains construction chemical demand dominance through Greater Jakarta's vertical residential pipeline. Eastern Indonesia infrastructure corridors remain underpenetrated relative to western industrial clusters.
Java
Greater Jakarta's high-rise residential towers concentrate admixture consumption into bulk-dosed concrete pours exceeding 50,000 cubic meters per project. The Ministry of Public Works and Housing mandates SNI certification for all waterproofing systems on state-funded toll road segments. Surabaya and Bandung industrial zones anchor manufacturing capacity for polymer-modified formulations serving central and east Java construction corridors.
Sumatra
Palm oil processing facilities and rubber plantation infrastructure generate corrosion protection demand for industrial flooring and chemical-resistant coatings. The Batam Free Trade Zone offers 10-year tax holidays for construction chemical manufacturers establishing formulation plants. Medan's logistics hub serves Aceh reconstruction projects and Malacca Strait port developments with pre-packaged repair mortar distribution.
Sulawesi
Nickel processing corridors in Morowali and Konawe drive emerging demand for acid-resistant flooring and structural protection systems. Indonesia's national infrastructure acceleration program prioritizes Central Sulawesi road and bridge construction with enhanced SNI compliance requirements. Makassar functions as the primary distribution node for construction chemicals reaching Papua and eastern archipelago projects.
Kalimantan
New capital city construction in East Kalimantan generates specification-intensive demand for structural adhesives and seismic-grade sealants. The Ibu Kota Nusantara Authority mandates GREENSHIP-aligned material selection for government building contracts. Balikpapan and Samarinda industrial clusters support mining-related construction with mobile on-site mixing capabilities for remote site delivery.
Papua
LNG facility expansions and trans-Papua highway segments require specialized waterproofing for high-rainfall tropical conditions. Indonesia's special autonomy infrastructure funds channel through Jayapura and Sorong procurement offices with extended SNI testing timelines. On-site mixing delivery modes dominate given shipping constraints across archipelago logistics chains.
Indonesia Construction Chemicals Market Competitive Landscape
Top-tier vendors anchor specification-intensive infrastructure bids, while mid-scale formulators compete on price-sensitive residential volume. The market structure concentrates around multinational technical service networks, localized manufacturing subsidiaries, and regional distribution specialists. Three archetypes dominate: polymer chemistry innovators with tropical formulation heritage, construction-focused conglomerates leveraging project finance relationships, and chemical traders with SNI certification navigation expertise. Competitive moves center on backward integration into petrochemical feedstocks and technical field force expansion into outer island corridors.
Within the multinational technical service tier, Sika AG, PT FOSROC Indonesia, and PT MBS Indonesia exemplify positioning anchored by specification influence on major infrastructure projects. These entities occupy positions defined by BIS equivalency testing capabilities and on-site application engineering presence. PT Dow Chemical Indonesia represents the petrochemical-backed archetype with captive polymer supply chains. Regional specialists including PT Propan Indonesia and PT Miranila Abadi sit within distribution-intensive segments where SNI compliance navigation and provincial logistics relationships determine market access.
| Leading Market Players |
|---|
| Saint-Gobain |
| PT FOSROC Indonesia |
| Sika AG |
| PT Dow Chemical Indonesia |
| PT Miranila Abadi (Ultrachem) |
| MAPEI S.p.A. |
| PT MBS (Master Builder Solutions) Indonesia |
| PT Propan Indonesia |
| Arkema (Bostik) |
| Others |
Supply & Pricing Matrix
GREENSHIP certification alignment gates both qualified supply and premium-tier pricing access in Indonesia's construction chemicals sector, as developers pursuing the rating system must source low-VOC sealants and recycled-content flooring from pre-approved supplier pools. This sustainability mandate compresses the qualified vendor base while elevating price premiums for certified formulations, particularly in Jakarta's premium commercial tower pipeline where specification consistency outweighs spot-market savings.
Pricing Analysis
Short lead-time premiums dominate pricing differentiation in Indonesia's construction chemicals market, with contractors paying material surcharges for expedited SNI-certified admixture delivery to active pour sites. Pricing stratifies across SNI-certified premium tiers, standard compliance grades, and economy imports lacking technical support, with certification level and volume scale as the primary differentiation drivers. Cost compression in economy-tier tile adhesives is intensifying because of substitution by conventional bituminous waterproofing methods in cost-sensitive residential segments. Provincial contractors in Eastern Indonesia exhibit highest price sensitivity due to fragmented demand and pre-packaged delivery premiums, while infrastructure contractors in Java prioritize performance guarantees over unit economics.
Supply Chain Analysis
Domestic-content mandates under Indonesia's Ministry of Industry regulations are reshaping sourcing patterns, requiring localized blending operations for state-funded project eligibility. Supply concentrates in Singapore, Malaysia, and Thailand for polymer-modified formulations, with specialty superplasticizers and corrosion inhibitors drawing from Southeast Asian chemical hubs. Raw material dependencies rest on ethylene and propylene derivatives, naphtha-based solvents, and tropical-grade latex emulsions. Single-source vulnerability concentrates in high-performance admixture additives where regional production is limited. Distribution runs through bulk tanker networks serving Greater Jakarta concrete plants, pre-packaged hardware channels reaching provincial contractors, and mobile on-site mixing units for remote infrastructure corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's construction chemicals sector is navigating a technology-transition phase as hybrid polymer-cementitious systems displace separate waterproofing and structural bonding procurement categories, compressing supplier counts per project while elevating technical service intensity.
For Market Incumbents: Acquire technical field force capabilities in outer island corridors to defend specification influence against emerging regional specialists. SNI certification backlog compression and qualified application engineer scarcity in Sulawesi and Papua present consolidation opportunities through targeted hiring or regional firm acquisition. Backward integration into captive polymer supply chains mitigates petrochemical feedstock volatility threatening formulation margins.
For New Entrants and Emerging Players: Prefabrication integration capabilities offer a technology-first wedge into Indonesia's construction chemicals value chain, as off-site concrete component manufacturers seek unified admixture dosing precision with just-in-time delivery partnerships. Eastern Indonesia infrastructure corridors remain the most penetrable geography, with nickel processing facilities in Morowali and Konawe generating unmet demand for acid-resistant flooring systems. A go-to-market angle anchored by mobile on-site mixing services bypasses established bulk distribution networks concentrated in Java.
For Investors and Strategic Acquirers: GREENSHIP certification acceleration among top-tier property developers is the leading indicator that premium-tier formulation capabilities will command sustained pricing power over the medium-term horizon. Acquisition targets should prioritize regional specialists with SNI compliance navigation expertise and established provincial logistics relationships in underpenetrated corridors. Watch for inflection signals in Ministry of Public Works and Housing tender specifications mandating extended SNI laboratory validation timelines, which will filter import-dependent suppliers and elevate domestic blending asset values.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstocks | Captive ethylene derivative supply secures formulation margins against regional refinery output fluctuations. |
| Technical Field Force Expansion | Qualified application engineers in Sulawesi and Papua anchor specification decisions on infrastructure bids. |
| SNI Certification Pre-Investment | Early BIS equivalency testing submission compresses product registration timelines before tender eligibility windows. |
| Prefabrication Partnership Development | Off-site concrete manufacturer alliances unify admixture dosing precision with just-in-time delivery integration. |
| GREENSHIP-Aligned Formulation Portfolio | Low-VOC sealant and recycled-content flooring compounds access premium commercial development procurement. |
Research Methodology
Trade statistics from Indonesia's Ministry of Industry, BIS equivalency testing records from the National Standardization Agency, and customs import data for construction chemical feedstocks formed the secondary backbone of this analysis. Primary interviews with concrete batching plant managers, waterproofing contractor procurement leads, technical R&D directors at formulation subsidiaries, and distribution channel partners in Java and Eastern Indonesia validated demand patterns and pricing dynamics. Bottom-up and top-down triangulation reconciled project-level admixture consumption estimates with national construction output data.
Bottom-up volume modeling segmented demand across admixtures, flooring compounds, sealants, and adhesives, with further disaggregation by SNI certification tier, end-use application intensity, and regional production hub proximity. CAGRs were derived from trend extrapolation of concrete pour volumes in Greater Jakarta's high-rise residential pipeline and infrastructure acceleration program allocations. Industry-specific forecast inputs incorporated polymer-modified formulation adoption curves and GREENSHIP certification penetration rates in premium commercial developments.
Several conditions sit outside the modeled scope, including abrupt SNI standard revisions, petrochemical feedstock supply disruptions from regional refinery outages, and currency volatility effects on imported specialty additive costs. Forecasts reflect assumptions about continued infrastructure program funding continuity and stable regulatory enforcement timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Pulp and Paper Enzymes Market
Industrial Chemicals
Commercial Electronic Detonator Market
Industrial Chemicals
2-Ethylhexanol (2-EH) Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
Tetrafluoroethane (R134A) Refrigerant Market
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
Non-PVC Waterstop Market
Industrial Chemicals
Dipropylene Glycol (DPG) Market
Industrial Chemicals
Metalworking Treating Fluid Market
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
Surface Treatment Chemicals Market
Industrial Chemicals
Decahydronaphthalene (Decalin) Market
Industrial Chemicals
Perchloroethylene Market
Industrial Chemicals
Batch Reactors Market