
 Spout Pouch Market | 2026-2036
Spout Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Spout Pouch Market Intelligence
Contract filling and co-packing services is broadening what converters sell, shifting revenue from empty pouches to filled-and-finished retail units. Amcor plc leverages its integrated film extrusion and converting footprint to anchor large beverage contracts across multiple continents. ProAmpac specializes in high-barrier structures for retort applications, sustaining technical differentiation against commodity suppliers. Mondi plc competes through paper-based spout pouch development, positioning its portfolio for fiber-focused regulatory thresholds.
A spout pouch is a flexible primary package integrating a welded or injection-molded dispensing fitment, typically constructed from laminated films or extruded co-polymers with sealant layers rated between 80°C and 135°C depending on pasteurization or retort requirements; it serves to contain, protect, and dispense liquid, semi-viscous, or powdered products while minimizing headspace and enabling single-handed use. Stand-up pouch configurations now carry the dominant share of value owing to shelf presence and pallet density advantages in retail distribution. Compostable materials represent the fastest-growing material category as brand owners respond to EPR legislation and consumer-facing sustainability scorecards, though plastic laminates still occupy the majority volume position due to cost and barrier performance.
FDA food contact regulations in the United States, REACH chemical compliance in Europe, and EFSA migration limits collectively dictate adhesive, ink, and substrate selections that determine which converters qualify for multinational brand supply. The EU Green Deal and emerging state-level packaging EPR laws in California and New York are forcing reformulation timelines that favor mono-material or fiber-containing structures over legacy multi-ply constructions. Stakeholders must monitor how rapidly retail chains enforce on-pack recycling labeling requirements, as this will determine which spout pouch constructions retain shelf access and which face delisting.
Market Dynamics
EU Green Deal mandates are forcing converters to abandon multi-material laminates and revalidate entire production lines around mono-polymer or fiber-based alternatives, compressing margins while opening first-mover advantages for certified sustainable suppliers.
Growth Catalysts
- Retort-ready mono-material structures:Food processors in Germany and France now specify single-polymer spout pouches capable of withstanding 121°C sterilization cycles, eliminating separation complexity at municipal recycling facilities.
- California's SB 54 EPR implementation:Brand owners face 2032 deadlines for 100% recyclable or compostable packaging, accelerating purchase commitments for validated paper-film hybrid spout pouch constructions.
- Contract filling service expansion:Beverage and sauce brands outsource filled-unit procurement to co-packers, extending converter revenue streams from empty pouches to shelf-ready retail inventory.
Market Restraints
- Ethylene-vinyl alcohol copolymer supply concentration:High-barrier EVOH resin production clusters in Japan and Belgium, exposing pouch converters to input cost volatility and force majeure allocation risk.
- Multi-layer adhesive incompatibility:Solvent-based polyurethane laminating adhesives fail REACH migration limits for fatty food contact, forcing costly reformulation to water-based or UV-cured alternatives with inferior line speeds.
- Stand-up rigid bottle substitution:HDPE and PET bottles retain cost advantages for volumes above 500ml in mass-market beverage applications, capping spout pouch penetration in family-size formats.
Strategic Opportunities
- Pharmaceutical liquid dosing applications:Oral suspension and enteral nutrition brands in Switzerland and the Netherlands are piloting child-resistant spout pouches as compliance aids for pediatric and geriatric patients.
- India's PLI scheme for packaging machinery:Domestic equipment subsidies enable local converters to install precision spout insertion lines, reducing dependence on Italian and German machinery imports.
- Digital printing convergence with short-run converting:HP Indigo and EFI-equipped lines enable batch-size-one production for regional craft food brands, collapsing minimum order quantities from 50,000 to 5,000 units.
Industry Challenges
- Migration testing laboratory capacity:EFSA and FDA dual-notification requirements for novel adhesive-substrate combinations create 14-18 month certification queues, delaying product launches.
- Spout-weld integrity at speed:Rotary form-fill-seal lines running above 200 pouches per minute generate heat-seal variability that requires statistical process control investments most mid-cap converters have deferred.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spout Pouch Market |
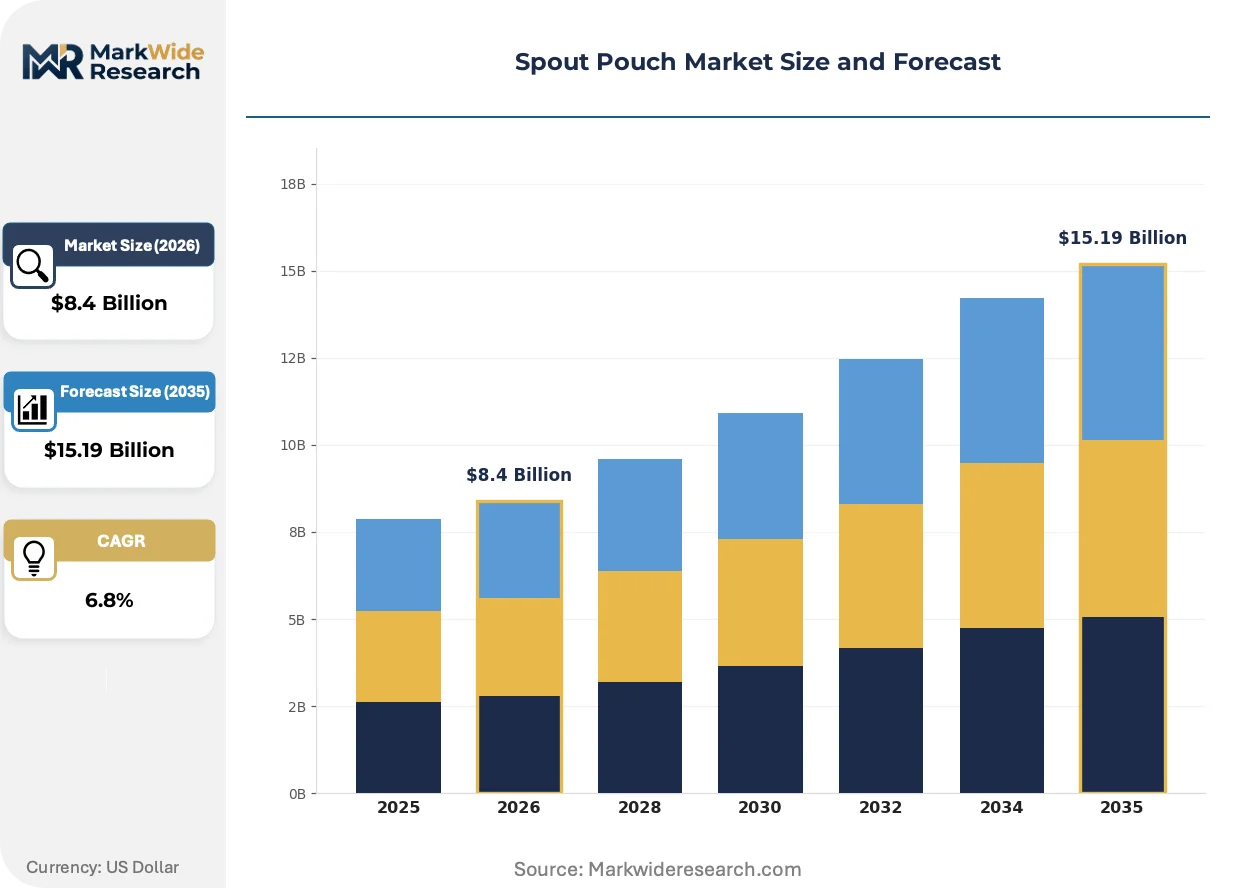
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouch, Stand-Up Pouch, Side Gusset Pouch, Retort Pouch Material: Plastic, Metalized Film, Paper, Compostable Materials Application: Food & Beverage, Personal Care, Household Products, Industrial Goods Closure System: Zip Lock, Screw Cap, Press-to-Close, Other |
| Companies Covered | Amcor plc, ProAmpac, Sonoco Products Company, Mondi plc, Berry Global, Smurfit Kappa, Sealed Air Corporation, AptarGroup, Glenroy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spout Pouch Market Strategic Shifts & Innovations
Digital manufacturing workflows and material science advances are collapsing the traditional trade-off between barrier performance and end-of-life recyclability, enabling constructions that satisfy both food safety and circular economy protocols.
Mono-material polyethylene spout pouches with plasma-enhanced barrier coatings are decentralizing the technical advantage historically held by multi-layer nylon-EVOH constructions. Baby food and organic sauce brands in Scandinavia have adopted these structures at commercial scale since 2023. The shift is decentralizing supply chain power from specialized high-barrier film suppliers toward commodity resin producers with coating capabilities.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling converters to eliminate fluorinated grease barriers from paper-based spout pouches. Industrial consequence includes accelerated R&D spending on bio-wax and clay-based oil resistance alternatives. Dry soup and nut butter applications in Germany and Austria are most affected, with reformulated constructions entering validation with EFSA.
Direct-to-retail e-commerce fulfillment is compressing traditional distributor leverage over pouch specification decisions. Amazon and specialized grocery delivery platforms in the United Kingdom now mandate drop-test certification and shelf-ready case packing that favors stand-up spout formats over bag-in-box alternatives. This pattern is most visible in premium pet food and adult nutrition verticals, where unboxing experience drives repeat purchase metrics.
Spout Pouch Market Segmentation
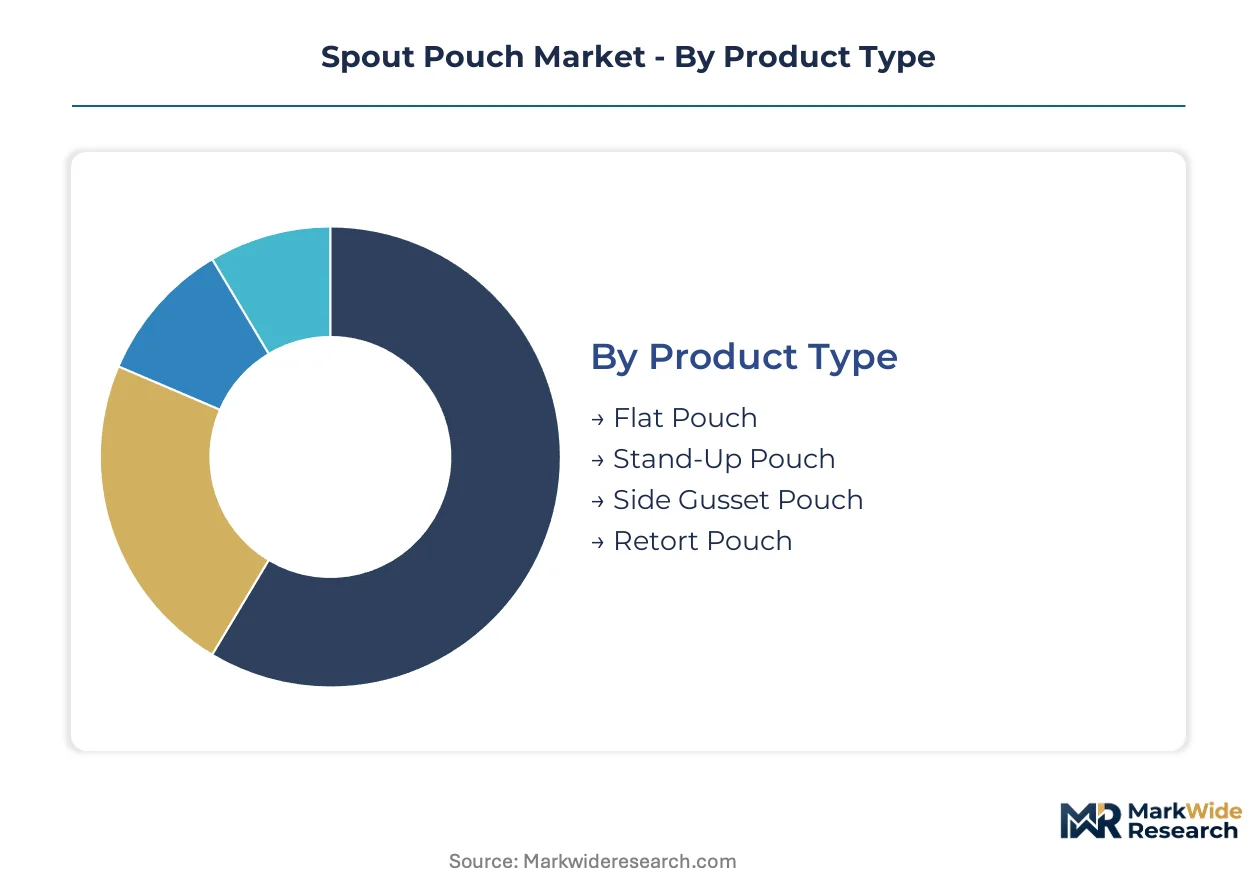
Spout pouch specification decisions cascade through material selection, thermal processing requirements, and retail channel constraints. Each segmentation dimension carries distinct margin profiles and regulatory compliance burdens that determine converter qualification for multinational brand supply.
Product Type:
Retail shelf presence and distribution economics drive format selection, with pallet density and vertical merchandising requirements separating premium from commodity applications.
- Stand-Up Pouch:Self-supporting bottom gusset construction maximizes billboard area for brand communication and enables vertical retail display. German private-label food processors and cosmetic houses have standardized this format across premium and mass-market lines, consolidating procurement around 250ml to 1L capacity ranges.
- Retort Pouch:Multi-layer laminate structures withstand 121°C sterilization cycles for ambient shelf-stable proteins and ready meals. French and German food processors now specify single-polymer variants to satisfy EU Green Deal recycling mandates, forcing converter line revalidation investments.
- Flat Pouch:Two-dimensional construction suits sampler packs and single-serve condiments where shipping cube efficiency outweighs shelf presence requirements.
- Side Gusset Pouch:Expanded volume capacity serves bulk dry goods and institutional food service applications with lower per-unit packaging cost targets.
Stand-Up Pouch leads on scale; Retort Pouch leads on momentum.
Material:
End-of-life regulations are compressing the historical dominance of multi-layer constructions, with compliance timelines determining which substrates retain shelf access.
- Plastic:Polyethylene and polypropylene laminates deliver cost efficiency and heat-seal reliability across high-speed form-fill-seal lines. California's SB 54 EPR implementation and EU Green Deal mandates are forcing rapid reformulation toward mono-material or certified recyclable variants.
- Compostable Materials:PLA and cellulose-based structures respond to EPR legislation and consumer-facing sustainability scorecards. Scandinavian baby food and organic sauce brands adopted these at commercial scale, though industrial composting infrastructure gaps limit geographic deployment.
- Paper:Fiber-based substrates with bio-wax or clay-based grease barriers serve dry soup and nut butter applications in Germany and Austria, with EFSA validation timelines constraining rollout speed.
- Metalized Film:Aluminum oxide or metallized PET layers provide oxygen and moisture barriers for oxygen-sensitive products, though multi-material construction complicates recycling certification.
Plastic dominates current volume; Compostable Materials are expanding most quickly.
Application:
Product viscosity, pH, and thermal processing requirements dictate barrier specifications and closure system integration complexity.
- Food & Beverage:Sauces, baby food, and ready-to-drink beverages drive specification innovation, with retort requirements and clean-label positioning forcing material science advances. Contract filling services are extending converter revenue from empty pouches to shelf-ready retail units.
- Personal Care:Shampoo, conditioner, and liquid soap applications prioritize dispensing precision and shelf differentiation, with mono-material PE constructions gaining share against rigid bottle alternatives.
- Household Products:Concentrated detergents and cleaning solutions demand chemical resistance and child-resistant closure compatibility, with HDPE bottles retaining cost advantages above 500ml.
- Industrial Goods:Lubricants, adhesives, and agricultural chemicals require specialized barrier films and UN-certified transport packaging, with lower volume scale and higher regulatory documentation burdens.
Food & Beverage leads on scale; Personal Care leads on momentum.
Closure System:
Dispensing precision, reseal reliability, and line integration speed determine converter equipment investments and brand owner qualification timelines.
- Screw Cap:Injection-molded PP or HDPE fitments with tamper-evident rings serve beverages and liquid foods requiring controlled flow rates. Rotary form-fill-seal lines running above 200 pouches per minute generate heat-seal variability that demands statistical process control systems.
- Press-to-Close:Integrated silicone or TPE valves enable single-handed dispensing for on-the-go consumption, with premium pet food and adult nutrition brands in the United Kingdom mandating drop-test certification for e-commerce fulfillment.
- Zip Lock:Interlocking plastic profiles suit dry goods and multi-serve applications where repeated access is valued over dispensing precision.
- Other:Spout-less tear-notch designs and specialty fitments for pharmaceutical liquid dosing in Switzerland and the Netherlands serve niche compliance and geriatric patient requirements.
Screw Cap leads on scale; Press-to-Close leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters are relocating production to jurisdictions where REACH compliance costs and EPR fee structures create arbitrage opportunities, with Germany and France absorbing premium-tier volumes while India captures machinery-driven cost advantages.
Germany
Private-label food processors and cosmetic houses in North Rhine-Westphalia have standardized stand-up spout pouch formats across premium and mass-market lines. EU Green Deal mandates compel converters in the Bergisch Gladbach cluster to phase out multi-material laminates and validate mono-polymer alternatives by 2030. The Düsseldorf-Ruhr industrial corridor hosts retort-ready production lines serving French and Benelux export markets.
France
Ready-meal brands in the Île-de-France region specify single-polymer spout pouches capable of withstanding 121°C sterilization cycles. EFSA migration limits for fatty food contact force adhesive reformulation to water-based alternatives with reduced line speeds. The Lyon-Saint-Étienne chemical corridor concentrates barrier coating R&D for paper-based constructions targeting dry soup applications.
United States
Beverage co-packers in California face SB 54 EPR deadlines requiring 100% recyclable or compostable packaging by 2032, accelerating purchase commitments for validated paper-film hybrid constructions. FDA food contact regulations dictate adhesive and substrate selections that determine converter qualification for multinational brand supply. The Chicago-Milwaukee corridor anchors contract filling services extending revenue streams from empty pouches to shelf-ready retail inventory.
India
Domestic converters in Gujarat and Maharashtra leverage PLI scheme subsidies to install precision spout insertion lines, reducing dependence on Italian and German machinery imports. FSSAI packaging safety standards govern ink and substrate selections for food contact applications. The Ahmedabad-Surat industrial belt concentrates form-fill-seal equipment manufacturing serving Southeast Asian export markets.
Switzerland
Pharmaceutical liquid dosing brands in Basel and Zurich pilot child-resistant spout pouches as compliance aids for pediatric and geriatric patients. Swissmedic medical device regulations govern fitment integrity and tamper-evidence standards. The Basel pharmaceutical cluster drives specification innovation for oral suspension and enteral nutrition applications with UN-certified transport packaging requirements.
Spout Pouch Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated film extruders commanding beverage volumes while regional converters capture short-run craft food orders. The vendor base organizes around three archetypes: multinational integrated packaging groups with captive resin supply, mid-cap specialists in high-barrier retort structures, and machinery-forward regional players in emerging markets. Dominant competitive moves include backward integration into film extrusion to secure resin allocation during supply shocks, and geographic expansion through toll manufacturing partnerships to bypass import tariff exposure.
Among integrated packaging groups, Amcor plc and Mondi plc exemplify contrasting strategic postures toward sustainability mandates. Amcor anchors large beverage contracts across multiple continents through its integrated film extrusion and converting footprint. Mondi occupies a position within the fiber-focused tier, competing through paper-based spout pouch development aligned with EU Green Deal regulatory thresholds. ProAmpac represents the high-barrier specialist archetype, sustaining technical differentiation in retort applications against commodity suppliers through proprietary laminate structures.
| Leading Market Players |
|---|
| Amcor plc |
| ProAmpac |
| Sonoco Products Company |
| Mondi plc |
| Berry Global |
| Smurfit Kappa |
| Sealed Air Corporation |
| AptarGroup |
| Glenroy Inc. |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between mono-material and multi-layer laminate constructions splits both pricing power and procurement patterns across the spout pouch value chain. Premium-tier converters in Germany command material premiums validated against EU Green Deal thresholds, while commodity suppliers in India compete on machinery-driven unit economics.
Pricing Analysis
Distributor margin layers compress as beverage brands consolidate procurement through direct co-packer relationships. Three-tier pricing structure across premium, standard, and economy levels tracks EFSA validation status and retort-cycle capability. Cost compression in standard-grade laminates intensifies because REACH-compliant adhesive reformulation extends production cycles. Mid-cap converters exhibit highest price sensitivity; multinational food processors with annual volume commitments of 50 million units or more negotiate most aggressively.
Supply Chain Analysis
Dual-sourcing requirements for EVOH resin compel converters to qualify suppliers in both Japan and Belgium simultaneously. High-barrier film production draws from ethylene-vinyl alcohol copolymer, polyethylene terephthalate, and bio-based PLA feedstocks. Single-source vulnerability concentrates in specialized retort-grade adhesive chemistries. Distribution runs through regional converting hubs serving private-label processors and contract filling networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in spout pouches rests on the shift toward validated mono-material structures that command certification premiums while reducing compliance-driven reformulation costs.
For Market Incumbents: Acquire plasma-enhanced barrier coating capabilities to defend technical differentiation against commodity polyethylene suppliers. Backward integration into film extrusion secures resin allocation during force majeure events. Capacity addition in the Bergisch Gladbach cluster addresses French and Benelux export demand for retort-ready mono-polymer lines. For New Entrants and Emerging Players: Regional craft food brands represent the most penetrable buyer segment given collapsing minimum order quantities enabled by digital printing convergence. Short-run converting lines equipped with HP Indigo or EFI technology access batch-size-one production previously reserved for multinational suppliers. Direct-to-retail e-commerce fulfillment mandates from Amazon and UK grocery delivery platforms create specification entry points. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing validated mono-material retort structures and established EFSA notification queues. Long-term viability favors converters with dual capability across plastic laminates and paper-based constructions. Watch EPR enforcement timelines in California and New York as inflection indicators for shelf-access delisting risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive resin supply insulates Amcor and Mondi from EVOH allocation shocks during force majeure events. |
| Mono-Material Retort Validation | ProAmpac's single-polymer 121°C structures unlock EU Green Deal compliance premiums in German ready-meal supply. |
| Paper-Based Pouch Development | Mondi's fiber-focused R&D positions for REACH Annex XVII fluorinated barrier phase-out in dry soup applications. |
| Contract Filling Service Expansion | Co-packer relationships extend converter revenue from empty pouches to shelf-ready retail inventory for beverage brands. |
| Digital Printing Line Investment | HP Indigo-equipped regional converters collapse minimum order quantities from 50,000 to 5,000 units for craft food brands. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured converter operations directors, brand owner packaging procurement leads, EFSA regulatory affairs specialists, and contract filling service managers. Secondary validation drew from EU Green Deal implementation documents, REACH Annex XVII restriction timelines, FDA food contact substance notifications, and FSSAI packaging safety standards. Bottom-up capacity modeling triangulated against top-down brand owner procurement survey data.
Comparable-period anchoring linked projection assumptions to historical validation queue durations and machinery installation cycles across the analysis window. Segmentation dimensions spanned product type, material substrate, thermal processing requirement, closure system complexity, and regional regulatory cluster. CAGRs derived from unit volume trajectories calibrated to EPR implementation deadlines and retail chain sustainability scorecard adoption curves. Forecast inputs incorporated adhesive-substrate migration testing laboratory capacity constraints and rotary form-fill-seal line speed thresholds.
Revisions become necessary when EFSA dual-notification queues extend beyond 18 months or when California SB 54 enforcement accelerates ahead of 2032 deadlines. Deviation in retail chain on-pack recycling labeling requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Indonesia Pouch Packaging Market
Pouch
Liquid Pouch Packing Machine Market
Pouch
Automatic Pre-Made Pouch Packaging Machine Market
Pouch
Russia Pouch Packaging Market
Pouch
High-Barrier Pouches Market
Pouch
Colombia Pouch Packaging Market
Pouch
Kraft Paper Pouch Market
Pouch
Retort Pouch Market
Pouch
Wrap-Around Packers Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Canada Pouch Packaging Market
Pouch
Four Side-Sealed Pouches Market
Pouch
Aluminum Foil Zipper Pouch Market
Pouch
Pre-Made Pouch Packaging Market
Pouch
United States Pouch Packaging Market
Pouch
Child Resistant Single Dose Pouches Market