
 Aluminum Foil Zipper Pouch Market | 2026-2036
Aluminum Foil Zipper Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Foil Zipper Pouch Market Outlook
Specialty food brands is collapsing the historical dominance of bulk industrial buyers in aluminum foil zipper pouch procurement. Amcor leverages its integrated film-to-pouch manufacturing network across North American and European plants. Mondi Group anchors its position through kraft-paper hybrid structures that reduce plastic dependency in retail-facing formats. ProAmpac differentiates via retort-capable zipper technologies serving ready-meal processors seeking shelf-stable convenience.
Aluminum foil zipper pouches are multi-layer flexible containers combining metallized or bare aluminum foil substrates with polyethylene, polyester, or polyamide films, heat-sealed to form oxygen and moisture barriers with integrated reclosure mechanisms; they preserve product integrity across temperature fluctuations while enabling repeated access without contamination. Stand-up pouches dominate retail shelf presence due to superior billboard space and pallet efficiency, while retort pouches represent the fastest-expanding category as pet food and prepared meal producers adopt autoclave-compatible barrier formats. Flat pouches maintain stable volume in pharmaceutical blister alternatives and sample sachets where dimensional constraints override display requirements.
The FDA regulates direct food-contact aluminum substrates under 21 CFR 177.1390, while the EU F-Gas Regulation and REACH framework govern fluoropolymer barrier coatings used in high-performance retort structures; compliance with these standards shapes material selection and cross-border market access for converters. China's SAMR enforces GB standards for composite packaging migration limits, adding testing burdens for exporters serving Asian pharmaceutical clients. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to invest in mono-material recyclable zipper structures or defend current multi-layer performance advantages through chemical recycling partnerships.
Market Dynamics
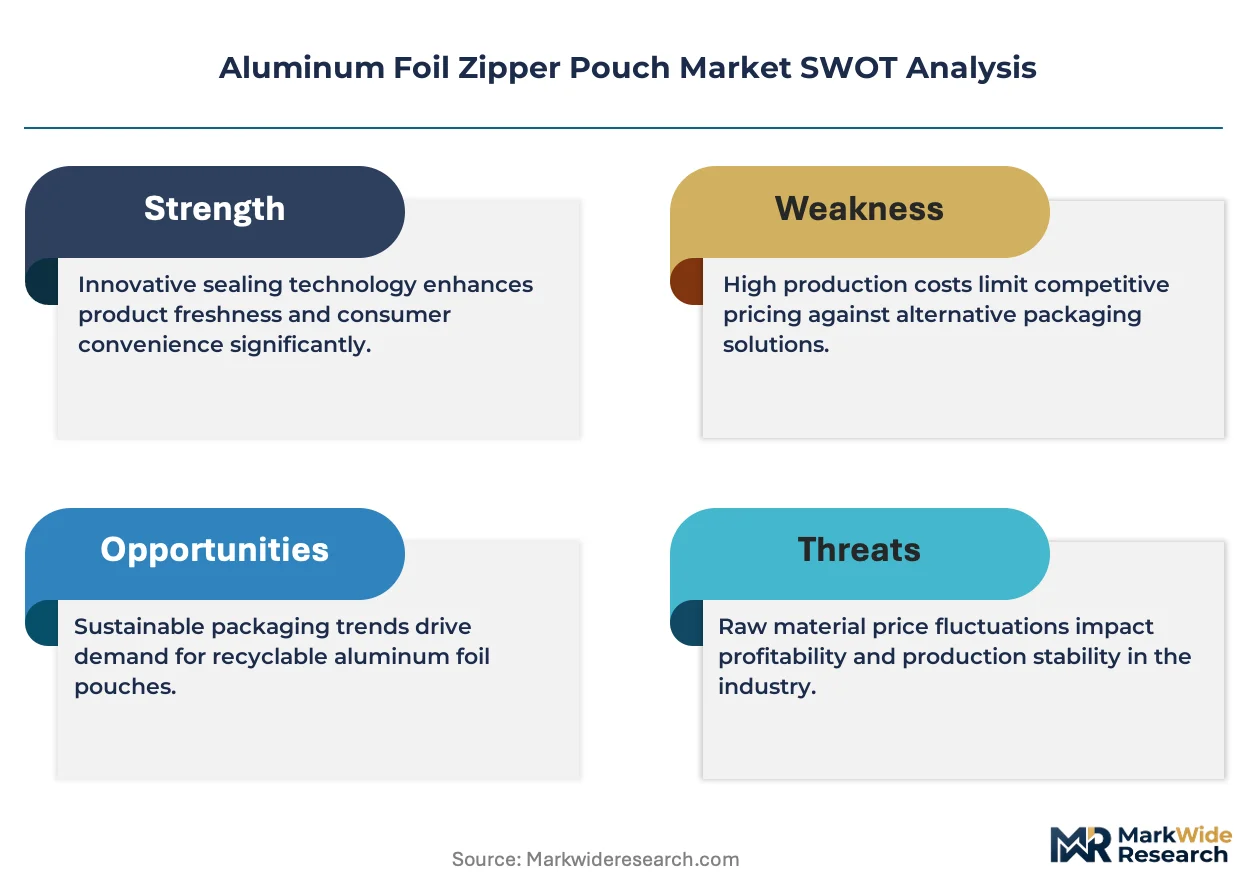
The EU Packaging and Packaging Waste Regulation is forcing aluminum foil zipper pouch converters to reengineer multi-layer structures for material recovery compliance, collapsing legacy design assumptions while specialty food brands accelerate format migration.
Growth Catalysts
- Retort-compatible barrier technology:Autoclave-stable zipper mechanisms enable pet food and ready-meal processors to shift from rigid cans to flexible formats without shelf-life sacrifice.
- Extended producer responsibility schemes:Germany's packaging ordinance mandates higher recycling quotas for flexible packaging, driving investment in mono-material zipper prototypes with aluminum foil alternatives.
- Specialty coffee roasting:Small-batch roasters in Scandinavia and the Pacific Northwest are standardizing degassing-valve zipper pouches to preserve aromatic compounds during direct-to-consumer shipping.
Market Restraints
- Aluminum ingot price volatility:Primary aluminum smelter curtailments in Sichuan and Yunnan provinces create input cost instability for metallized film laminators.
- Multi-layer incompatibility with mechanical recycling:Current polyethylene-aluminum-polyamide structures fail European sorting facility detection systems, limiting circular economy claims.
- Fluoropolymer coating restrictions:The EU F-Gas Regulation phases down perfluorinated barrier coatings used in high-performance retort pouches, forcing reformulation.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:Temperature-indicating zipper pouches with phase-change material integration address biologics distribution in India and Southeast Asia.
- Paper-based hybrid structures:Kraft-aluminum laminates reduce plastic mass fraction to meet French supermarket plastic reduction mandates ahead of 2025 deadlines.
- Chemical recycling partnerships:Pyrolysis-based depolymerization of mixed flexible waste streams enables converters to defend multi-layer performance advantages while satisfying EPR obligations.
Industry Challenges
- Migration testing complexity:China's SAMR enforces GB 31604 composite packaging standards requiring 18-month validation timelines for new aluminum substrate suppliers.
- Legacy filling equipment retrofit costs:Vertical form-fill-seal lines designed for three-side-seal pouches demand $2-4 million capital outlays to accommodate zipper applicator modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Foil Zipper Pouch Market |
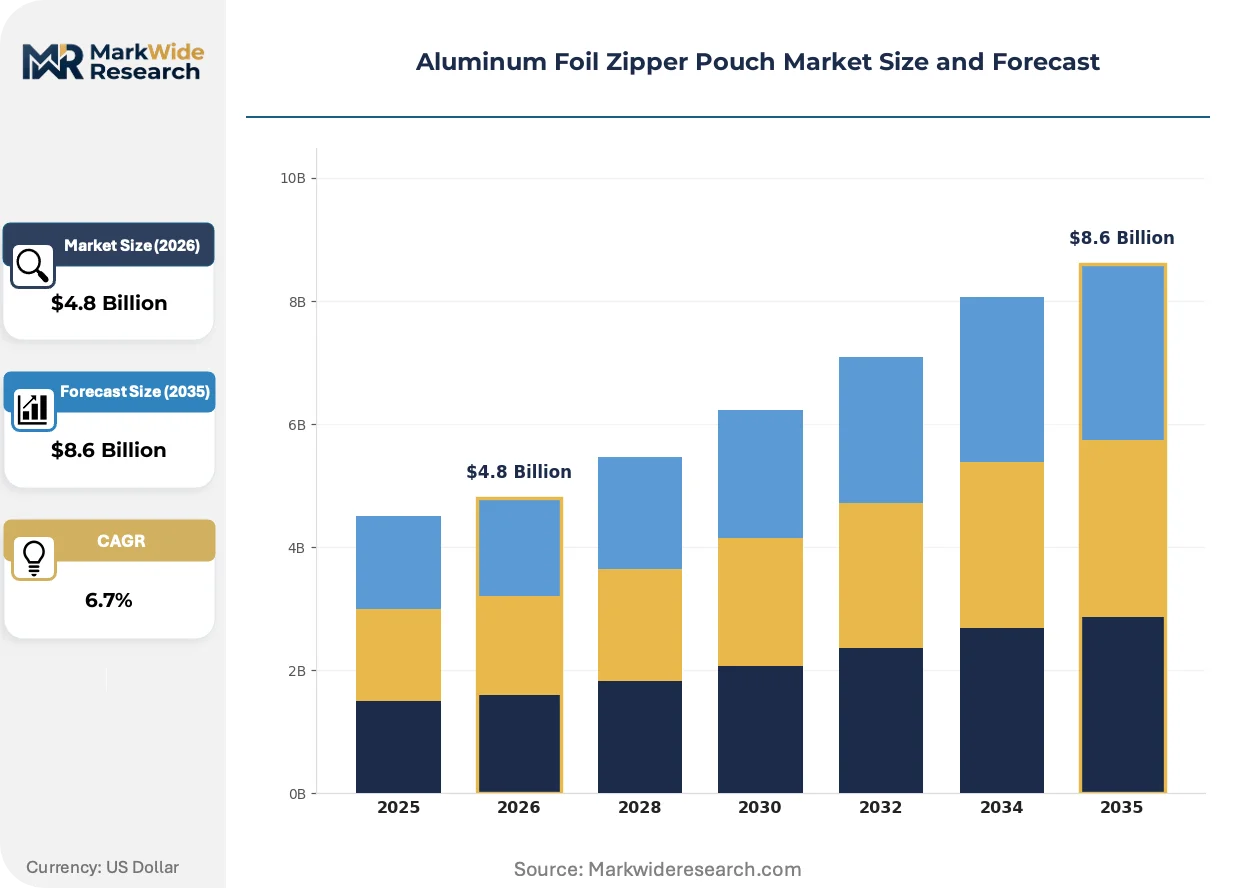
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Gusset Pouches, Retort Pouches Application: Food Packaging, Pharmaceutical Packaging, Cosmetic Packaging, Industrial Packaging Closure Type: Zip Closure, Slider Closure, Press-to-Seal Closure, Tear Notch Closure End User: Retailers, Manufacturers, Distributors, Wholesalers |
| Companies Covered | Amcor, Mondi Group, Sealed Air, Huhtamaki, ProAmpac, Sonoco, Berry Global, Constantia Flexibles, Winpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Foil Zipper Pouch Market Strategic Shifts
Material science breakthroughs and regulatory compression are converging to redefine aluminum foil zipper pouch architecture, with sustainability performance now inseparable from barrier functionality in buyer specifications.
Water-based barrier coatings are supplanting solvent-based laminating adhesives and extrusion-coated polyethylene in mid-performance pouch applications. European snack brands adopting these systems achieve volatile organic compound reduction without oxygen transmission rate penalties. The shift is compressing converter margins as equipment amortization cycles shorten.
REACH authorization requirements for bisphenol-A derivatives in food-contact coatings are eliminating legacy epoxy-based interior linings from aluminum foil zipper pouch specifications. German and Dutch converters are accelerating migration to polyester-based alternatives. High-acid sauce and prepared meal segments face the steepest compliance timelines.
Direct-to-consumer subscription fulfillment is consolidating buyer power among specialty food brands that specify custom pouch dimensions and print runs below traditional minimum order quantities. This fragmentation is compressing converter batch economics and favoring digital printing hybrid lines. Pacific Northwest coffee roasters and Nordic freeze-dried meal startups represent the vanguard of this specification shift.
Aluminum Foil Zipper Pouch Market Segmentation
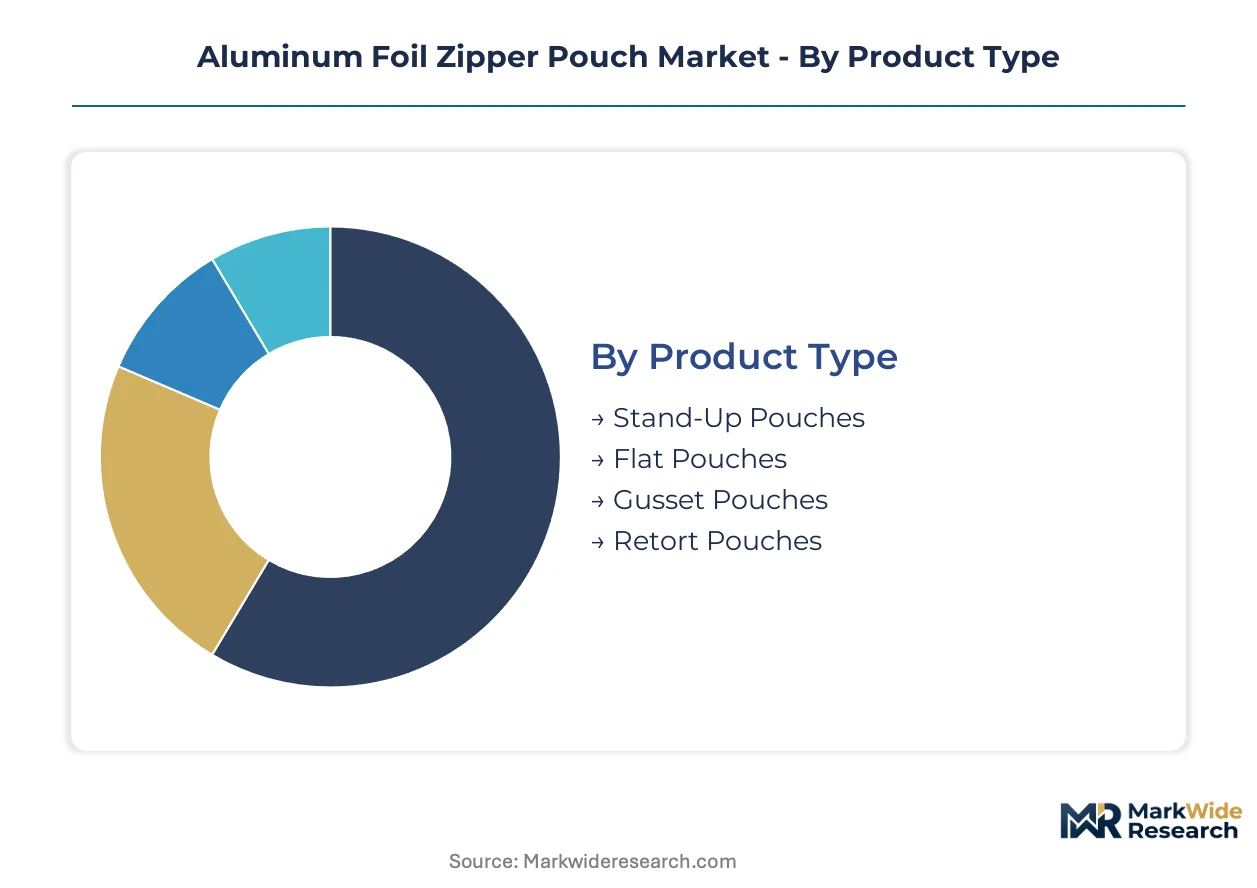
Segmentation in aluminum foil zipper pouches reveals how format choices cascade through channel economics and regulatory exposure. Buyers optimize across barrier performance, filling-line compatibility, and end-of-life compliance obligations.
Product Type:
Channel mix varies sharply by pouch geometry, with retail-facing formats demanding shelf presence and industrial formats prioritizing pallet density and shipping cube efficiency.
- Stand-Up Pouches:These structures incorporate bottom gussets that enable vertical display, combining aluminum foil barriers with polyethylene or polyamide outer layers. German and Scandinavian specialty food brands specify these for coffee and premium snacks where billboard space drives trial. Shelf-stable convenience and direct-to-consumer shipping compatibility concentrate demand in small-batch roasting and freeze-dried meal segments.
- Retort Pouches:Autoclave-stable multi-layer laminates withstand 121°C sterilization cycles while maintaining seal integrity through integrated zipper mechanisms. Pet food processors in the Pacific Northwest and ready-meal manufacturers in Germany are migrating from rigid cans to these formats. The shift collapses shipping weight and enables microwave-in-bag consumption without shelf-life sacrifice.
- Flat Pouches:Two-dimensional seals without dimensional expansion suit pharmaceutical blister alternatives and sample sachets where display requirements are secondary to material efficiency and migration testing compliance.
- Gusset Pouches:Side-folded expansions increase volumetric capacity for bulk industrial ingredients and agricultural chemicals where pallet stability overrides retail presentation needs.
By volume, stand-up pouches lead. By growth pace, retort pouches are expanding most quickly.
Application:
Cost tier separation is pronounced, with food applications absorbing commodity-grade laminates and pharmaceutical buyers paying premiums for batch-traceable barrier validation.
- Food Packaging:Oxygen transmission rates below 0.1 cc/m²/day preserve lipid oxidation-sensitive products across temperature fluctuations. Specialty coffee roasters in the Pacific Northwest and premium snack brands in Germany specify degassing-valve configurations for aromatic compound retention.
- Pharmaceutical Packaging:US FDA 21 CFR 177.1390 compliance for direct food-contact aluminum substrates combines with EU REACH authorization constraints on interior coatings. Cold-chain biologics distribution in India and Southeast Asia drives demand for temperature-indicating zipper integrations.
- Cosmetic Packaging:Mid-tier barrier specifications serve sample sachets and travel-format prestige products where moisture protection competes with unboxing aesthetics.
- Industrial Packaging:Basic polyethylene-aluminum laminates protect chemical powders and electronic components from humidity ingress during extended storage.
Food packaging commands the largest volume share. Pharmaceutical packaging carries the steepest margin expansion trajectory.
Closure Type:
Volume concentration sits with legacy zipper formats, while premium segments experiment with slider and press-to-seal mechanisms that reduce consumer failure rates.
- Zip Closure:Interlocking polyethylene or polypropylene tracks formed during extrusion lamination provide repeated reclosure at lowest unit cost. Standard across coffee, snacks, and prepared meals where consumer familiarity reduces instruction burden.
- Slider Closure:Integrated plastic runners enable one-handed operation, penetrating premium pet food and senior-targeted nutrition formats where dexterity constraints matter.
- Press-to-Seal Closure:Adhesive-based interlayers suit single-use pharmaceutical sachets and sample formats where reclosure frequency is minimal.
- Tear Notch Closure:Perforated initiation points without reclosure capability serve unit-dose pharmaceuticals and promotional samples where access speed outweighs preservation needs.
Zip closures dominate unit economics. Slider closures are gaining share fastest in premium tier migration.
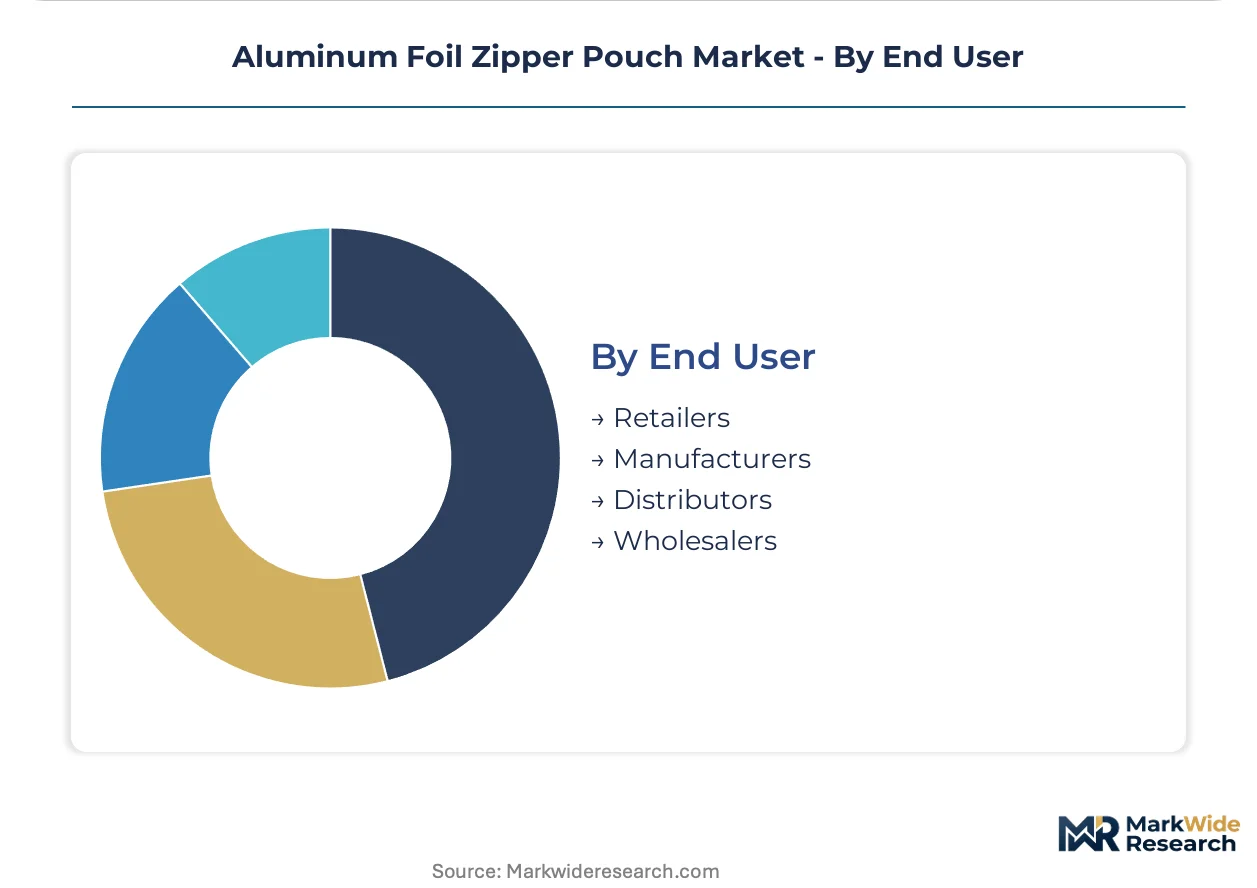
End User:
Customer type determines specification authority, with manufacturers controlling material selection and retailers dictating format dimensions through private-label programs.
- Manufacturers:Brand-owning processors specify custom laminate structures and commission filling-line retrofits for zipper applicator integration. Capital outlays of $2-4 million for vertical form-fill-seal modifications concentrate procurement authority at this tier.
- Retailers:Supermarket chains and specialty grocers impose private-label pouch specifications, with French plastic reduction mandates ahead of 2025 deadlines driving kraft-aluminum hybrid adoption.
- Distributors:Logistics intermediaries influence secondary packaging configurations for pallet efficiency and cross-dock handling compatibility.
- Wholesalers:Volume aggregators prioritize standard dimensions that minimize inventory fragmentation across multiple brand portfolios.
Manufacturers lead specification volume. Retailers are accelerating format innovation through sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty food brands and pharmaceutical cold-chain distributors concentrate procurement authority across distinct national clusters, with regulatory pressure on multi-layer recyclability reshaping converter investment priorities in each market.
Germany
Pet food processors and ready-meal manufacturers in Lower Saxony and Bavaria are retrofitting production lines for retort-capable zipper formats. The national packaging ordinance mandates escalating recycling quotas for flexible packaging, forcing converters to prototype mono-material alternatives. Hamburg anchors chemical recycling pilot programs targeting mixed aluminum-polyethylene waste streams from industrial laminators.
United States
Pacific Northwest coffee roasters and direct-to-consumer snack subscription services standardize degassing-valve zipper specifications for aromatic compound preservation. FDA 21 CFR 177.1390 compliance requirements for direct food-contact aluminum substrates shape material selection protocols. Chicago and New Jersey corridor converters serve pharmaceutical cold-chain distributors integrating temperature-indicating zipper technologies for biologics transport.
China
Primary aluminum smelter curtailments in Sichuan and Yunnan provinces generate input cost volatility for metallized film laminators serving domestic snack brands. SAMR enforces GB 31604 composite packaging migration limits requiring extended validation timelines for new substrate suppliers. Shanghai and Guangdong industrial zones concentrate pouch converter capacity targeting export pharmaceutical clients.
India
Cold-chain biologics distributors in Maharashtra and Karnataka are adopting phase-change material-integrated zipper pouches for temperature-sensitive pharmaceutical distribution. CDSCO alignment with international pharmaceutical packaging standards elevates barrier validation requirements. Mumbai-Pune industrial corridor converters specialize in mid-tier barrier specifications for generic drug exporters.
France
Supermarket plastic reduction mandates ahead of 2025 deadlines accelerate kraft-aluminum hybrid pouch adoption among private-label food brands. ANSM oversight of pharmaceutical packaging materials adds compliance layers for converters serving dual-use food-pharma facilities. Lyon and Paris basin industrial zones concentrate paper-based hybrid structure development for retail-facing formats.
Aluminum Foil Zipper Pouch Market Competitive Environment
Player mix skews toward integrated multinational converters with captive film extrusion capabilities, though mid-tier regional specialists retain share in pharmaceutical validation-intensive segments. Three strategic archetypes dominate: vertically integrated packaging conglomerates with global plant networks, paper-hybrid specialists leveraging fiber-based sustainability positioning, and retort-technology-focused engineering houses serving autoclave-stable format migration. Competitive dynamics center on chemical recycling partnership formation and digital printing hybrid line installation to capture fragmented specialty brand volumes.
Among integrated packaging conglomerates, Amcor and Mondi Group exemplify contrasting strategic anchors. Amcor represents the film-to-pouch manufacturing network archetype spanning North American and European production assets. Mondi Group occupies a position within the fiber-based hybrid structure segment, reducing plastic mass fraction through kraft-aluminum laminates. ProAmpac sits within the retort-capable technology specialist tier, serving processors migrating from rigid cans to autoclave-stable flexible formats.
| Leading Market Players |
|---|
| Amcor |
| Mondi Group |
| Sealed Air |
| Huhtamaki |
| ProAmpac |
| Sonoco |
| Berry Global |
| Constantia Flexibles |
| Winpak |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between metallized film laminators and primary aluminum smelters lock in both supply access and price visibility, insulating converters from spot-market volatility in Sichuan and Yunnan provinces while committing buyers to volume thresholds that constrain sourcing flexibility.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate converter-smelter relationships, anchoring laminate pricing to aluminum ingot benchmarks with negotiated conversion premiums. Three-tier pricing structure across premium, standard, and economy levels separates retort-capable barrier laminates from mid-performance snack formats and basic industrial specifications. Price differentiation hinges on oxygen transmission rate certification and FDA 21 CFR 177.1390 compliance tier. Cost compression in standard-grade laminates is intensifying because water-based coating adoption shortens equipment amortization cycles. Private-label retailers exhibit highest price sensitivity; pharmaceutical cold-chain distributors show least.
Supply Chain Analysis
Port congestion on Shanghai-Ningbo and Hamburg-Antwerp trade lanes elevates inbound logistics costs for metallized film imports, compressing converter margins on just-in-time delivery commitments to German pet food processors. Primary aluminum supply concentrates in China, Russia, and Canada; secondary foil rolling capacity clusters in Germany, Japan, and the United States. The supply chain draws from bauxite refining, cold-rolling mills, and fluoropolymer coating chemical suppliers. Single-source vulnerability in high-purity aluminum substrate creates exposure to smelter curtailment announcements. Distribution runs through converter-direct relationships with brand-owning manufacturers, bypassing wholesale intermediaries for specialty coffee and pharmaceutical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum foil zipper pouch procurement is evolving into a service-attach opportunity as chemical recycling partnerships and filling-line retrofit consulting expand faster than commodity laminate sales, enabling converters to capture recurring revenue from extended producer responsibility compliance.
For Market Incumbents: Consolidate captive film extrusion capacity in Lower Saxony and the Pacific Northwest to defend against kraft-paper hybrid substitutes gaining share through French supermarket mandates. Deepen backward integration into water-based barrier coating R&D to offset REACH-driven epoxy lining phase-outs. Lock in long-term offtake with Sichuan smelters before capacity curtailments tighten.
For New Entrants and Emerging Players: Digital print-to-pouch service gaps in sub-10,000 unit runs represent the most penetrable white space, as Pacific Northwest coffee roasters and Nordic freeze-dried meal startups fragment minimum order quantities below incumbent batch economics. Target pharmaceutical cold-chain distributors in Maharashtra and Karnataka with temperature-indicating zipper integrations. Pursue white-label converter partnerships rather than greenfield extrusion assets.
For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors retort-technology specialists with autoclave-stable zipper IP over commodity stand-up pouch converters. Five-to-ten year viability favors players with chemical recycling offtake agreements already in pilot. Watch for EU Packaging and Packaging Waste Regulation enforcement variance across member states as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Pyrolysis-based depolymerization enables multi-layer laminate compliance with Germany's packaging ordinance quotas. |
| Retort-Capable Zipper Scale-Up | Autoclave-stable barrier expansion captures pet food and ready-meal migration from rigid cans in Lower Saxony. |
| Kraft-Paper Hybrid Development | Fiber-aluminum laminates meet French supermarket plastic reduction mandates ahead of regulatory deadlines. |
| Degassing-Valve Integration | Aromatic compound preservation specifications lock in Pacific Northwest coffee roaster direct-to-consumer volumes. |
| Digital Printing Hybrid Line Installation | Sub-batch economics capture specialty brand fragmentation below traditional converter minimum order thresholds. |
Study Parameters
Desk research of EU regulatory filings, SAMR GB standard documentation, and customs trade data preceded structured interviews with plant managers at metallized film laminators, procurement leads at German pet food processors, technical R&D directors at barrier coating suppliers, and sustainability officers at specialty coffee roasters. Primary fieldwork combined with secondary validation from FDA 21 CFR guidance documents, REACH authorization databases, and flexible packaging industry association reports. Bottom-up volume modeling triangulated against top-down converter capacity assessments.
Variance decomposition across product type, application, closure mechanism, and end-user specification authority shaped the analytical framework over the projection horizon. Modeled segmentation captured stand-up versus retort versus flat pouch geometries; food, pharmaceutical, cosmetic, and industrial end-uses; zip, slider, press-to-seal, and tear notch closures; and manufacturer versus retailer versus distributor procurement authority. CAGRs derived from segment-level growth rate blending weighted by current volume shares. Forecast inputs incorporated EU EPR scheme implementation timelines and primary aluminum smelter curtailment patterns.
Forecasts assume regulatory continuity in EU REACH, FDA 21 CFR, and China's SAMR enforcement regimes; material policy shifts would require re-modeling. Aluminum ingot price volatility, fluoropolymer coating phase-down acceleration, or mechanical recycling detection system upgrades present specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Wrap-Around Packers Market
Pouch
Doyen Style Pouches Market
Pouch
Child Resistant Pouches Market
Pouch
Squeeze Pouch Market
Pouch
Inflatable Pouches Market
Pouch
Pouch Dispensing Fitment Market
Pouch
Feed Pouches Market
Pouch
Twist Wrap Packaging Market
Pouch
Japan Pouch Packaging Market
Pouch
Slider Pouches Market
Pouch
Four Side-Sealed Pouches Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Pouches Market
Pouch
Indonesia Pouch Packaging Market
Pouch
Utility Pouches Market
Pouch
Nigeria Pouch Packaging Market