
 Indonesia Pouch Packaging Market | 2026-2036
Indonesia Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Pouch Packaging Market Insights
Indonesia's National Standardization Agency (BSN) material safety regulations is hardening the cost-of-entry calculus for imported flexible packaging substrates. PT Supernova Flexible Packaging leverages vertical integration across blown film and printing to sustain margin control in domestic food pouch supply. Amcor Group GmbH anchors premium barrier technology leadership for retort and aseptic applications serving multinational beverage companies. Mondi Group differentiates through kraft paper-based pouch structures targeting European export compliance requirements from Indonesian manufacturing.
Pouch packaging denotes a flexible primary container format constructed from single or multi-layer films, typically ranging from 70 to 250 microns in total caliper, formed through heat-sealing of web-fed materials to create three- or four-side sealed geometries with optional reclosure features. Stand-up pouches with bottom gusset configurations dominate shelf presence in Indonesian retail environments due to superior cube utilization and billboard graphics area. Composite material constructions lead value pools given their essential role in oxygen and moisture barrier performance for tropical climate distribution, while zipper pouches represent the fastest-growing type segment as convenience-driven reclosure demand spreads from personal care into food and beverage applications.
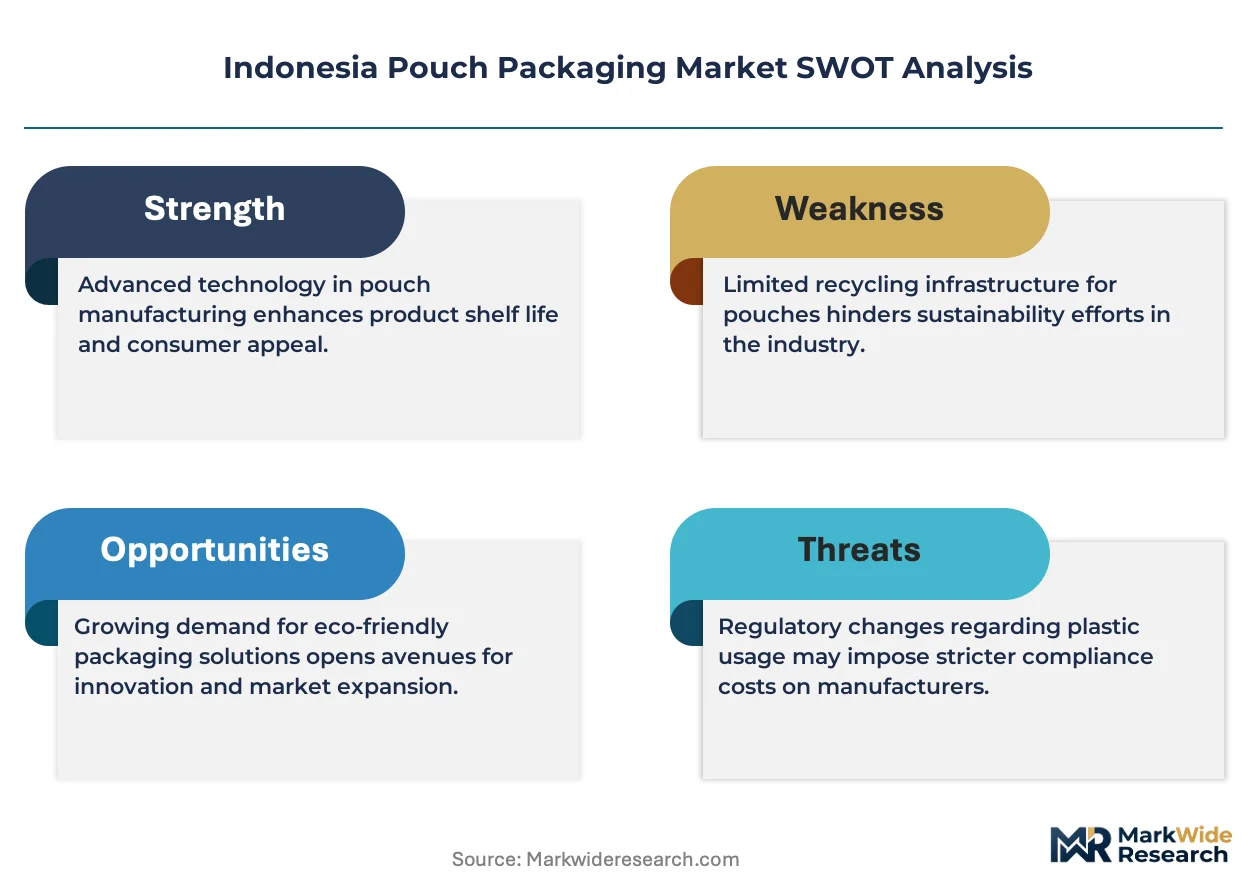
BIS standards for food contact materials, Ministry of Environment and Forestry waste reduction directives, and ASEAN harmonized packaging regulations collectively shape substrate selection, recyclability claims, and import substitution strategies across Indonesian converter operations. Central Java and East Java provinces concentrate enforcement capacity and testing infrastructure, creating geographic asymmetry in compliance cost burdens. Stakeholders must monitor evolving extended producer responsibility frameworks and local recycling ecosystem development to calibrate material platform investments against regulatory trajectory.
Market Dynamics
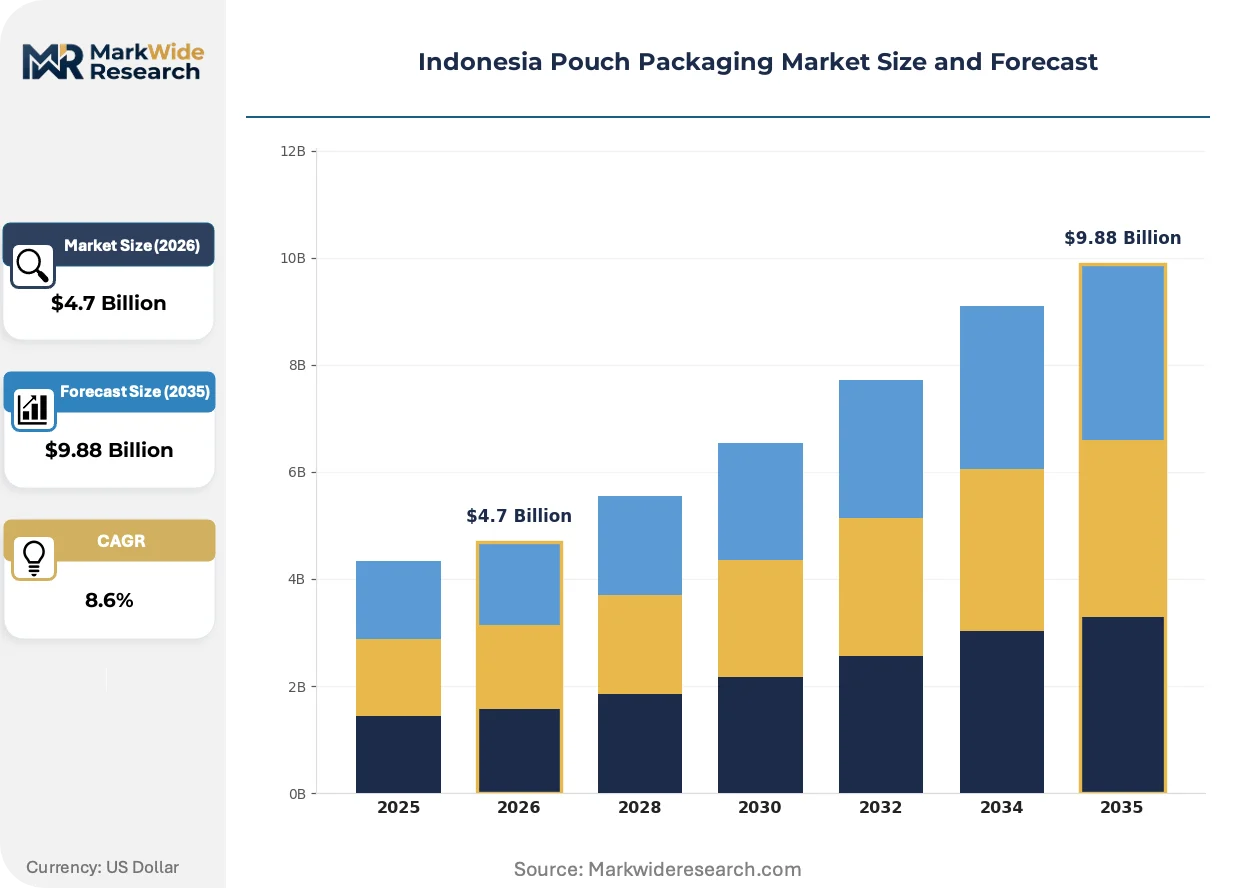
Indonesia's National Standardization Agency (BSN) material safety regulations is compressing import-dependent substrate supply chains while redirecting converter capex toward Surabaya and Jakarta industrial zones with local testing infrastructure.
Growth Catalysts
- BSN-equivalent national standards:Tightened food contact material rules are accelerating domestic procurement from Java-based converters with certified in-house laboratories.
- Mono-material polyethylene structures:Surabaya film extruders are scaling blown film capacity to serve instant noodle manufacturers seeking simplified recyclability pathways.
- Local compostability certifications:Ministry of Environment and Forestry waste reduction directives are creating pull-through for certified biodegradable pouch formats in snack food applications.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin costs fluctuate with naphtha-linked import pricing, squeezing margin control for non-integrated converters in Central Java.
- Barrier film supply concentration:Premium metallized and coextruded substrates remain concentrated among Thai and Malaysian suppliers, exposing Indonesian retort pouch producers to cross-border logistics risk.
- Extended producer responsibility uncertainty:Pending waste management framework revisions are freezing long-term material platform commitments among mid-tier food brands.
Strategic Opportunities
- East Java underpenetration:Surabaya's industrial corridor lacks sufficient high-barrier pouch conversion capacity relative to its food processing density, creating greenfield entry potential.
- E-commerce direct-to-consumer channels:Shopee and Tokopedia fulfillment specifications are driving demand for lightweight, damage-resistant stand-up pouch formats with reclosure features.
- ASEAN harmonized packaging regulations:Cross-border standard alignment is enabling Indonesian converters to certify once and supply multi-country beverage brand regional networks.
Industry Challenges
- Multi-layer lamination technical talent scarcity:Adhesive formulation and barrier layer calibration expertise concentrates among senior technicians nearing retirement in Jakarta satellite plants.
- Compostability certification timeline compression:BSN and Ministry of Environment parallel approval pathways are extending time-to-market for novel biodegradable structures by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Pouch Packaging Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Flat Pouches, Stand-Up Pouches, Zipper Pouches, Gusseted Pouches Material: Plastic, Paper, Aluminum Foil, Composite Application: Food, Beverage, Personal Care, Household End User: Food Manufacturers, Beverage Companies, Cosmetic Brands, Retailers |
| Companies Covered | PT Supernova Flexible Packaging, Amcor Group GmbH, Sonoco Products Company, ePac Holdings LLC, Toppan Packaging Service Co., Ltd., Innopack, PT Argha Karya Prima Industry, Mondi Group, Berry Indonesia Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Pouch Packaging Market Trends and Innovations
Material science convergence with regulatory compliance requirements is redefining competitive advantage across Indonesian flexible packaging, with substrate simplification and digital printing integration emerging as primary vectors of differentiation.
Mono-material polyethylene pouch structures is overtaking conventional multi-layer laminates in shelf-stable snack applications. PT Supernova Flexible Packaging and similar integrated converters are deploying these formats for instant noodle brands seeking streamlined mechanical recycling compatibility. The shift is compressing demand for imported metallized barrier films while elevating in-house blown film and extrusion coating capabilities as strategic assets.
BSN food contact material safety standards are hardening substrate traceability requirements across the supply chain. Indonesian converters must now document resin sourcing and additive composition through batch-level testing at accredited Central Java laboratories. Retort and aseptic pouch segments face the steepest compliance cost escalation, driving consolidation toward vertically integrated players with captive laboratory infrastructure.
Zipper-equipped stand-up pouches are displacing traditional three-side-seal formats in personal care and emerging food categories. Convenience-driven reclosure demand from urban Indonesian consumers is reshaping converter equipment investment priorities, with Jakarta and Surabaya plants retrofitting form-fill-seal lines for slider and press-to-close integration. Premium beverage and sauce segments exhibit the fastest format conversion velocity.
Indonesia Pouch Packaging Market Segmentation
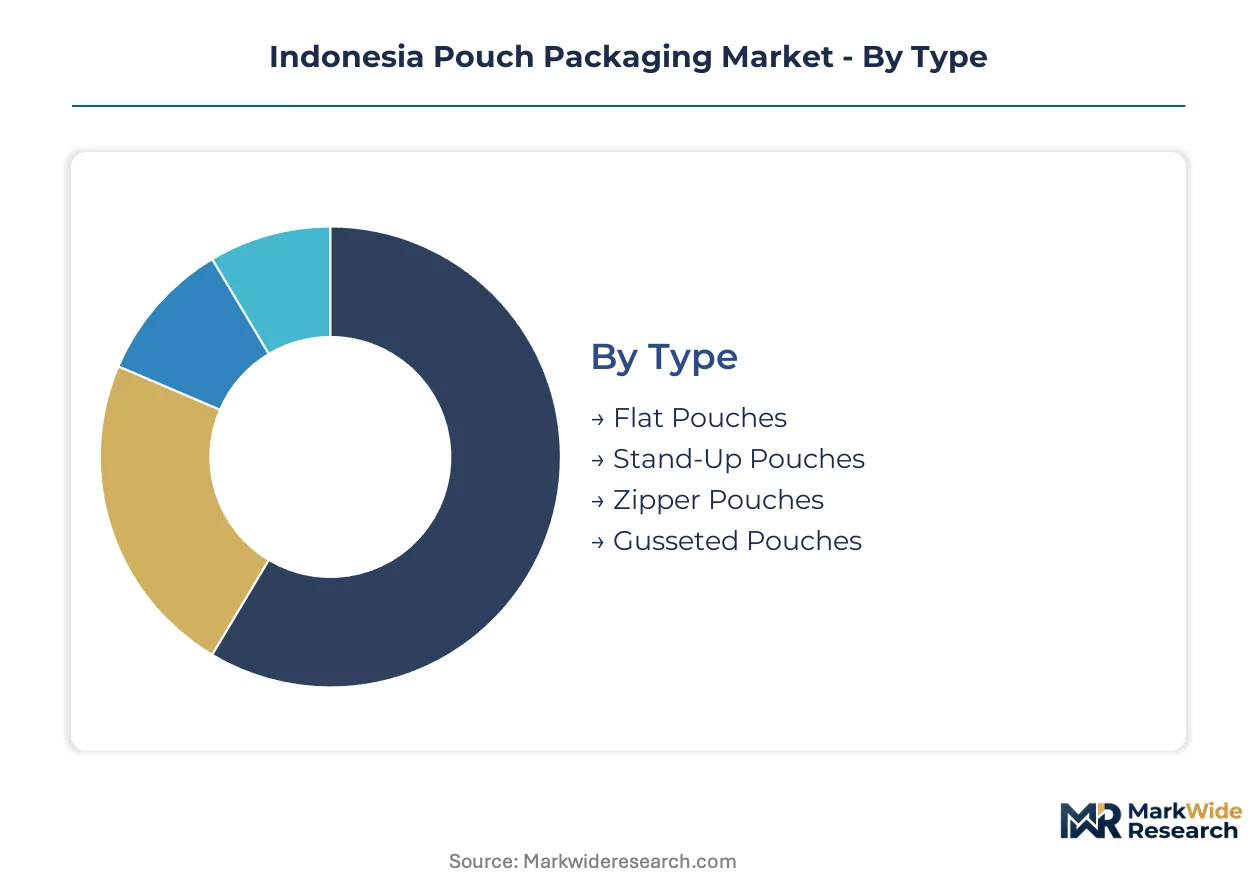
Indonesia's pouch packaging market fragments across format, substrate, and customer type dimensions that each carry distinct margin profiles and regulatory exposure. Converter investment priorities diverge sharply between commodity food service volumes and premium barrier applications serving multinational beverage brands.
Type:
Volume concentration sits with shelf-stable food formats while premium differentiation concentrates in reclosure-enabled convenience packaging.
- Stand-Up Pouches:Bottom gusset configurations dominate Indonesian retail shelf presence through superior cube utilization and expanded billboard graphics area. Instant noodle and cooking oil manufacturers in Central Java and East Java provinces drive procurement scale for this format.
- Zipper Pouches:Press-to-close and slider reclosure mechanisms are displacing traditional three-side-seal formats in urban personal care and emerging sauce categories. Shopee and Tokopedia fulfillment specifications are accelerating converter line retrofits in Jakarta industrial zones.
- Flat Pouches:Three-side-seal geometries retain cost advantage for single-serve condiment and sample applications where reclosure adds no functional value.
- Gusseted Pouches:Side-gusset configurations serve bulk dry goods and institutional food service channels with lower unit economics than stand-up alternatives.
Mature deployment sits with flat pouch formats in commodity food service. Newer deployment is concentrated in zipper-equipped stand-up configurations for e-commerce direct-to-consumer channels.
Material:
Substrate selection in Indonesia tracks BSN food contact compliance burden and Ministry of Environment waste reduction directives rather than pure cost optimization.
- Composite:Multi-layer laminates combining polyethylene, polyamide, and aluminum foil layers deliver oxygen and moisture barrier performance essential for tropical climate distribution. Retort pouch applications for ready-to-eat meals and aseptic beverage formats require this construction despite recycling complexity.
- Plastic:Mono-material polyethylene structures are overtaking conventional laminates in shelf-stable snack applications as Surabaya film extruders scale blown film capacity for simplified mechanical recycling pathways.
- Aluminum Foil:Metallized and foil layers remain concentrated among Thai and Malaysian suppliers, exposing Indonesian retort pouch producers to cross-border logistics risk and feedstock volatility.
- Paper:Kraft paper-based pouch structures serve European export compliance requirements with compostability certifications that Indonesian converters are pursuing for premium positioning.
Established penetration rests with composite multi-layer laminates in barrier-critical food applications. Material platform investment is shifting most quickly toward mono-material polyethylene for domestic circular economy alignment.
Application:
End-use demand splits between high-volume food processing clusters in Java and premium beverage applications requiring aseptic and retort barrier technology.
- Food:Instant noodle, snack, and cooking oil manufacturers account for the dominant procurement volume, with procurement decisions concentrated among Java-based converters with certified in-house BSN testing laboratories.
- Beverage:Retort and aseptic pouch segments face steepest compliance cost escalation from hardened substrate traceability requirements, driving consolidation toward vertically integrated players with captive laboratory infrastructure.
- Personal Care:Shampoo, conditioner, and body wash brands are adopting stand-up pouch formats with reclosure features as convenience-driven demand spreads from traditional rigid packaging.
- Household:Detergent and cleaning product applications favor larger format gusseted pouches with spout fitments for controlled dispensing.
Volume leadership remains with food applications across Java's manufacturing corridor. Beverage applications are climbing the fastest as multinational brands regionalize aseptic pouch sourcing through Indonesian manufacturing.
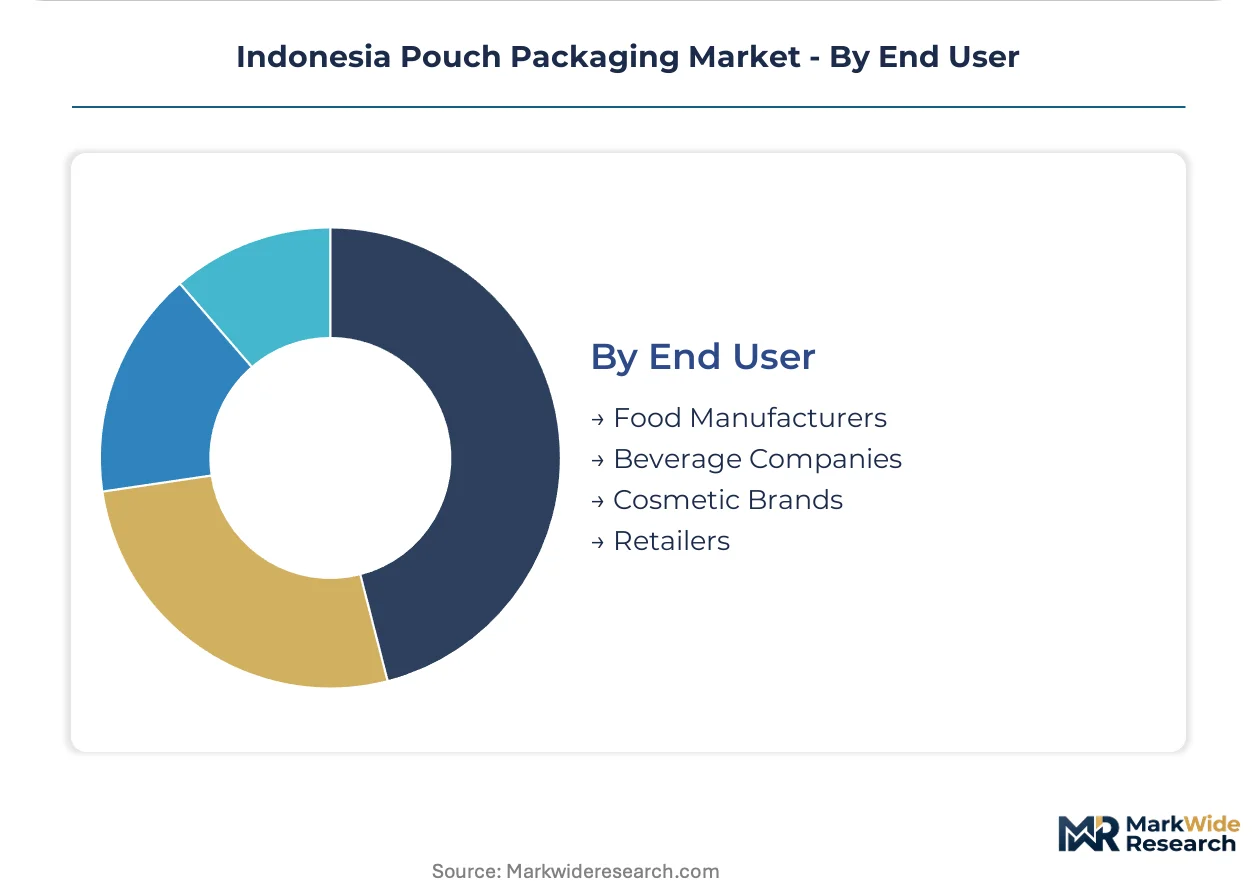
End User:
Customer concentration patterns mirror Indonesia's industrial geography, with procurement authority fragmenting between integrated food conglomerates and emerging cosmetic direct-to-consumer brands.
- Food Manufacturers:Instant noodle and snack producers in Java and Sumatra are accelerating pouch procurement as BIS-equivalent national standards tighten material safety rules and redirect converter capex toward Surabaya and Jakarta industrial zones.
- Beverage Companies:Multinational beverage brands anchor premium barrier technology demand for retort and aseptic applications, with procurement decisions favoring converters with ASEAN harmonized packaging certification for multi-country regional supply.
- Cosmetic Brands:Urban Indonesian personal care brands are driving zipper pouch format conversion velocity as convenience positioning displaces traditional tube and bottle formats.
- Retailers:Private label and house brand procurement from supermarket chains and e-commerce platforms is concentrating demand for lightweight, damage-resistant stand-up pouch formats with reclosure features.
Established procurement relationships dominate food manufacturer segments. Emerging purchasing concentration is occurring among cosmetic brands and e-commerce retailers seeking differentiated format specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kawasan Industri Jababeka and other special economic zones in Bekasi are concentrating flexible packaging investment through tax holidays and import duty exemptions for capital equipment. Java's manufacturing corridor generates over seventy percent of national pouch demand.
Java
Central Java and East Java provinces host Indonesia's densest food processing clusters, with instant noodle manufacturers in Surabaya and Semarang driving stand-up pouch procurement at scale. BSN food contact material standards enforcement concentrates testing infrastructure in these provinces, elevating compliance costs for non-integrated converters. Surabaya's industrial corridor is attracting blown film capacity expansion as mono-material polyethylene demand accelerates.
Sumatra
Snack food manufacturing in Medan and Palembang is redirecting pouch sourcing toward Java-based converters with certified BSN laboratories rather than imported substrates. Ministry of Environment and Forestry waste reduction directives are creating demand for compostable formats in palm oil derivative packaging. North Sumatra's logistics connectivity to Singapore and Malaysia is exposing local producers to cross-border barrier film supply volatility.
Sulawesi
Seafood processing in Makassar and Manado is generating niche demand for high-barrier retort pouches serving export markets with stringent shelf-life requirements. National Standardization Agency material safety rules are compressing lead times for substrate qualification among smaller regional converters. South Sulawesi's port infrastructure is improving cold chain connectivity for aseptic pouch applications.
Kalimantan
Edible oil refining clusters in Balikpapan and Samarinda are driving bulk gusseted pouch demand for institutional food service channels. Extended producer responsibility framework uncertainty is freezing long-term material commitments among mid-tier palm oil brands. East Kalimantan's industrial zones lack sufficient high-barrier conversion capacity relative to processing density.
Bali and Eastern Islands
Tourism-driven food and beverage manufacturing in Denpasar is adopting lightweight stand-up pouch formats for hotel and airline catering supply. E-commerce fulfillment specifications from Shopee and Tokopedia are penetrating these markets with reclosure-equipped convenience formats. Local converter presence remains thin, creating dependency on Java-based supply chains.
Indonesia Pouch Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Indonesia's pouch packaging sector. Market structure tilts toward consolidation among vertically integrated players with captive blown film and laboratory infrastructure, while mid-tier converters face margin compression from feedstock volatility and compliance cost escalation. Three strategic archetypes dominate: integrated domestic champions controlling upstream resin conversion, multinational technology leaders anchoring premium barrier applications, and regional specialists serving export compliance niches. Competitive dynamics center on backward integration into film extrusion and strategic partnerships with food manufacturers seeking BSN-certified supply security.
Among Indonesia-based integrated converters, PT Supernova Flexible Packaging and PT Argha Karya Prima Industry exemplify the domestic champion archetype through captive blown film capacity and in-house testing infrastructure. Amcor Group GmbH and Mondi Group occupy positions as multinational technology anchors, with the former representing premium barrier leadership and the latter exemplifying export-oriented sustainable formats. These three companies collectively illustrate the competitive tension between local integration advantages and global technology access.
| Leading Market Players |
|---|
| PT Supernova Flexible Packaging |
| Amcor Group GmbH |
| Sonoco Products Company |
| ePac Holdings LLC |
| Toppan Packaging Service Co., Ltd. |
| Innopack |
| PT Argha Karya Prima Industry |
| Mondi Group |
| Berry Indonesia Inc. |
| Others |
Pricing and Supply Chain Analysis
Naphtha-linked polyethylene resin indices cascade through Indonesian converter operations into three distinct pricing tiers that separate BSN-certified integrated producers from import-dependent mid-tier competitors and spot-market buyers.
Pricing Analysis
Lead-time premiums reward converters with certified in-house laboratories and captive blown film capacity, while spot inventory discounts attract buyers accepting cross-border logistics risk. Three-tier pricing structure across premium, standard, and economy levels tracks BSN certification status, volume commitment scale, and barrier performance tier. Price compression intensifies in standard-tier mono-material polyethylene as Surabaya film extruders expand capacity. Small snack food manufacturers in Central Java exhibit highest price sensitivity, whereas multinational beverage brands anchoring retort applications show lowest elasticity due to compliance requirements.
Supply Chain Analysis
Metallized and coextruded barrier film supply rests on Thai and Malaysian specialty producers, with Indonesian converters drawing from these cross-border sources for oxygen and moisture-critical applications. Ethylene feedstock, adhesive formulations, and printing inks constitute the critical input trinity. Single-source vulnerability concentrates in premium metallized substrates, exposing retort pouch producers to logistics chokepoints at Strait of Malacca transit points. Distribution runs through Java-based converter hubs serving food processing clusters, with secondary channels reaching Sumatra and Sulawesi via Surabaya port consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's pouch packaging sector sits in a substrate-transition phase as mono-material polyethylene displaces conventional multi-layer laminates in shelf-stable food applications.
For Market Incumbents: To counter feedstock volatility compressing margins at non-integrated converters, PT Supernova Flexible Packaging and similar domestic champions should deepen backward integration into resin compounding and expand captive laboratory certification capacity. BSN traceability requirements favor players controlling batch-level testing infrastructure. Channel control through long-term supply agreements with instant noodle manufacturers secures volume visibility against spot-market competitors. For New Entrants and Emerging Players: Launch via e-commerce direct-to-consumer fulfillment specifications targeting Shopee and Tokopedia damage-resistant stand-up pouch demand. East Java's Surabaya industrial corridor offers the most penetrable geography given underdeveloped high-barrier conversion capacity relative to food processing density. Compostable format certification for snack food applications provides differentiated go-to-market positioning against commodity polyethylene suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap specialists with captive blown film infrastructure in Central Java industrial zones. Long-term viability hinges on regulatory trajectory alignment with extended producer responsibility frameworks. The signal to watch is Ministry of Environment and Forestry waste reduction directive implementation pace as inflection indicator for biodegradable substrate demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive ethylene feedstock control insulates margin compression from naphtha price volatility at BSN-certified Central Java plants. |
| Mono-Material Polyethylene Capacity Expansion | Surabaya blown film scale-up aligns converter assets with Ministry of Environment circular economy compliance trajectories. |
| BSN Laboratory Certification Investment | In-house testing infrastructure accelerates substrate qualification timelines for instant noodle manufacturer supply contracts. |
| E-Commerce Fulfillment Format Development | Shopee and Tokopedia damage-resistant stand-up pouch specifications open direct-to-consumer channel penetration in urban Indonesian markets. |
| Compostable Certification Parallel Pathway | BSN and Ministry of Environment dual-track approval navigation reduces time-to-market for biodegradable snack food packaging launches. |
Research Methodology
Trade association filings, BSN regulatory databases, and Indonesian customs records formed the secondary backbone, supplemented by primary interviews with blown film plant managers, food manufacturer procurement leads, flexible packaging technical directors, and Ministry of Environment compliance officers. Bottom-up and top-down triangulation validated volume estimates across substrate type and application segments.
Historical trendline analysis established baseline growth patterns across the projection horizon, with analytical framework segmentation by pouch format, material construction, end-use application, and geographic production cluster. CAGRs derived from regression modeling incorporating ethylene feedstock price elasticity, BSN certification penetration curves, and e-commerce channel expansion rates as industry-specific forecast inputs.
Ethylene feedstock volatility, extended producer responsibility framework revision timing, and compostability certification pathway compression are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about regulatory implementation pace and substitution elasticity between multi-layer and mono-material structures. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Liquid Pouch Packaging Market
Pouch
Peel Pouches Market
Pouch
Foil Pouch Packaging Market
Pouch
China Pouch Packaging Market
Pouch
Brazil Pouch Packaging Market
Pouch
Wrap-Around Packers Market
Pouch
Contour Pouches Market
Pouch
Heat Seal Pouch Market
Pouch
Digital Printed Pouch Market
Pouch
Flat Bottom Pouch Market
Pouch
Doy Pouch Packaging Market
Pouch
Self-Seal Pouches Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Aluminium Bags and Pouches Market
Pouch
Cold Seal Lamination Pouch Market