
 Nigeria Pouch Packaging Market | 2026-2036
Nigeria Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Pouch Packaging Market Insights
Food-grade laminate specifications are rotating toward higher oxygen-barrier and moisture-resistant configurations as Nigerian processors target export-compliant packaging. PrimePak Industries Nigeria Ltd leverages integrated extrusion and printing capabilities to serve domestic fast-moving consumer goods brands. UFlex Limited sustains its position through backward integration into film substrates, reducing import dependency for base materials. All Time Packaging competes on short-run flexibility, serving mid-tier food processors in the northern trade corridor.
Nigeria pouch packaging denotes flexible primary containers formed from laminated films or single-ply substrates, typically sealed on three or four sides with optional reclose features, designed to protect shelf-stable and refrigerated goods from moisture, oxygen, and light ingress. Stand-up pouches with spout closures command premium positioning in beverage applications where dispensing convenience drives repeat purchase. Biodegradable materials represent the fastest-growing material segment as NAFDAC and SON alignment with food-contact safety protocols creates certified demand channels. Flat pouches remain the volume backbone in dried food and seasoning markets where cost minimization governs procurement.
NAFDAC's food-contact notification requirements and SON's compliance marking rules shape product registration timelines and material selection for both local manufacturers and importers. The country's national standards body enforces dimensional and seal-strength benchmarks that differentiate formal-sector suppliers from informal pack converters. Stakeholders must monitor enforcement intensity at Lagos and Onne port entry points, where customs classification disputes over pre-formed versus roll-stock film imports create working-capital uncertainty.
Market Dynamics
NAFDAC's food-contact notification requirements are compressing product registration timelines and forcing laminate re-specification across Nigerian processors seeking export compliance.
Growth Catalysts
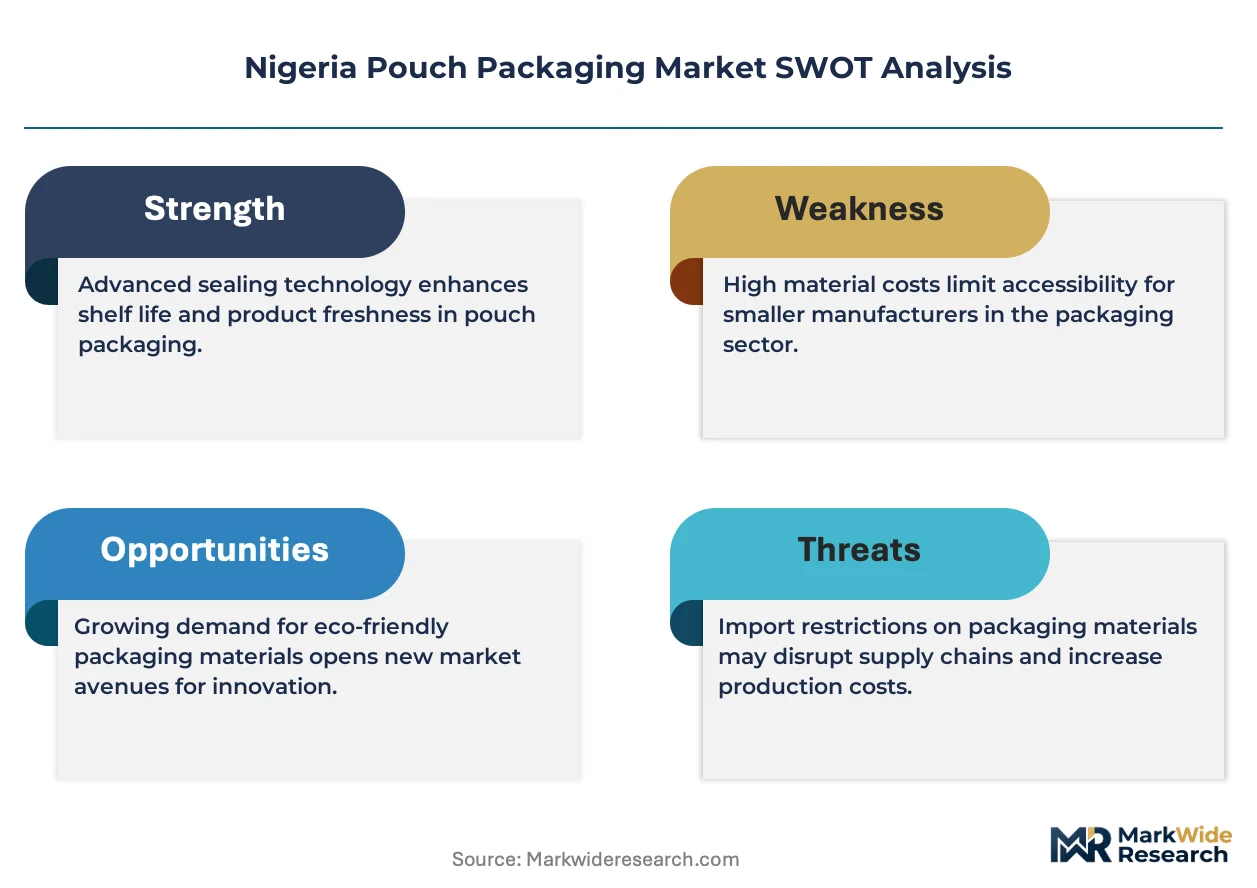
- SON Compliance Marking Rules:Mandatory dimensional and seal-strength benchmarks differentiate formal-sector suppliers from informal converters, channeling procurement toward certified domestic manufacturers.
- Apapa Port Infrastructure:Lagos State's manufacturing belt concentrates food and beverage producers near import gateways, reducing film substrate logistics costs for pouch converters.
- Multilayer Barrier Films:Adoption of oxygen-barrier and moisture-resistant configurations enables Nigerian processors to meet Gulf of Guinea export shelf-life standards.
Market Restraints
- Petrochemical Import Dependency:Base film substrates remain import-reliant, exposing converters to naira-dollar volatility and Lagos port clearance delays.
- Customs Classification Disputes:Pre-formed pouch versus roll-stock film categorization at Onne port creates working-capital uncertainty for importers lacking advance ruling agreements.
- Informal Sector Competition:Uncertified Kano and Aba converters undercut formal players on price, fragmenting quality-tier pricing power.
Strategic Opportunities
- Northern Trade Corridor:Kano's dried food and seasoning clusters remain underpenetrated by SON-certified laminate suppliers, offering first-mover positioning for compliant converters.
- Biodegradable Certification:NAFDAC alignment with food-contact safety protocols for compostable films creates certified demand channels among sustainability-targeting FMCG brands.
- Spout Closure Technology:Beverage applications in Lagos and Abuja metro markets show accelerating preference for recloseable dispensing formats in family-size SKUs.
Industry Challenges
- Extrusion Technician Scarcity:Limited domestic training programs for co-extrusion line operators constrain capacity expansion timelines for integrated converters.
- NAFDAC Registration Timelines:Food-contact material notification reviews average 14-18 months, delaying new laminate commercialization and locking processors into legacy specifications.
- Legacy Printing Press Integration:Gravure-to-flexo conversion requirements for water-based ink compliance demand capital outlays that mid-tier converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Pouch Packaging Market |
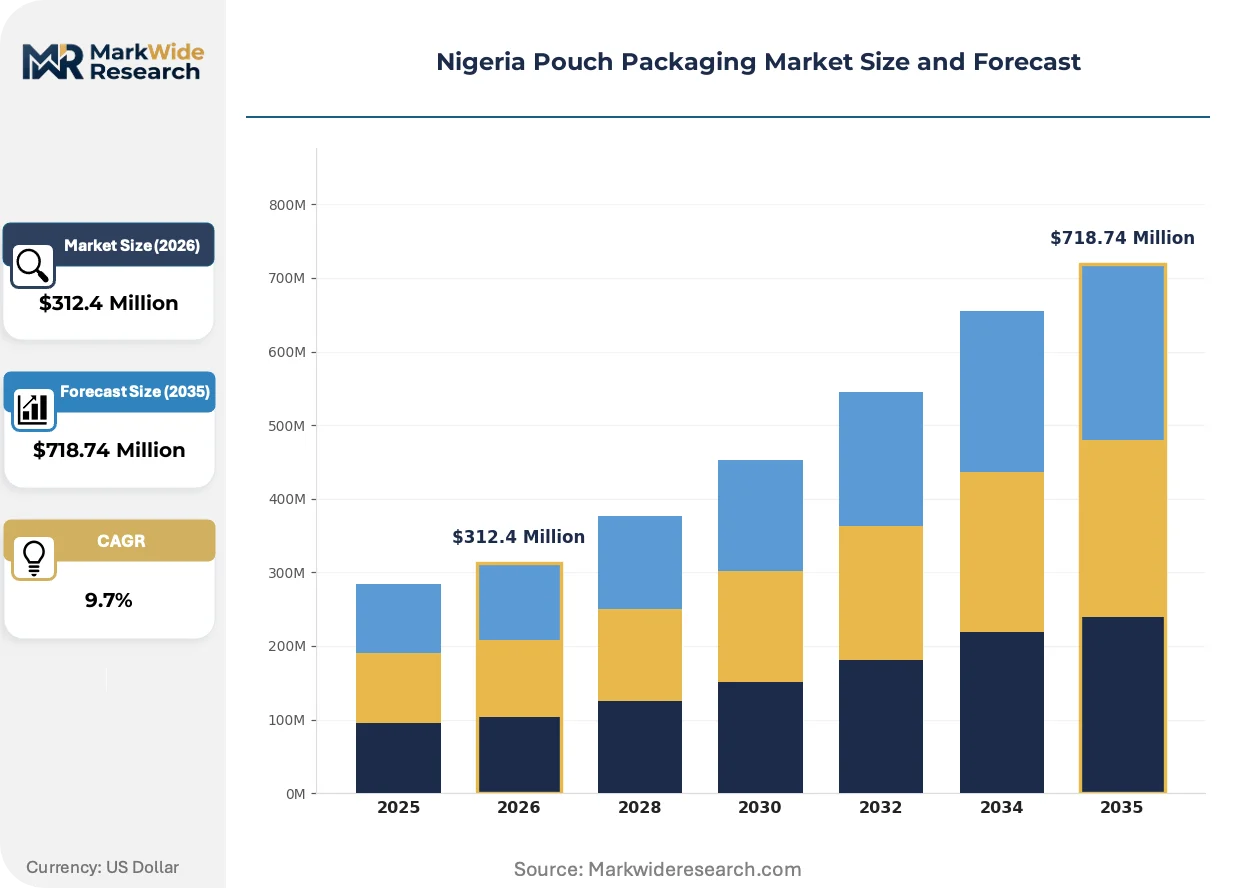
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $718.74 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Stand-Up Pouches, Zipper Pouches, Gusseted Pouches Material: Plastic, Paper, Foil, Biodegradable Materials Application: Food, Beverage, Healthcare, Personal Care Closure Type: Zip Lock, Heat Seal, Press-to-Close, Spout |
| Companies Covered | PrimePak Industries Nigeria Ltd, All Time Packaging, UFlex Limited, Bischof + Klein SE & Co. KG, Radiant Packaging LLC, Insignia Print Technology LFTZ Enterprise, Packageit ng, JC Packaging Ltd, Sonnex Packaging Nigeria, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Pouch Packaging Market Trends and Innovations
Film substrate technology and regulatory compliance protocols are converging to reshape material specifications and procurement patterns across Nigerian flexible packaging.
High-barrier metallized polyethylene terephthalate laminates are displacing conventional aluminum foil in oxygen-sensitive applications. Lagos-based beverage processors are adopting these substrates for 12-month shelf-life targets. The technology is miniaturizing barrier-layer thickness while maintaining performance, reducing per-unit material costs and enabling lighter freight economics for export-bound shipments.
NAFDAC's updated food-contact material guidelines now mandate migration testing for all laminate structures used in infant nutrition and pharmaceutical packaging. This regulatory tightening excludes uncertified Asian imports from premium segments. Domestic converters with in-house testing laboratories are capturing share from traders dependent on third-party certification delays.
Brand procurement teams are consolidating supplier rosters from twelve-plus vendors to three-to-four strategic partners. This concentration is displacing spot-market purchasing in favor of annual volume commitments with price-adjustment clauses. The shift is most visible among Pan-African FMCG headquartered in Lagos, where supply assurance now outweighs unit-cost minimization in vendor selection criteria.
Nigeria Pouch Packaging Market Segmentation
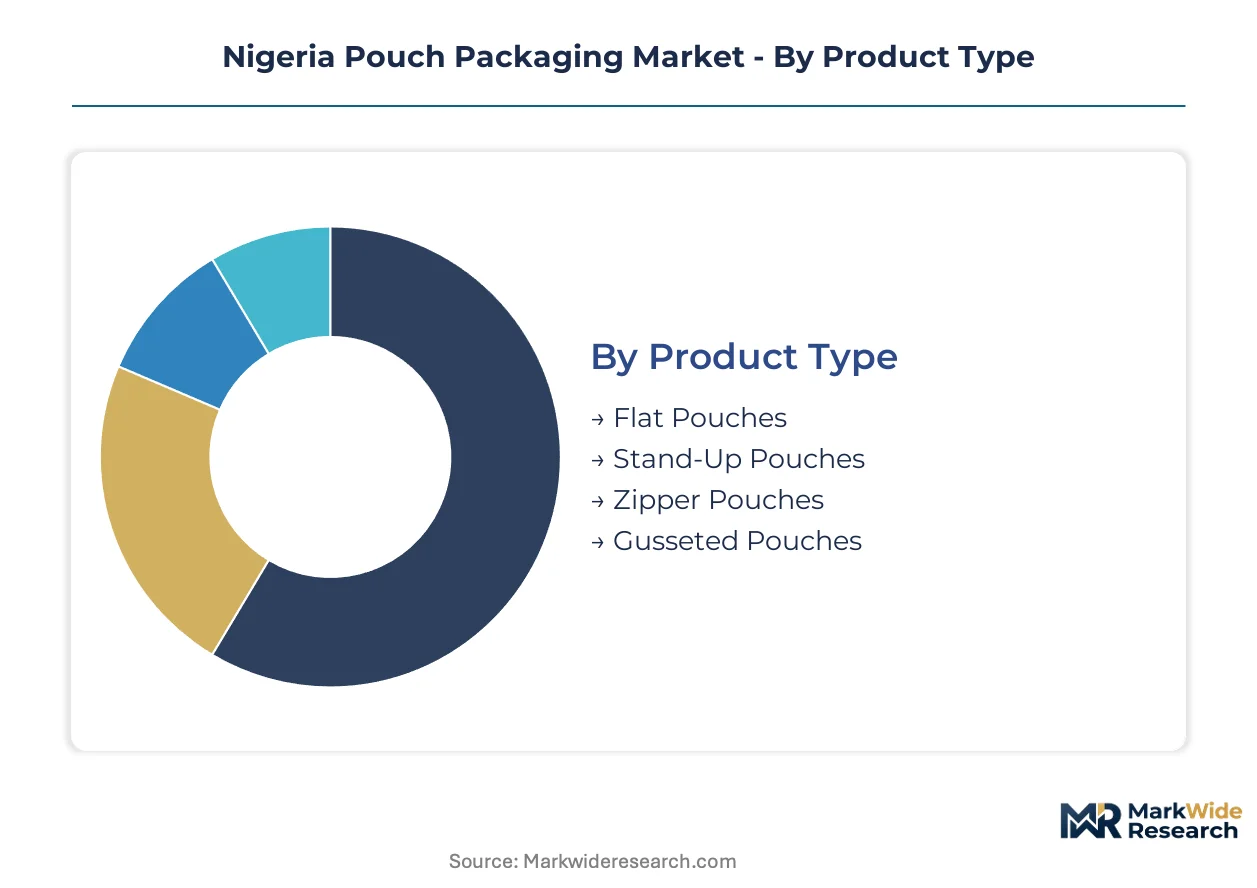
Nigerian pouch converters configure product portfolios around Lagos beverage clusters and Kano dried-food processors, where closure performance and barrier specifications determine procurement premiums. Segment stratification reflects divergent technical requirements between export-facing manufacturers seeking NAFDAC-compliant laminates and domestic traders prioritizing unit-cost minimization.
Product Type:
Margin pools concentrate in formats commanding machinery lock-in and design differentiation, particularly where spout integration and standing stability create switching costs for FMCG brand owners.
- Stand-Up Pouches:Self-supporting bottom gusset structures enable vertical shelf display and optimize retail space efficiency. Lagos beverage processors specify these for family-size juice and dairy SKUs where dispensing convenience drives repeat purchase. Spout-equipped variants capture premium positioning in Abuja metro retail channels.
- Flat Pouches:Three-side-seal or four-side-seal configurations without dimensional stability features. Kano's dried-food and seasoning clusters consume these in volume for single-serve condiment and grain packaging where cost minimization governs procurement decisions.
- Zipper Pouches:Track-and-slider or interlocking profile reclosure systems extending product freshness across multiple use occasions. Northern Nigerian spice traders favor these for humidity-sensitive ginger and pepper flakes.
- Gusseted Pouches:Side-folded expansion panels accommodating bulk contents without compromising seal integrity. Industrial ingredient suppliers in Port Harcourt specify these for 5-10 kilogram chemical and food-additive shipments.
The dominant share belongs to Flat Pouches, while Stand-Up Pouches is closing the gap fastest.
Material:
Cost tiers separate import-dependent petrochemical substrates from emerging certified-alternative supply chains reshaping converter sourcing strategies.
- Plastic:Multilayer polyethylene and polypropylene laminates dominate through extrusion coaters serving high-volume FMCG contracts. Apapa-port logistics integration favors converters with captive film supply arrangements reducing naira-dollar exposure.
- Biodegradable Materials:Compostable films certified under NAFDAC food-contact protocols. Lagos-headquartered Pan-African brands specify these for sustainability-marketed product lines targeting export markets with single-use plastic restrictions.
- Foil:Aluminum-laminated structures providing absolute light and oxygen barrier for pharmaceutical and infant nutrition applications. SON dimensional tolerances differentiate formal-sector foil converters from informal Aba suppliers.
- Paper:Kraft and grease-resistant substrates for dry-food and limited-moisture applications. Kano's traditional grain traders maintain steady demand for paper-polyethylene duplex structures.
Plastic commands the volume base, though Biodegradable Materials is expanding most quickly among certified converters.
Application:
End-use concentration patterns track Nigeria's consumption geography, with Lagos manufacturing belt and northern trade corridor driving divergent specification requirements.
- Food:Primary demand concentration spanning dried seasonings, grains, and processed snacks. NAFDAC migration-testing mandates for infant nutrition and ready-to-eat segments exclude uncertified imports from premium laminate procurement.
- Beverage:Spout-equipped stand-up pouches for juice, dairy, and drinking water. Lagos and Abuja metro markets show accelerating preference for recloseable family-size formats.
- Healthcare:Pharmaceutical and medical-device packaging requiring sterilization compatibility and child-resistant features. SON seal-strength benchmarks govern formal-sector supplier qualification.
- Personal Care:Sachet and pouch formats for shampoo, lotion, and cosmetic samples. Onne port customs classification disputes create working-capital uncertainty for pre-formed pouch importers serving this segment.
Food holds the established revenue base, while Beverage is gaining share fastest through spout-format premiumization.
Closure Type:
Technology maturity curves separate heat-seal commodity supply from patented mechanical closure systems generating recurring royalty streams for equipment licensors.
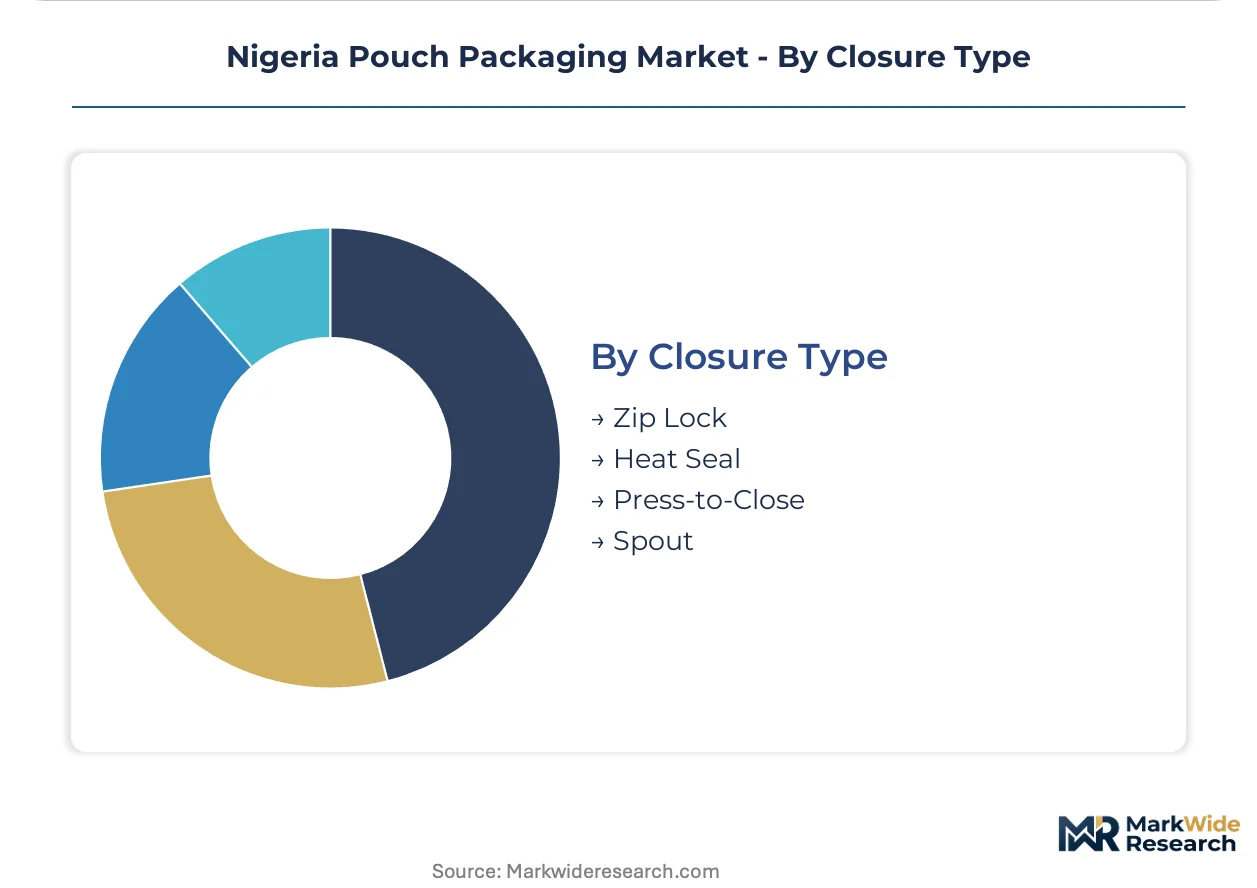
- Heat Seal:Thermal fusion of compatible film layers providing hermetic barrier at lowest unit cost. Volume backbone across Kano dried-food clusters where reclosure is unnecessary.
- Spout:Injection-molded dispensing fitments welded to pouch body during form-fill-seal operations. Lagos beverage processors specify these for 12-month shelf-life export targets.
- Zip Lock:Interlocking plastic profiles enabling finger-press reclosure. Nigerian spice and snack brands specify these for humidity-sensitive products.
- Press-to-Close:Adhesive or cohesive strip systems providing temporary reseal. Mid-tier converters favor these for short-run flexibility serving northern trade corridor processors.
Heat Seal maintains the volume advantage, while Spout is climbing the fastest on beverage premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria's pouch packaging trade flows reflect a structural import dependency for base films, with domestic converters clustering near Lagos port infrastructure to minimize naira-dollar exposure and customs clearance delays. Export-oriented food processors in the Lagos manufacturing belt drive demand for NAFDAC-compliant laminates meeting Gulf of Guinea shelf-life standards.
Lagos State
Apapa port infrastructure anchors the nation's largest concentration of pouch converters, with PrimePak Industries Nigeria Ltd and UFlex Limited maintaining integrated extrusion and printing operations near import gateways. NAFDAC's food-contact notification requirements compress registration timelines for processors seeking export compliance. The Ikeja-Ogba industrial corridor hosts beverage specialists specifying spout-equipped stand-up pouches for family-size juice and dairy SKUs.
Kano State
Northern Nigeria's dried-food and seasoning clusters consume flat pouches in volume for single-serve condiment packaging where cost minimization governs procurement. SON compliance marking rules differentiate formal-sector suppliers from informal converters in this underpenetrated trade corridor. All Time Packaging competes on short-run flexibility serving mid-tier processors distributing through the Dawanau grains market.
Rivers State
Onne port customs classification disputes over pre-formed versus roll-stock film imports create working-capital uncertainty for converters serving Port Harcourt's industrial ingredient suppliers. SON seal-strength benchmarks govern formal-sector qualification for 5-10 kilogram chemical and food-additive shipments. Gusseted pouch specifications dominate bulk packaging requirements for Gulf of Guinea export routes.
Federal Capital Territory
Abuja metro markets show accelerating preference for recloseable beverage formats in premium retail channels, driving spout closure technology adoption among Lagos-based suppliers extending distribution northward. NAFDAC alignment with food-contact safety protocols for compostable films creates certified demand channels among sustainability-targeting FMCG brands with headquarters in the capital.
Nigeria Pouch Packaging Market Competitive Landscape
Concentration sits with integrated converters controlling extrusion and printing capabilities, while mid-tier specialists compete on short-run flexibility for regional trade corridors. The market structures around three archetypes: port-proximate integrated manufacturers, northern corridor flexible converters, and import-dependent traders. Competitive moves center on backward integration into film substrates and NAFDAC certification investments that exclude uncertified Asian imports from premium segments.
Among Nigeria-based integrated manufacturers, PrimePak Industries Nigeria Ltd and UFlex Limited exemplify the port-proximate archetype with captive supply arrangements reducing currency exposure. All Time Packaging anchors the flexible-converter tier, occupying a position serving underpenetrated northern markets with short-run capabilities. These three represent the strategic positioning spectrum from scale-driven integration to regional agility.
| Leading Market Players |
|---|
| PrimePak Industries Nigeria Ltd |
| All Time Packaging |
| UFlex Limited |
| Bischof + Klein SE & Co. KG |
| Radiant Packaging LLC |
| Insignia Print Technology LFTZ Enterprise |
| Packageit ng |
| JC Packaging Ltd |
| Sonnex Packaging Nigeria |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Lagos-based integrated converters shapes both supply concentration and minimum viable pricing floors for formal-sector pouch manufacturers. PrimePak Industries Nigeria Ltd and UFlex Limited leverage captive extrusion lines to compress per-unit costs below import-dependent traders, creating tiered entry barriers across NAFDAC-certified and uncertified supply tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in Nigeria's pouch packaging market. Price differentiation separates SON-certified laminates with in-house migration testing from informal Kano converters lacking compliance documentation. Cost compression in the economy tier is intensifying because uncertified Asian imports undercut domestic producers on spot-market transactions. Fast-moving consumer goods brands with Pan-African headquarters show lowest price sensitivity, prioritizing supply assurance and NAFDAC registration speed over unit-cost minimization.
Supply Chain Analysis
Apapa port congestion and container availability constraints on the Asia-West Africa trade lane elevate inbound logistics costs for film substrate importers. Raw material dependencies draw from China, India, and Saudi Arabia for polyethylene and polypropylene resins, with metallized polyethylene terephthalate barrier films resting on South Korean and Taiwanese supply. Single-source vulnerability concentrates in base resin procurement, where naira-dollar volatility amplifies working-capital exposure. Distribution runs through converter-direct relationships with Lagos beverage processors and northern trade corridor dried-food clusters, bypassing traditional distributor networks for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigeria's pouch packaging market represents an early-cycle expansion story driven by NAFDAC's tightening food-contact compliance mandates, which accelerate formal-sector substitution of uncertified imports across infant nutrition and pharmaceutical applications.
For Market Incumbents: Consolidate procurement relationships with backward integration into film substrates to reduce naira-dollar exposure and lock in margin buffers against petrochemical import volatility. Defend market position by accelerating NAFDAC certification investments that exclude informal Kano and Aba converters from premium laminate segments, while adding co-extrusion capacity in Lagos State to capture spout-equipped stand-up pouch demand from beverage exporters.
For New Entrants and Emerging Players: Short-run flexibility gaps in northern Nigeria's dried-food corridor present viable white-space entry points for SON-certified converters willing to serve mid-tier processors below PrimePak's minimum order thresholds. Target Kano's Dawanau grains market with flat pouch configurations optimized for single-serve condiment packaging, using press-to-close closure technology to differentiate from commodity heat-seal suppliers. A channel partnership approach with established northern distributors accelerates customer acquisition without direct sales infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated converters with captive film supply and long-term offtake agreements with Pan-African FMCG brands. Over a multi-year holding period, acquisition targets should demonstrate in-house NAFDAC testing laboratories and established spout closure technology licensing relationships. The signal to watch is enforcement intensity at Lagos and Onne ports, where customs classification rulings on pre-formed versus roll-stock imports determine working-capital efficiency and competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Substrates | Captive resin supply reduces naira-dollar exposure for Lagos-based converters serving export-facing processors. |
| NAFDAC Certification Investment | In-house migration testing laboratories accelerate product registration timelines and exclude uncertified Asian competitors. |
| Spout Closure Technology Licensing | Patented dispensing fitments capture premium positioning in Lagos and Abuja beverage markets seeking family-size convenience. |
| Northern Trade Corridor Expansion | Kano's underpenetrated dried-food clusters offer first-mover positioning for SON-certified laminate suppliers with short-run capabilities. |
| Biodegradable Material Certification | NAFDAC-aligned compostable films access sustainability-marketed demand channels among Pan-African FMCG brands. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Interviews captured perspectives from pouch converter operations managers, NAFDAC regulatory affairs officers, FMCG procurement directors, SON compliance auditors, and Apapa port customs brokers. Secondary sources included NAFDAC food-contact material guidelines, SON dimensional and seal-strength standards, Nigerian Customs Service import classification records, and trade flow data for polyethylene and polypropylene substrates. Bottom-up unit economics and top-down market sizing were triangulated to reconcile volume estimates.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, material substrate, end-use application, closure technology, and regional production cluster. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory enforcement intensity assumptions. Key inputs included naira exchange rate volatility scenarios, Apapa port throughput capacity utilization, and NAFDAC registration timeline distributions for new laminate structures.
Forecasts assume regulatory continuity in NAFDAC food-contact notification protocols and SON compliance marking enforcement; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Doy Pouch Packaging Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market
Pouch
Pouch Dispensing Fitment Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Kraft Block Bottom Pouch Market
Pouch
Self-Seal Pouches Market
Pouch
High-Barrier Pouches Market
Pouch
UAE Pouch Packaging Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Brazil Pouch Packaging Market
Pouch
Kraft Paper Pouch Market
Pouch
Ziplock Products Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Pouches Market
Pouch
MAP Flow Wrappers Market
Pouch
China Pouch Packaging Market