
 Russia Pouch Packaging Market | 2026-2036
Russia Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Pouch Packaging Market Insights
Central Russia's converting capacity is tilting toward multilayer flexible film production to serve domestic food processors. Danaflex Group anchors its position through backward integration into film extrusion, reducing resin cost exposure. Vakumpak-M specializes in vacuum pouch systems for protein processors across the Volga region. Constantia Flexibles competes via its European technical base, supplying high-barrier laminates to multinational brand owners operating Russian production lines.
Pouch packaging denotes a flexible primary container formed from flat or gusseted films, sealed on two or three sides, with typical wall constructions of 80–150 microns incorporating oriented polyamide, cast polypropylene, and metallized polyethylene terephthalate layers to achieve oxygen transmission rates below 1 cc/m²/day. Its industrial purpose centers on product protection, portion control, and shelf-space efficiency across fast-moving consumer goods supply chains. Stand-up pouches dominate value capture due to their billboard effect on retail shelves and compatibility with automated filling equipment. Vacuum pouches represent the fastest-expanding product type as meat and seafood processors adopt extended shelf-life formats. Composites command margin concentration because their engineered barrier properties justify premium pricing over monolayer plastic alternatives.
BIS-aligned Eurasian Conformity certification and Russia's Federal Service for Surveillance in Consumer Rights Protection and Human Wellbeing technical regulations govern migration limits and food-contact material safety, compelling converters to validate laminate structures through accredited laboratories. The national packaging waste extended producer responsibility framework, administered by the Russian Environmental Operator, forces brand owners to fund collection infrastructure or face tariff penalties, directly influencing mono-material versus multilayer design choices. Stakeholders must monitor regulatory enforcement intensity in the Northwestern and Siberian Federal Districts, where regional environmental inspectorates have divergent track records on compliance verification.
Market Dynamics
Central Russia's converting base is pivoting toward multilayer film production as Eurasian Economic Union technical regulations on recyclability force laminate redesigns and resin specification changes across food-contact applications.
Growth Catalysts
- Extended Producer Responsibility Framework:The Russian Environmental Operator's packaging waste mandates compel brand owners to fund collection infrastructure, accelerating mono-material pouch adoption over multilayer alternatives.
- Protein Processing Modernization:Vacuum pouch systems are gaining traction among Volga region meat and seafood processors seeking extended shelf-life formats for retail distribution.
- Central Federal District Logistics Density:Moscow's industrial corridor concentrates demand for lightweight, shelf-ready formats that reduce transport costs and warehouse cube utilization.
Market Restraints
- Resin Import Dependency:Polyamide and metallized polyethylene terephthalate supply chains remain exposed to currency volatility and trade friction, compressing converter margins.
- Multilayer Recycling Incompatibility:Current mechanical recycling infrastructure cannot process oriented polyamide-cast polypropylene laminates, creating end-of-life liability for brand owners.
- Regional Enforcement Divergence:Northwestern and Siberian Federal Districts exhibit inconsistent compliance verification track records, complicating national rollout of standardized laminate structures.
Strategic Opportunities
- Mono-Material Barrier Films:Single-polymer pouch constructions compatible with existing polyethylene recycling streams offer compliance pathways under tightening Eurasian Economic Union recyclability mandates.
- Siberian Federal District Penetration:Underdeveloped converting capacity in remote regions creates first-mover advantages for regional film extrusion and pouch converting investments.
- High-Barrier Coatings Convergence:Atomic layer deposition and plasma-enhanced chemical vapor deposition technologies applied to mono-material substrates are displacing metallized layers while maintaining oxygen transmission performance.
Industry Challenges
- Migration Testing Bottlenecks:BIS-aligned Eurasian Conformity certification requires validation through accredited laboratories, creating 12-18 month product development timelines for new laminate structures.
- Legacy Equipment Retrofit Costs:Existing form-fill-seal lines require modification to handle mono-material films with different sealing temperatures and elongation properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Pouch Packaging Market |
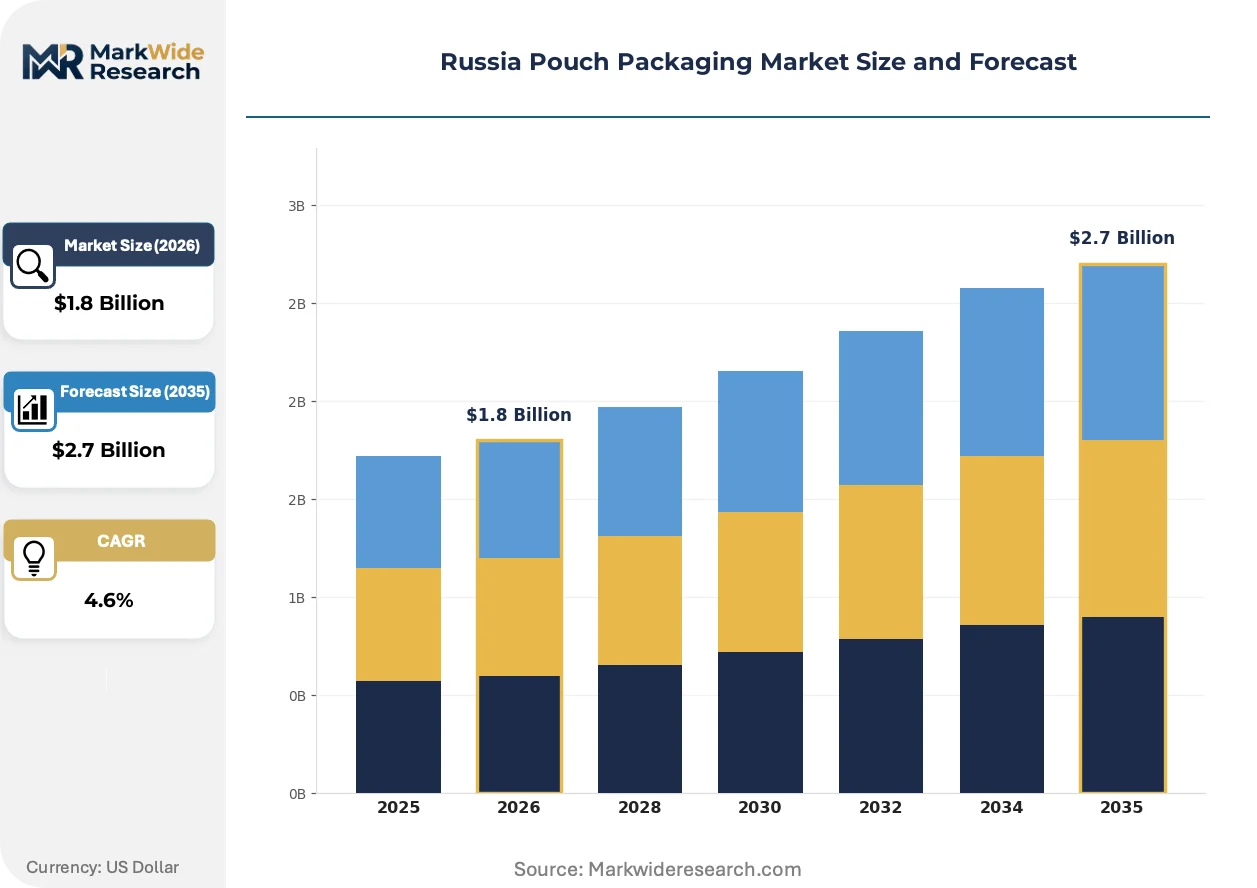
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Zipper Pouches, Vacuum Pouches Material: Plastic, Paper, Aluminum, Composites End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Vakumpak-M, Izaslav Company, Uflex Limited, 2a - Upakovka, KubRotoPak, Sonoco Products Company, Danaflex Group, Constantia Flexibles, OKHTA LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Pouch Packaging Market Trends and Innovations
Digital printing and smart packaging integration are compressing minimum order quantities and enabling batch-level traceability for Russian food processors navigating stricter supply chain documentation requirements.
Digital printing technology is digitizing artwork changeover and variable data insertion for regional brand owners. Mid-sized dairy and confectionery processors in the Central Federal District are adopting this capability to reduce plate costs and enable promotional versioning. The technology is digitizing converter-customer relationships by collapsing setup economics and enabling just-in-time production runs previously uneconomical at sub-50,000 unit volumes.
Russia's Federal Service for Surveillance in Consumer Rights Protection and Human Wellbeing has tightened migration limits for food-contact materials under technical regulations aligned with Eurasian Economic Union standards. Industrial consequence includes mandatory laboratory validation of laminate structures for heavy metal and primary aromatic amine content. Small and mid-sized converters in the Volga region are most affected, responding by consolidating supplier bases to pre-certified resin sources.
Retailer-driven specification consolidation is compressing supplier rosters for Russian fast-moving consumer goods brands. Magnit and X5 Retail Group are centralizing pouch procurement through approved vendor lists, displacing fragmented local converter relationships. This concentration is most visible in Moscow's retail corridor, where shelf-ready format compliance and automated warehouse compatibility have become non-negotiable entry criteria.
Russia Pouch Packaging Market Segmentation
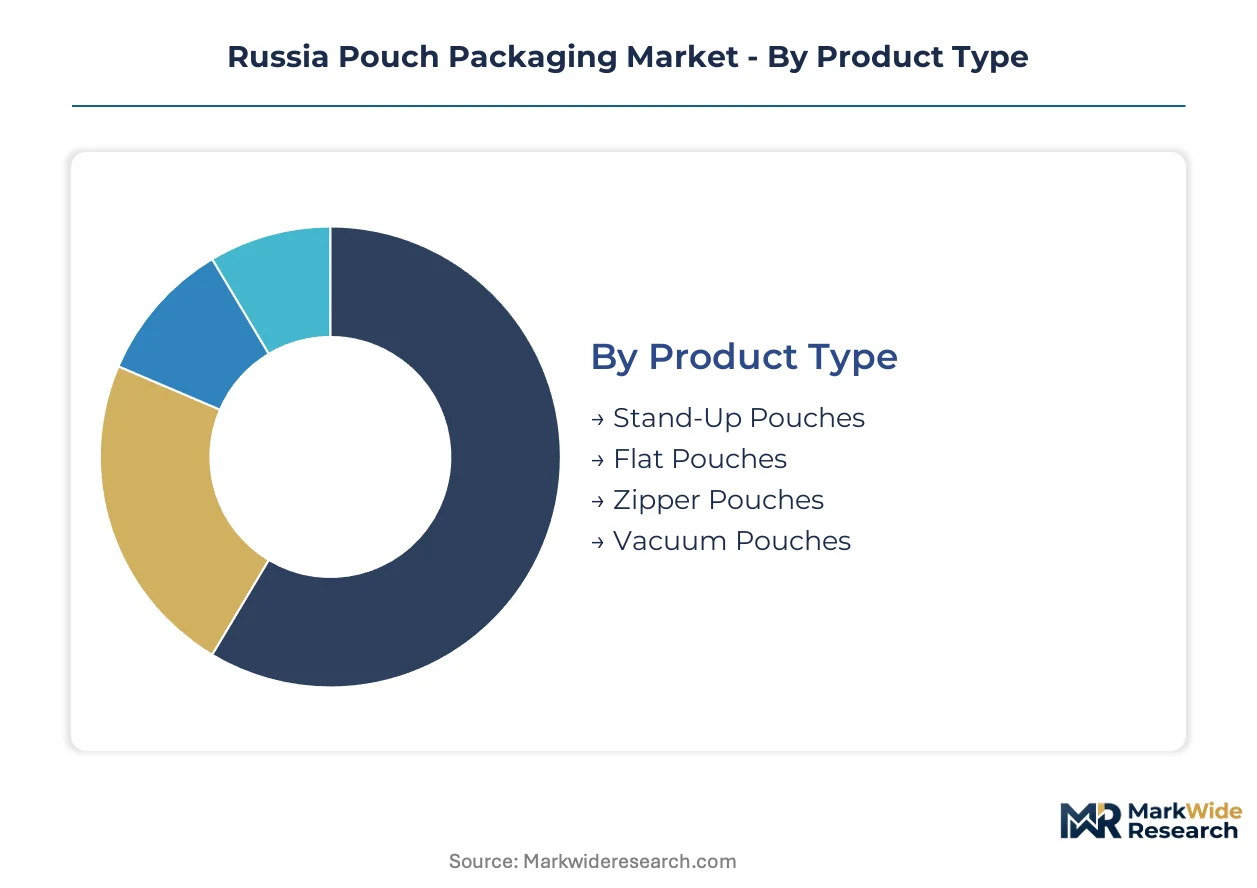
Pouch packaging converters in Russia engineer segment-specific barrier properties and sealing geometries to match shelf-life requirements across protein processing, dairy, and pharmaceutical applications. Technical specification divergence between vacuum formats for meat processors and stand-up configurations for retail-ready dry goods drives material selection and equipment investment patterns.
Product Type:
After-sales service intensity varies sharply across pouch formats, with vacuum systems requiring specialized technical support for seal integrity validation and gas-flushing equipment integration.
- Stand-Up Pouches:Gusseted bottom construction with 120-180 micron multilayer laminates incorporating cast polypropylene and metallized polyethylene terephthalate. Moscow's Central Federal District retail corridor concentrates procurement from dairy and confectionery processors seeking billboard shelf presence and automated filling compatibility.
- Vacuum Pouches:Three-side-sealed or tubular formats with oriented polyamide-cast polypropylene laminates achieving oxygen transmission rates below 1 cc/m²/day. Volga region meat and seafood processors drive adoption for extended shelf-life distribution, though Eurasian Economic Union recyclability mandates are forcing laminate redesigns.
- Flat Pouches:Two-side-sealed configurations for single-serve portions and sample sachets. Pharmaceutical and cosmetic brand owners in Moscow specify these for unit-dose compliance.
- Zipper Pouches:Reclosable interlocking profiles laminated between film layers. Snack food processors favor these for moisture protection across repeated opening cycles.
Stand-up pouches hold the largest share; momentum sits with vacuum pouches as protein processors modernize cold-chain distribution.
Material:
Material cost tiers stratify converter margins, with commodity polyethylene films at the base and engineered barrier laminates commanding premium positioning.
- Composites:Engineered multilayer structures combining oriented polyamide, ethylene vinyl alcohol, and polyethylene sealant layers. Central Russia's converting base is pivoting toward these constructions to serve high-barrier food-contact applications under tightening migration limits.
- Plastic:Monolayer and coextruded polyethylene or polypropylene films. The Russian Environmental Operator's extended producer responsibility framework is accelerating mono-material polyethylene adoption for mechanical recycling compatibility.
- Aluminum:Metallized or foil-laminate pouches for oxygen and light-sensitive pharmaceuticals. Regulatory validation through BIS-aligned Eurasian Conformity certification limits supplier pools.
- Paper:Fiber-based substrates with polymer barrier coatings. Emerging niche for organic and premium-positioned dry goods where end-of-life composting claims support brand differentiation.
Composites dominate value capture; mono-material plastic films are climbing the fastest as recyclability mandates reshape specification sheets.
End User:
Application-specific performance requirements drive volume concentration, with food-contact regulations creating the steepest compliance barriers.
- Food & Beverage:Dominant demand source spanning dairy, meat, confectionery, and ready-meal segments. Central Federal District processors specify high-barrier laminates for shelf-stable and refrigerated distribution formats.
- Pharmaceuticals:Unit-dose and bulk API packaging with child-resistant and senior-friendly closure requirements. Federal Service for Surveillance in Consumer Rights Protection and Human Wellbeing migration testing creates 12-18 month qualification timelines.
- Cosmetics:Sample sachets and primary flexible containers for creams and serums. Digital printing adoption enables promotional versioning for regional brand owners.
- Household Products:Detergent pods and cleaning chemical pouches with chemical resistance specifications. Concentrated formulations drive single-dose format demand.
Food & Beverage commands the volume base; Pharmaceuticals offers the steepest margin expansion trajectory as barrier requirements intensify.
Distribution Channel:
Channel concentration patterns reflect retail consolidation, with approved vendor lists compressing supplier relationships for national chains.
- Supermarkets:Magnit and X5 Retail Group centralize procurement through standardized specification programs. Shelf-ready format compliance and automated warehouse compatibility are mandatory entry criteria.
- Wholesale:Industrial and foodservice volume through distributor networks. Protein processors in the Volga region rely on these channels for bulk vacuum pouch supply.
- Online Retail:Direct-to-consumer fulfillment requiring damage-resistant formats for last-mile distribution. Regional brand owners adopt digital printing for promotional versioning.
- Convenience Stores:Smaller format pouches for immediate consumption and impulse categories. Urban Moscow density supports specialized logistics configurations.
Supermarkets anchor volume concentration; online retail is expanding most quickly as e-commerce penetration reshapes packaging specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Central Federal District consumes pouch formats for retail-ready dairy and confectionery, while the Volga region prioritizes vacuum systems for protein distribution—creating divergent material specification demands across Russian territory.
Central Federal District
Moscow's retail corridor drives demand for stand-up pouches with billboard shelf presence. The Russian Environmental Operator's extended producer responsibility framework compels brand owners to fund collection infrastructure. Industrial converting capacity clusters along the Moscow-St. Petersburg logistics axis, where Danaflex Group operates integrated film extrusion facilities.
Volga Federal District
Meat and seafood processors in Samara and Kazan specify oxygen barrier laminates below 1 cc/m²/day for extended shelf-life distribution. Eurasian Economic Union technical regulations on food-contact material safety mandate laboratory validation of heavy metal content. Vakumpak-M anchors regional supply through specialized vacuum pouch systems serving protein processors.
Northwestern Federal District
St. Petersburg's port infrastructure supports import-dependent resin supply chains for metallized polyethylene terephthalate layers. Regional environmental inspectorates exhibit inconsistent compliance verification track records compared to Central Russia. Converters here concentrate on pharmaceutical and cosmetic flat pouch formats for unit-dose applications.
Siberian Federal District
Underdeveloped converting capacity across Novosibirsk and Krasnoyarsk creates supply gaps for remote food processors. BIS-aligned Eurasian Conformity certification bottlenecks extend product development timelines to 12-18 months for new laminate structures. First-mover investments in regional film extrusion could capture unmet demand for lightweight distribution formats.
Southern Federal District
Rostov-on-Don's agricultural processing base generates seasonal demand for bulk grain and oilseed pouches. The Federal Service for Surveillance in Consumer Rights Protection and Human Wellbeing enforces migration limits that pre-certify resin sources. Local converters serve fragmented wholesale channels with commodity polyethylene constructions.
Russia Pouch Packaging Market Competitive Landscape
Capability concentration sits with integrated film extruders; scale advantage sits with multinational laminate suppliers. The vendor base stratifies across three tiers: backward-integrated domestic groups controlling resin costs, European technical specialists supplying barrier laminates, and regional converters serving approved vendor lists of consolidated retailers. Dominant competitive moves include upstream integration into polymer production and retrofit of legacy form-fill-seal lines for mono-material compatibility.
Among Russia-based integrated producers, Danaflex Group exemplifies the backward-integrated archetype through captive film extrusion capacity. Vakumpak-M occupies a specialist position in vacuum pouch systems for protein applications. Constantia Flexibles represents the European technical tier, supplying high-barrier laminates to multinational brand owners operating Russian production lines.
| Leading Market Players |
|---|
| Vakumpak-M |
| Izaslav Company |
| Uflex Limited |
| 2a - Upakovka |
| KubRotoPak |
| Sonoco Products Company |
| Danaflex Group |
| Constantia Flexibles |
| OKHTA LLC |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Siberian film extrusion capacity tilts pricing power toward Central Federal District converters, who leverage Moscow-St. Petersburg logistics density to command premium positioning for high-barrier laminates while remote processors absorb inflated transport costs for resin-dependent formats.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between multinational brand owners and backward-integrated converters like Danaflex Group, insulating volume commitments from polyamide spot price volatility while smaller regional players transact on project-based terms exposed to currency swings. Price differentiation rests on Eurasian Conformity certification tier and vertical integration depth, with accredited laboratories validating migration-compliant laminates at substantial premiums. Cost compression in commodity polyethylene tiers is intensifying as the Russian Environmental Operator's extended producer responsibility framework forces brand owners toward mono-material specifications. Small and mid-sized Volga region processors exhibit highest price sensitivity due to thin margins on vacuum pouch systems, whereas pharmaceutical brand owners in Moscow demonstrate lowest sensitivity given 12-18 month qualification timelines that lock in supplier relationships.
Supply Chain Analysis
Upstream polyamide and metallized polyethylene terephthalate feedstock draws from Germany, China, and South Korea, with St. Petersburg's port infrastructure serving as the primary import gateway for Central and Northwestern Federal District converters. Resin supply chains rest on ethylene vinyl alcohol copolymers, cast polypropylene substrates, and oriented polyamide films as critical laminate components. Single-source vulnerability concentrates in metallized layer supply, where European technical specialists like Constantia Flexibles control proprietary barrier formulations. Distribution runs through Magnit and X5 Retail Group's centralized procurement systems, compressing supplier rosters and standardizing shelf-ready format specifications across Moscow's retail corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mono-material barrier film innovation represents high-growth disruption as Eurasian Economic Union recyclability mandates force laminate redesigns, with atomic layer deposition technologies displacing metallized layers while maintaining oxygen transmission performance below 1 cc/m²/day.
For Market Incumbents: Build regulatory certification moats through captive laboratory validation capacity and BIS-aligned Eurasian Conformity pre-certification of resin sources, defending against emerging mono-material specialists by retrofitting legacy form-fill-seal lines for polyethylene compatibility and anchoring long-term offtake relationships with protein processors across the Volga region. For New Entrants and Emerging Players: Siberian Federal District underpenetration offers first-mover advantages in regional film extrusion, with Novosibirsk and Krasnoyarsk supply gaps creating white-space for lightweight distribution formats; target wholesale channels serving remote agricultural processors with commodity polyethylene constructions while building technical credibility through plasma-enhanced chemical vapor deposition coating partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among backward-integrated converters with captive resin supply and approved vendor list status at consolidated retailers; acquisition targets should demonstrate 5-10 year viability through Eurasian Economic Union regulatory alignment rather than spot-market commodity positioning, with the signal to watch being enforcement intensity divergence between Northwestern and Siberian environmental inspectorates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Danaflex Group's captive polypropylene supply shields margins from import volatility. |
| Mono-Material Barrier Film Development | Atomic layer deposition coatings enable Eurasian Economic Union recyclability compliance. |
| Siberian Federal District Capacity Buildout | Novosibirsk extrusion investments capture unmet demand from remote food processors. |
| Digital Printing Platform Integration | Mid-sized dairy processors adopt variable data insertion for promotional versioning. |
| Approved Vendor List Consolidation | Magnit and X5 Retail Group centralization compresses supplier relationships to certified converters. |
Research Methodology
Cross-validation between primary interviews with film extrusion plant managers, brand owner procurement leads, and Eurasian Conformity certification specialists anchors the qualitative findings, supplemented by secondary validation through Russian Environmental Operator extended producer responsibility filings, customs records for polyamide and metallized polyethylene terephthalate imports, and BIS-aligned laboratory accreditation databases. Bottom-up triangulation across converter capacity utilization rates and top-down reconciliation against retail channel procurement volumes ensures segmentation integrity.
Calibration against historical laminate adoption curves and protein processor cold-chain investment cycles shapes the analytical framework across the projection horizon, with segmentation modeling spanning product type, material construction, end-use application, and Federal District demand cluster. CAGRs derive from volume-weighted average of segment-specific growth trajectories, incorporating Eurasian Economic Union regulatory phase-in schedules and retailer specification consolidation timelines as industry-specific forecast inputs.
Practitioners should monitor Eurasian Economic Union enforcement intensity divergence and mono-material recycling infrastructure buildout for early signals of laminate specification shifts. Forecasts reflect assumptions regarding regulatory timeline adherence and resin import channel stability. Cross-checking against Russian Environmental Operator tariff penalty disclosures and regional environmental inspectorate compliance verification records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Peel Pouches Market
Pouch
Foil Pouch Packaging Market
Pouch
Zipper Pouch Market
Pouch
Inflatable Pouches Market
Pouch
Liquid Pouch Packing Machine Market
Pouch
Slider Pouches Market
Pouch
Child Resistant Pouches Market
Pouch
MAP Flow Wrappers Market
Pouch
Stick Pouches Packaging Market
Pouch
North America Pouch Packaging Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Spain Pouch Packaging Market
Pouch
Digital Printed Pouch Market
Pouch
Italy Pouch Packaging Market
Pouch
UAE Pouch Packaging Market
Pouch
Horizontal Premade Pouch Packing Machine Market