
 USA and Canada Packer Bottle Market | 2026-2036
USA and Canada Packer Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
USA and Canada Packer Bottle Market Analytics
Modular multi-count bottle configurations is consolidating buyer preference as pharmaceutical and nutraceutical contract packers seek to reduce line-changeover frequency and simplify inventory. Berry Global Group Inc. leverages its broad thermoforming portfolio to supply nested packer bottle families across dosage tiers. Amcor Plc anchors North American pharmaceutical packaging through controlled-substance compliant PET and HDPE lines. Comar LLC specializes in small-batch custom molds that serve emerging biologic and compounding pharmacy channels.
Packer bottles are rigid primary containers engineered to dispense solid oral doses, capsules, tablets, and powders, typically manufactured via injection blow molding or extrusion blow molding with dimensional tolerances calibrated to capping-line automation. Their primary commercial purpose centers on product protection, child-resistance compliance, and supply-chain traceability for regulated contents. PET packer bottles dominate unit volume in over-the-counter pharmaceuticals where clarity and barrier performance justify material cost, while HDPE variants lead in institutional and chemical applications where chemical resistance and lower unit economics prevail. Screw cap closures retain the largest installed base though child-resistant and senior-friendly flip-top formats are gaining share in direct-to-consumer channels.
FDA's Drug Supply Chain Security Act mandates unit-level serialization that elevates demand for packer bottles with molded-in datamatrix-ready surfaces and tamper-evident neck finishes. Health Canada's Good Manufacturing Practice guidelines and the EPA's resin identification and recycled content rules for rigid containers jointly shape material selection and supplier qualification timelines. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in California, New York, and Canadian provincial jurisdictions that will increasingly dictate post-consumer recycled content minimums and recyclability design standards.
Market Dynamics
FDA's Drug Supply Chain Security Act serialization mandates are compressing supplier qualification timelines while concentrating procurement among blow-molders capable of integrated datamatrix molding and tamper-evident neck engineering.
Growth Catalysts
- Traceability Mandates:FDA's DSCSA unit-level serialization requirements are elevating demand for packer bottles with molded-in datamatrix-ready surfaces. Contract manufacturers are consolidating procurement to qualified suppliers.
- Great Lakes Manufacturing Corridor:Concentration of pharmaceutical formulators across Michigan, Ohio, and Ontario creates dense demand clusters adjacent to blow-molding facilities.
- Biologics Expansion:Emerging biologic and compounding pharmacy channels are driving small-batch custom mold requirements that favor regional specialists.
Market Restraints
- Resin Cost Volatility:PET and HDPE feedstock prices tied to crude oil and natural gas liquids create margin pressure across injection blow molding operations.
- Extended Producer Responsibility:California, New York, and Canadian provincial frameworks are mandating post-consumer recycled content minimums that strain supply chains.
- Substitution Risk:Blister packaging and strip foil formats are capturing unit-dose pharmaceutical applications where portability outweighs bottle convenience.
Strategic Opportunities
- Underpenetrated Compounding Channel:US compounding pharmacies and 503B outsourcing facilities represent fragmented demand for customizable packer bottle specifications.
- Senior-Friendly Design:Health Canada's accessibility guidelines and US aging demographics are elevating flip-top and easy-open closure formats.
- Recycled Content Technology:Advanced PET decontamination and HDPE compatibilization processes are enabling food-grade and pharmaceutical-grade recycled resin integration.
Industry Challenges
- Tooling Lead Times:Custom injection blow molds for serialized neck finishes require 16-24 week fabrication cycles that conflict with compressed product launch schedules.
- Validation Complexity:FDA process validation and Health Canada GMP compliance for new bottle specifications demand extensive stability testing and line qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA and Canada Packer Bottle Market |
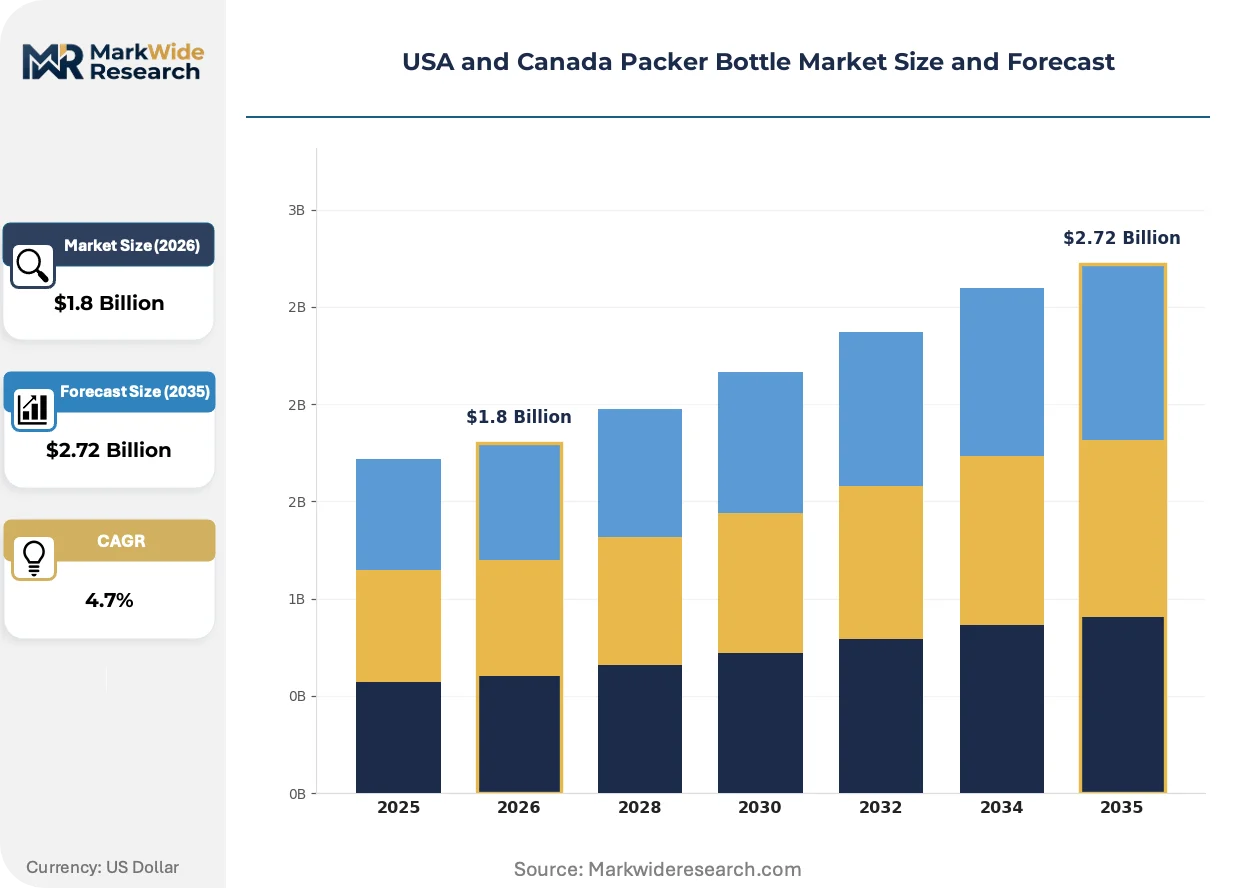
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, PET, HDPE Closure Type: Screw Cap, Flip Top, Dropper Cap, Snap-On Cap End User: Pharmaceuticals, Cosmetics, Food & Beverage, Chemicals Capacity: 50ml, 100ml, 250ml, 500ml |
| Companies Covered | Amcor Plc, Berry Global Group Inc., Gerresheimer AG, Comar LLC, Alpha Packaging, CL Smith, Clarke Container Inc., O.Berk Company, LLC, Graham Packaging Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA and Canada Packer Bottle Market Evolving Landscape
Digital printing and smart packaging integration are transforming how packer bottles communicate supply-chain provenance and patient adherence data, compressing the boundary between primary container and information infrastructure.
Embedded NFC and RFID tag integration is decentralizing authentication and cold-chain monitoring from external packaging to the bottle itself. Pharmaceutical contract packers in Ontario and Michigan are piloting these capabilities for high-value biologics. The technology is decentralizing quality assurance functions from centralized labs to distributed patient and pharmacy touchpoints.
Health Canada's evolving traceability regulations and EPA resin identification rules are jointly mandating design-for-recyclability standards that exceed current US federal requirements. Blow-molders serving cross-border supply chains must engineer dual-compliant specifications. Ontario-based facilities are responding by qualifying rPET streams that satisfy both jurisdictions.
Direct-to-consumer pharmacy channels are compressing traditional wholesale distribution and demanding packer bottles optimized for individual shipper compatibility rather than case-pack efficiency. Amazon Pharmacy and Canadian telehealth platforms are driving this specification shift. The behavioral change is most visible in vitamin and nutraceutical segments across both countries.
USA and Canada Packer Bottle Market Segmentation
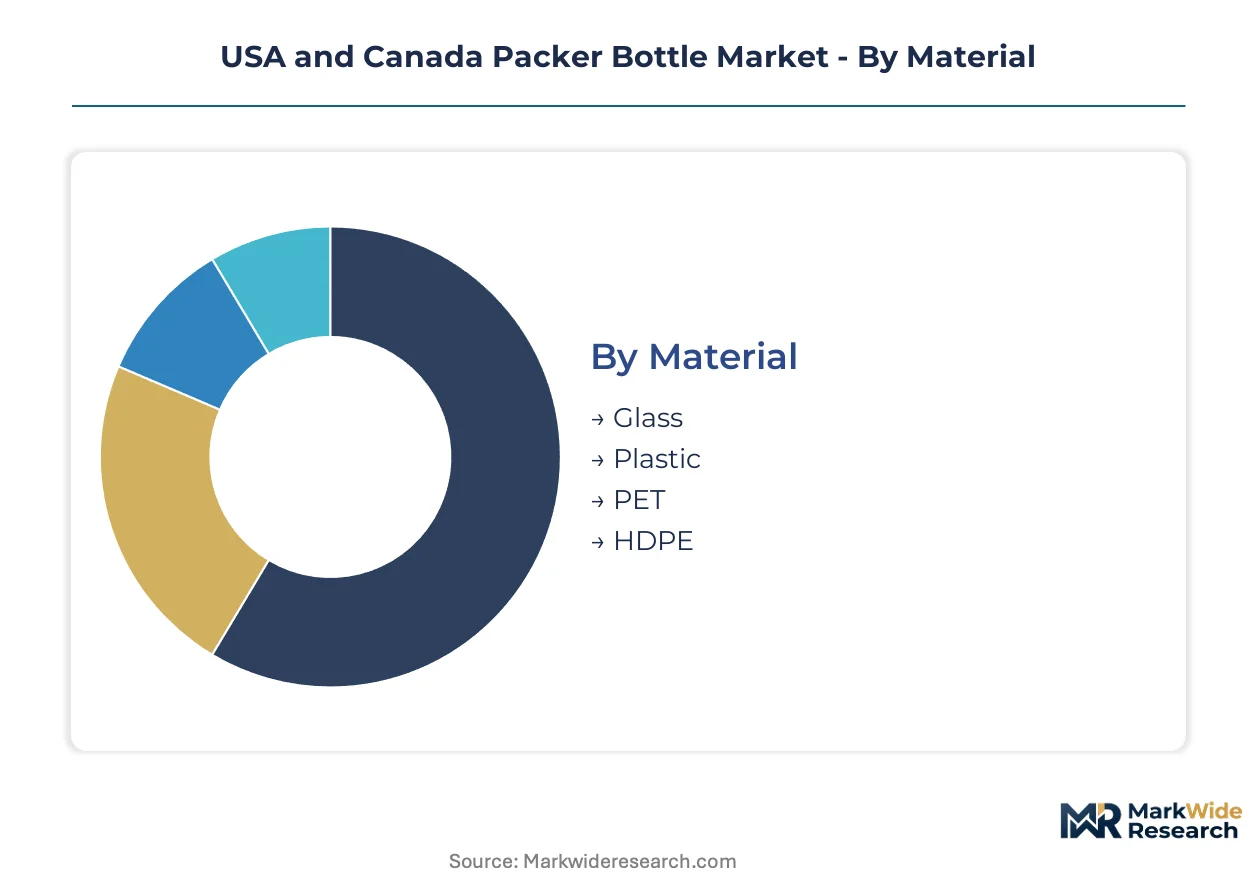
Packer bottle procurement decisions in the USA and Canada hinge on material compliance, closure security, and capacity-line compatibility. Each segmentation dimension carries distinct FDA and Health Canada validation burdens that reshape supplier selection and tooling investments.
Material:
FDA's Type III drug master file requirements and Health Canada's good manufacturing practice standards impose divergent certification timelines across material classes.
- PET:Injection-stretch blow molding delivers optical clarity and moisture barrier performance essential for hygroscopic oral solid doses. Pharmaceutical contract manufacturers in Michigan and Ontario concentrate procurement here for over-the-counter visibility and shelf appeal.
- HDPE:Extrusion blow molding yields chemical resistance and lower unit economics for institutional dispensing and industrial chemical applications. Ohio-based formulators favor this material for controlled-substance storage where opacity and ruggedness outweigh clarity requirements.
- Glass:USP Type I borosilicate and soda-lime compositions serve light-sensitive and oxygen-sensitive formulations requiring inert contact surfaces. The material demands longer lead times for mold qualification and line validation.
- Plastic:Polypropylene and other engineered thermoplastics occupy niche positions where specific chemical compatibility or sterilization tolerance is required.
PET sits at the top of the volume ranking, with HDPE climbing the fastest as institutional channels expand.
Closure Type:
Cost tiers separate commodity screw caps from engineered child-resistant and senior-friendly formats that command tooling premiums and patent royalties.
- Screw Cap:Standard continuous thread designs retain the largest installed base across capping-line automation. The format dominates vitamin and nutraceutical contract packing where cost minimization outweighs convenience features.
- Flip Top:Hinged senior-friendly and child-resistant mechanisms address Health Canada accessibility guidelines and US aging demographics. Direct-to-consumer pharmacy channels in both countries are accelerating specification shifts toward this format.
- Dropper Cap:Calibrated dispensing closures serve liquid and suspension formulations in compounding and 503B outsourcing facilities.
- Snap-On Cap:Press-fit designs for single-use and sample applications where resealability is not required.
Screw cap formats hold the largest revenue share, with flip top variants expanding most quickly through telehealth-driven pharmacy channels.
End User:
Application-specific validation protocols create steep segmentation barriers between pharmaceutical-grade and general industrial supply.
- Pharmaceuticals:Solid oral dose, capsule, and tablet containers requiring FDA drug master file compliance, stability testing, and serialization-ready surfaces. The segment absorbs the majority of custom mold investment and supplier qualification resources.
- Cosmetics:Nutricosmetic and personal care applications where aesthetic differentiation and premium closure mechanics drive specification. California and New York formulators concentrate demand here.
- Food & Beverage:Powdered supplements and functional food formats where GRAS status and migration testing requirements apply.
- Chemicals:Industrial and agricultural chemical storage where UN certification and chemical resistance testing predominate over pharmaceutical protocols.
Pharmaceuticals command the highest margin tier, with cosmetics gaining share fastest through cross-border nutricosmetic expansion.
Capacity:
Volume scale dictates blow-molding equipment configuration and line-changeover economics across contract packaging operations.
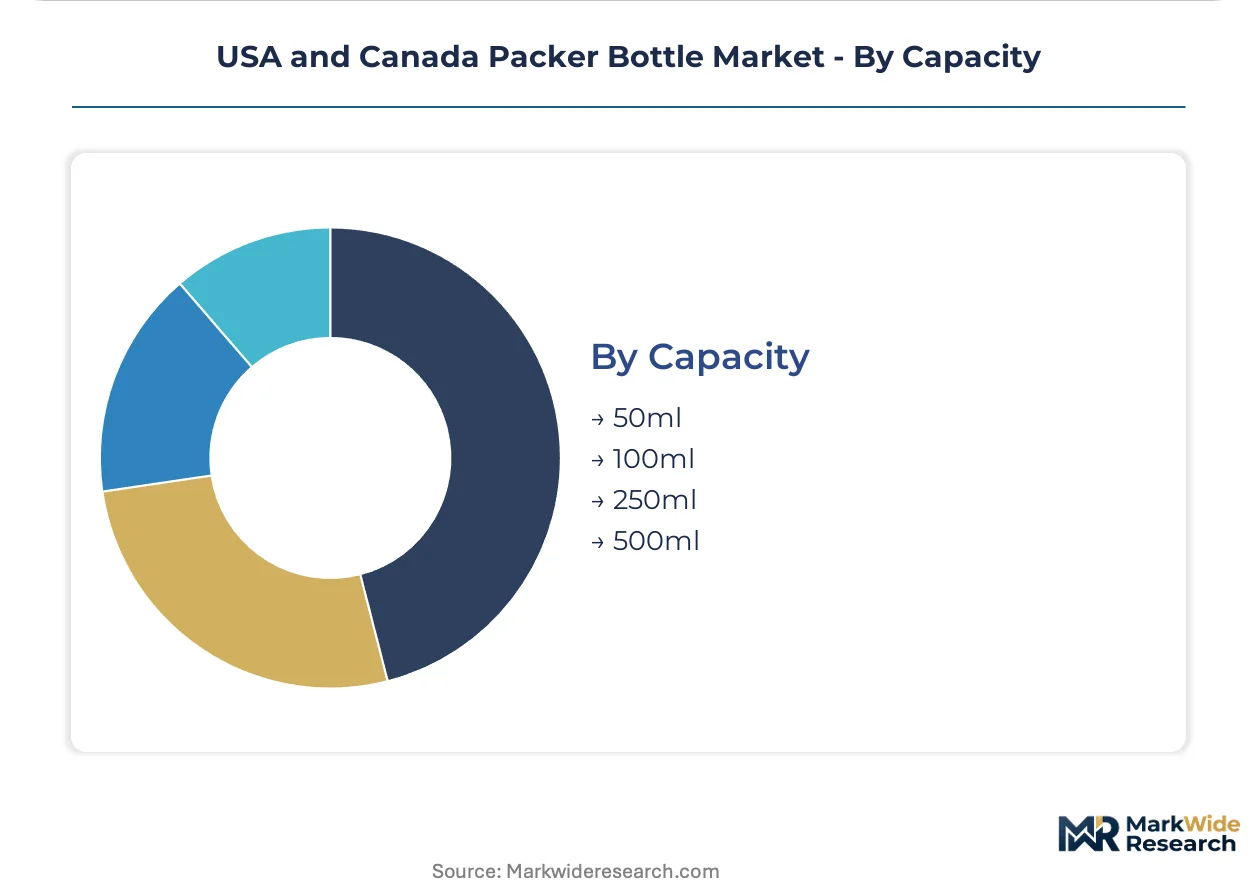
- 100ml:The workhorse format for standard 30-count and 60-count solid oral dose presentations. Great Lakes corridor facilities optimize line efficiency around this capacity point.
- 250ml:Mid-range volume serving 90-count and 120-count prescriptions plus powder formulations. The segment bridges retail pharmacy and institutional dispensing channels.
- 50ml:Compact trial-size and travel-format containers for sample distribution and adherence program packaging.
- 500ml:Bulk institutional and powder applications where case-pack efficiency outweighs individual portability.
100ml formats anchor production volume, with 250ml capacities climbing fastest as 90-day prescription fulfillment expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packer bottle manufacturing in North America traces its industrial lineage to mid-20th century glassworks along the Great Lakes, where proximity to pharmaceutical formulators established enduring supply relationships that persist in today's thermoforming corridor.
United States
Michigan and Ohio anchor domestic blow-molding capacity, with Detroit-area facilities supplying serialized PET containers to pharmaceutical contract manufacturers. FDA's Drug Supply Chain Security Act mandates unit-level traceability that concentrates procurement among blow-molders with integrated datamatrix molding capabilities. The Great Lakes manufacturing corridor generates dense demand clusters adjacent to oral solid dose formulators in Indianapolis and New Jersey.
Canada
Ontario's pharmaceutical packaging sector serves both domestic Health Canada compliance requirements and cross-border FDA-regulated exports. Toronto-area facilities are qualifying rPET streams that satisfy dual-jurisdiction recycled content standards. The province's compounding pharmacy network creates fragmented demand for small-batch custom mold specifications.
Mexico
Querétaro and Tamaulipas states are emerging as nearshore alternatives for US pharmaceutical packagers seeking tariff-advantaged supply chains. The country's national pharmaceutical regulator enforces traceability standards aligned with USMCA pharmaceutical annex provisions. Monterrey-based converters are investing in injection-stretch capacity to serve Texas and California formulators.
Germany
German pharmaceutical packaging specialists supply high-barrier PET and glass configurations to North American markets through established distribution networks. EMA serialization requirements and REACH chemical compliance create specification templates that influence FDA packaging submissions. Bavarian engineering firms license blow-molding automation technology to Michigan and Ohio facilities.
Switzerland
Swiss precision mold-makers provide high-tolerance tooling for serialized neck finishes and tamper-evident closures serving North American biologics packagers. Swissmedic quality standards exceed typical FDA validation thresholds, creating premium-tier reference specifications. Basel-area pharmaceutical clusters export packaging design protocols that shape Michigan contract manufacturer requirements.
USA and Canada Packer Bottle Market Competitive Landscape
Premium-margin players sit above commodity-margin players across serialization capability and custom mold engineering dimensions. The vendor base stratifies into three tiers: integrated multinational converters with captive resin streams, regional specialists serving compounding and 503B channels, and commodity blow-molders competing on unit economics for nutraceutical applications. Dominant competitive moves include backward integration into recycled resin processing and strategic partnerships with pharmaceutical contract manufacturers for co-developed packaging specifications.
Among North American-based fabricators, Amcor Plc and Berry Global Group Inc. exemplify the integrated multinational archetype with broad thermoforming portfolios spanning dosage tiers. Comar LLC occupies a specialist position serving emerging biologic and compounding pharmacy channels with small-batch custom mold capabilities. These three companies anchor the competitive structure that smaller regional converters must navigate through niche specialization or geographic proximity advantages.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Group Inc. |
| Gerresheimer AG |
| Comar LLC |
| Alpha Packaging |
| CL Smith |
| Clarke Container Inc. |
| O.Berk Company, LLC |
| Graham Packaging Company |
| Others |
Value Network & Pricing Analysis
Injection-stretch blow molding automation is compressing unit economics while concentrating procurement power among Great Lakes corridor converters with integrated serialization capabilities. FDA's Drug Supply Chain Security Act elevates tooling premiums for datamatrix-ready neck finishes, bifurcating supplier tiers between qualified pharmaceutical-grade molders and commodity nutraceutical blow-molders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade PET with FDA drug master file compliance from institutional HDPE and generic nutraceutical formats. Price differentiation rests on certification grade and volume scale, with custom mold serialization commanding substantial premiums over catalog specifications. Cost compression in standard-tier HDPE is intensifying because of resin volatility and extended producer responsibility compliance investments. Contract manufacturers in the pharmaceutical segment exhibit lowest price sensitivity, while vitamin packers in direct-to-consumer channels drive aggressive unit economics negotiations.
Supply Chain Analysis
Freight cost advantages from Great Lakes waterway access and cross-border highway corridors anchor supply concentration in Michigan, Ohio, and Ontario. Raw material flows draw from Texas and Alberta petrochemical complexes for virgin resin, with post-consumer rPET streams increasingly sourcing from Ontario collection infrastructure. Single-source vulnerability concentrates in specialized serialization tooling from Swiss and German precision mold-makers. Distribution runs through pharmaceutical contract manufacturing networks and direct-to-consumer pharmacy fulfillment centers rather than traditional wholesale drug channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The USA and Canada Packer Bottle Market functions as a stable compounder anchored by irreversible traceability mandates that embed recurring specification upgrades into pharmaceutical procurement cycles.
For Market Incumbents: Hedge against resin cost volatility through backward integration into rPET processing or long-term offtake agreements with Alberta and Texas feedstock suppliers. Consolidate mold fabrication partnerships with Swiss precision engineering firms to compress 16-24 week tooling cycles that threaten product launch timelines. Defensive positioning requires locking in pharmaceutical contract manufacturer co-development agreements before emerging biologic channels fragment procurement.
For New Entrants and Emerging Players: Health Canada's evolving accessibility guidelines in Ontario open a window for senior-friendly flip-top closure specialists to capture share from legacy screw-cap incumbents. Target the underpenetrated US 503B outsourcing facility segment where small-batch custom specifications favor regional agility over multinational scale. A compounding pharmacy-focused go-to-market strategy with rapid mold turnaround capabilities bypasses entrenched supplier qualification barriers at major OTC contract packers.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional blow-molders with Health Canada GMP compliance and cross-border logistics infrastructure already in place. The five-to-ten-year viability window favors acquisition targets with demonstrated FDA drug master file submissions and active rPET qualification programs. Monitor California and New York extended producer responsibility implementation timelines as the inflection signal for recycled content technology premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Serialization-Ready Mold Investment | FDA DSCSA compliance anchors pharmaceutical contract manufacturer procurement consolidation. |
| rPET Stream Qualification | Dual-jurisdiction compliance with California EPR and Health Canada standards opens premium tier access. |
| Compounding Channel Specialization | Small-batch agility captures fragmented 503B outsourcing facility demand in Michigan and Ohio. |
| Senior-Friendly Closure Development | Health Canada accessibility guidelines and US aging demographics accelerate flip-top specification shifts. |
| Nearshore Mexico Capacity Expansion | Querétaro injection-stretch capacity serves Texas and California formulators with tariff-advantaged supply chains. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical contract manufacturing executives, blow-molding operations directors, Health Canada regulatory consultants, and compounding pharmacy procurement managers with secondary validation from FDA drug master file databases, EPA resin identification rule dockets, and customs trade flow records. Bottom-up capacity modeling across Michigan, Ohio, and Ontario facilities triangulated against top-down pharmaceutical packaging spend estimates.
Segment-weighting approaches distributed volume and value projections across material classes, closure security tiers, end-use applications, and capacity configurations throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporated pharmaceutical serialization mandate phase-in schedules, extended producer responsibility compliance timelines, and biologics pipeline expansion trajectories specific to the Great Lakes manufacturing corridor.
Revisions become necessary when resin cost volatility exceeds historical bands, when Health Canada or FDA accelerate traceability implementation timelines, or when major pharmaceutical contract manufacturers consolidate supplier panels more rapidly than modeled. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Snap Secure Containers Market
Containers
Lift-Off Lid Box Market
Containers
Global Food Containers Market
Containers
Intermediate Bulk Container Liner Market
Containers
Square Pails Market
Containers
Container Market
Containers
Global Multi Pack Carriers Market
Containers
HDPE Crates Market
Containers
PS Containers Market
Containers
Shipping Container Liners Market
Containers
LDPE Containers Market
Containers
Trigger Sprayer Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Americas Container Technology Market
Containers
Disposable Lids Market
Containers
Compartment Trays Market