
 United States Pouch Packaging Market | 2026-2036
United States Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Pouch Packaging Market Insights
E-commerce fulfillment channels are reshaping how pouch packaging specifications travel from converter to brand owner. Amcor Plc leverages its North American film extrusion network to supply pre-qualified structures direct to co-manufacturers. ProAmpac LLC anchors its growth in high-barrier retort pouches for shelf-stable proteins. Glenroy, Inc. specializes in precision-printed flexible packaging for premium personal care brands competing on shelf impact.
United States pouch packaging denotes flexible containers formed from laminated films or papers, typically ranging from two to seven material layers with total calipers between three and twelve mils, engineered to protect contents from moisture, oxygen, and light while enabling efficient filling and consumer access. Stand-up pouches with spout closures command premium positioning in beverages and liquid detergents due to their resealability and dispensing convenience. Retort pouches are gaining structural share in ready-meal applications where aluminum foil barrier layers replace rigid cans. Plastic laminates still dominate material tonnage, though biodegradable films represent the fastest-growing margin pool as California and New York advance packaging waste regulations.
FDA food-contact substance notifications, EPA guidelines on per- and polyfluoroalkyl substances in packaging, and state-level extended producer responsibility frameworks in California, Oregon, and Maine collectively dictate material migration limits, recyclability labeling, and fee structures that shape converter R&D budgets. The USDA BioPreferred program creates procurement preference pathways for bio-based pouch films in federal and institutional purchasing. Stakeholders must monitor how PFAS restrictions propagate across additional state legislatures and whether mechanical recycling infrastructure investments keep pace with flexible format proliferation.
Market Dynamics
State-level extended producer responsibility mandates are forcing converters to redesign multi-layer laminates for mechanical recyclability, compressing development timelines while raising qualification costs for brand owners.
Growth Catalysts
- E-commerce fulfillment:Direct-to-consumer shipping volumes demand lighter, damage-resistant formats that reduce dimensional weight charges. Co-packing clusters in California and the Upper Midwest scale pouch specifications for national CPG distribution.
- PFAS phase-outs:EPA restrictions on per- and polyfluoroalkyl substances in food-contact packaging accelerate migration to fluorine-free barrier coatings. Brand owners pre-qualify alternative structures ahead of state enforcement deadlines.
- Retort pouch substitution:Shelf-stable protein brands replace rigid cans with aluminum-foil barrier laminates to cut shipping cube and enable microwave heating. Co-manufacturers invest in high-barrier filling lines to capture this conversion wave.
Market Restraints
- Resin cost volatility:Ethylene and propylene feedstock swings compress converter margins on polyethylene and polypropylene dominant layers. Long-term supply agreements with Gulf Coast petrochemical producers partially hedge exposure.
- Mechanical recycling incompatibility:Seven-layer laminates containing EVOH and aluminum foil lack end-market offtake under current sorting infrastructure. California's SB 54 fee structures penalize non-recyclable formats.
- Flexible-to-rigid substitution limits:Carbonated beverages and highly acidic products remain captive to glass and aluminum due to CO2 retention and corrosion constraints. Barrier film R&D has not closed this performance gap.
Strategic Opportunities
- USDA BioPreferred procurement:Federal and institutional purchasing preferences create dedicated demand channels for bio-based pouch films. Converters with third-party certification access premium-margin supply contracts.
- Spouted pouch expansion:Liquid detergent and personal care brands adopt resealable dispensing formats previously limited to beverages. Tooling investments for fitment welding equipment create first-mover advantages.
- Post-consumer recycled content:California and Oregon EPR frameworks mandate minimum recycled content thresholds. Early compliance positions converters for brand owner volume commitments as thresholds escalate.
Industry Challenges
- Migration testing backlog:FDA food-contact substance notification queues extend qualification timelines for novel barrier coatings. Brand owners delay line conversions pending regulatory clearance.
- Legacy equipment retrofit costs:Converting assets engineered for three-layer structures require capital-intensive upgrades to handle seven-layer high-barrier laminates. Mid-tier converters face financing constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Pouch Packaging Market |
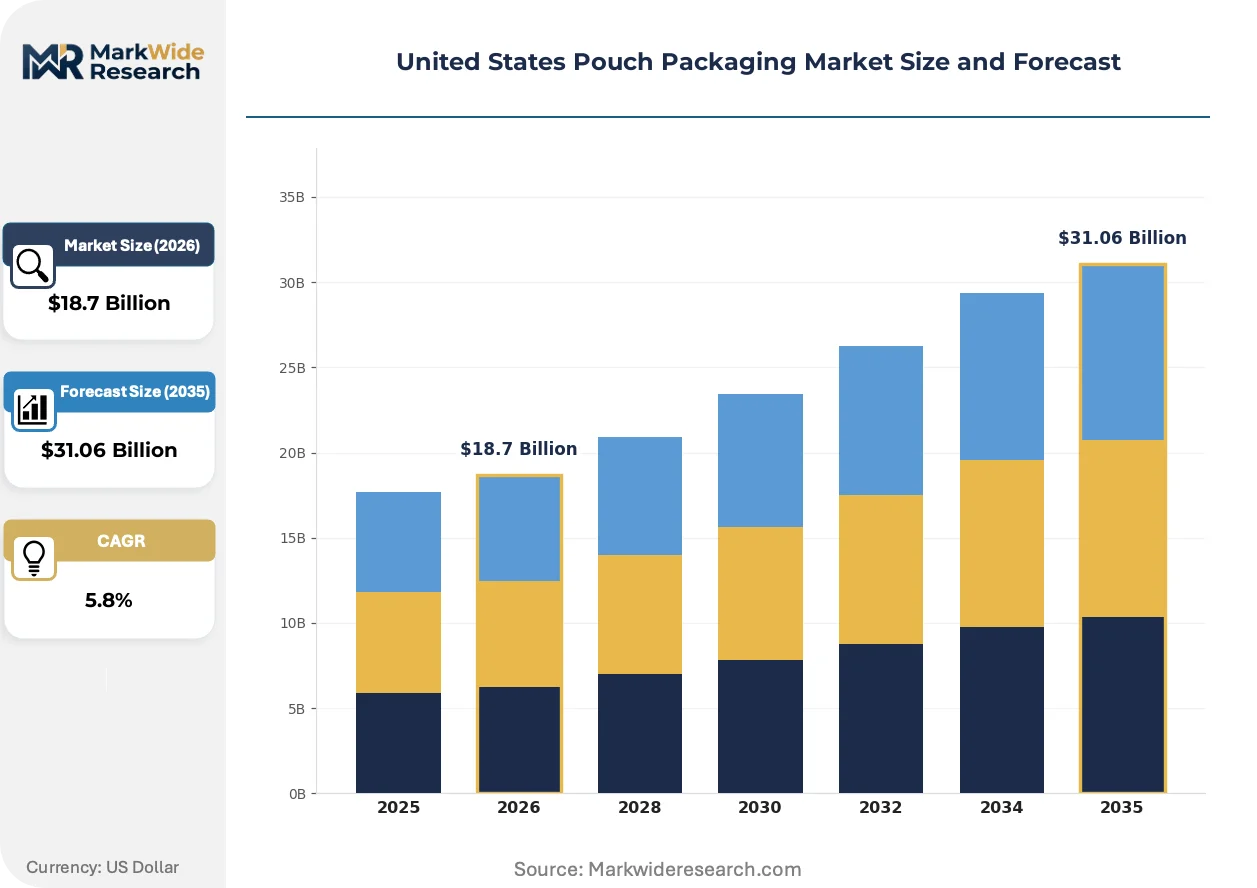
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Gusseted Pouches, Retort Pouches Material: Plastic, Paper, Aluminum Foil, Biodegradable Films Application: Food & Beverages, Cosmetics, Pharmaceuticals, Household Products Closure Type: Zipper, Heat Seal, Spout, Pressure Seal |
| Companies Covered | Amcor Plc, Sonoco Products Company, ProAmpac LLC, Sealed Air Corporation, Mondi Group, Glenroy, Inc., Berry Global Group, Inc., Smurfit Westrock, American Packaging Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Pouch Packaging Market Trends and Innovations
Material science breakthroughs and regulatory pressure are compressing the viable design space for conventional multi-layer laminates, forcing simultaneous innovation in barrier performance and end-of-life pathways.
Mono-material polyethylene structures with plasma-deposited silicon oxide coatings are collapsing the technical justification for aluminum foil in medium-barrier applications. Snack and dry goods brands in the Upper Midwest pilot these formats to preempt California recyclability mandates. The elimination of foil layers enables mechanical recycling streams while maintaining 12-month shelf stability.
EPA enforcement discretion letters on PFAS in food packaging are accelerating fluorine-free barrier chemistry adoption ahead of formal rulemaking. Converters in the Southeast requalify grease-resistant structures using clay-based coatings for quick-serve restaurant chains. Brand owners demand dual-source supply to mitigate single-supplier risk during this transition.
Direct-store-delivery networks are compressing order cycles for pouch packaging from quarterly to monthly replenishment. Regional dairy and beverage co-packers in California adopt digital print workflows to enable SKU proliferation without plate costs. This pattern concentrates demand among converters with hybrid flexographic-digital asset bases.
United States Pouch Packaging Market Segmentation
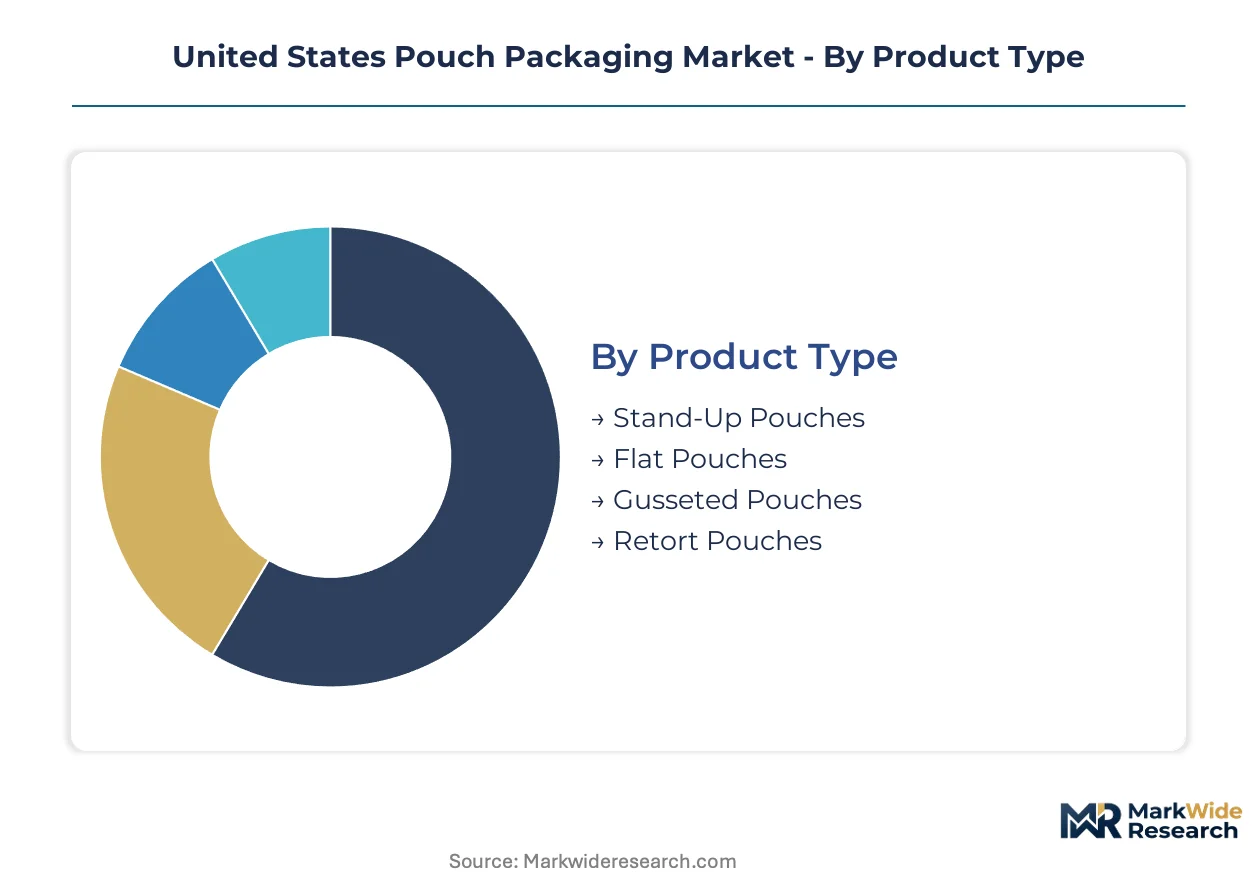
Pouch packaging specifications diverge sharply across end-use requirements, with barrier performance and filling line compatibility dictating converter specialization. Material selection and closure engineering create distinct margin tiers that reshape competitive positioning within each segment cluster.
Product Type:
Mature formats dominate volume throughput while emerging structures capture conversion waves from rigid packaging.
- Stand-Up Pouches:Self-supporting bottom gusset structures with total calipers between four and ten mils enable shelf-stable presentation without secondary cartoning. California beverage co-packers and Upper Midwest dairy processors drive specification proliferation for resealable liquid formats. FDA food-contact qualification timelines compress development cycles for novel barrier laminates.
- Retort Pouches:Aluminum-foil barrier laminates withstand sterilization temperatures while replacing rigid cans in shelf-stable protein applications. Co-manufacturers in the Upper Midwest invest in high-barrier filling lines to capture this substitution wave as shipping cube reductions justify line conversion costs.
- Flat Pouches:Two- or three-side seal structures serve single-serve dry goods and sample applications where minimal material cost outweighs shelf presence requirements.
- Gusseted Pouches:Side-folded expansions accommodate bulk dry goods and institutional foodservice portions with efficient pallet cube utilization.
Stand-up pouches handle the majority of throughput; retort pouches are expanding most quickly on share as protein brands abandon cans.
Material:
Cost tier stratification separates commodity resin laminates from certified bio-based alternatives commanding procurement premiums.
- Plastic:Multi-layer polyethylene and polypropylene laminates with EVOH oxygen barriers constitute the dominant tonnage base. California SB 54 fee structures penalize non-recyclable formats, forcing converters toward mono-material redesigns. Gulf Coast petrochemical supply agreements partially hedge ethylene feedstock volatility.
- Biodegradable Films:PLA and PHA structures certified under USDA BioPreferred protocols access federal and institutional procurement channels. Early compliance positions converters for brand owner volume commitments as California and Oregon recycled content thresholds escalate.
- Paper:Fiber-based structures with polymer barrier coatings serve premium dry goods where tactile differentiation supports shelf positioning.
- Aluminum Foil:Ultra-high barrier layers in retort and pharmaceutical applications face displacement pressure from silicon oxide coated alternatives.
Plastic laminates retain volume leadership; biodegradable films are gaining share fastest as EPR mandates reshape material specifications.
Application:
Customer type concentration creates distinct qualification barriers and margin profiles across end-use segments.
- Food & Beverages:Retort-ready proteins and aseptic beverages demand the most complex barrier engineering. FDA food-contact substance notifications and EPA PFAS restrictions compress development timelines while raising qualification costs. Direct-store-delivery networks in California compress order cycles from quarterly to monthly replenishment.
- Pharmaceuticals:USP Class VI compliance and child-resistant closure integration create regulatory moats that limit converter participation. Precision-printed structures for unit-dose applications command premium positioning.
- Cosmetics:Premium personal care brands compete on shelf impact through precision-printed flexible packaging with metallic effects and soft-touch finishes.
- Household Products:Liquid detergents and cleaning concentrates adopt spouted dispensing formats previously limited to beverages, requiring fitment welding equipment investments.
Food and beverage applications absorb the dominant share of converter capacity; pharmaceuticals are climbing the fastest on margin contribution.
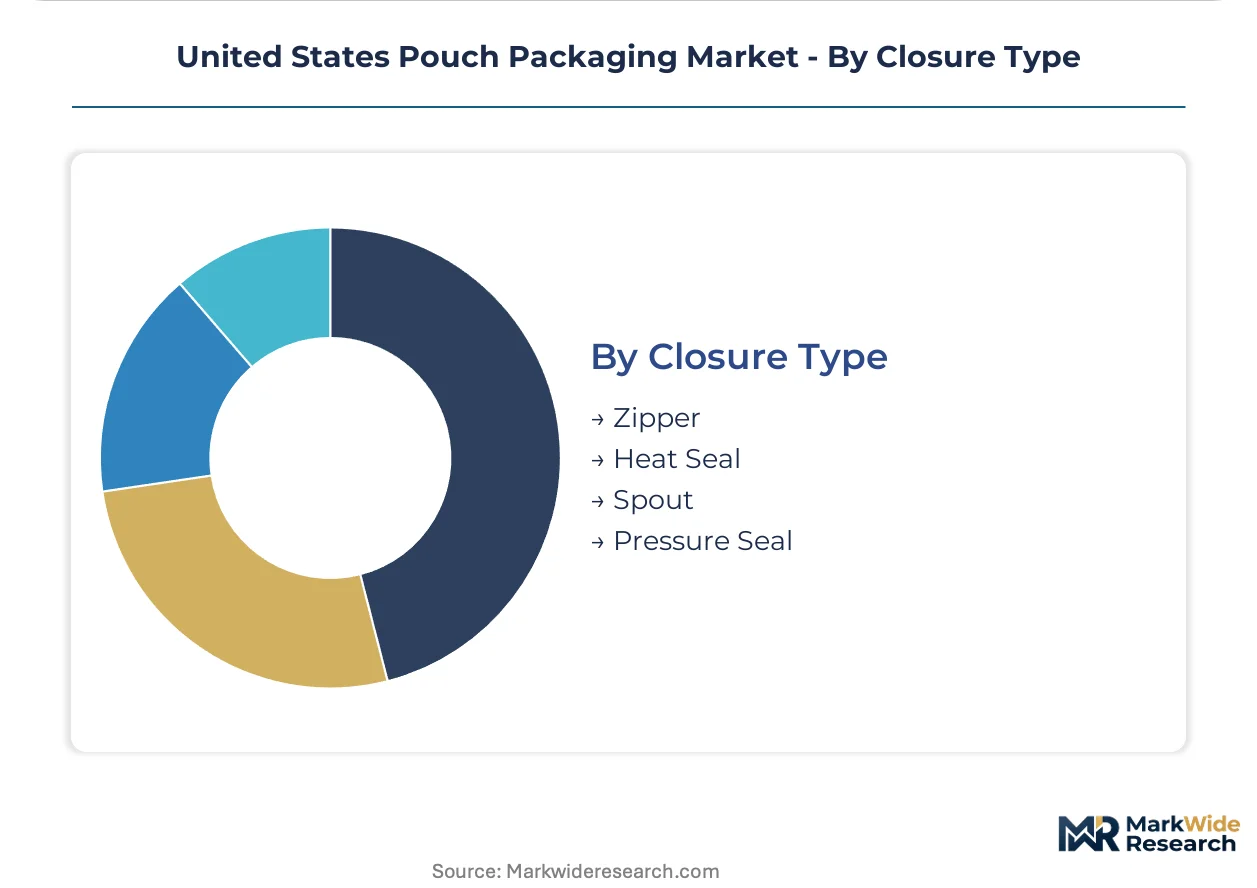
Closure Type:
Volume scale separates high-throughput heat-seal operations from precision fitment assemblies with tooling-intensive setups.
- Heat Seal:Induction and impulse sealing systems dominate dry goods and single-serve applications where resealability is unnecessary. Equipment ubiquity minimizes capital barriers for mid-tier converters.
- Spout:Injection-molded fitments welded to pouch structures enable controlled dispensing for beverages, detergents, and personal care liquids. First-mover tooling investments in California co-packing clusters create regional supply concentration.
- Zipper:Press-to-close profiles add resealability to snack and frozen food formats without specialized filling equipment beyond standard pouch makers.
- Pressure Seal:Cold-seal cohesive coatings serve heat-sensitive confectionery and chocolate applications where thermal exposure risks product integrity.
Heat seal closures process the highest volume throughput; spout fitments are advancing fastest on specification adoption across liquid categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex handles the dominant share of imported flexible film substrates, anchoring West Coast converter supply chains. Interstate rail corridors linking Gulf Coast petrochemical hubs to Upper Midwest co-packing clusters enable just-in-time resin delivery. These infrastructure assets concentrate pouch packaging demand in three distinct sub-regional production zones.
California
Beverage co-packers in the Central Valley and Los Angeles basin drive specification proliferation for resealable liquid formats. State-level SB 54 extended producer responsibility mandates penalize non-recyclable multi-layer laminates, forcing converters toward mono-material redesigns. The Bay Area hosts precision-printing specialists serving premium personal care brands competing on shelf impact.
Upper Midwest
Retort-ready protein processors in Wisconsin and Minnesota replace rigid cans with aluminum-foil barrier laminates to cut shipping cube. FDA food-contact substance notification queues compress development timelines for novel barrier coatings. Chicago-area converting assets scale pouch specifications for national CPG distribution through direct-store-delivery networks.
Southeast
Quick-serve restaurant chains in Georgia and Florida accelerate fluorine-free barrier chemistry adoption ahead of EPA enforcement deadlines. Clay-based grease-resistant coatings gain qualification for food-service applications. Atlanta-based distributors serve regional dairy processors adopting monthly replenishment cycles.
Pacific Northwest
Institutional foodservice operators in Oregon demand biodegradable film certifications under state-level EPR frameworks. USDA BioPreferred procurement preferences create dedicated demand channels for bio-based pouch films. Seattle-area converters pilot post-consumer recycled content laminates to preempt compliance thresholds.
Southwest
Household product brands in Texas adopt spouted dispensing formats for liquid detergents and cleaning concentrates. Fitment welding equipment investments concentrate in Dallas-Fort Worth co-packing clusters. State procurement guidelines increasingly reference federal bio-based purchasing preferences.
United States Pouch Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in film extrusion and precision coating. The United States pouch packaging market structures around three tiers: multinational converters with North American film networks, mid-tier regional specialists, and niche players in certified sustainable formats. Two dominant competitive moves shape positioning: backward integration into resin compounding to hedge feedstock volatility, and strategic partnerships with co-manufacturers to lock in volume commitments for high-barrier retort lines.
Within the multinational tier, Amcor Plc and ProAmpac LLC exemplify divergent specialization vectors. Amcor leverages its integrated North American film extrusion network to supply pre-qualified structures direct to co-manufacturers. ProAmpac anchors its growth position in high-barrier retort pouches for shelf-stable proteins. Glenroy, Inc. occupies a distinct position among precision-printing specialists serving premium personal care brands where shelf impact determines purchasing decisions.
| Leading Market Players |
|---|
| Amcor Plc |
| Sonoco Products Company |
| ProAmpac LLC |
| Sealed Air Corporation |
| Mondi Group |
| Glenroy, Inc. |
| Berry Global Group, Inc. |
| Smurfit Westrock |
| American Packaging Corporation |
| Others |
Pricing and Supply Chain Analysis
Gulf Coast petrochemical clusters anchor resin supply for polyethylene and polypropylene dominant layers, translating feedstock volatility into converter margin compression that reshapes pricing power across the value chain. California SB 54 fee structures on non-recyclable formats force brand owners to absorb qualification premiums for mono-material redesigns, concentrating negotiating leverage among converters with certified sustainable capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USDA BioPreferred-certified bio-based films from commodity multi-layer laminates and spot-market resin conversions. Price differentiation hinges on barrier performance tier and California-compliant recyclability certification. Pricing pressure stems from ethylene feedstock swings compressing margins on polyethylene-dominant structures. National CPG brand owners exhibit highest price sensitivity, while pharmaceutical and premium personal care buyers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Co-manufacturing capacity concentrates in California Central Valley beverage processors and Upper Midwest retort-ready protein facilities, with Chicago-area assets scaling specifications for national distribution. Raw material dependencies center on Gulf Coast ethylene crackers, EVOH barrier resin imports, and aluminum foil supply from domestic rolling mills. Supply chain risk manifests in mechanical recycling infrastructure gaps that strand seven-layer laminate volumes under California EPR penalties. Distribution runs through direct-store-delivery networks compressing replenishment cycles from quarterly to monthly intervals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among national CPG brand owners into co-packing clusters in California and the Upper Midwest has shifted procurement leverage toward volume-aggregated buyers capable of dictating qualification timelines and sustainability specifications.
For Market Incumbents: Insulate margin position through backward integration into Gulf Coast resin compounding to hedge ethylene feedstock exposure, and accelerate FDA food-contact substance notification pre-submissions to compress barrier coating qualification timelines ahead of PFAS enforcement deadlines. Lock in multi-year volume commitments with Upper Midwest retort pouch co-manufacturers before high-barrier filling line capacity saturates. For New Entrants and Emerging Players: Establish a beachhead in USDA BioPreferred-certified bio-based films for federal and institutional procurement channels where incumbent converters lag certification timelines. Target Pacific Northwest dairy and foodservice operators demanding post-consumer recycled content laminates under Oregon EPR frameworks. Lead with digital print workflows enabling monthly SKU proliferation without plate costs. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because state-level extended producer responsibility mandates will progressively penalize non-recyclable formats and reward early mono-material adopters. Acquisition candidates include mid-tier converters with hybrid flexographic-digital assets and pending bio-based certifications. Monitor California SB 54 fee structure implementation pace as the primary inflection signal for compliance-driven volume migration.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Laminate Redesign | California SB 54 compliance unlocks brand owner volume commitments as recyclability thresholds escalate. |
| Fluorine-Free Barrier Coating Qualification | EPA PFAS restrictions position early adopters for quick-serve restaurant chain supply contracts. |
| Spouted Pouch Fitment Welding Investment | Liquid detergent and personal care brands adopt dispensing formats previously limited to beverages. |
| Digital Print Workflow Adoption | Monthly replenishment cycles for direct-store-delivery networks concentrate demand among hybrid asset converters. |
| USDA BioPreferred Certification | Federal procurement preferences create dedicated margin-premium channels for bio-based pouch films. |
Research Methodology
Cross-validation between primary interviews with flexible packaging converters, co-manufacturer operations directors, and CPG brand sustainability leads anchors the qualitative findings against secondary validation from FDA food-contact substance notification databases, EPA enforcement discretion letters, and California SB 54 implementation guidance. Trade data from Gulf Coast petrochemical producers, flexible film import records through the Port of Los Angeles-Long Beach complex, and USDA BioPreferred certified product registries complete the evidentiary base. Bottom-up capacity assessments triangulate with top-down demand modeling across end-use segments.
Calibration against historical resin price volatility patterns and regulatory implementation timelines in comparable packaging markets shapes the projection framework. Segmentation dimensions span product type, material composition, application vertical, and closure configuration, with regional regulatory cluster treated as an orthogonal modeling layer. CAGRs derive from elasticity-adjusted volume trajectories incorporating EPR mandate compliance schedules and retort pouch substitution rates from rigid cans. Feedstock cost assumptions and mechanical recycling infrastructure buildout pace constitute key forecast sensitivities.
Stress conditions across ethylene-propylene spread volatility, PFAS enforcement acceleration, and California recycled content threshold escalation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding co-packing cluster expansion rates and brand owner sustainability procurement timelines. Quarterly review of FDA notification queue lengths, state EPR fee structure adjustments, and Gulf Coast petrochemical outage patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
GCC Retort Pouches Market
Pouch
Heat Sealed Lamination Pouch Market
Pouch
Stand-Up Pouches Market
Pouch
Kraft Pouch Market
Pouch
Liquid Pouch Market
Pouch
Utility Pouches Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Bio PE Pouches Market
Pouch
Morocco Pouch Packaging Market
Pouch
Pouch Equipment Market
Pouch
Box Pouch Market
Pouch
High-Barrier Pouches Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Asia-Pacific Retort Pouch Market
Pouch
Clipless Vertical Pouches Market
Pouch
Clear Pouches Market