
 Canada Pouch Packaging Market | 2026-2036
Canada Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Pouch Packaging Market Insights
Polyethylene terephthalate (PET) and oriented polypropylene (OPP) films is broadening the cost-performance envelope for mid-tier food brands migrating from rigid containers. Amcor PLC leverages its North American extrusion network to supply multilayer barrier films with consistent lead times. Mondi PLC anchors its Canadian position through kraft-paper-based flexible solutions that align with retailer sustainability scorecards. ProAmpac LLC differentiates via specialized retort pouch capabilities serving premium pet food and human meal-kit segments.
Canada pouch packaging denotes flexible, sealed containers fabricated from mono- or multi-layer substrates—typically 2–7 mils thick—formed through horizontal or vertical form-fill-seal processes, designed to protect contents from moisture, oxygen, and light while minimizing material mass versus rigid alternatives. Stand-up pouches with spout closures command the highest value per unit in liquid and semi-liquid applications, while flat pouches dominate dry goods volume due to simpler converting economics and lower freight cube. Retort pouches represent the fastest-expanding product category as brands replace metal cans for ambient soups, sauces, and prepared proteins.
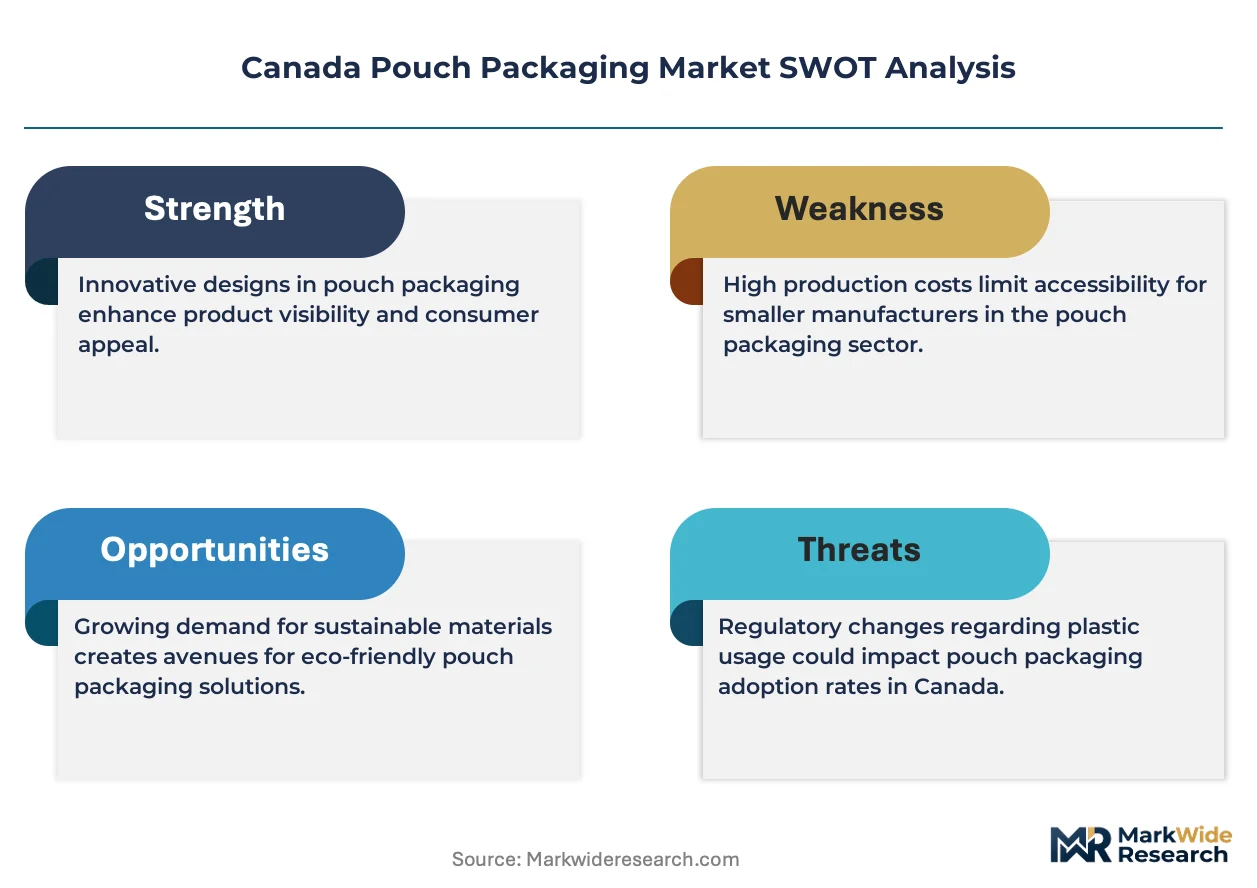
Health Canada and the Canadian Food Inspection Agency enforce migration limits and compositional standards under the Food and Drugs Act, while the Competition Bureau monitors environmental claims under the Competition Act to prevent greenwashing. The Canadian Council of Ministers of the Environment's harmonized extended producer responsibility frameworks are tightening post-consumer collection targets, forcing converters to validate recyclability through third-party certification. Stakeholders must weigh capital allocation between near-term compliant film formulations and longer-term reusable or refillable pouch infrastructures.
Market Dynamics
Health Canada's extended producer responsibility mandates are compressing converter margins while redirecting capital toward recyclable and compostable film structures, fundamentally restructuring procurement priorities across Ontario and Quebec co-packing clusters.
Growth Catalysts
- Retort pouch substitution:Food processors are accelerating migration from metal cans to flexible retort formats for ambient soups and prepared proteins, driven by freight cost reduction and shelf-space efficiency.
- CCME harmonized frameworks:Provincial extended producer responsibility targets are forcing brand owners to validate recyclability through third-party certification, creating pull for mono-material barrier films.
- Paper-laminate innovation:Kraft-paper-based flexible solutions are capturing shelf-space commitments from retailers with sustainability scorecards, particularly in premium dry goods segments.
Market Restraints
- Resin input volatility:Polyethylene and polypropylene price swings compress converter margins on fixed-price annual contracts with CPG brand owners.
- Barrier film supply concentration:North American extrusion capacity for high-oxygen-barrier coextrusions concentrates among limited multinationals, creating lead-time vulnerability for mid-tier brands.
- Compostable performance gaps:Current bio-based films fail to match PET/OPP barrier specifications for shelf-stable proteins, limiting application scope.
Strategic Opportunities
- Atlantic Canada underpenetration:Maritime provinces lack localized co-packing infrastructure for flexible formats, creating white space for regional converter investment.
- Refillable pouch infrastructure:Bulk retail and zero-waste store formats in British Columbia are piloting return-loop systems for liquid detergents and personal care products.
- Smart packaging convergence:Integration of time-temperature indicators with flexible substrates is opening premium positioning for temperature-sensitive nutraceuticals.
Industry Challenges
- Multilayer delamination expertise:Separating incompatible polymer layers for mechanical recycling requires specialized equipment and trained technicians that converters struggle to source.
- Certification timeline compression:Third-party recyclability validation under CCME guidelines demands 12-18 month lead times that misalign with product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Pouch Packaging Market |
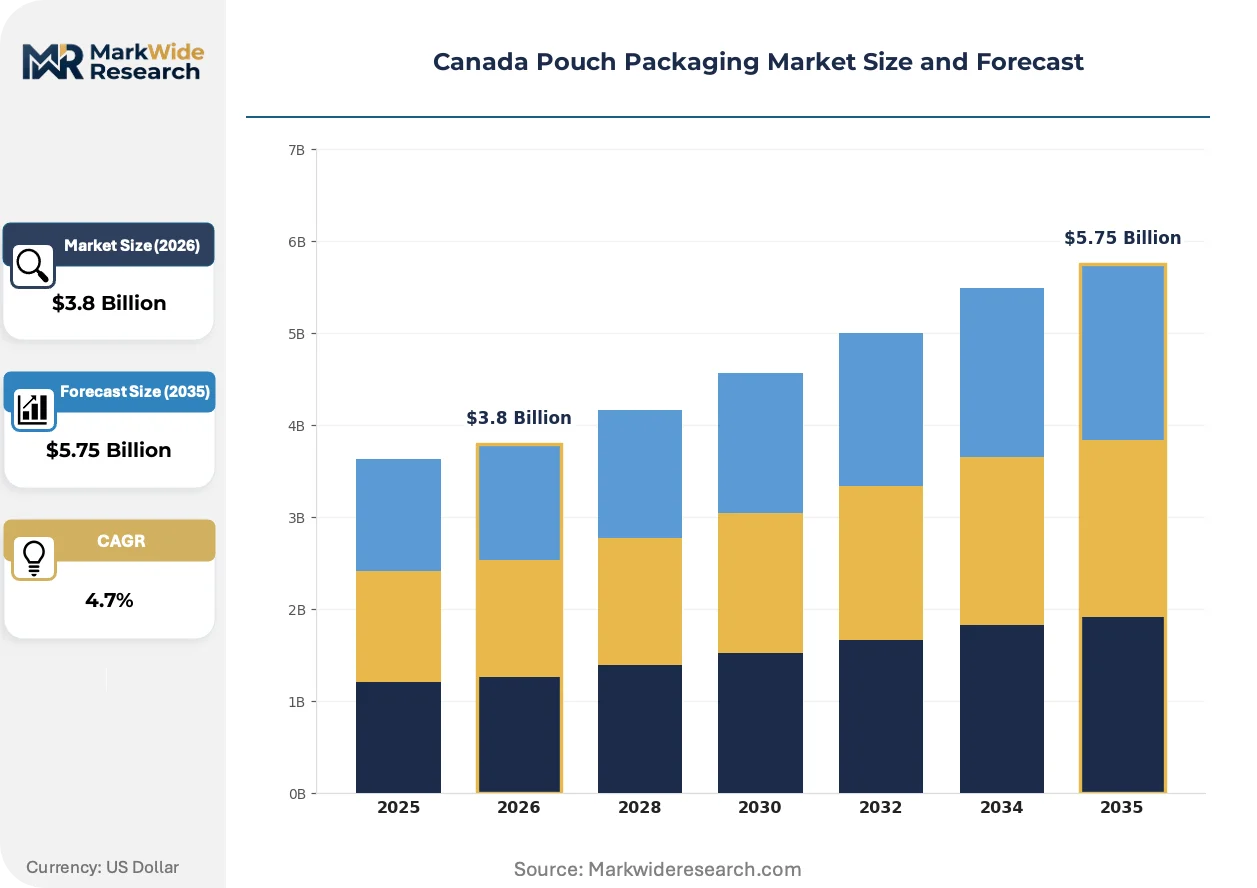
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Vacuum Pouches, Retort Pouches Material: Plastic, Paper, Aluminum Foil, Composites End User: Food & Beverage, Personal Care, Pharmaceuticals, Pet Care Closure Type: Zip Lock, Tear Notch, Spout, Easy Open |
| Companies Covered | Amcor PLC, Mondi PLC, Sonoco Products Company, ProAmpac LLC, Flair Flexible Packaging Corporation, C-P Flexible Packaging Inc., Constantia Flexibles Group GmbH, Emmerson Packaging Holdings Inc, WINPAK Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Pouch Packaging Market Trends and Innovations
Flexible packaging converters are racing to decouple performance from petroleum dependence, deploying novel barrier technologies and circular service models that redefine value capture across the supply chain.
Mono-material polyethylene structures with advanced plasma-deposited silicon oxide coatings are integrating oxygen and moisture barrier properties previously requiring aluminum foil or ethylene vinyl alcohol copolymers. Mid-tier snack and pet food brands in Ontario are adopting these formats at accelerated pace to meet retailer recyclability mandates. This integration is compressing the cost premium between sustainable and conventional multilayer films, eroding the historical three-tier pricing structure.
Health Canada's guidance on reducing plastic content in single-use packaging, aligned with CCME harmonized frameworks, is forcing converters to validate post-consumer collection and reprocessing pathways. The industrial consequence is capital reallocation from incremental film reformulation toward fundamental substrate architecture redesign. Stand-up pouches with spout closures for liquid applications face the steepest compliance burden, driving experimentation with fiber-based alternatives in Vancouver and Toronto pilot markets.
Brand procurement teams are consolidating supplier relationships around converters offering integrated design-to-recycling accountability, displacing transactional spot purchasing. Direct partnerships between CPG headquarters in Montreal and specialized film extruders are replacing distributor intermediaries. This concentration is most visible in ready-to-eat meal segments, where co-manufacturers demand single-source responsibility for format performance and end-of-life compliance.
Canada Pouch Packaging Market Segmentation
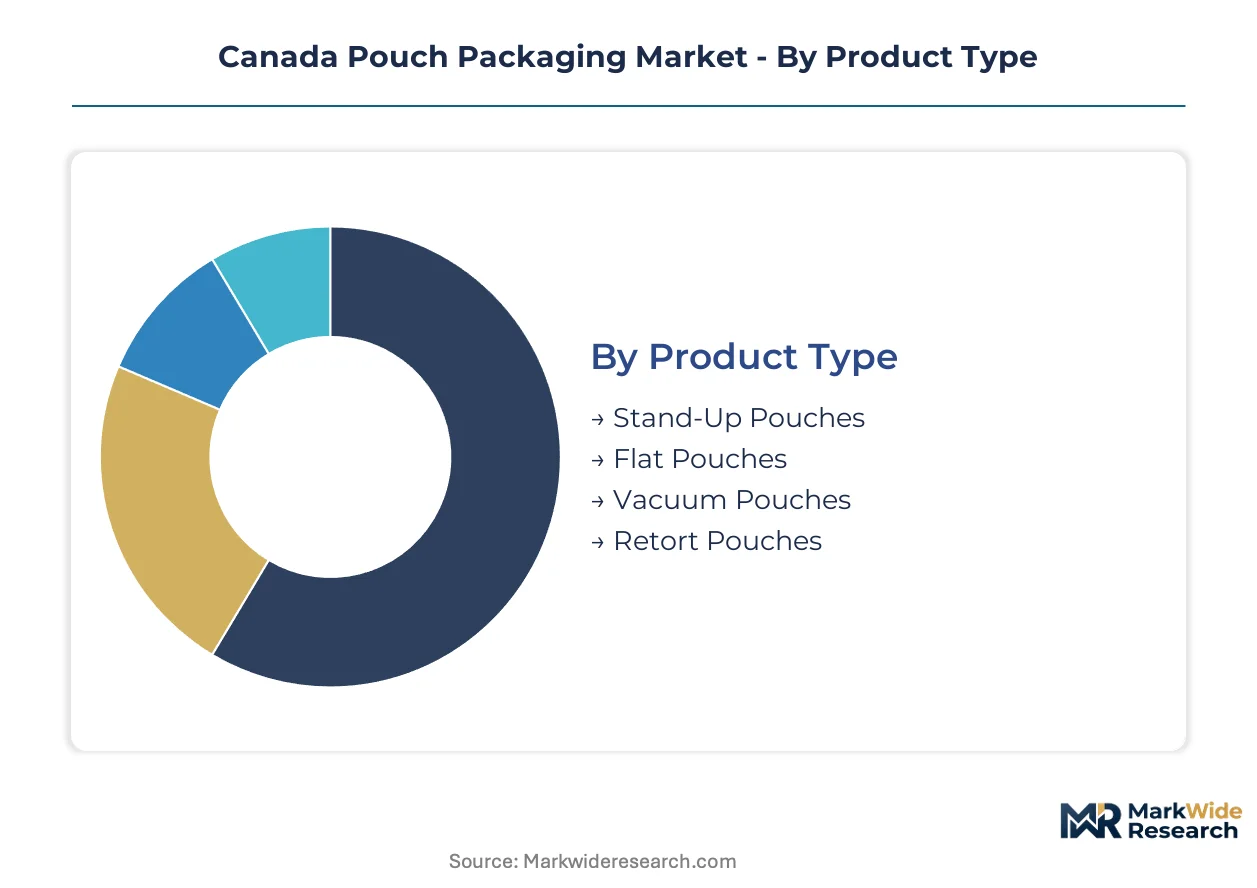
Pouch format selection in Canada hinges on shelf-space economics, barrier requirements, and Health Canada's evolving extended producer responsibility mandates. Converters must align substrate architecture with specific product shelf-life needs while validating end-of-life pathways under provincial harmonized frameworks.
Product Type:
Buyers differentiate primarily by liquid handling requirements and vertical shelf presence needs.
- Stand-Up Pouches:These structures incorporate gusseted bottoms enabling vertical display, typically 4-7 mils thick with multi-layer barrier construction. Demand clusters in Ontario dairy alternatives and British Columbia plant-based beverages, where spout-equipped formats command premium placement in refrigerated sets. Health Canada's scrutiny of single-use plastic spouts is accelerating fiber-based alternative trials in Vancouver and Toronto pilot markets.
- Retort Pouches:Four-layer laminates withstand 121°C sterilization cycles, replacing metal cans for ambient soups and prepared proteins. Quebec food processors are migrating volume fastest, driven by freight cube reduction and retailer shelf-space efficiency mandates. The format's expansion is reshaping co-packing infrastructure investments across Montreal and Toronto corridors.
- Flat Pouches:Simple two- to three-layer structures dominate dry goods volume in Prairie grain handling and Ontario snack distribution.
- Vacuum Pouches:High-barrier coextrusions serve processed meat and cheese segments with oxygen transmission rates below 1 cc/m²/day.
Flat pouches lead volumes today; retort pouches are gaining share fastest.
Material:
Specification choices track directly against CCME recyclability certification timelines and retailer sustainability scorecard deadlines.
- Plastic:Mono-material polyethylene and polypropylene structures, often silicon oxide-coated for barrier, now dominate mid-tier food applications. Ontario snack brands are adopting these at accelerated pace to meet third-party recyclability validation requirements. The shift is compressing cost premiums versus conventional multilayer films.
- Composites:Paper-laminate structures with thin polymer barrier layers capture premium dry goods placement in retailer sustainability programs. Quebec and British Columbia co-packers are prioritizing these for private-label commitments, though delamination complexity challenges mechanical recycling pathways.
- Paper:Uncoated kraft formats serve short-shelf-life bakery and produce applications with minimal barrier demands.
- Aluminum Foil:High-barrier laminates retain dominance in pharmaceutical and premium coffee segments requiring near-zero moisture transmission.
Plastic structures retain volume leadership; composites are climbing the fastest.
End User:
Procurement sophistication varies sharply across sectors, with food safety compliance and claim substantiation requirements driving supplier consolidation.
- Food & Beverage:Shelf-stable proteins, ready-to-eat meals, and dairy alternatives constitute the largest addressable demand pool. Major CPG headquarters in Toronto and Montreal anchor procurement volumes, with co-manufacturers demanding single-source accountability for format performance and end-of-life compliance.
- Pet Care:Premium wet food and treat segments are adopting retort and high-barrier stand-up formats at rates exceeding human food categories. Ontario specialty pet food processors are driving specification innovation for extended shelf-life without preservatives.
- Personal Care:Liquid detergent and body care applications in British Columbia are piloting refillable pouch systems for zero-waste retail formats.
- Pharmaceuticals:Nutraceutical and OTC applications require validated barrier performance with integration potential for time-temperature indicators.
Food & Beverage dominates volume; Pet Care shows the steepest expansion trajectory.
Closure Type:
Functionality requirements and reseal expectations determine specification, with sustainability pressures reshaping spout design priorities.
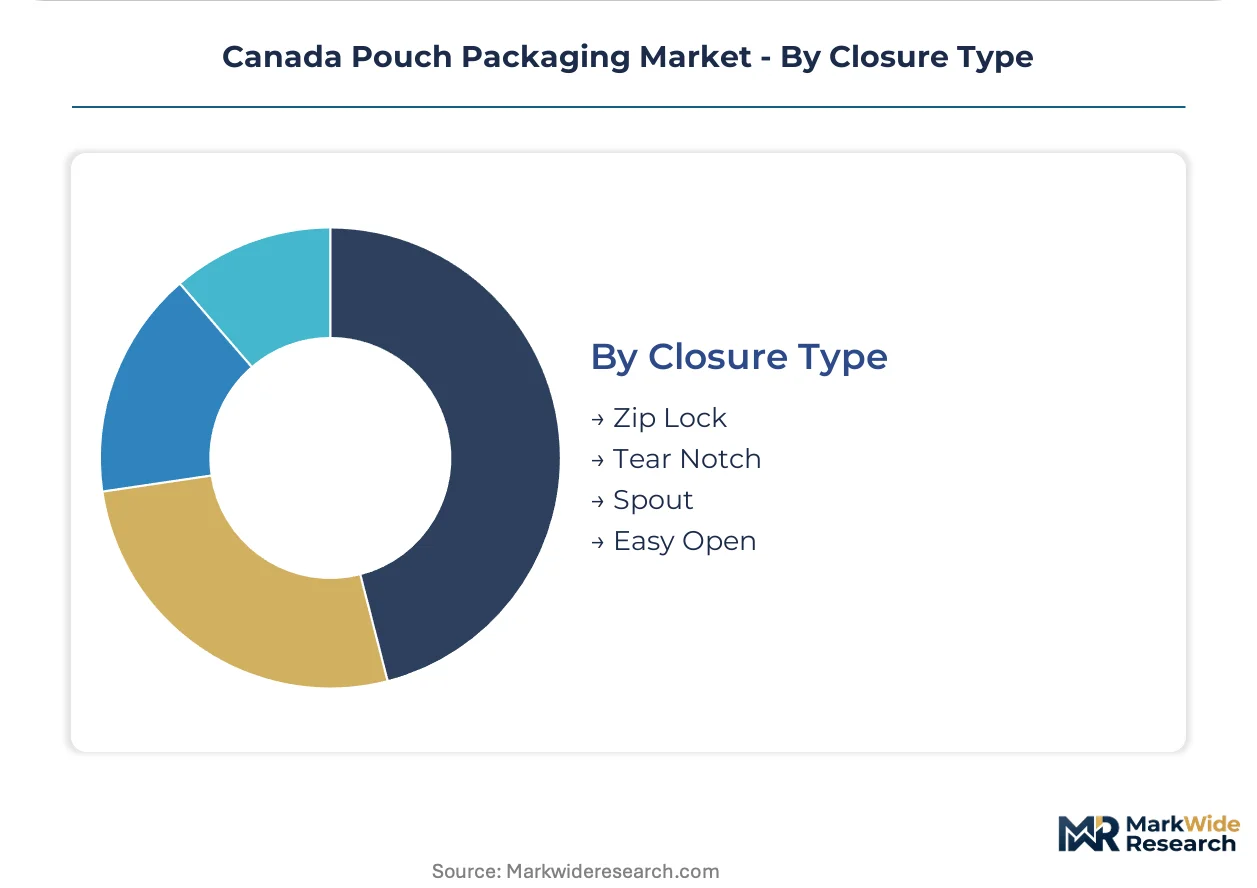
- Spout:Injection-molded fitments enable controlled dispensing for liquids and semi-solids, commanding highest value per unit. Health Canada's plastic reduction guidance is forcing redesign trials in fiber-based alternatives, with Vancouver and Toronto markets hosting pilot programs.
- Zip Lock:Press-to-close profiles serve multi-serve dry goods and resealable snack applications across Ontario and Quebec retail channels.
- Tear Notch:Laser-scored openings provide tamper evidence and controlled initial access for single-serve portions.
- Easy Open:Frangible seals and directional tear features address aging demographic needs and convenience positioning.
Zip lock closures lead current volumes; spout formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's Golden Horseshoe corridor anchors Canadian pouch packaging demand through Toronto's concentration of CPG headquarters and Mississauga-Brampton co-packing clusters.
Ontario
Ready-to-eat meal processors and dairy alternative brands drive specification innovation for spout-equipped stand-up pouches. Health Canada's extended producer responsibility consultations under CCME frameworks are accelerating mono-material polyethylene adoption among snack manufacturers. Toronto's co-packing corridor is consolidating supplier relationships around converters offering integrated recyclability certification.
Quebec
Retort pouch migration from metal cans dominates procurement priorities among Montreal-area soup and prepared protein processors. The province's harmonized EPR regulations are tightening post-consumer collection targets faster than national baselines. Laval and Longueuil industrial zones are attracting film extrusion investment to serve private-label commitments.
British Columbia
Zero-waste retail formats in Vancouver are piloting refillable pouch systems for liquid detergents and personal care applications. The province's single-use plastic reduction mandates are forcing fiber-based spout alternatives into commercial trials. Lower Mainland distribution hubs are prioritizing paper-laminate structures for premium dry goods placement.
Alberta
Prairie grain handling and pet food processing anchor flat pouch and high-barrier vacuum format demand. The province's plastics diversion targets lag Ontario and Quebec, preserving conventional multilayer film specifications. Calgary's logistics infrastructure supports distribution economics for bulk flexible packaging procurement.
Atlantic Canada
Maritime provinces lack localized co-packing infrastructure for flexible formats, creating white space for regional converter investment. Nova Scotia and New Brunswick food processors currently ship products to Ontario and Quebec for pouch filling. Halifax's port capacity offers import advantages for European film substrate sourcing.
Canada Pouch Packaging Market Competitive Landscape
Global majors compete with regional champions across substrate technology and sustainability certification capabilities. The vendor base concentrates around multinationals with North American extrusion networks and mid-tier Canadian specialists with retort and barrier film expertise. Three archetypes dominate: integrated multinational converters with polymer supply chain control, regional flexible packaging specialists with co-manufacturing relationships, and paper-based substrate innovators targeting retailer sustainability scorecards. Competitive moves center on mono-material barrier film R&D partnerships and third-party recyclability certification acquisition.
Within the multinational tier, Amcor PLC and Mondi PLC occupy anchor positions through their respective plastic and fiber-based platform breadth. ProAmpac LLC exemplifies the North American specialist archetype with concentrated capabilities in high-barrier applications. These three entities represent the competitive spectrum from global scale to segment-specific technical depth that defines procurement options for Ontario and Quebec brand owners.
| Leading Market Players |
|---|
| Amcor PLC |
| Mondi PLC |
| Sonoco Products Company |
| ProAmpac LLC |
| Flair Flexible Packaging Corporation |
| C-P Flexible Packaging Inc. |
| Constantia Flexibles Group GmbH |
| Emmerson Packaging Holdings Inc |
| WINPAK Ltd. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between third-party validated mono-material films and conventional multilayer structures manifests in both procurement premiums and converter sourcing strategies across Ontario and Quebec co-packing corridors. Health Canada's CCME-aligned extended producer responsibility timelines compress this bifurcation, forcing brand owners to pay recyclability premiums or absorb compliance penalties while extrusion capacity concentrates among North American multinationals.
Pricing Analysis
Resin input pass-through mechanisms dominate converter pricing models, with polyethylene and polypropylene volatility transmitted through annual fixed-price contracts to CPG brand owners. Three-tier pricing structure across premium, standard, and economy levels reflects barrier performance grade and third-party recyclability certification status. Pricing pressure stems from Health Canada's plastic reduction mandates accelerating substrate redesign cycles. Mid-tier snack brands exhibit highest price sensitivity, while premium pet food and nutraceutical segments absorb certified-film premiums with minimal volume elasticity.
Supply Chain Analysis
Reverse-logistics infrastructure for post-consumer pouch collection remains underdeveloped, forcing converters to front-load recyclability validation costs without guaranteed reprocessing pathways. Extrusion capacity concentrates in the United States, Canada, and Mexico, with barrier film coextrusion drawing from specialized North American facilities. Raw material dependencies center on polyethylene resins, silicon oxide barrier coatings, and kraft paper substrates. Single-source vulnerability concentrates in high-oxygen-barrier coextrusion supply. Distribution runs through Toronto-Montreal co-packing clusters serving CPG headquarters procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's pouch packaging market operates as a regulatory compounder where Health Canada's extended producer responsibility mandates under CCME frameworks continuously intensify compliance burdens and redirect capital allocation.
For Market Incumbents: Hedge against resin price volatility through backward integration into polymer compounding or long-term offtake agreements with Alberta petrochemical producers. Consolidate supplier relationships around single-source accountability for format performance and end-of-life compliance to defend against emerging mono-material specialists. Prioritize certification investment ahead of retailer sustainability scorecard deadlines to lock in shelf-space commitments. For New Entrants and Emerging Players: Direct-to-brand digital procurement platforms bypass established distributor intermediaries and capture mid-tier food brands seeking transparent recyclability documentation. Atlantic Canada presents the most penetrable geography, with Maritime food processors currently shipping to Ontario and Quebec for pouch filling. Target retort pouch co-manufacturing partnerships with Quebec soup and prepared protein processors as the fastest path to volume scale. For Investors and Strategic Acquirers: Consolidation pressure builds where CCME certification timelines misalign with product launch cycles, stranding mid-tier converters without validated recyclability pathways. Long-term viability favors converters with integrated design-to-recycling accountability and captive extrusion capacity. Monitor third-party recyclability certification acquisition velocity as the primary inflection signal for procurement relationship stability.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Film R&D Partnership | Silicon oxide coating integration enables PET/OPP replacement while meeting Health Canada migration limits. |
| Third-Party Recyclability Certification Acquisition | CCME validation secures retailer sustainability scorecard compliance and procurement relationship consolidation. |
| Atlantic Canada Co-Packing Infrastructure Investment | Halifax port access reduces European substrate import costs for Maritime food processors. |
| Refillable Pouch Return-Loop System Pilot | British Columbia zero-waste retail formats test circular service models for liquid detergent applications. |
| Retort Pouch Co-Manufacturing Capacity Expansion | Quebec soup processors accelerate metal can substitution driving equipment utilization premiums. |
Research Methodology
Multiple input streams — converter production data, CPG procurement pattern analysis, and regulatory filing documentation — were reconciled through bottom-up and top-down triangulation. Primary interviews with flexible packaging plant managers, brand sustainability officers, retailer category buyers, and film extrusion technical directors were validated against secondary sources including Health Canada guidance documents, CCME framework harmonization reports, Canadian Food Inspection Agency migration limit standards, and customs trade data on resin imports.
Historical volume trajectories were cross-referenced against expert panel input on substrate substitution timelines to construct projection scenarios across the analysis window. Segmentation dimensions modeled include pouch format type, material substrate architecture, end-use application, and closure mechanism. CAGRs were derived from elasticity-adjusted demand curves incorporating EPR mandate phase-in schedules. Forecast inputs encompassed resin price volatility indices and retailer sustainability scorecard adoption rates.
The model assumes a particular technology adoption path; alternative pathways for fiber-based spout commercialization would alter the outlook for stand-up pouch format share. Forecasts reflect assumptions about CCME collection target achievement and third-party certification timeline compression. Practitioners should monitor Health Canada single-use plastic guidance revisions and provincial EPR harmonization progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Pouches Market
Pouch
MAP Flow Wrappers Market
Pouch
Brazil Pouch Packaging Market
Pouch
Liquid Pouch Packing Machine Market
Pouch
Foil Pouch Packaging Market
Pouch
Heat Seal Pouch Market
Pouch
Spout and Non-Spout Liquid Pouch Packaging Market
Pouch
Foil Zipper Bags Market
Pouch
Doy Pouch Packaging Market
Pouch
Indonesia Pouch Packaging Market
Pouch
Liquid Pouch Packaging Market
Pouch
Kraft Pouch Market
Pouch
PCR Pouches Market
Pouch
Slider Zipper Pouch Market
Pouch
Box Pouch Market
Pouch
Vacuum Chamber Pouches Market