
 Pre-Made Pouch Packaging Market | 2026-2036
Pre-Made Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Made Pouch Packaging Market Outlook
Retail shelf-space allocation is fragmenting as e-commerce fulfillment centers and convenience store chains demand different pouch formats and case counts. Amcor leverages its global converting footprint to supply both channels from regional plants. Mondi Group anchors European demand through integrated paper-based barrier solutions. ProAmpac specializes in high-barrier retort structures for shelf-stable protein applications.
Pre-made pouch packaging consists of flexible containers manufactured off-line from multi-layer films or laminates, typically incorporating polyethylene, polyester, aluminum oxide, or ethylene vinyl alcohol barrier layers, then filled and sealed by brand owners or contract packers. These structures reduce material weight versus rigid alternatives while extending product shelf life through controlled oxygen and moisture transmission rates. Stand-up pouches capture the largest volume share across food and beverage applications, where spout-equipped formats command premium positioning in infant nutrition and sports drinks. Retort pouches represent the fastest-expanding material-design segment, driven by ambient meal replacement and pet food brands seeking metal-can replacement without sacrificing sterilization compatibility. Composites dominate material value due to their tunable barrier properties, though paper-based laminates gain share in dry goods where moisture sensitivity permits.
FDA food contact substance notifications govern barrier layer approvals in the United States, while EFSA evaluates migration limits for recycled content incorporation under evolving EU circularity mandates. REACH compliance constrains adhesive and ink chemistries available to European converters, pushing formulation shifts toward water-based systems. Stakeholders must monitor emerging extended producer responsibility fee structures and decide whether to internalize recycling infrastructure or absorb pass-through costs from resin suppliers.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates for recyclable mono-material structures are forcing converters to dismantle multi-layer barrier architectures and rebuild supply chains around compatible sealing layers and sorting infrastructure.
Growth Catalysts
- Retort-compatible mono-materials:Advances in high-temperature polyethylene and polypropylene coextrusion enable metal-can replacement in ambient meal applications without sacrificing sterilization performance.
- German converting cluster density:Machinery suppliers and brand owners co-locate near major converting hubs, compressing equipment lead times and accelerating format innovation cycles.
- EU circularity mandates:Extended producer responsibility fee structures under PPWR create direct economic pull for recyclable pouch structures versus legacy composites.
Market Restraints
- Aluminum oxide barrier cost volatility:Sputtered barrier deposition requires vacuum metallization equipment with long replacement cycles, exposing converters to energy-intensive process cost swings.
- Ethylene vinyl alcohol supply concentration:EVOH resin production clusters in Japan and Belgium, creating geographic single-point vulnerability for oxygen barrier specifications.
- Migration limit stringency:EFSA evaluation timelines for recycled content incorporation extend 18-24 months, delaying circular material qualification.
Strategic Opportunities
- Indian organized retail expansion:Modern trade format growth in Mumbai and Delhi creates first-mover positioning for spout-equipped pouch formats in edible oils and dairy.
- Paper-based barrier convergence:Integration of fiber substrates with water-based barrier coatings captures dry goods segments where moisture sensitivity permits material substitution.
- E-commerce fulfillment specialization:Direct-to-consumer protein powder and infant nutrition brands demand case-count flexibility and damage-resistant pouch geometries absent from retail-optimized formats.
Industry Challenges
- Multi-layer delamination expertise:Separating incompatible polymers for chemical recycling requires mechanical engineering and polymer science skill sets scarce in conventional converting workforces.
- Water-based adhesive validation:REACH-compliant formulation shifts demand 12-18 month requalification cycles for bond strength and heat-seal performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Made Pouch Packaging Market |
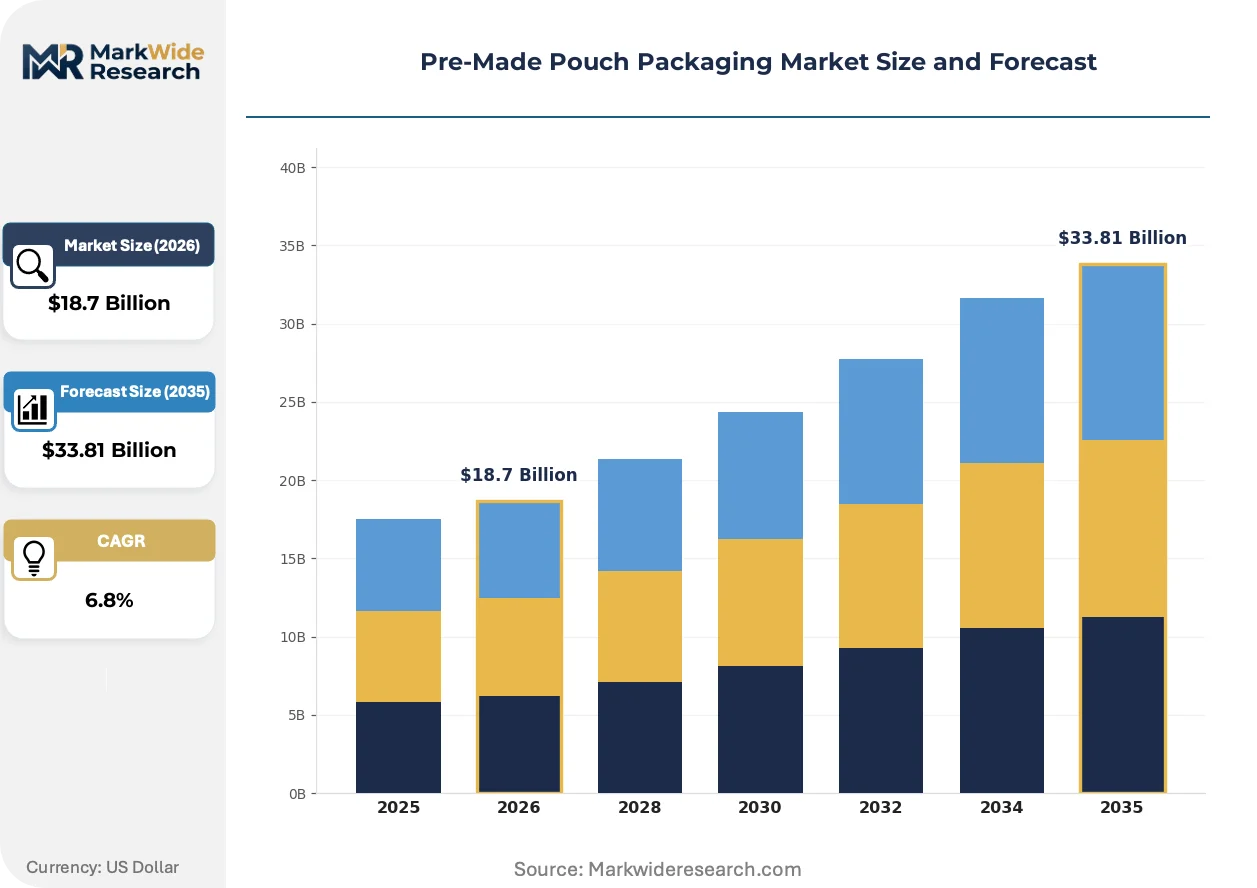
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Pouches, Flat Pouches, Gusseted Pouches, Retort Pouches Material: Plastic, Aluminum, Paper, Composites End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Closure Type: Zip Lock, Spout, Heat Seal, Tear Notch |
| Companies Covered | Amcor, Mondi Group, Berry Global, Sealed Air Corporation, Sonoco Products Company, ProAmpac, Huhtamaki, Constantia Flexibles, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Made Pouch Packaging Market Strategic Shifts
Active barrier technologies and digital printing integration are compressing development cycles while regulatory deadlines force material architecture decisions before full performance validation.
Mono-material barrier films incorporating chemically recycled polyethylene and polypropylene are hybridizing oxygen and moisture protection previously delivered by aluminum laminates. Pet food manufacturers and ambient meal brands in Germany and the Netherlands adopt these structures fastest, accepting 10-15% shelf-life tradeoffs for recyclability claims. The technology is hybridizing converter business models toward integrated resin recycling partnerships rather than arm's-length commodity purchasing.
REACH Article 33 disclosure requirements for substances of very high concern now extend to printing inks and adhesives throughout the EU. Converters face reformulation mandates that eliminate solvent-based systems entirely by 2027, pushing capital allocation toward water-based and UV-curable alternatives. German and Italian packaging printers absorb the steepest compliance costs given their legacy equipment bases and export exposure to EEA markets.
Brand-owner technical buyers now specify pouch formats by fulfillment channel rather than universal retail optimization. Convenience store chains demand smaller case counts and vertical display geometries, while e-commerce fulfillment centers prioritize damage-resistant structures and right-sized void fill. Food and beverage manufacturers in the United States and France fragment their SKU architectures fastest, running parallel production lines for channel-specific pouch specifications.
Pre-Made Pouch Packaging Market Segmentation
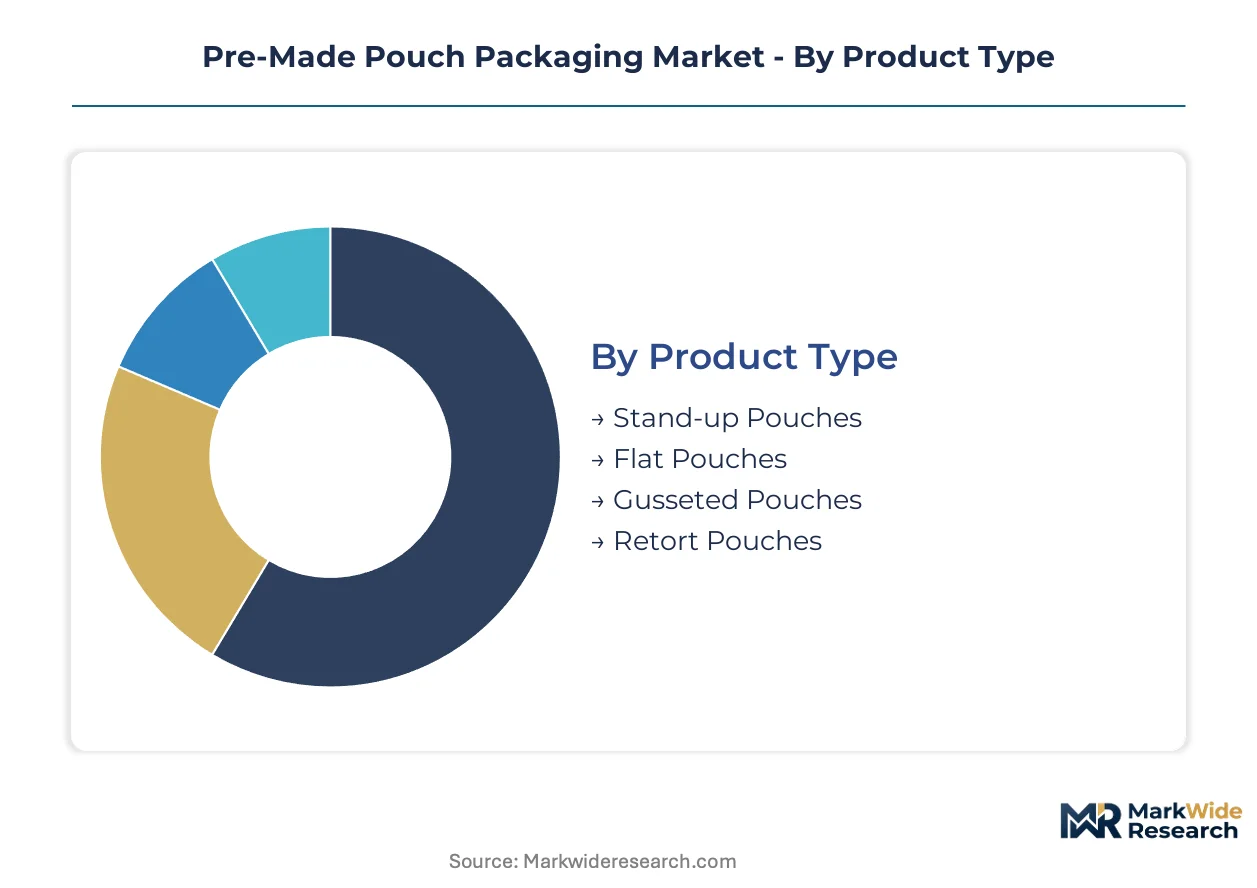
Pre-made pouch packaging serves divergent functional requirements across sterilization cycles, shelf stability, and consumer convenience. Manufacturers configure material architectures and closure systems to match specific barrier demands and filling equipment constraints. Each segmentation dimension carries distinct supply chain implications for converters and brand owners.
Product Type:
Format selection tracks filling speed requirements and retail display geometry across ambient meal, beverage, and dry goods applications.
- Stand-up Pouches:These structures incorporate bottom gussets that enable vertical shelf presentation while minimizing material weight versus rigid alternatives. Spout-equipped variants dominate infant nutrition and sports drink applications in Germany and the Netherlands, where brand owners prioritize premium positioning and resealability.
- Retort Pouches:Multi-layer laminates engineered for high-temperature sterilization cycles enable metal-can replacement in shelf-stable protein and pet food segments. Ambient meal brands in Germany adopt these formats fastest, accepting shelf-life tradeoffs for material efficiency and logistics cost reduction.
- Flat Pouches:Two-dimensional structures serve single-serve condiments and sample portions where shipping cube efficiency outweighs display requirements.
- Gusseted Pouches:Side-folded expansions accommodate volume fluctuations in dry goods and bulk ingredients while maintaining pallet stability.
The dominant share belongs to stand-up pouches, while retort pouches are closing the gap fastest.
Material:
Cost tier and recyclability mandates reshape procurement priorities as EU circularity deadlines approach.
- Composites:Multi-layer structures combining polyethylene, polyester, and aluminum oxide deliver tunable oxygen and moisture barriers for high-sensitivity applications. These materials face dismantling pressure under PPWR mono-material mandates, forcing converters toward chemically recycled polyethylene alternatives.
- Plastic:Mono-material polyethylene and polypropylene films enable mechanical recycling compatibility but require advanced coextrusion to match composite barrier performance. German converters lead qualification cycles for retort-compatible mono-material structures.
- Paper:Fiber-based laminates with water-based barrier coatings capture dry goods segments where moisture sensitivity permits material substitution, particularly in French and Italian markets with paper-forward retail positioning.
- Aluminum:Foil laminates retain niche applications requiring absolute light and oxygen exclusion, though sputtered deposition costs constrain volume expansion.
Composites retain the largest value position, though plastic is expanding most quickly as recyclability specifications harden.
End User:
Customer type determines barrier specification stringency and regulatory compliance burden.
- Food & Beverage:Sterilization compatibility and migration limit compliance dominate technical specifications, with FDA food contact notifications governing US approvals and EFSA evaluating recycled content incorporation timelines.
- Pharmaceuticals:Child-resistant features and tamper-evident seals add regulatory layers beyond food-grade requirements, extending qualification cycles.
- Personal Care:Chemical resistance and aesthetic surface properties drive material selection for cosmetics and hygiene products.
- Household Products:Cost minimization and chemical compatibility predominate in cleaning and laundry applications with lower barrier demands.
Food & Beverage commands the dominant volume position, while Pharmaceuticals shows the steepest expansion trajectory as unit-dose formats proliferate.
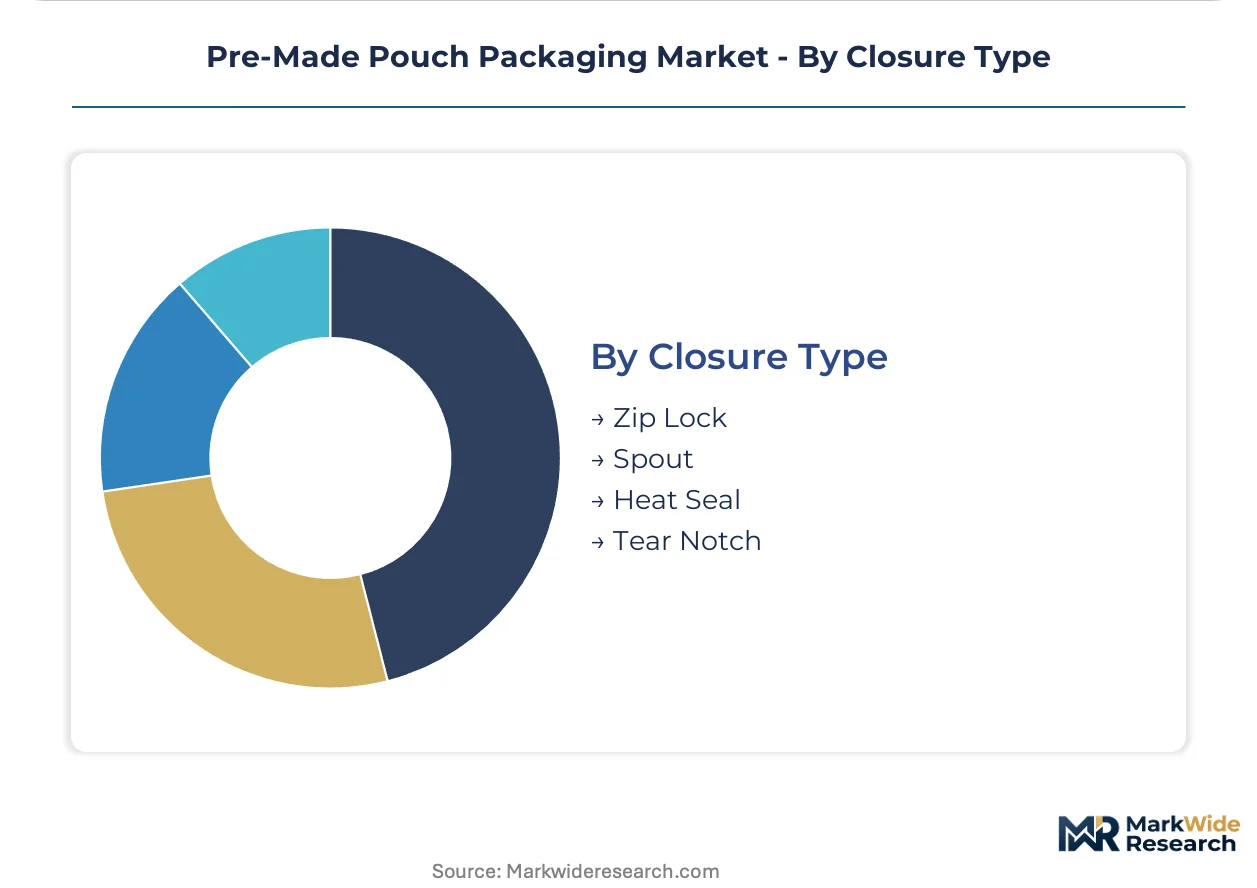
Closure Type:
Application context dictates resealability requirements and consumer interaction design.
- Spout:Screw-cap or fitment-integrated openings enable controlled dispensing and repeated reseal for beverages and viscous products. Premium positioning in infant nutrition drives specification in Germany and France.
- Zip Lock:Interlocking plastic tracks provide resealability without additional components, serving snack and dry goods segments where cost constraints exclude spout economics.
- Heat Seal:Permanent fusion closures deliver tamper evidence and extended shelf life for single-use portions and sterile applications.
- Tear Notch:Perforated initiation points facilitate clean opening without tools, common in condiments and sample formats where resealability is unnecessary.
Heat seal maintains the widest application base, while spout closures are gaining share fastest in premium beverage and nutrition segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Packaging and Packaging Waste Regulation mandates are accelerating investment in recyclable mono-material pouch structures across major converting clusters. Brand owners in Germany, France, and the Netherlands lead format conversion from rigid containers, while machinery suppliers compress equipment lead times through geographic co-location with converters.
Germany
Retort-compatible mono-material qualification cycles concentrate in Baden-Württemberg and North Rhine-Westphalia, where ambient meal brands replace metal cans with high-temperature polyethylene laminates. REACH Article 33 disclosure requirements push converters toward water-based adhesive systems by 2027. Machinery suppliers and brand owners cluster around Stuttgart and Düsseldorf, shortening format innovation cycles.
United States
FDA food contact substance notifications govern barrier layer approvals for infant nutrition and sports drink pouches, with spout-equipped formats commanding premium positioning. E-commerce fulfillment centers demand damage-resistant geometries distinct from retail-optimized structures. Converting capacity concentrates in the Midwest and Southeast, serving fragmented channel-specific SKU architectures.
France
Paper-based barrier laminates capture dry goods segments where moisture sensitivity permits material substitution, particularly in Île-de-France retail positioning. EFSA migration limit timelines extend 18-24 months for recycled content incorporation, delaying circular material qualification. Converters near Lyon and Paris integrate fiber substrates with water-based coatings.
India
Modern trade expansion in Mumbai and Delhi creates positioning for spout-equipped formats in edible oils and dairy. FSSAI compliance frameworks govern food contact specifications for flexible packaging. Organized retail growth concentrates in Maharashtra and Gujarat, driving first-mover adoption of convenience-oriented pouch geometries.
Netherlands
Pet food manufacturers adopt retort-compatible mono-materials fastest, accepting shelf-life tradeoffs for recyclability claims under PPWR implementation. Extended producer responsibility fee structures create direct economic pull versus legacy composites. Converting clusters near Rotterdam and Eindhoven anchor integrated resin recycling partnerships.
Pre-Made Pouch Packaging Market Competitive Environment
On the supply side, the industry is consolidating around integrated film producers and specialized converters with barrier technology expertise. Tiered competition separates global multi-material suppliers from regional mono-material specialists and paper-based solution providers. Two strategic archetypes dominate: integrated resin-to-pouch converters capturing economies of scale, and technology-focused specialists commanding premium positioning through high-barrier retort structures. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing chemical recycling feedstock agreements and co-development relationships with brand owners.
Within the integrated global tier, Amcor leverages regional plant networks to supply fragmented channel demands, while Mondi Group anchors European paper-based barrier convergence. ProAmpac occupies a specialist position exemplifying high-barrier retort expertise for shelf-stable protein applications. These three entities represent distinct strategic archetypes: geographic footprint optimization, fiber substrate integration, and sterilization-compatible material science.
| Leading Market Players |
|---|
| Amcor |
| Mondi Group |
| Berry Global |
| Sealed Air Corporation |
| Sonoco Products Company |
| ProAmpac |
| Huhtamaki |
| Constantia Flexibles |
| Smurfit Kappa |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp barge freight corridors shape converter cost structures, concentrating supply-side leverage among integrated resin producers while downstream brand owners fragment procurement across channel-specific pouch specifications. This logistics concentration amplifies price differentiation between mono-material recyclability tiers and legacy multi-layer barrier structures.
Pricing Analysis
Certification level (FDA food contact notification, EFSA migration compliance, REACH Article 33 disclosure) creates the primary spread between commodity converters and qualified barrier specialists. Three-tier pricing structure across premium retort-compatible, standard mono-material, and economy multi-layer tiers reflects qualification investment recovery timelines. Pricing pressure stems from EVOH resin supply concentration in Japan and Belgium compressing converter margins. Food and beverage brand owners exhibit highest price sensitivity in ambient meal segments, while pharmaceutical buyers absorb premium positioning for child-resistant spout formats.
Supply Chain Analysis
Extended payment terms from German machinery suppliers and supply-chain finance facilities anchored by Dutch pet food manufacturers reshape working capital dynamics across the converting tier. Resin production concentrates in Germany, Belgium, and Japan, with sputtered aluminum oxide deposition equipment clustering in Italian and German engineering hubs. Raw material dependencies center on polyethylene, EVOH barrier resins, and water-based adhesive chemistries. Single-source vulnerability in vacuum metallization equipment exposes converters to energy-intensive process cost swings. Distribution runs through co-located brand owner-contract packer networks in Baden-Württemberg and North Rhine-Westphalia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as German ambient meal brands and Dutch pet food manufacturers consolidate procurement volumes, forcing converters to absorb extended producer responsibility fee pass-throughs or invest in captive recycling infrastructure.
For Market Incumbents: Entrench barrier technology differentiation through accelerated retort-compatible mono-material qualification cycles in Baden-Württemberg, defending against emerging paper-based laminate substitutes in French dry goods segments. Prioritize backward integration into chemically recycled polyethylene feedstock partnerships near Rotterdam to offset legacy composite dismantling pressure under PPWR mandates. For New Entrants and Emerging Players: Establish a beachhead in Indian organized retail spout-equipped formats for edible oils and dairy, where FSSAI compliance frameworks remain less stringent than EU migration limits. Target Maharashtra and Gujarat modern trade expansion with channel-specific case-count flexibility absent from incumbent retail-optimized architectures. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with stranded multi-layer composite assets requiring PPWR-mandated mono-material conversion capital. Five-to-ten year viability hinges on integrated resin-to-pouch converter models capturing chemical recycling feedstock economics. Monitor EFSA recycled content incorporation timeline acceleration as inflection signal for circular material qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Retort-Compatible Mono-Material Qualification | German ambient meal brands replace metal cans with sterilization-compatible polyethylene laminates. |
| Chemical Recycling Feedstock Partnership | Dutch converters near Rotterdam anchor integrated resin recycling to capture PPWR compliance economics. |
| Water-Based Adhesive System Conversion | Italian and German printers absorb REACH Article 33 reformulation costs by 2027 deadline. |
| E-Commerce Fulfillment Specialization | US protein powder and infant nutrition brands demand damage-resistant geometries distinct from retail formats. |
| Paper-Based Barrier Convergence | French and Italian dry goods segments adopt fiber substrates with water-based coatings for retail positioning. |
Study Parameters
Operator-level perspectives from converting plant managers, brand owner technical buyers, contract packer procurement leads, and machinery supplier application engineers anchored the qualitative base. Primary interview insights triangulated against secondary sources including EFSA migration limit databases, FDA food contact substance notification filings, EU PPWR implementation guidance, and REACH Article 33 substance disclosure registries. Bottom-up volume builds across product type, material architecture, end-use segment, and closure configuration converged with top-down macroeconomic anchors.
Scenario-bracketing framed low, base, and high cases across regulatory implementation velocity, resin recycling infrastructure buildout, and brand owner format conversion willingness. Segmentation dimensions spanned sterilization compatibility requirements, barrier performance tiers, fulfillment channel specifications, and geographic regulatory clusters. CAGRs derived from trend-line extrapolation validated against industry stakeholder consensus on mono-material adoption trajectories. Forecast inputs incorporated EU extended producer responsibility fee structure evolution and retort pouch sterilization cycle performance validation timelines.
Stress conditions across EVOH supply disruption, PPWR enforcement acceleration, and e-commerce fulfillment center demand volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory timeline adherence and resin recycling capacity scaling. Macroeconomic contraction, regulatory delay, or breakthrough barrier coating technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
OPP Pouches Market
Pouch
Paper Pouch Market
Pouch
Liquid Pouch Market
Pouch
Fin Seal Pouches Market
Pouch
Spain Pouch Packaging Market
Pouch
Four Side Flat Pouch Market
Pouch
Germany Pouch Packaging Market
Pouch
India Pouch Packaging Market
Pouch
Europe Retort Pouches Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
South Africa Pouch Packaging Market
Pouch
France Pouch Packaging Market
Pouch
Stand Up Paper Pouches Market
Pouch
Zipper Pouch Market
Pouch
High-Barrier Pouches Market
Pouch
Egypt Pouch Packaging Market