
 Thermal Laminating Machine Market | 2026-2036
Thermal Laminating Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Laminating Machine Market Outlook
The EU Green Deal is hardening material recovery mandates across European packaging supply chains. BOBST Group SA leverages its Swiss engineering heritage to dominate high-throughput roll-to-roll systems for flexible packaging converters. Nordmeccanica Group anchors its position through solventless adhesive lamination technology that reduces volatile organic compound emissions. Comexi Group Industries specializes in hybrid configurations serving Spanish and Latin American print-to-pack integrated operations.
A thermal laminating machine bonds multiple substrate layers through heated rollers applying pressure-activated adhesives, typically operating at temperatures between 100°C and 150°C depending on film and adhesive chemistry, to produce durable composite materials for protective and decorative applications. Double-sided laminators command premium positioning in commercial printing workflows where simultaneous two-side processing eliminates second-pass labor and registration drift. Hot roll technology leads installed base volumes while digital thermal systems represent the fastest-growing technology segment as print shops adopt shorter-run, variable-data packaging formats.
REACH and RoHS frameworks in Europe restrict hazardous substance content in laminated consumer goods, while FDA food-contact regulations in the United States govern adhesive migration limits for thermal laminates used in food packaging. The EU F-Gas Regulation further shapes equipment design by phasing high-global-warming-potential refrigerants from cooling subsystems in larger laminating lines. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions as these chemicals historically enabled grease-resistant barrier properties in laminated food-service materials.
Market Dynamics
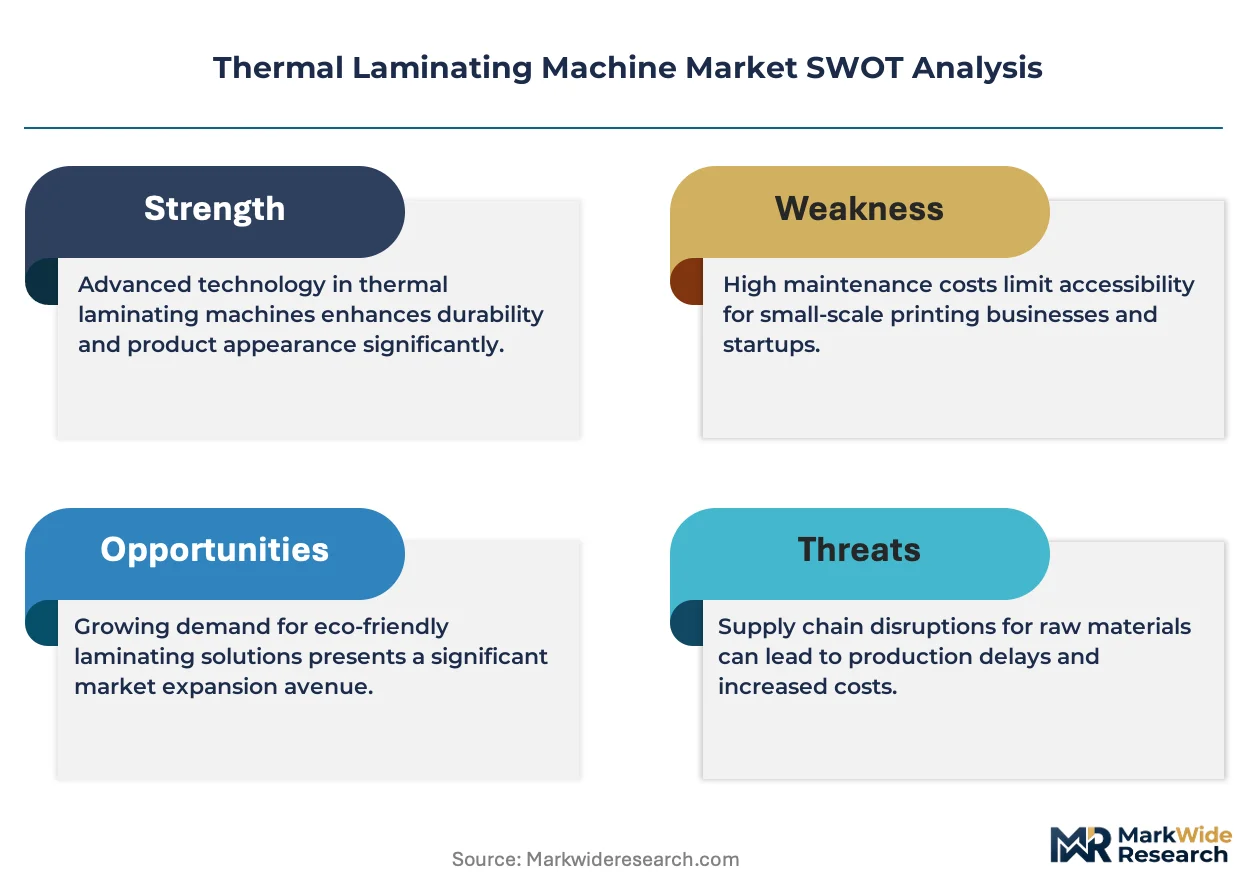
EU Green Deal mandates on material recovery are forcing packaging converters to replace legacy solvent-based systems with thermal lamination equipment that eliminates volatile organic compound emissions while maintaining throughput.
Growth Catalysts
- Food-grade flexible packaging demand:Pharmaceutical blister formats and ready-meal pouches in Germany, the United States, and China are compressing equipment replacement cycles as converters chase barrier performance specifications.
- REACH and RoHS substance restrictions:Hazardous content limits in laminated consumer goods across Europe are disqualifying older adhesive chemistries, redirecting capital toward compliant thermal systems.
- Hot roll technology maturation:Temperature-precision advances between 100°C and 150°C are expanding substrate compatibility to bioplastics and recycled films previously excluded from thermal bonding.
Market Restraints
- Aluminum and specialty polymer input volatility:Thermal laminating films depend on petrochemical feedstocks and rolled metal supplies concentrated in Gulf Coast and Middle Eastern production clusters.
- EU F-Gas Regulation equipment redesign costs:Phase-out schedules for high-global-warming-potential refrigerants in cooling subsystems are extending engineering timelines for larger laminating lines.
- Digital print-to-pack substitution:Inkjet and toner-based direct-to-substrate decoration is capturing short-run label work that thermal lamination historically dominated.
Strategic Opportunities
- India packaging converter modernization:FSSAI food-contact enforcement and BIS quality mandates are creating first-mover advantages for thermal equipment suppliers as domestic flexible packaging capacity scales.
- Per- and polyfluoroalkyl substance replacement:Evolving restrictions on grease-resistant barrier chemicals are opening formulation partnerships for thermal adhesive developers with fluorine-free alternatives.
- Service-contract revenue unbundling:Predictive maintenance subscriptions and remote diagnostics are capturing margin pools separate from hardware sales as uptime guarantees become procurement criteria.
Industry Challenges
- Mechatronics and thermal engineering skill scarcity:Converters struggle to staff commissioning and optimization roles for hybrid digital-thermal systems that blend precision mechanics with data-driven process control.
- CE marking and FDA food-contact parallel certification:Dual-jurisdiction validation timelines for equipment destined for transatlantic supply chains are extending order-to-revenue cycles by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Laminating Machine Market |
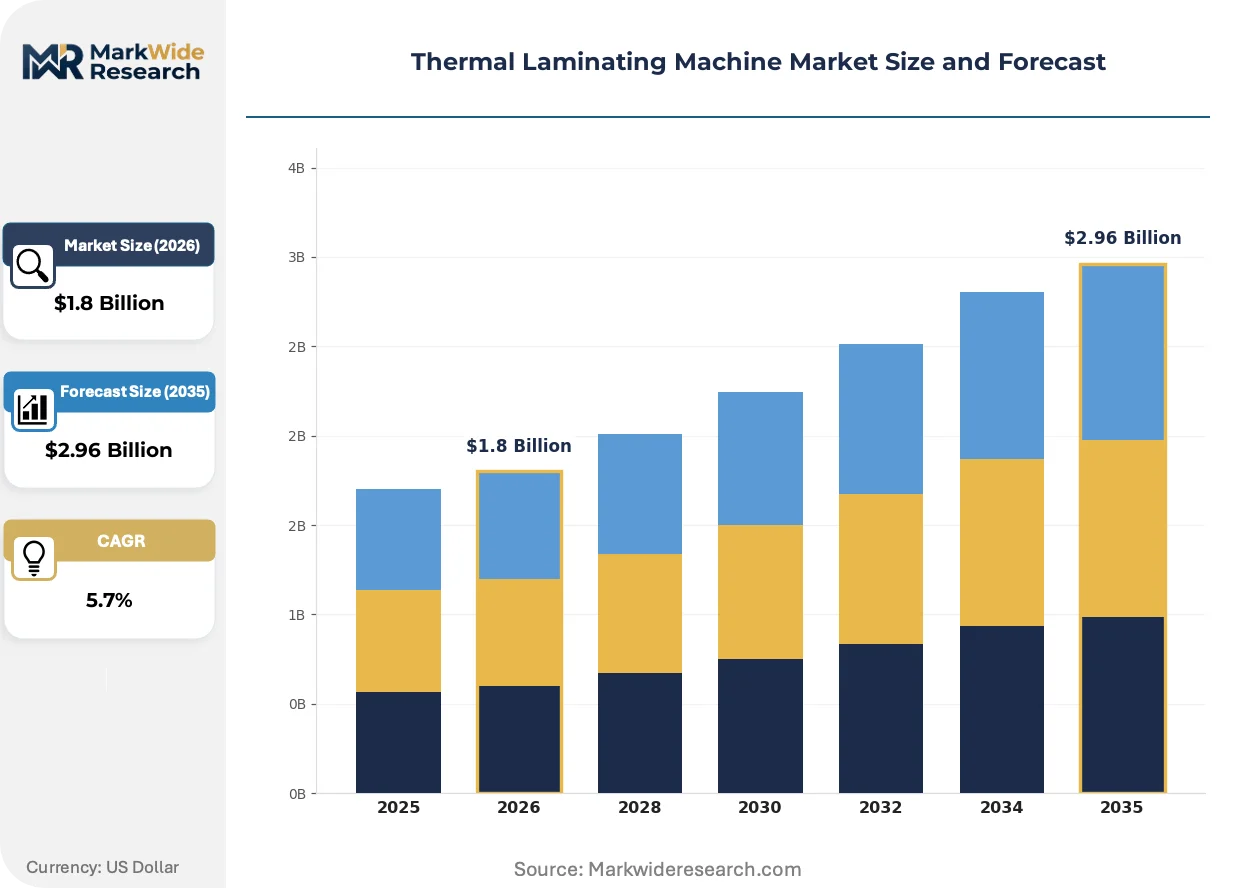
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided Laminators, Double-Sided Laminators, Roll Laminators, Pouch Laminators Application: Commercial Printing, Packaging, Paper Crafting, Educational Material End User: Small Businesses, Corporations, Educational Institutions, Print Shops Technology: Hot Roll, Cold Roll, Digital, Manual |
| Companies Covered | Comexi Group Industries, Uteco Converting, BOBST Group SA, D&K Group, Thermal Laminating Corporation, Nordson Corporation, Nordmeccanica Group, 3M Company, FRIMO Group GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Laminating Machine Market Strategic Shifts
Digital thermal systems are compressing run-length economics while regulatory chemistry restrictions are rewriting adhesive formulation roadmaps across converter operations.
Induction heating modules are converging with traditional hot roll architectures to enable rapid temperature zone switching without thermal mass lag. Narrow-web label converters in North America and Western Europe are retrofitting existing lines with hybrid configurations to capture variable-data pharmaceutical serialization work. This convergence is collapsing minimum efficient scale thresholds and fragmenting order books toward shorter, more frequent runs.
The EU F-Gas Regulation is mandating refrigerant transitions in cooling subsystems for laminating lines above specified throughput thresholds. Equipment manufacturers are engineering closed-loop chiller designs using hydrofluoroolefin alternatives or natural refrigerants to maintain compliance without sacrificing temperature stability. German and Italian converter clusters are absorbing premium pricing for compliant systems to avoid production interruptions during enforcement phase-ins.
Converter procurement teams are unbundling aftermarket service from capital equipment negotiations, treating uptime guarantees and spare-part availability as standalone evaluation criteria. This behavioral shift is compressing vendor selection timelines while elevating regional service density as a competitive differentiator. The pattern is most visible in United States commercial print-to-pack operations where maintenance cost predictability outweighs initial capital expenditure in total cost of ownership models.
Thermal Laminating Machine Market Segmentation
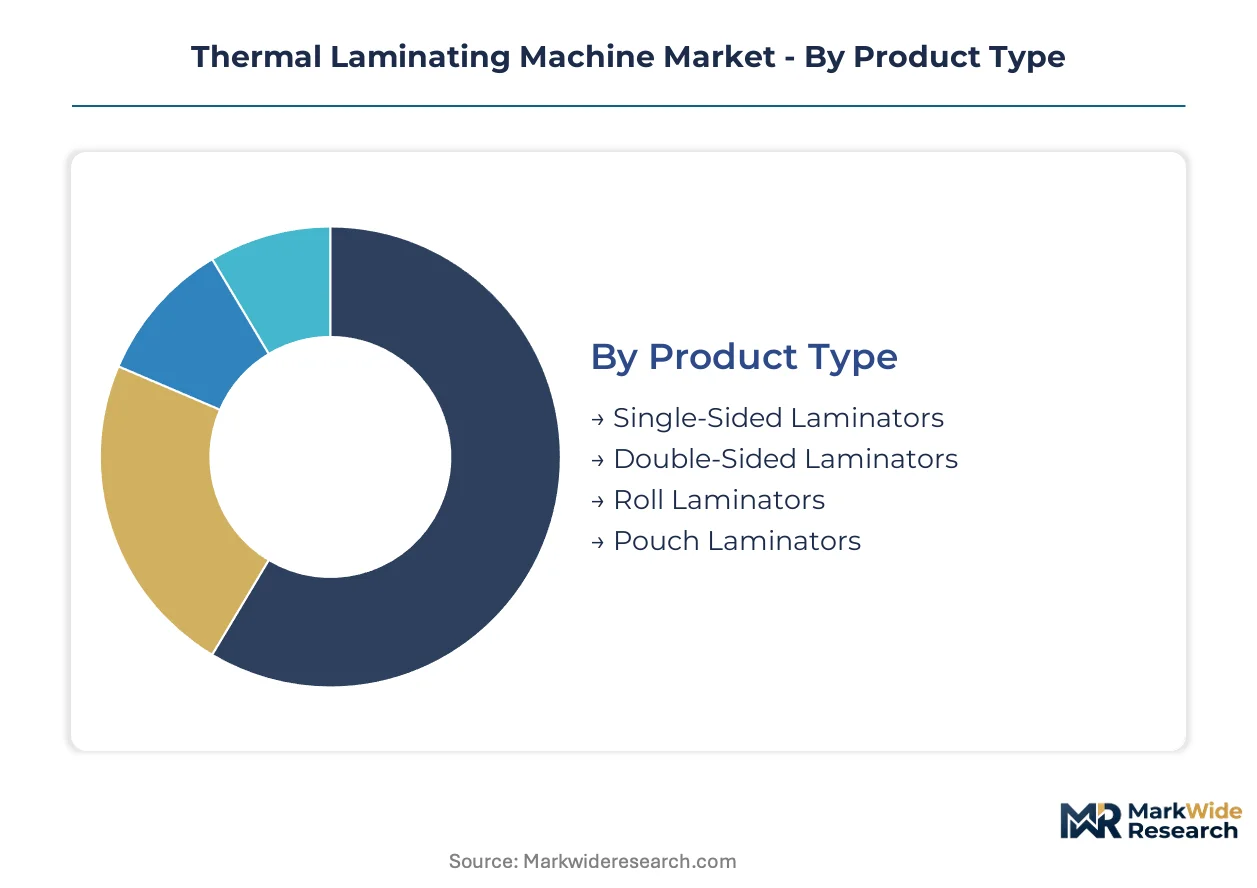
Thermal laminating machine segmentation reveals divergent equipment economics across print-to-pack workflows. Buyers prioritize throughput consistency, substrate versatility, or capital efficiency depending on operational scale and regulatory exposure.
Product Type:
Equipment selection hinges on labor cost structure and registration precision requirements.
- Double-Sided Laminators:Simultaneous two-side processing eliminates second-pass labor and registration drift in commercial printing workflows. Demand concentrates in Germany and the United States where print shops chase productivity guarantees for high-volume contract work.
- Roll Laminators:Continuous-feed architecture bonds flexible substrates at speeds exceeding sheet-fed alternatives, serving food-grade flexible packaging converters. German and Chinese packaging clusters drive replacement cycles as EU Green Deal mandates harden material recovery requirements.
- Single-Sided Laminators:Entry-level systems dominate small-business procurement with lower capital thresholds and simpler maintenance protocols.
- Pouch Laminators:Desktop formats serve educational institutions and sporadic-use environments where batch sizes remain below fifty units.
Volume sits with roll laminators; growth tilts toward double-sided configurations.
Application:
End-use concentration determines adhesive chemistry compliance burdens and throughput specifications.
- Packaging:Food-contact barrier specifications and pharmaceutical blister formats impose FDA migration limits and REACH substance restrictions. German and United States converters absorb premium equipment pricing to maintain multi-jurisdiction certification.
- Commercial Printing:Variable-data short runs and versioning requirements compress job changeover times. North American print shops retrofit hybrid digital-thermal systems to capture pharmaceutical serialization contracts.
- Paper Crafting:Scrapbooking and specialty paper finishing sustain demand for cold-roll and manual alternatives in hobbyist and small-retailer channels.
- Educational Material:K-12 procurement cycles favor pouch and entry-level roll systems with durability warranties and simplified operator training.
Installed base concentrates in commercial printing; packaging applications are expanding most quickly.
End User:
Scale thresholds separate buyers by technical staffing depth and service contract appetite.
- Print Shops:Independent and franchise operations prioritize uptime guarantees and regional service density over capital expenditure minimization. United States commercial print-to-pack operations treat predictive maintenance subscriptions as standalone procurement criteria.
- Corporations:In-house document centers and marketing production units demand enterprise-grade throughput with IT integration for job tracking and cost allocation.
- Educational Institutions:K-12 and university procurement favors pouch laminators and entry-level roll systems with simplified maintenance protocols and extended warranty terms.
- Small Businesses:Cost minimization dominates equipment selection, with manual and cold-roll alternatives capturing price-sensitive demand in sporadic-use environments.
Revenue concentrates with print shops; small businesses represent the steepest expansion trajectory in emerging markets.
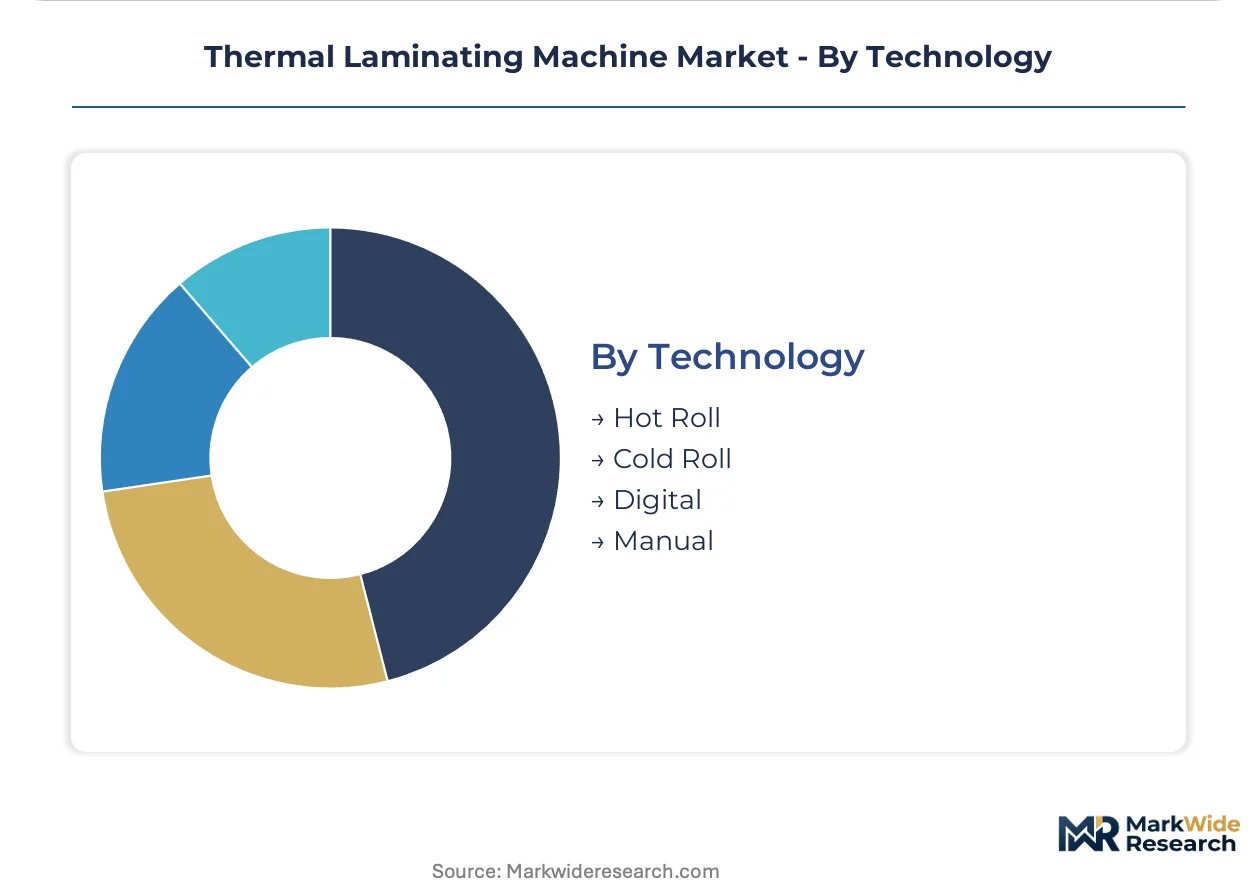
Technology:
Heat delivery mechanisms differentiate substrate compatibility and energy efficiency profiles.
- Hot Roll:Temperature-precision advances between 100°C and 150°C expand compatibility to bioplastics and recycled films previously excluded from thermal bonding. Mature installed base sustains aftermarket parts revenue across European and North American converter clusters.
- Digital:Variable-data integration and rapid job changeover capabilities serve short-run packaging formats. Print shops in Germany and the United States adopt these systems to capture pharmaceutical serialization and personalized label work.
- Cold Roll:Pressure-activated adhesive systems serve heat-sensitive substrates including certain photographic papers and specialty synthetics.
- Manual:Hand-cranked alternatives persist in educational and hobbyist segments where capital constraints outweigh throughput requirements.
Hot roll dominates installed volumes; digital systems are gaining share fastest as run lengths compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wuhan's optics and photonics corridor anchors thermal laminating equipment demand through integrated flexible packaging supply chains serving pharmaceutical and food-grade converters.
Germany
Pharmaceutical blister packaging and ready-meal pouch converters in Baden-Württemberg compress equipment replacement cycles. The EU F-Gas Regulation mandates refrigerant transitions in cooling subsystems for high-throughput laminating lines. Stuttgart's packaging machinery cluster absorbs premium pricing for compliant systems to avoid production interruptions during enforcement phase-ins.
United States
Commercial print-to-pack operations and pharmaceutical serialization contracts drive hybrid digital-thermal system adoption. FDA food-contact regulations govern adhesive migration limits for thermal laminates used in food packaging. Chicago's flexible packaging corridor treats predictive maintenance subscriptions as standalone procurement criteria, elevating regional service density as a competitive differentiator.
China
Food-grade flexible packaging capacity expansion in the Yangtze River Delta and Pearl River Delta accelerates equipment procurement. The country's national quality standards enforce food-contact compliance for laminated consumer goods. Suzhou's converter cluster scales domestic capacity as international brands localize supply chains to reduce tariff exposure.
India
FSSAI food-contact enforcement and BIS quality mandates create first-mover advantages for thermal equipment suppliers as flexible packaging capacity scales. The PLI scheme for manufacturing incentivizes domestic production of precision machinery components. Ahmedabad's packaging converter corridor modernizes solvent-based legacy systems to meet hardened material recovery requirements.
Italy
Solventless adhesive lamination technology demand concentrates in Emilia-Romagna's flexible packaging belt to reduce volatile organic compound emissions. REACH substance restrictions disqualify older adhesive chemistries, redirecting capital toward compliant thermal systems. Bologna's converter cluster leverages regional engineering expertise to optimize roll-to-roll system throughput for export-oriented food packaging.
Thermal Laminating Machine Market Competitive Environment
The competitive structure tilts toward engineering-intensive specialists with Swiss and Italian heritage dominating high-throughput roll-to-roll configurations. Tiered differentiation separates premium-positioned precision mechanics providers from mid-market fabricators competing on capital efficiency. Three archetypes anchor positioning: precision-engineering heritage players, solventless technology specialists, and diversified industrial conglomerates with laminating divisions. Capacity expansion in Asian converter clusters and technology licensing partnerships represent the dominant competitive moves reshaping geographic presence.
Among Swiss-heritage precision engineering groups, BOBST Group SA exemplifies the high-throughput roll-to-roll archetype for flexible packaging converters. Italian specialists Nordmeccanica Group and Uteco Converting occupy positions within the solventless adhesive lamination tier, serving emission-sensitive European converter operations. Comexi Group Industries anchors the hybrid configuration segment for print-to-pack integrated operations across Spanish and Latin American markets. These three represent divergent strategic postures on technology specialization versus geographic diversification.
| Leading Market Players |
|---|
| Comexi Group Industries |
| Uteco Converting |
| BOBST Group SA |
| D&K Group |
| Thermal Laminating Corporation |
| Nordson Corporation |
| Nordmeccanica Group |
| 3M Company |
| FRIMO Group GmbH |
| Others |
Value Chain & Pricing Dynamics
Captive in-house production of precision heating modules and cooling subsystems anchors pricing power for Swiss and German equipment manufacturers serving pharmaceutical and food-grade converter clusters. This backward integration insulates premium-tier vendors from petrochemical feedstock volatility while forcing mid-market fabricators toward outsourced component sourcing that compresses margin buffers.
Pricing Analysis
Throughput-guarantee contracts anchor value-based pricing for high-volume roll-to-roll systems serving flexible packaging converters. Pricing stratifies across premium, standard, and economy tiers based on CE-FDA dual certification status and regional service density commitments. Cost compression in the standard tier intensifies as Chinese domestic manufacturers scale precision machining capabilities. Small-business procurement teams exhibit highest price sensitivity, while pharmaceutical converters absorb premium positioning for uptime certainty.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Chicago, and Suzhou feed hub-and-spoke service networks that determine aftermarket parts availability and commissioning response times. Component sourcing draws from German precision mechanics, Italian adhesive engineering, and Chinese steel fabrication clusters. Single-source vulnerability concentrates in induction heating coil suppliers serving narrow-web retrofit configurations. Distribution runs through authorized dealer networks with direct OEM relationships for large converter accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over thermal engineering talent and refrigerant-compliant cooling subsystem production determines long-term positioning. Players are pursuing backward integration into precision mechanics to defend margin pools against emerging Asian competitors.
For Market Incumbents: Anchor market position through exclusive service-contract bundling that locks pharmaceutical converters into predictive maintenance subscriptions. Acquire regional aftermarket service providers in the United States and Germany to elevate response-time guarantees. Digital print-to-pack substitution and Chinese equipment cost compression represent parallel threats requiring differentiated defensive postures.
For New Entrants and Emerging Players: Enter via fluorine-free adhesive formulation partnerships that address evolving per- and polyfluoroalkyl substance restrictions across European and North American jurisdictions. Target India's packaging converter modernization wave as the most penetrable geography, leveraging FSSAI enforcement timelines to establish first-mover relationships. Lead with remote diagnostics capabilities that incumbent service networks lack.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking laminating equipment divisions. Long-term viability hinges on refrigerant-transition engineering capabilities and digital-thermal hybrid system portfolios. Monitor EU F-Gas Regulation enforcement phase-ins as the critical inflection signal for distressed asset availability in non-compliant equipment manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant-Compliant Cooling Subsystem Engineering | EU F-Gas Regulation mandates closed-loop chiller redesigns for high-throughput laminating lines in German and Italian clusters. |
| Fluorine-Free Adhesive Formulation Partnership | REACH substance restrictions on grease-resistant barrier chemicals open formulation alliances for thermal adhesive developers. |
| Predictive Maintenance Subscription Unbundling | Chicago's flexible packaging corridor treats uptime guarantees as standalone procurement criteria separate from hardware capital expenditure. |
| Regional Service Density Expansion | United States commercial print-to-pack operations prioritize maintenance cost predictability over initial equipment pricing in total cost models. |
| Hybrid Digital-Thermal System Development | Pharmaceutical serialization contracts in North America and Western Europe compress job changeover times for variable-data packaging formats. |
Study Parameters
Independent corroboration across converter procurement directors, thermal engineering specialists, and aftermarket service heads underwrites the qualitative findings in this study. Primary fieldwork encompassed equipment manufacturer sales executives, plant engineers at flexible packaging facilities, and regulatory compliance officers navigating REACH and FDA food-contact frameworks. Secondary validation drew from EU F-Gas Regulation implementation schedules, SEC filings of publicly traded packaging machinery groups, and customs data on thermal laminating equipment trade flows. Bottom-up equipment shipment tallies and top-down converter capacity expansion estimates were cross-referenced to anchor segmentation splits.
Rate-of-change decomposition across technology segments, application verticals, and geographic clusters structured the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, heat delivery mechanism, end-use industry, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, capacity expansion announcements, and enforcement timelines for substance restrictions. Forecast inputs incorporated EU Green Deal material recovery mandate compliance costs and FSSAI food-contact enforcement intensity in emerging converter markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated refrigerant phase-out schedules or abrupt per- and polyfluoroalkyl substance bans. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that dual-jurisdiction certification timelines and mechatronics skill scarcity could extend order-to-revenue cycles beyond modeled parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Shrink Wrapping Machines Market
Packaging Machinery
Vial Capping Machines Market
Packaging Machinery
Enveloping & Stacking Machine Market
Packaging Machinery
Vial Filling and Capping Machines Market
Packaging Machinery
Thermal Film Laminating Machines Market
Packaging Machinery
Automatic Filling Machine Market
Packaging Machinery
LAMEA Printing Machinery Market
Packaging Machinery
Liquid Capsule Filling Machines Market
Packaging Machinery
Package Closing Machines Market
Packaging Machinery
Pouch Sealing Machine Market
Packaging Machinery
Bag in Box Packaging Machine Market
Packaging Machinery
Blow Fill Seal (BFS) Technology Market
Packaging Machinery
Orbital Wrapping Machine Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Tube Sealing Machines Market
Packaging Machinery
Capping Machine Market