
 Kraft Paper Pouch Market | 2026-2036
Kraft Paper Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Kraft Paper Pouch Market Foresight
Specialty food brands and direct-to-consumer retailers is unwinding legacy procurement patterns that long favored rigid containers. Novolex leverages integrated film-to-paper lamination capabilities across North American converting plants. Mondi Group anchors European supply through its recycled-fiber kraft operations in Central Europe. Smurfit Kappa competes on corrugated-to-paperboard vertical integration that feeds pouch substrate lines.
A kraft paper pouch is a flexible packaging vessel constructed from unbleached sulfate pulp with basis weights typically ranging from 30 to 80 grams per square meter, often laminated with moisture or oxygen barrier layers to protect shelf-sensitive contents. Stand-up pouches with zipper closures dominate value pools in the food industry where resealability commands premium positioning. Flat pouches lead volume in the retail sector for dry goods distribution, while spout pouches represent the fastest-growing configuration in liquid and semi-liquid personal care applications.
The European Union's Packaging and Packaging Waste Regulation mandates extended producer responsibility and recyclability targets that directly elevate kraft paper pouch demand against plastic alternatives. The US Food and Drug Administration maintains contact-substance safety standards under 21 CFR that govern barrier coatings and adhesives in food-contact paper packaging. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York alongside FDA guidance revisions on recycled fiber purity to anticipate compliance-driven specification changes.
Market Dynamics
Single-use plastic bans under the EU Packaging and Packaging Waste Regulation are compressing demand timelines for barrier-coated kraft paper as specialty food brands accelerate specification changes ahead of compliance deadlines.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are forcing brand owners to eliminate multi-layer plastic laminates from food-contact packaging by specified deadlines.
- Specialty coffee roasting:Small-batch roasters in Germany and Italy are specifying high-barrier kraft pouches with one-way degassing valves to preserve aromatics during direct-to-consumer shipping.
- Barrier coating chemistry:Water-based polymer coatings and bio-derived waxes are achieving oxygen transmission rates below 0.1 cc per square meter per day, matching metallized film performance.
Market Restraints
- Pulp cost volatility:Unbleached kraft pulp prices fluctuate with Nordic softwood supply disruptions and energy costs at Swedish and Finnish mills.
- Converting concentration:Central European coating and laminating capacity clusters in Germany and Poland, creating logistics constraints for southern European brand owners.
- High-barrier limitation:Current bio-based coatings fail to match aluminum oxide metallized films for ultra-low moisture vapor transmission required in tropical distribution.
Strategic Opportunities
- Spout pouch liquids:Personal care brands in France and the Netherlands are piloting kraft-based spouted pouches for shampoo and conditioner refills.
- Digital printing integration:HP Indigo and Xeikon presses enable run-length flexibility for craft food brands requiring frequent SKU rotation with minimal plate costs.
- Italian organic food retail:Coop Italia and Esselunga private-label expansion creates procurement volume for domestic converting partners.
Industry Challenges
- Barrier-coating chemist scarcity:Formulation expertise spanning paper science and polymer chemistry concentrates at a handful of technical institutes in Darmstadt and Grenoble.
- Recyclability certification timelines:Interseroh and FSC chain-of-custody audits require six-to-nine-month lead times that compress product launch windows.
- Legacy filling equipment retrofit:Horizontal form-fill-seal lines designed for polypropylene films require jaw temperature and tension recalibration for kraft paper web handling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraft Paper Pouch Market |
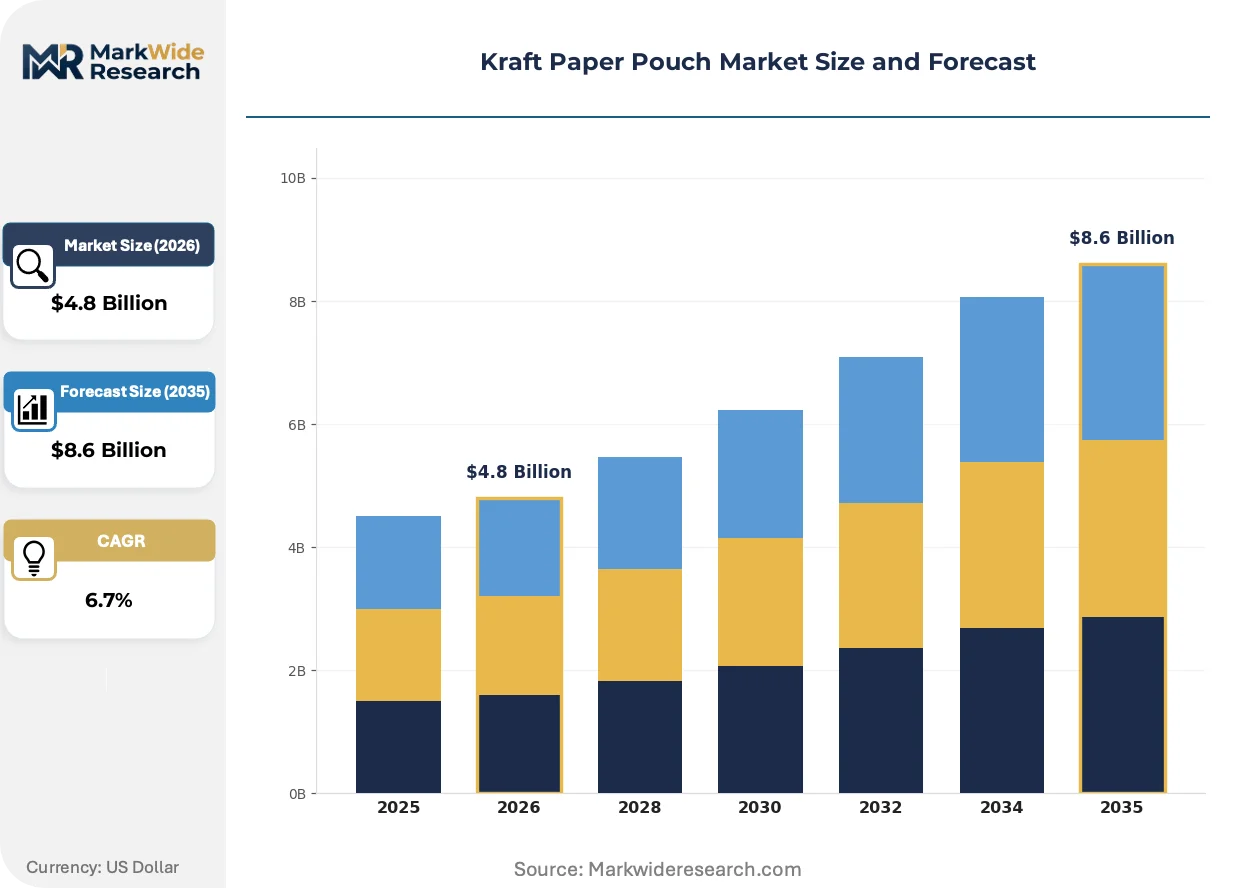
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Gusseted Pouches, Spout Pouches End User: Food Industry, Retail Sector, Healthcare, Personal Care Closure Type: Zipper, Velcro, Heat Seal, Tear Notch Application: Packaging, Storage, Distribution, Marketing |
| Companies Covered | Novolex, ProAmpac, Mondi Group, HEMCBags, Georgia-Pacific, Smurfit Kappa, WestRock, Forest Package, International Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraft Paper Pouch Market Shifts & Advancements
Barrier coating chemistry and digital print integration are collapsing minimum order quantities while regulatory compliance deadlines compress specification cycles across European food packaging procurement.
High-barrier water-based coatings incorporating bio-derived polymers are displacing conventional polyethylene extrusion laminates in dry food applications. German and Swiss chocolate brands are adopting these structures for 50-gram single-serve formats. The shift is displacing legacy metallized polyester films from premium positioning segments where matte kraft aesthetics command shelf differentiation.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated grease barriers from food-contact paper across EU member states. Bakery and confectionery brands must reformulate packaging specifications by phased deadlines. French converting operations are accelerating migration to alternative bio-wax barrier systems ahead of enforcement timelines.
Direct-to-consumer subscription models are fragmenting order sizes and compressing lead time expectations. Italian specialty pasta brands now specify 500-unit digital print runs with two-week turnaround. This pattern is most visible in northern European markets where Shopify-integrated food startups bypass traditional retail distribution entirely.
Kraft Paper Pouch Market Segmentation
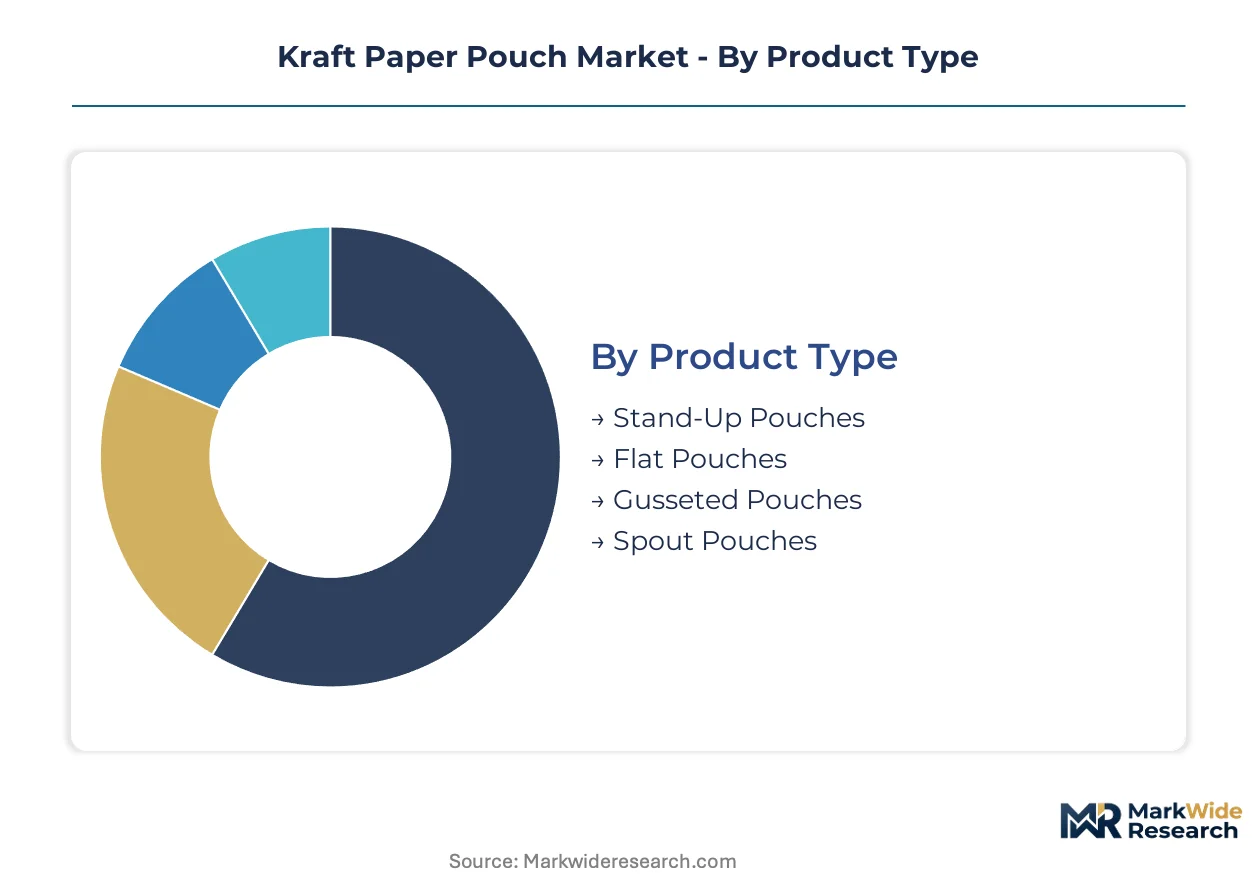
Kraft paper pouch specifications fragment across four structural dimensions. Procurement patterns diverge sharply between domestic European brands and export-oriented manufacturers serving tropical distribution corridors.
Product Type:
German and Italian converters dominate stand-up pouch supply for domestic specialty food brands, while Polish and Czech plants feed export volume into Middle Eastern and Southeast Asian markets.
- Stand-Up Pouches:These structures incorporate bottom gussets enabling vertical shelf display with resealable zipper mechanisms. Specialty coffee roasters in Hamburg and Milan specify high-barrier versions with one-way degassing valves for aromatic preservation during direct-to-consumer shipping.
- Spout Pouches:The fastest-climbing configuration incorporates molded fitments for controlled dispensing of liquids and semi-liquids. French personal care brands in Lyon and Dutch refill retailers are piloting kraft-based spouted formats for shampoo and conditioner concentrates.
- Flat Pouches:Simple three-side-seal constructions dominate dry goods volume through Esselunga and Coop Italia private-label programs.
- Gusseted Pouches:Side-folded structures expand cubic capacity for bulk flour and grain distribution through Central European agricultural cooperatives.
Stand-up configurations command the established base. The steepest expansion runs through spout-equipped liquid formats.
End User:
Cost-tier stratification separates premium-positioned organic food brands from commodity dry goods distributors, with specification intensity correlating directly with shelf-life requirements and regulatory exposure.
- Food Industry:Chocolate manufacturers in Switzerland and bakery brands across Belgium specify barrier-coated kraft for grease-resistant primary packaging. REACH restrictions on fluorinated compounds are forcing reformulation timelines ahead of enforcement deadlines.
- Personal Care:Refill subscription services in Amsterdam and Paris are specifying matte kraft aesthetics for bathroom-counter visibility and plastic-reduction marketing claims.
- Retail Sector:Discounters in Germany and Austria utilize uncoated flat pouches for private-label pasta, rice, and legume distribution.
- Healthcare:Medical device sterilization pouches require validated seal integrity under ISO 11607 standards, limiting kraft penetration to secondary packaging applications.
Food industry applications absorb the dominant procurement volume. Personal care refill formats are climbing fastest on sustainability positioning.
Closure Type:
Volume scale separates high-frequency reseal specifications from single-use convenience features, with zipper mechanisms commanding three-to-four-fold unit premiums over tear-notch alternatives.
- Zipper:Interlocking plastic tracks laminated to kraft facestocks enable repeated opening cycles. Premium pet food brands in the UK and specialty nut roasters in Portugal specify this mechanism for pantry storage convenience.
- Heat Seal:Permanent fusion barriers dominate portion-control formats and tamper-evident pharmaceutical applications where resealability is unnecessary or undesirable.
- Tear Notch:Laser-scored initiation points provide clean opening without tools, standard for single-serve confectionery and airline catering portions.
- Velcro:Hook-and-loop systems appear in reusable produce bags and bulk-bin shopping applications through Scandinavian zero-waste retail chains.
Zipper mechanisms anchor the premium tier. Tear-notch simplicity dominates volume throughput.
Application:
Customer-type stratification separates brand-owner marketing specifications from third-party logistics pure-play storage and distribution requirements.
- Packaging:Primary containment functions dominate value capture, with shelf-differentiation requirements driving specification complexity for specialty food brands.
- Marketing:Matte kraft surfaces and tactile embossing serve sustainability storytelling for direct-to-consumer unboxing experiences.
- Storage:Long-term preservation specifications concentrate in heritage grain and dried fruit applications requiring moisture vapor transmission below 5 grams per square meter per day.
- Distribution:E-commerce fulfillment pouches prioritize dimensional efficiency and print durability through automated sorting facilities.
Primary packaging commands specification investment. Marketing-driven aesthetic differentiation is gaining fastest on digital-native brand proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barrier coating capacity clusters heavily in Central Europe, with German and Polish converters supplying kraft paper pouches across EU compliance deadlines. Nordic pulp mills anchor raw material flows through integrated supply chains reaching Mediterranean brand owners.
Germany
Specialty coffee roasters in Hamburg and Berlin specify high-barrier kraft pouches with one-way degassing valves for direct-to-consumer aromatic preservation. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility timelines that accelerate specification shifts away from multi-layer plastics. Converting capacity in North Rhine-Westphalia and Bavaria has expanded coating and laminating lines to serve domestic organic food brands.
Italy
Artisan pasta producers and chocolate makers in Piedmont and Lombardy pilot matte kraft formats for premium shelf differentiation. REACH restrictions on per- and polyfluoroalkyl substances force bakery brands to reformulate grease-resistant specifications ahead of enforcement deadlines. Milan-based converters integrate HP Indigo presses for 500-unit digital print runs serving subscription-model food startups.
France
Personal care refill retailers in Lyon and Paris specify kraft-based spouted pouches for shampoo and conditioner concentrates targeting bathroom-counter sustainability marketing. ECHA maintains vigilance on barrier coating chemistry through REACH substance evaluations. Converting operations in Auvergne-Rhône-Alpes accelerate migration to bio-wax barrier systems ahead of fluorinated compound phase-outs.
Poland
Export-oriented manufacturers supply flat and gusseted pouches to Middle Eastern and Southeast Asian dry goods distributors. The EU Green Deal carbon border adjustment mechanisms incentivize low-carbon kraft substrates in cross-border procurement. Industrial zones around Łódź and Kraków concentrate heat-seal converting capacity for high-volume private-label programs.
Netherlands
Amsterdam-based zero-waste retail chains specify hook-and-loop closure kraft bags for bulk-bin shopping and reusable produce applications. Dutch national packaging waste regulations implement EU extended producer responsibility frameworks with accelerated recyclability targets. Rotterdam logistics hubs facilitate barrier-coated kraft distribution to UK and Scandinavian markets post-Brexit trade realignment.
Kraft Paper Pouch Market Competitive Landscape
Concentration sits with integrated paperboard converters and specialized flexible packaging groups that control coating chemistry and laminating capacity. Three archetypes dominate: multinational paperboard giants with captive pulp supply, mid-scale regional converters with digital print integration, and niche specialists in high-barrier food-contact formulations. Competitive moves center on backward integration into barrier coating R&D and strategic partnerships with specialty food brands for co-developed sustainable packaging specifications.
Among North American integrated players, Novolex and WestRock exemplify scale-driven archetypes with film-to-paper lamination capabilities across continental converting networks. Mondi Group anchors European supply positioning through recycled-fiber kraft operations. Smurfit Kappa occupies a position emphasizing corrugated-to-paperboard upstream control that feeds pouch substrate lines.
| Leading Market Players |
|---|
| Novolex |
| ProAmpac |
| Mondi Group |
| HEMCBags |
| Georgia-Pacific |
| Smurfit Kappa |
| WestRock |
| Forest Package |
| International Paper |
| Others |
Supply & Pricing Matrix
Water-based barrier coatings displacing polyethylene extrusion laminates are redrawing procurement geography toward German and Polish converting clusters while compressing margin structures for legacy metallized film suppliers. Specialty coffee roasters and organic food brands now capture volume-discount leverage through consolidated specification orders that span direct-to-consumer subscription cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates kraft paper pouch procurement. Premium tiers command substantial markups for FSC-certified substrates with oxygen transmission rates below 0.1 cc per square meter per day, while economy tiers serve German discounters with uncoated flat pouches for dry goods. Price differentiation hinges on barrier performance certification and volume scale, with subscription-model food startups extracting favorable terms through multi-SKU consolidation. Pricing pressure stems from pulp cost volatility at Nordic softwood mills, compressing converter margins. Commodity dry goods distributors exhibit highest price sensitivity, whereas Swiss chocolate brands and Italian organic food retailers prioritize barrier performance over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate inventory strategy as converters buffer against Nordic pulp supply disruptions and energy cost spikes at Swedish and Finnish mills. Raw material flows draw from Germany, Poland, and Czechia for coating and laminating capacity, with unbleached kraft pulp anchored in Nordic integrated paperboard operations. Supply chain risk centers on single-source vulnerability for high-barrier water-based polymer formulations concentrated at technical institutes in Darmstadt. Distribution runs through Rotterdam logistics hubs facilitating post-Brexit trade realignment to UK and Scandinavian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kraft paper pouch market sits in early-cycle expansion as EU Packaging and Packaging Waste Regulation compliance deadlines force accelerated substitution away from multi-layer plastic laminates. Penetration tailwinds concentrate in personal care refill formats and specialty food direct-to-consumer channels.
For Market Incumbents: Fortify backward integration into barrier coating R&D to defend against specialty chemical entrants capturing high-margin food-contact formulations. Captive supply of bio-derived polymer coatings and accelerated FSC chain-of-custody certification investment neutralizes emerging mid-scale converters with digital print integration. Priority capacity addition in North Rhine-Westphalia and Bavaria anchors domestic German organic food brand relationships against Polish export-oriented competitors. For New Entrants and Emerging Players: Short-run digital print flexibility for Italian subscription-model food startups represents the most penetrable service-layer gap, where incumbents under-serve 500-unit turnaround requirements. French personal care refill retailers in Lyon piloting kraft-based spouted pouches offer secondary white-space targeting. Go-to-market positioning through Shopify-integrated brand partnerships bypasses traditional retail distribution gatekeepers entirely. For Investors and Strategic Acquirers: The market sits at a consolidation-ready phase that favors mid-scale regional converters with digital print integration and established specialty food brand relationships. Long-term viability over a multi-year horizon rests on barrier coating chemistry capabilities and EU regulatory compliance infrastructure. Acquisition target archetype: German or Italian converters with validated bio-wax barrier systems and Interseroh recyclability certification. Signal to watch: REACH enforcement timelines accelerating fluorinated compound phase-outs and compressing reformulation windows for bakery and confectionery packaging specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating R&D Partnership | Co-development with Darmstadt technical institutes secures oxygen transmission performance matching metallized films. |
| Digital Print Integration | HP Indigo press deployment enables 500-unit runs for Italian subscription food startups requiring rapid SKU rotation. |
| FSC Chain-of-Custody Certification | Accelerated audit completion compresses six-to-nine-month timelines for EU organic food brand procurement windows. |
| Spout Pouch Liquid Format Expansion | French personal care refill pilots in Lyon validate kraft-based shampoo concentrate packaging for bathroom-counter visibility. |
| Rotterdam Logistics Hub Control | Post-Brexit distribution positioning captures UK and Scandinavian specialty food brand procurement flows. |
Research Methodology
A standing panel of coating chemistry specialists, converting plant managers, specialty food brand procurement directors, and EU regulatory affairs consultants provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews captured specification evolution at German coffee roasters, Italian pasta producers, and French personal care refill retailers. Secondary sources incorporated EU Packaging and Packaging Waste Regulation implementation timelines, ECHA REACH substance evaluation databases, FSC chain-of-custody audit records, and Nordic pulp mill production disclosures. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for kraft paper pouch exports, converting capacity expansion announcements in North Rhine-Westphalia and Bavaria, and specialty food brand sustainability reporting disclosures. Segmentation dimensions spanned product type, end user, closure mechanism, and application function, with regional regulatory cluster differentiation for EU member state compliance deadlines. CAGRs derived from fitted growth curves incorporating pulp cost volatility assumptions and substitution elasticity estimates for plastic-to-paper packaging transitions.
Underlying assumptions cover EU extended producer responsibility implementation timelines and bio-based barrier coating performance trajectories, with deviation risk concentrated in REACH enforcement acceleration and Nordic softwood supply disruptions. Revision becomes warranted when fluorinated compound phase-out deadlines compress reformulation windows beyond current bio-wax barrier system capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Ziplock Products Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Brazil Pouch Packaging Market
Pouch
Heat Seal Pouch Market
Pouch
Twin Pouch Packaging Market
Pouch
MAP Flow Wrappers Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Four Side-Sealed Pouches Market
Pouch
Foam Pouch Market
Pouch
Pouch-Bowl Packaging Market
Pouch
Pouches Market
Pouch
Peelable Pouches Market
Pouch
Squeeze Pouch Market
Pouch
Peel Pouches Market
Pouch
Flexible Pouch Market
Pouch
United States Retort Pouches Market