
 Four Side-Sealed Pouches Market | 2026-2036
Four Side-Sealed Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Four Side-Sealed Pouches Market Analysis
E-commerce fulfillment channels is rewriting last-mile packaging requirements for lightweight, damage-resistant formats. Amcor leverages vertical integration across resin and film extrusion to control substrate quality for high-barrier pouches. ProAmpac sustains R&D intensity in recyclable mono-material structures that meet emerging extended producer responsibility mandates. Smurfit Kappa anchors European supply through regional converting plants serving fresh produce and dairy brands.
Four side-sealed pouches are flexible containers sealed on all edges with widths typically ranging from 50 mm to 400 mm, constructed from laminated films of polyethylene, polyester, or aluminum oxide-coated substrates to provide oxygen and moisture barriers. These pouches serve primary industrial purposes in portion-controlled food packaging, single-use pharmaceutical unit doses, and sample-size personal care sachets where hermetic integrity and flat storage efficiency matter. Stand-up pouches command premium positioning in shelf-stable beverages and liquid detergents where display aesthetics drive brand differentiation. Composites dominate material selection where aluminum-polymer laminates deliver the highest barrier performance for retort and aseptic applications, though plastic mono-materials are gaining share as recyclability targets harden across major retail channels.
FDA maintains food-contact notification requirements for pouch substrates, while the EU Packaging and Packaging Waste Regulation sets recycled content minimums that reshape material procurement. REACH and ECHA substance restrictions on perfluorinated compounds are forcing reformulation of grease-resistant barrier coatings. Stakeholders must monitor how California's SB 54 extended producer responsibility rules and China's GB standards for composite packaging interact with brand sustainability commitments to determine which substrate investments will retain market access.
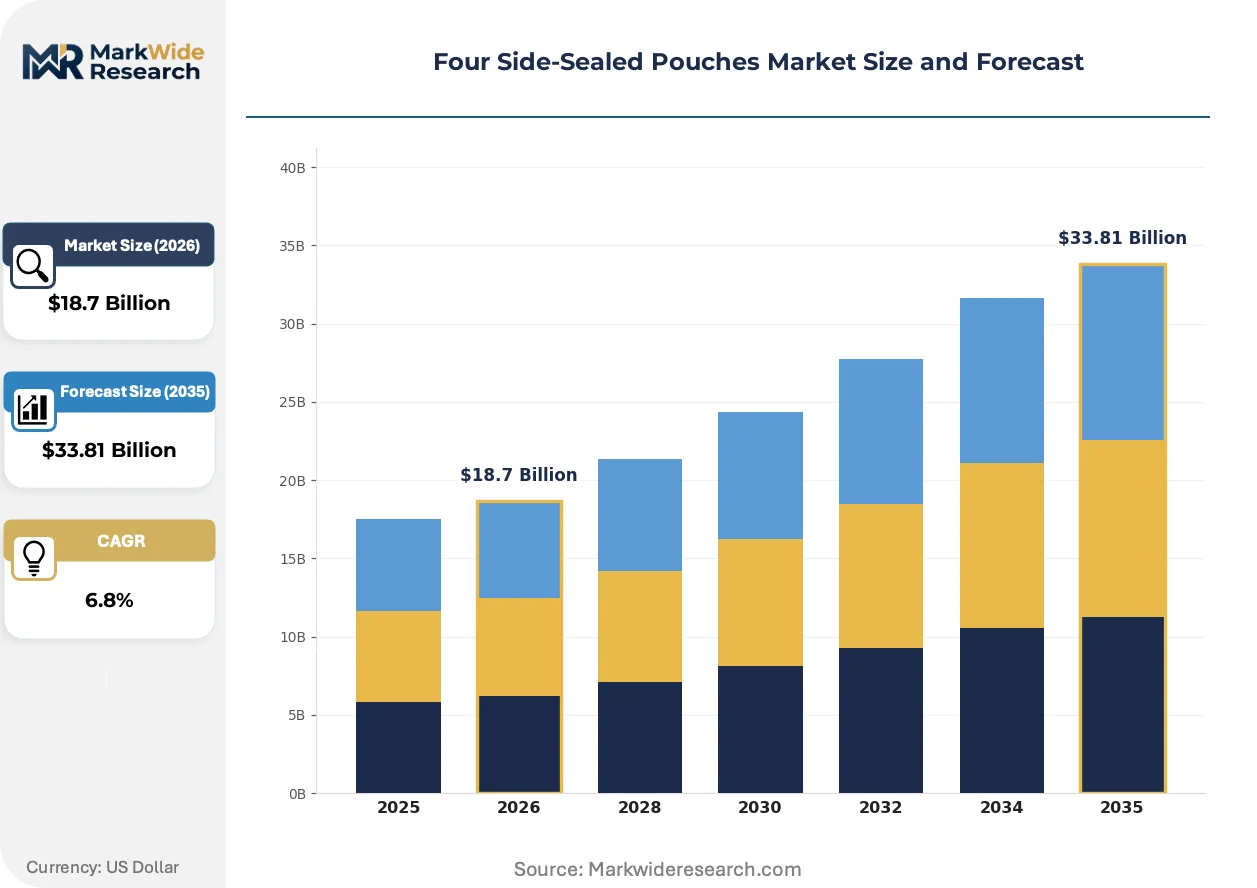
Market Dynamics
EU Packaging and Packaging Waste Regulation recycled-content mandates are forcing substrate portfolio rewrites across the value chain, compressing multi-material laminates while elevating mono-material and chemically recycled alternatives.
Growth Catalysts
- Ready-to-eat meal penetration:Food processors in China and North America are converting retort tray lines to four side-sealed formats for portion control and microwave convenience. Steam-assisted microwaveable structures eliminate venting requirements.
- REACH perfluorinated compound restrictions:ECHA substance bans on PFAS grease barriers are accelerating migration to clay-coated and bio-based barrier papers that maintain oil resistance without fluorochemistry.
- Aluminum oxide deposition:Vacuum-coated PET and PP films are replacing foil laminates in oxygen-sensitive applications, enabling transparent high-barrier pouches with improved sortability in mechanical recycling streams.
Market Restraints
- Ethylene and propylene feedstock volatility:Polyolefin resin prices track naphtha and natural gas liquids, creating margin compression for converters without resin hedging programs or backward integration into polymer production.
- Barrier film supply concentration:Capacity for EVOH and PVDC coextruded substrates clusters in Japan, Germany, and South Korea, exposing brand owners to logistics disruption and currency exposure.
- Mechanical recycling incompatibility:Multi-layer aluminum-polymer laminates face sorting rejection at materials recovery facilities, limiting circular economy claims and threatening retail channel access under emerging extended producer responsibility frameworks.
Strategic Opportunities
- India packaged food formalization:FSSAI enforcement of packaged food labeling and hygiene standards is displacing loose bulk distribution in spices, pulses, and edible oils, creating first-mover advantage for pre-qualified pouch suppliers.
- Pharmaceutical unit-dose expansion:Blow-fill-seal integration with four side-sealed secondary pouches enables aseptic packaging of biologics and vaccines without glass vial dependency, particularly for tropical climate distribution.
- California SB 54 implementation:The state's extended producer responsibility rules mandate 30% recycled content by 2030, creating premium pricing power for converters with verified post-consumer resin supply chains and mass balance certification.
Industry Challenges
- Barrier chemist talent scarcity:Formulation expertise in water-based coatings and bio-derived sealants sits concentrated with retired specialists from legacy flexible packaging majors, constraining R&D velocity for mid-tier converters.
- Migration testing timeline compression:FDA food-contact notification reviews for novel substrates extend 120-180 days, delaying commercial launches and consuming working capital during shelf-life validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Four Side-Sealed Pouches Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Stand-Up Pouches, Zipper Pouches, Liquid Pouches Material: Plastic, Aluminum, Paper, Composites Closure Type: Seal, Zipper, Tear Notch, Induction Seal End User: Food & Beverage, Personal Care, Pharmaceuticals, Others |
| Companies Covered | Ultimate Flexipack Limited, Fres-co System USA, Inc., Kanishka Technopack Industries, ProAmpac, Smurfit Kappa, Swiss Pac, Ampac Pty Ltd, Amcor, Constantia Flexibles Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Four Side-Sealed Pouches Market Emerging Trajectories
Active barrier technologies and substrate hybridization are collapsing the performance gap between conventional multi-material laminates and recyclable mono-material structures, while regulatory pressure accelerates the obsolescence of legacy chemistries.
PE-based mono-material pouches with EVOH oxygen barrier layers are hybridizing with tie-layer adhesives that maintain seal integrity across retort sterilization cycles. European dairy and pet food brands are qualifying these structures for 12-month shelf life applications previously reserved for foil laminates. The shift is compressing demand for aluminum oxide metallization in mid-barrier segments where transparency is not required.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorinated coatings from snack food packaging by 2026. Brand owners are reformulating with cellulose nanofiber and starch-based barrier coatings that require line speed reductions of 15-20%. German and French confectionery exporters face the steepest compliance costs due to existing equipment amortization schedules and high-volume production commitments.
Direct-to-consumer subscription models for specialty coffee and nutritional supplements are fragmenting order sizes and compressing production runs. E-commerce fulfillment centers in the Netherlands and California are rejecting corrugated overbox requirements for pouches below 150 mm width, forcing converter investment in inline printing and laser scoring for consumer-facing graphics. This channel shift is most visible in single-origin coffee and personalized vitamin segments where unboxing experience drives repeat purchase rates.
Four Side-Sealed Pouches Market Segmentation
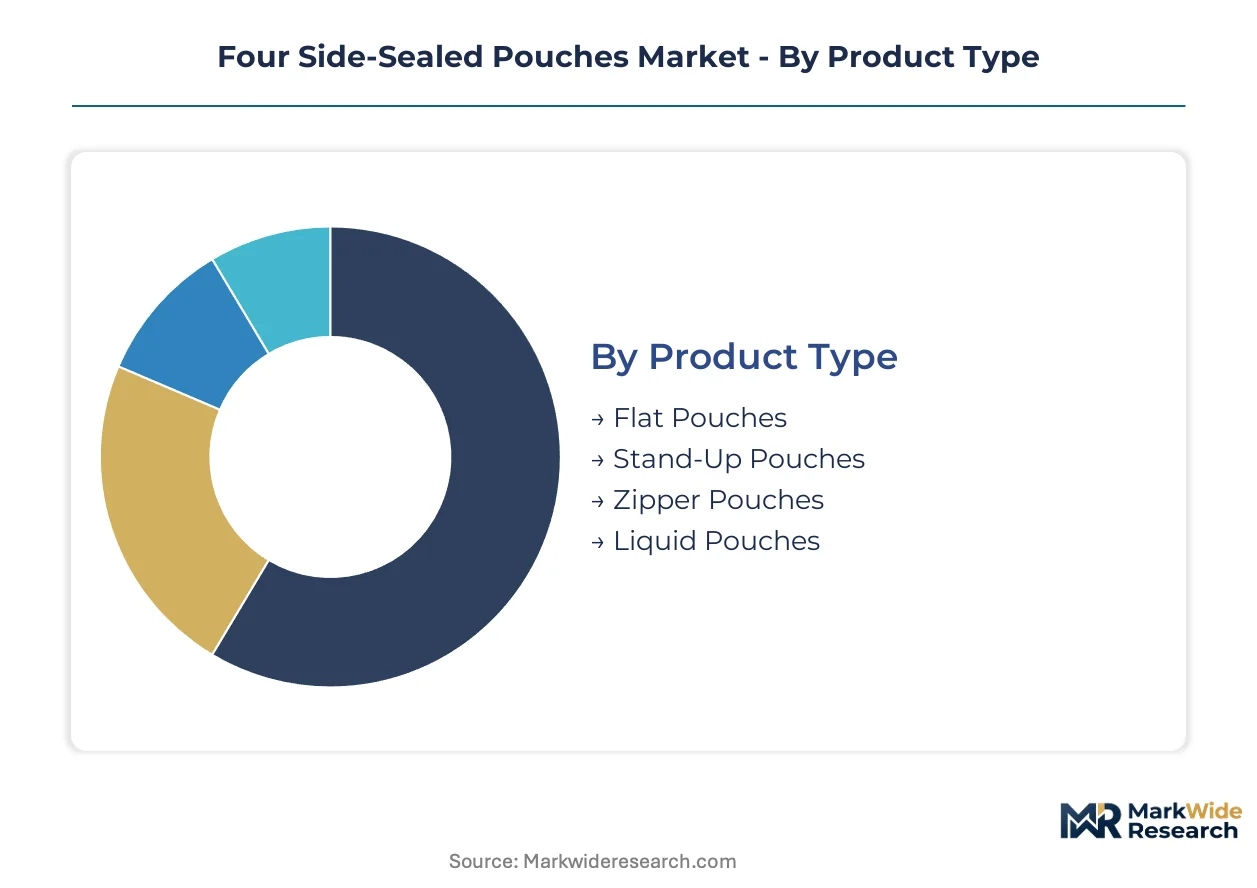
Four side-sealed pouches serve divergent functional requirements across product formats, material stacks, and end-use specifications. Understanding segment turnover velocity and margin stratification enables converters to allocate extrusion capacity and barrier-film procurement against predictable demand cycles.
Product Type:
Flat pouches turn inventory fastest in high-volume snack and condiment applications, while stand-up formats carry longer production lead times due to gusset welding complexity and brand-customized graphics.
- Flat Pouches:Two-dimensional sealed containers constructed from laminated PET/PE or aluminum oxide-coated films, optimized for pallet density and automated filling speeds. Demand concentrates in China's instant noodle seasoning sachets and India's spice portion packs where FSSAI hygiene mandates displace loose bulk distribution.
- Stand-Up Pouches:Bottom-gusseted structures with self-supporting bases enabling vertical shelf display, typically incorporating EVOH barrier layers for oxygen-sensitive contents. European dairy brands and US liquid detergent manufacturers specify these formats for retail differentiation, accepting 15-20% unit cost premiums over flat alternatives.
- Zipper Pouches:Reclosable interlocking profiles heat-sealed below the top edge, extending product usability across multiple consumption occasions.
- Liquid Pouches:High-seal-strength constructions with spout fitments or straw holes, engineered for beverage and sauce viscosity ranges.
Flat pouches anchor the volume base while stand-up configurations gain share at the steepest rate.
Material:
Cost tier stratification separates commodity polyolefins from precision-barrier laminates, with procurement cycles ranging from spot-market resin purchases to six-month aluminum foil contracts.
- Plastic:Mono-material PE or PP structures with EVOH oxygen barriers, increasingly specified for EU Packaging and Packaging Waste Regulation compliance. German pet food brands and French dairy processors are qualifying these for 12-month shelf life applications previously reserved for metallized laminates.
- Aluminum:Foil laminates delivering near-zero oxygen and moisture transmission rates for retort sterilization and aseptic pharmaceutical packaging. Japanese and South Korean converters dominate capacity, exposing brand owners to logistics disruption and currency exposure.
- Paper:Clay-coated and cellulose nanofiber barrier papers replacing PFAS grease-resistant coatings under REACH Annex XVII restrictions.
- Composites:Multi-layer aluminum-polymer laminates with highest barrier performance, facing mechanical recycling rejection at materials recovery facilities.
Plastic substrates command the widest application breadth while paper alternatives expand most quickly under regulatory pressure.
Closure Type:
Application criticality determines seal integrity specifications, from hermetic pharmaceutical induction seals to convenience-oriented tear notches in single-serve food portions.
- Seal:Permanent heat-sealed edges across all four sides, providing tamper-evidence and maximum barrier protection for oxygen-sensitive pharmaceuticals and retort-processed meals.
- Zipper:Reclosable profiles requiring precise interlock geometry and seal layer compatibility, extending product shelf life after initial opening in snack and pet food segments.
- Tear Notch:Laser-scored or die-cut initiation points for clean opening without tools, standard in condiment sachets and sample-size personal care.
- Induction Seal:Foil membranes hermetically bonded via electromagnetic heating, mandatory for liquid pharmaceuticals and probiotic supplements requiring aseptic integrity.
Permanent seals dominate unit volume while zipper closures climb fastest in premium repositioning applications.
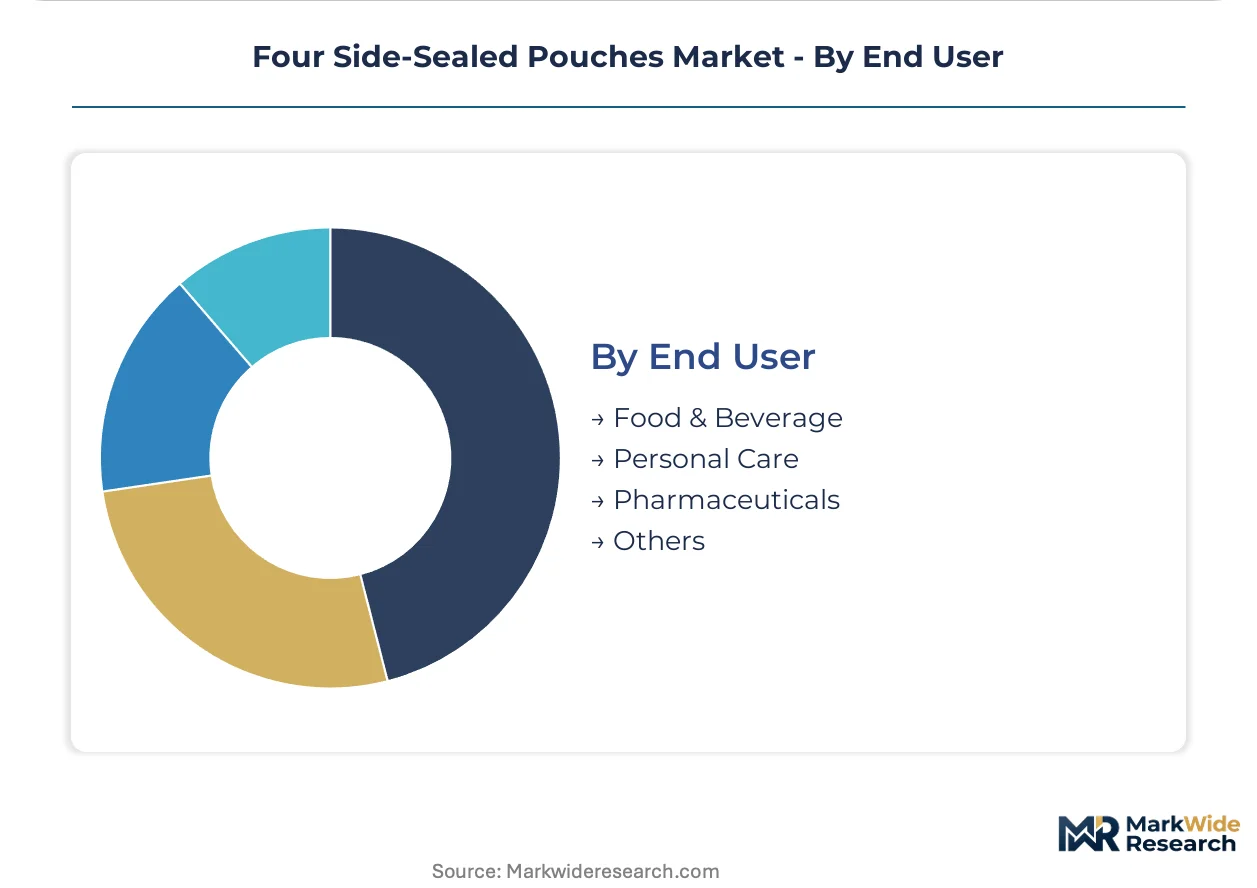
End User:
Customer procurement sophistication spans centralized category management in multinational food processors to fragmented specification-by-specification purchasing in pharmaceutical contract packagers.
- Food & Beverage:Ready-to-eat meal processors in China and North America converting retort tray lines to four side-sealed formats for microwave convenience. Steam-assisted structures eliminate venting requirements while maintaining hermetic integrity through sterilization cycles.
- Personal Care:Sample-size sachets and travel pouches for shampoo, conditioner, and skincare serums, where flat storage efficiency and portion control drive format selection.
- Pharmaceuticals:Unit-dose packaging for vaccines and biologics in tropical climates, integrating blow-fill-seal primary containers with four side-sealed secondary pouches to eliminate glass vial dependency.
- Others:Agricultural chemicals, industrial lubricants, and automotive fluids requiring chemical resistance and puncture tolerance.
Food and beverage anchors the volume base while pharmaceutical applications gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deep-water port underwrites China's dominance in flexible packaging trade, handling polymer resin imports and finished pouch exports that connect Asian converters to European and North American brand owners.
China
Domestic packaged food consumption drives retort pouch demand for instant meals and liquid concentrates. GB standards for composite packaging compliance reshape material procurement toward mono-material structures. Yangtze River Delta converters in Jiangsu and Zhejiang provinces scale aluminum oxide barrier-film capacity to serve local dairy and beverage brands.
United States
Ready-to-eat meal processors convert tray lines to four side-sealed formats for microwave convenience and portion control. California SB 54 mandates 30% recycled content by 2030, forcing substrate portfolio rewrites. Midwest converting clusters in Illinois and Wisconsin invest in post-consumer resin supply chains to maintain retail channel access.
Germany
EU Packaging and Packaging Waste Regulation recycled-content minimums compress multi-material laminate demand. ECHA REACH Annex XVII restrictions on PFAS grease barriers accelerate clay-coated paper adoption. Bavarian pet food brands and dairy processors qualify PE-based mono-material pouches for 12-month shelf life applications.
India
FSSAI enforcement of packaged food labeling displaces loose bulk distribution in spices, pulses, and edible oils. Domestic hygiene mandates create first-mover advantage for pre-qualified pouch suppliers. Gujarat and Maharashtra converting corridors expand barrier-film extrusion to capture formalizing food sector demand.
Japan
Pharmaceutical unit-dose packaging for biologics and vaccines integrates blow-fill-seal primary containers with four side-sealed secondary pouches. METI guidance on sustainable packaging steers R&D toward recyclable mono-material structures. Osaka-Kobe industrial zone maintains concentration in EVOH and PVDC coextruded substrate production.
Four Side-Sealed Pouches Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in resin extrusion and barrier-film supply. The vendor base stratifies between multinational converters with captive polymer production and regional specialists serving single-country markets. Three archetypes dominate: vertically integrated resin-to-pouch operators, technology-licensing barrier-film innovators, and regional pure-play converters. Capacity expansion and portfolio diversification toward recyclable mono-materials constitute the dominant competitive moves.
Among diversified packaging conglomerates, Amcor and ProAmpac exemplify platform-scale operators with upstream control over substrate quality, while Smurfit Kappa anchors European supply through regional converting plants. Ultimate Flexipack Limited represents the specialist tier focused on flexible format engineering. These entities occupy distinct competitive positions based on integration depth and geographic coverage rather than product-specific differentiation.
| Leading Market Players |
|---|
| Ultimate Flexipack Limited |
| Fres-co System USA, Inc. |
| Kanishka Technopack Industries |
| ProAmpac |
| Smurfit Kappa |
| Swiss Pac |
| Ampac Pty Ltd |
| Amcor |
| Constantia Flexibles Group |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port congestion swings freight costs for resin imports, compressing converter margins while amplifying price spreads between high-barrier foil laminates and commodity mono-material pouches across buyer tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates retort-capable aluminum oxide laminates from mid-tier EVOH structures and basic PE pouches. Price differentiation hinges on barrier certification grade and volume scale, with annual offtake commitments commanding 12-18% discounts over spot procurement. Pricing pressure stems from ethylene feedstock volatility eroding converter margins. Brand owners in private-label snacks exhibit highest price sensitivity; pharmaceutical contract packagers show lowest due to regulatory compliance premiums.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate supplier financing, straining working capital for mid-tier converters without supply-chain finance facilities. Raw material sourcing draws from Saudi Arabia for polyethylene resin, Japan for EVOH barrier films, and Germany for PVDC coextrusion substrates. Single-source vulnerability concentrates in Japanese EVOH capacity following recent Osaka plant consolidation. Distribution runs through regional converting clusters serving fresh produce and dairy brands within 500-kilometer radii.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Four side-sealed pouches enter a cyclical recovery phase as post-pandemic food service normalization restocks institutional packaging inventories and retail channel replenishment accelerates.
For Market Incumbents: Harden barrier-film supply security through captive extrusion capacity in Jiangsu province or six-year offtake agreements with Japanese EVOH producers. Consolidate position against emerging mono-material specialists by accelerating FDA food-contact notification pipelines for novel water-based coatings, compressing rival launch timelines by 90-120 days.
For New Entrants and Emerging Players: Pursue white-space opportunities in Indian spice portion packs where FSSAI hygiene mandates displace loose bulk distribution, and in pharmaceutical blow-fill-seal secondary pouches for tropical climate vaccines. Target Gujarat converting corridor entry through toll-manufacturing partnerships with established extrusion houses rather than greenfield capacity.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates spinning non-core flexible divisions; mid-tier converters with validated post-consumer resin supply chains and California SB 54 compliance infrastructure command premium multiples. Monitor aluminum oxide deposition equipment order backlogs as inflection indicator for transparent high-barrier capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier-Film Extrusion | Captive EVOH supply insulates Amcor and ProAmpac from Japanese logistics disruption and yen exposure. |
| Mono-Material Recyclable Structure Qualification | PE-based retort pouches with EVOH barriers unlock EU Packaging and Packaging Waste Regulation compliance for German dairy brands. |
| California SB 54 Recycled Content Certification | Verified post-consumer resin supply chains secure retail channel access under extended producer responsibility mandates. |
| Pharmaceutical Blow-Fill-Seal Integration | Secondary pouch pairing with aseptic primary containers eliminates glass vial dependency for tropical climate vaccine distribution. |
| India FSSAI Pre-Qualification Investment | Early compliance with packaged food hygiene standards captures first-mover advantage in formalizing spice and edible oil segments. |
Methodological Framework
Operator-level perspectives from extrusion plant managers, brand owner packaging engineers, resin procurement leads, and regulatory affairs directors anchored the qualitative base. Secondary validation drew from FDA food-contact notification databases, EU ECHA substance restriction filings, customs trade data for polymer resin imports, and SEC disclosures from listed packaging conglomerates. Bottom-up capacity modeling triangulated against top-down demand segmentation across product formats and end-use specifications.
Scenario-bracketing framed the analytical approach, with base, upside, and downside cases tested against feedstock price volatility and regulatory implementation delays across the projection horizon. Segmentation dimensions modeled include product type, material stack, closure specification, and end-use vertical. CAGRs derived from volume trajectory analysis incorporating capacity expansion announcements, line conversion schedules, and brand owner procurement pipeline visibility. Industry-specific inputs encompassed retort sterilization cycle validation timelines and EVOH barrier-film lead times.
Macroeconomic conditions sit as an overlay; deviation in naphtha pricing, ocean freight rates, or yuan-dollar exchange would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation schedules and substitution elasticity between barrier technologies. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Stick Pouches Packaging Market
Pouch
Kraft Pouch Market
Pouch
Clear Pouches Market
Pouch
High-Barrier Pouches Market
Pouch
Stand-Up Pouches Market
Pouch
Global Pre Zippered Pouches Market
Pouch
Automatic Pre-Made Pouch Packaging Machine Market
Pouch
Argentina Pouch Packaging Market
Pouch
Japan Pouch Packaging Market
Pouch
Feed Pouches Market
Pouch
Benelux Pouch Packaging Market
Pouch
Doyen Style Pouches Market
Pouch
Pillow Pouch Packaging Market
Pouch
Thailand Pouch Packaging Market
Pouch
Pre-Made Pouch Packaging Market
Pouch
Global Anti Static Bubble Pouch Market