
 Child Resistant Single Dose Pouches Market | 2026-2036
Child Resistant Single Dose Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Child Resistant Single Dose Pouches Market Outlook
ASTM D3475 classification for child-resistant packaging is redrawing competitive boundaries among pouch converters. Berry Global Inc. leverages multi-layer coextrusion capabilities to supply compliant structures for regulated cannabis and pharmaceutical clients. Amcor plc anchors its position through integrated film manufacturing and pre-qualified substrate libraries that accelerate customer certification timelines. Sonoco Products Company differentiates via rigid-flexible hybrid designs that bridge traditional blister packs and flexible pouch formats.
Child resistant single dose pouches are engineered flexible containers incorporating tear-resistant films, multi-point closure systems, and tactile opening mechanisms designed to prevent access by children under fifty-two months while remaining senior-friendly. These units typically employ oriented polypropylene or aluminum-laminate constructions with heat-sealed fin or lap seams to achieve hermetic barrier performance against moisture and oxygen ingress. Composite material structures currently lead volume owing to their balanced cost and barrier performance, while push-and-turn closure mechanisms command premium positioning due to higher tooling complexity and patent-protected designs. The cannabis industry vertical generates disproportionate growth momentum as state-level mandates proliferate, though pharmaceuticals retains the deepest qualification heritage and longest purchase cycles.
FDA 16 CFR 1700 poison prevention standards, ASTM D3475 test protocols, and state cannabis packaging boards collectively determine market access and product liability exposure for pouch suppliers. Compliance validation requires third-party laboratory certification, creating sustained demand for pre-qualified material platforms and documented batch consistency. Stakeholders must monitor evolving state cannabis regulations and pharmaceutical serialization requirements to align capital deployment with the highest-velocity qualification pathways.
Market Dynamics
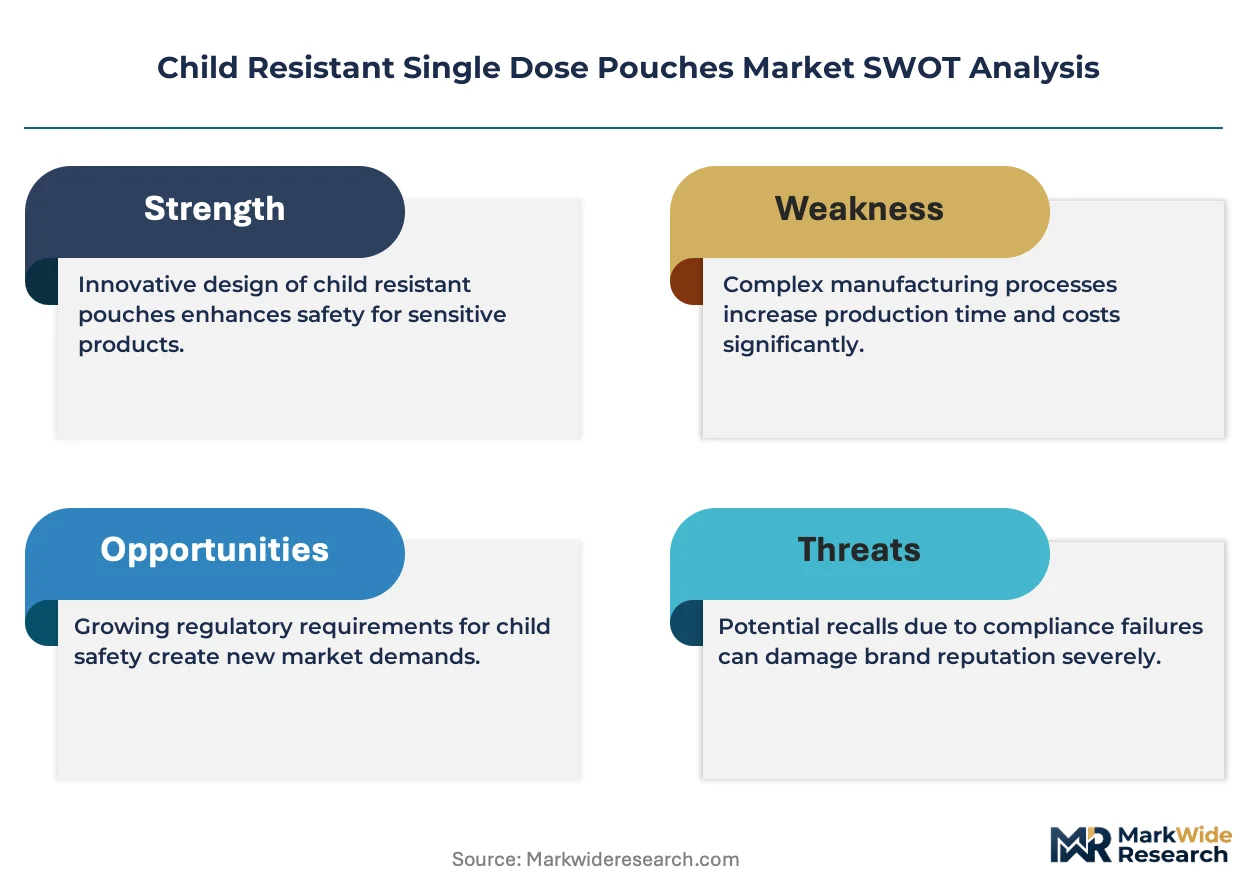
ASTM D3475 certification requirements are compressing supplier margins while creating tiered qualification barriers that favor converters with captive laboratory testing and documented batch traceability systems.
Growth Catalysts
- State cannabis packaging mandates:US state-level regulations for edibles and concentrates mandate child-resistant formats, creating sustained procurement volume from licensed dispensaries and processors.
- Pharmaceutical compliance packaging:Pediatric and geriatric medication protocols favor single-dose adherence formats that incorporate senior-friendly opening mechanisms alongside child-resistant properties.
- Multi-layer coextrusion advances:Barrier film technologies enable hermetic moisture and oxygen protection in flexible formats previously requiring rigid containers.
Market Restraints
- Aluminum-laminate input volatility:Commodity price swings for foil substrates compress converter margins and complicate long-term contract pricing.
- Third-party certification dependency:ASTM D3475 and FDA 16 CFR 1700 validation requires external laboratory testing, extending qualification timelines and concentrating access among pre-certified material platforms.
- Blister pack substitution:Rigid thermoformed formats retain preference for high-value pharmaceuticals with established cold-chain infrastructure.
Strategic Opportunities
- German pharmaceutical serialization:EU Falsified Medicines Directive implementation creates demand for unit-dose formats with integrated track-and-trace capabilities.
- Push-and-turn patent licensing:Premium closure mechanisms command price premiums through protected designs that differentiate commoditized film structures.
- Direct-to-pharmacy distribution:E-commerce channels for specialty medications bypass wholesale consolidation, enabling pouch converters to capture margin previously allocated to intermediaries.
Industry Challenges
- Regulatory harmonization gaps:Divergent state cannabis board requirements force SKU proliferation and complicate national-scale production planning.
- Senior-friendly design validation:ASTM senior-adult testing protocols add certification layers that extend product development cycles without guaranteed market acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child Resistant Single Dose Pouches Market |
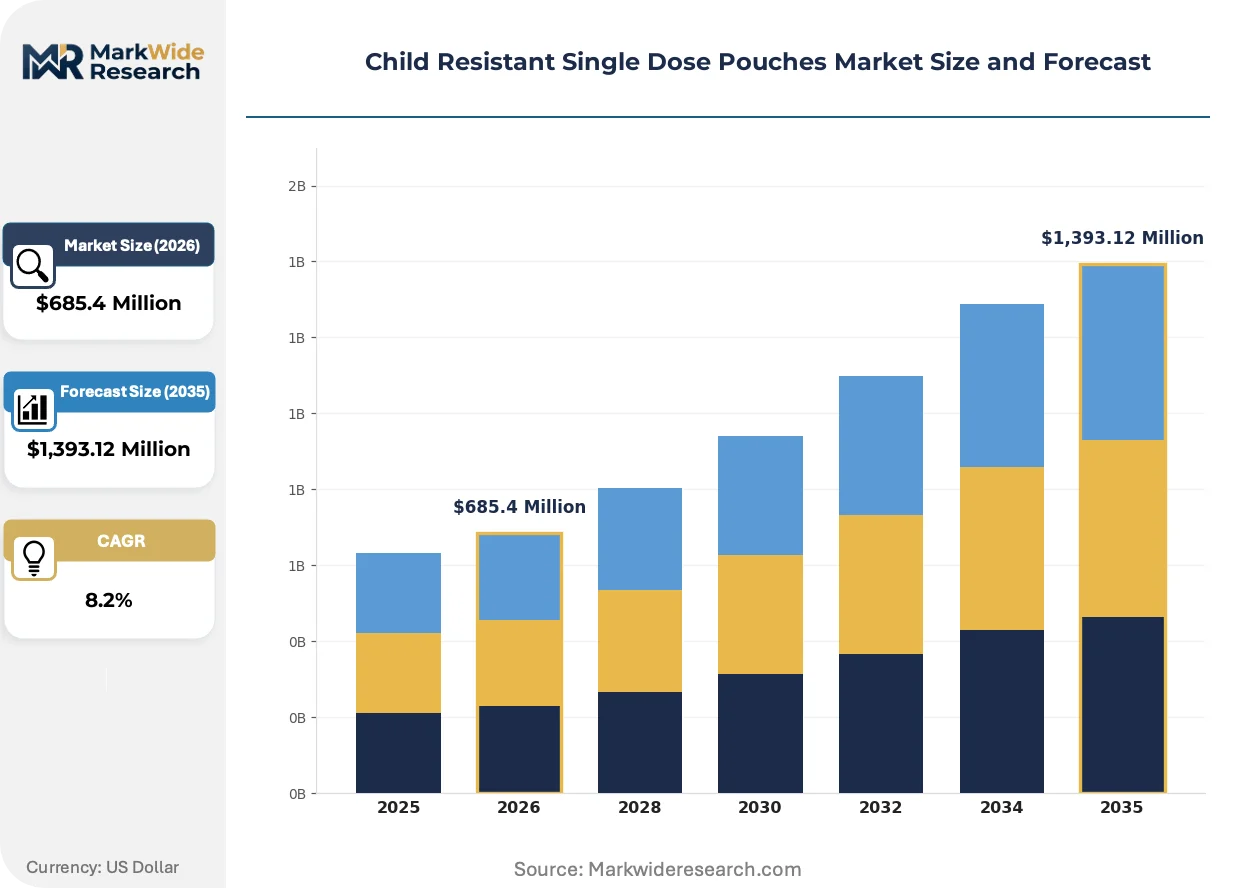
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Foil, Paper, Composite Closure Mechanism: Push and Turn, Squeeze, Locking, Flip-top Industry Vertical: Pharmaceuticals, Cannabis, Food & Beverages, Household Chemicals End User: Parents, Caregivers, Retailers, Manufacturers |
| Companies Covered | IMPAK Corporation, ePac Holdings LLC, CarePac, Amcor plc, Berry Global Inc., Constantia Flexibles, Sonoco Products Company, ProAmpac, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child Resistant Single Dose Pouches Market Strategic Shifts
Material science convergence with digital printing and smart packaging is redefining how compliance, authentication, and patient engagement integrate into single-dose formats.
Oriented polypropylene-aluminum hybrid laminates are fragmenting the traditional barrier film landscape by delivering metalized protection at reduced caliper weights. Cannabis processors in Colorado and California have accelerated adoption of these structures for concentrate packaging. The technology is fragmenting converter specialization patterns as generalist film suppliers capture share from dedicated pharmaceutical laminators.
EU MDR serialization requirements are mandating unique device identifiers on primary packaging, forcing pouch converters to integrate print-on-demand or pre-printed variable data layers. Medical device manufacturers serving European markets face compliance deadlines that compress supplier qualification windows. Germany and the Netherlands represent the most advanced implementation, with contract manufacturers already specifying 2D Data Matrix compatibility in procurement specifications.
Hospital and long-term care facilities are consolidating purchasing through group purchasing organizations that specify ASTM D3475 pre-certification as a table-stakes requirement. This procurement concentration displaces fragmented distributor relationships with direct converter contracts. The shift is most pronounced in the United States, where three national GPOs control the majority of acute-care pharmaceutical packaging spend.
Child Resistant Single Dose Pouches Market Segmentation
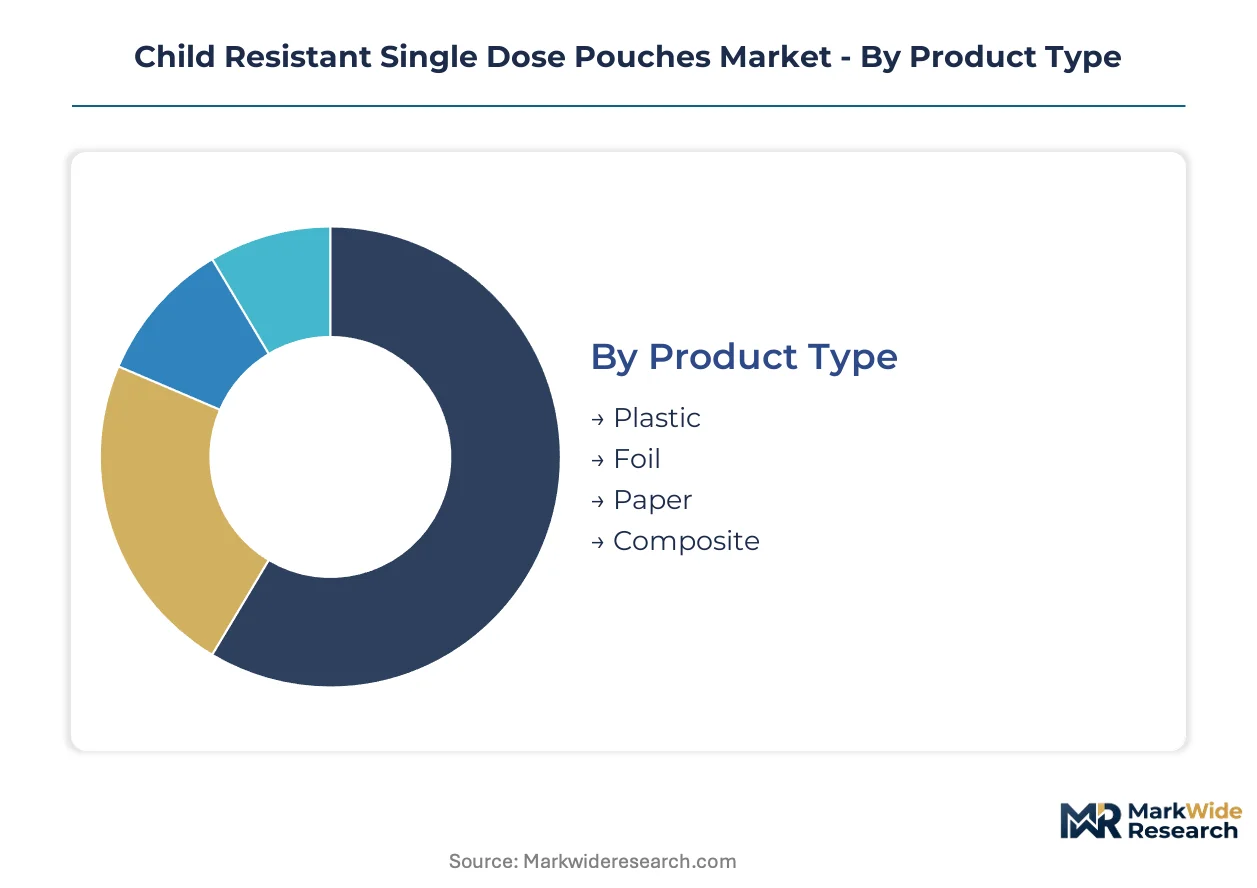
Segmentation in child resistant single dose pouches reveals how material selection, closure complexity, and regulatory exposure concentrate margin pools across converter portfolios. Each dimension carries distinct qualification burdens and pricing power dynamics that reshape supplier positioning.
Product Type:
Margin pools concentrate in multi-layer constructions where barrier performance justifies premium positioning against commodity substrates.
- Composite:Laminated structures combining oriented polypropylene with aluminum or ethylene vinyl alcohol deliver hermetic moisture and oxygen barriers. Cannabis processors in Colorado and California specify these formats for concentrate packaging to satisfy state board stability requirements. FDA 16 CFR 1700 certification timelines favor converters with pre-qualified composite libraries.
- Plastic:Mono-material polypropylene or polyethylene structures dominate high-volume pharmaceutical applications where cost efficiency outweighs extended shelf-life demands. Geriatric medication compliance programs in long-term care facilities specify plastic pouches for short-cycle dispensing protocols.
- Foil:Aluminum-laminate substrates provide maximum barrier protection for moisture-sensitive APIs.
- Paper:Fiber-based structures with polymer coatings serve limited applications in sustainability-focused pilot programs.
The dominant share belongs to Composite, while Plastic is closing the gap fastest through pharmaceutical serialization mandates.
Closure Mechanism:
Patent-protected designs command price premiums through differentiation that commoditized film structures cannot replicate.
- Push and Turn:Rotational locking systems requiring simultaneous compression and torque represent the most stringent ASTM D3475 certification tier. Tooling complexity and royalty structures limit supplier participation to converters with captive engineering capabilities. German pharmaceutical manufacturers specify push-and-turn formats for EU MDR compliance packaging.
- Squeeze:Compression-activated openings balance child resistance with senior accessibility through tactile feedback mechanisms. Massachusetts and Illinois cannabis regulations explicitly recognize squeeze closures as compliant for edible packaging.
- Locking:Multi-point latch systems secure contents through sequential engagement.
- Flip-top:Hinged rigid components bridge flexible pouch formats with traditional blister pack familiarity.
Push and Turn captures the steepest expansion trajectory as serialization requirements favor unit-dose formats with tamper-evident integration.
Industry Vertical:
Regulatory velocity determines procurement cycle length and supplier qualification investment recovery.
- Pharmaceuticals:Pediatric and geriatric medication protocols drive demand for single-dose adherence formats with documented batch traceability. EU Falsified Medicines Directive implementation compresses supplier qualification windows for contract manufacturers serving European markets.
- Cannabis:State-level mandates for edibles and concentrates create procurement volume from licensed dispensaries and processors. Divergent requirements across California, Colorado, and Massachusetts force SKU proliferation.
- Food & Beverages:Nicotine pouch and supplement applications adopt child-resistant formats ahead of anticipated regulatory expansion.
- Household Chemicals:Laundry detergent pods and cleaning concentrates represent emerging specification territory.
Pharmaceuticals retains the deepest qualification heritage, though Cannabis is expanding most quickly through mandate proliferation.
End User:
Purchasing authority concentration reshapes distribution economics and direct converter relationships.
- Manufacturers:Brand-owning pharmaceutical and cannabis companies specify primary packaging through procurement teams with ASTM D3475 pre-certification requirements. Three national group purchasing organizations in the United States control the majority of acute-care pharmaceutical packaging spend.
- Retailers:Licensed dispensaries and pharmacy chains specify secondary compliance packaging for repackaged or private-label products.
- Parents:Direct consumer purchasing remains minimal outside subscription medication services.
- Caregivers:Institutional procurement through long-term care facilities consolidates volume.
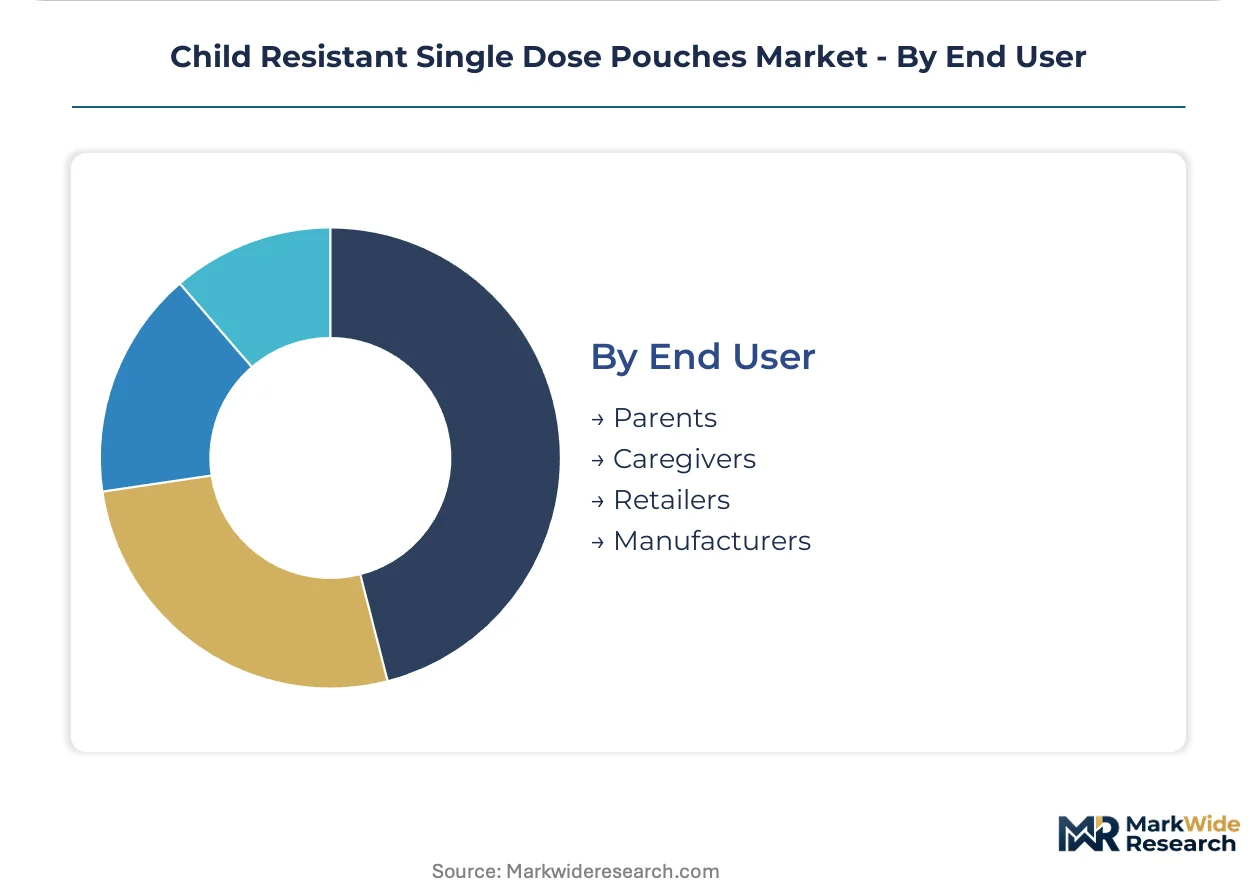
Manufacturers command the dominant procurement volume, while Retailers are gaining specification authority fastest through vertical integration into packaging decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex anchors North American import logistics for barrier film substrates, while Rotterdam's Europoort terminal serves equivalent throughput for European pharmaceutical converters.
United States
State cannabis boards in Colorado and California mandate child-resistant formats for edibles, driving procurement from licensed processors. FDA 16 CFR 1700 poison prevention standards govern pharmaceutical applications through third-party laboratory certification. Denver and Oakland host concentrated clusters of cannabis packaging converters serving multi-state operators.
Germany
EU MDR serialization deadlines compress supplier qualification windows for contract manufacturers. EMA guidelines on pediatric medication packaging favor unit-dose adherence formats with documented batch traceability. The Rhine-Main region around Frankfurt concentrates pharmaceutical packaging engineering capabilities for export markets.
Canada
Health Canada and PMRA regulations align with ASTM D3475 protocols for cannabis concentrates and pediatric pharmaceuticals. Licensed producers in Ontario and British Columbia specify pre-certified barrier structures to accelerate product registration timelines. Toronto's packaging district hosts converters serving both domestic and US cross-border demand.
Netherlands
Rotterdam's port infrastructure enables just-in-time delivery of aluminum-laminate substrates from Asian suppliers. EMA coordination with national regulators streamlines multi-market certification for pouch converters. The Eindhoven-Tilburg corridor concentrates flexible packaging R&D facilities serving German pharmaceutical clients.
Australia
TGA requirements for prescription medication packaging incorporate child-resistance testing aligned with ISO 8317 protocols. Cannabis legalization in multiple states creates emerging demand for compliant single-dose formats. Melbourne's manufacturing belt hosts converters supplying hospital and long-term care group purchasing organizations.
Child Resistant Single Dose Pouches Market Competitive Environment
Listed leaders compete with private specialists across certification infrastructure and captive testing capabilities. The supplier base organizes into three tiers: integrated multinationals with pre-qualified substrate libraries, mid-scale converters with regional ASTM D3475 accreditation, and specialized cannabis-focused fabricators with state-level compliance expertise. Dominant competitive moves include backward integration into film manufacturing and strategic partnerships with third-party testing laboratories to compress customer certification timelines.
Within the integrated multinational tier, Amcor plc and Berry Global Inc. exemplify converters with captive film production and documented batch traceability systems. Sonoco Products Company occupies a position bridging rigid and flexible formats through hybrid engineering capabilities. Private specialists including ePac Holdings LLC and ProAmpac represent the mid-scale accreditation tier, serving regional pharmaceutical and cannabis processors with faster qualification turnaround.
| Leading Market Players |
|---|
| IMPAK Corporation |
| ePac Holdings LLC |
| CarePac |
| Amcor plc |
| Berry Global Inc. |
| Constantia Flexibles |
| Sonoco Products Company |
| ProAmpac |
| Huhtamaki |
| Others |
Value Chain & Pricing Dynamics
FDA 16 CFR 1700 certification requirements gate both supplier qualification and price differentiation simultaneously, compressing margins for converters without pre-qualified substrate libraries while enabling premium positioning for those with documented batch traceability. ASTM D3475 testing costs concentrate pricing power among integrated multinationals that amortize laboratory investments across high-volume pharmaceutical and cannabis contracts.
Pricing Analysis
Volume-discount tiering structures separate push-and-turn closure premiums from squeeze-mechanism standard tiers and plastic mono-material economy lots. Price differentiation rests on ASTM D3475 certification grade and multi-layer coextrusion complexity, with cannabis processors in Colorado and California showing highest sensitivity to per-unit costs. Cost compression in standard-tier composite laminates is intensifying because aluminum foil commodity volatility transfers directly to converter margins.
Supply Chain Analysis
Strait of Malacca transit underwrites oriented polypropylene resin flows from South Korean and Thai petrochemical complexes to North American converters. Raw material dependencies center on aluminum foil from Chinese smelters, ethylene vinyl alcohol copolymers from Japanese suppliers, and specialty adhesives from German chemical producers. Single-source vulnerability concentrates in aluminum-laminate substrates where tariff exposure on Chinese foil disrupts contract pricing. Distribution runs through three national group purchasing organizations that consolidate acute-care pharmaceutical packaging procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR serialization mandates are disrupting qualification timelines, creating acquisition opportunities for converters with integrated track-and-trace capabilities and pre-certified variable data platforms.
For Market Incumbents: Fortify ASTM D3475 captive testing infrastructure against mid-scale competitors relying on third-party laboratories. Backward integration into oriented polypropylene film manufacturing defends margin position against commodity substrate volatility. Acquire regional cannabis-focused fabricators in Massachusetts and Illinois to capture state-mandate procurement volume before qualification windows close. For New Entrants and Emerging Players: Anchor in Australian long-term care group purchasing channels where TGA requirements lag FDA implementation and create qualification arbitrage. Target nicotine pouch and supplement applications in food and beverages ahead of anticipated regulatory expansion. Deploy direct-to-pharmacy e-commerce distribution to bypass wholesale consolidation and capture intermediary margin. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across push-and-turn closure tooling as patent licensing fees and rotational molding equipment costs escalate. Five-to-ten year viability favors converters with hybrid rigid-flexible engineering capabilities bridging blister pack substitution threats. Monitor German pharmaceutical serialization compliance deadlines as inflection indicator for EU MDR-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM D3475 Certification Investment | Pre-qualified substrate libraries compress customer onboarding timelines for pharmaceutical manufacturers. |
| Multi-layer Coextrusion Capacity Expansion | Hermetic barrier performance captures cannabis concentrate packaging mandates in Colorado and California. |
| Backward Integration into Film Manufacturing | Captive polypropylene production insulates margins from Asian resin price volatility. |
| EU MDR Serialization Platform Development | 2D Data Matrix compatibility opens German and Dutch pharmaceutical contract manufacturing channels. |
| Direct-to-Pharmacy Distribution Launch | E-commerce channels bypass wholesale consolidation for specialty medication pouch procurement. |
Study Parameters
Cross-validation between primary interviews with packaging procurement managers at pharmaceutical manufacturers and secondary validation through FDA 510(k) filings anchors the qualitative findings. Conversations with cannabis packaging converters in Denver and Oakland, group purchasing organization contracts managers, and ASTM D3475 laboratory directors combined with customs trade data, state cannabis board regulatory filings, and SEC 10-K disclosures from listed packaging multinationals. Bottom-up volume estimates from substrate consumption patterns triangulate against top-down pharmaceutical and cannabis market sizing.
Sensitivity analysis across material cost scenarios, regulatory implementation timelines, and substitution elasticity parameters stress-tests the analytical framework. Segmentation dimensions modeled include closure mechanism complexity, barrier performance tier, industry vertical regulatory cluster, and geographic certification pathway across the projection horizon. CAGRs derive from historical qualification velocity and mandated adoption curves for pediatric medication and cannabis edible packaging. Forecast inputs incorporate aluminum foil commodity price trajectories and EU MDR serialization compliance deadlines.
Material uncertainties — state cannabis board requirement divergence, ASTM senior-adult testing protocol revisions, and aluminum-laminate input volatility — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization velocity and pharmaceutical serialization adoption curves. Practitioners should keep alternative scenarios live as state-level cannabis mandate proliferation and EU MDR implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Ziplock Products Market
Pouch
Benelux Pouch Packaging Market
Pouch
Automatic Pre-Made Pouch Packaging Machine Market
Pouch
PCR Pouches Market
Pouch
Inflatable Pouches Market
Pouch
Pouch Dispensing Fitment Market
Pouch
Inverted Pouch Market
Pouch
Open Mouth Sacks Market
Pouch
Flexible Pouch Market
Pouch
Spain Pouch Packaging Market
Pouch
High-Barrier Pouches Market
Pouch
Dual-Chamber Pouches Market
Pouch
Monodose Packs Market
Pouch
United States Retort Pouches Market
Pouch
Poland Pouch Packaging Market
Pouch
Aluminum Pouches Market