
 Spinal Implants and Devices Market | 2026-2036
Spinal Implants and Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Implants and Devices Market Intelligence
The rise of ambulatory surgery centers as a primary site for spinal procedures is reorganizing historical purchasing patterns once dominated by large hospital networks. Medtronic plc leverages its extensive product portfolio and global distribution to serve both of these settings effectively. Meanwhile, Globus Medical specializes in innovative technologies like robotic-assisted surgery, targeting high-volume orthopedic centers and specialty clinics. Stryker Corporation competes through its broad offering in both fusion and non-fusion devices, maintaining a strong presence across multiple price points.
Spinal implants and devices are medical products surgically placed to stabilize and correct deformities of the spine. These products, often manufactured from materials like titanium alloys or PEEK, are designed to facilitate fusion, preserve motion, or replace damaged vertebral components. Fusion devices represent the largest product segment, though non-fusion technologies for motion preservation are gaining traction among younger patients. The adoption of minimally invasive surgery and computer-assisted navigation defines the market's premium technology tier.
Market access is governed by stringent regulatory approvals from bodies such as the FDA in the United States and the EMA under the MDR framework in Europe. Compliance with the ISO 13485 standard for quality management systems is a universal prerequisite for manufacturers seeking to commercialize their products globally. Stakeholder success will hinge on navigating evolving reimbursement landscapes and demonstrating clear clinical and economic value for new technologies.
Market Dynamics
The increasing emphasis on clinical and economic value by payors and providers is the central force shaping the market. This pressure compels manufacturers to innovate beyond product features, focusing on procedural efficiency and improved patient-reported outcomes to justify premium pricing.
Growth Catalysts
- Advanced Manufacturing:The adoption of 3D printing and additive manufacturing allows for the creation of porous titanium and PEEK-based implants with bone-like structures, promoting better osseointegration.
- Demographic Shifts:Aging populations in countries like Japan and Germany, coupled with a higher prevalence of degenerative spinal conditions, are expanding the eligible patient pool for surgical intervention.
- Site-of-Care Migration:Policy and reimbursement shifts encouraging procedures in ambulatory surgery centers create demand for implant systems optimized for minimally invasive, efficient surgeries.
Market Restraints
- Raw Material Costs:Price volatility and supply chain constraints for medical-grade titanium alloys and implantable PEEK polymer directly impact the manufacturing cost structure and final device pricing.
- Regulatory Scrutiny:Stringent pre-market approval pathways, such as the FDA's PMA process and the EU's MDR requirements, create long and costly development timelines for novel devices.
- Non-Surgical Competition:Advances in physical therapy, pain management pharmaceuticals, and interventional spine procedures present effective non-operative alternatives for a subset of patients with spinal pathologies.
Strategic Opportunities
- Emerging Market Penetration:Expanding healthcare infrastructure and rising disposable incomes in countries like Brazil and India present significant growth opportunities for established spinal device technologies.
- Biologics and Regenerative Medicine:Development of bone graft substitutes, growth factors, and cell-based therapies to enhance fusion or stimulate disc regeneration represents a new frontier for spinal treatment.
- Surgical Technology Convergence:Integrating augmented reality overlays with robotic-assisted surgical platforms offers the potential for enhanced precision and improved procedural workflows in complex spine surgery.
Industry Challenges
- Specialized Skill Requirements:The effective use of robotic surgery systems and advanced navigation technologies requires extensive surgeon training and credentialing, limiting initial adoption rates.
- Reimbursement Complexity:Navigating disparate and evolving reimbursement codes and payment policies for new technologies across national systems, from the US DRG system to Germany's G-BA, is a constant operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Implants and Devices Market |
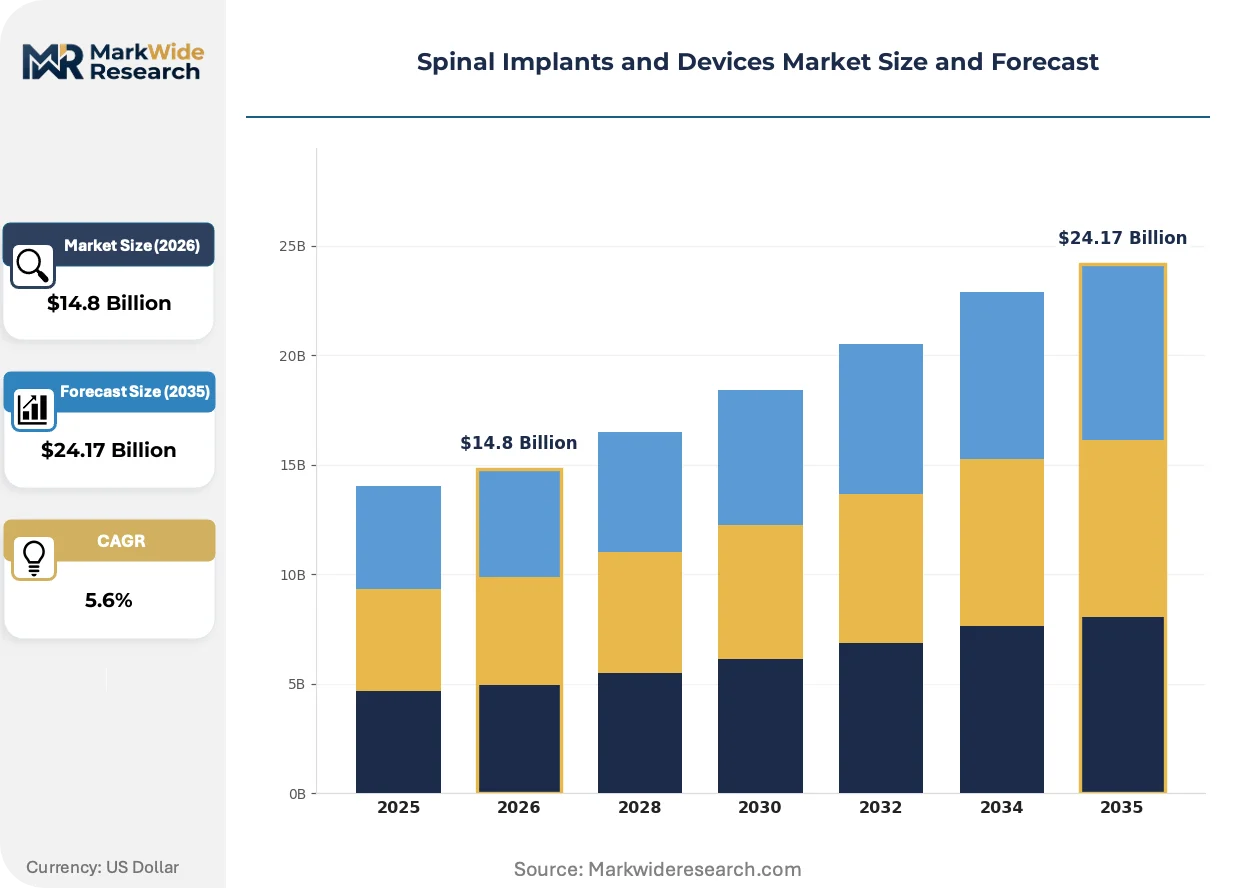
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fusion Devices, Non-fusion Devices, Spinal Biologics, Vertebral Bodies End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Ambulatory Surgery Centers Technology: Minimally Invasive Surgery, Computer-assisted Navigation, Robotic Assistance, Traditional Surgery Application: Degenerative Disc Disease, Spinal Stenosis, Scoliosis, Trauma |
| Companies Covered | Medtronic plc, Johnson & Johnson (DePuy Synthes), Stryker Corporation, Zimmer Biomet, Globus Medical, NuVasive, Alphatec Spine, Orthofix Holdings, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Implants and Devices Market Strategic Shifts & Innovations
Innovation within the spinal implant sector is defined by a dual pursuit of personalization and procedural standardization. This creates a market where technologies must simultaneously cater to unique patient anatomy while also enabling scalable, reproducible surgical outcomes for broader adoption.
Patient-specific implants, created using 3D printing with materials like porous titanium, are designed to precisely match an individual's vertebral anatomy. High-volume orthopedic centers adopt these for complex deformity and revision surgeries. This technology is bifurcating the market into standardized off-the-shelf devices and premium-priced, highly customized solutions for anatomically challenging cases.
Europe's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence and post-market surveillance on all medical devices. This regulation increases the compliance burden and costs for spinal device manufacturers seeking CE marking. Products with long-term clinical data are gaining a competitive advantage under this framework.
A notable behavioral shift involves ambulatory surgery centers consolidating their purchasing power through specialized buying consortia and group purchasing organizations. This model often bypasses traditional sales channels, favoring vendors who provide transparent, volume-based pricing and simplified inventory management. This pattern is highly visible in the United States healthcare market.
Spinal Implants and Devices Market Segmentation
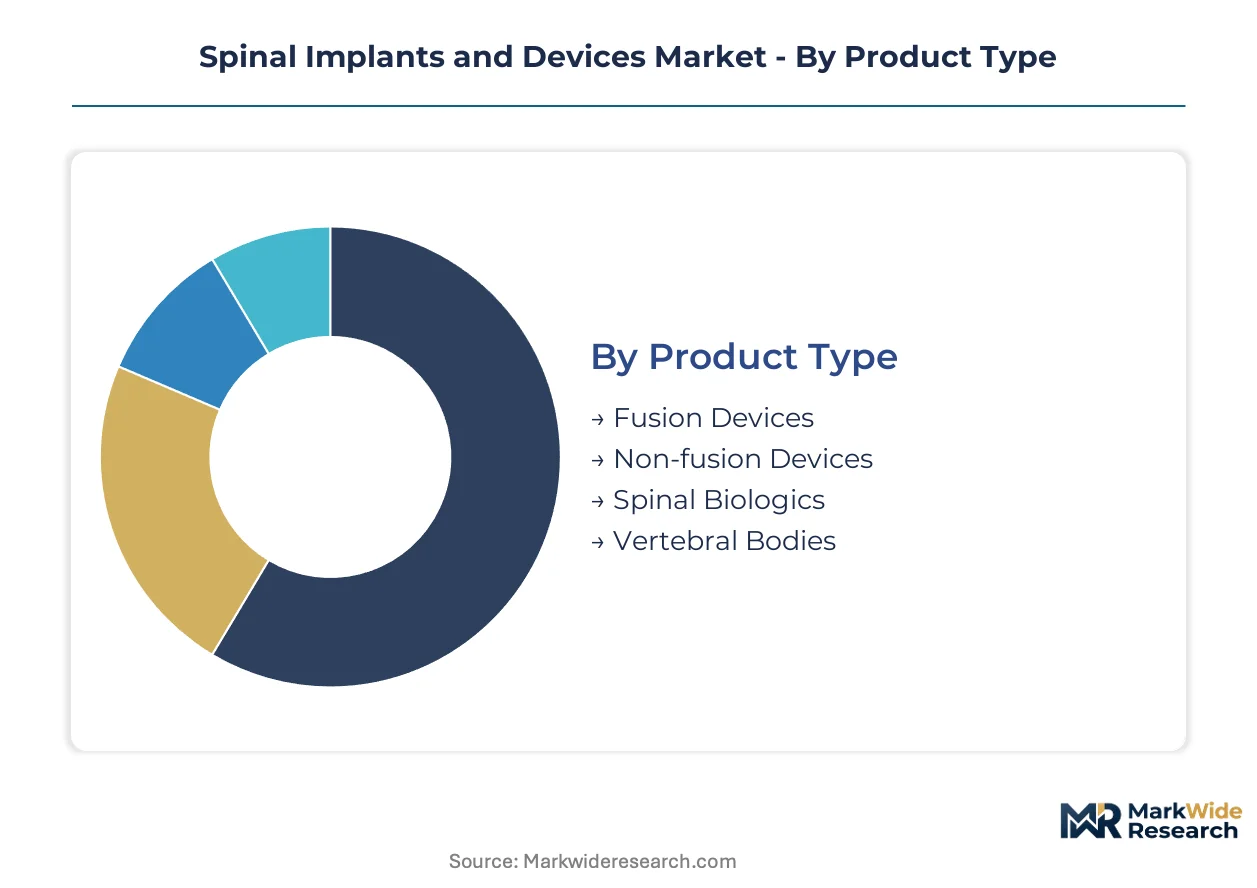
Segmentation within the spinal implants and devices market reveals distinct demand patterns and competitive dynamics. Understanding these categories is crucial for manufacturers to align product development and market access strategies with evolving clinical needs and healthcare delivery models.
Product Type:
Substitution pressure significantly influences product type segmentation, as non-operative treatments and next-generation technologies continuously challenge established implant categories.
- Fusion Devices:These implants stabilize adjacent vertebrae, often using rods, screws, and cages to promote bone growth across the segment. Demand concentrates in older populations across the United States, driven by the prevalence of degenerative spinal conditions requiring definitive stabilization.
- Non-fusion Devices:Designed to preserve motion at the spinal segment, these devices include artificial discs and dynamic stabilization systems. Younger patients in European markets increasingly seek these solutions, valuing preserved mobility and reduced adjacent segment disease risk.
- Spinal Biologics:These include bone graft substitutes and growth factors, enhancing fusion rates and promoting bone regeneration.
- Vertebral Bodies:Implants designed to replace diseased or damaged vertebral bodies, often used in tumor or trauma cases.
Fusion Devices retain volume leadership; Non-fusion Devices hold the steepest expansion curve.
End User:
Procurement patterns are shifting across end-user segments, reflecting differing operational scales and patient care models.
- Hospitals:Large institutional settings provide comprehensive surgical care, handling complex cases and high patient volumes. Procurement patterns in German hospitals prioritize integrated solutions and comprehensive service contracts, reflecting their broad patient base.
- Ambulatory Surgery Centers:Specialized outpatient facilities performing minimally invasive spinal procedures, emphasizing efficiency and cost-effectiveness. These centers in the United States drive demand for streamlined implant systems and transparent, volume-based pricing structures.
- Orthopedic Clinics:These outpatient facilities primarily focus on diagnosis, non-surgical treatment, and post-operative follow-up for spinal conditions.
- Rehabilitation Centers:Facilities specializing in physical therapy and recovery programs for patients post-spinal surgery or injury.
Market share dynamics are being reshaped by the increasing procedural migration towards Ambulatory Surgery Centers, while Hospitals maintain their foundational role.
Technology:
Innovation velocity varies significantly across technology segments, with newer platforms driving premiumization and requiring specialized training.
- Minimally Invasive Surgery:Techniques involving smaller incisions, specialized instruments, and endoscopic visualization to reduce tissue disruption and recovery time. Patient preference in countries like Canada drives demand for less invasive options, reducing hospital stays and improving outcomes.
- Robotic Assistance:Surgical platforms providing enhanced precision and visualization through robotic arms guided by pre-operative planning and intra-operative imaging. High-volume orthopedic centers in Japan are adopting these systems to improve accuracy and standardize complex spinal procedures.
- Computer-assisted Navigation:Systems that use real-time imaging and tracking to guide instrument placement during spinal surgery, enhancing accuracy.
- Traditional Surgery:Open surgical techniques involving larger incisions to directly visualize and access the spinal anatomy for complex or extensive interventions.
Adoption rates for Robotic Assistance are rapidly expanding, while Traditional Surgery continues to be the bedrock for complex interventions.
Application:
The patient pool size and demographic characteristics define demand patterns across various application segments.
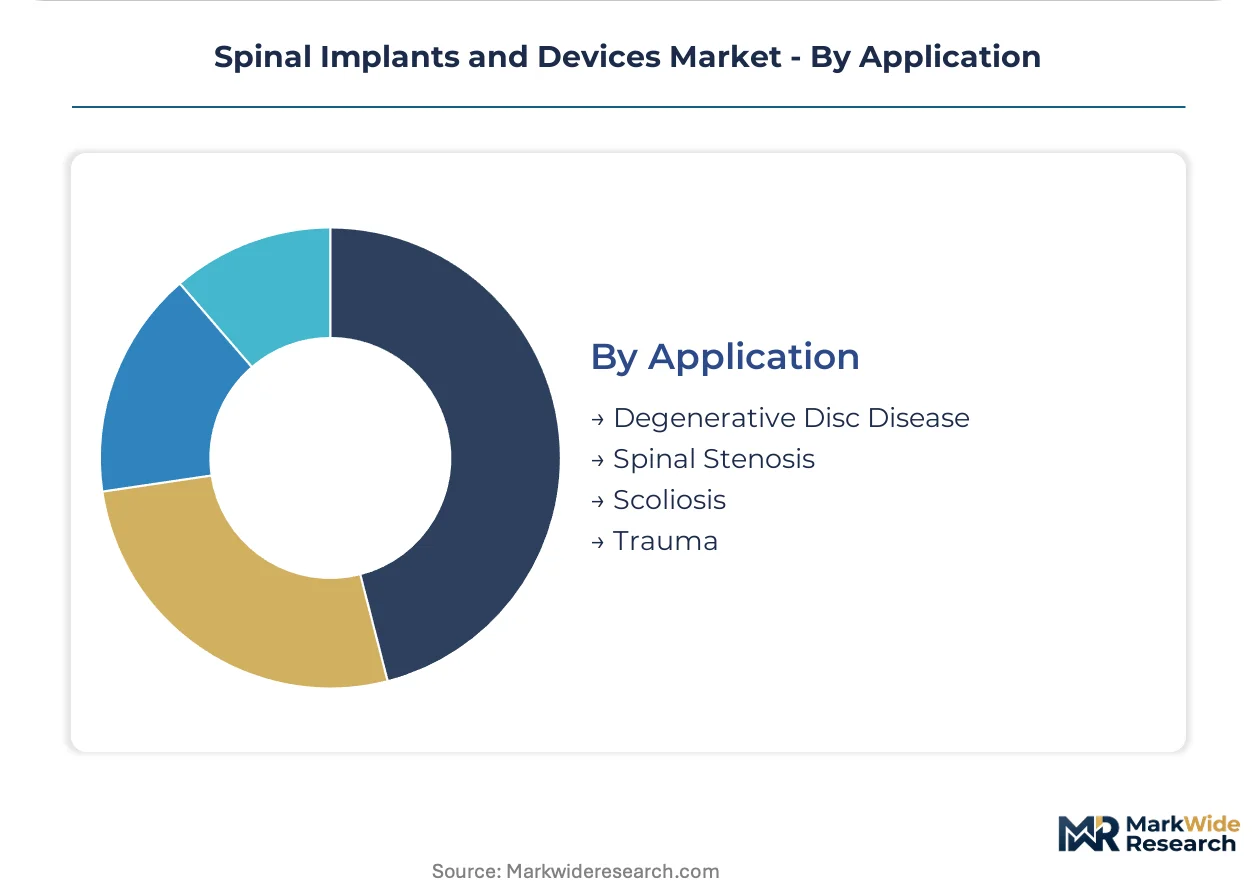
- Degenerative Disc Disease:Conditions arising from the breakdown of intervertebral discs, leading to pain, instability, and neurological symptoms requiring surgical intervention. Aging populations in the United States significantly drive the volume of surgical treatments for this widespread condition.
- Spinal Stenosis:Narrowing of the spinal canal, often due to age-related changes, compressing nerves and causing pain, numbness, or weakness. European healthcare systems observe a consistent demand for decompression and stabilization procedures due to increasing prevalence among seniors.
- Scoliosis:Lateral curvature of the spine, often treated surgically with fusion devices in adolescent and adult populations.
- Trauma:Spinal injuries resulting from accidents or falls, requiring immediate surgical stabilization to prevent neurological damage.
The largest patient cohorts fall under Degenerative Disc Disease, with Spinal Stenosis representing a significant and growing surgical burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for advanced spinal implants from the United States significantly influences global trade flows, with key manufacturing hubs in Europe and Asia supplying specialized devices. Germany and Japan, with their aging demographics, also represent substantial end-markets. Brazil and India are emerging as critical growth territories for established spinal implant technologies.
United States
Demand for fusion devices in the United States is driven by the high prevalence of degenerative disc disease among its aging population. The FDA's stringent pre-market approval process ensures device safety and efficacy before market entry. Advanced healthcare infrastructure in states like California and Massachusetts supports innovative spinal surgery techniques.
Germany
German hospitals prioritize integrated solutions for spinal care, reflecting a broad patient base and complex case management. The EMA's MDR framework imposes strict requirements for clinical evidence on devices sold across Europe. Munich and Berlin host significant medical technology clusters, fostering research and development in spinal devices.
Japan
Japan's rapidly aging population experiences a high incidence of spinal stenosis, necessitating advanced surgical interventions. The PMDA regulates medical devices, ensuring compliance with national quality and safety standards. High-volume orthopedic centers in Tokyo are early adopters of robotic-assisted surgical platforms.
Brazil
Expanding healthcare infrastructure in Brazil contributes to rising demand for established spinal device technologies. ANVISA, the national health surveillance agency, oversees the registration and commercialization of medical products. Sao Paulo and Rio de Janeiro represent major medical hubs, driving the adoption of new surgical techniques.
India
India's rising disposable incomes and improving healthcare access are creating new opportunities for spinal implant manufacturers. The CDSCO regulates medical devices, focusing on quality and affordability for its large population. Bengaluru's medical technology sector is growing, attracting investment in local manufacturing and distribution.
Spinal Implants and Devices Market Key Industry Players
Listed leaders compete with private specialists across technology innovation and market access strategies. The spinal implants market exhibits a tiered structure, with large multinational corporations coexisting with niche technology developers. Companies prioritize strategic partnerships and portfolio diversification to maintain competitive positioning.
Specialists in advanced surgical solutions, such as Medtronic plc, leverage extensive global distribution networks to serve diverse healthcare settings. Globus Medical exemplifies innovation in robotic-assisted surgery, targeting high-volume orthopedic centers with its specialized platforms. Stryker Corporation occupies a strong position through a broad offering in both fusion and non-fusion devices.
| Leading Market Players |
|---|
| Medtronic plc |
| Johnson & Johnson (DePuy Synthes) |
| Stryker Corporation |
| Zimmer Biomet |
| Globus Medical |
| NuVasive |
| Alphatec Spine |
| Orthofix Holdings |
| B. Braun Melsungen AG |
| Others |
Cost & Logistics Intelligence
High volume manufacturing of PEEK and titanium implants drives scale economies, influencing global supply concentration and establishing competitive price floors for standardized devices. This manufacturing efficiency shapes market access for diverse product offerings.
Pricing Analysis
The pricing gap between traditional fusion devices and next-generation robotic-assisted platforms reflects differing value propositions. Per-unit transactional pricing dominates, though value-based agreements emerge for advanced technologies. Price differentiation stems from material quality, regulatory certification like FDA approval, and the level of patient-specific customization. Pricing softness intensifies across standardized products due to consolidated purchasing power from ambulatory surgery centers, making them highly price-sensitive buyers.
Supply Chain Analysis
Volatility in medical-grade titanium and PEEK polymer supply presents a chokepoint for implant manufacturing. Global supply for these critical raw materials primarily sources from specialized chemical and metal processing hubs in Asia and Europe. Commodity price volatility for these inputs poses a significant structural risk, impacting manufacturing costs and final device pricing. Distribution networks for established products extend globally through large medical device firms, while niche technologies often utilize direct sales to specialized centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spinal implants market functions as a high-growth disruption, driven by the technological inflection of robotic-assisted surgery platforms. This innovation reshapes surgical precision and patient outcomes, creating new competitive dynamics.
For Market Incumbents: Consolidate market position by acquiring niche technology developers specializing in patient-specific implants or biologics. Expand product portfolios to offer comprehensive solutions across fusion and non-fusion devices, mitigating the threat from non-surgical alternatives. Invest in robust clinical evidence generation to navigate Europe's MDR framework and reinforce market access. Control distribution channels within ambulatory surgery centers through volume-based pricing agreements.
For New Entrants and Emerging Players: Expedited FDA 510(k) pathways for novel materials or minor device modifications offer a certification fast-track for new entrants. Target underpenetrated emerging markets like Brazil and India with established spinal device technologies. Focus on non-fusion devices for younger patients, leveraging the demand for motion preservation. A go-to-market strategy emphasizing cost-effective, minimally invasive solutions for ambulatory surgery centers provides an entry point.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among companies providing integrated surgical platforms with consumable components and service contracts. The long-term viability of this market hinges on sustained demand from aging populations and continuous technological innovation. Identify acquisition targets specializing in robotic assistance, regenerative medicine, or advanced biomaterials. A signal to watch for future growth is increased reimbursement for advanced non-fusion technologies, indicating broader payer acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Biologics | Enhances fusion rates and stimulates disc regeneration, addressing unmet clinical needs. |
| Robotic Platform Integration | Improves surgical precision and procedural workflows, standardizing complex spine surgery outcomes. |
| ASC Partnership Model | Secures high-volume purchasing agreements and streamlines logistics for outpatient procedures. |
| CE Marking Pathway Investment | Ensures market access across European Union countries under stringent MDR requirements. |
| Patient-Specific Implant Development | Catters to unique patient anatomy, optimizing outcomes for complex deformity cases. |
Research Approach
Desk research of regulatory filings, medical journals, and industry association reports preceded structured interviews with orthopedic surgeons, hospital procurement managers, and medical device engineers. This primary data collection, combined with secondary validation, ensures comprehensive market insights. Bottom-up and top-down triangulation methods verified market size and growth projections.
Variance decomposition across product types, end-users, and technologies informed the analytical framework for this market over the projection horizon. The model also incorporated application-specific demand patterns and regional regulatory environments. Compound annual growth rates were derived from historical data and anticipated future trends. Key industry-specific forecast inputs included aging population demographics and the increasing prevalence of degenerative spinal conditions.
Decision-makers should treat outputs as directional under current raw material stability and reimbursement policy assumptions; material deviation would warrant model refresh. Forecasts reflect a dynamic market influenced by technological advancements and healthcare expenditure. Practitioners should keep alternative scenarios live as regulatory frameworks and healthcare delivery models evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Smart Orthopedic Implants Market
Orthopedic Devices
South Korea Spinal Surgery Devices Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Market
Orthopedic Devices
Global Shockwave Therapy Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
North America Spinal Surgery Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Devices Market
Orthopedic Devices
Veterinary Prosthetics and Orthotics Market
Orthopedic Devices
Patients Repositioning and Offloading Device Market
Orthopedic Devices
Orthopedic Devices Market
Orthopedic Devices
Global Acetabular Cups Market
Orthopedic Devices
Bone Void Fillers Market