
 Smart Orthopedic Implants Market | 2026-2036
Smart Orthopedic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Orthopedic Implants Market Intelligence
Remote patient monitoring subscriptions tied to implantable hardware is recalibrating revenue models across the orthopedic supply chain. Stryker leverages its digital surgery platform to anchor recurring service revenue alongside device sales. Zimmer Biomet sustains competitive positioning through biomechanical sensor R&D concentrated in Warsaw, Indiana. Medtronic controls distribution breadth across hospital networks with integrated data analytics infrastructure.
Smart orthopedic implants comprise sensor-integrated prostheses and fixation devices that transmit biomechanical load, temperature, and positional data to external receivers for clinical decision support. These devices typically incorporate titanium alloy substrates with embedded wireless transponders operating in the 402-405 MHz medical implant communications service band, manufactured through additive processes that embed circuitry without compromising fatigue resistance. Sensor-enhanced implants and connected prosthetics command premium positioning due to real-time monitoring capabilities that reduce revision surgery incidence. Wireless monitoring and biomechanical sensors represent the fastest-expanding technology layers as surgeons demand objective recovery metrics. Orthopedic clinics and specialty care facilities constitute the highest-margin end-user channel where procedure volume and device sophistication converge.
The FDA governs premarket submission pathways for smart implants under combined device-software regulations, while the EU Medical Device Regulation imposes clinical evidence requirements on sensor-enabled Class III devices. Japan's PMDA maintains distinct standards for radio-equipped implantables that delay market entry without local testing partnerships. Stakeholders must monitor evolving cybersecurity mandates for connected medical devices as regulators in multiple jurisdictions impose post-market surveillance obligations on data-transmitting hardware.
Market Dynamics
Reimbursement pathway fragmentation is forcing orthopedic manufacturers to architect dual-track regulatory submissions simultaneously for device hardware and software components, compressing development timelines while expanding compliance overhead.
Growth Catalysts
- Japan's PMDA radio-equipment testing mandates:Local partnership requirements with Osaka-based testing laboratories are accelerating indigenous manufacturing capabilities and reducing import dependency for sensor-integrated hip replacements.
- Additive manufacturing with embedded circuitry:Direct metal laser sintering processes now embed 402-405 MHz transponders within titanium alloy substrates without fatigue resistance degradation, enabling single-procedure implantation of monitoring-capable devices.
- Germany's DiGA fast-track pathway:Digital health application approval streams for connected implant data platforms are shortening time-to-reimbursement for sensor-enabled knee arthroplasty systems in Bavarian hospital networks.
Market Restraints
- Titanium powder supply concentration:Spherical Ti-6Al-4V feedstock for additive manufacturing concentrates among three specialized European metallurgical suppliers, creating input cost volatility for sensor-embedded implant producers.
- FDA combined device-software submission complexity:Premarket notification requirements spanning 510(k) hardware clearance and Software as Medical Device classification impose structural timeline extensions averaging fourteen additional months.
- Biomechanical sensor calibration limitations:Temperature drift in load-sensing piezoelectric elements above body temperature thresholds constrains measurement fidelity in high-activity patient cohorts.
Strategic Opportunities
- India's orthopedic corridor expansion:Tamil Nadu and Gujarat medical device manufacturing zones offer cost-advantaged production capacity for wireless transponder assembly with emerging CDSCO streamlined registration for Class III implantables.
- EU MDR Post-Market Clinical Follow-up mandates:Regulatory requirements for long-term sensor data collection create recurring revenue infrastructure opportunities for implant manufacturers pivoting to monitoring-as-a-service models.
- Machine learning convergence with biomechanical telemetry:Predictive revision surgery algorithms trained on implant load-pattern data streams enable outcome-based contracting with United States integrated delivery networks.
Industry Challenges
- Cross-functional talent scarcity:Orthopedic device engineering teams require simultaneous expertise in RF communications protocol design and ISO 14155 clinical investigation standards, creating recruitment bottlenecks in Warsaw and Warsaw-adjacent talent markets.
- Legacy hospital IT integration friction:Electronic health record systems at mid-tier United States community hospitals lack API architectures compatible with real-time implant data ingestion, forcing costly middleware development.
- Biocompatibility certification timeline compression:ISO 10993 cytotoxicity and sensitization testing for novel polymer sensor encapsulants extends preclinical phases without parallel pathway options.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Orthopedic Implants Market |
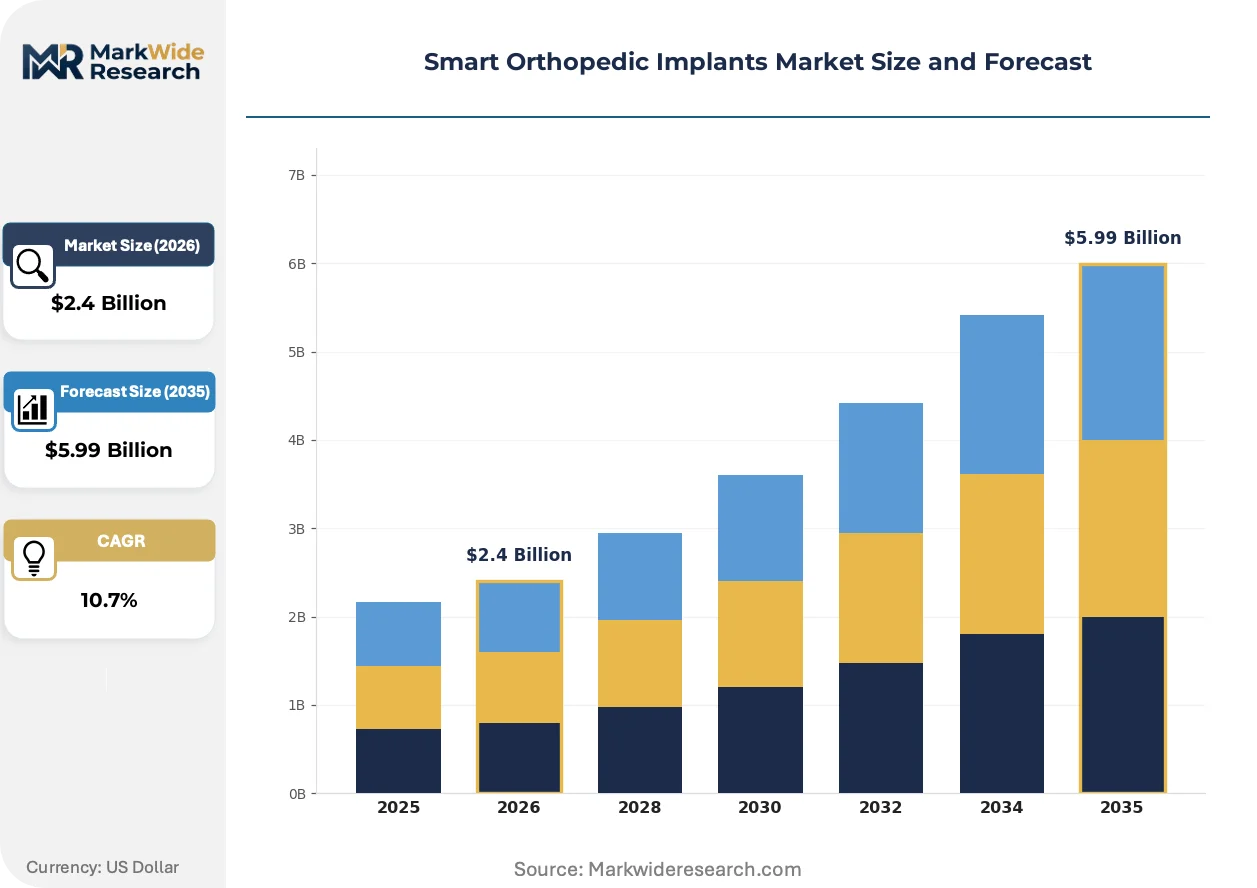
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Bone Plates, Smart Screws, Sensor-Enhanced Implants, Connected Prosthetics End User: Orthopedic Clinics, Hospitals, Rehabilitation Centers, Specialty Care Facilities Technology: Wireless Monitoring, Biomechanical Sensors, 3D Printing, Data Analytics Application: Fracture Treatment, Joint Replacement, Sports Injuries, Postoperative Monitoring |
| Companies Covered | Stryker, Zimmer Biomet, Johnson & Johnson, Medtronic, Smith+Nephew, Globus Medical, Exactech Inc., Corin Group, Orthofix Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Orthopedic Implants Market Strategic Shifts & Innovations
Orthopedic implant architecture is bifurcating between passive mechanical devices and active monitoring platforms, with sensor integration becoming the primary axis of product differentiation rather than biomaterial composition alone.
Additive manufacturing with embedded antenna structures is overtaking conventional subtractive machining for complex orthopedic geometries. Titanium alloy substrates now incorporate helical RF coils during powder-bed fusion, eliminating secondary assembly steps. Major academic medical centers in Germany and Japan are specifying additively manufactured femoral stems with integrated telemetry for revision-risk patient cohorts. This manufacturing shift is overtaking traditional supply chain configurations centered on Swiss and German precision machining subcontractors.
The EU Medical Device Regulation's clinical evidence requirements for Class III sensor-enabled devices are reshaping premarket strategy. Manufacturers must now submit prospective clinical data rather than predicate device equivalency for wireless implantables. German notified bodies are enforcing stricter biocompatibility documentation for polymer-encapsulated sensors. Small and mid-cap orthopedic specialists without established clinical affairs infrastructure face exclusion from premium product categories.
Surgeon preference is gravitating toward objective recovery metrics over subjective patient-reported outcome measures. Hospital purchasing committees now mandate real-time load monitoring capabilities for high-volume joint replacement contracts. Specialty orthopedic clinics in the United States are unbundling device procurement from postoperative monitoring subscriptions. This behavioral shift concentrates demand among integrated platform providers with data analytics infrastructure.
Smart Orthopedic Implants Market Segmentation
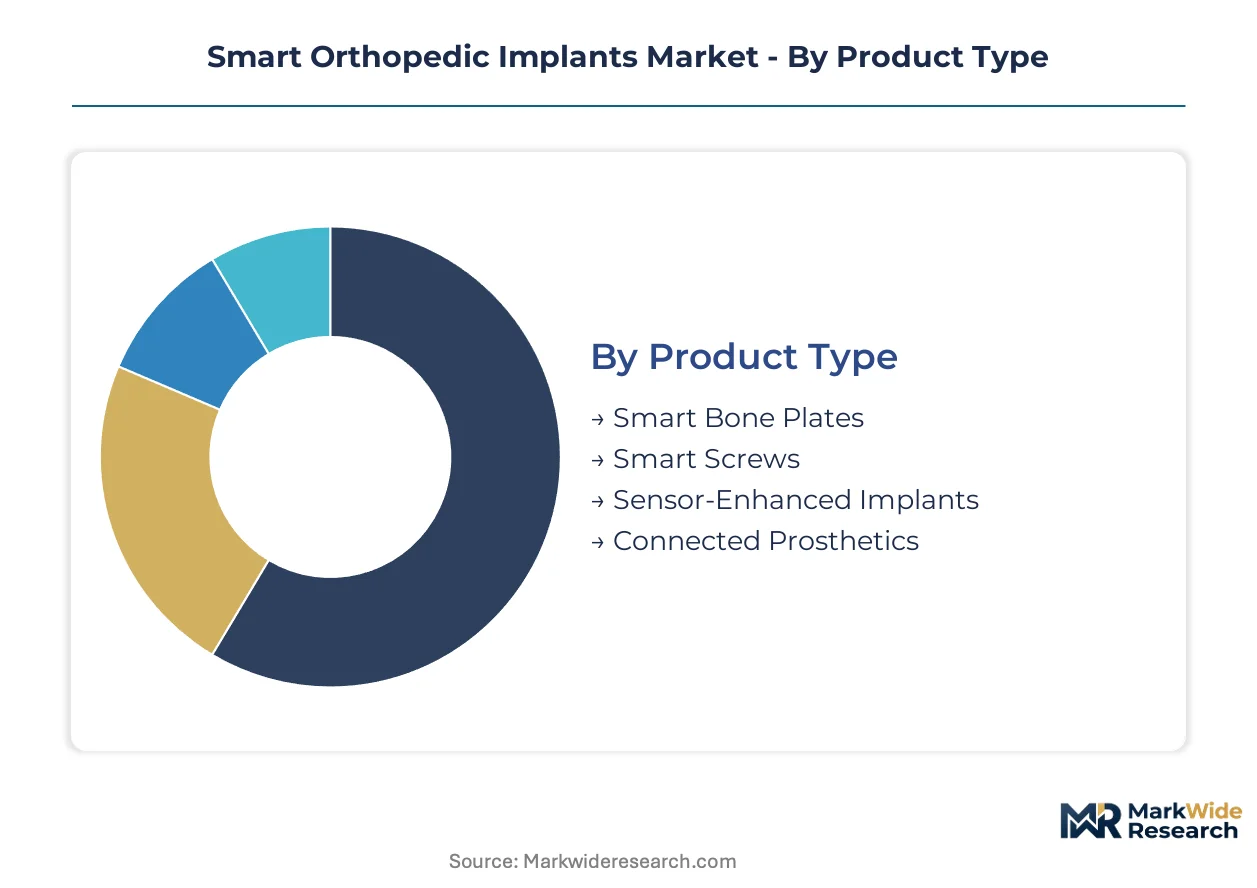
Smart orthopedic implants fragment across hardware sophistication, clinical setting, sensing modality, and surgical indication. Each dimension carries distinct reimbursement pathways, regulatory burdens, and margin structures that shape manufacturer portfolio strategy.
Product Type:
Standardization dominates load-bearing hardware while sensor integration introduces customization tiers based on monitoring intensity and telemetry range.
- Sensor-Enhanced Implants:Titanium alloy substrates embed 402-405 MHz wireless transponders for real-time biomechanical load transmission. Demand concentrates in German Bavarian hospital networks where DiGA fast-track reimbursement rewards postoperative monitoring data.
- Connected Prosthetics:Microprocessor-controlled knee and ankle systems adjust damping algorithms through embedded gyroscopes and accelerometers. United States integrated delivery networks prioritize these devices for revision-risk patient cohorts demanding objective functional metrics.
- Smart Bone Plates:Additive-manufactured fixation hardware with strain-gauge arrays.
- Smart Screws:Miniaturized sensor packages for compression monitoring in spinal fusion.
Most installed capacity flows through Sensor-Enhanced Implants. Expansion is steepest in Connected Prosthetics.
End User:
Channel economics diverge sharply between high-volume hospital purchasing committees and specialty clinics with subscription-based service models.
- Specialty Care Facilities:Orthopedic-focused ambulatory surgery centers command premium pricing through bundled device-plus-monitoring contracts. Japan's PMDA radio-equipment testing partnerships with Osaka laboratories accelerate procurement of telemetry-enabled systems for these settings.
- Orthopedic Clinics:Surgeon-owned practices drive adoption of biomechanical sensor platforms that differentiate patient outcomes. United States specialty clinics unbundle hardware procurement from remote monitoring subscriptions, creating recurring revenue streams.
- Hospitals:Centralized procurement favors integrated platform providers with data analytics infrastructure.
- Rehabilitation Centers:Post-acute facilities leverage implant telemetry for gait retraining protocol optimization.
Specialty Care Facilities capture the highest margin per procedure. Orthopedic Clinics are climbing the fastest as surgeon preference shifts toward objective recovery metrics.
Technology:
Manufacturing process maturity separates deployable platforms from developmental sensing architectures still resolving biocompatibility and power constraints.
- Biomechanical Sensors:Piezoelectric load cells and MEMS accelerometers measure strain, temperature, and positional data with sub-millimeter precision. Additive manufacturing with embedded antenna structures now integrates these elements during titanium powder-bed fusion without secondary assembly.
- Wireless Monitoring:Medical Implant Communications Service band transceivers transmit encrypted telemetry to external receivers. FDA combined device-software submission complexity extends development timelines for manufacturers architecting dual-track regulatory pathways.
- 3D Printing:Direct metal laser sintering enables patient-specific geometries with embedded circuitry.
- Data Analytics:Machine learning algorithms trained on implant telemetry enable predictive revision surgery scheduling.
Wireless Monitoring infrastructure supports the broadest installed base. Biomechanical Sensors are gaining share fastest as measurement fidelity improves in high-activity patient cohorts.
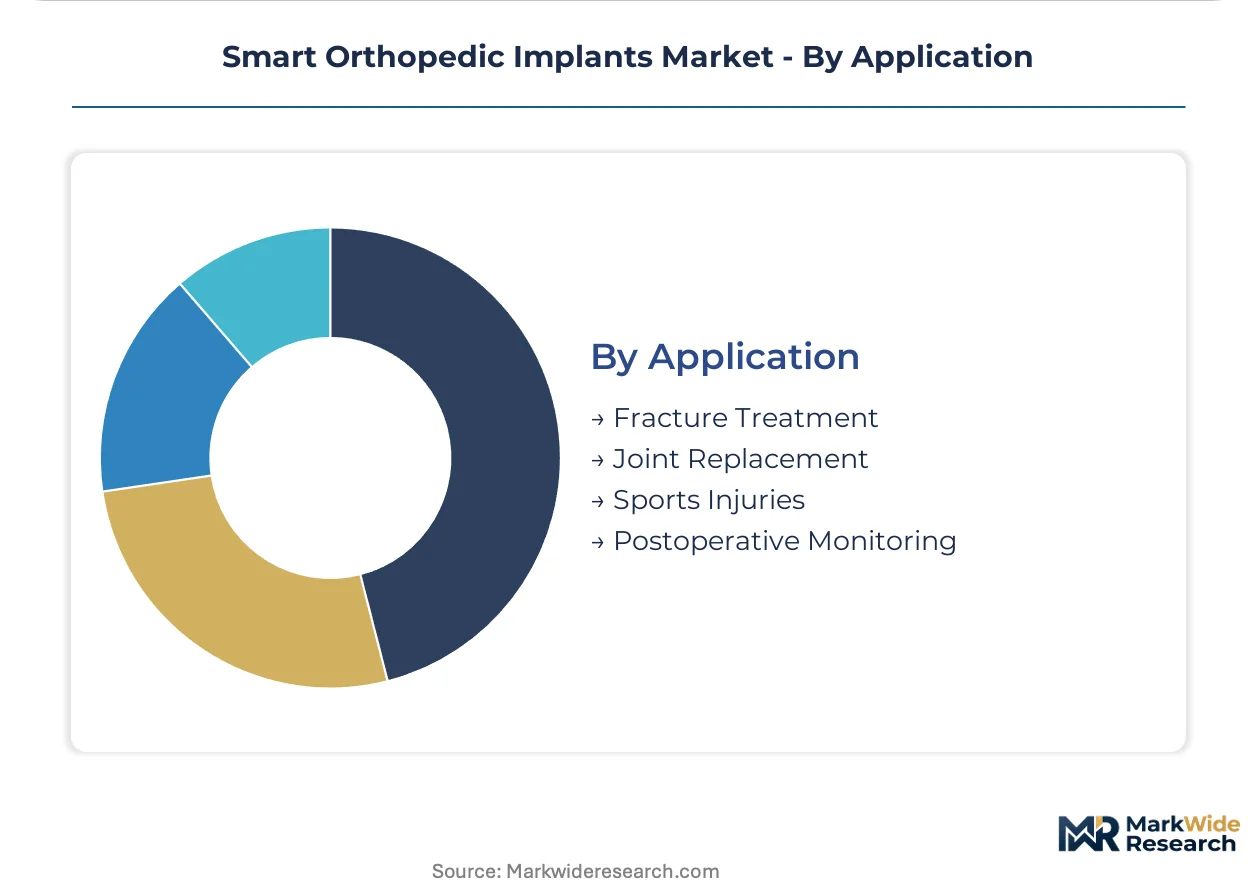
Application:
Procedure reimbursement rates and revision surgery risk profiles determine sensor investment justification across surgical indications.
- Joint Replacement:Total knee and hip arthroplasty systems incorporate the most sophisticated telemetry packages due to high procedure volumes and revision cost exposure. Germany's DiGA pathway specifically targets connected implant data platforms for this indication.
- Postoperative Monitoring:Continuous telemetry subscription services generate recurring revenue independent of initial device sale. United States hospitals expanding procurement of sensor-enabled devices concentrate demand in this application layer.
- Fracture Treatment:Load-sharing fixation devices with strain monitoring reduce non-union complications.
- Sports Injuries:Athlete-specific implants prioritize rapid return-to-play metrics over long-term durability monitoring.
Joint Replacement absorbs the majority of sensor-integrated hardware production. Postoperative Monitoring shows the steepest expansion trajectory as revenue models pivot toward subscription infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's DiGA fast-track pathway accelerates sensor-enabled knee system reimbursement faster than the FDA's combined device-software submission process in the United States. Japan's PMDA radio-equipment mandates create localized manufacturing partnerships unavailable in Western markets.
United States
Integrated delivery networks in the Midwest and Southeast prioritize objective recovery metrics for revision-risk patient cohorts. FDA combined device-software submission requirements under 510(k) and SaMD classifications extend development timelines for wireless implantables. Warsaw, Indiana anchors biomechanical sensor R&D concentration with established orthopedic engineering talent pools.
Germany
Bavarian hospital networks drive procurement of telemetry-enabled joint replacement systems through DiGA reimbursement pathways. EU MDR clinical evidence requirements for Class III sensor-enabled devices mandate prospective data submission rather than predicate equivalency. Berlin-Brandenburg medical technology clusters specialize in additive manufacturing with embedded antenna structures for femoral stems.
Japan
Aging demographics in Kanto and Kansai regions concentrate demand for postoperative monitoring subscriptions tied to implantable hardware. PMDA radio-equipment testing mandates require Osaka-based laboratory partnerships for 402-405 MHz transponder certification. Nagoya manufacturing zones develop indigenous production capacity for sensor-integrated hip replacements.
India
Tamil Nadu and Gujarat medical device manufacturing zones attract wireless transponder assembly operations seeking cost-advantaged production capacity. CDSCO streamlined registration pathways for Class III implantables reduce market entry friction compared to legacy pharmaceutical approval timelines. Chennai-based orthopedic corridors expand cleanroom capacity for sensor package encapsulation.
United Kingdom
London and Southeast England specialist orthopedic clinics unbundle hardware procurement from remote monitoring subscriptions. MHRA alignment with EU MDR post-market surveillance obligations imposes long-term sensor data collection requirements on manufacturers. Midlands manufacturing bases transition from precision machining to direct metal laser sintering for complex implant geometries.
Smart Orthopedic Implants Market Key Industry Players
Top-tier vendors anchor integrated platform provision with data analytics infrastructure, while mid-cap specialists concentrate on additive manufacturing process differentiation. The vendor base stratifies across three tiers: multinational conglomerates with hospital network distribution breadth, regional technology licensors with embedded circuitry expertise, and niche sensor calibration houses. Two strategic archetypes dominate: monitoring-as-a-service platform operators and biomechanical telemetry hardware specialists. Competitive moves center on M&A for clinical affairs infrastructure and capacity expansion in India-based manufacturing zones.
Within the integrated platform tier, Stryker and Medtronic exemplify archetypes combining device sales with recurring service revenue streams. Zimmer Biomet occupies a position representing biomechanical sensor R&D concentration in established orthopedic manufacturing geographies. These three entities anchor competitive positioning through differentiated approaches to regulatory pathway navigation and hospital procurement channel access.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Johnson & Johnson |
| Medtronic |
| Smith+Nephew |
| Globus Medical |
| Exactech Inc. |
| Corin Group |
| Orthofix Medical Inc. |
| Others |
Cost & Logistics Intelligence
Spherical Ti-6Al-4V titanium powder feedstock flows from three specialized European metallurgical suppliers through additive manufacturing facilities in Germany and Indiana, stratifying sensor-embedded implant pricing across premium telemetry-enabled tiers and standard passive hardware. Cost compression in the standard tier intensifies because hospital purchasing committees consolidate volume around integrated platform providers, while premium sensor-integrated devices command pricing power through bundled monitoring subscriptions.
Pricing Analysis
Capacity additions in India's Tamil Nadu and Gujarat medical device manufacturing zones are reshaping price floors for wireless transponder assembly operations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared sensor platforms with real-time telemetry from CE-marked monitoring-capable devices and basic passive implants. Price differentiation rests on ISO 14155 clinical investigation certification status and after-sales data analytics bundling. Mid-tier United States community hospitals exhibit highest price sensitivity due to constrained capital equipment budgets, while German Bavarian hospital networks show lowest sensitivity under DiGA fast-track reimbursement pathways.
Supply Chain Analysis
Japan's PMDA radio-equipment testing mandates and local-content requirements with Osaka-based laboratories are reshaping sourcing patterns for 402-405 MHz transponder certification. Geographic supply concentrates in Germany for precision additive manufacturing equipment, India for cost-advantaged wireless transponder assembly, and the United States for biomechanical sensor R&D talent pools. Raw material dependencies center on spherical titanium alloy feedstock, piezoelectric load-sensing elements, and medical-grade polymer sensor encapsulants. Single-source vulnerability runs through the concentrated European metallurgical supplier base for Ti-6Al-4V powder. Distribution runs through integrated platform providers with hospital network contracts and specialty orthopedic clinics with direct procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between India's CDSCO streamlined registration pathways for Class III implantables and the FDA's fourteen-month combined device-software submission timeline extensions, compressing development costs for manufacturers willing to anchor initial certification in South Asian regulatory corridors.
For Market Incumbents: Extend clinical affairs infrastructure through targeted capacity addition in Berlin-Brandenburg medical technology clusters specializing in additive manufacturing with embedded antenna structures. Defend against emerging entrant displacement by deepening backward integration into spherical titanium powder supply through captive offtake agreements with European metallurgical suppliers. Certification investment in EU MDR Post-Market Clinical Follow-up data collection infrastructure anchors recurring revenue streams.
For New Entrants and Emerging Players: Additive manufacturing process differentiation for patient-specific femoral stem geometries offers entry leverage into revision-risk patient cohorts underserved by standardized implant portfolios. The most penetrable segment sits in United States specialty orthopedic clinics unbundling hardware procurement from remote monitoring subscriptions. A software-first go-to-market angle through machine learning predictive revision surgery algorithms enables outcome-based contracting with integrated delivery networks without immediate device manufacturing scale requirements.
For Investors and Strategic Acquirers: Consolidation pressure builds where clinical evidence generation capabilities and regulatory pathway expertise concentrate among a narrowing tier of multinational conglomerates. Long-term viability across the next decade hinges on pivoting from transactional device sales toward monitoring-as-a-service subscription infrastructure. Target acquisition archetypes include niche sensor calibration houses with ISO 10993 biocompatibility certification expertise and established Osaka-based PMDA testing partnerships. The signal to watch is CDSCO registration timeline compression for Class III implantables accelerating indigenous Indian manufacturing capacity buildout.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Stryker leverages digital surgery platform relationships to anchor recurring monitoring subscription revenue alongside device sales. |
| Software Companion Development | Zimmer Biomet concentrates biomechanical sensor R&D in Warsaw, Indiana to differentiate through real-time telemetry integration. |
| FDA Submission | Medtronic navigates combined 510(k) hardware clearance and Software as Medical Device classification for wireless implantables. |
| CE Marking Pathway | German notified bodies enforce stricter biocompatibility documentation for polymer-encapsulated sensors under EU MDR. |
| Reimbursement Strategy | DiGA fast-track pathway in Bavarian hospital networks shortens time-to-reimbursement for sensor-enabled knee arthroplasty systems. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with orthopedic device engineering executives, hospital purchasing committee members, biomedical engineers specializing in RF communications protocol design, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, PMDA radio-equipment testing records, and CMS Medicare reimbursement databases. Bottom-up demand modeling across procedure volumes and implant unit economics triangulated against top-down market sizing through manufacturer revenue disclosures.
Comparable-period anchoring tied projection assumptions to historical reference windows spanning pre-pandemic baseline, disruption period, and recovery trajectory phases across the analysis window. Segmentation dimensions modeled include product type sophistication tiers, end-user channel economics, sensing modality technology maturity, and surgical indication reimbursement profiles. CAGRs derived from fitted growth curves applied to sensor-integrated hardware production volumes and postoperative monitoring subscription revenue streams, with specific inputs for titanium powder feedstock cost volatility and regulatory pathway timeline variability.
The model holds under stable FDA digital health guidance evolution and sustained DiGA reimbursement pathway expansion; deviation in PMDA radio-equipment testing mandate stringency or EU MDR clinical evidence requirement enforcement would shift market entry friction assumptions. Forecasts reflect documented assumptions regarding additive manufacturing yield improvement trajectories and wireless telemetry protocol standardization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Hip Resurfacing Implants Market
Orthopedic Devices
Japan Spinal Surgery Devices Market
Orthopedic Devices
India Orthopedic Braces and Supports Market
Orthopedic Devices
Bone Graft Fixation System Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
Global Acetabular Cups Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
US Orthopedic Devices Market
Orthopedic Devices
3D Orthopedic Scanning System Market
Orthopedic Devices
Global Artificial Joints Market
Orthopedic Devices
Global Orthopedic Implant Market
Orthopedic Devices
Orthopedic Fracture Repairing Implants for Osteoporosis Market