
 Mobile Hospitals Market | 2026-2036
Mobile Hospitals Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Hospitals Market Outlook
A capital-intensity divergence between fully integrated manufacturers and assembly-only contractors is redrawing competitive boundaries in mobile hospital supply. Vanguard Healthcare Solutions leverages in-house fabrication of modular clinical pods to sustain margin control across European defense contracts. Odulair LLC anchors its position through specialized production of self-contained surgical trailers for African and Middle Eastern government buyers.
Mobile hospitals deploy as rapidly relocatable clinical environments, typically comprising standardized shipping containers or expandable trailer systems equipped with HVAC filtration achieving ISO 8 cleanroom equivalence, redundant power generation, and sterilizable surgical surfaces. Their primary purpose is to restore trauma and acute care capacity within hours of natural disasters, armed conflict, or pandemic surge events. Container hospitals dominate current procurement volumes due to intermodal compatibility with military logistics networks, while telemedicine integration represents the fastest-expanding technology segment as remote specialist consultation reduces on-site staffing requirements. Emergency response applications command the largest existing revenue pool, though military operations segments are deepening as armed forces modernize forward surgical capabilities.
The US FDA regulates mobile medical devices under 21 CFR 820 quality system requirements, while EU CE marking under the Medical Device Regulation mandates clinical evidence for deployable diagnostic equipment. Germany's KBA enforces roadworthiness standards for trailer-based units that constrain chassis design choices and add compliance cost layers. Buyers must weigh modular upgrade paths against total lifecycle portability when specifying platforms for multi-mission deployment.
Market Dynamics
Defense procurement programs across NATO member states are compressing deployment timelines for container-based surgical platforms, while FDA emergency use authorization pathways accelerate civilian field hospital activation. This dual-track demand structure is reshaping supplier capability requirements and certification investments.
Growth Catalysts
- Emergency Use Authorization Pathways:The US FDA's streamlined 21 CFR 820 compliance routes for deployable medical devices reduce field activation delays from months to weeks.
- German Federal Civil Defense Expansion:Bundeswehr and civilian disaster response agencies are expanding mobile healthcare reserves through multi-year framework agreements.
- Telemedicine Integration:Remote specialist consultation capabilities reduce on-site staffing requirements by enabling real-time surgical guidance across distributed clinical networks.
Market Restraints
- Specialized Chassis Supply Concentration:Germany's KBA roadworthiness standards constrain trailer design options to a limited pool of certified European chassis manufacturers.
- HVAC Filtration Input Costs:ISO 8 cleanroom-equivalent filtration systems rely on specialized HEPA media subject to semiconductor industry demand competition.
- Container Hospital Substitution Pressure:Fixed modular clinics in semi-permanent disaster zones compete for the same civil defense budgets with lower relocation flexibility.
Strategic Opportunities
- Middle East Government Procurement:Saudi Arabia's SFDA and UAE's MOHAP are establishing national mobile hospital reserves for Hajj surge capacity and desert emergency response.
- EU Medical Device Regulation Tailwind:MDR Article 120 transition provisions create compliance windows for manufacturers to capture defense contract renewals with updated technical documentation.
- AI-Assisted Triage Convergence:Machine learning diagnostic tools paired with portable imaging equipment enable point-of-care decision support without specialist deployment.
Industry Challenges
- Multi-Jurisdiction Certification Complexity:Simultaneous FDA 510(k), EU MDR, and national defense qualification timelines create resource bottlenecks for mid-scale manufacturers.
- Interoperable Power System Integration:NATO STANAG electrical standards, national grid specifications, and renewable microgrid architectures demand redundant engineering across single platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Hospitals Market |
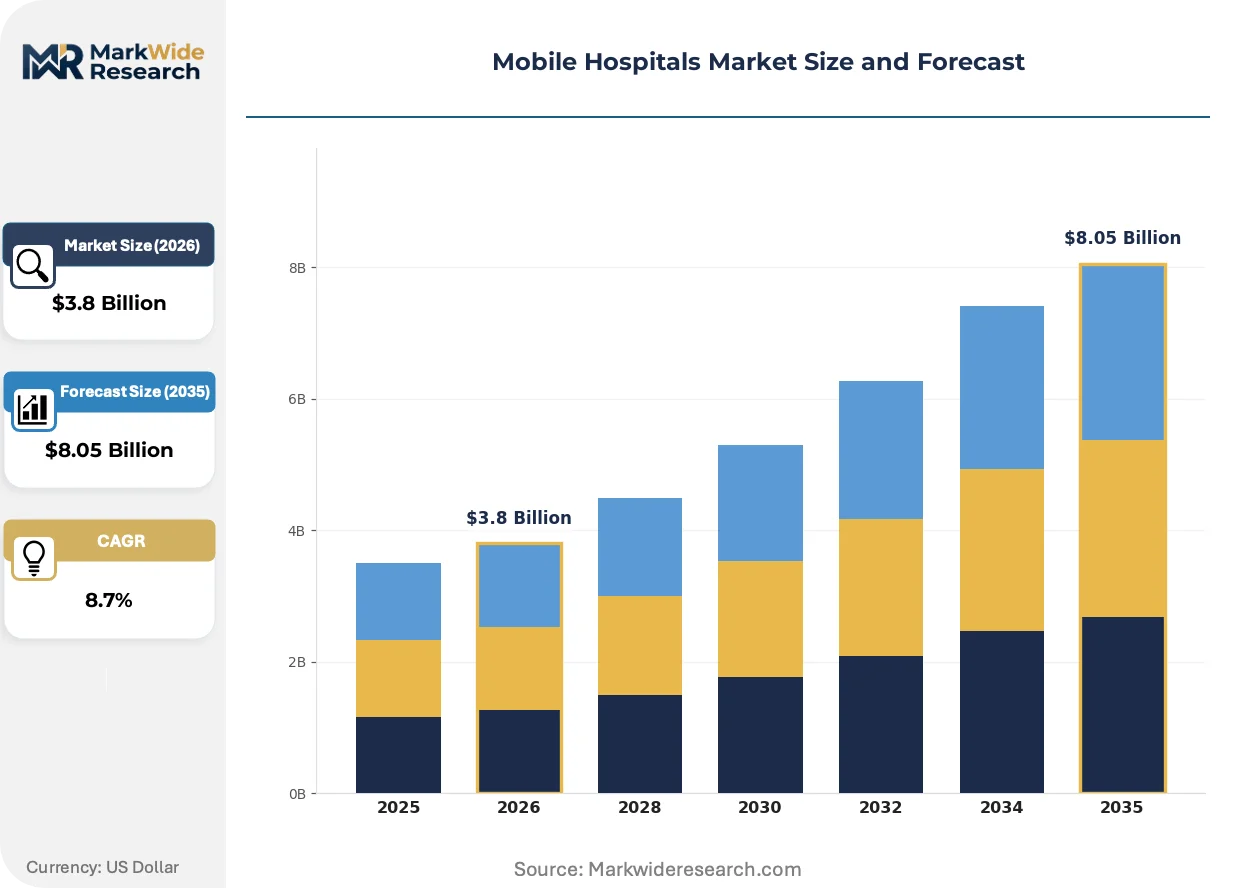
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Field Hospitals, Portable Units, Container Hospitals, Modular Structure Technology: Telemedicine, IoT Integration, Mobile Imaging, Remote Monitoring Application: Emergency Response, Disaster Relief, Military Operations, Public Health Initiatives End User: Government Agencies, NGOs, Private Organizations, Military |
| Companies Covered | Alvo Medical Aspen Medical, CGS Premier, Saba Palaye, Lamboo Medical, Vanguard Healthcare Solutions, Vetter GmbH, U-PROJECT, EMS Healthcare Ltd., Odulair LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Hospitals Market Strategic Shifts
Telemedicine infrastructure is embedding into mobile surgical platforms as a core architectural layer rather than aftermarket accessory. This shift compresses specialist deployment requirements while expanding treatable case complexity in remote settings.
Container-based hospital architecture is bifurcating between intermodal military platforms and civilian rapid-deployment variants. NATO logistics networks drive standardized 20-foot and 40-foot surgical modules with STANAG compatibility. Civilian operators prioritize expandable trailer systems with faster site preparation. The technology is bifurcating supply chains into defense-certified and commercial-grade fabrication tracks with diverging margin profiles.
The EU Medical Device Regulation's clinical evidence requirements for deployable diagnostic equipment are extending certification timelines for manufacturers without predicate device portfolios. German notified bodies are prioritizing mobile imaging and anesthesia systems for MDR conformity assessment. Smaller assembly-only contractors face capital barriers to updated technical documentation and post-market surveillance systems.
Buyers are unbundling after-sales service contracts from equipment procurement, selecting specialized regional maintenance providers over manufacturer captive service networks. African government purchasers lead this pattern, leveraging local biomedical engineering capacity for preventive maintenance. Middle Eastern defense customers retain integrated service agreements due to security-cleared technician requirements.
Mobile Hospitals Market Segmentation
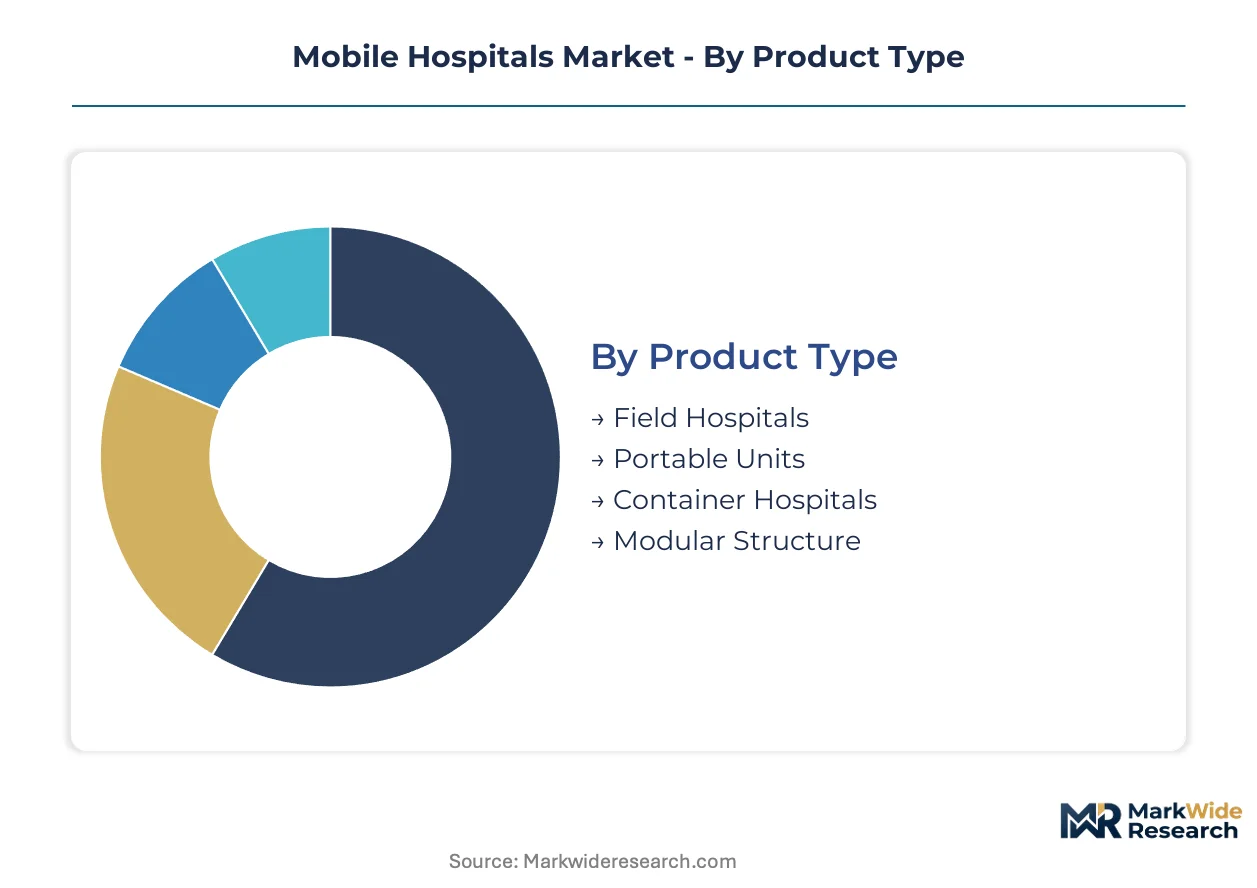
Segmentation in mobile hospitals determines procurement pathways, certification requirements, and deployment velocity. Product architecture dictates logistics compatibility while end-user identity shapes financing mechanisms and operational protocols.
Product Type:
Defense procurement channels favor container-based platforms with intermodal transportability, while civilian emergency response contracts flow through expandable trailer systems with rapid site activation.
- Container Hospitals:Standardized ISO shipping containers modified with surgical suites, HVAC filtration, and redundant power systems. NATO logistics networks and German Bundeswehr procurement programs drive concentrated demand for 20-foot and 40-foot modules with STANAG compatibility.
- Modular Structure:Expandable clinical pods fabricated from composite panels with rapid-assembly framing. Saudi Arabia's SFDA and UAE's MOHAP are establishing national reserves for Hajj surge capacity and desert emergency response.
- Field Hospitals:Tent-based deployable systems with inflatable or frame-supported enclosures.
- Portable Units:Compact single-patient or limited-capability platforms for point-of-care stabilization.
Container hospitals dominate installed base. Modular structures are where expansion concentrates.
Technology:
Cost tiers separate defense-grade hardened systems from commercial rapid-deployment variants, with telemedicine infrastructure commanding premium positioning across both categories.
- Telemedicine:Real-time specialist consultation infrastructure embedded as core architectural layer rather than aftermarket accessory. Remote surgical guidance capabilities reduce on-site staffing requirements across distributed clinical networks in Middle Eastern government deployments.
- Mobile Imaging:Portable CT, X-ray, and ultrasound systems with deployable shielding. German notified bodies are prioritizing these systems for EU MDR conformity assessment, extending certification timelines for manufacturers without predicate device portfolios.
- IoT Integration:Connected device ecosystems for asset tracking and environmental monitoring.
- Remote Monitoring:Patient telemetry systems enabling centralized oversight of distributed field units.
Telemedicine claims the steepest expansion trajectory. Mobile imaging carries the heaviest regulatory compliance burden.
Application:
Volume concentration follows emergency response funding cycles, with military operations deepening as armed forces modernize forward surgical capabilities.
- Military Operations:Forward surgical platforms for combat casualty care and battlefield stabilization. NATO member states are accelerating adoption through multi-year framework agreements with compressed deployment timelines.
- Emergency Response:Rapid activation for natural disasters, mass casualty events, and pandemic surge. US FDA emergency use authorization pathways reduce field activation delays from months to weeks for civilian operators.
- Disaster Relief:Sustained deployment in semi-permanent disaster zones with humanitarian funding mechanisms.
- Public Health Initiatives:Screening, vaccination, and preventive care outreach programs.
Emergency response commands the largest revenue pool. Military operations are climbing the fastest.
End User:
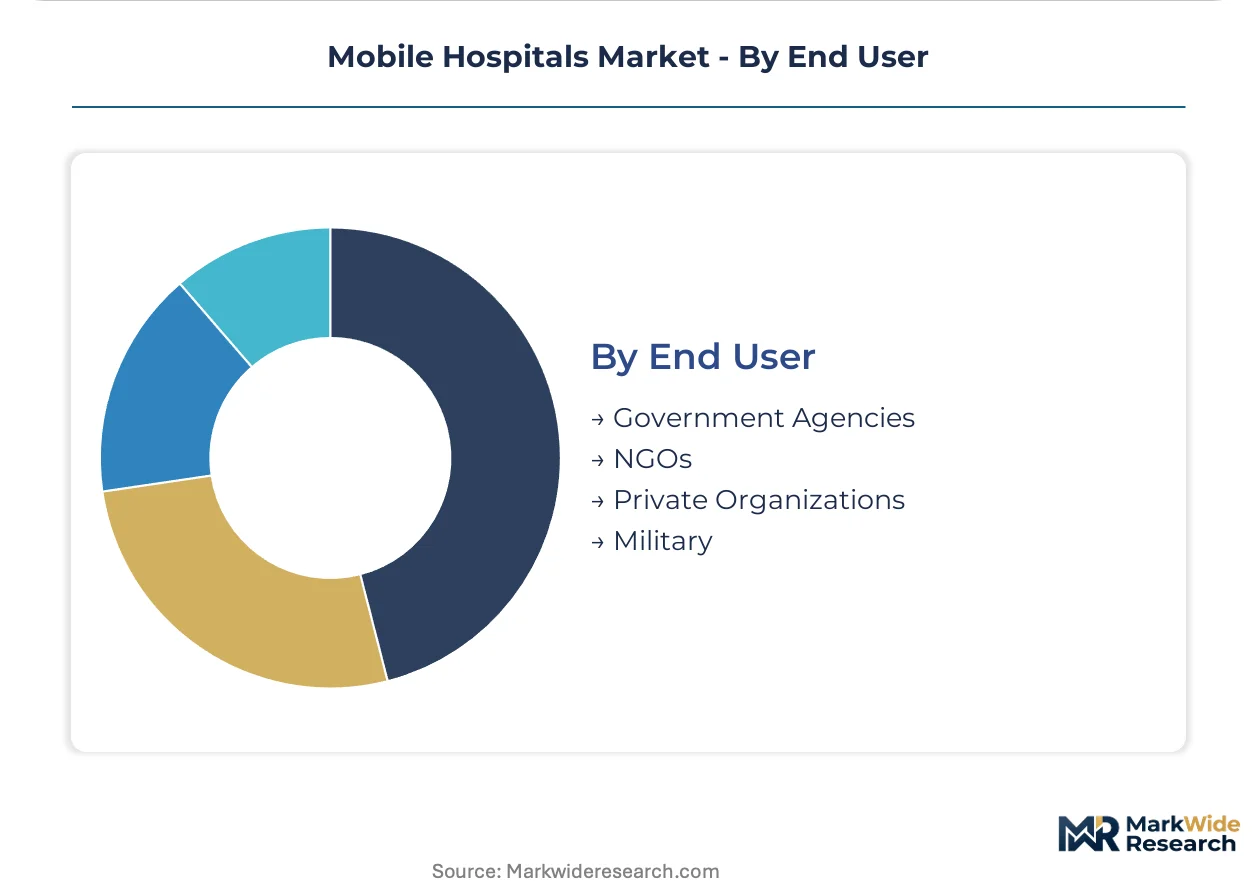
Customer type determines service contract structures, with government agencies unbundling maintenance from procurement while military customers retain integrated agreements due to security-cleared technician requirements.
- Government Agencies:Federal civil defense and health ministries with framework contracting mechanisms. German federal budgets are expanding mobile healthcare reserves through civilian disaster response agencies alongside Bundeswehr programs.
- Military:Armed forces with STANAG interoperability requirements and classified operational protocols. Security-cleared service networks and defense qualification timelines create vendor lock-in effects.
- NGOs:Humanitarian organizations with grant-dependent procurement and local maintenance capacity.
- Private Organizations:Corporate and insurance-funded emergency preparedness programs.
Government agencies anchor procurement volume. Military end users concentrate margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German defense procurement channels while cost-sensitive African government tenders compress margins for assembly-only contractors. Container-based platforms command premiums in NATO-aligned markets. Expandable trailer systems face substitution pressure in humanitarian funding environments.
United States
FDA emergency use authorization pathways accelerate civilian field hospital activation timelines. Military procurement through Defense Health Agency contracts prioritizes STANAG-compatible surgical modules. Manufacturing clusters in Texas and Virginia support rapid fabrication of container-based platforms for domestic emergency response reserves.
Germany
Bundeswehr framework agreements and federal civil defense budget expansion drive concentrated demand for mobile healthcare reserves. KBA roadworthiness standards constrain trailer chassis design to certified European manufacturers. Industrial fabricators in North Rhine-Westphalia specialize in ISO 8 cleanroom-equivalent HVAC systems for surgical containers.
Saudi Arabia
SFDA regulatory frameworks establish national mobile hospital reserves for Hajj surge capacity and desert emergency response. Government procurement favors expandable modular structures over container platforms for rapid site activation. Riyadh-based healthcare infrastructure planners coordinate multi-year framework agreements with European and regional suppliers.
United Arab Emirates
MOHAP national reserve programs target mobile diagnostic and surgical capacity for remote area coverage. Federal procurement prioritizes telemedicine-integrated platforms to reduce specialist deployment requirements. Dubai's healthcare free zones host regional distribution and maintenance hubs serving Gulf Cooperation Council markets.
Japan
METI industrial policy supports domestic production of disaster-response medical modules for earthquake and tsunami preparedness. PMDA regulatory alignment with EU MDR streamlines certification of deployable diagnostic equipment. Manufacturing clusters in Chubu region fabricate compact trailer-based units optimized for narrow urban deployment corridors.
Mobile Hospitals Market Competitive Environment
Concentration sits with vertically integrated fabricators controlling in-house production of modular clinical pods and HVAC filtration systems. The vendor base spans three tiers: defense-qualified system integrators with STANAG certification, commercial-grade container modifiers serving civilian emergency response, and regional assembly contractors dependent on outsourced chassis and filtration inputs. Competitive moves center on backward integration into cleanroom-equivalent HVAC production and geographic expansion into Middle Eastern government procurement channels.
Among European defense contractors, Vanguard Healthcare Solutions and Vetter GmbH exemplify the integrated fabrication archetype with captive supply of surgical pod components. Odulair LLC anchors the specialist tier focused on self-contained trailer systems for cost-sensitive government buyers in Africa and the Middle East. EMS Healthcare Ltd. occupies a position bridging commercial emergency response and NHS framework contracting. The competitive dynamic pits certification-heavy NATO suppliers against agile regional assemblers competing on deployment speed and localized service networks.
| Leading Market Players |
|---|
| Alvo Medical Aspen Medical |
| CGS Premier |
| Saba Palaye |
| Lamboo Medical |
| Vanguard Healthcare Solutions |
| Vetter GmbH |
| U-PROJECT |
| EMS Healthcare Ltd. |
| Odulair LLC |
| Others |
Value Chain & Pricing Dynamics
Container fabrication scale economies in Germany and Poland anchor supply-side pricing power, compressing cost floors for ISO-certified surgical modules while pushing customization premiums toward defense-qualified system integrators. High utilization rates at North Rhine-Westphalia HVAC filtration facilities tighten input availability for mid-scale assemblers, forcing price stratification between captive-supply incumbents and chassis-dependent contractors.
Pricing Analysis
The customization-premium spread separates configured-to-order NATO STANAG platforms from standard commercial container hospitals by margins reflecting certification depth and after-sales bundling. Contract-based long-term offtake dominates defense procurement, with price differentiation driven by ISO 8 cleanroom equivalence tier and KBA roadworthiness certification level. Cost compression in expandable trailer systems intensifies as African government tenders prioritize rapid deployment over hardened specifications. NGOs exhibit highest price sensitivity; Middle Eastern defense customers retain integrated service premiums.
Supply Chain Analysis
Germany and Poland anchor container modification and HVAC filtration production for European defense contracts, while Turkey and UAE fabricate expandable modular structures for Middle Eastern government buyers. Raw material dependencies center on specialized HEPA media, certified European chassis, and composite paneling. Single-source vulnerability concentrates in Germany's KBA-certified chassis pool. Distribution runs through defense procurement frameworks, civilian disaster response agencies, and regional healthcare infrastructure planners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile hospital procurement is recovering from pandemic-budget retrenchment, with NATO defense modernization programs and Middle Eastern national reserve buildouts providing cyclical lift through multi-year framework agreements.
For Market Incumbents: Secure backward integration into ISO 8 cleanroom-equivalent HVAC production to defend margin position against chassis-cost inflation and HEPA media supply competition. Deepen STANAG certification portfolios to exploit vendor lock-in effects as NATO qualification timelines extend. For New Entrants and Emerging Players: Differentiate on telemedicine-native architectural design to bypass capital barriers facing legacy assemblers. Target African government tenders for expandable trailer systems, leveraging localized service networks against integrated incumbents. Pursue partnership routes with regional healthcare infrastructure planners rather than direct defense qualification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated fabricators with captive HVAC and modular pod production. Long-term viability centers on defense-civilian dual-use platform flexibility. Monitor German federal civil defense budget allocations as inflection indicator for European demand cyclicality.| Strategic Initiative | Industry Significance |
|---|---|
| STANAG Certification Investment | Unlocks NATO defense procurement channels with multi-year framework visibility. |
| Telemedicine Platform Integration | Reduces specialist deployment requirements for Saudi SFDA and UAE MOHAP contracts. |
| Backward Integration into HVAC Filtration | Insulates margin from semiconductor industry demand competition for HEPA media. |
| Regional Maintenance Hub Establishment | Captures unbundled service contracts from African government purchasers. |
| EU MDR Technical Documentation Update | Secures defense contract renewals under Article 120 transition provisions. |
Study Parameters
The analysis maps container-based platforms, expandable trailer systems, modular structures, and portable units, each validated through procurement officers at defense ministries, biomedical engineers, GPO contracts managers, and healthcare infrastructure planners. Primary interview findings triangulate against secondary sources including FDA 510(k) filings, EU MDR conformity assessment databases, NATO STANAG documentation, and German federal budget appropriations records. Bottom-up unit economics and top-down defense spending trajectories cross-validate market sizing.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture, technology tier, application mission profile, and end-user procurement mechanism. CAGRs derive from deployment velocity assumptions tied to FDA emergency use authorization pathway utilization and Bundeswehr framework agreement execution rates.
The analysis sits within stated boundaries; outcomes outside sustained NATO defense modernization or Middle Eastern national reserve buildouts would require recalibration. Forecasts reflect assumptions regarding KBA chassis certification capacity and HEPA media supply availability. Recalibration cycles align with material shifts in German federal civil defense budgets and EU MDR transition timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
Bedless Hospitals Market
Healthcare Facilities
US Skilled Nursing Facility and Rehabilitation Market
Healthcare Facilities
US Office-Based Labs Market
Healthcare Facilities
Confinement Center Market
Healthcare Facilities
US Skilled Nursing Facility Market
Healthcare Facilities
Global Healthcare Facilities Management Market
Healthcare Facilities
Hospital Lighting Market
Healthcare Facilities
US Assisted Living Facility Market
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
Micro-Hospitals Market
Healthcare Facilities
Sauna and Spa Market
Healthcare Facilities
Longevity Clinic Chain Infrastructure Market
Healthcare Facilities
Global Ambulatory Surgery Centers (Ascs) Market
Healthcare Facilities
Assisted Living Facilities Market
Healthcare Facilities
US and Europe Ambulatory Surgery Centers Market
Healthcare Facilities
US Hospital Facilities Market