
 Ambulatory Aids Market | 2026-2036
Ambulatory Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Ambulatory Aids Market Analysis
Germany is reconfiguring European supply dynamics for ambulatory aids through concentrated engineering capacity in Duderstadt and other production hubs. Ottobock leverages its prosthetics heritage to extend capabilities into rollators and walking frames with integrated sensor technology. Sunrise Medical anchors Nordic and Central European distribution through specialized rehabilitation dealer networks. Drive DeVilbiss Healthcare competes on cost-engineered aluminum walker platforms scaled through Asian contract manufacturing partnerships.
Ambulatory aids encompass mechanical and electromechanical devices that support independent locomotion for individuals with impaired gait, balance, or lower-extremity function, typically fabricated from aluminum tubing, carbon-fiber composites, or high-impact polymers with adjustable height mechanisms and load ratings spanning 250 to 400 pounds. Their primary purpose is to reduce fall risk and preserve functional mobility in home, clinical, and long-term care environments. Rollators command premium positioning due to brake-system complexity and accessory integration, while basic canes represent a mature, price-commoditized segment with thin margin pools concentrated in retail pharmacy channels. Home care end users drive the fastest structural expansion as aging-in-place policies shift institutional rehabilitation into domestic settings, creating demand for collapsible, lightweight designs with tool-free assembly.
FDA 510(k) clearance requirements and ISO 11199 durability standards govern product entry and liability exposure in the United States, while the EU Medical Device Regulation (MDR) reclassifies many rollators to higher scrutiny tiers, extending certification timelines for European market access. Medicare Part B durable medical equipment fee schedules directly influence United States pricing floors and manufacturer reimbursement strategy, creating divergence between commercial and government-channel product configurations. Stakeholders must monitor evolving MDR technical documentation requirements and telehealth-integrated mobility assessments that promise to reshape prescribing workflows and channel economics.
Market Dynamics
The structural force reshaping ambulatory aids is the EU Medical Device Regulation's 2021 reclassification of rollators to Class I higher-scrutiny tiers, extending certification timelines and forcing manufacturers to consolidate technical documentation capabilities.
Growth Catalysts
- MDR compliance infrastructure:The EU MDR's expanded clinical evidence requirements for walking aids creates competitive moats for firms with captive notified-body relationships, compressing vendor pools and concentrating margin capture among prepared manufacturers.
- Home care provider procurement:Medicare Part B durable medical equipment fee schedules in the United States incentivize lightweight aluminum walker configurations that reduce delivery logistics costs for home health agencies serving rural counties.
- Carbon-fiber tubing:Composite material substitution in rollator frames enables 40% weight reduction versus legacy aluminum platforms, unlocking premium positioning for collapsible designs targeting aging-in-place consumers.
Market Restraints
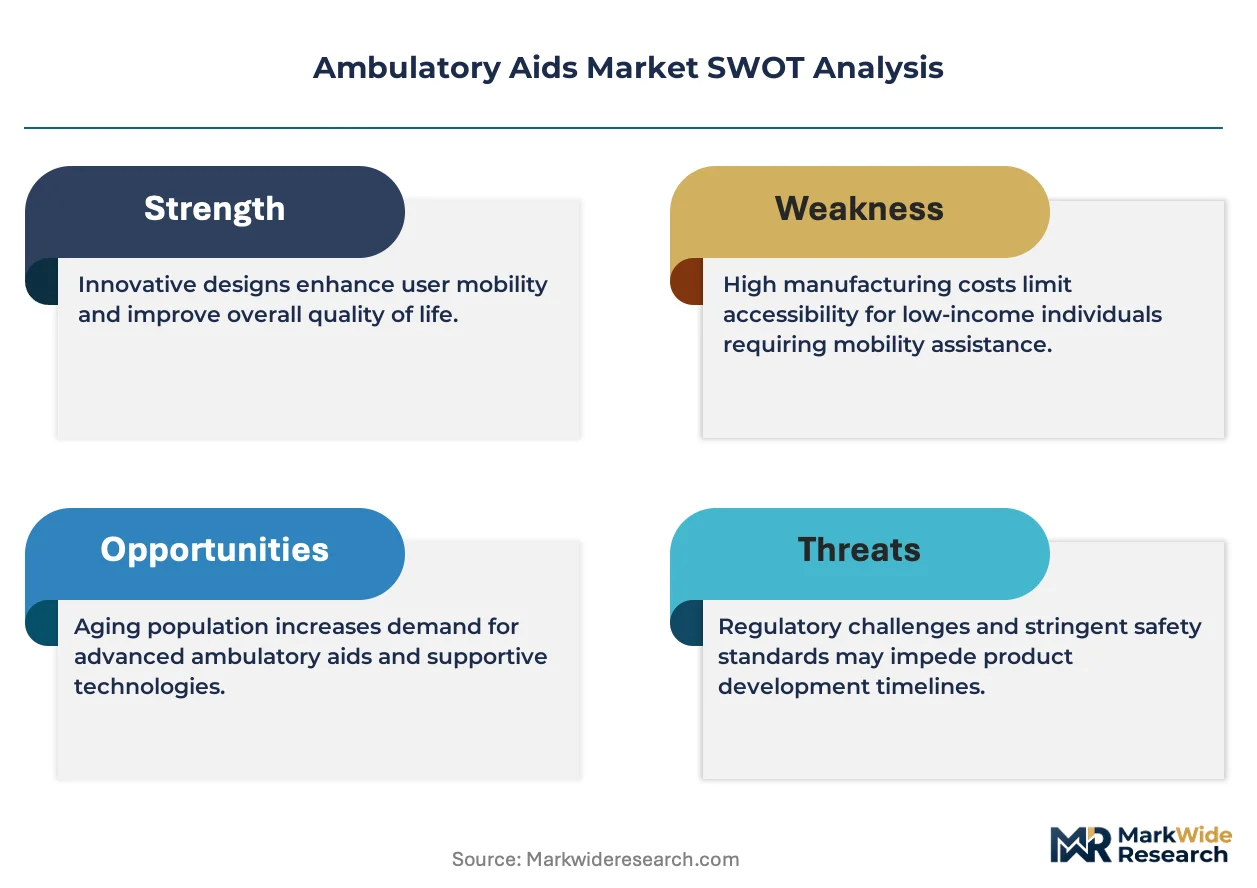
- Aluminum price volatility:Raw material input costs for walker and rollator frames fluctuate with London Metal Exchange pricing, compressing margin pools for manufacturers without long-term smelter contracts or backward integration into extrusion.
- Notified-body bottleneck:EU MDR implementation has reduced the number of designated conformity assessment bodies by two-thirds since 2017, extending rollator certification timelines from six to eighteen months and freezing product launches.
- Retail pharmacy commoditization:Basic cane and crutch segments face price erosion through mass-market pharmacy chains sourcing from Asian contract manufacturers, eliminating R&D recovery windows for branded entrants.
Strategic Opportunities
- Telehealth-integrated mobility assessments:Remote gait analysis platforms enable occupational therapists to prescribe customized rollator configurations without in-person clinic visits, opening rural and exurban patient populations previously underserved by rehabilitation networks.
- Japan's super-aged society:METI's Silver Human Resource Center subsidies for assistive device procurement create a $2 billion annual channel for premium rollators with integrated fall-detection sensors targeting the 75-plus demographic.
- Outcome-based reimbursement pilots:United States Medicare Advantage plans in Florida and Arizona are testing bundled payment models tying ambulatory aid provision to 90-day fall-reduction metrics, rewarding manufacturers with predictive analytics capabilities.
Industry Challenges
- Biomechanical engineering talent scarcity:Firms struggle to recruit specialists capable of integrating load-sensor arrays with ergonomic frame design, forcing reliance on external design consultancies that fragment IP ownership.
- Legacy ERP integration:MDR-mandated unique device identification and post-market surveillance systems require costly middleware development to connect manufacturing execution systems with regulatory databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ambulatory Aids Market |
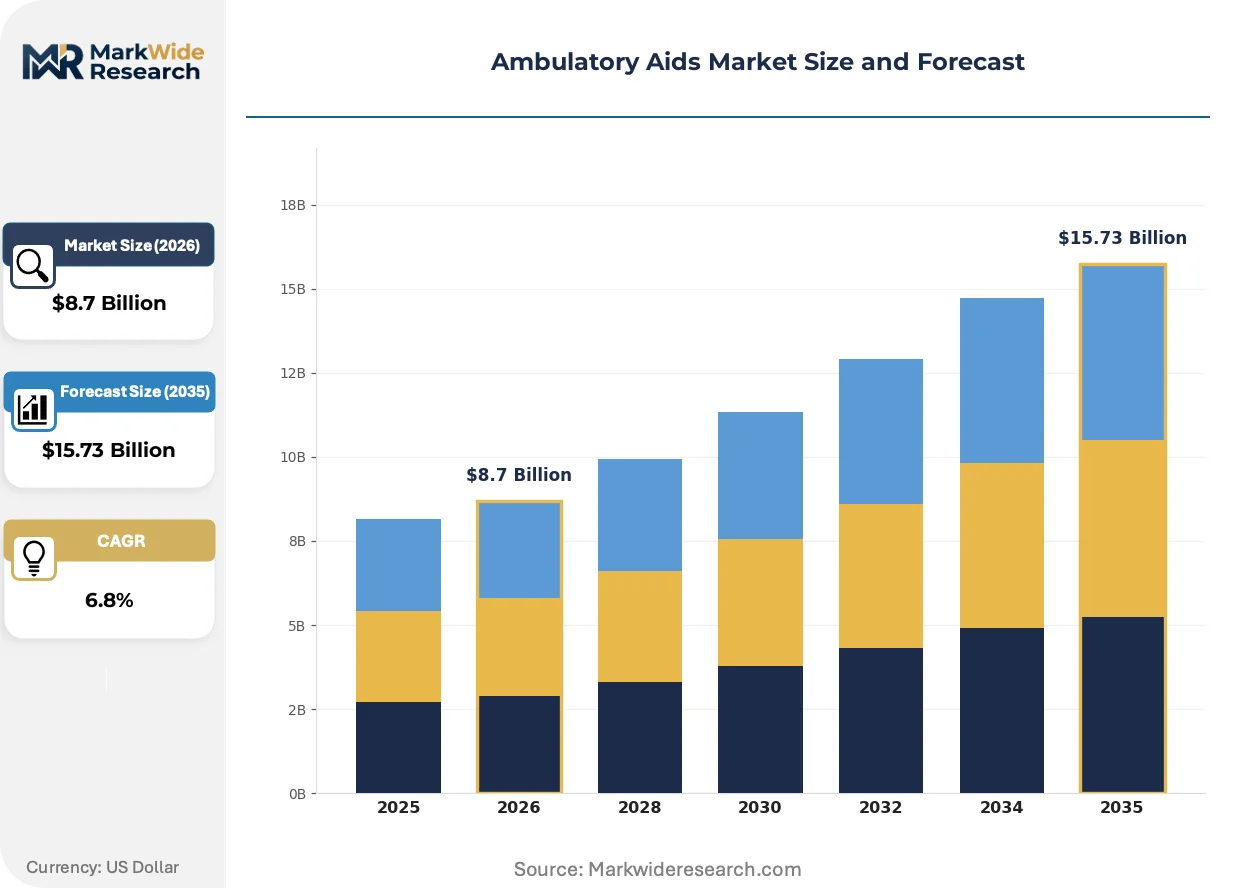
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walkers, Crutches, Canes, Rollators End User: Home Care, Hospitals, Rehabilitation Centers, Elderly Care Material: Aluminum, Steel, Plastic, Composite Distribution Channel: Retail Stores, E-Commerce, Pharmacies, Medical Supply Stores |
| Companies Covered | Invacare Corporation, Drive DeVilbiss Healthcare, Sunrise Medical, Ottobock, Medline Industries, GF Health Products, Pride Mobility Products Corporation, Permobil, Arjo AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ambulatory Aids Market Emerging Trajectories
Active sensor integration and predictive analytics capabilities are migrating from high-end prosthetics into mainstream rollator platforms, compressing the technology diffusion cycle and redefining competitive differentiation beyond frame materials.
Sensor-embedded rollators are migrating from rehabilitation clinic settings into consumer retail channels. Home care agencies in Germany and the Netherlands now specify brake-force monitoring and usage-pattern logging as standard procurement requirements. This technology migration from clinical to domestic environments is compressing price premiums for smart mobility aids and forcing traditional manufacturers to acquire firmware development capabilities or cede positioning to electronics-integrated entrants.
The EU MDR's post-market surveillance obligations for Class I walking aids now require systematic complaint handling and trend reporting to national competent authorities. Manufacturers must maintain vigilance systems capable of detecting field failures across distributed European user bases. Rollator producers with legacy paper-based quality management systems face the steepest compliance retrofit costs, advantaging firms that implemented electronic quality management infrastructure during the 2017-2021 transition window.
Hospital procurement departments are consolidating ambulatory aid purchasing through group purchasing organizations that negotiate multi-year sole-source agreements. This channel concentration displaces the traditional dealer-rehabilitation clinic relationship model in the United States, compressing distributor margins and forcing manufacturers to absorb logistics costs previously borne by intermediaries. The shift is most visible in the Southeast and Midwest regions where health system consolidation has advanced furthest.
Ambulatory Aids Market Segmentation
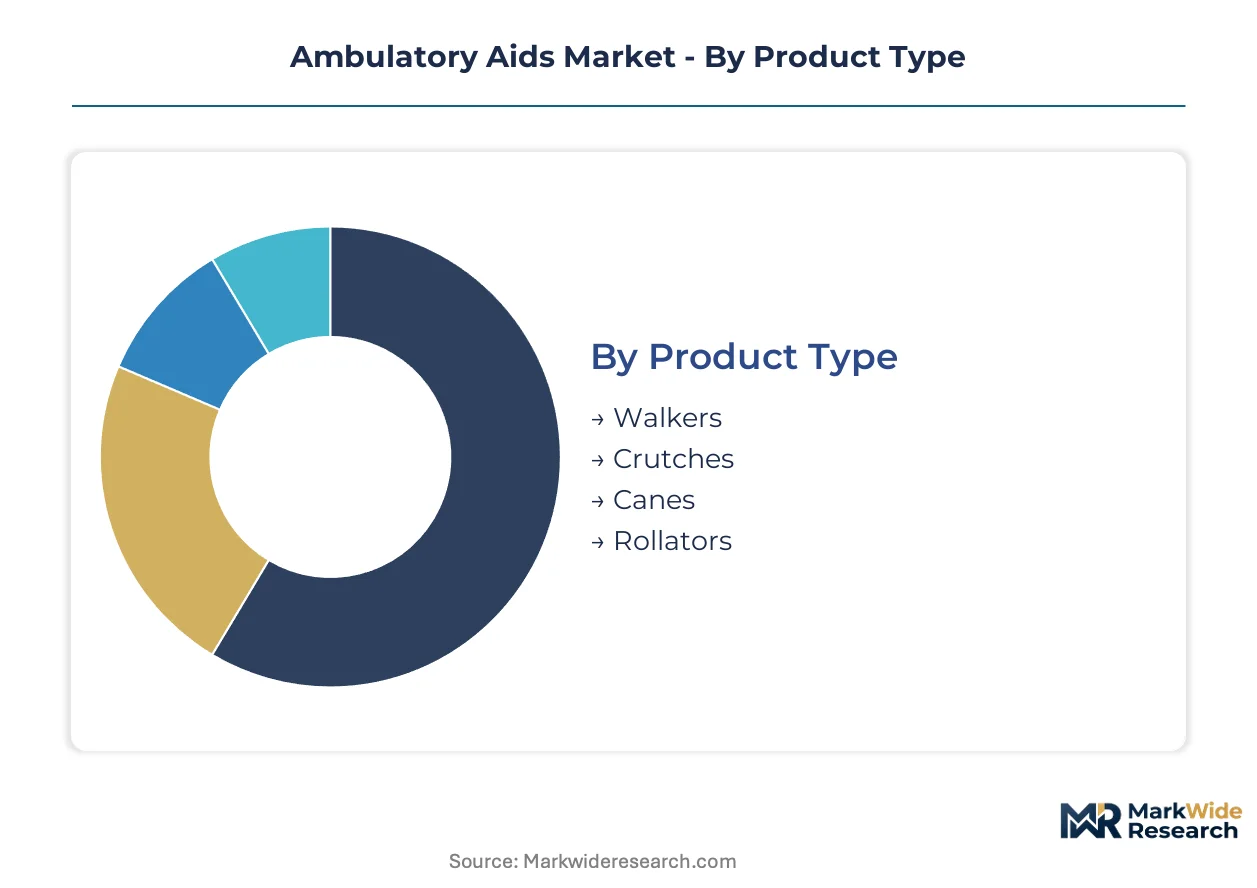
Ambulatory aids segment across four dimensions that shape procurement workflows and margin architecture. Product type determines technical complexity and reimbursement coding, while end-use setting dictates durability specifications and assembly requirements.
Product Type:
Cost tier differentiation separates commodity platforms from premium configurations with integrated braking and sensor systems.
- Walkers:Aluminum-frame platforms with rubber-tipped legs support 250-400 pound load ratings through adjustable height mechanisms. Medicare Part B fee schedules in the United States favor lightweight folding configurations that reduce rural home health delivery costs.
- Rollators:Four-wheeled designs incorporate hand-operated brake systems and padded seats, commanding price premiums through accessory integration. German elderly care networks specify rollators with usage-logging sensors as standard procurement requirements.
- Crutches:Axillary and forearm variants fabricated from aluminum tubing serve short-term rehabilitation protocols.
- Canes:Single-point and quad-base configurations represent mature, price-commoditized segments with thin margin pools concentrated in retail pharmacy channels.
Walkers command the established base. The steepest expansion runs through rollators.
End User:
Application setting determines regulatory pathway and product lifecycle requirements.
- Home Care:Aging-in-place policies shift institutional rehabilitation into domestic settings, creating demand for collapsible designs with tool-free assembly. United States Medicare Advantage plans in Florida and Arizona pilot bundled payment models tying device provision to fall-reduction metrics.
- Hospitals:Acute care procurement departments consolidate purchasing through group purchasing organizations that negotiate multi-year sole-source agreements, compressing distributor margins.
- Rehabilitation Centers:Occupational therapists prescribe customized configurations following gait analysis protocols.
- Elderly Care:Long-term care facilities in the Netherlands specify brake-force monitoring as standard equipment requirements.
Home Care captures volume leadership. Rehabilitation Centers are climbing the fastest as telehealth-integrated mobility assessments expand rural access.
Material:
Weight-performance tradeoffs and raw material input costs define competitive positioning across fabrication methods.
- Aluminum:Extruded tubing dominates walker and rollator frames through strength-to-weight ratios and weldability. London Metal Exchange pricing volatility compresses margin pools for manufacturers without long-term smelter contracts.
- Composite:Carbon-fiber substitution enables 40% weight reduction versus legacy aluminum platforms, unlocking premium positioning for collapsible designs targeting aging-in-place consumers.
- Steel:Chromed and powder-coated variants serve bariatric load requirements in institutional settings.
- Plastic:High-impact polymers form handgrips, seats, and basket components through injection molding.
Aluminum retains the installed base. Composite materials are gaining share fastest through premium rollator positioning.
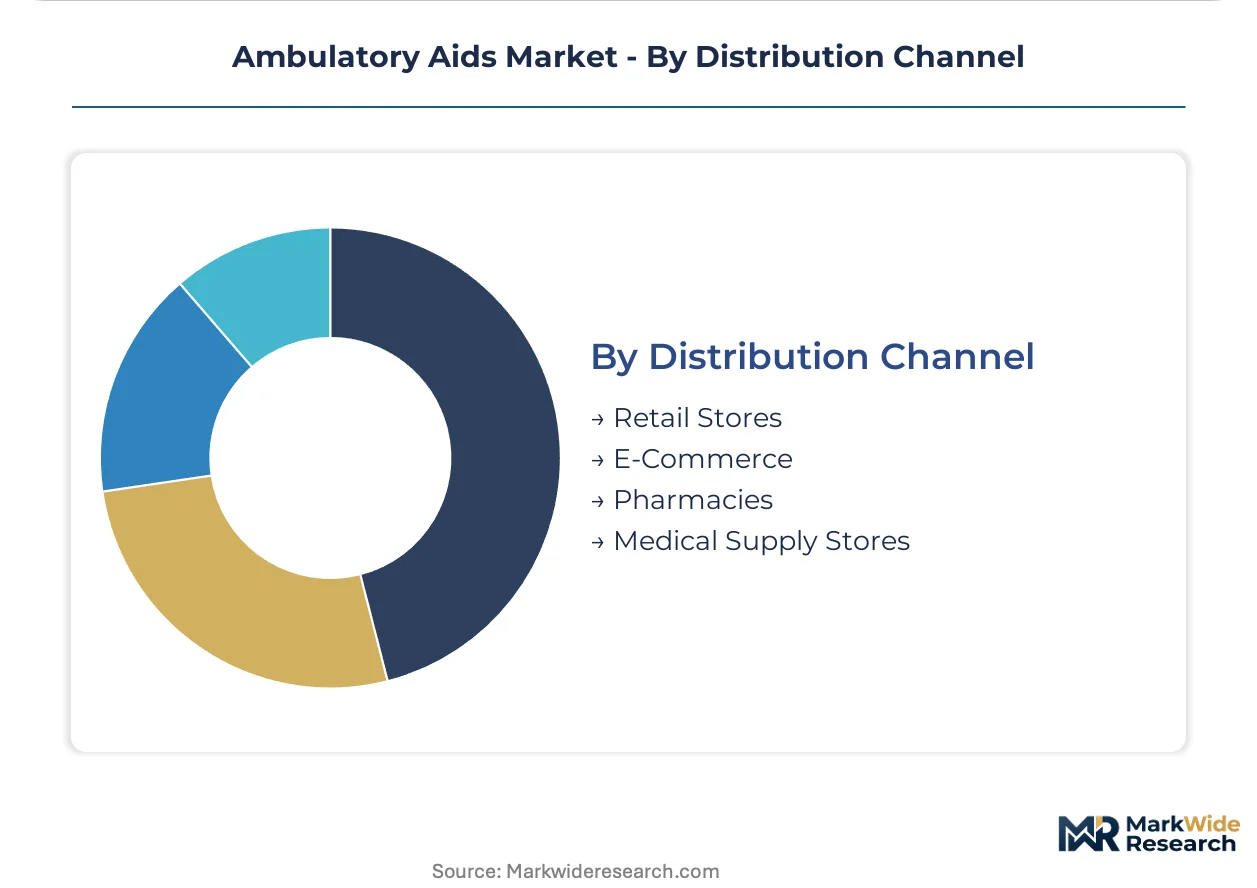
Distribution Channel:
Customer type and purchase urgency shape channel economics and product configuration.
- Medical Supply Stores:Specialized dealers maintain rehabilitation clinic relationships, offering fitting services and insurance documentation support. EU MDR technical documentation requirements advantage firms with electronic quality management infrastructure.
- E-Commerce:Direct-to-consumer platforms bypass intermediary markups for collapsible walker configurations, though return rates run higher for improperly fitted devices.
- Retail Stores:Mass-market chains source basic canes from Asian contract manufacturers, eliminating R&D recovery windows for branded entrants.
- Pharmacies:Convenience-driven procurement of single-point canes faces price erosion through generic sourcing.
Medical Supply Stores anchor the established channel. E-Commerce is expanding most quickly as remote gait analysis platforms enable unsupervised prescription workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's export dominance in engineered mobility equipment, connecting Duderstadt manufacturing clusters to Nordic and Baltic care networks.
United States
Medicare Part B durable medical equipment fee schedules drive procurement of lightweight aluminum walker configurations among rural home health agencies. FDA 510(k) clearance pathways shape product development priorities for domestic manufacturers. The Southeast region, particularly Florida, hosts bundled payment pilots tying device provision to fall-reduction metrics.
Germany
Aging-in-place policies shift institutional rehabilitation into domestic settings, creating demand for collapsible rollator designs. EU Medical Device Regulation reclassifies walking aids to higher-scrutiny tiers, extending certification timelines. Duderstadt anchors European manufacturing clusters serving elderly care networks across the Netherlands and Scandinavia.
Japan
METI's Silver Human Resource Center subsidies for assistive device procurement create premium channel demand for sensor-integrated rollators. The country's super-aged society concentrates procurement among the 75-plus demographic. Kansai region manufacturers develop fall-detection sensor platforms for domestic and export markets.
Netherlands
Long-term care facilities specify brake-force monitoring as standard equipment requirements, driving technology migration into domestic rollator procurement. National health insurance reimbursement codes favor electromechanical platforms with usage-logging capabilities. Randstad logistics networks distribute equipment to Belgian and German border regions.
China
Contract manufacturing partnerships supply cost-engineered aluminum walker platforms to North American and European distributors. NMPA medical device registration requirements govern domestic market entry for foreign brands. Pearl River Delta fabrication clusters specialize in high-volume extrusion and component assembly.
Ambulatory Aids Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and sensor supply. The vendor base separates into three tiers: multinational rehabilitation equipment conglomerates with diversified mobility portfolios; regional specialists concentrated in single product categories; and contract manufacturers serving private-label retail channels. Two strategic moves dominate competitive positioning: acquisitions of sensor technology firms to embed predictive analytics capabilities, and consolidation of notified-body relationships to navigate EU MDR certification bottlenecks.
Among diversified rehabilitation equipment manufacturers, Invacare Corporation, Drive DeVilbiss Healthcare, and Sunrise Medical occupy positions spanning multiple mobility aid categories. Invacare represents the multinational conglomerate archetype with broad geographic manufacturing footprints. Drive DeVilbiss Healthcare exemplifies cost-engineered platform scaling through Asian supply chain partnerships. Sunrise Medical anchors specialized distribution networks across Nordic and Central European rehabilitation markets. These three firms collectively illustrate the competitive tension between premium sensor-integrated positioning and volume-driven aluminum platform commoditization.
| Leading Market Players |
|---|
| Invacare Corporation |
| Drive DeVilbiss Healthcare |
| Sunrise Medical |
| Ottobock |
| Medline Industries |
| GF Health Products |
| Pride Mobility Products Corporation |
| Permobil |
| Arjo AB |
| Others |
Supply Flow & Price Mechanics
Aluminum price volatility on the London Metal Exchange determines both tier spreads between basic canes and carbon-fiber rollators and the geographic distribution of extrusion capacity. Manufacturers lacking long-term smelter contracts or backward integration into aluminum production face compressed margins that force supply chain consolidation toward Asian contract fabrication partnerships.
Pricing Analysis
Volume-discount tiering separates Medicare Part B reimbursed lightweight aluminum walkers from premium sensor-integrated rollators targeting aging-in-place consumers. Price differentiation hinges on ISO 11199 durability certification tiers and brake-system complexity. Cost compression in basic cane segments intensifies because retail pharmacy chains source generic Asian-manufactured units. Home care agencies exhibit lowest price sensitivity due to bundled reimbursement models, while individual retail consumers drive hardest bargain hunting.
Supply Chain Analysis
Extended payment terms from German and Dutch hospital procurement departments strain working capital for component suppliers of brake assemblies and sensor arrays. Manufacturing concentrates in China, Germany, and the United States. Supply chains draw from aluminum extrusion, carbon-fiber prepreg, and electromechanical sensor modules. Single-source vulnerability concentrates in EU MDR notified-body certification capacity. Distribution runs through medical supply stores, group purchasing organizations, and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth-integrated gait assessment platforms are transforming ambulatory aids from commodity hardware into connected health endpoints, creating platform-economics dynamics where firmware ecosystems determine vendor lock-in.
For Market Incumbents: Build regulatory compliance moats through captive notified-body relationships and EU MDR technical documentation capabilities. Consolidate sensor technology acquisitions to embed predictive analytics before electronics-integrated entrants capture rehabilitation clinic procurement. Channel control through exclusive GPO contracts defends against private-label Asian competitors.
For New Entrants and Emerging Players: Japan's super-aged society offers underpenetrated premium rollator demand among METI-subsidized Silver Human Resource Center procurement channels. Target rural United States home health agencies underserved by traditional rehabilitation networks through remote mobility assessment partnerships. Direct-to-consumer e-commerce with virtual fitting support circumvents entrenched medical supply store distribution.
For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors firms with pre-built MDR infrastructure and electronic quality management systems. Long-term viability across the projection horizon rests on sensor-embedded product portfolios capable of outcome-based reimbursement pilots. Watch Medicare Advantage bundled payment expansion into additional states as inflection indicator for predictive analytics valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Technology Acquisition | Embedded brake-force monitoring meets Dutch and German elderly care procurement standards. |
| EU MDR Certification Investment | Notified-body relationships compress competitor entry timelines from eighteen to six months. |
| Carbon-Fiber Platform Development | Forty percent weight reduction unlocks premium positioning for collapsible aging-in-place designs. |
| Telehealth Partnership Formation | Remote gait analysis expands rural patient access beyond traditional rehabilitation clinic networks. |
| Group Purchasing Organization Contract | Sole-source agreements with United States health systems displace traditional dealer intermediaries. |
Methodological Framework
A standing panel of biomedical engineers, hospital procurement managers, home health agency directors, and occupational therapists provided ongoing calibration against field conditions. Primary interviews with rehabilitation equipment manufacturers and GPO contracts managers combined with secondary validation from FDA 510(k) filings, CMS Medicare fee schedule databases, EU MDR technical documentation registries, and hospital procurement databases. Bottom-up unit shipment estimates triangulated against top-down reimbursement claim analysis.
Scenario-bracketing framed low, base, and high cases across the projection horizon using aluminum price volatility bands and EU MDR implementation pace variants. Segmentation dimensions modeled include product type, end-use setting, material composition, and distribution channel. CAGRs derived from fitted trend extrapolation of Medicare claims data and European elderly care procurement records, cross-checked against import-export trade statistics.
Practitioners should monitor notified-body capacity expansion, METI subsidy program modifications, and Medicare Advantage bundled payment geographic rollout for early signals. Forecasts reflect documented assumptions regarding regulatory implementation timelines and raw material cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Global Corneal Topographers Market
Medical Devices
Brazil Respiratory Devices Market
Medical Devices
North America General Surgical Devices Market
Medical Devices
Intraoral Scanners Market
Medical Devices
Surgical Mesh Market
Medical Devices
Global Blood Processing Devices and Consumables Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Global Medical Device Labeling Market
Medical Devices
Deflectable Catheters Market
Medical Devices
Transient Elastography Device Market
Medical Devices
Ear Tube Devices Market