
 Global Acetabular Cups Market | 2026-2036
Global Acetabular Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acetabular Cups Market Foresight
The gap between premium ceramic-titanium constructs and standard polyethylene-metal configurations is broadening. Zimmer Biomet leverages its integrated manufacturing footprint to sustain cost leadership across commodity tiers. Stryker differentiates through proprietary porous coating technologies that anchor premium positioning in academic medical centers. Smith & Nephew competes by emphasizing modular platform designs that extend surgical flexibility across primary and revision procedures.
Acetabular cups are hemispherical implants, typically 48–66 mm in outer diameter, that replace the damaged hip socket and articulate with a femoral head to restore biomechanical function. They are manufactured through precision casting, additive manufacturing, or machining of biocompatible alloys and ceramics, then finished with porous or bioactive surfaces to achieve osseointegration. Cementless titanium and trabecular metal variants command the strongest margin pools, reflecting surgeon preference for biological fixation in younger, active patients. Polyethylene liners retain the largest procedural volume but face gradual displacement by cross-linked and antioxidant-stabilized formulations that reduce osteolysis risk. Ceramic-on-ceramic articulations occupy the fastest-growing premium niche, driven by demand for wear resistance in high-activity demographics.
The FDA's 510(k) framework and the EU Medical Device Regulation (MDR) impose divergent evidentiary requirements that reshape regional product launch sequencing. ISO 5832 material standards and ASTM F2077 testing protocols define the baseline for international market access, with notified body capacity constraints in Europe extending certification timelines. Stakeholders must monitor how FDA digital health pre-certification pilots and EUDAMED database integration reshape post-market surveillance obligations and competitive entry dynamics.
Market Dynamics
The acetabular cups market pivots on surgeon demand for biological fixation in younger patients, which is compressing polyethylene-metal procedural share and elevating titanium-trabecular metal margin pools across orthopedic service lines.
Growth Catalysts
- EU MDR certification timelines:European notified body capacity constraints are filtering out marginal competitors, concentrating procurement among ISO 13485-certified manufacturers with established technical documentation.
- Ceramic-on-ceramic articulation:Wear-resistant bearing surfaces are capturing preference in high-activity patient demographics, extending implant longevity and reducing revision burden.
- Japan's aging surgical population:METI reimbursement frameworks for hip arthroplasty sustain procedural volumes as the 75-plus demographic expands faster than replacement workforce capacity.
Market Restraints
- Titanium sponge input volatility:Aerospace and medical demand competition for high-purity titanium feedstock creates margin pressure on cast and forged cup substrates.
- Additive manufacturing capacity concentration:Electron beam melting and laser powder bed fusion expertise clusters in Germany and the United States, limiting supply diversification.
- Ceramic fracture risk:Brittle failure modes in third-generation alumina-zirconia composites constrain adoption in high-impact loading scenarios despite superior wear profiles.
Strategic Opportunities
- India's orthopedic infrastructure buildout:CDSCO streamlined import licensing and hospital chain expansion in tier-2 cities create first-mover positioning for cementless titanium platforms.
- Digital surgical planning integration:Preoperative templating software linked to patient-specific instrumentation is opening channel partnerships between implant manufacturers and radiology AI vendors.
- FDA breakthrough device designation:Expedited review pathways for antioxidant-stabilized polyethylene formulations accelerate premium liner commercialization timelines.
Industry Challenges
- Trabecular metal topology expertise:Porous coating R&D and osseointegration validation require specialized biomaterials PhDs that orthopedic OEMs compete for against aerospace and energy sectors.
- Legacy sterilization revalidation:Gamma to e-beam transition for cross-linked polyethylene necessitates extensive fatigue testing and biocompatibility dossier updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acetabular Cups Market |
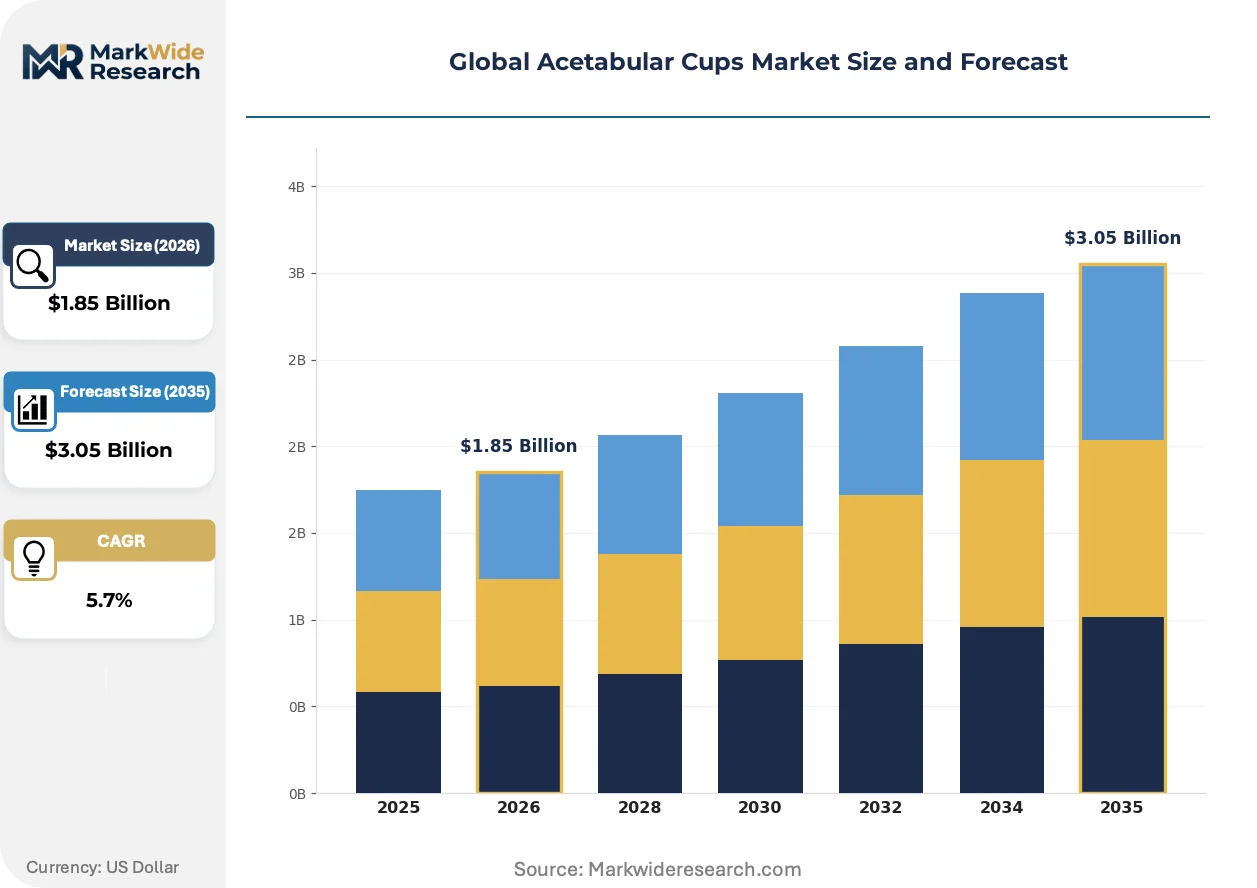
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Cups, Monoblock Cups, Cemented Cups, Cementless Cups, Hybrid Cups Material: Titanium, Cobalt Chromium, Polyethylene, Ceramic, Trabecular Metal Application: Primary Hip Replacement, Revision Hip Arthroplasty, Trauma Treatment, Tumor Reconstruction End User: Orthopedic Clinics, Ambulatory Surgical Centers, Rehabilitation Centers, Specialized Hospitals |
| Companies Covered | Stryker, Zimmer Biomet, Johnson & Johnson Services Inc. (DePuy Synthes), Smith & Nephew, Corin, Medacta International, Exactech, Inc., Merete GmbH, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acetabular Cups Market Shifts & Advancements
Manufacturing process convergence and regulatory data infrastructure are restructuring how acetabular cups move from design validation to surgical implantation, with digital thread continuity emerging as a competitive differentiator.
Additive manufacturing of titanium-tantalum gradient structures is electrifying porous fixation surface production. Academic medical centers in Germany and the United States are piloting patient-matched acetabular augments for complex revision scenarios. The technology is compressing lead times for custom geometry from 16 weeks to under 4 weeks while eliminating conventional machining waste streams.
The EU MDR's EUDAMED database integration mandates unique device identification traceability across the full implant lifecycle. Manufacturers must reconfigure quality management systems to capture post-market clinical follow-up data. Smaller notified bodies in Italy and the Netherlands are exiting orthopedic certification, consolidating conformity assessment among TÜV SÜD and BSI.
Hospital procurement committees are unbundling implant provision from instrument loaner programs, forcing manufacturers to price trays and sterilization cases separately. Integrated delivery networks in the United States are consolidating vendor lists to three preferred suppliers per joint reconstruction category. The shift is most visible in Florida and Texas health systems where orthopedic service line co-management contracts dominate.
Global Acetabular Cups Market Segmentation
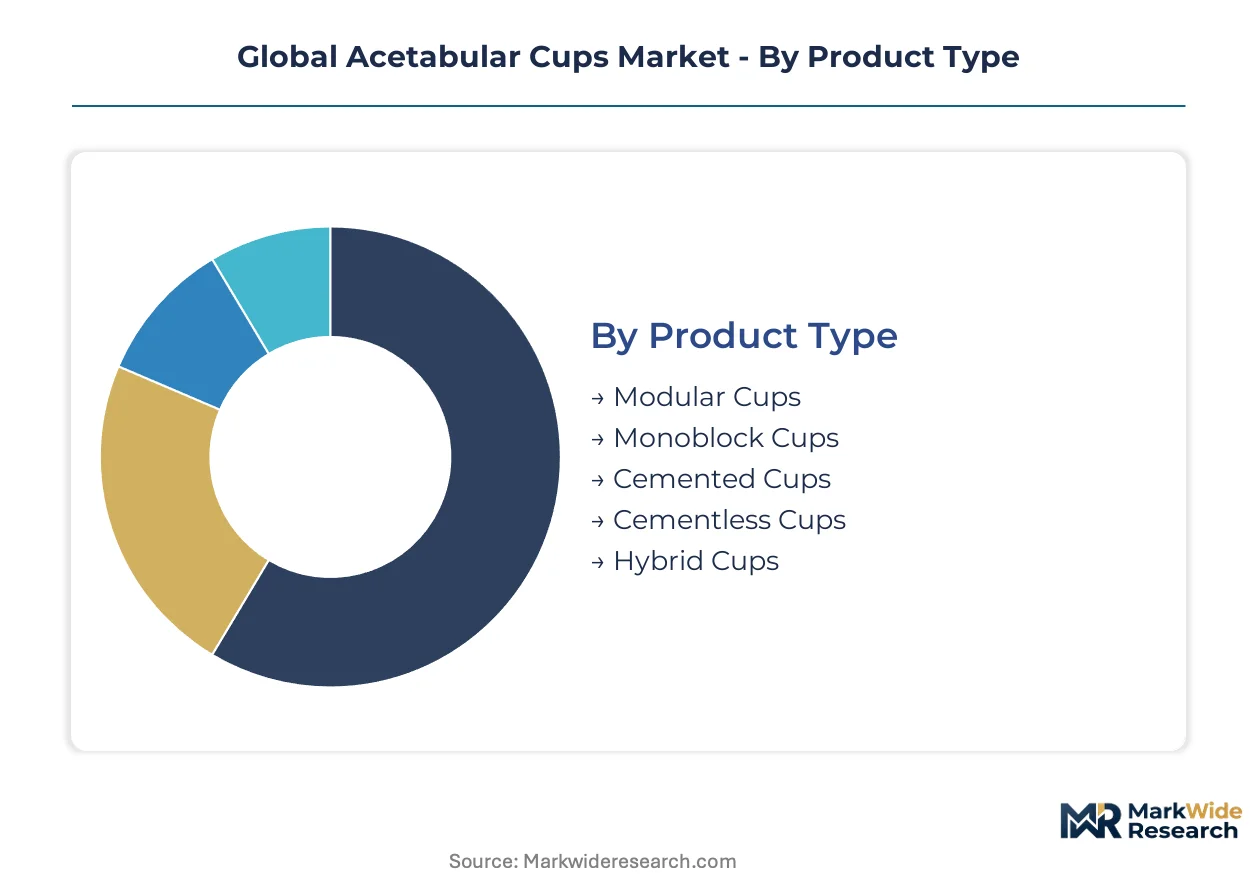
Acetabular cup segmentation reveals divergent margin profiles across fixation philosophy and bearing surface choices. Procurement committees weight biological fixation premiums against revision risk economics.
Product Type:
Volume concentrates in cementless platforms while cemented variants retain cost-sensitive procedural share.
- Cementless Cups:Porous titanium or trabecular metal surfaces achieve biological fixation without bone cement. Demand clusters in United States academic medical centers and German orthopedic clinics serving active patients under 65.
- Modular Cups:Separate shell and liner components enable intraoperative flexibility for bearing surface selection. Japanese surgeons leverage modularity to match antioxidant-stabilized polyethylene or ceramic inserts to patient activity profiles.
- Monoblock Cups:Single-piece constructs reduce disassembly risk in high-impact loading scenarios.
- Cemented Cups:Polymethylmethacrylate fixation dominates elderly osteoporotic populations in United Kingdom NHS trusts.
- Hybrid Cups:Combined fixation approaches address compromised bone stock in revision scenarios.
Mature deployment sits with cemented cups. Newer deployment is concentrated in cementless titanium-trabecular metal platforms.
Material:
Cost tier separation runs from commodity polyethylene to premium ceramic constructs with margin expansion at each step.
- Titanium:Commercially pure and alloy grades (Ti-6Al-4V ELI) form the structural substrate for cementless shells. Electron beam melting capacity in Germany and the United States constrains supply elasticity for porous variants.
- Trabecular Metal:Tantalum-based porous structures achieve elastic modulus matching cancellous bone. FDA breakthrough device designations have accelerated United States commercialization timelines for antioxidant-stabilized polyethylene pairings.
- Ceramic:Alumina and zirconia-toughened alumina articulations command premium positioning in high-activity demographics.
- Cobalt Chromium:Cast and forged substrates retain share in metal-on-metal articulations despite adverse event surveillance.
- Polyethylene:Cross-linked and vitamin E-stabilized formulations dominate procedural volume in cost-constrained settings.
Established volume sits with polyethylene liners. Steepest expansion trajectory belongs to ceramic-on-ceramic and ceramic-on-polyethylene articulations.
Application:
Customer type stratification separates routine primary procedures from complex revision economics.
- Primary Hip Replacement:Elective arthroplasty for osteoarthritis and avascular necrosis constitutes the procedural base. United States integrated delivery networks and Japan's METI-reimbursed hospital chains sustain volume concentration.
- Revision Hip Arthroplasty:Aseptic loosening, instability, and infection management drive specialized implant demand. Academic medical centers in Germany and the United States pilot patient-matched augments from additive manufacturing workflows.
- Trauma Treatment:Acetabular fracture fixation with provisional or definitive cup placement addresses younger polytrauma patients.
- Tumor Reconstruction:Custom mega-prostheses following pelvic resection require specialized design and extended lead times.
Standardized workflows dominate primary replacement. Custom engineering capabilities concentrate in revision and tumor reconstruction.
End User:
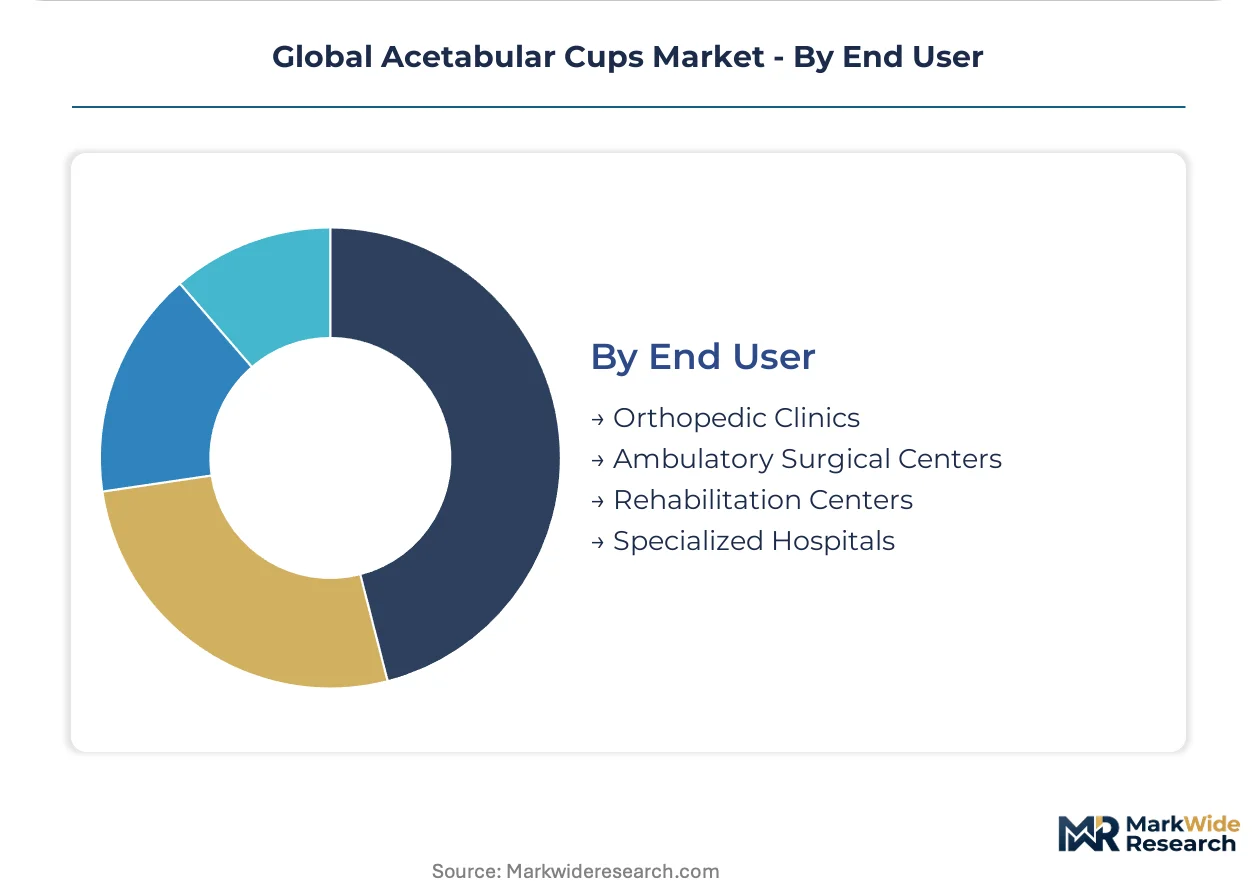
Procurement authority is shifting from surgeons toward supply chain committees with standardized vendor lists.
- Orthopedic Clinics:Dedicated arthroplasty service lines in United States specialty practices and German Schwerpunktschwerpunkte achieve economies through high procedural volume. Vendor consolidation to three preferred suppliers per joint category is most advanced in Florida and Texas health systems.
- Specialized Hospitals:Tertiary referral centers manage complex revisions and research protocols. EUDAMED traceability mandates are forcing quality system reconfigurations across European orthopedic units.
- Ambulatory Surgical Centers:Same-day discharge protocols are expanding cementless procedural eligibility in United States outpatient settings.
- Rehabilitation Centers:Post-acute recovery facilities influence implant selection through readmission risk metrics in bundled payment models.
Institutional purchasing maturity sits with specialized hospitals. Fastest volume migration is occurring in ambulatory surgical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warsaw's orthopedic manufacturing corridor anchors European acetabular cup production, with precision machining clusters feeding supply chains across Germany and Switzerland. FDA-cleared United States volumes and METI-reimbursed Japanese procedures sustain the two largest national demand pools. Regulatory divergence between FDA 510(k) pathways and EU MDR certification timelines is fragmenting product launch sequencing across major markets.
United States
Academic medical centers in Boston and the Research Triangle drive demand for cementless titanium-trabecular metal constructs among active patients under 65. FDA breakthrough device designations for antioxidant-stabilized polyethylene formulations compress commercialization timelines for premium liners. Additive manufacturing expertise clusters in Pittsburgh and Austin, where electron beam melting capacity supports patient-matched augments for complex revisions.
Germany
Schwerpunktschwerpunkte in Bavaria and North Rhine-Westphalia achieve procedural economies through high-volume arthroplasty service lines serving aging populations. EU MDR notified body capacity constraints filter procurement toward ISO 13485-certified manufacturers with established technical documentation. TÜV SÜD and BSI now dominate conformity assessment as smaller Italian and Dutch bodies exit orthopedic certification.
Japan
METI reimbursement frameworks sustain hip arthroplasty volumes as the 75-plus demographic expands faster than replacement surgical workforce capacity. Osaka and Nagoya orthopedic chains leverage modular cup platforms to match bearing surfaces to patient activity profiles. Ceramic-on-ceramic articulations capture preference in high-activity demographics seeking wear-resistant longevity.
India
CDSCO streamlined import licensing and hospital chain expansion in tier-2 cities create first-mover positioning for cementless titanium platforms. Mumbai and Delhi-NCR specialty clinics build arthroplasty capacity to address osteoarthritis burden in the 60-plus population. Domestic manufacturing incentives attract precision casting investment from European and American OEMs seeking cost-competitive substrates.
Switzerland
Swissmedic certification requirements and proximity to German orthopedic markets sustain boutique manufacturing of premium ceramic constructs. Basel and Zurich precision engineering clusters specialize in porous coating technologies and osseointegration validation. The country's medical device ecosystem focuses on high-margin niches rather than commodity polyethylene-metal configurations.
Global Acetabular Cups Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fixation philosophy and bearing surface tiers, with biological fixation specialists commanding superior returns in academic medical centers. The vendor base concentrates among integrated orthopedic OEMs with captive manufacturing footprints and specialized porous coating capabilities. Three archetypes dominate: diversified multinational reconstructive surgery platforms, mid-cap European precision manufacturers, and emerging Asia-Pacific fabricators building CDSCO-compliant quality systems. Competitive moves center on additive manufacturing capacity expansion and strategic partnerships with radiology AI vendors for digital surgical planning integration.
Within the diversified multinational tier, Stryker, Zimmer Biomet, and Johnson & Johnson Services Inc. (DePuy Synthes) represent the dominant reconstructive surgery platforms with integrated manufacturing footprints spanning precision casting through porous surface finishing. These companies exemplify scale-driven positioning across commodity and premium tiers, with regulatory dossier depth enabling synchronized FDA 510(k) and EU MDR submissions. Mid-cap specialists including Smith & Nephew and Medacta International occupy positions emphasizing modular platform architectures and geographic focus in European and Asia-Pacific markets respectively.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Johnson & Johnson Services Inc. (DePuy Synthes) |
| Smith & Nephew |
| Corin |
| Medacta International |
| Exactech, Inc. |
| Merete GmbH |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
Titanium sponge price indices cascade through acetabular cup manufacturing into three distinct procurement tiers, with aerospace demand competition for high-purity feedstock compressing margins on cast and forged substrates while cementless porous variants retain premium positioning.
Pricing Analysis
Value-based pricing anchored to revision-free survival outcomes stratifies procurement across United States integrated delivery networks. Three-tier pricing structure across premium ceramic-titanium, standard polyethylene-metal, and economy cemented configurations reflects certification grade and osseointegration performance. Cost compression in standard polyethylene-metal tiers is intensifying because hospital procurement committees now unbundle instrument loaner programs from implant pricing. Ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers prioritize bearing surface longevity over unit cost.
Supply Chain Analysis
India's domestic content mandates under PLI scheme incentives are reshaping sourcing patterns for precision casting investment. Manufacturing gravity centers on Germany, the United States, and Switzerland for electron beam melting capacity and porous coating expertise. Raw material dependencies rest on titanium sponge from aerospace suppliers, tantalum powder for trabecular metal structures, and alumina-zirconia ceramic precursors. Single-source vulnerability concentrates in electron beam melting equipment providers. Distribution runs through orthopedic OEM direct sales forces and hospital group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acetabular cups market functions as a cost-of-compliance story where EU MDR certification timelines and FDA 510(k) dossier depth erect barrier-to-entry moats favoring ISO 13485-certified incumbents with established technical documentation.
For Market Incumbents: Lock in porous coating R&D talent through specialized biomaterials PhD pipelines before aerospace and energy sectors exhaust the limited pool. Accelerate additive manufacturing capacity expansion in Pittsburgh and Austin clusters to capture patient-matched augment demand from academic medical centers. Defend against mid-cap European modular platform specialists by deepening backward integration into titanium-tantalum gradient structure production. For New Entrants and Emerging Players: Digital surgical planning software partnerships offer the lowest-friction entry vector for cementless titanium platforms in India's tier-2 city hospital chains. White-space concentration sits with CDSCO-compliant quality systems serving Mumbai and Delhi-NCR specialty clinics building arthroplasty capacity. Target antioxidant-stabilized polyethylene liner niches where FDA breakthrough device designations compress commercialization timelines relative to full PMA pathways. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European precision manufacturers with ISO 13485 certification and established EU MDR technical documentation as notified body capacity constraints filter marginal competitors. Long-term viability over a multi-year horizon rests on captive additive manufacturing expertise and porous coating validation capabilities. Monitor FDA digital health pre-certification pilot expansions as the inflection signal for platform-level consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review pathways compress premium liner commercialization timelines for antioxidant-stabilized polyethylene formulations. |
| Additive Manufacturing Capacity Expansion | Electron beam melting clusters in Pittsburgh and Austin enable patient-matched acetabular augments for complex revision scenarios. |
| Digital Surgical Planning Integration | Preoperative templating software partnerships with radiology AI vendors open channel control in academic medical centers. |
| EU MDR Certification Investment | ISO 13485 quality system depth filters procurement toward compliant manufacturers as Italian and Dutch notified bodies exit. |
| Hospital System Partnership | Integrated delivery network vendor consolidation to three preferred suppliers per joint category in Florida and Texas demands exclusivity negotiations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) clearances, EU MDR technical documentation, EUDAMED registration records, and hospital procurement databases provided validation layers. Bottom-up procedural volume estimates and top-down manufacturer revenue triangulation converged on segment-level figures.
Data-stream reconciliation across fixation philosophy, bearing surface material, application type, and end-user procurement authority generated consistent outputs over the projection horizon. CAGRs derived from regression against aging demographic trajectories, reimbursement framework stability, and arthroplasty service line expansion rates. Forecast inputs incorporated METI reimbursement schedules, CDSCO import licensing velocity, and additive manufacturing lead time compression curves.
The model holds under stable regulatory frameworks and continued aerospace-medical titanium demand competition; deviation in notified body capacity collapse or ceramic fracture risk reassessment would shift premium tier adoption curves. Forecasts reflect documented assumptions regarding surgeon preference migration toward biological fixation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
India Orthopedic Braces and Supports Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Kyphoplasty Systems Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Devices Market
Orthopedic Devices
Orthopedic Prosthetic Devices Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Japan Spinal Surgery Devices Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
Global Animal Ortho-Prosthetics Market
Orthopedic Devices
Polyethylene Orthopaedic Insert Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Limb Salvage Systems Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Brazil Spinal Surgery Devices Market
Orthopedic Devices
France Neurology Devices Market