
 Global Shockwave Therapy Market | 2026-2036
Global Shockwave Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shockwave Therapy Market Foresight
The capital-intensity gap between electrohydraulic system manufacturers and portable device entrants is collapsing as piezoelectric miniaturization lowers barrier costs. Boston Scientific Corporation leverages its interventional cardiology infrastructure to cross-sell shockwave platforms into vascular suites. Dornier MedTech anchors its position through captive lithotripter supply chains that feed orthopedic device pipelines. Zimmer MedizinSysteme competes via rehabilitation center partnerships that lock in multi-year service contracts.
Shockwave therapy delivers acoustic pulses at 0.03 to 0.5 mJ/mm² energy flux density to stimulate neovascularization and tissue regeneration without incision. Focused shockwave devices generate deeper focal zones through electromagnetic or electrohydraulic sources, while radial shockwave devices disperse energy across broader superficial areas for tendinopathy and fasciopathy treatment. Portable shockwave devices are capturing margin pools in private clinics where space constraints and capital budgets favor mobile units over fixed installations. Orthopedic treatments dominate application revenue as Medicare and statutory health insurers expand coverage for calcific shoulder tendinitis and plantar fasciitis protocols.
FDA 510(k) premarket notification and EU MDR conformity assessment shape device classification, clinical evidence requirements, and post-market surveillance obligations for manufacturers seeking US and European market access. Japan's PMDA enforces QMS Ministerial Ordinance standards that delay entry but reward compliant players with long-term hospital purchasing agreements. Stakeholders must monitor reimbursement code expansions and real-world evidence mandates that will determine which technology tiers achieve sustainable clinical adoption.
Market Dynamics
Piezoelectric miniaturization is collapsing the capital barrier between fixed electrohydraulic installations and portable shockwave platforms, redistributing competitive advantage toward device makers with semiconductor sourcing relationships rather than precision machining heritage.
Growth Catalysts
- EU MDR Class IIa pathway expansion:Streamlined conformity assessment for radial shockwave devices accelerates market entry for orthopedic applications across Germany, France, and Italy.
- Medicare reimbursement broadening:Coverage extensions for calcific shoulder tendinitis and plantar fasciitis protocols drive clinical adoption in ambulatory surgical centers and sports medicine clinics.
- Electromagnetic source efficiency gains:Next-generation coil designs reduce energy consumption per pulse while maintaining focal precision, lowering operational costs for high-volume practices.
Market Restraints
- Piezoelectric crystal supply concentration:Synthetic quartz and lead zirconate titanate sourcing depends on a limited supplier base concentrated in East Asian manufacturing corridors.
- FDA 510(k) clinical evidence escalation:Pre-market notification requirements now demand larger patient cohorts for novel energy flux density protocols, extending clearance timelines.
- Ultrasound-guided injection substitution:Image-guided corticosteroid and platelet-rich plasma delivery competes for the same chronic tendinopathy patient population.
Strategic Opportunities
- Brazil ANVISA pathway optimization:Underdeveloped regulatory infrastructure for extracorporeal shockwave devices creates first-mover positioning for manufacturers with established ISO 13485 quality systems.
- Telemedicine-integrated remote monitoring:Convergence of shockwave treatment protocols with digital therapeutic platforms enables outcome tracking and protocol adherence verification.
- Veterinary orthopedic expansion:Equine tendonitis and canine hip dysplasia protocols represent untapped application segments with lower regulatory barriers than human indications.
Industry Challenges
- Clinical training pipeline constraints:Qualified physiotherapists and sports medicine physicians capable of protocol customization remain scarce relative to device deployment rates.
- Legacy lithotripter integration complexity:Hospital capital planning cycles struggle to justify shockwave platform upgrades when existing urology equipment retains functional capacity.
- Post-market surveillance data harmonization:Divergent adverse event reporting standards between FDA, EU MDR, and PMDA complicate global safety database management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shockwave Therapy Market |
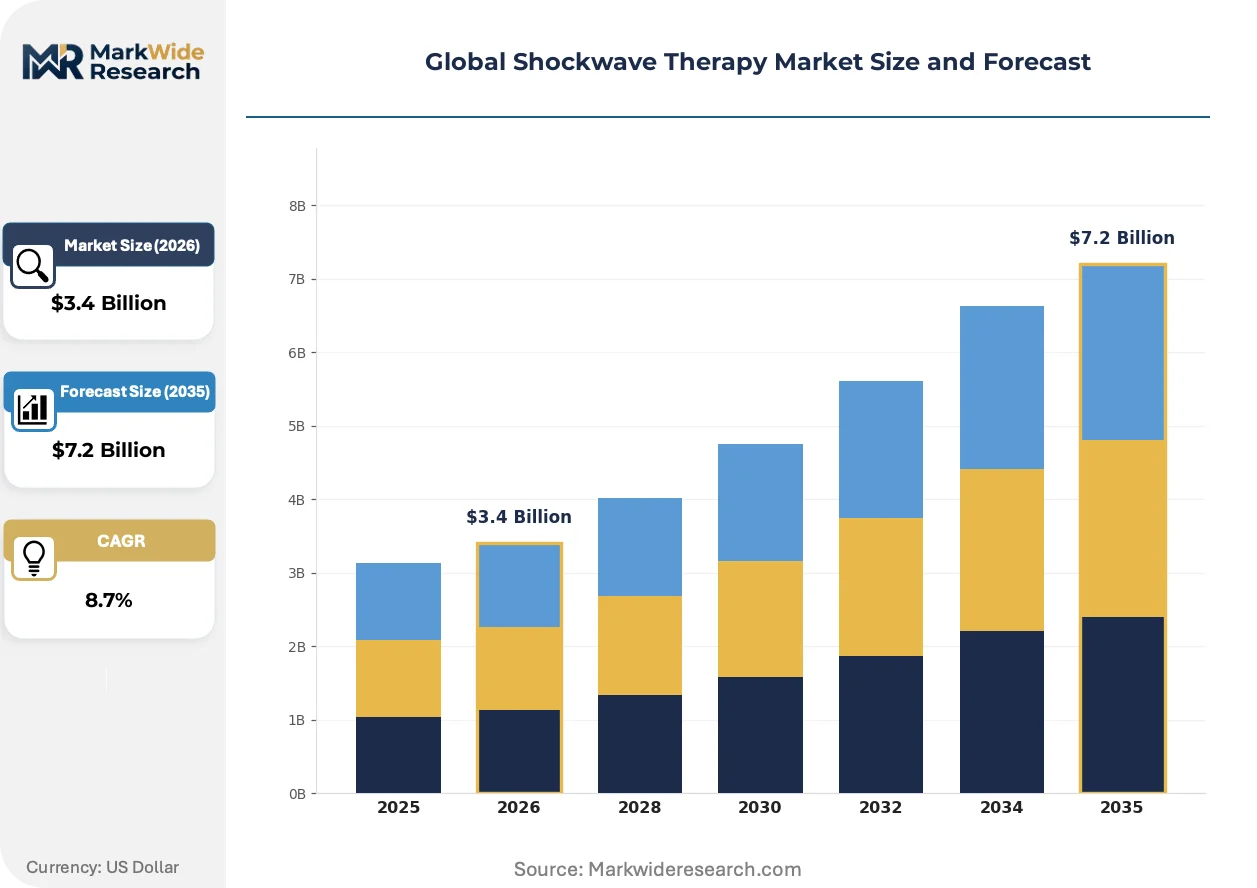
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Focused Shockwave Devices, Radial Shockwave Devices, Mini Shockwave Devices, Portable Shockwave Devices Application: Orthopedic Treatments, Sports Injury Recovery, Urology Therapy, Dermatology Procedures, Pain Management End User: Rehabilitation Centers, Private Clinics, Physiotherapy Units, Specialized Hospitals Technology: Electrohydraulic, Electromagnetic, Piezoelectric, Pneumatic |
| Companies Covered | Boston Scientific Corporation, Dornier MedTech, EMS Electro Medical Systems, BTL Corporate, Olympus Corporation, Zimmer MedizinSysteme, KARL STORZ SE & Co. KG, Siemens Healthineers, Shockwave Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shockwave Therapy Market Shifts & Advancements
Device architecture is pivoting from facility-anchored installations toward point-of-care mobility, while regulatory frameworks and procurement models recalibrate around real-world evidence generation and value-based care metrics.
Electromagnetic shockwave generation is miniaturizing through advanced ferrite core materials and compact capacitor banks, enabling handheld devices that match the energy output of cabinet-sized predecessors. Private physiotherapy chains in Germany and the Netherlands are deploying these units for house-call services and corporate wellness contracts. The technology is compressing the addressable market for rental and lease-based equipment financing, forcing traditional manufacturers to restructure pricing architectures around consumable revenue streams.
EU MDR post-market clinical follow-up requirements are mandating systematic registry participation for medium-risk orthopedic devices, compelling manufacturers to fund longitudinal outcome studies. The regulation is diverting R&D budgets toward clinical affairs infrastructure and away from hardware innovation. Small-cap device makers without existing European notified body relationships are exiting the market, consolidating competitive positioning among established CE marking holders.
Hospital procurement committees are unbundling device acquisition from service contracts, separating capital expenditure approval from multi-year maintenance agreements. This pattern is fragmenting vendor relationships and shortening equipment replacement cycles as facilities mix-and-match hardware and service providers. The shift is most pronounced in Japan's university hospital system, where METI procurement guidelines emphasize competitive tendering for each contract element.
Global Shockwave Therapy Market Segmentation
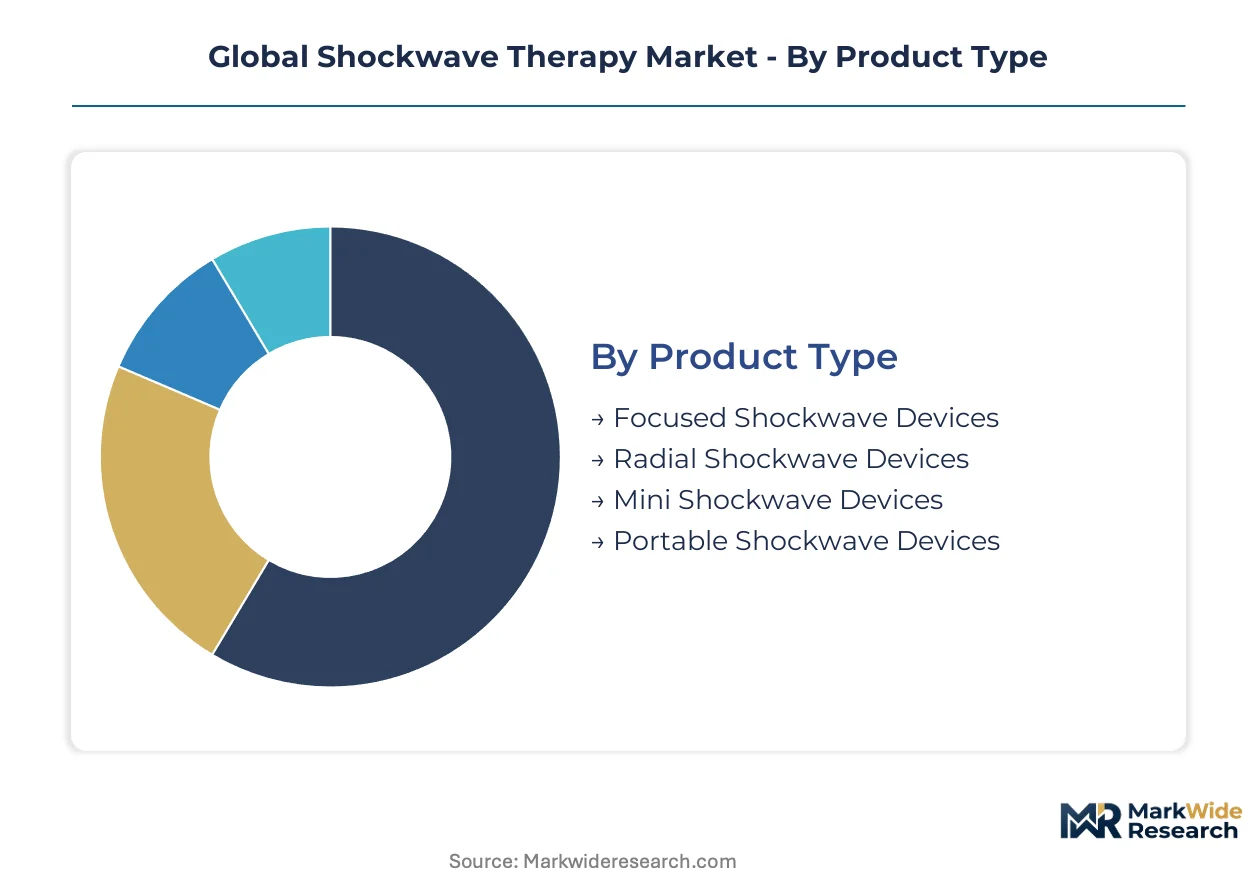
Device architecture and clinical application boundaries determine procurement pathways, reimbursement eligibility, and service contract structures across the shockwave therapy market. Segment-level channel strategies diverge sharply between capital-intensive hospital installations and mobile units targeting ambulatory settings.
Product Type:
Channel mix varies by installation footprint—fixed electrohydraulic systems flow through hospital capital committees, while piezoelectric miniaturization enables direct-to-clinic sales bypassing traditional distributor networks.
- Focused Shockwave Devices:Electromagnetic and electrohydraulic sources generate precise focal zones at 0.03 to 0.5 mJ/mm² energy flux density for deep tissue targeting. German university hospitals and Japanese cardiovascular centers anchor demand as these institutions prioritize focal precision for calcific tendinitis and vascular interventions.
- Radial Shockwave Devices:Pneumatic ballistic mechanisms disperse acoustic energy across broader superficial zones for fasciopathy and myofascial trigger point treatment. Private physiotherapy chains in the Netherlands and corporate wellness providers in the United States drive procurement volume for radial platforms given lower capital thresholds and faster treatment protocols.
- Mini Shockwave Devices:Compact electromagnetic architectures reduce cabinet dimensions by 40-60% versus legacy installations.
- Portable Shockwave Devices:Battery-powered piezoelectric units enable point-of-care deployment in sports venues and home-care settings.
Radial shockwave devices dominate installed base across European rehabilitation networks. Portable shockwave devices are where expansion concentrates as private clinics in the United States and Germany bypass capital committee procurement.
Application:
Reimbursement code availability and clinical evidence maturity create tiered margin structures across indication categories.
- Orthopedic Treatments:Calcific shoulder tendinitis, plantar fasciitis, and lateral epicondylitis protocols carry established CPT and EBM reimbursement codes in the United States and Germany. Medicare coverage expansion and statutory health insurer recognition in Bavaria and North Rhine-Westphalia sustain volume concentration.
- Sports Injury Recovery:Tendinopathy and stress fracture protocols target professional athletics programs and Olympic training centers. Australian Institute of Sport and UK Sport procurement frameworks prioritize devices with validated return-to-play protocols.
- Urology Therapy:Extracorporeal shockwave lithotripsy retains installed base concentration in hospital urology departments.
- Dermatology Procedures:Cellulite and scar revision applications operate outside established reimbursement pathways.
- Pain Management:Myofascial pain syndrome and chronic regional pain syndrome protocols compete with neuromodulation alternatives.
Orthopedic treatments command the highest reimbursement-attached revenue per procedure. Sports injury recovery is climbing the fastest as professional team medical budgets expand device procurement outside hospital systems.
End User:
Procurement authority and capital allocation timelines segment customer economics.
- Rehabilitation Centers:Multi-year service contracts and bundled device-plus-therapist training packages dominate German and Japanese purchasing patterns. Zimmer MedizinSysteme and regional distributors lock in exclusive supply agreements through outcome-based contracting.
- Private Clinics:Lease financing and per-procedure consumable models reduce upfront capital requirements. Physiotherapy entrepreneurs in Florida and Texas favor portable electromagnetic units with 24-36 month depreciation schedules.
- Physiotherapy Units:Hospital-embedded departments operate within centralized capital planning cycles.
- Specialized Hospitals:Academic medical centers in Switzerland and Austria prioritize research collaboration clauses in procurement tenders.
Rehabilitation centers concentrate installed base through multi-year exclusive agreements. Private clinics are gaining share fastest as direct-to-practice distribution erodes traditional hospital supply chain intermediation.
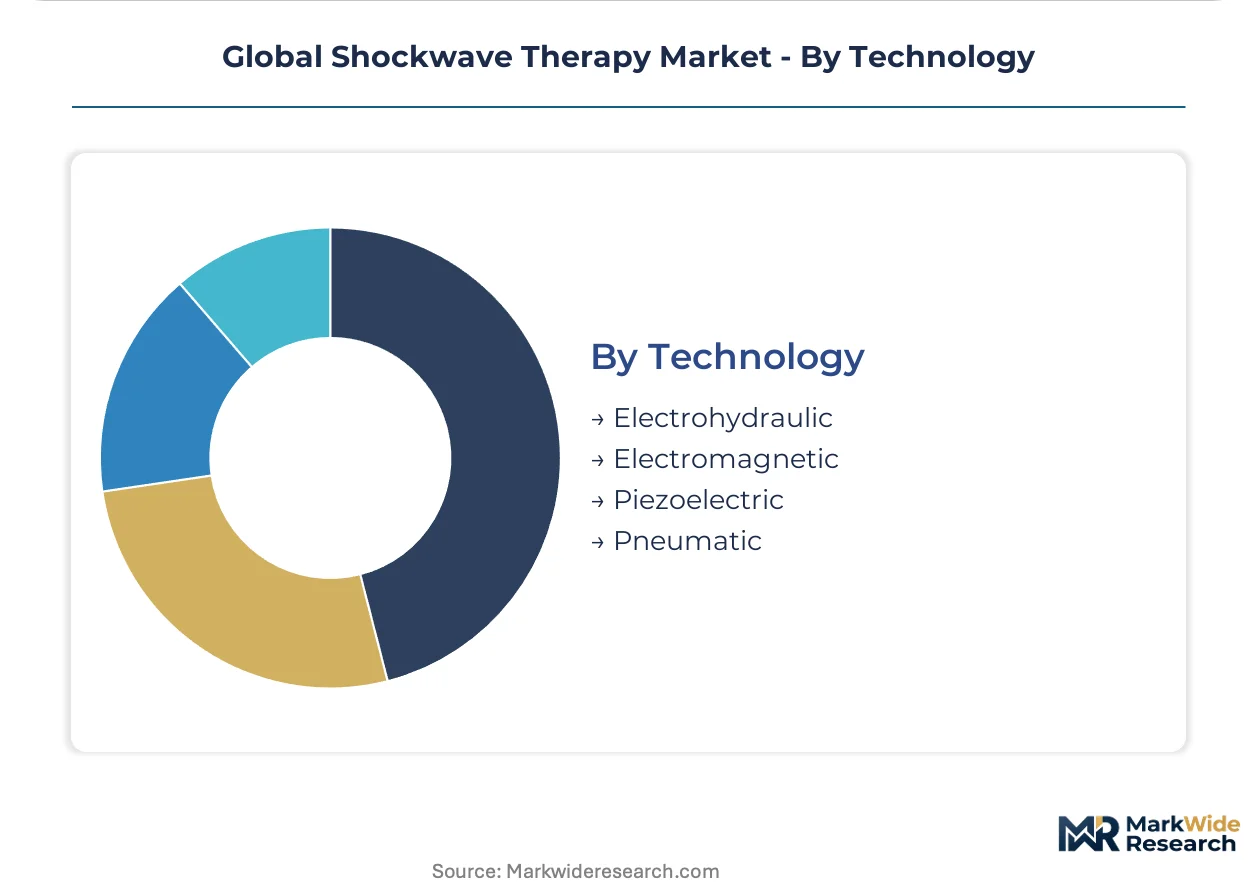
Technology:
Energy generation physics determines component sourcing, manufacturing geography, and service interval economics.
- Electrohydraulic:Spark-gap electrodes and elliptical reflectors deliver highest peak pressures for urological lithotripsy. Dornier MedTech's captive reflector machining in Germany and Switzerland sustains premium positioning through precision optical manufacturing heritage.
- Electromagnetic:Flat coil and cylindrical coil designs enable miniaturization without focal degradation. Ferrite core suppliers in South Korea and Taiwan are displacing traditional European electromagnetic component vendors.
- Piezoelectric:Lead zirconate titanate crystal arrays require precision ceramic sintering capabilities concentrated in Japanese and Chinese manufacturing corridors.
- Pneumatic:Ballistic projectile mechanisms offer lowest unit cost but higher consumable replacement frequency.
Electrohydraulic systems anchor legacy installed base in urology suites. Electromagnetic platforms are expanding most quickly as coil efficiency gains enable handheld form factors without energy output compromise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys shockwave platforms primarily through statutory health insurance reimbursement pathways for orthopedic outpatient care, whereas the United States channels volume through Medicare-covered ambulatory surgical centers and Japan concentrates installation in university hospital cardiovascular suites.
Germany
Bavaria and North Rhine-Westphalia anchor device procurement through expanded EBM reimbursement codes for calcific shoulder tendinitis and plantar fasciitis protocols. The EU MDR Class IIa pathway streamlines conformity assessment for radial shockwave devices entering German, French, and Italian markets. Rehabilitation centers in Munich and Cologne lock in multi-year exclusive supply agreements through outcome-based contracting with regional distributors.
United States
Medicare coverage extensions for orthopedic shockwave procedures drive clinical adoption across ambulatory surgical centers and sports medicine clinics in Florida and Texas. The FDA 510(k) premarket notification pathway demands larger patient cohorts for novel energy flux density protocols, extending clearance timelines for device innovators. Physiotherapy entrepreneurs in Houston and Miami favor portable electromagnetic units with 24-36 month depreciation schedules.
Japan
PMDA QMS Ministerial Ordinance standards delay market entry but reward compliant manufacturers with long-term hospital purchasing agreements. METI procurement guidelines emphasize competitive tendering for device acquisition and service contracts across university hospital systems. The Kanto region surrounding Tokyo concentrates cardiovascular shockwave installations in academic medical centers prioritizing research collaboration clauses.
Netherlands
Private physiotherapy chains deploy compact electromagnetic units for house-call services and corporate wellness contracts in Amsterdam and Rotterdam. EU MDR post-market clinical follow-up requirements mandate systematic registry participation, diverting R&D budgets toward clinical affairs infrastructure. The Randstad cluster leads European adoption of battery-powered piezoelectric platforms for point-of-care mobility.
Brazil
Underdeveloped ANVISA regulatory infrastructure for extracorporeal shockwave devices creates first-mover positioning for manufacturers with established ISO 13485 quality systems. São Paulo's private clinic networks represent the primary demand concentration as public hospital capital budgets remain constrained. Sports medicine facilities in Rio de Janeiro pursue direct-to-practice distribution channels bypassing traditional supply chain intermediation.
Global Shockwave Therapy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding hospital capital committee relationships and the lower tier competing through portable platform innovation. Electrohydraulic heritage manufacturers retain premium positioning in urology suites, while electromagnetic miniaturization specialists capture private clinic volume. Competitive moves center on M&A for European notified body relationships and strategic partnerships for semiconductor sourcing.
Within the integrated device tier, Boston Scientific Corporation and Dornier MedTech occupy positions reflecting interventional infrastructure leverage and captive lithotripter supply chain control. Zimmer MedizinSysteme exemplifies the rehabilitation center partnership archetype, anchoring multi-year service contract relationships. These three manufacturers represent distinct competitive vectors: cross-selling into vascular suites, precision optical manufacturing heritage, and exclusive supply agreements with physiotherapy networks.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Dornier MedTech |
| EMS Electro Medical Systems |
| BTL Corporate |
| Olympus Corporation |
| Zimmer MedizinSysteme |
| KARL STORZ SE & Co. KG |
| Siemens Healthineers |
| Shockwave Medical Inc. |
| Others |
Supply & Pricing Matrix
Piezoelectric crystal substitution for electrohydraulic spark-gap assemblies redraws component sourcing maps from German precision machining corridors toward East Asian ceramic sintering clusters, collapsing legacy premium pricing while elevating semiconductor-style procurement economics.
Pricing Analysis
Consumable revenue from replacement transducers and preventive service contracts drives lifetime customer value more than initial hardware margins. Three-tier pricing structure across premium electromagnetic platforms, standard radial pneumatic systems, and economy portable piezoelectric units stratifies by focal precision certification and after-sales bundling intensity. Pricing pressure stems from private clinic lease-finance proliferation in Florida and Texas that compresses upfront capital recovery windows. Rehabilitation centers anchored by multi-year exclusive agreements show lowest price sensitivity; independent physiotherapy startups exhibit highest elasticity.
Supply Chain Analysis
Japan and China anchor synthetic quartz and lead zirconate titanate crystal production for piezoelectric transducer arrays. Ferrite core electromagnetic components draw from South Korean and Taiwanese semiconductor foundry networks. Supply chain risk centers on single-source vulnerability for precision ceramic sintering capabilities concentrated in Nagoya and Shenzhen manufacturing corridors. Distribution runs through regional medical device distributors in Germany, direct-to-practice sales forces in the United States, and hospital procurement committees in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects as telemedicine-integrated shockwave protocols create interoperability standards between hardware manufacturers and digital therapeutic ecosystems, redefining competitive moats around data infrastructure rather than device specifications alone.
For Market Incumbents: Secure European notified body relationships under EU MDR post-market clinical follow-up mandates before smaller competitors exit due to registry participation cost burdens. Deepen backward integration into ferrite core supply through South Korean semiconductor partnerships to offset East Asian component sourcing concentration risks. For New Entrants and Emerging Players: Anchor in Brazilian private clinic networks where ANVISA regulatory infrastructure remains underdeveloped for extracorporeal shockwave categories, creating first-mover positioning for ISO 13485-certified manufacturers. Target São Paulo sports medicine facilities through direct-to-practice distribution channels that bypass entrenched hospital supply chain intermediation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed electromagnetic miniaturization specialists lacking European CE marking infrastructure. Five-to-ten year viability hinges on reimbursement code expansion sustainability rather than hardware innovation cycles. Monitor Medicare coverage determinations for novel energy flux density protocols as the definitive inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Relationship Acquisition | Accelerates CE marking timelines for radial shockwave orthopedic devices entering German and French markets. |
| Telemedicine Platform Integration | Enables remote treatment protocol adherence verification and outcome tracking for corporate wellness contracts. |
| Veterinary Orthopedic Protocol Development | Opens equine tendonitis and canine hip dysplasia segments with lower regulatory barriers than human indications. |
| Ferrite Core Supply Partnership | Secures electromagnetic coil component access from South Korean semiconductor foundries for handheld device miniaturization. |
| Reimbursement Strategy Investment | Expands Medicare and statutory health insurer recognition for calcific shoulder tendinitis and plantar fasciitis protocols. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with device development executives, regulatory affairs leads at notified bodies, hospital purchasing committee chairs, and physiotherapy chain procurement directors; and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare coverage determinations, and hospital GPO contract repositories. Bottom-up installed base modeling and top-down reimbursement flow analysis triangulated volume and value estimates.
Across the analysis window, the forecast framework modeled device architecture segmentation by energy generation physics, application tier by reimbursement code maturity, and end-user channel by procurement authority concentration. CAGRs derived from procedure volume elasticity to coverage expansion events and capital expenditure cycle timing in ambulatory surgical centers. Electromagnetic efficiency gain curves and piezoelectric miniaturization cost reduction trajectories informed technology transition assumptions.
Material uncertainties — reimbursement code retraction, piezoelectric crystal supply disruption, and EU MDR notified body capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and clinical evidence generation timelines. Recalibration cycles align with material shifts in Medicare coverage determinations and EU MDR post-market surveillance mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
Orthopedic Braces and Supports Market
Orthopedic Devices
Global Total Ankle Replacement Market
Orthopedic Devices
India Spinal Surgery Devices Market
Orthopedic Devices
Global Artificial Joints Market
Orthopedic Devices
US Tendon Repair Market
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market
Orthopedic Devices
Bone Void Fillers Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Orthopedic Trauma Devices Market
Orthopedic Devices
Japan Spinal Surgery Devices Market