
 Chondroplasty Market | 2026-2036
Chondroplasty Market Size, Share, and Industry Trends Forecast 2026-2036
Chondroplasty Market Analysis
The gap between premium biologic chondroplasty and commodity mechanical debridement is shifting as payers tighten coverage for high-cost regenerative interventions while expanding access to basic arthroscopic procedures. Smith & Nephew leverages its integrated sports medicine portfolio to anchor premium positioning across hospital and ambulatory settings. Medtronic competes through sustained R&D investment in minimally invasive delivery platforms. Zimmer Biomet differentiates via specialized orthopedic reconstruction expertise that extends into cartilage repair workflows.
Chondroplasty encompasses surgical and biologic interventions designed to restore articular cartilage integrity, typically involving arthroscopic mechanical debridement, marrow stimulation, or cellular transplantation techniques performed at tissue depths of 2–4 millimeters to preserve subchondral bone architecture. The primary purpose is to alleviate joint pain, restore mechanical function, and delay or prevent progression to total joint arthroplasty in patients with focal chondral defects. Microfracture remains the most frequently performed procedure due to its technical simplicity and established reimbursement, though autologous chondrocyte implantation occupies the highest margin tier as regulatory pathways for cell-based therapies mature. Orthobiologics represents the fastest-expanding technology segment, with stem cell therapy applications attracting significant clinical trial investment despite lingering payer uncertainty.
The FDA regulates chondroplasty devices and biologics under distinct premarket pathways, with 510(k) clearance governing mechanical instruments and BLA or IND requirements applying to cell-based products, while CMS reimbursement determinations directly shape provider adoption economics. ISO 13485 quality management standards and the EU Medical Device Regulation impose additional compliance burdens on manufacturers seeking multi-jurisdictional market access. Stakeholders must monitor evolving payer evidence requirements for regenerative therapies and calibrate portfolio investments between proven mechanical solutions and higher-risk biologic innovations.
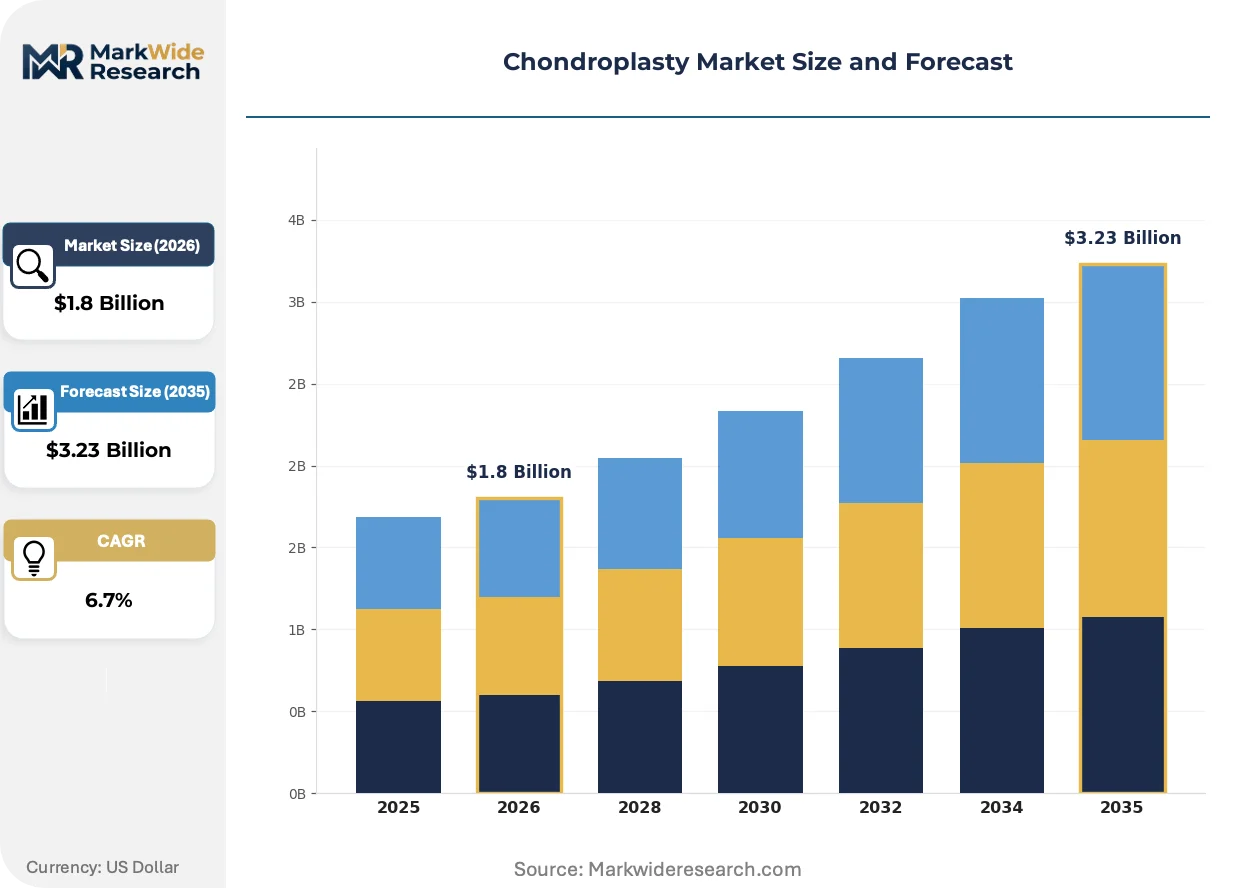
Market Dynamics
The chondroplasty market pivots on CMS reimbursement recalibration for outpatient orthopedic procedures, which is compressing margins for biologic interventions while expanding volume access for mechanical debridement techniques.
Growth Catalysts
- CMS outpatient reimbursement expansion:Medicare's Ambulatory Surgical Center payment reforms incentivize same-day chondroplasty procedures, driving facility investment in arthroscopic suites across United States health systems.
- Sports medicine facility buildout:Dedicated orthopedic centers targeting active aging populations are standardizing cartilage repair protocols, creating procedural volume anchors in metropolitan clusters.
- FDA regenerative medicine framework:The agency's Regenerative Medicine Advanced Therapy designation pathway accelerates cell-based product development timelines, attracting venture funding toward autologous chondrocyte platforms.
Market Restraints
- Biologic cost compression:Payer prior authorization requirements for matrix-induced autologous chondrocyte implantation create 45-90 day reimbursement delays, restricting patient access to high-margin therapies.
- Supply concentration in collagen matrices:Porcine-derived scaffold manufacturing concentrates among three European suppliers, exposing producers to veterinary disease outbreak disruptions and import inspection bottlenecks.
- Technical ceiling at subchondral bone:Current marrow stimulation techniques cannot reliably restore hyaline cartilage architecture in defects exceeding 4 square centimeters, limiting addressable patient populations.
Strategic Opportunities
- India ambulatory surgery center penetration:Underdeveloped cartilage repair infrastructure in tier-2 Indian cities creates first-mover positioning for arthroscopy equipment leasing models paired with surgeon training programs.
- Allogeneic off-the-shelf platforms:Cryopreserved juvenile cartilage products eliminate patient-specific manufacturing delays, opening same-day surgical scheduling previously reserved for mechanical debridement.
- EU MDR Article 117 convergence:Coordinated device-drug-biologic regulatory pathways streamline combination product approvals, reducing time-to-market for matrix-delivered cellular therapies.
Industry Challenges
- Arthroscopy fellowship pipeline constraints:United States orthopedic residency programs graduate insufficient cartilage repair specialists to match procedural demand growth, extending patient wait times.
- Cell therapy manufacturing scale-up:Autologous chondrocyte expansion requires GMP-compliant cleanroom infrastructure with 18-24 month validation timelines, constraining production flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chondroplasty Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfracture, Osteochondral Autograft, ACI, Allograft Delivery Mode: Intra-articular Injection, Surgical Procedure, Outpatient Therapy, Rehabilitation End User: Orthopedic Clinics, Hospitals, Rehabilitation Centers, Sports Medicine Facilities Technology: Biologic Therapy, Regenerative Medicine, Stem Cell Therapy, Orthobiologics |
| Companies Covered | Smith & Nephew, Medtronic, Zimmer Biomet, B. Braun, Exactech, DePuy Synthes, Arthrex, CONMED Corporation, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chondroplasty Market Emerging Trajectories
Cartilage repair technology is bifurcating between commodity arthroscopic tools and precision biologic delivery systems, with regulatory science increasingly determining competitive boundaries between mechanical and cellular approaches.
Matrix-assisted autologous chondrocyte implantation is absorbing demand from first-generation periosteal patch techniques, offering sutureless fixation and reduced operative time. Academic medical centers in Germany and South Korea are adopting these platforms at replacement rates exceeding 60% for focal femoral condyle defects. The technology is absorbing market share from microfracture in athletes under 40, though payer resistance limits penetration in commercial populations.
EU MDR Annex XVI expansion reclassifies certain cartilage repair scaffolds as Class III devices, imposing clinical evidence requirements previously reserved for permanent implants. Swiss and Dutch notified bodies are applying enhanced scrutiny to resorbable matrix durability claims, extending review timelines by 8-14 months. Manufacturers are responding with prospective registry commitments and real-world evidence collection protocols to satisfy post-market surveillance obligations.
Hospital purchasing committees are consolidating orthopedic vendor contracts, bundling arthroscopy visualization systems with disposable instrument commitments. This concentration is displacing standalone chondroplasty device suppliers in United States integrated delivery networks, forcing smaller manufacturers toward distributor partnerships or private-label arrangements. The shift is most pronounced in Florida and Texas health systems pursuing supply chain standardization.
Chondroplasty Market Segmentation
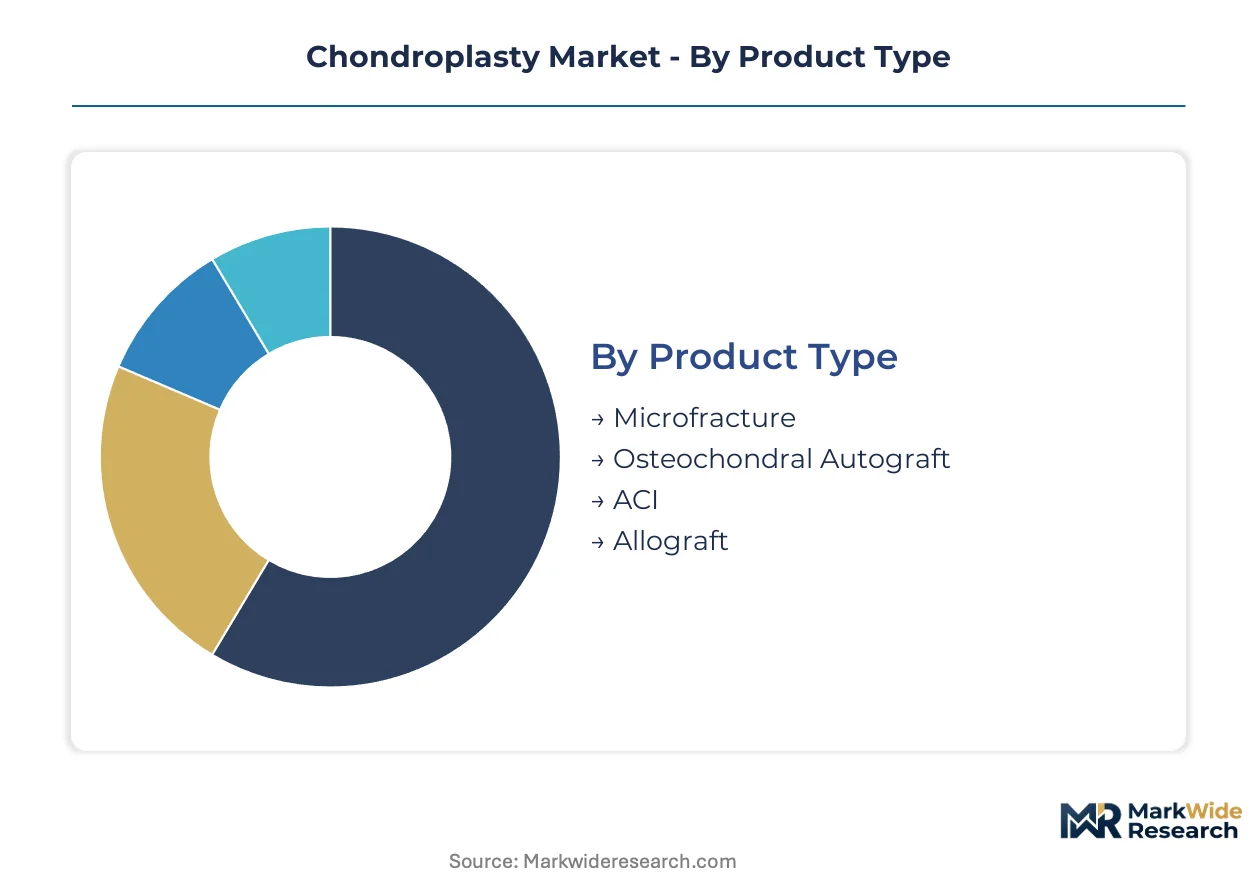
Chondroplasty segmentation reveals distinct commercial profiles across intervention types, with reimbursement pathways and technical complexity creating divergent margin structures. Product portfolios must balance high-volume mechanical procedures against premium biologic platforms with elongated sales cycles.
Product Type:
Technology sophistication defines the product hierarchy, ranging from established marrow stimulation to cell-based regeneration platforms.
- Microfracture:Arthroscopic technique creating subchondral bone perforations to release marrow elements and stimulate fibrocartilage formation. Demand concentrates in United States ambulatory surgical centers where CMS reimbursement for outpatient knee procedures drives procedural volume.
- ACI:Two-stage autologous chondrocyte harvesting, expansion, and implantation requiring GMP-compliant cell processing facilities. German and South Korean academic medical centers absorb disproportionate volume as national health systems maintain favorable reimbursement for matrix-assisted variants.
- Osteochondral Autograft:Mosaicplasty technique transferring cylindrical bone-cartilage plugs from non-weight-bearing donor sites.
- Allograft:Cryopreserved donor tissue eliminating donor site morbidity but introducing supply chain dependencies on tissue bank networks.
Microfracture leads on scale; ACI leads on momentum.
Delivery Mode:
Care setting migration toward outpatient environments is reshaping delivery infrastructure requirements across all intervention types.
- Surgical Procedure:Open or arthroscopic operative intervention requiring sterile field and anesthesia support. United States hospital outpatient departments and ambulatory surgery centers capture the dominant share as CMS payment reforms expand same-day procedure eligibility.
- Intra-articular Injection:Image-guided delivery of biologic suspensions including platelet-rich plasma or cell concentrates. Sports medicine facilities in metropolitan United States clusters standardize these protocols for active aging populations seeking cartilage preservation alternatives.
- Outpatient Therapy:Non-surgical management protocols including viscosupplementation and physical therapy integration.
- Rehabilitation:Post-interventional recovery protocols addressing range of motion and quadriceps strengthening.
Surgical procedure anchors revenue concentration; intra-articular injection expands most quickly.
End User:
Facility type determines purchasing authority structure and capital equipment requirements for chondroplasty platforms.
- Hospitals:Integrated delivery networks with centralized orthopedic service lines and value-based care contracts. United States health systems in Florida and Texas pursue vendor consolidation strategies bundling arthroscopy systems with disposable instrument commitments.
- Sports Medicine Facilities:Dedicated centers targeting athletes and active populations with specialized cartilage repair protocols. Metropolitan United States clusters see accelerated buildout as private equity consolidates orthopedic practice assets.
- Orthopedic Clinics:Physician-owned or affiliated outpatient settings with focused musculoskeletal specialization.
- Rehabilitation Centers:Post-acute facilities managing recovery protocols following surgical intervention.
Hospitals dominate procurement volume; sports medicine facilities gain share fastest.
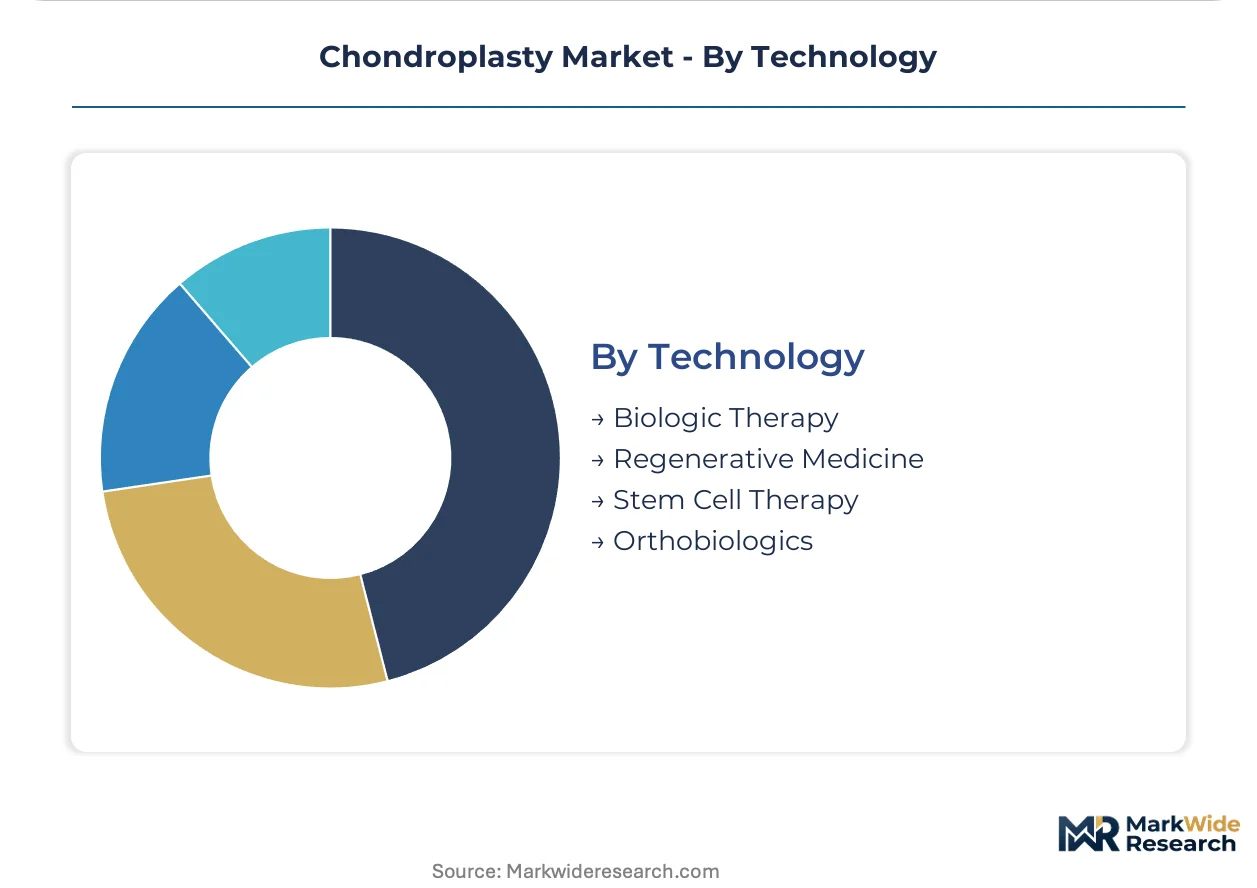
Technology:
Biologic sophistication tiering separates commodity interventions from premium regenerative platforms with distinct regulatory pathways.
- Orthobiologics:Scaffold-based and cell-supportive matrices including collagen and hyaluronic acid derivatives. Supply concentrates among three European porcine-derived scaffold manufacturers, exposing producers to veterinary disease outbreak disruptions and import inspection bottlenecks.
- Stem Cell Therapy:Mesenchymal stromal cell applications attracting significant clinical trial investment despite lingering FDA and CMS uncertainty on coverage determination. Academic medical centers in Germany and South Korea lead adoption for focal femoral condyle defects.
- Biologic Therapy:Growth factor and cytokine-based interventions modulating cartilage repair biology.
- Regenerative Medicine:Broad category encompassing tissue engineering and cell-based approaches under evolving regulatory frameworks.
Orthobiologics command current revenue concentration; stem cell therapy carries the steepest expansion trajectory contingent on payer evidence maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains more favorable reimbursement for matrix-assisted autologous chondrocyte implantation than the United States, while South Korea's academic medical centers adopt these platforms at replacement rates exceeding 60% for focal femoral condyle defects.
United States
Medicare's Ambulatory Surgical Center payment reforms incentivize same-day chondroplasty procedures, driving facility investment in arthroscopic suites across health systems. FDA's Regenerative Medicine Advanced Therapy designation pathway accelerates cell-based product development timelines. Hospital purchasing committees in Florida and Texas health systems are consolidating orthopedic vendor contracts, bundling arthroscopy visualization systems with disposable instrument commitments.
Germany
Academic medical centers absorb disproportionate volume of autologous chondrocyte implantation as the national health system maintains favorable reimbursement for matrix-assisted variants. EU MDR Annex XVI expansion reclassifies certain cartilage repair scaffolds as Class III devices, imposing clinical evidence requirements previously reserved for permanent implants. Swiss and Dutch notified bodies are applying enhanced scrutiny to resorbable matrix durability claims, extending review timelines by 8-14 months for German manufacturers.
South Korea
Academic medical centers lead adoption of matrix-assisted autologous chondrocyte implantation for focal femoral condyle defects, with replacement rates exceeding 60% from first-generation periosteal patch techniques. MFDS regulates chondroplasty devices and biologics under distinct premarket pathways. Seoul metropolitan clusters see accelerated buildout of sports medicine facilities as private equity consolidates orthopedic practice assets targeting active aging populations.
India
Underdeveloped cartilage repair infrastructure in tier-2 Indian cities creates first-mover positioning for arthroscopy equipment leasing models paired with surgeon training programs. CDSCO oversight applies to imported orthopedic devices and biologics entering the market. Maharashtra and Karnataka are witnessing initial penetration of dedicated sports medicine centers, though reimbursement frameworks for outpatient orthopedic procedures remain less developed than in mature markets.
Switzerland
Swissmedic applies enhanced scrutiny to resorbable matrix durability claims for cartilage repair scaffolds, extending review timelines in coordination with Dutch notified bodies. ISO 13485 quality management standards impose compliance burdens on manufacturers seeking multi-jurisdictional market access. Basel and Zurich clusters host specialized orthopedic reconstruction expertise extending into cartilage repair workflows, with proximity to European porcine-derived scaffold suppliers.
Chondroplasty Market Vendor Landscape
Top-tier vendors anchor integrated sports medicine portfolios, while mid-tier specialists compete through sustained R&D investment in minimally invasive delivery platforms. The vendor base stratifies across three archetypes: diversified orthopedic conglomerates with reconstruction expertise, pure-play arthroscopy device manufacturers, and emerging cell therapy platform developers. Dominant competitive moves include strategic partnerships between mechanical instrument suppliers and biologic scaffold producers, plus geographic expansion through distributor arrangements in underpenetrated ambulatory surgery center markets.
Among diversified orthopedic conglomerates, Smith & Nephew, Medtronic, and Zimmer Biomet occupy positions representing distinct strategic archetypes. Smith & Nephew exemplifies premium-tier positioning anchored across hospital and ambulatory settings. Medtronic represents sustained R&D investment archetypes focused on minimally invasive delivery platforms. Zimmer Biomet sits within specialized orthopedic reconstruction expertise extending into cartilage repair workflows. These three entities collectively illustrate how market participants calibrate portfolio investments between proven mechanical solutions and higher-risk biologic innovations.
| Leading Market Players |
|---|
| Smith & Nephew |
| Medtronic |
| Zimmer Biomet |
| B. Braun |
| Exactech |
| DePuy Synthes |
| Arthrex |
| CONMED Corporation |
| Stryker |
| Others |
Supply Flow & Price Mechanics
GMP-certified cell processing technicians in Germany and South Korea command wage premiums that widen spreads between matrix-assisted autologous chondrocyte implantation and commodity microfracture procedures. Labor-cost differentials in cell therapy manufacturing propagate through pricing tiers, with European cleanroom validation timelines extending cost absorption periods versus United States ambulatory surgical center throughput models.
Pricing Analysis
Bundled arthroscopy system contracts dominate hospital purchasing committee negotiations, while unbundled biologic scaffold pricing faces prior authorization friction. Three-tier pricing structure across premium cellular therapies, standard orthobiologic matrices, and economy mechanical debridement reflects FDA pathway complexity and CMS reimbursement tiering. Pricing pressure stems from payer cost compression on regenerative interventions, with commercial insurers imposing 45-90 day authorization delays. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers absorb premium cellular therapy costs through research budgets.
Supply Chain Analysis
Reverse logistics for explanted cartilage biopsy specimens and cryopreserved allograft returns anchor cold-chain complexity in this sector. Manufacturing concentrates in Germany, South Korea, and Switzerland for GMP-compliant cell expansion facilities; porcine-derived collagen matrices source primarily from three European suppliers. Raw material dependencies include veterinary-grade porcine tissue, hyaluronic acid derivatives, and cryopreservation media. Single-source vulnerability in scaffold supply exposes producers to veterinary disease outbreak disruptions. Distribution runs through orthopedic distributor networks and direct hospital contracts for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FDA's Regenerative Medicine Advanced Therapy designation accelerating cell-based product development timelines and expanding addressable premium segments.
For Market Incumbents: Cement integrated sports medicine portfolio positioning by anchoring arthroscopy visualization system contracts with disposable instrument bundling. Deepen backward integration into porcine-derived scaffold manufacturing to neutralize European supply concentration risk. Prioritize GMP facility capacity expansion in Germany and South Korea to capture matrix-assisted autologous chondrocyte implantation volume growth. For New Entrants and Emerging Players: Begin with ambulatory surgery center equipment leasing models in tier-2 Indian cities, where cartilage repair infrastructure remains underdeveloped and first-mover positioning is attainable. Target sports medicine facility buildouts in United States metropolitan clusters as private equity consolidates orthopedic practice assets. Pursue surgeon training program partnerships as primary go-to-market channel. For Investors and Strategic Acquirers: Orthopedic conglomerates with reconstruction expertise represent the most active acquirer category in this space, seeking cell therapy platform developers to fill biologic portfolio gaps. Long-term viability hinges on payer evidence maturation for regenerative therapies over the coming decade. Acquisition target archetypes include GMP-certified cell processing facilities and proprietary scaffold technologies. Monitor CMS national coverage determinations for cell-based interventions as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy Development | CMS outpatient procedure coding alignment secures ambulatory surgical center payment eligibility. |
| GMP Manufacturing Scale-Up | Cleanroom infrastructure investment in Germany and South Korea accelerates autologous chondrocyte platform commercialization. |
| Hospital System Partnership | Integrated delivery network bundling contracts displace standalone device suppliers in Florida and Texas. |
| Regulatory Pathway Navigation | FDA Regenerative Medicine Advanced Therapy designation compresses cell-based product development timelines. |
| Surgeon Training Program | Arthroscopy fellowship pipeline expansion addresses specialist shortage extending patient wait times. |
Methodological Framework
Coverage spans the United States, Germany, South Korea, India, and Switzerland, with primary inputs from each market cluster. The analysis combines structured interviews with orthopedic surgeons, hospital purchasing committee members, GPO contracts managers, and cell therapy manufacturing executives with secondary validation from FDA 510(k) and BLA filings, CMS Medicare payment data, hospital procurement databases, and EU MDR notified body guidance documents. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchor market sizing.
Granularity extends to procedure-level modeling across microfracture, autologous chondrocyte implantation, and osteochondral graft interventions, with parallel technology-tier segmentation for mechanical, orthobiologic, and stem cell platforms. CAGRs derive from logistic growth curve fitting applied to reimbursement-capped adoption scenarios. Forecast inputs incorporate CMS Ambulatory Surgical Center payment reform implementation trajectories and EU MDR Annex XVI reclassification timelines for resorbable scaffolds.
Several conditions sit outside the modeled scope, including veterinary disease outbreaks disrupting porcine-derived matrix supply, abrupt CMS coverage determinations for cell therapies, and orthopedic fellowship training program expansion rates. Forecasts reflect assumptions regarding payer prior authorization burden stability and GMP facility validation timeline consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
Knee Cartilage Repair Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
Kyphoscoliosis Treatment Market
Orthopedic Devices
Bone Void Fillers Market
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
China Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Cartilage Repair Market
Orthopedic Devices
Veterinary Orthopedic Drills Market
Orthopedic Devices
Vertebroplasty Needles Market
Orthopedic Devices
Global Animal Ortho-Prosthetics Market