
 North America Spinal Surgery Market | 2026-2036
North America Spinal Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Spinal Surgery Market Analytics
Spine surgeon workforce shortages across the United States and Canada is bifurcating market access between metropolitan hospital systems and rural orthopedic practices. Medtronic plc leverages its integrated navigation and implant portfolio to dominate high-complexity fusion procedures. Stryker Corporation anchors its position through sustained R&D investment in robotic-assisted spinal platforms. NuVasive specializes in lateral access techniques that differentiate its offering in minimally invasive correction surgeries.
Spinal surgery encompasses operative interventions on the vertebral column, spinal cord, and nerve roots using metallic implants, polyetheretherketone cages, bone graft substitutes, and precision-milled instruments to restore structural integrity, decompress neural elements, or correct deformity. The primary purpose spans treatment of degenerative disc disease, traumatic fractures, scoliosis, and spinal stenosis in acute and chronic patient populations. Implants and biologics command the deepest margin pools as surgeon preference and fusion biology drive premium pricing. Minimally invasive technology represents the fastest-expanding application segment as hospital systems prioritize reduced length-of-stay metrics. Robotic surgery platforms remain concentrated among academic medical centers with capital budgets sufficient to absorb acquisition and training costs.
FDA 510(k) premarket notification requirements shape product development timelines and clinical evidence standards for implantable spinal devices across the United States. Health Canada's Medical Devices Bureau imposes parallel but distinct quality system requirements that manufacturers must satisfy for Canadian market entry. The US Centers for Medicare & Medicaid Services reimbursement determinations directly influence hospital purchasing decisions for advanced spinal technologies. Stakeholders must monitor evolving FDA guidance on spinal biologics and real-world evidence requirements to anticipate competitive positioning shifts.
Market Dynamics
The migration of spinal procedures from inpatient hospitals to ambulatory surgical centers is compressing reimbursement rates and forcing implant manufacturers to reconfigure their distribution economics around lower-acuity sites of care.
Growth Catalysts
- FDA 510(k) Clearance Pathway:The streamlined premarket notification process accelerates commercialization timelines for spinal implants and biologics, enabling faster patient access to novel fusion technologies.
- Sun Belt Demographics:Population aging across Florida, Arizona, and Texas concentrates surgical demand where private payor density supports higher procedural volumes and premium technology adoption.
- Minimally Invasive Techniques:Lateral access and percutaneous approaches reduce length-of-stay metrics that hospital systems prioritize under value-based care contracts.
Market Restraints
- Titanium Alloy Input Volatility:Spinal implant manufacturers face margin pressure from fluctuating raw material costs for rods, screws, and interbody cages.
- Surgeon Workforce Concentration:Fellowship-trained spine specialists cluster in metropolitan academic centers, leaving rural markets dependent on general orthopedic practitioners with limited complex case exposure.
- Health Canada Parallel Requirements:Medical Devices Bureau quality system mandates create duplicative compliance burdens for manufacturers seeking unified North American market access.
Strategic Opportunities
- Robotic Platform Expansion:Academic medical centers with sufficient capital budgets represent untapped installation base for navigation-assisted spinal systems beyond current early adopters.
- CMS Innovation Center Models:Alternative payment demonstrations for spinal episodes create financial incentives for hospitals to adopt technologies that reduce readmission risk.
- Biologics-Implant Convergence:Synthetic bone graft substitutes combined with PEEK cages offer differentiated positioning in fusion procedures where autograft limitations persist.
Industry Challenges
- Navigation System Integration:Robotic platforms require substantial IT infrastructure upgrades and staff retraining that disrupts existing surgical workflows.
- Real-World Evidence Generation:FDA guidance evolution demands expanded post-market surveillance capabilities that strain smaller manufacturers' regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Spinal Surgery Market |
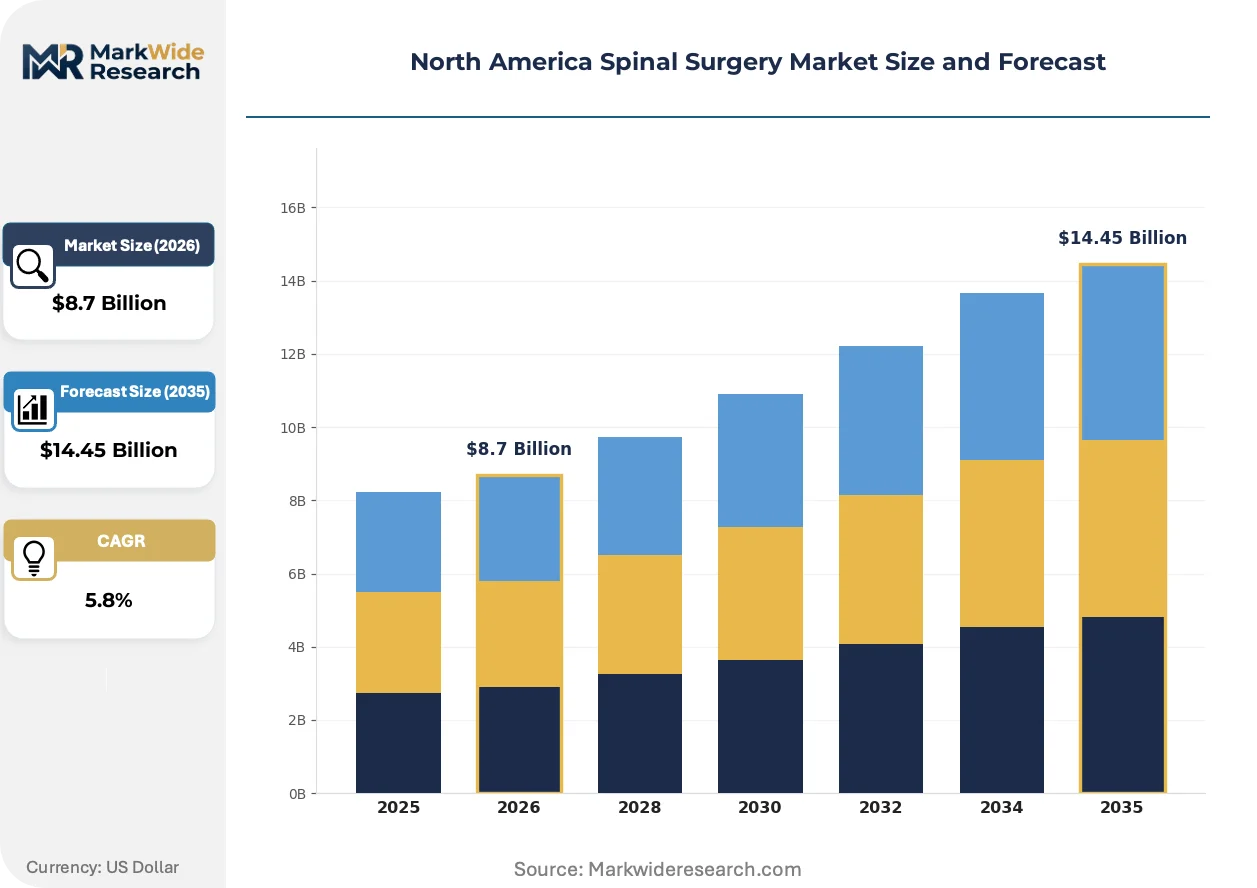
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Surgical Instruments, Biologics, Diagnostic Tools End User: Hospitals, Surgical Centers, Rehabilitation Clinics, Orthopedic Practices Application: Decompression, Fusion, Correction, Disc Replacement Technology: Minimally Invasive, Robotic Surgery, Imaging, Navigation |
| Companies Covered | Medtronic plc, Stryker Corporation, Johnson & Johnson, Globus Medical, ZimVie Inc, DePuy Synthes, NuVasive, Zimmer Biomet Holdings, Orthofix Medical, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Spinal Surgery Market Evolving Landscape
Digital surgical planning and intraoperative navigation are dissolving the traditional boundary between preoperative imaging and real-time implant placement, compressing the learning curve for complex deformity correction.
Patient-specific implants manufactured through additive metal printing are fragmenting the standardized implant market. Academic medical centers in California and Massachusetts are adopting these technologies for revision fusion cases with anomalous anatomy. The technology is fragmenting procurement patterns as hospitals negotiate direct manufacturing partnerships rather than distributor-mediated supply contracts.
Health Canada's Medical Devices Bureau is tightening quality system requirements for spinal biologics, extending review timelines for products containing recombinant proteins. Manufacturers are responding by segregating Canadian regulatory submissions from US 510(k) pathways, creating divergent product launch sequences across the border. The policy shift most affects bone graft substitute portfolios where biological activity claims trigger enhanced scrutiny.
Hospital purchasing committees are unbundling implant costs from procedural reimbursement, forcing device representatives to justify premium pricing through discrete outcome metrics. Integrated delivery networks in Texas and Florida are consolidating vendor contracts to three or fewer suppliers per implant category. This concentration is most visible in degenerative disc disease procedures where commoditized interbody cages dominate volume.
North America Spinal Surgery Market Segmentation
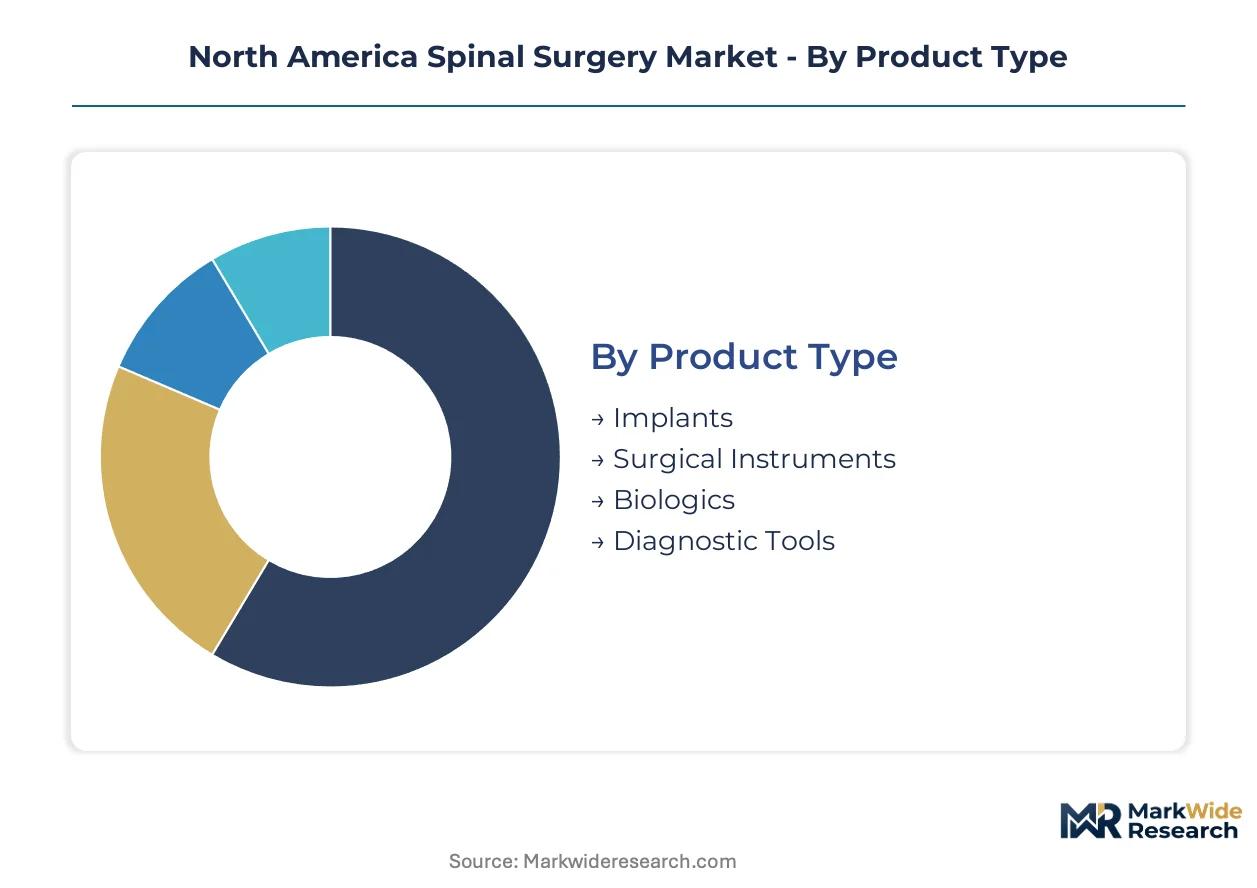
Segmentation in spinal surgery reveals how reimbursement compression and site-of-care migration are fragmenting demand across product categories and delivery settings. Understanding these divisions exposes where manufacturers must reconfigure distribution economics and where providers face the steepest technology adoption hurdles.
Product Type:
Implants face the most acute substitution pressure as hospital purchasing committees unbundle hardware costs from procedural reimbursement and consolidate vendor contracts to three or fewer suppliers per category.
- Implants:Titanium alloy rods, polyetheretherketone cages, and pedicle screw systems constitute the hardware backbone of fusion procedures. Demand concentrates in Texas and Florida integrated delivery networks where private payor density supports premium technology adoption despite unbundling pressures.
- Biologics:Bone graft substitutes and recombinant protein products command differentiated positioning where autograft harvest limitations persist. Health Canada's Medical Devices Bureau is extending review timelines for biological activity claims, forcing manufacturers to segregate Canadian submissions from FDA 510(k) pathways.
- Surgical Instruments:Precision-milled retractors, drills, and distractors serve procedural execution across all surgical sites.
- Diagnostic Tools:Intraoperative neuromonitoring and imaging systems enable real-time neural element assessment.
Implants anchor the volume base while biologics gains share at the steepest rate as surgeons seek alternatives to autograft morbidity.
End User:
Cost tier stratification dominates this dimension as capital-intensive robotic platforms remain inaccessible to lower-acuity settings while basic instrumentation penetrates broadly.
- Hospitals:Academic medical centers in California and Massachusetts absorb capital budgets for navigation-assisted systems and patient-specific additive manufacturing partnerships. These institutions handle complex deformity correction and revision fusion cases that justify infrastructure investment.
- Surgical Centers:Ambulatory facilities across the Sun Belt are expanding spinal procedure volumes under value-based care contracts prioritizing reduced length-of-stay metrics. CMS Innovation Center alternative payment demonstrations create financial incentives for technologies that reduce readmission risk.
- Rehabilitation Clinics:Post-acute facilities manage recovery protocols following operative intervention.
- Orthopedic Practices:Rural general practitioners with limited fellowship training handle degenerative cases using conventional approaches.
Hospitals retain the highest-complexity case concentration while surgical centers capture volume growth fastest as migration from inpatient settings accelerates.
Application:
Procedure maturity varies widely across this dimension, with established techniques facing commoditization pressure while emerging approaches require substantial surgeon retraining.
- Fusion:Arthrodesis procedures using interbody cages and posterior instrumentation represent the established revenue base. Degenerative disc disease applications dominate procedural volume, though commoditized cage pricing forces manufacturers to justify premiums through discrete outcome metrics.
- Decompression:Laminectomy and discectomy procedures relieve neural element pressure in spinal stenosis patients. Demand concentrates among aging demographics in Arizona and Florida where stenosis prevalence drives surgical consultation rates.
- Correction:Deformity procedures for scoliosis and kyphosis require specialized training and navigation assistance.
- Disc Replacement:Motion-preserving arthroplasty offers alternatives to fusion in select cervical and lumbar applications.
Fusion procedures anchor the volume base while correction applications expand most quickly as navigation technology compresses the learning curve for complex deformity surgery.
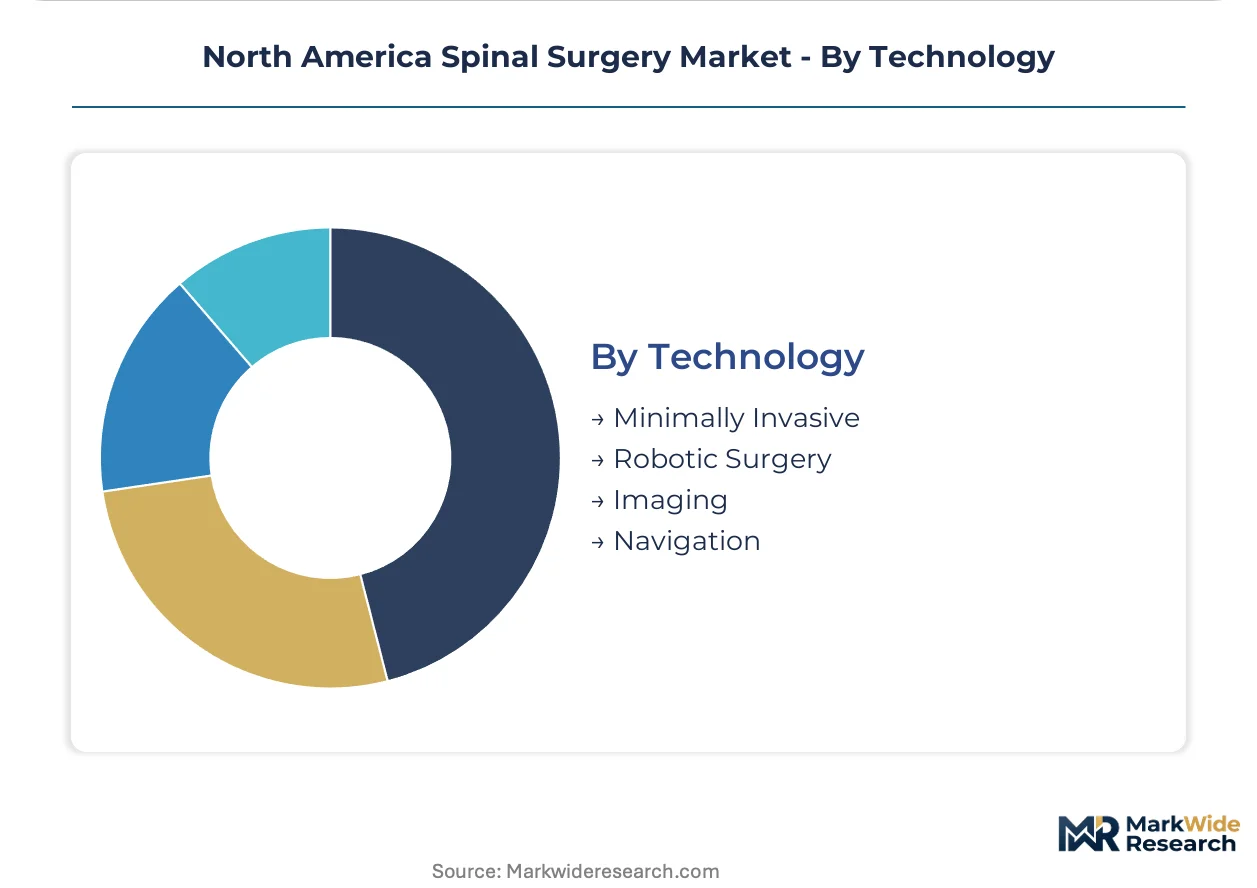
Technology:
Capital requirements and IT infrastructure demands create sharp adoption boundaries between technologies that penetrate broadly versus those confined to elite institutions.
- Minimally Invasive:Lateral access and percutaneous approaches reduce tissue disruption and accelerate discharge timelines. Hospital systems under value-based contracts prioritize these techniques for their length-of-stay impact across degenerative disc disease and stenosis populations.
- Robotic Surgery:Navigation-assisted platforms require substantial capital outlay and staff retraining that disrupts existing surgical workflows. Installation concentrates among academic medical centers with sufficient budgets to absorb acquisition costs and fellowship-trained specialists to exploit precision capabilities.
- Imaging:Intraoperative fluoroscopy and MRI guidance enable real-time anatomical visualization.
- Navigation:Computer-assisted trajectory planning integrates preoperative imaging with implant placement execution.
Minimally invasive techniques anchor the volume base while robotic surgery climbs the fastest as early adopter institutions demonstrate outcome advantages that justify capital commitment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's 510(k) clearance pathway anchors commercialization timelines across the dominant United States market, while Health Canada's Medical Devices Bureau imposes parallel compliance burdens for unified North American access. The Sun Belt states concentrate procedural demand where aging demographics intersect with private payor density.
United States
The Sun Belt corridor spanning Florida, Arizona, and Texas drives procedural volume through Medicare Advantage penetration and retiree migration patterns. CMS Innovation Center alternative payment demonstrations for spinal episodes reshape hospital technology procurement incentives. Academic medical centers in California and Massachusetts absorb capital budgets for navigation-assisted systems and patient-specific additive manufacturing partnerships.
Canada
Health Canada's Medical Devices Bureau extends review timelines for spinal biologics containing recombinant proteins, forcing manufacturers to segregate Canadian submissions from FDA 510(k) pathways. Provincial health authorities in Ontario and Quebec negotiate provincial formularies that constrain premium implant adoption. Toronto and Vancouver anchor surgical training capacity, concentrating fellowship-trained specialists in metropolitan hospital systems while rural markets depend on general orthopedic practitioners.
Mexico
Private hospital chains in Mexico City and Monterrey attract medical tourism for spinal fusion procedures, leveraging cost differentials against US reimbursement rates. COFEPRIS regulatory alignment with FDA standards accelerates product registration for manufacturers seeking nearshoring advantages. Guadalajara's medical device manufacturing corridor supplies precision-milled instrumentation to North American distributors.
North America Spinal Surgery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum controlling navigation platforms and comprehensive implant portfolios while mid-cap players occupy defined technique niches. The market structure rewards scale in regulatory affairs and health economics evidence generation. Two strategic archetypes dominate: diversified medtech conglomerates with spine divisions, and pure-play spine specialists with focused lateral access or deformity correction positioning. Competitive moves concentrate on robotic platform installations at academic medical centers and ambulatory surgical center distribution reconfiguration.
Among diversified medtech conglomerates, Medtronic plc and Stryker Corporation exemplify the integrated leader archetype through comprehensive navigation and implant portfolios. NuVasive occupies a distinct position within the pure-play specialist tier, representing lateral access technique differentiation. These three entities anchor competitive dynamics across high-complexity fusion procedures, robotic-assisted platforms, and minimally invasive correction surgeries respectively.
| Leading Market Players |
|---|
| Medtronic plc |
| Stryker Corporation |
| Johnson & Johnson |
| Globus Medical |
| ZimVie Inc |
| DePuy Synthes |
| NuVasive |
| Zimmer Biomet Holdings |
| Orthofix Medical |
| Others |
Value Network & Pricing Analysis
PEEK cage substitution for titanium interbody devices simultaneously shifts procurement toward polymer compounders in Germany and the United States while compressing per-unit hardware economics across ambulatory surgical center contracts. This material transition redraws supplier geography and forces manufacturers to recalibrate margin structures around biologics-implant bundles rather than standalone metal hardware.
Pricing Analysis
Price spreads between academic medical centers in California and ambulatory surgical centers in Texas exceed threefold for identical pedicle screw systems, reflecting divergent procurement scale and GPO negotiation leverage. Three-tier pricing structure across premium navigation-compatible, standard modular, and economy basic fixation levels stratifies the market, with FDA 510(k) clearance tier and robotic system compatibility serving as primary differentiation drivers. Cost compression in economy tiers is intensifying because integrated delivery networks in Florida and Arizona are consolidating vendor contracts to single-source arrangements. Ambulatory surgical centers exhibit the highest price sensitivity due to fixed-fee reimbursement constraints, while academic medical centers with dedicated capital budgets demonstrate lowest sensitivity for navigation platform acquisitions.
Supply Chain Analysis
Germany and the United States anchor precision polymer compounding for PEEK interbody cages, while China and Switzerland supply titanium alloy rod and screw forgings to North American implant finishers. Raw material dependencies center on medical-grade PEEK resin, Ti-6Al-4V ELI titanium billet, and recombinant human bone morphogenetic protein-2 for biologics portfolios. Single-source vulnerability concentrates in rhBMP-2 active pharmaceutical ingredient supply, where one contract manufacturer serves multiple spinal biologics brands. Distribution runs through distributor-mediated hospital sales representatives for capital equipment, with direct-to-facility logistics for disposable implants and biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent implant manufacturers face sustained substitution pressure from patient-specific additive manufacturing partnerships at elite academic centers, requiring defensive repositioning around outcome-guaranteed contracting and biologics-implant convergence.
For Market Incumbents: Fortify ambulatory surgical center distribution economics through inventory consignment programs and disposable instrument kits that reduce capital barriers for lower-acuity sites. Deepen backward integration into titanium alloy forging capacity to offset raw material volatility from Chinese and Swiss suppliers. Prioritize FDA 510(k) clearance accumulation for navigation-compatible implant families that command premium positioning in academic center RFPs. For New Entrants and Emerging Players: Lead with lateral access retractor systems and percutaneous fixation devices targeting the fastest-expanding ambulatory surgical center segment in Texas and Florida Sun Belt markets. Exploit surgeon workforce concentration gaps in rural orthopedic practices across the US Mountain West and Canadian Prairie provinces where generalists seek simplified procedural solutions. Pursue direct-to-facility digital marketing and limited sales representative models to circumvent entrenched distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play spine specialists with differentiated access technique portfolios and established ambulatory surgical center case volume. Long-term viability across the projection horizon hinges on regulatory clearance velocity and reimbursement strategy execution rather than manufacturing scale alone. Watch for Health Canada Medical Devices Bureau guidance shifts on spinal biologics as an inflection indicator for North American market access complexity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notification compresses commercialization timelines for novel fusion technologies. |
| Ambulatory Surgical Center Partnership | Direct contracting with Texas and Florida ASCs captures migration from inpatient procedural volumes. |
| Biologics-Implant Bundle Development | Synthetic bone graft substitutes combined with PEEK cages differentiate against commodity hardware. |
| Robotic Platform Installation | Capital equipment placement at academic medical centers locks in recurring implant pull-through. |
| Health Canada Parallel Submission | Early engagement with Medical Devices Bureau quality system requirements prevents launch sequence divergence. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with spine surgeons, hospital purchasing committee chairs, biomedical engineers at integrated delivery networks, GPO contracts managers, and regulatory affairs directors at implant manufacturers. Secondary validation drew from FDA 510(k) premarket notification databases, Health Canada Medical Devices Bureau submission records, CMS Medicare reimbursement determinations, hospital procurement databases, and GPO contract disclosure filings. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue segmentation across the analysis window.
Across the modeling period, analytical framework integrated product type, end user facility tier, application complexity, and technology adoption stage as core segmentation dimensions. CAGRs were derived from regression-based trending of historical procedural volumes adjusted for demographic shift projections and reimbursement policy evolution. Forecast inputs incorporated Sun Belt population aging trajectories, CMS Innovation Center alternative payment demonstration expansion, and robotic platform installation base growth at academic medical centers.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and Health Canada Medical Devices Bureau quality system requirements; material policy shifts toward enhanced clinical evidence standards or extended biologics review timelines would require re-modeling. Specific risks include titanium alloy commodity price volatility, fellowship-trained surgeon workforce expansion constraints, and ambulatory surgical center reimbursement compression under Medicare Advantage penetration. Recalibration cycles align with material shifts in CMS payment policy, FDA guidance evolution, and Health Canada regulatory posture.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Brazil Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Extremity Market
Orthopedic Devices
Orthopedic Fracture Repairing Implants for Osteoporosis Market
Orthopedic Devices
Global Spinal Fusion Devices Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Market
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Japan Spinal Surgery Devices Market
Orthopedic Devices
Adult Orthopedic Insole Market
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Spinal Implants and Surgical Devices Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Global Total Ankle Replacement Market