
 Humeral Implant Market | 2026-2036
Humeral Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Humeral Implant Market Intelligence
CE marking under the EU Medical Device Regulation is redrawing competitive access across European distribution channels. Zimmer Biomet leverages its established notified body relationships to sustain portfolio breadth across stemmed and reverse shoulder platforms. Stryker anchors its position through integrated trauma-to-arthroplasty workflow systems that dominate hospital purchasing committees. DePuy Synthes competes on cobalt chromium forging expertise that extends its revision surgery product lines.
A humeral implant is a prosthetic device designed to replace the proximal humerus or resurface its articular head, typically manufactured from titanium alloys or cobalt chromium with polyethylene bearing surfaces, and engineered to restore glenohumeral joint kinematics following fracture, arthritis, or oncologic resection. Reverse shoulder implants now command the fastest expansion within product type segmentation as aging populations present with rotator cuff-deficient arthropathy. Titanium alloys lead material selection due to osseointegration performance, though ceramic heads are gaining traction in younger, higher-activity patients where polyethylene wear debris drives revision risk.
FDA 510(k) clearance pathways and the EU MDR framework jointly shape product development timelines and clinical evidence requirements for humeral implant manufacturers. ISO 5832 material standards and ASTM F136 specifications govern titanium alloy biocompatibility and mechanical fatigue thresholds that determine regulatory submission success. Stakeholders must monitor how FDA's evolving orthopedic advisory panel scrutiny of reverse shoulder indications reshapes predicate device strategies and clinical trial investment priorities.
Market Dynamics
Reverse shoulder arthroplasty is fragmenting the traditional stemmed implant hierarchy as rotator cuff-deficient patients now dominate surgical queues across ambulatory surgical centers and specialty hospitals.
Growth Catalysts
- EU MDR recertification waves:The compressed approval timeline is forcing smaller competitors to exit, concentrating shelf space for compliant portfolios in German and French distribution channels.
- Titanium alloy osseointegration:ASTM F136-compliant forged stems now anchor primary fixation in revision-heavy patient populations, extending implant survival curves.
- Ambulatory surgical center expansion:United States outpatient facilities are adding dedicated orthopedic suites that prioritize same-day discharge protocols.
Market Restraints
- Cobalt chromium price volatility:Mining concentration in the Democratic Republic of Congo creates input cost instability for forged humeral head production.
- FDA 510(k) predicate erosion:The orthopedic advisory panel's heightened scrutiny of reverse shoulder indications is lengthening clearance timelines for novel designs.
- Ceramic bearing substitution:Younger, high-activity patients are migrating toward ceramic-on-polyethylene constructs that reduce polyethylene wear debris.
Strategic Opportunities
- Patient-specific instrumentation:3D-printed surgical guides paired with preoperative planning software are compressing operative time and cementless fixation failure rates.
- Japan's aging surgical population:METI reimbursement adjustments for reverse shoulder arthroplasty are expanding addressable volumes in rotator cuff-deficient cohorts.
- Direct-to-hospital distribution:Manufacturers are bypassing traditional implant distributors to capture margin through owned sales forces in high-volume ASC networks.
Industry Challenges
- Notified body capacity constraints:EU MDR technical documentation reviews now stretch 18-24 months, freezing product line extensions.
- Revision surgery complexity:Explant analysis and bone defect reconstruction require specialized training that general orthopedic surgeons lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Humeral Implant Market |
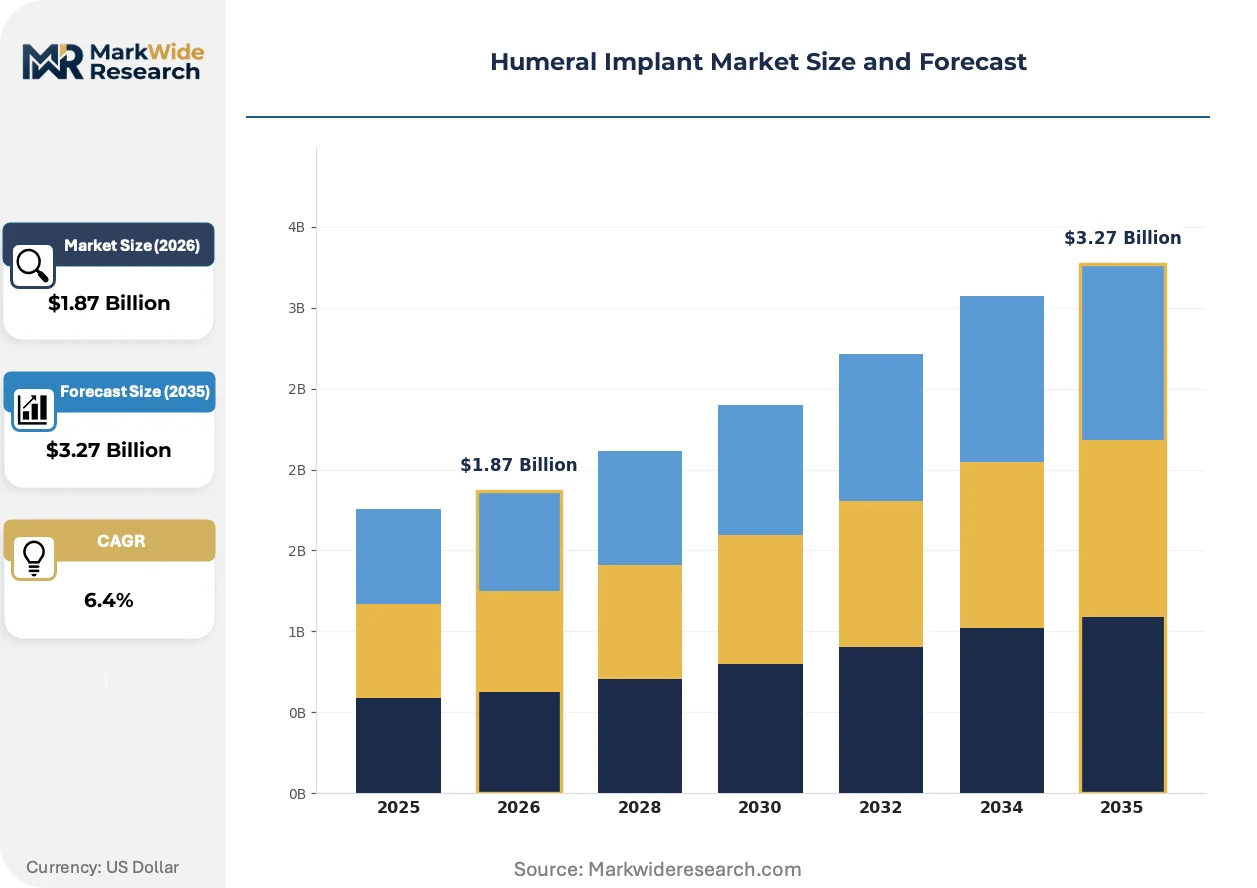
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $3.27 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stemmed Implants, Stemless Implants, Modular Implants, Reverse Shoulder Implants Material: Titanium Alloys, Cobalt Chromium, Polyethylene, Ceramic Application: Fracture Fixation, Shoulder Arthroplasty, Revision Surgery, Tumor Resection End User: Orthopedic Clinics, Specialty Hospitals, Ambulatory Surgical Centers, Rehabilitation Centers |
| Companies Covered | Zimmer Biomet, Stryker, DePuy Synthes, Exactech, Smith & Nephew, Arthrex, Wright Medical Group, B. Braun, DJO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Humeral Implant Market Strategic Shifts & Innovations
Digital surgical planning and bearing surface engineering are converging to compress operative variability and extend implant longevity in younger patient cohorts.
Modular humeral stem platforms are fragmenting the monoblock legacy installed base. High-volume shoulder surgeons in United States academic medical centers are adopting convertible stem designs that accommodate intraoperative conversion from anatomic to reverse configuration. This flexibility is compressing hospital inventory carrying costs while enabling same-day implant customization.
CE marking under EU MDR is redrawing competitive access across European distribution channels. The notified body consolidation from twenty-plus entities to under ten viable auditors has created bottlenecks that favor incumbents with established technical documentation libraries. Smaller manufacturers without legacy MDD certificates are exiting or partnering to retain market presence.
ASC purchasing committees are consolidating supplier relationships around bundled procedural contracts. United States ambulatory surgical centers now negotiate implant-plus-instrumentation-plus-disposables packages that displace traditional fee-per-item pricing. This compression is visible most acutely in Florida and Texas markets where ASC joint venture models dominate outpatient orthopedic volume.
Humeral Implant Market Segmentation
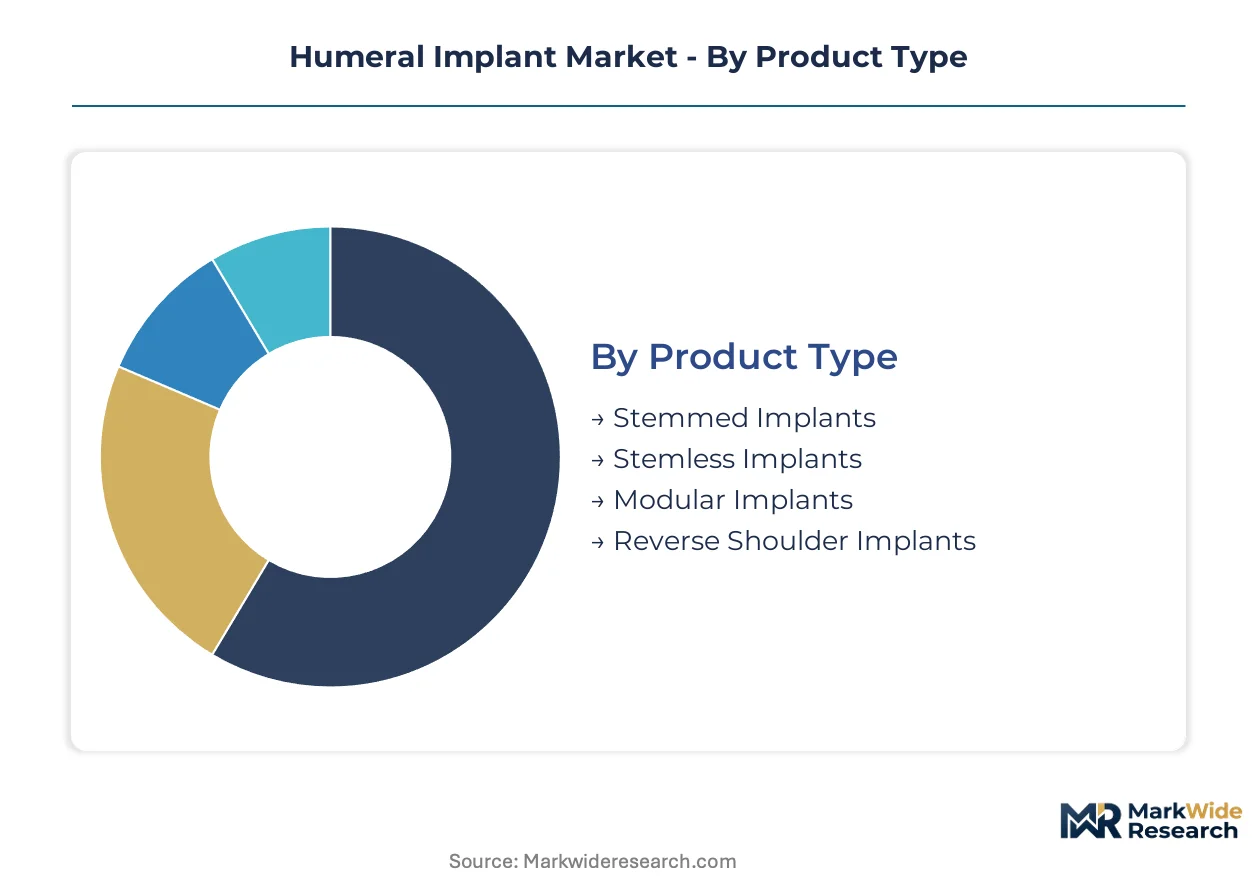
Humeral implant segmentation reveals how surgical technique evolution and patient demographic shifts are redistributing revenue across product architectures. Each dimension carries distinct substitution pressures from bearing surface innovations, ambulatory migration, and material science advances.
Product Type:
Modular and reverse configurations face the most intense substitution pressure as convertible stem platforms displace dedicated anatomic designs in high-volume surgical centers.
- Stemmed Implants:Monoblock or modular stems with metaphyseal fixation surfaces anchor primary shoulder arthroplasty in academic medical centers. German and French specialty hospitals maintain substantial inventory for complex primary cases requiring diaphyseal engagement.
- Reverse Shoulder Implants:Glenosphere-humeral socket constructs reverse normal joint kinematics to deltoid-dependent function. United States ASC networks are expanding reverse shoulder programs fastest as rotator cuff-deficient arthropathy dominates surgical queues.
- Stemless Implants:Metaphyseal-anchoring designs preserve bone stock in younger patients. Bone-preserving fixation is gaining traction in European markets where revision surgery complexity drives conservative initial approaches.
- Modular Implants:Convertible stem platforms enable intraoperative anatomic-to-reverse conversion. Same-day customization is compressing hospital inventory carrying costs across Florida and Texas ASC joint ventures.
Stemmed implants anchor the volume base while reverse shoulder platforms gain share at the steepest rate.
Material:
Cost tier stratification separates premium bearing surfaces from commodity substrates, with ceramic commanding price multiples over standard polyethylene in high-activity patient segments.
- Titanium Alloys:ASTM F136-compliant forged titanium delivers osseointegration performance that extends implant survival in revision-heavy populations. Primary fixation demand concentrates in United States outpatient facilities prioritizing cementless fixation protocols.
- Ceramic:Alumina or zirconia heads reduce polyethylene wear debris in younger, higher-activity patients. Premium bearing substitution is accelerating in academic medical centers serving manual laborers and athletic populations.
- Cobalt Chromium:Forged CoCr heads dominate legacy installed base and revision surgery product lines. Democratic Republic of Congo mining concentration creates input cost instability for manufacturers without captive supply arrangements.
- Polyethylene:Cross-linked UHMWPE bearing surfaces articulate against metallic or ceramic heads. Wear debris generation limits application in patients under sixty or with anticipated high cyclic loading.
Cobalt chromium retains the broadest installed base while ceramic climbs the fastest among material selections.
Application:
Volume distribution across applications reflects population aging trajectories and trauma incidence patterns in target geographies.
- Shoulder Arthroplasty:Elective joint replacement for osteoarthritis and cuff tear arthropathy. United States ASC expansion is shifting arthroplasty volume away from inpatient settings.
- Fracture Fixation:Acute proximal humerus fracture management with primary or reverse arthroplasty. German trauma networks maintain dedicated shoulder fracture protocols.
- Revision Surgery:Explant analysis and bone defect reconstruction following aseptic loosening or infection. Complexity requirements limit qualified surgeon supply and concentrate volume in tertiary referral centers.
- Tumor Resection:Oncologic proximal humerus replacement with custom or modular megaprostheses. Low absolute volume but high per-procedure value supports specialized manufacturing capabilities.
Shoulder arthroplasty carries the volume weight while revision surgery commands the highest per-case value.
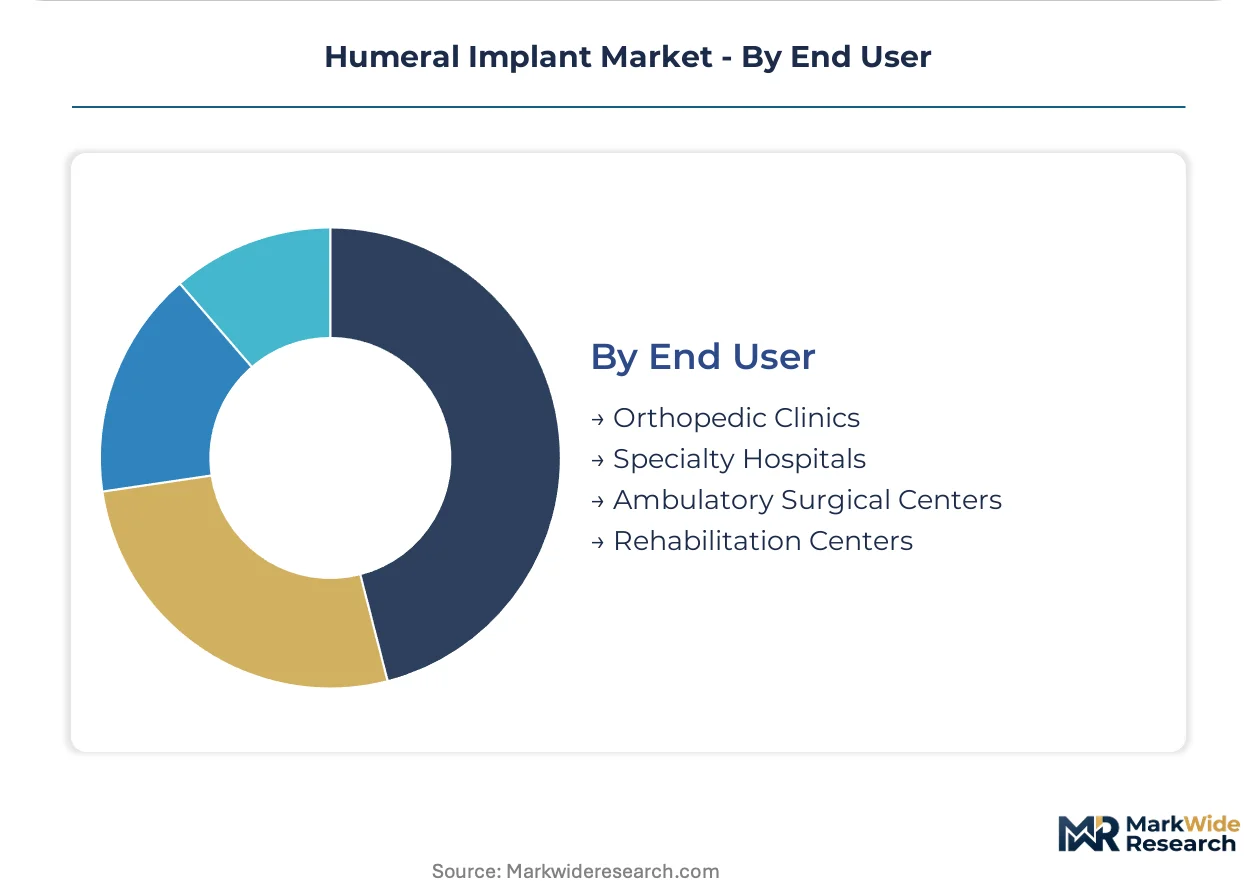
End User:
Customer type stratification tracks the ambulatory migration reshaping implant procurement and surgeon training pathways.
- Specialty Hospitals:Dedicated orthopedic facilities with comprehensive shoulder service lines. German and French programs are expanding reverse shoulder arthroplasty capacity fastest.
- Ambulatory Surgical Centers:Outpatient facilities with same-day discharge protocols. United States ASC joint ventures in Florida and Texas are consolidating supplier relationships around bundled procedural contracts.
- Orthopedic Clinics:Office-based practices with surgical privileges at affiliated hospitals. Preoperative planning and patient selection functions are migrating to clinic settings.
- Rehabilitation Centers:Post-acute facilities managing range-of-motion recovery. Implant selection influences rehabilitation protocol intensity and duration.
Specialty hospitals maintain the deepest case complexity while ambulatory surgical centers expand procedure volume most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical logistics hub underwrites Europe's implant distribution efficiency, while the US Interstate highway network enables same-day implant delivery to ambulatory surgical centers across the Sun Belt.
United States
Ambulatory surgical centers in Florida and Texas are expanding dedicated orthopedic suites fastest. FDA 510(k) clearance pathways shape product development timelines for domestic manufacturers. The Dallas-Fort Worth metroplex anchors distribution networks serving ASC joint ventures with bundled procurement contracts.
Germany
Specialty hospitals in Bavaria and North Rhine-Westphalia are scaling reverse shoulder arthroplasty programs for aging populations. EU MDR recertification through notified bodies in Berlin-Brandenburg compresses approval windows for compliant portfolios. The Stuttgart industrial cluster concentrates precision forging capabilities for cobalt chromium humeral heads.
France
Parisian academic medical centers drive adoption of convertible stem platforms enabling intraoperative configuration changes. ANSM oversight of high-risk implant classifications extends technical documentation requirements. The Lyon biomedical corridor houses notified body operations serving southern European distribution channels.
Japan
METI reimbursement adjustments for reverse shoulder arthroplasty are expanding addressable surgical volumes. PMDA marketing authorization pathways prioritize clinical evidence from domestic patient cohorts. The Osaka-Kobe manufacturing belt produces titanium alloy forgings meeting ASTM F136 specifications.
United Kingdom
NHS England procurement frameworks are consolidating supplier relationships around value-based implant contracts. MHRA post-Brexit regulatory autonomy diverges from EU MDR timelines in Northern Ireland. The Cambridge-Oxford medical technology corridor attracts patient-specific instrumentation startups.
Humeral Implant Market Key Industry Players
Listed leaders compete with private specialists across portfolio breadth and notified body access. The vendor base concentrates around three tiers: diversified orthopedics conglomerates with full shoulder platforms, mid-cap trauma specialists extending into arthroplasty, and niche instrument manufacturers. Strategic archetypes include M&A-driven portfolio expanders, regulatory compliance consolidators, and ASC-focused direct distributors. Dominant competitive moves encompass backward integration into titanium forging capacity and exclusive distribution partnerships with high-volume hospital networks.
Within the diversified conglomerate tier, Zimmer Biomet and Stryker exemplify scale-driven positioning across stemmed and reverse shoulder platforms. DePuy Synthes occupies a position anchored in cobalt chromium metallurgy expertise. Among these, Zimmer Biomet and Stryker represent the regulatory access archetype through established notified body relationships, while DePuy Synthes sits within the materials specialization vector serving revision surgery product lines.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker |
| DePuy Synthes |
| Exactech |
| Smith & Nephew |
| Arthrex |
| Wright Medical Group |
| B. Braun |
| DJO |
| Others |
Cost & Logistics Intelligence
CE marking under the EU MDR gates both supplier qualification and price differentiation simultaneously, compressing approval windows for smaller manufacturers while concentrating shelf space for compliant portfolios that command premium positioning in German and French distribution channels. ASTM F136 certification tiers separate premium titanium alloy constructs from standard cobalt chromium offerings, with notified body access becoming the decisive cost component in procurement decisions.
Pricing Analysis
Volume-discount tiering structures dominate ASC procurement negotiations, where bundled implant-plus-instrumentation-plus-disposables packages displace traditional fee-per-item pricing across Florida and Texas joint ventures. Price differentiation hinges on certification grade (EU MDR compliance tier) and vertical integration depth in titanium forging capacity. Cost compression in standard polyethylene-bearing tiers is intensifying because cobalt chromium input volatility from Democratic Republic of Congo mining concentration feeds through to forged head production. Academic medical centers show least price sensitivity, prioritizing convertible stem platforms and ceramic bearing surfaces for younger patient cohorts.
Supply Chain Analysis
Port congestion at Rotterdam and container availability constraints on Asia-Europe trade lanes are extending inbound logistics timelines for precision-forged components. Supply concentrates in Germany, Switzerland, and Japan for ASTM F136-compliant titanium alloy forgings, with cobalt chromium feedstock drawing from Democratic Republic of Congo mining operations. Single-source vulnerability in ceramic bearing supply creates structural risk for manufacturers serving high-activity patient segments. Distribution runs through hospital system GPO contracts and direct-to-ASC sales forces that bypass traditional implant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient-specific instrumentation and digital surgical planning software represent a service-attach opportunity expanding faster than hardware revenues, with preoperative planning subscriptions and 3D-printed surgical guide recurring orders capturing margin beyond implant sales.
For Market Incumbents: Fortify notified body relationships and technical documentation libraries to defend EU MDR recertification positioning against smaller competitors exiting the market. Backward integration into titanium forging capacity in the Osaka-Kobe manufacturing belt secures ASTM F136 supply continuity against Democratic Republic of Congo cobalt chromium volatility. Prioritize convertible stem platform R&D to capture intraoperative flexibility demand from high-volume ASC networks. For New Entrants and Emerging Players: Post-operative rehabilitation protocol software and remote patient monitoring services represent a service-layer gap where incumbents under-serve, creating entry pathways without capital-intensive implant manufacturing. Target Japan's rotator cuff-deficient arthropathy segment where METI reimbursement adjustments are expanding addressable volumes faster than domestic supply response. Pursue direct-to-hospital distribution partnerships with emerging ASC joint ventures in Sun Belt markets to bypass established distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across patient-specific instrumentation and 3D-printed surgical guide manufacturing, favoring acquisition targets with digital workflow capabilities over pure hardware manufacturers. Long-term viability over a multi-year window hinges on regulatory compliance infrastructure and ASC channel access rather than legacy hospital relationships. Watch FDA orthopedic advisory panel scrutiny of reverse shoulder indications as the signal for clinical trial investment requirements and predicate device strategy viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR recertification through Berlin-Brandenburg notified bodies gates German and French market access. |
| Hospital System Partnership | Exclusive distribution agreements with high-volume ASC networks in Florida and Texas consolidate procurement relationships. |
| Software Companion Development | Preoperative planning platforms and patient-specific instrumentation software attach recurring revenue to hardware sales. |
| Reimbursement Strategy | METI alignment in Japan and CMS outpatient procedure coding in the United States shape addressable surgical volumes. |
| Backward Integration | Captive titanium forging capacity in Japan and Germany insulates against Democratic Republic of Congo cobalt chromium volatility. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured interviews with shoulder surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and ASC operations directors. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS outpatient procedure data. Bottom-up surgical volume estimates and top-down manufacturer revenue triangulation anchored market sizing across product type, material, and end-user dimensions.
Across the projection horizon, the analytical framework modeled stemmed, reverse, stemless, and modular implant configurations alongside titanium alloy, ceramic, cobalt chromium, and polyethylene material selections. CAGRs were derived from surgical queue growth trajectories, ambulatory migration rates, and reimbursement policy adjustments. Forecast inputs incorporated rotator cuff-deficient arthropathy incidence curves, ASC joint venture expansion pipelines, and notified body capacity constraints.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR recertification timelines; material policy shifts in orthopedic advisory panel scrutiny or notified body consolidation would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Non-Operative Spine Care Market
Orthopedic Devices
Scoliosis Treatment Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Knee Implants Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Orthopedic Bone Cement and Casting Materials Market
Orthopedic Devices
Bone Graft Fixation System Market
Orthopedic Devices
Distal Compression Plates Market
Orthopedic Devices
Global Total Knee Replacement Market
Orthopedic Devices
Spinal Devices Market
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
China Spinal Surgery Devices Market
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
North America Kyphoplasty Market