
 South Korea Spinal Surgery Devices Market | 2026-2036
South Korea Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Spinal Surgery Devices Market Analytics
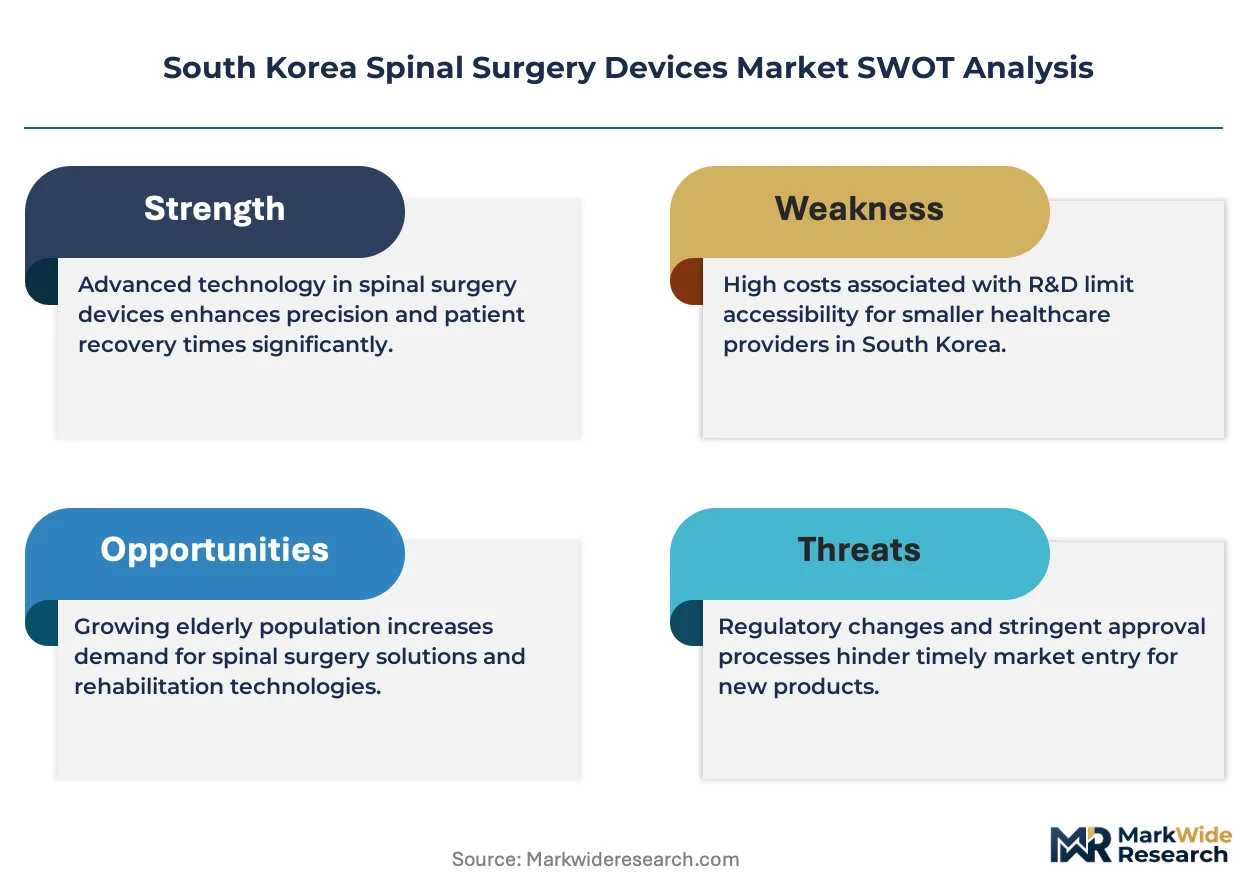
South Korean orthopedic implant manufacturers is rebalancing capacity toward robotic-assisted and minimally invasive platforms. Medtronic PLC leverages its integrated navigation and fusion portfolio to sustain premium positioning in Seoul's tertiary hospital networks. Stryker Corporation anchors its presence through specialized power tools and biologics distribution. GENOSS Co., Ltd. competes on domestic manufacturing scale and cost-efficient fixation devices for regional hospitals.
Spinal surgery devices encompass implantable hardware, biologics, and instrument systems designed to stabilize, decompress, or replace vertebral segments, typically manufactured from titanium alloys, PEEK polymers, or demineralized bone matrices for mechanical compatibility and osseointegration. These systems restore spinal alignment and neurological function following degenerative, traumatic, or neoplastic pathology. Spinal fusion devices dominate current revenue flows due to established reimbursement and surgeon familiarity, while robotic-assisted technology captures the fastest expansion trajectory as hospitals amortize capital equipment across high-volume caseloads. Fixation devices occupy mature margin pools where domestic producers challenge multinational pricing.
MFDS regulates pre-market approval, clinical evidence requirements, and post-market surveillance for spinal implants under Korea's Medical Device Act, tightening safety documentation for novel materials. The Ministry of Health and Welfare sets reimbursement fee schedules that directly determine hospital procurement budgets and technology adoption thresholds. Stakeholders must monitor MFDS guidance on real-world evidence standards and Health Insurance Review and Assessment Service reimbursement adjustments for robotic surgery codes to anticipate access and pricing dynamics.
Market Dynamics
Robotic-assisted surgical platforms are restructuring capital allocation across South Korean tertiary hospitals, compressing the traditional device procurement cycle and forcing implant manufacturers to bundle navigation software with hardware to secure multi-year service contracts.
Growth Catalysts
- MFDS Accelerated Approval Pathway:The streamlined pre-market review for robotic surgical systems reduces time-to-market by consolidating clinical evidence requirements, enabling faster hospital adoption of navigation-integrated platforms.
- Seoul-Gyeonggi Hospital Expansion:Tertiary medical centers in these provinces are adding dedicated spinal surgery wings with robotic capability, creating concentrated demand for compatible implant systems.
- PEEK Polymer Biocompatibility:Advanced polymer cages with optimized elastic modulus matching human bone are displacing titanium in select fusion procedures, driving material-level upgrade cycles.
Market Restraints
- Titanium Alloy Price Volatility:Raw material cost fluctuations for implant-grade Ti-6Al-4V constrain margin predictability for domestic fixation device producers competing on price.
- Capital Equipment Amortization Pressure:Robotic system depreciation schedules force high-volume surgical throughput requirements that smaller regional hospitals cannot sustain, limiting addressable facility base.
- Health Insurance Review and Assessment Service Reimbursement Rigidity:Fixed fee schedules for spinal fusion procedures cap hospital technology budgets, creating procurement friction for premium-priced navigation systems.
Strategic Opportunities
- Daegu-Gwangju Regional Hospital Penetration:Secondary metropolitan areas outside Seoul-Gyeonggi show underdeveloped robotic surgical capacity, offering first-mover positioning for platform-agnostic implant suppliers.
- Navigation-Implant Bundling:Convergence of pre-operative planning software with patient-specific instrumentation creates service-based revenue streams beyond hardware sales.
- MFDS Real-World Evidence Pilot:Post-market surveillance data collection requirements for novel materials create competitive differentiation for manufacturers with established clinical registries.
Industry Challenges
- Robotic Surgery Training Pipeline:The limited pool of fellowship-trained spine surgeons capable of operating navigation-integrated systems constrains effective capacity utilization of installed capital equipment.
- Legacy EMR Integration Complexity:Proprietary data formats from competing robotic platforms create interoperability friction with hospital information systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Spinal Surgery Devices Market |
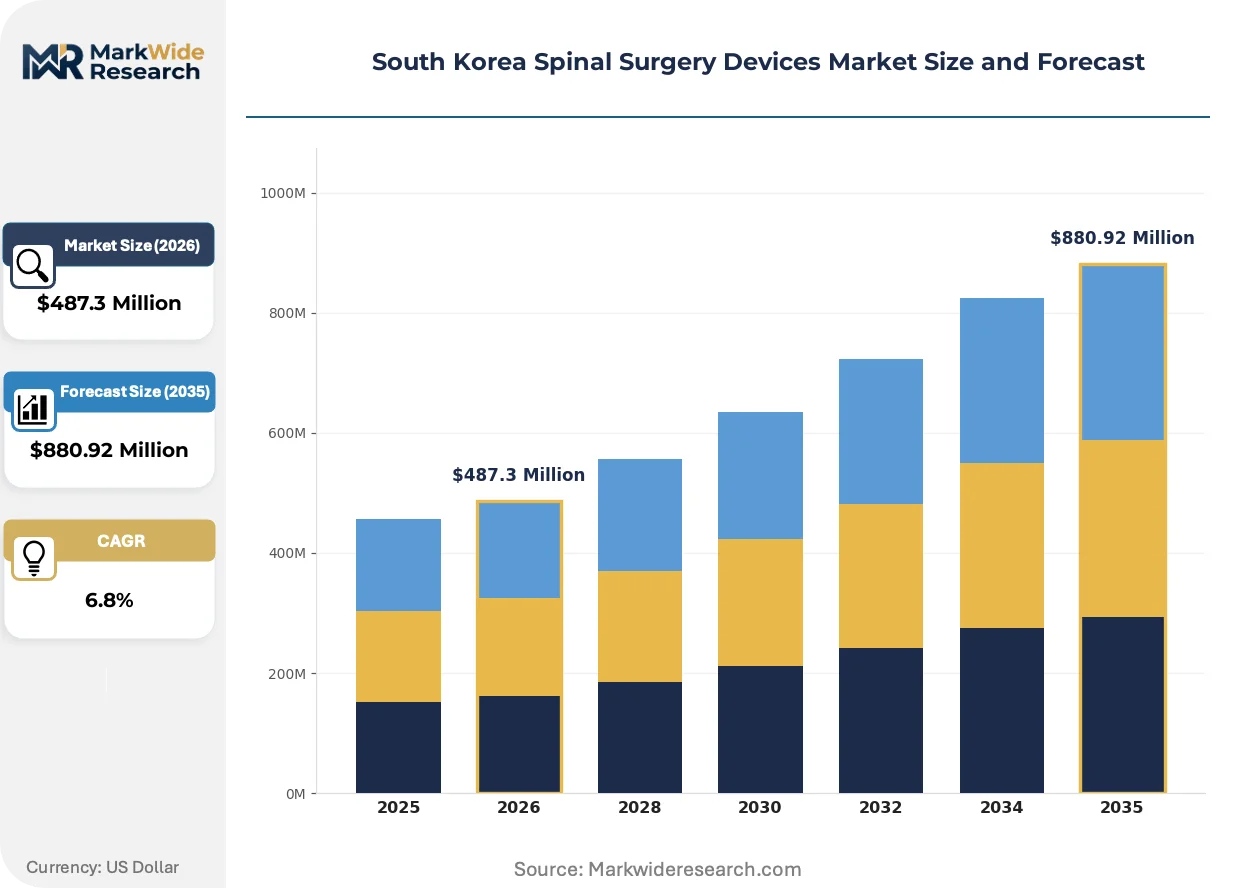
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinal Fusion Devices, Artificial Discs, Bone Grafts, Fixation Devices Technology: Minimally Invasive, Robotic-Assisted, Navigation Systems, Traditional Open Surgery End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Centers Application: Degenerative Disc Disease, Spinal Stenosis, Trauma, Tumors |
| Companies Covered | Medtronic PLC, Stryker Corporation, Johnson & Johnson (DePuy Synthes), B. Braun SE, Zimmer Biomet, ZimVie Inc., GENOSS Co., Ltd., GSMEDICAL CORPORATION, BK Meditech Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Spinal Surgery Devices Market Evolving Landscape
Digital surgical workflows are compressing the gap between pre-operative planning and intra-operative execution, with software-defined precision displacing manual technique as the primary value driver in spinal implant positioning.
Navigation-integrated robotic platforms are automating vertebral screw placement through haptic guidance and real-time trajectory correction. Seoul's Asan Medical Center and Samsung Medical Center have adopted these systems for complex deformity cases, reducing fluoroscopy exposure and revision rates. The technology is automating previously manual steps in the surgical workflow, compressing training curves for new surgeons and standardizing outcomes across operator experience levels.
MFDS tightened clinical evidence standards for demineralized bone matrix products under revised biologics safety guidelines, requiring extended follow-up data for osteoinductive claims. Domestic manufacturers must now conduct longer-term post-market studies to maintain product registrations. Spinal fusion biologics face the steepest compliance burden, with several suppliers reformulating toward synthetic alternatives to accelerate approval timelines.
Hospital purchasing committees are consolidating vendor relationships around full-procedure solutions rather than discrete implant categories. Tertiary centers now negotiate multi-year contracts spanning robotics, navigation, implants, and disposables, displacing the traditional device-by-device tender process. This concentration is most visible in Seoul's university-affiliated hospitals, where procurement authority has centralized from individual surgeons to supply chain departments.
South Korea Spinal Surgery Devices Market Segmentation
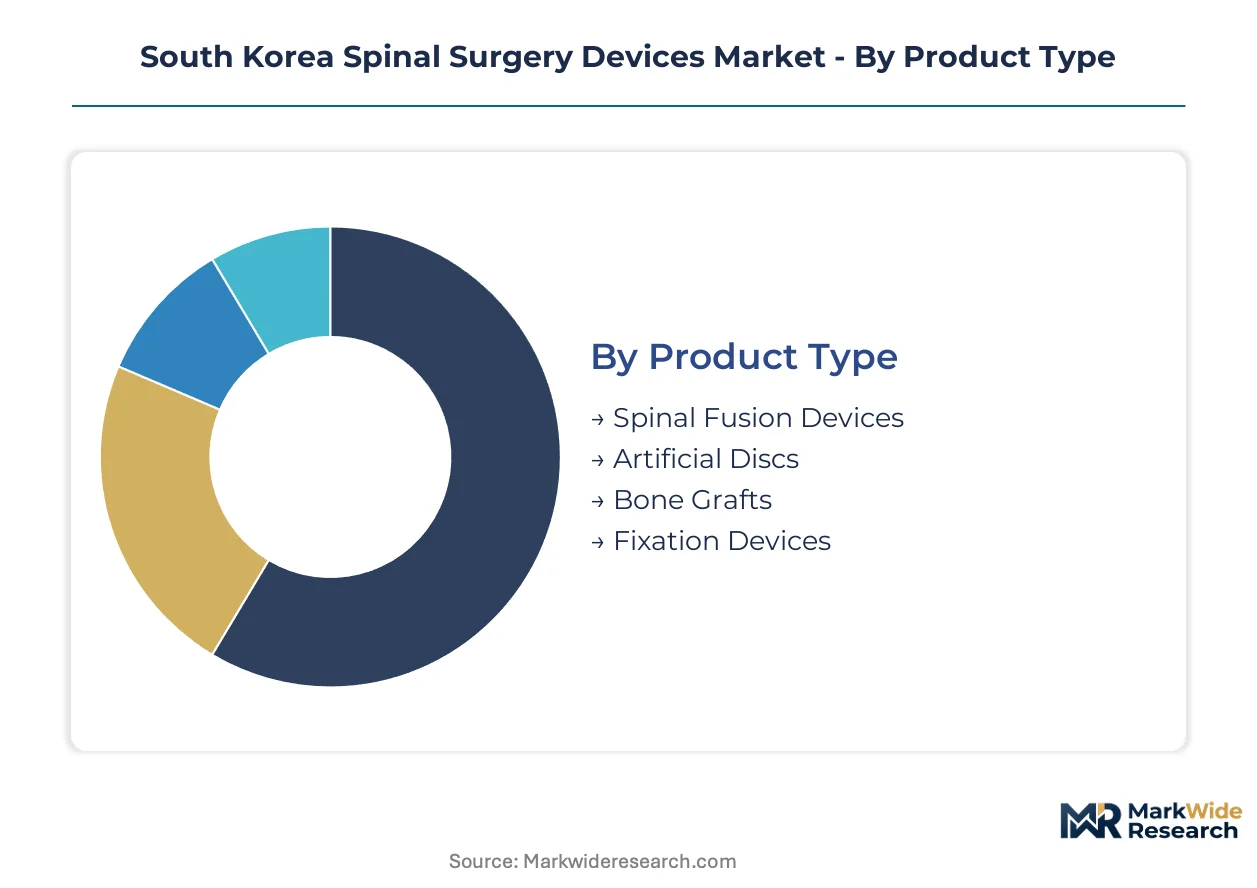
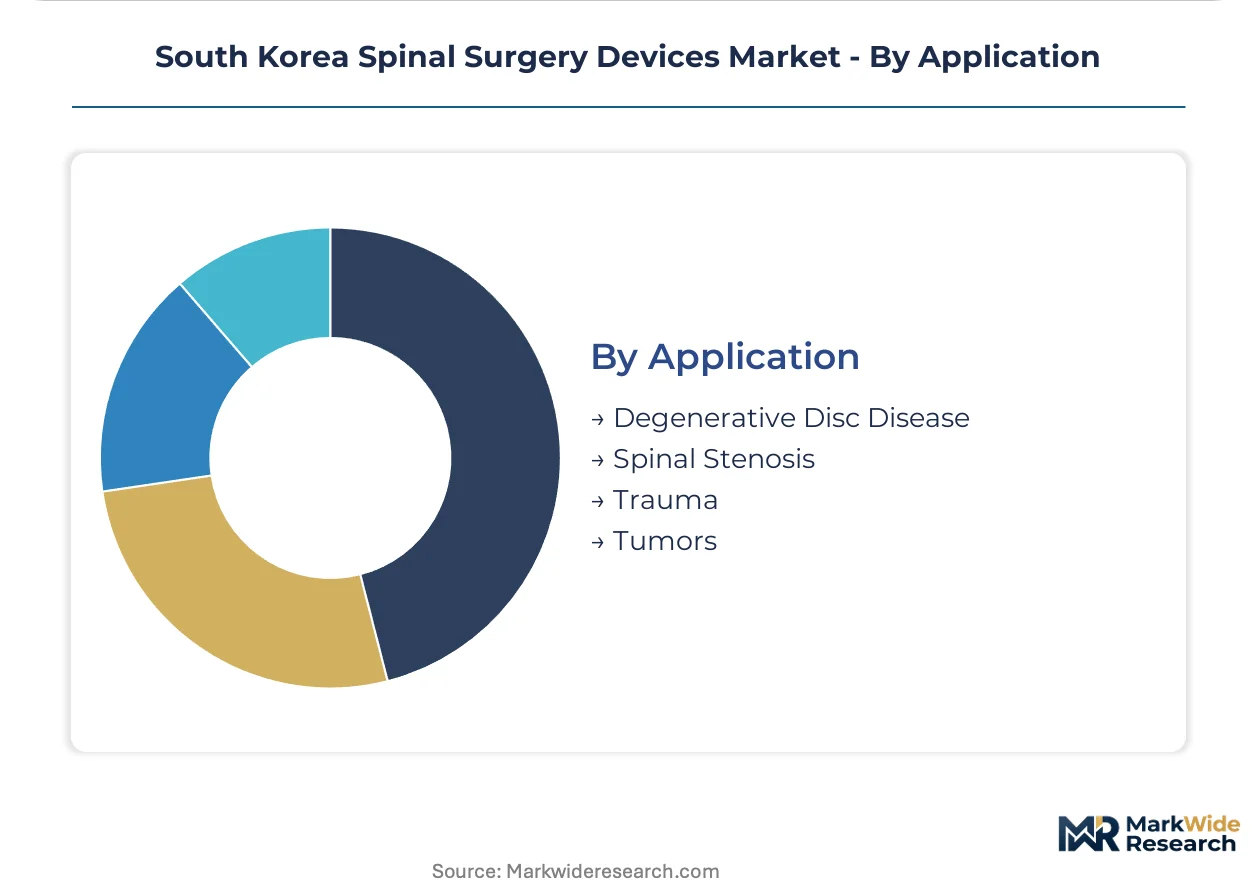
Segmentation reveals how MFDS regulatory pathways and Health Insurance Review and Assessment Service reimbursement tiers fragment procurement authority across South Korean healthcare facilities. Device manufacturers must align product portfolios with distinct approval timelines and hospital capital budgets.
Product Type:
MFDS classifies spinal implants by material risk and biocompatibility testing burden, with titanium-alloy fixation devices facing streamlined review while demineralized bone matrices trigger extended clinical evidence requirements.
- Spinal Fusion Devices:Titanium cages and PEEK polymer interbody spacers dominate Seoul's tertiary hospital procurement, with Asan Medical Center and Samsung Medical Center driving demand for navigation-compatible instrumentation. MFDS tightened biocompatibility documentation for PEEK variants under revised polymer safety guidelines.
- Fixation Devices:Pedicle screw systems and rod constructs from domestic manufacturers like GENOSS Co., Ltd. compete on cost efficiency for regional hospitals in Daegu and Gwangju. Raw material volatility for implant-grade Ti-6Al-4V constrains margin predictability.
- Artificial Discs:Motion-preserving cervical and lumbar replacements face selective reimbursement from Health Insurance Review and Assessment Service, limiting adoption to self-pay patient segments.
- Bone Grafts:Synthetic alternatives gain share as MFDS extended follow-up requirements for demineralized bone matrix products compress approval timelines for osteoinductive claims.
Spinal fusion devices sit at the top of the volume ranking, with artificial discs climbing the fastest as tertiary hospitals expand motion-preserving surgical protocols.
Technology:
Capital intensity and surgeon training requirements stratify adoption across South Korean hospital tiers, with robotic platforms concentrating in Seoul-Gyeonggi while regional centers retain conventional approaches.
- Robotic-Assisted:Navigation-integrated platforms automate vertebral screw placement through haptic guidance, reducing fluoroscopy exposure at Asan Medical Center and Samsung Medical Center. MFDS accelerated approval pathways compress time-to-market for new system entrants.
- Minimally Invasive:Tubular retractor systems and percutaneous fixation techniques expand addressable patient populations beyond traditional open-surgery candidates. Gyeonggi Province hospitals favor these approaches for faster recovery metrics.
- Navigation Systems:Pre-operative planning software bundled with implant hardware creates multi-year service contracts, displacing discrete device procurement.
- Traditional Open Surgery:Conventional techniques retain volume in regional hospitals lacking robotic capital budgets or fellowship-trained spine surgeons.
Traditional open surgery maintains the largest procedure base, though robotic-assisted platforms are expanding most quickly as hospitals amortize capital equipment across high-volume caseloads.
End User:
Procurement centralization and reimbursement fee schedules determine technology access tiers, with university-affiliated hospitals exercising consolidated purchasing authority.
- Hospitals:Tertiary medical centers in Seoul and Gyeonggi Province negotiate multi-year vendor contracts spanning robotics, navigation, implants, and disposables. Supply chain departments have displaced individual surgeon procurement authority.
- Ambulatory Surgical Centers:Limited spinal procedure authorization under national health insurance restricts these facilities to select decompression cases.
- Orthopedic Clinics:Pre-operative diagnostic and post-operative rehabilitation services complement hospital-based surgical care.
- Rehabilitation Centers:Post-fusion physical therapy demand tracks surgical volume concentration in metropolitan areas.
Hospitals command the dominant share of device procurement, with ambulatory surgical centers gaining traction fastest where minimally invasive techniques enable same-day discharge protocols.
Application:
Pathology-specific procedure volumes align with South Korea's aging demographic profile and trauma incidence patterns.
- Degenerative Disc Disease:Cervical and lumbar fusion procedures driven by osteoarthritis prevalence in patients over sixty-five. Seoul's tertiary hospitals report highest caseload concentration.
- Spinal Stenosis:Decompression and fusion combinations address neural compression symptoms, with navigation systems reducing revision rates in complex deformity cases.
- Trauma:Fracture stabilization demand correlates with industrial accident rates and traffic injury patterns.
- Tumors:Neoplastic resection and reconstruction procedures require advanced navigation-integrated platforms for precision margin control.
Degenerative disc disease accounts for the highest procedure volume, while tumor applications are gaining share fastest as navigation technology enables previously inoperable resections.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in South Korea's spinal surgery devices sector concentrate production capacity where MFDS compliance costs align with manufacturing scale advantages, driving domestic producers toward cost-efficient fixation platforms while multinational firms anchor premium navigation-integrated systems in Seoul's tertiary hospital networks.
Seoul Capital Area
Seoul's university-affiliated hospitals generate concentrated demand for robotic-assisted spinal platforms and navigation-compatible PEEK polymer implants. MFDS accelerated approval pathways for these capital-intensive systems enable faster hospital adoption. Asan Medical Center and Samsung Medical Center anchor this cluster, performing complex deformity procedures that amortize robotic equipment across high-volume caseloads.
Gyeonggi Province
Hospital systems in Gyeonggi Province are expanding dedicated spinal surgery wings with minimally invasive capability, creating procurement demand for tubular retractor systems and percutaneous fixation devices. The Ministry of Health and Welfare's reimbursement fee schedules directly determine technology adoption thresholds for these facilities. Bundled vendor contracts spanning robotics, navigation, and implants are displacing discrete device procurement at centralized supply chain departments.
Busan-Ulsan
Secondary metropolitan demand in Busan-Ulsan concentrates on cost-efficient fixation devices for regional trauma and degenerative cases. Domestic manufacturers like GENOSS Co., Ltd. compete on pricing for pedicle screw systems in this price-sensitive segment. Raw material volatility for implant-grade Ti-6Al-4V constrains margin predictability for suppliers serving this regional hospital base.
Daegu-Gyeongbuk
Daegu-Gyeongbuk presents underdeveloped robotic surgical capacity relative to Seoul-Gyeonggi, offering first-mover positioning for platform-agnostic implant suppliers. The Health Insurance Review and Assessment Service's fixed fee schedules for spinal fusion procedures cap hospital technology budgets in this region. Regional hospitals retain conventional open-surgery approaches due to limited fellowship-trained spine surgeon availability.
Daejeon-Sejong
Government research institutions in Daejeon-Sejong support clinical evidence generation for novel spinal biologics under MFDS real-world evidence pilot programs. Post-market surveillance data collection requirements for demineralized bone matrix products create competitive differentiation for manufacturers with established clinical registries. Synthetic bone graft alternatives gain share as extended follow-up requirements compress approval timelines for osteoinductive claims.
South Korea Spinal Surgery Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue navigation-implant bundling and regional hospital penetration outside Seoul-Gyeonggi. The market structures around three tiers: multinational corporations with integrated robotics portfolios, domestic manufacturers competing on fixation device pricing, and specialists in biologics and patient-specific instrumentation. Consolidation pressures favor full-procedure solution providers over discrete implant vendors. Dominant competitive moves include multi-year service contract negotiations with tertiary hospital supply chain departments and backward integration into navigation software development.
Among multinational platform providers, Medtronic PLC and Stryker Corporation anchor premium positioning through Seoul's tertiary hospital networks. Domestic scale producers include GENOSS Co., Ltd., which occupies a cost-efficiency archetype for regional hospital fixation device procurement. These three entities represent distinct competitive vectors: integrated navigation-fusion systems, specialized power tools and biologics distribution, and domestic manufacturing scale for price-sensitive segments.
| Leading Market Players |
|---|
| Medtronic PLC |
| Stryker Corporation |
| Johnson & Johnson (DePuy Synthes) |
| B. Braun SE |
| Zimmer Biomet |
| ZimVie Inc. |
| GENOSS Co., Ltd. |
| GSMEDICAL CORPORATION |
| BK Meditech Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Fellowship-trained spine surgeon concentration in Seoul-Gyeonggi compresses labor-cost differentials across South Korea's spinal surgery devices market, widening pricing-tier spreads between capital-intensive robotic platforms and conventional fixation systems. Raw material volatility for implant-grade Ti-6Al-4V and PEEK polymer supply constraints further stratify procurement budgets across tertiary and regional hospital tiers.
Pricing Analysis
Distributor margins on navigation-integrated robotic systems absorb 15-25 point markups before hospital procurement committees, compressing manufacturer net pricing power. Three-tier pricing structure across premium navigation-robotic bundles, standard minimally invasive instrumentation, and economy fixation devices reflects certification grade and after-sales service bundling. Pricing pressure stems from Health Insurance Review and Assessment Service reimbursement rigidity for spinal fusion procedures, capping hospital technology budgets. Regional hospitals in Daegu-Gwangju exhibit highest price sensitivity, while Seoul's university-affiliated centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with implant-grade titanium alloy feedstock from Japan and Germany, constraining domestic manufacturers like GENOSS Co., Ltd. when spot prices fluctuate. South Korea's spinal device production draws from PEEK polymer resin sourced from the United Kingdom and Switzerland, plus precision-machined components from Taiwan. Tariff exposure on European-sourced biologics and navigation software licensing fees from the United States create margin unpredictability. Distribution runs through GPO-negotiated contracts with hospital supply chain departments, displacing traditional surgeon-directed procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's spinal surgery devices market functions as a stable compounder, with demographic aging and tertiary hospital capital expansion providing durable procedure volume growth across the analysis window.
For Market Incumbents: Extend service contract durations with Seoul-Gyeonggi tertiary hospitals to lock in multi-year implant procurement commitments before MFDS real-world evidence requirements reshape competitive positioning. Deepen backward integration into PEEK polymer compounding to offset Ti-6Al-4V price volatility and defend margin structure against domestic fixation device competitors. For New Entrants and Emerging Players: Regional hospitals in Daegu-Gwangju lacking robotic surgical capacity present the most penetrable buyer archetype for platform-agnostic implant suppliers. Target these secondary metropolitan centers with navigation-compatible fixation bundles priced below Medtronic and Stryker premiums. Pursue MFDS accelerated approval pathway designation to compress time-to-revenue versus established competitors. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic manufacturers with established PEEK polymer processing capabilities and MFDS-registered biologics pipelines. Long-term viability over a 5-10 year horizon rests on convergence toward full-procedure solution providers rather than discrete implant vendors. Watch Health Insurance Review and Assessment Service reimbursement adjustments for robotic surgery codes as the primary inflection signal for capital equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Accelerated Approval Pathway | Navigation-robotic platform entrants compress regulatory timelines versus conventional review. |
| Hospital System Partnership | Multi-year service contracts with Asan Medical Center and Samsung Medical Center anchor revenue visibility. |
| Reimbursement Strategy | Health Insurance Review and Assessment Service code advocacy determines hospital technology budget elasticity. |
| Software Companion Development | Pre-operative planning integration with implant hardware creates sticky vendor relationships. |
| Backward Integration | In-house PEEK polymer compounding insulates margin from raw material spot price volatility. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down implant manufacturer shipment tracking forms the analytical core of this study. Primary interviews with spine surgeons, hospital supply chain directors, biomedical engineers, and GPO contracts managers combined with secondary validation from MFDS registration databases, Health Insurance Review and Assessment Service reimbursement schedules, and hospital capital expenditure disclosures. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of procedure volumes, capital equipment installations, and implant shipment patterns established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, technology tier, end-user facility class, and application pathology. CAGRs derived from regression-adjusted trend extrapolation, with robotic-assisted platform penetration curves and PEEK polymer adoption rates as key forecast inputs.
Underlying measurement precision varies by segment; spinal fusion device volumes carry tighter precision than emerging artificial disc replacement categories due to established reimbursement coding. Forecasts reflect assumptions on MFDS regulatory timelines, Health Insurance Review and Assessment Service fee schedule stability, and titanium alloy price normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
Adult Orthopedic Insole Market
Orthopedic Devices
Patients Repositioning and Offloading Device Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Scoliosis Treatment Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
Limb Salvage Systems Market
Orthopedic Devices
Spinal Implants and Surgical Devices Market
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Global Personalized 3D Printed Orthopedic Implants Market
Orthopedic Devices
Antibacterial Orthopedic Implant Market
Orthopedic Devices
Global Artificial Joints Market
Orthopedic Devices
Global Shoulder Replacement Market