
 Spinal Devices Market | 2026-2036
Spinal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Devices Market Intelligence
Software-as-a-service platforms for pre-operative planning and robotic guidance is hardening the connection between device sales and recurring service revenue. Medtronic leverages its broad portfolio of implants and navigation systems to secure comprehensive hospital contracts. Stryker Corporation differentiates with its Mako robotic-arm assisted surgery platform, creating a distinct technological ecosystem. Johnson & Johnson's DePuy Synthes unit competes by integrating digital surgery solutions across its established implant portfolio.
Spinal devices are medical products, including implants and fixation systems, used to correct spinal deformities, treat trauma, and manage degenerative conditions. These devices are manufactured from biocompatible materials like titanium alloys or PEEK to provide structural support and facilitate bone fusion. Spinal implants and fixation devices form the core revenue-generating product segments in the market. The adoption of Minimally Invasive Surgery technology is accelerating, driven by its association with reduced recovery times and shorter hospital stays for patients.
Market access requires stringent approvals from bodies like the US Food and Drug Administration (FDA) and adherence to the European Union's Medical Device Regulation (MDR). These frameworks, along with standards from China's NMPA, mandate extensive clinical evidence for new product clearance, which influences R&D timelines. Future competitive advantage will hinge on a manufacturer's ability to navigate evolving reimbursement policies and demonstrate clear clinical-economic value to hospital administrators.
Market Dynamics
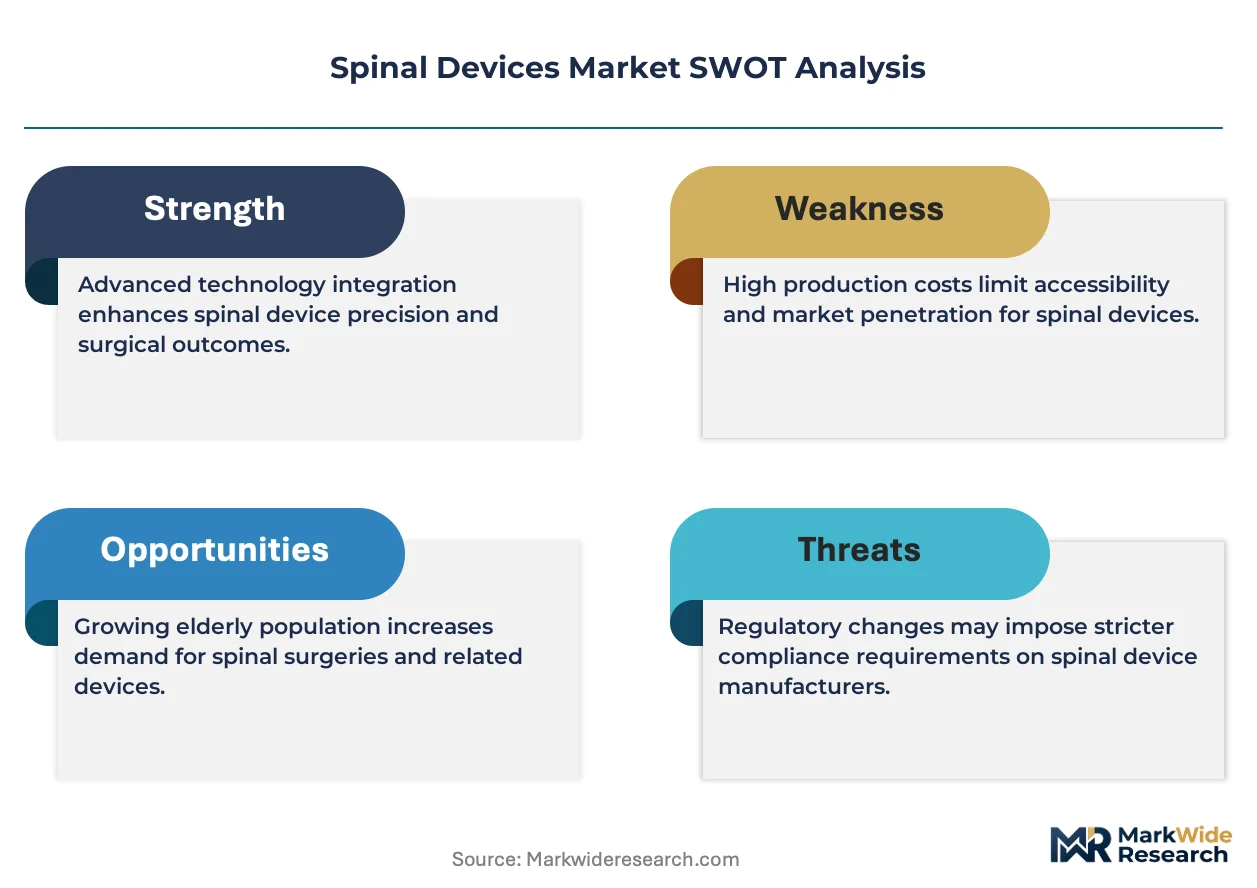
The convergence of robotic-assisted surgery and pre-operative planning software is the central force shaping the market. This integration transforms the value proposition from discrete implants to comprehensive procedural ecosystems, tying device sales directly to recurring digital service revenue.
Growth Catalysts
- Ambulatory Surgical Centers:The policy-driven migration of spinal procedures to ASCs in the United States creates demand for cost-effective, efficient implant systems and instrumentation suitable for outpatient settings.
- Aging Demographics:An increasing prevalence of degenerative disc disease in aging populations, particularly in Japan and Germany, directly expands the patient pool for fusion and fixation procedures.
- Advanced Materials:The adoption of 3D-printed porous titanium and PEEK implants enhances biocompatibility and promotes better osseointegration, which improves long-term clinical outcomes for patients.
Market Restraints
- High Capital Costs:The significant initial investment required for robotic surgery platforms limits their adoption to large, well-funded hospital systems, creating an access barrier for smaller facilities.
- Regulatory Scrutiny:The European Union's Medical Device Regulation (MDR) imposes stringent clinical evidence requirements and longer review timelines, delaying new product introductions into the European market.
- Reimbursement Uncertainty:Inconsistent reimbursement codes and payment levels for novel minimally invasive techniques can deter adoption by surgeons and hospitals across various national healthcare systems.
Strategic Opportunities
- Emerging Market Penetration:Expanding into markets like Brazil and Mexico, where improving healthcare access and rising disposable incomes create new demand for advanced spinal treatments.
- Technology Convergence:Integrating augmented reality overlays into surgical navigation systems offers surgeons real-time, intraoperative guidance, potentially reducing procedure times and improving screw placement accuracy.
- Biologics Integration:Developing complementary biologic products, such as bone graft substitutes and growth factors, creates opportunities to enhance fusion rates and overall clinical success of implant procedures.
Industry Challenges
- Specialized Surgeon Training:A critical shortage of surgeons proficient in operating advanced robotic-assisted platforms creates a bottleneck for technology adoption and procedural volume growth.
- Data Interoperability:Integrating proprietary surgical planning software with diverse hospital Electronic Health Record (EHR) systems presents significant technical and data security challenges for providers.
- Post-Market Surveillance Costs:Complying with extensive post-market clinical follow-up data demands from regulators like the FDA and China's NMPA increases long-term operational costs for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Devices Market |
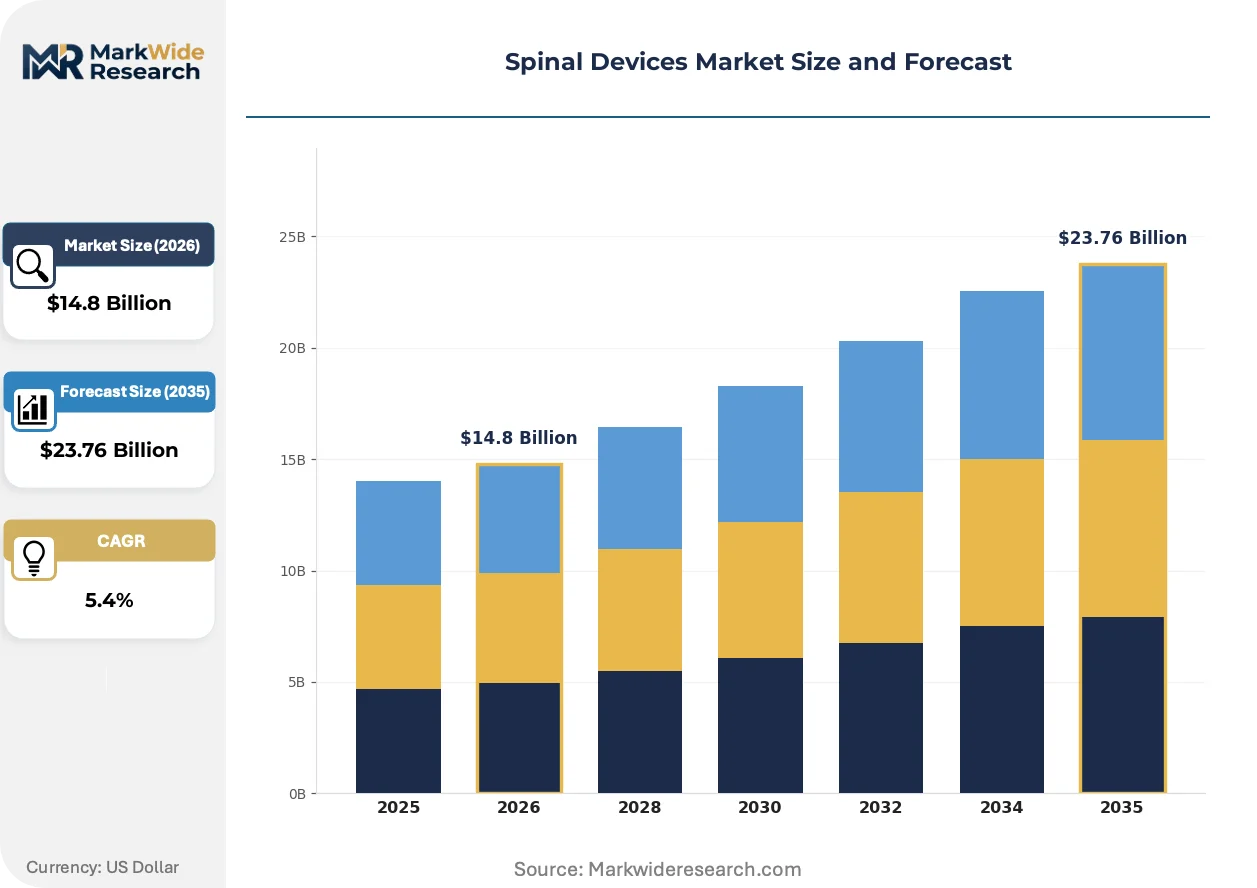
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Fixation Devices, Surgical Instruments, Artificial Discs End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Rehabilitation Centers Technology: Minimally Invasive Surgery, Computer-Assisted Surgery, Robotics, Traditional Surgery Application: Degenerative Disc Disease, Spinal Stenosis, Scoliosis, Trauma |
| Companies Covered | Medtronic, Stryker Corporation, Johnson & Johnson (DePuy Synthes), Zimmer Biomet Holdings, Globus Medical, NuVasive, Orthofix Medical, B. Braun Melsungen AG, RTI Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Devices Market Strategic Shifts & Innovations
This market's evolution is defined by the shift from selling standalone implants to providing integrated platforms that combine hardware, software, and data analytics. The change is prioritizing procedural efficiency and clinical data, altering the basis of competition.
3D-printed patient-specific implants, often fabricated from titanium or PEEK, provide a customized anatomical fit. Specialized orthopedic centers are adopting this technology to improve surgical precision and patient outcomes. This innovation is modularizing the implant portfolio, enabling surgeons to construct personalized spinal solutions from both standard and custom components.
Mandates from the US Food and Drug Administration for Unique Device Identification (UDI) on medical devices enhance traceability. The regulation strengthens post-market surveillance and enables more targeted, efficient recalls of spinal products. Device manufacturers are most impacted, needing to integrate robust data management systems to track implants from factory to patient.
A clear movement toward value-based purchasing within large hospital groups is altering procurement dynamics. This approach replaces per-unit implant pricing with bundled payments for an entire episode of care, including the device and associated services. This purchasing behavior is most advanced in the United States and parts of Western Europe.
Spinal Devices Market Segmentation
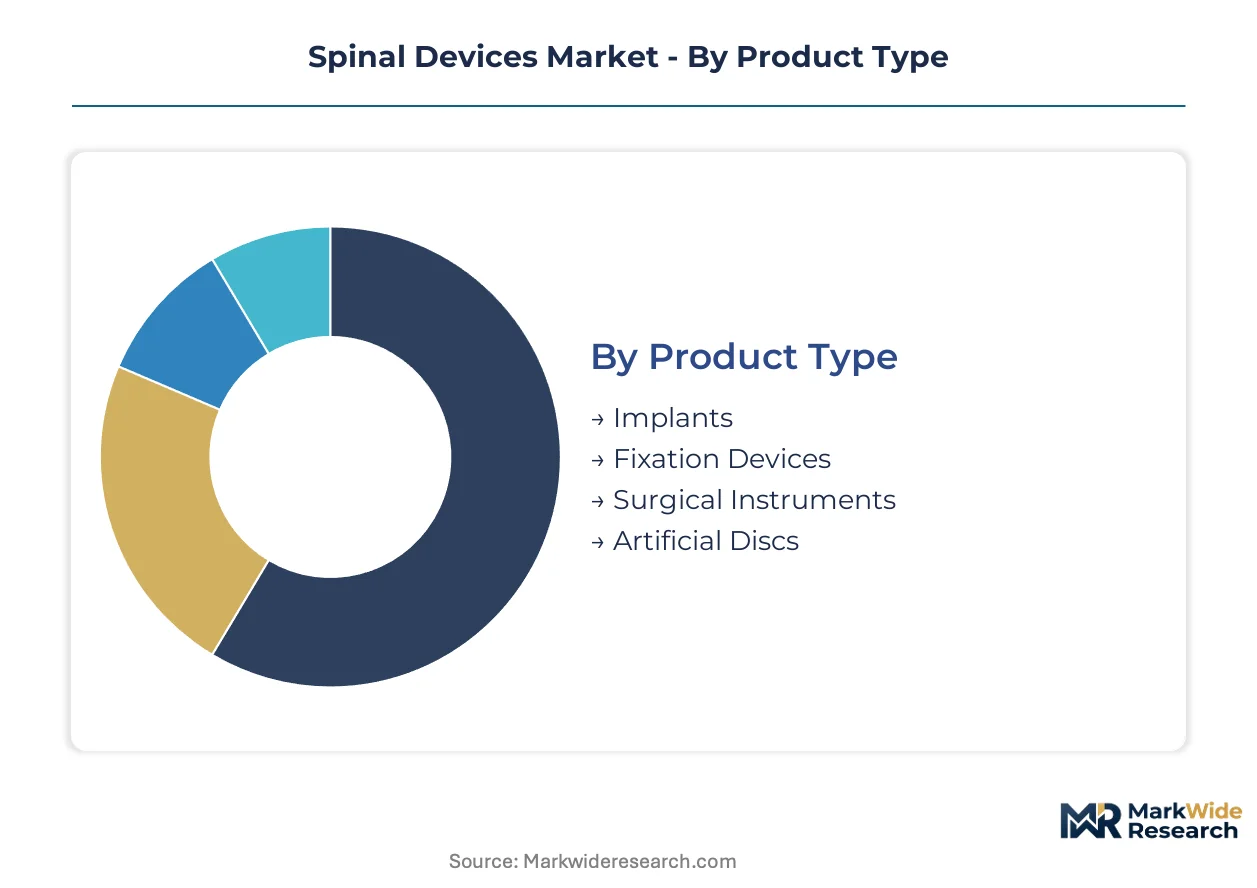
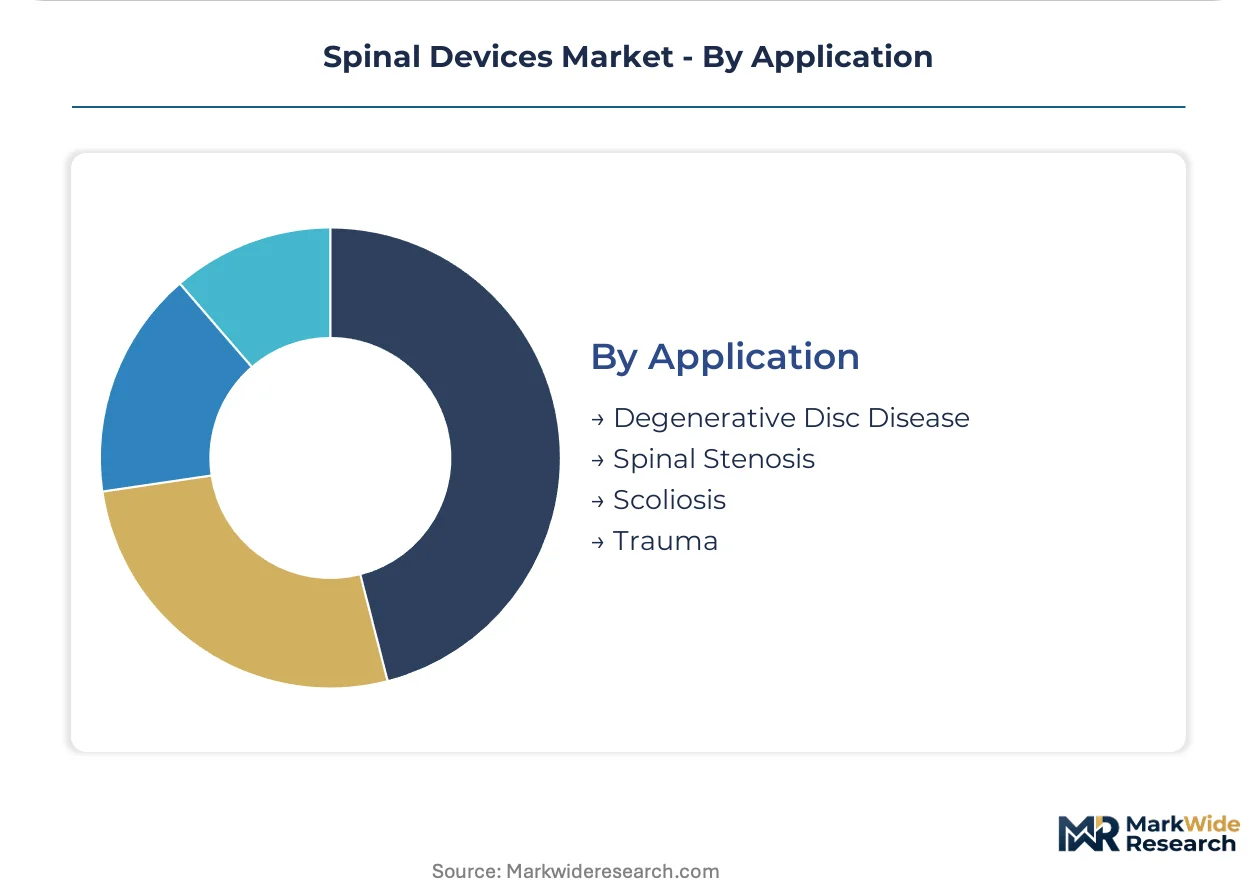
The Spinal Devices Market exhibits diverse segments driven by technological advancements and evolving healthcare delivery models. Understanding these distinctions allows manufacturers to tailor product development and market access strategies effectively. Precise segmentation highlights areas of concentrated demand and emerging growth within the broader market landscape.
Product Type:
The supply concentration in spinal devices heavily favors complex implantable solutions, reflecting their critical role in surgical outcomes.
- Implants:These devices, often crafted from titanium alloys or PEEK, are surgically inserted to replace or support damaged spinal structures. Demand for these sophisticated components is particularly strong in Germany and Japan due to the high incidence of degenerative spinal conditions in aging populations.
- Fixation Devices:Comprising rods, screws, and plates, these systems stabilize the spine after trauma or deformity correction, facilitating bone fusion. The adoption of advanced fixation devices is accelerating in ambulatory surgical centers, which seek efficient and reliable solutions for outpatient procedures.
- Surgical Instruments:This category includes specialized tools like retractors, drills, and reamers essential for precise placement of implants and devices during spinal procedures.
- Artificial Discs:Designed to restore motion and alleviate pain, these prosthetic devices offer an alternative to traditional spinal fusion in select patient cases.
Implants absorb the bulk of installed capacity; Artificial Discs are expanding most quickly.
End User:
Application focus drives differentiation among end-user segments, each with distinct procurement priorities and patient care models.
- Hospitals:These large facilities serve as primary sites for complex spinal surgeries, often requiring comprehensive contracts for a broad portfolio of devices and navigation systems. Hospitals in the United States and Western Europe prioritize integrated solutions that enhance surgical efficiency and patient safety.
- Ambulatory Surgical Centers:ASCs specialize in outpatient procedures, demanding cost-effective and efficient implant systems suitable for shorter patient stays and reduced recovery times. The policy-driven migration of procedures to ASCs in the US creates significant demand for specialized instrumentation.
- Specialty Clinics:These clinics often focus on specific spinal conditions or non-surgical treatments, occasionally performing minor procedures requiring targeted device solutions.
- Rehabilitation Centers:Post-operative care and physical therapy are central to these centers, which indirectly influence device selection through recovery protocols and patient outcomes.
Hospitals prioritize comprehensive contracts, while ASCs seek cost-effective solutions.
Technology:
Innovation in procedural approaches defines this segment, with new technologies transforming surgical precision and patient recovery.
- Minimally Invasive Surgery:MIS techniques involve smaller incisions, leading to reduced patient trauma, shorter hospital stays, and faster recovery. Adoption of MIS is accelerating globally, particularly in developed nations seeking improved patient outcomes.
- Computer-Assisted Surgery:This technology uses advanced imaging and software to provide surgeons with real-time guidance during spinal procedures, improving accuracy. The integration of robotics within computer-assisted surgery is a pivotal technological driver, enhancing procedural precision.
- Robotics:Robotic-arm assisted surgery platforms, such as Stryker's Mako, offer enhanced precision and control, though they involve significant initial capital costs.
- Traditional Surgery:Open surgical techniques remain vital for complex cases, especially in regions with limited access to advanced technological platforms.
Minimally Invasive Surgery continues its rapid adoption curve, with robotics gaining significant traction.
Application:
Patient demographics directly influence demand within these applications, with degenerative conditions forming a substantial patient base.
- Degenerative Disc Disease:This condition, common in aging populations, involves the breakdown of spinal discs, leading to pain and instability. Treatments often involve fusion or artificial disc replacement, driving demand for specific implants.
- Spinal Stenosis:Characterized by the narrowing of the spinal canal, this condition compresses nerves and causes pain, often requiring decompression surgery and stabilization devices. The prevalence of spinal stenosis is increasing with global aging demographics.
- Scoliosis:This spinal deformity, often diagnosed in adolescence, requires corrective surgery using specialized rods and screws to realign the spine.
- Trauma:Spinal injuries resulting from accidents or falls necessitate immediate surgical intervention using fixation devices to stabilize fractured vertebrae.
Addressing degenerative conditions remains the largest application area, with trauma procedures also requiring specialized devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global spinal devices market exhibits a notable production-consumption divide, with advanced manufacturing concentrated in developed economies. Consumption patterns are increasingly driven by aging demographics and healthcare infrastructure development. This dynamic shapes regional demand and regulatory landscapes across key geographies.
United States
Demand for spinal devices in the United States is propelled by the policy-driven migration of procedures to ambulatory surgical centers. The US Food and Drug Administration (FDA) mandates extensive clinical evidence for new product clearance. Major medical device clusters in states like California and Massachusetts are developing integrated surgical platforms.
Germany
An aging population in Germany significantly drives the need for spinal fusion and fixation procedures to address degenerative disc disease. The European Union's Medical Device Regulation (MDR) imposes stringent requirements for market access and post-market surveillance. The MedTech cluster in Tuttlingen focuses on precision surgical instrumentation and implant manufacturing.
Japan
Degenerative spinal conditions are highly prevalent among Japan's rapidly aging demographics, creating sustained demand for advanced spinal implants. Japan's Pharmaceuticals and Medical Devices Agency (PMDA) regulates product approvals, emphasizing safety and efficacy. The Tokyo metropolitan area sees significant investment in robotic-assisted surgery development and adoption.
Brazil
Improving healthcare access and rising disposable incomes in Brazil are creating new demand for advanced spinal treatments. The Brazilian Health Regulatory Agency (ANVISA) oversees medical device registration and market entry. São Paulo's healthcare infrastructure is expanding, leading to increased adoption of minimally invasive spinal techniques.
China
Expanding patient demographics for spinal conditions in China, combined with healthcare infrastructure upgrades, fuels demand for both implants and fixation devices. China's National Medical Products Administration (NMPA) requires comprehensive clinical evidence for new product clearance. Medical device parks in cities like Suzhou are becoming hubs for domestic spinal implant innovation.
Spinal Devices Market Key Industry Players
Top-tier vendors anchor the global spinal devices market, while specialized mid-tier players focus on niche segments and technological differentiation. The market structure exhibits consolidation among leading companies, alongside fragmentation within smaller innovators. Strategic archetypes include diversified medical technology conglomerates, pure-play spinal device specialists, and emerging digital surgery solution providers. Dominant competitive moves involve strategic partnerships for technology integration and continuous portfolio diversification to capture adjacent market opportunities.
Within the diversified medical technology conglomerate archetype, Medtronic and Johnson & Johnson's DePuy Synthes unit exemplify comprehensive hospital contract strategies, leveraging broad portfolios of implants and navigation systems. These entities prioritize integrated solutions that span various spinal conditions and surgical approaches. Stryker Corporation occupies a distinct position by focusing on its Mako robotic-arm assisted surgery platform, creating a proprietary technological ecosystem that emphasizes procedural accuracy and efficiency. These companies collectively anchor the market's evolution towards integrated procedural solutions, influencing procurement dynamics across major healthcare systems.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| Johnson & Johnson (DePuy Synthes) |
| Zimmer Biomet Holdings |
| Globus Medical |
| NuVasive |
| Orthofix Medical |
| B. Braun Melsungen AG |
| RTI Surgical |
| Others |
Cost & Logistics Intelligence
A clear performance gap between advanced robotic platforms and traditional instrumentation defines a tier divergence, impacting both pricing and supply chain configurations. This bifurcation drives specialized manufacturing requirements and influences procurement strategies across healthcare systems.
Pricing Analysis
Cost compression on traditional spinal implants intensifies as ambulatory surgical centers prioritize efficiency and value-based purchasing models. Pricing stratifies across premium, standard, and economy tiers, reflecting product complexity, material innovation, and regulatory clearance. Certification level, such as FDA approval or CE marking, and the degree of customization drive price differentiation. Hospitals in developed nations exhibit lower price sensitivity for integrated robotic systems due to their precision benefits, while ASCs remain highly price-sensitive for commodity implants.
Supply Chain Analysis
Workforce availability and specialized manufacturing expertise in Germany and the United States anchor the production of advanced spinal devices. Raw material dependencies include titanium alloys and PEEK polymers, sourced globally, with processing concentrated in specialized facilities. Single-source vulnerability for certain high-precision components represents a structural supply chain risk. Distribution runs through a direct sales force model for large conglomerates and specialized medical distributors for mid-tier players, reaching hospitals and ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story, with the European Union's Medical Device Regulation (MDR) creating a significant barrier-to-entry moat for established, compliant players.
For Market Incumbents: Deploy strategic partnerships with artificial intelligence software developers to enhance pre-operative planning and intraoperative guidance systems. This move defends against emerging digital surgery solution providers and strengthens comprehensive hospital contracts. Invest in advanced materials R&D, particularly in 3D-printed porous titanium, to maintain a technological edge against generic implant manufacturers.
For New Entrants and Emerging Players: Underserved regional clinics in emerging markets like Brazil and Mexico represent a penetrable segment for cost-effective, minimally invasive spinal solutions. Focus on developing specialized instrumentation for outpatient settings, offering a clear value proposition to ambulatory surgical centers. A go-to-market angle emphasizing rapid surgeon training and simplified workflows can accelerate adoption.
For Investors and Strategic Acquirers: Re-rating potential sits with pure-play spinal device specialists given their focused expertise in rapidly evolving technology segments like robotics and biologics. These companies often possess strong intellectual property in niche areas, making them attractive targets. Watch for increased M&A activity among diversified medical technology conglomerates seeking to acquire advanced digital surgery platforms as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Robotic Platform Ecosystem | Medtronic strengthens its surgical navigation capabilities, improving procedural accuracy and hospital efficiency. |
| Invest in 3D Printing Capabilities | Stryker Corporation enhances patient-specific implant offerings, improving anatomical fit and clinical outcomes. |
| Develop Complementary Biologics | Johnson & Johnson's DePuy Synthes unit improves fusion rates and overall success of implant procedures. |
| Target Ambulatory Surgical Centers | Globus Medical increases market penetration for cost-effective, efficient implant systems in outpatient settings. |
| Streamline Regulatory Approval Processes | NuVasive accelerates new product introductions into key markets like the European Union. |
Research Approach
Independent corroboration across clinical literature, regulatory filings, and industry reports underwrites the qualitative findings presented in this analysis. Primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and medical device executives provided critical market insights. This approach ensured a robust bottom-up and top-down triangulation of market data.
Rate-of-change decomposition framed the analytical approach over the projection horizon, dissecting market expansion by product type, end-user, technology, and application. This framework also incorporated regional regulatory shifts and patient demographic changes as key drivers. Compound annual growth rates were derived from historical data analysis and forward-looking projections, with adoption rates of minimally invasive surgery serving as a primary forecast input.
Revisions become necessary when significant policy changes, unforeseen technological breakthroughs, or shifts in global economic conditions materialize. Forecasts reflect assumptions documented through extensive primary and secondary research. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Patients Repositioning and Offloading Device Market
Orthopedic Devices
Kyphoplasty Systems Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Podiatry Laser Market
Orthopedic Devices
Orthopedic Braces Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
Medical Traction Devices Market
Orthopedic Devices
Physiotherapy Devices Market
Orthopedic Devices
North America Kyphoplasty Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market