
 Bone Void Fillers Market | 2026-2036
Bone Void Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Void Fillers Market Intelligence
Ambulatory surgical centers is redrawing procurement patterns in bone void fillers as hospital outpatient departments cede volume to same-day facilities. Stryker Corporation leverages its integrated trauma and extremities portfolio to sustain channel dominance across both inpatient and outpatient settings. Zimmer Biomet anchors its position through specialized synthetic graft formulations that target minimally invasive spinal procedures. Bioventus competes on differentiated biologic offerings that address non-union and complex fracture gaps.
Bone void fillers comprise synthetic, allograft, and xenograft materials engineered to restore structural integrity in osseous defects following trauma, tumor resection, or degenerative joint procedures. Calcium phosphate formulations, typically hydroxyapatite or beta-tricalcium phosphate with porosities exceeding 60 percent, provide osteoconductive scaffolds that integrate with host bone over six to eighteen months. Demineralized bone matrix retains morphogenetic proteins that stimulate osteoinduction, commanding premium positioning in spinal fusion applications where fusion rates determine reimbursement. Putty and injectable forms are capturing share from traditional granules as surgeons prioritize controlled delivery in arthroscopic and percutaneous techniques.
The FDA's 510(k) pathway and the European Medicines Agency's Medical Device Regulation impose distinct evidentiary standards on biologic versus synthetic graft classifications, directly shaping R&D allocation and time-to-market economics. ISO 10993 biocompatibility testing and ASTM F1185 specifications for surgical-grade hydroxyapatite further constrain material sourcing and manufacturing validation. Stakeholders must monitor evolving CMS site-of-service payment differentials and the trajectory of hospital-ASC vertical integration to anticipate where procurement authority and pricing leverage will concentrate next.
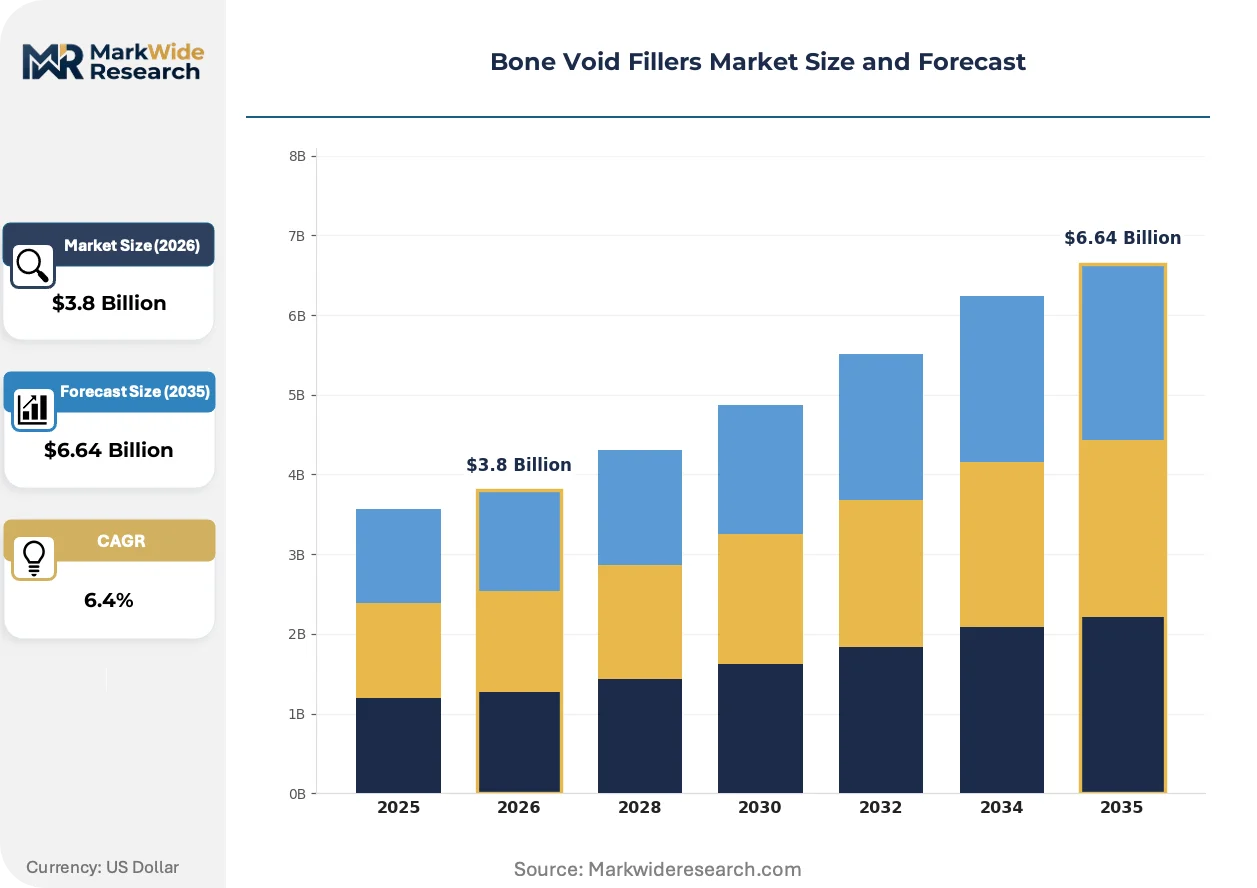
Market Dynamics
The migration of orthopedic procedures to ambulatory surgical centers is compressing hospital purchasing power while elevating distributor influence over material selection and inventory management.
Growth Catalysts
- Sports medicine volume:Rising participation in recreational athletics across the United States sustains demand for arthroscopic defect repair requiring synthetic and biologic grafts.
- MDR harmonization:The European Medicines Agency's Medical Device Regulation streamlines conformity assessment pathways for hydroxyapatite-based products, accelerating cross-border commercialization.
- Injectable delivery systems:Putty and gel formulations compatible with minimally invasive techniques capture preference from granules in percutaneous spinal and extremity procedures.
Market Restraints
- Allograft supply concentration:Tissue bank consolidation in the United States creates single-source vulnerability for demineralized bone matrix processors.
- 510(k) evidentiary burden:FDA demands for predicate device equivalence extend development timelines for novel synthetic compositions.
- Calcium phosphate cost volatility:Feedstock phosphate rock pricing fluctuates with fertilizer industry demand, pressuring hydroxyapatite manufacturer margins.
Strategic Opportunities
- Outpatient orthopedics expansion:Ambulatory surgical centers in Texas and Florida represent underpenetrated volume for same-day spinal fusion and trauma fixation.
- Biologic-synthetic hybrids:Convergence of demineralized bone matrix with beta-tricalcium phosphate scaffolds addresses osteoinduction and structural support in single products.
- IRA site-of-service incentives:Medicare reimbursement differentials favoring ASCs over hospital outpatient departments redirect procurement authority to independent surgery centers.
Industry Challenges
- ISO 10993 biocompatibility testing:Cytotoxicity and sensitization validation for new formulations requires 12-18 month timelines that delay commercial launches.
- Surgeon training gaps:Arthroscopic delivery techniques for injectable grafts demand cadaveric lab investment that distributor partners struggle to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Void Fillers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Phosphate, Synthetic Bone Graft, Demineralized Bone Matrix, Composite Bone Graft Form: Granules, Putty, Powder, Injectable, Blocks Application: Spinal Fusion, Orthopedic Surgery, Dental Grafting, Trauma Repair End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Dental Practices |
| Companies Covered | Stryker Corporation, DePuy Synthes (Johnson & Johnson), Zimmer Biomet, Medtronic, Arthrex, Bonesupport, Bioventus, Baxter International, Biocomposites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Void Fillers Market Strategic Shifts & Innovations
Material science advances and regulatory pathway refinements are compressing the traditional trade-off between osteoinduction and mechanical strength in defect repair.
3D-printed patient-specific scaffolds is decomposing the one-size-fits-all implant model by enabling porous architectures matched to individual defect geometry. Academic medical centers in the United States and Germany pilot these constructs for complex pelvic and craniofacial reconstructions. The technology is decomposing inventory-heavy distribution models into build-to-order manufacturing relationships between hospitals and contract manufacturers.
REACH substance restriction proposals for nanomaterial classifications are forcing European manufacturers to requalify hydroxyapatite particle size distributions in existing product lines. The ECHA consultation process creates 18-24 month uncertainty windows that delay formulation updates. Synthetic graft suppliers are responding by accelerating ASTM F1185 compliance documentation to demonstrate surgical-grade purity independent of emerging nanomaterial definitions.
Surgeon preference for single-use, pre-mixed delivery systems is consolidating purchasing decisions around kit completeness rather than standalone graft material performance. Ambulatory surgery centers negotiate bundled pricing that includes applicators and mixing accessories, compressing standalone material margins. This pattern concentrates in the United States where ASC buying groups aggregate volume across multi-state networks.
Bone Void Fillers Market Segmentation
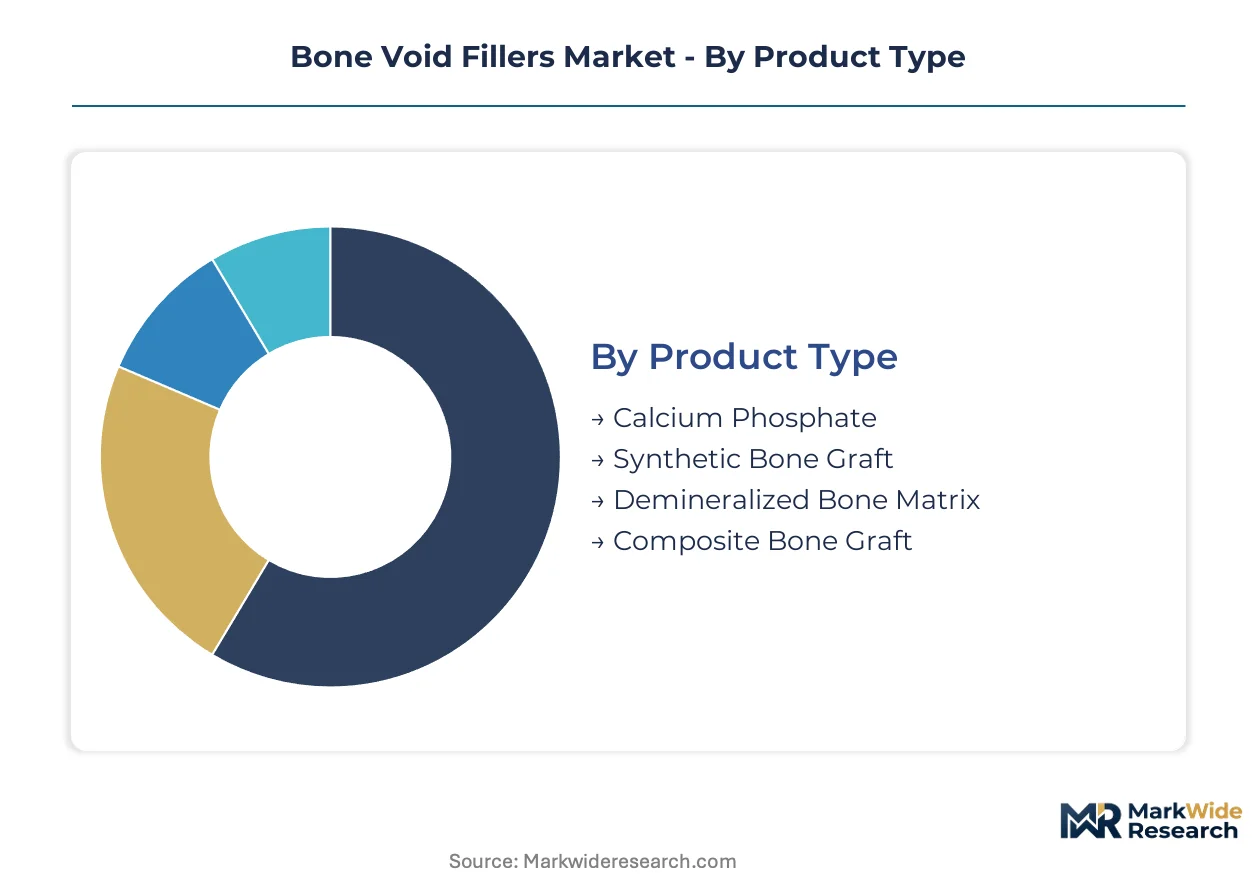
Segmentation in bone void fillers reveals how material properties, delivery formats, and care settings intersect to determine procurement patterns. Manufacturers align R&D portfolios against these dimensions to capture volume in spinal fusion, sports medicine, and ambulatory surgery expansion.
Product Type:
Domestic production concentrates calcium phosphate and synthetic grafts in the United States and Germany, while demineralized bone matrix depends on domestic tissue bank networks with limited export orientation.
- Calcium Phosphate:Hydroxyapatite and beta-tricalcium phosphate formulations provide osteoconductive scaffolds with porosities exceeding 60 percent. Demand clusters in spinal fusion procedures across Texas and Florida ASCs where surgeons prioritize predictable resorption timelines.
- Synthetic Bone Graft:Engineered polymers and ceramics offer off-the-shelf availability without tissue processing constraints. Export-led growth targets European markets where EMA MDR harmonization accelerates hydroxyapatite-based product registrations.
- Demineralized Bone Matrix:Retains bone morphogenetic proteins for osteoinduction in complex non-union cases. Supply chains concentrate in domestic US tissue banks serving hospital orthopedic departments.
- Composite Bone Graft:Blends synthetic scaffolds with biologic components to merge structural support and inductive signaling. Niche positioning targets revision spinal surgeries requiring dual functionality.
Calcium Phosphate holds the largest share; momentum sits with Synthetic Bone Graft as supply security concerns reshape procurement priorities.
Form:
Cost tier differentiation separates premium injectable systems from economy granules, with mid-tier putty formats capturing volume in ambulatory settings.
- Granules:Traditional loose particulate formats require intraoperative mixing and packing. Economy positioning sustains volume in emerging markets and cost-constrained hospital systems.
- Putty:Pre-mixed, moldable consistency enables controlled placement in open orthopedic procedures. Premium pricing in spinal fusion applications reflects surgeon preference for handling characteristics.
- Powder:Requires hydration and activation before implantation. Limited adoption concentrates in academic medical centers with specialized mixing protocols.
- Injectable:Gel and paste formulations compatible with percutaneous delivery techniques. Fastest-expanding segment as minimally invasive spinal and extremity procedures migrate to ASCs.
- Blocks:Pre-formed structural implants for load-bearing defects in trauma and tumor resection. Premium tier serves craniofacial and pelvic reconstruction cases requiring immediate mechanical stability.
Granules retain volume leadership; Injectable formats are climbing the fastest as arthroscopic techniques displace open approaches.
Application:
Volume concentration varies by reimbursement intensity, with spinal fusion commanding highest per-procedure material value and trauma repair driving highest absolute case counts.
- Spinal Fusion:Interbody and posterolateral fusion procedures consume demineralized bone matrix and ceramic scaffolds. CMS site-of-service differentials redirect volume toward ASCs in Texas and Florida.
- Orthopedic Surgery:Joint reconstruction and extremity procedures utilize synthetic grafts for cyst filling and bone loss restoration. Sports medicine volume sustains demand in US metropolitan markets.
- Dental Grafting:Ridge augmentation and sinus lift procedures employ particulate and putty formats. Smaller volume per case compresses pricing power relative to spinal applications.
- Trauma Repair:Fracture gap management and comminuted defect filling across emergency and elective settings. Highest case volume segment with pressure on material cost per procedure.
Spinal Fusion captures the highest value per procedure; Trauma Repair represents the steepest expansion trajectory as same-day fixation protocols proliferate.
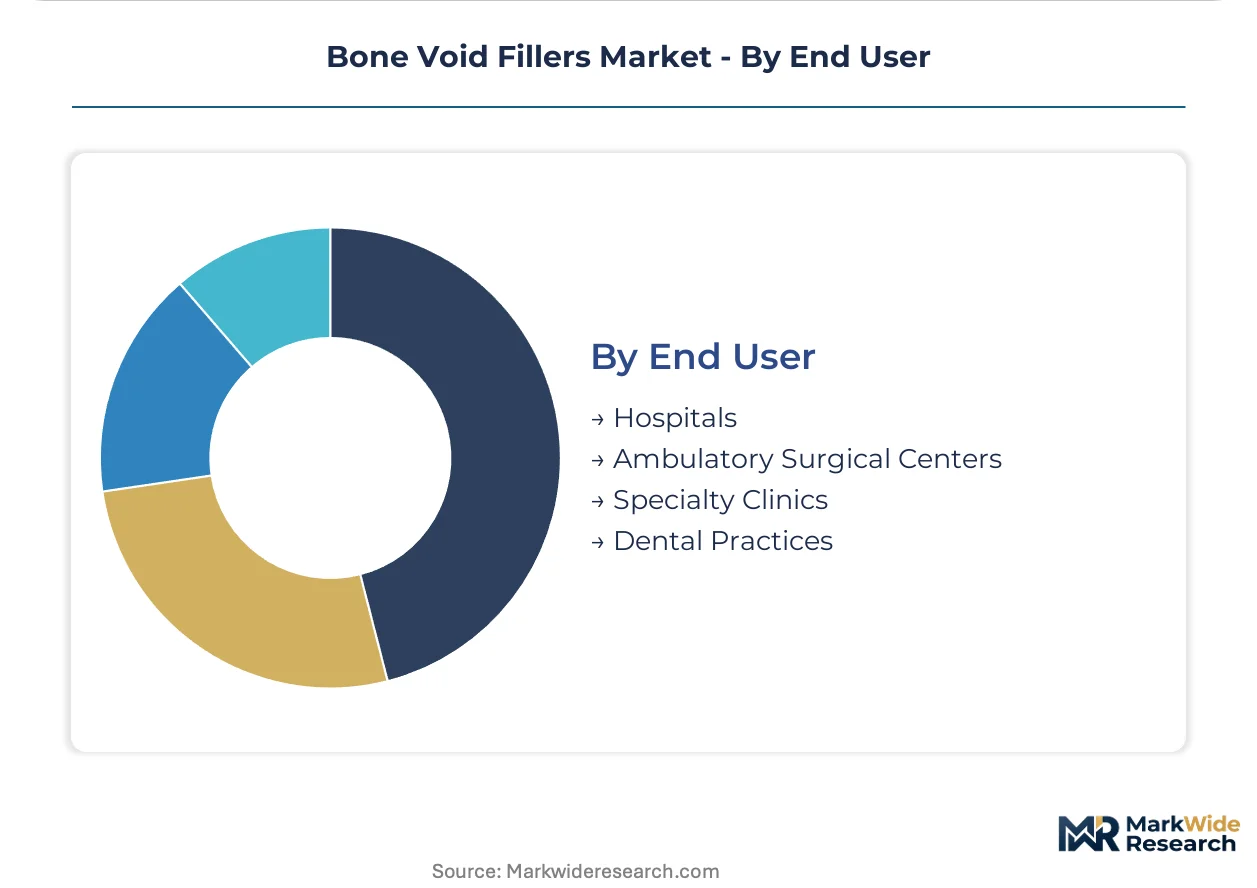
End User:
Customer type determines procurement authority, with hospital systems leveraging scale purchasing and ASCs prioritizing kit completeness and inventory turns.
- Hospitals:Inpatient orthopedic and neurosurgical departments maintain centralized purchasing with multi-year vendor contracts. Volume concentration in academic medical centers with fellowship-trained spine surgeons.
- Ambulatory Surgical Centers:Independent and hospital-affiliated same-day facilities negotiate bundled pricing for graft-plus-delivery-system kits. Buying groups aggregate multi-state volume to compress distributor margins.
- Specialty Clinics:Orthopedic and sports medicine practices performing office-based minor procedures. Limited bone void filler utilization concentrates in minor fracture management.
- Dental Practices:Oral surgeons and periodontists performing implant site preparation. Smaller account size limits direct manufacturer engagement, channeling volume through dental distributors.
Hospitals retain procurement scale leadership; ASCs are gaining share fastest as outpatient migration accelerates under IRA site-of-service incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of synthetic bone grafts clusters in the United States and Germany, while tissue-derived products depend on domestic processing networks with limited cross-border trade. Each major market exhibits distinct procurement patterns shaped by reimbursement structures and regulatory pathways.
United States
Ambulatory surgical centers in Texas and Florida drive volume growth for injectable graft formats as same-day spinal procedures expand. The FDA's 510(k) clearance framework shapes product development timelines for hydroxyapatite manufacturers. Orthopedic device clusters in Warsaw, Indiana and Memphis, Tennessee concentrate trauma and extremities innovation.
Germany
Specialized ceramic producers supply beta-tricalcium phosphate scaffolds to European spinal fusion markets. EMA MDR harmonization accelerates conformity assessments for synthetic graft categories. The Baden-Württemberg medical technology corridor around Tübingen and Ulm anchors 3D-printed scaffold research programs.
China
Domestic manufacturers expand calcium phosphate production capacity to reduce import dependence in trauma repair segments. NMPA regulatory reforms streamline Class III medical device registrations for bone graft substitutes. The Yangtze River Delta medical device cluster in Suzhou and Shanghai drives localization of synthetic graft manufacturing.
Japan
Aging demographics sustain demand for vertebral augmentation procedures utilizing injectable bone cements and grafts. PMDA consultation pathways extend timelines for novel biologic-synthetic hybrid products. The Kansai region around Osaka maintains concentration of orthopedic biomaterial research institutions.
United Kingdom
NHS procurement frameworks prioritize cost-effective synthetic grafts over premium demineralized bone matrix in elective spinal procedures. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR implementation timelines. The Cambridge-Oxford-London biotech corridor hosts early-stage scaffold engineering ventures.
Bone Void Fillers Market Key Industry Players
Concentration sits with diversified orthopedic conglomerates that leverage integrated trauma and spine portfolios to secure multi-year hospital contracts. The vendor base stratifies across three tiers: multinational device manufacturers with full orthobiologic suites, mid-cap specialists focused on synthetic ceramic formulations, and regional tissue processors dependent on domestic allograft networks. Dominant competitive moves include backward integration into phosphate rock sourcing and strategic partnerships with ambulatory surgery center buying groups.
Among the integrated multinational tier, Stryker Corporation and Zimmer Biomet occupy positions that span synthetic graft manufacturing through surgical instrumentation. DePuy Synthes represents the conglomerate archetype with diversified orthobiologic holdings across trauma, spine, and sports medicine segments. These three companies exemplify the scale-driven competitive vector where procurement scale and kit completeness determine contract outcomes.
| Leading Market Players |
|---|
| Stryker Corporation |
| DePuy Synthes (Johnson & Johnson) |
| Zimmer Biomet |
| Medtronic |
| Arthrex |
| Bonesupport |
| Bioventus |
| Baxter International |
| Biocomposites |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety day phosphate rock inventory cycles at hydroxyapatite manufacturers compress margin buffers when fertilizer industry demand spikes, concentrating pricing power with integrated suppliers in Germany and the United States while forcing spot-market buyers into unfavorable contract renegotiations.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across bone void filler categories. Three-tier pricing separates premium demineralized bone matrix from standard calcium phosphate scaffolds and economy synthetic granules. Price differentiation stems from osteoinduction certification levels and volume scale through hospital-ASC buying groups. Cost compression in injectable putty formats is intensifying because bundled kit negotiations aggregate applicator and graft material into single-price contracts. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with dedicated spine fellowships demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling of demineralized bone matrix dominates inventory strategy given tissue bank consolidation risks, while synthetic ceramic producers favor just-in-time phosphate rock sourcing. Manufacturing concentrates in the United States, Germany, and China. Production draws from phosphate rock feedstock, surgical-grade ceramic powders, and processed allograft tissue. Single-source vulnerability in US tissue bank networks creates supply disruption exposure. Distribution runs through orthopedic distributor networks serving hospital systems and ASC buying groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bone void fillers are shifting toward platform-economics dynamics where kit completeness and delivery system interoperability determine contract outcomes, mirroring the consolidation seen in arthroscopic instrument ecosystems.
For Market Incumbents: Compound channel control through backward integration into phosphate rock sourcing and captive tissue bank relationships. Synthetic graft specialists face substitution pressure from biologic-synthetic hybrids; defend through ASTM F1185 certification investment and exclusive ASC buying group partnerships.
For New Entrants and Emerging Players: Anchor in Texas and Florida ASC expansion corridors where IRA site-of-service incentives redirect spinal fusion volume. Injectable delivery formats for percutaneous extremity repair represent the most penetrable white space. Pursue co-development agreements with ambulatory surgery center buying groups to secure formulary access.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because tissue bank network scarcity and 510(k) regulatory moats protect incumbent positions. Target acquisition archetype: mid-cap ceramic specialists with EMA MDR clearance and established German manufacturing footprints. Watch FDA predicate device equivalence determinations for novel synthetic compositions as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market entry for hydroxyapatite-based products through predicate device equivalence. |
| EMA MDR Harmonization | Streamlines cross-border commercialization for synthetic graft manufacturers targeting European markets. |
| ASC Buying Group Partnership | Secures bundled kit contracts with independent surgery centers in high-growth US corridors. |
| Biologic-Synthetic Hybrid R&D | Addresses surgeon demand for dual-function grafts combining osteoinduction with structural support. |
| Phosphate Rock Backward Integration | Insulates hydroxyapatite margins from fertilizer industry feedstock price volatility. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to construct this analysis. Primary interviews engaged orthopedic surgeons, ASC procurement directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Across the analysis window, forecasts reflect modeled interactions between site-of-service migration, regulatory pathway timelines, and material substitution patterns. Segmentation dimensions include product type, delivery form, application setting, and end-user procurement authority. CAGRs were derived from trend extrapolation of procedure volumes and per-procedure material intensity. Industry-specific inputs incorporated phosphate rock price indices and ASC construction permitting data.
Material uncertainties — regulatory reclassification of nanomaterial hydroxyapatite, tissue bank supply disruptions, and CMS site-of-service payment revisions — sit outside the modeled envelope. Forecasts reflect assumptions about predicate device availability and MDR implementation timelines. Revision becomes warranted when ASC spinal fusion volume crosses hospital outpatient department parity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Patients Repositioning and Offloading Device Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
Polyethylene Orthopaedic Insert Market
Orthopedic Devices
Veterinary Orthopedic Drills Market
Orthopedic Devices
Spinal Implants and Surgical Devices Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Market
Orthopedic Devices
Bone Graft Fixation System Market
Orthopedic Devices
Non-Operative Spine Care Market
Orthopedic Devices
North America Kyphoplasty Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
Scoliosis Treatment Market