
 Pneumoconiosis Treatment Market | 2026-2036
Pneumoconiosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumoconiosis Treatment Market Analysis
Cell-based antifibrotic delivery is fragmenting traditional oral-first protocols across pneumoconiosis care pathways. Pfizer leverages its respiratory biologics infrastructure to anchor development programs in inhaled corticosteroid combinations. Novartis sustains competitive pressure through its specialty generics portfolio in emerging markets. AstraZeneca differentiates via its inhaled respiratory franchise and hospital channel control across Asia-Pacific.
Pneumoconiosis treatment encompasses pharmacological and supportive interventions targeting fibrotic lung tissue damage from inhaled mineral dusts, primarily silica and coal mine dust, with therapeutic goals centered on inflammation suppression, airway dilation, and oxygenation support. The condition arises from prolonged occupational exposure to respirable particles smaller than five micrometers, triggering progressive interstitial fibrosis that reduces pulmonary compliance and gas exchange efficiency. Antifibrotic agents command the fastest-expanding segment position as nintedanib and pirfenidone indications extend beyond idiopathic pulmonary fibrosis into occupational lung disease protocols. Hospitals retain the dominant end-user share due to acute exacerbation management requirements and specialist pulmonology access, while homecare settings capture incremental growth through portable oxygen concentrator diffusion and remote monitoring integration.
FDA orphan drug designations and EPA silica permissible exposure limit enforcement jointly shape product development priorities and reimbursement frameworks in the United States. China's NMPA accelerated review pathways for occupational disease therapeutics align with national coal mine safety administration mandates reducing dust concentration thresholds. EMA MDR compliance requirements and REACH chemical safety assessments in Europe establish dual barriers for device-drug combination therapies entering the market. Stakeholders must monitor antifibrotic pipeline readouts and regulatory harmonization progress across major jurisdictions to anticipate portfolio positioning requirements.
Market Dynamics
Cell-based antifibrotic delivery systems are fragmenting established oral-first treatment protocols across pneumoconiosis care pathways, forcing incumbent manufacturers to reconfigure respiratory biologics infrastructure around inhaled corticosteroid combinations and hospital channel control.
Growth Catalysts
- Safe Work Australia silica standards:Tightened permissible exposure limits in mining operations are expanding employer-funded occupational health programs and diagnostic screening demand.
- Coal worker pneumoconiosis protocols:China's industrial provinces maintain concentrated disease burden, driving sustained procurement of antifibrotic agents and oxygenation support equipment.
- Nintedanib indication expansion:Clinical protocol extensions beyond idiopathic pulmonary fibrosis into occupational lung diseases are accelerating hospital formulary adoption.
Market Restraints
- Specialist pulmonologist scarcity:Limited qualified practitioners in industrial mining regions restricts treatment access and protocol compliance.
- Device-drug combination complexity:EMA MDR compliance requirements and REACH chemical safety assessments create dual certification barriers for novel delivery systems.
- Biologic cold chain infrastructure:Inhaled corticosteroid combinations require temperature-controlled distribution networks absent in remote mining corridors.
Strategic Opportunities
- Homecare oxygen concentrators:Portable device diffusion and remote monitoring integration capture incremental growth outside acute hospital settings.
- FDA orphan drug designation:Expedited review pathways and reimbursement premium structures incentivize development programs targeting progressive massive fibrosis subtypes.
- China NMPA accelerated pathways:National coal mine safety administration mandates align regulatory review with dust concentration reduction targets.
Industry Challenges
- Interstitial fibrosis biomarker validation:Lack of standardized diagnostic endpoints complicates clinical trial design and regulatory submission pathways.
- Legacy oxygen concentrator integration:Remote monitoring retrofit requirements impose technical complexity on installed base equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumoconiosis Treatment Market |
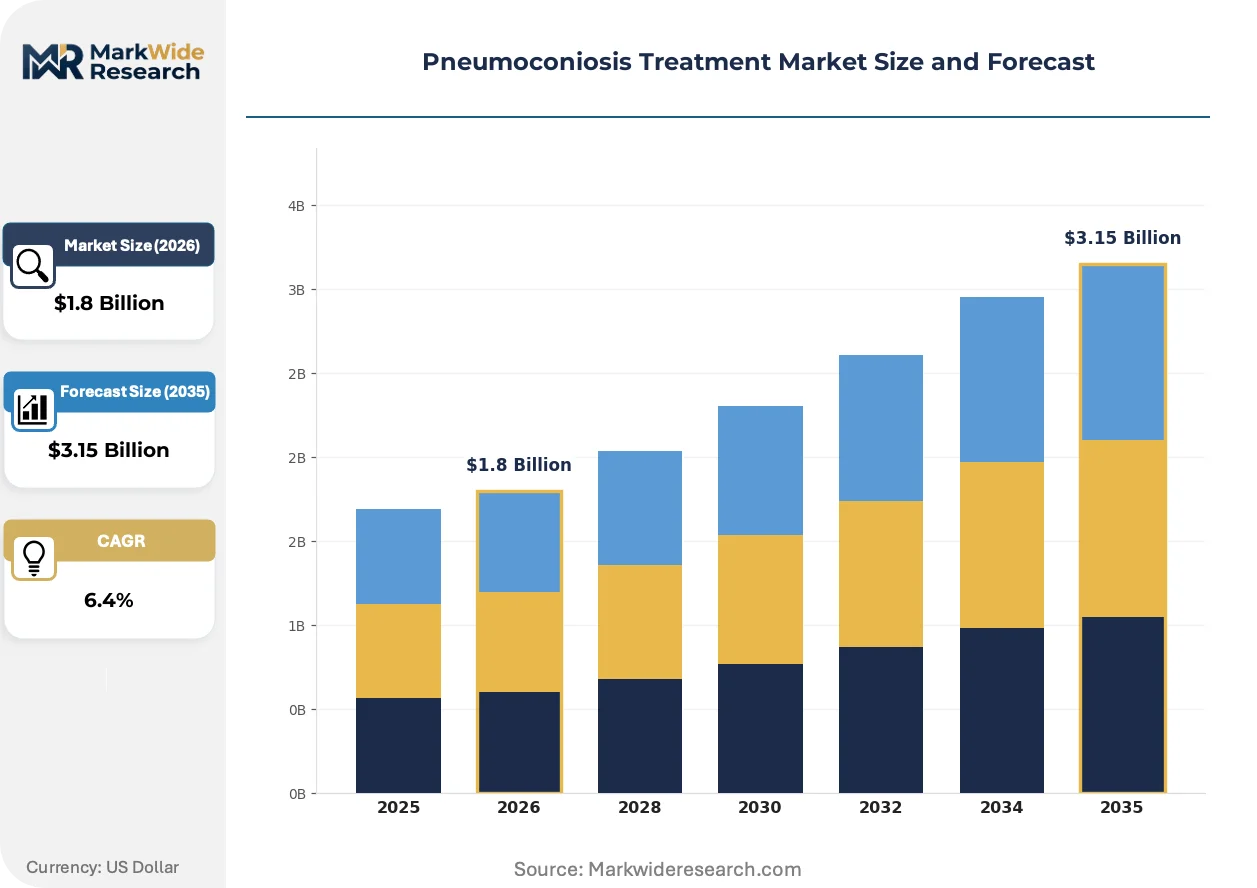
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Bronchodilators, Oxygen Therapy, Antifibrotic Agents End User: Hospitals, Specialty Clinics, Homecare Settings, Rehabilitation Centers Delivery Mode: Inhalation, Injectable, Oral, Continuous Supply Treatment Phase: Acute Care, Maintenance Therapy, Palliative Care, Preventive Care |
| Companies Covered | Pfizer, Novartis, AstraZeneca, Sanofi, Eli Lilly, Merck & Co., GlaxoSmithKline, Johnson & Johnson, F. Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumoconiosis Treatment Market Emerging Trajectories
Inhaled biologic delivery platforms are compressing treatment administration from hospital infusion centers toward ambulatory settings, while regulatory agencies across multiple jurisdictions tighten occupational exposure frameworks and reimbursement structures simultaneously.
Cell-based antifibrotic delivery systems encapsulate therapeutic agents in lipid nanoparticles for direct pulmonary deposition. Hospital pulmonology departments in Australia and China are piloting these platforms for progressive massive fibrosis cases. The technology is rendering obsolete conventional oral pirfenidone regimens that require hepatic first-pass metabolism and extended dosing intervals.
EPA silica permissible exposure limit enforcement in the United States is mandating real-time dust monitoring and medical surveillance programs across metal mining and construction operations. Mining sector employers must expand occupational health budgets to include diagnostic imaging and specialist consultation coverage. Underground coal operations in Appalachia and the Powder River Basin face the steepest compliance cost escalation.
Homecare procurement is consolidating around bundled service contracts that combine portable oxygen concentrator leasing with remote patient monitoring subscriptions. Traditional durable medical equipment distributors are losing share to respiratory-focused home health agencies. This pattern concentrates in China's Shanxi and Shaanxi provinces where coal worker pneumoconiosis prevalence drives sustained equipment demand.
Pneumoconiosis Treatment Market Segmentation
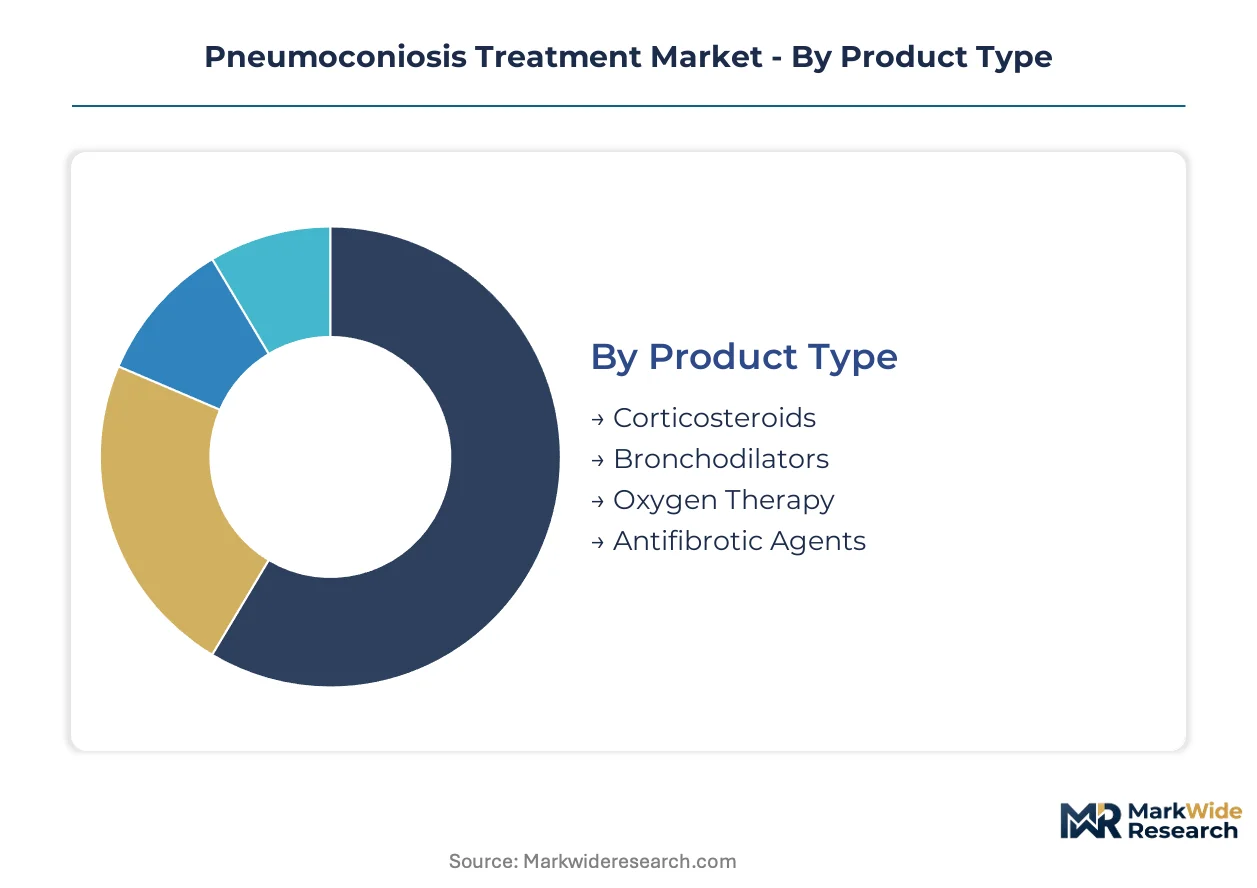
Therapeutic modality selection in pneumoconiosis care hinges on disease progression stage, fibrotic burden, and patient mobility constraints. Segmentation reveals how hospital-centric acute protocols are fragmenting toward ambulatory and home-based delivery models.
Product Type:
Mature oral formulations coexist with emerging biologic delivery platforms across the therapeutic spectrum.
- Corticosteroids:Inhaled and systemic formulations suppress inflammatory cascades in early-stage pneumoconiosis. Demand concentrates in Australian mining corridors where Safe Work Australia mandates drive employer-funded diagnostic and treatment programs.
- Antifibrotic Agents:Nintedanib and pirfenidone derivatives target transforming growth factor-beta pathways to retard fibrotic progression. Procurement accelerates in China's Shanxi and Shaanxi provinces where coal worker pneumoconiosis dominates occupational disease registries.
- Bronchodilators:Beta-agonist and anticholinergic combinations improve forced expiratory volume in maintenance protocols.
- Oxygen Therapy:Concentrator and liquid oxygen systems address hypoxemia in advanced interstitial disease.
Corticosteroids retain volume leadership; antifibrotic agents hold the steepest expansion curve.
End User:
Facility-based care yields share to distributed delivery models as remote monitoring technology matures.
- Hospitals:Acute exacerbation management and specialist pulmonology access anchor tertiary care demand. China's provincial medical centers in industrial regions absorb the highest patient volumes for progressive massive fibrosis interventions.
- Homecare Settings:Portable oxygen concentrator leasing bundled with remote monitoring subscriptions displaces traditional durable medical equipment distribution. Growth concentrates in China's coal belt provinces where patient density justifies dedicated respiratory home health agencies.
- Specialty Clinics:Occupational medicine practices manage surveillance and early intervention programs.
- Rehabilitation Centers:Pulmonary rehabilitation protocols address functional capacity decline in compensated disease.
Hospitals retain the dominant patient share; homecare settings are expanding most quickly.
Delivery Mode:
Route selection balances bioavailability requirements with patient compliance and care setting constraints.
- Inhalation:Nebulized and dry powder formulations achieve direct pulmonary deposition with reduced systemic exposure. Lipid nanoparticle encapsulation platforms are piloting in Australian hospital pulmonology departments for antifibrotic agent delivery.
- Oral:Traditional first-pass metabolism routes face displacement from pulmonary-targeted alternatives.
- Injectable:Biologic formulations require cold chain infrastructure absent in remote mining corridors.
- Continuous Supply:Oxygen concentrator systems sustain ambulatory patients outside acute episodes.
Oral delivery maintains procedural familiarity; inhalation platforms are gaining share fastest.
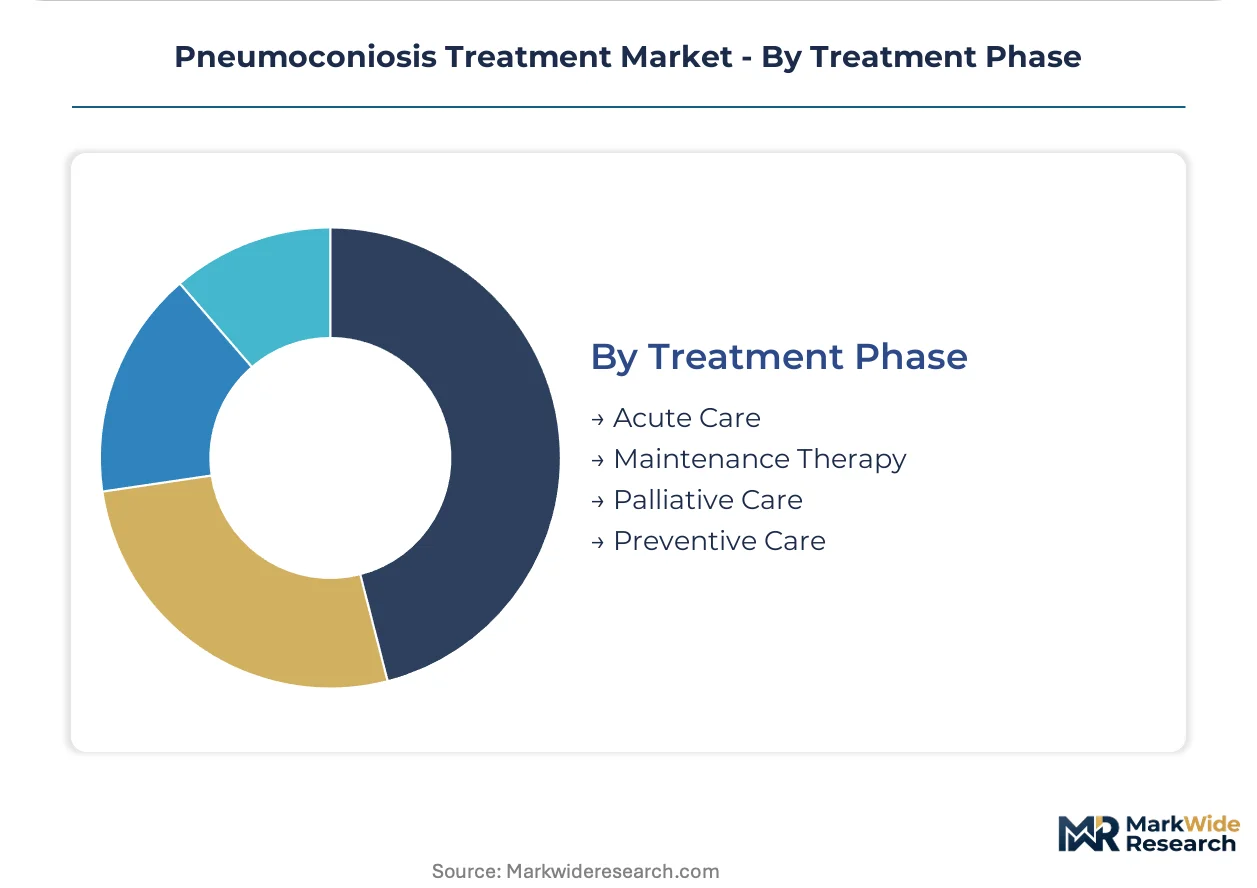
Treatment Phase:
Stage-appropriate intervention allocation determines resource utilization and outcome trajectories.
- Maintenance Therapy:Long-term antifibrotic and bronchodilator regimens stabilize lung function decline. China's NMPA accelerated review pathways align procurement with national coal mine safety administration dust reduction mandates.
- Acute Care:Exacerbation management requires hospital admission for respiratory failure and infection control.
- Palliative Care:Symptom-focused protocols address end-stage hypoxemia and quality-of-life preservation.
- Preventive Care:Surveillance programs and early detection drive employer-funded occupational health expansion.
Maintenance therapy commands the sustained patient population; preventive care is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement managers in industrial mining corridors drive concentrated demand for antifibrotic agents and oxygenation equipment across five national markets.
China
Shanxi and Shaanxi provinces absorb the highest volumes of coal worker pneumoconiosis therapeutics as the NMPA accelerates review pathways for occupational disease drugs. National coal mine safety administration mandates reducing dust concentration thresholds align procurement with regulatory timelines. Xi'an and Taiyuan medical centers pilot lipid nanoparticle antifibrotic delivery for progressive massive fibrosis cases.
Australia
Queensland and Western Australia mining employers fund expanded occupational health programs following Safe Work Australia's tightened silica exposure standards. TGA oversight of device-drug combination therapies shapes hospital formulary decisions in Perth and Brisbane. Pilbara iron ore operations face steepest compliance cost escalation for real-time dust monitoring and specialist pulmonology access.
United States
Appalachian underground coal operations and Powder River Basin surface mines absorb rising EPA enforcement of silica permissible exposure limits. FDA orphan drug designations for progressive massive fibrosis subtypes incentivize development programs targeting refractory cases. Pittsburgh and Charleston medical centers anchor tertiary care demand for acute exacerbation management.
Germany
Ruhr industrial heritage regions sustain residual pneumoconiosis burden among retired mining cohorts as EMA MDR compliance requirements filter device-drug combinations. REACH chemical safety assessments create dual certification barriers for novel inhalation platforms. Essen and Dortmund pulmonary clinics manage surveillance protocols for compensated occupational lung disease.
South Africa
Gold and platinum belt mining corridors in Gauteng and North West provinces drive demand for maintenance therapy and palliative oxygen support. The country's national pharmaceutical regulator evaluates antifibrotic registration pathways against WHO occupational health guidelines. Johannesburg academic hospitals anchor specialist pulmonology capacity for progressive interstitial fibrosis interventions.
Pneumoconiosis Treatment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across hospital and homecare procurement segments. The vendor base organizes into three tiers: multinational respiratory franchises with biologics infrastructure, specialty generics manufacturers with emerging market reach, and device-drug combination developers targeting pulmonary delivery innovation. Consolidation pressure intensifies around inhaled corticosteroid combinations and antifibrotic pipeline assets. Strategic moves center on hospital formulary anchoring and respiratory home health agency partnerships.
Within the multinational pharmaceutical tier, Pfizer, Novartis, and AstraZeneca occupy distinct positioning vectors. Pfizer exemplifies the respiratory biologics infrastructure archetype through its hospital channel dominance. Novartis represents the specialty generics and emerging market access model. AstraZeneca anchors the inhaled respiratory franchise archetype with Asia-Pacific hospital network control. These three companies collectively illustrate how therapeutic modality specialization and geographic channel control define competitive differentiation in pneumoconiosis care pathways.
| Leading Market Players |
|---|
| Pfizer |
| Novartis |
| AstraZeneca |
| Sanofi |
| Eli Lilly |
| Merck & Co. |
| GlaxoSmithKline |
| Johnson & Johnson |
| F. Hoffmann-La Roche |
| Others |
Supply Flow & Price Mechanics
Regulatory chokepoint exposure through EMA MDR compliance and REACH chemical safety assessments determines both the three-tier pricing structure across premium, standard, and economy certification levels and the geographic configuration of antifibrotic manufacturing and device assembly networks.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate procurement between Chinese coal mine safety administration programs and antifibrotic suppliers. Price differentiation hinges on FDA orphan drug designation tier and bundled remote monitoring service inclusion. Cost compression in standard-tier oral formulations is intensifying because of specialty generics competition from Novartis and emerging market manufacturers. Employer-funded occupational health programs in Australian mining corridors demonstrate lowest price sensitivity; homecare oxygen concentrator leasing in China's Shanxi province shows highest sensitivity to per-unit pricing.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for lipid nanoparticle encapsulation components and specialized nebulizer hardware. Manufacturing concentrates in China for active pharmaceutical ingredients and device assembly, in Germany for precision inhalation platform components, and in India for specialty excipient supply. Raw material dependencies include silica-grade pharmaceutical polymers, temperature-stable biologic carriers, and medical-grade aluminum for concentrator housings. Distribution runs through hospital procurement consortiums in industrial mining regions and respiratory-focused home health agencies in China's coal belt provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FDA orphan drug designation and EMA MDR compliance create certification barriers that protect incumbent formulary positions against commodity substitution.
For Market Incumbents: Insulate hospital channel control through backward integration into lipid nanoparticle manufacturing capacity in Germany or Australia. Deepen pulmonologist network capture in China's provincial medical centers to preempt emerging biologic delivery platforms. Counter the threat of cell-based antifibrotic delivery fragmenting oral-first protocols by accelerating inhaled corticosteroid combination pipeline advancement.
For New Entrants and Emerging Players: Establish a beachhead in homecare oxygen concentrator remote monitoring subscriptions in China's Shaanxi province where patient density justifies dedicated respiratory home health agency partnerships. Target the most penetrable segment of maintenance therapy antifibrotic agents for progressive massive fibrosis subtypes lacking orphan drug designation. Pursue a go-to-market angle through direct hospital pulmonology department pilot programs in Australian tertiary centers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors device-drug combination developers with EMA MDR compliance already secured. Long-term viability across the analysis window rests on regulatory entrenchment rather than manufacturing scale alone. Acquisition target archetype: specialty generics manufacturers with emerging market reach and existing NMPA accelerated pathway relationships. The signal to watch is antifibrotic pipeline readout success for nintedanib indication expansion beyond idiopathic pulmonary fibrosis.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Lipid nanoparticle antifibrotic delivery pilots in Xi'an and Taiyuan medical centers validate pulmonary deposition efficacy. |
| Regulatory Approval Pathway | FDA orphan drug designation for progressive massive fibrosis subtypes unlocks reimbursement premium structures. |
| Hospital System Partnership | Formulary anchoring in China's provincial medical centers absorbs highest patient volumes for acute interventions. |
| Manufacturing Scale-Up | Cold chain infrastructure expansion into remote Australian mining corridors addresses biologic distribution gaps. |
| Reimbursement Strategy | Employer-funded occupational health program integration in Queensland mining operations secures procurement volume. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA orphan drug designation databases, EMA MDR compliance filings, and NMPA accelerated pathway records. Primary interviews engaged drug development executives at respiratory biologics franchises, regulatory affairs leads navigating REACH chemical safety assessments, hospital procurement managers in China's Shanxi province, and formulary directors at Australian tertiary medical centers. Secondary validation drew from ClinicalTrials.gov protocol registries, Safe Work Australia exposure standard documentation, and national coal mine safety administration procurement records. Bottom-up patient population modeling and top-down therapeutic modality spend analysis were cross-referenced for triangulation.
Forecast inputs considered disease progression stage distribution, fibrotic burden severity classification, and patient mobility constraint profiles across the projection horizon. Segmentation dimensions modeled include therapeutic modality, end-user facility type, delivery mode route, treatment phase stage, and regional regulatory cluster. CAGRs were derived from patient volume growth trajectories and per-patient therapy cost evolution. Industry-specific forecast inputs incorporated EPA silica permissible exposure limit enforcement timelines and China NMPA review pathway acceleration schedules.
Stress conditions across antifibrotic pipeline failure rates, EMA MDR compliance timeline extensions, and China dust concentration threshold reduction pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding specialist pulmonologist supply expansion and cold chain infrastructure buildout. Material shifts in FDA orphan drug designation criteria or Safe Work Australia enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Asia Pacific Respiratory Therapeutic Devices Market
Respiratory Therapy
Respiratory Biologics Market
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
Croup Treatment Market
Respiratory Therapy
Viral Pneumonia Treatment Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
US Respiratory Assist Devices EUA Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis Management Market
Respiratory Therapy
Bronchial Thermoplasty Market
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market
Respiratory Therapy
Home Respiratory Therapy Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Respiratory Gating Market