
 Spectacles Market | 2026-2036
Spectacles Market Size, Share, and Industry Trends Forecast 2026-2036
Spectacles Market Intelligence
The capability gap between direct-to-consumer channel control and traditional wholesale distribution is rotating competitive dynamics. EssilorLuxottica leverages its vast retail footprint and brand portfolio to maintain market leadership. Warby Parker specializes in an online-first, direct-to-consumer model, disrupting conventional sales channels. Meanwhile, Fielmann AG dominates the German market through its extensive network of optometry clinics and value-oriented positioning.
Spectacles are optical devices consisting of corrective or protective lenses set within a frame that rests on the nose and ears. The lenses are manufactured from materials like polycarbonate or high-index plastics and ground to precise dioptric powers to correct visual impairments. Prescription glasses constitute the core product type, while demand for computer and blue light blocking glasses accelerates due to digital screen usage. Frame material choices like acetate and titanium are central to design differentiation and pricing strategies for fashion consumers.
Regulatory oversight from bodies like the U.S. FDA and compliance with Europe’s Medical Device Regulation (MDR) govern prescription eyewear as medical devices. Global standards, including ISO 12870 for spectacle frames, ensure product safety and quality across international markets. Future competitive advantage will hinge on a manufacturer's ability to integrate sustainable materials and smart technology features into their product lines.
Market Dynamics
The market's central dynamic is the redefinition of spectacles from a medical necessity to a dual-purpose wellness and fashion accessory. This shift is propelled by rising consumer health consciousness regarding digital eye strain and the influence of social media on eyewear trends.
Growth Catalysts
- Lens Technology Innovation:Advancements in blue light filtering and anti-reflective coatings, integrated into polycarbonate and high-index plastics, meet demand from office professionals and digital device users, expanding the market beyond simple vision correction.
- Rising Myopia in Asia:High prevalence of myopia and increasing screen time among younger populations in countries like China and South Korea are creating a sustained demand base for corrective prescription lenses.
- Occupational Health Mandates:Workplace safety regulations in Europe, requiring employers to provide vision screening and necessary corrective devices for VDU workers, stimulate bulk corporate purchases of computer glasses.
Market Restraints
- Alternative Vision Correction:The growing popularity and technological improvement of contact lenses and refractive surgeries, such as LASIK, present a significant substitution threat, particularly among younger, appearance-conscious consumer segments.
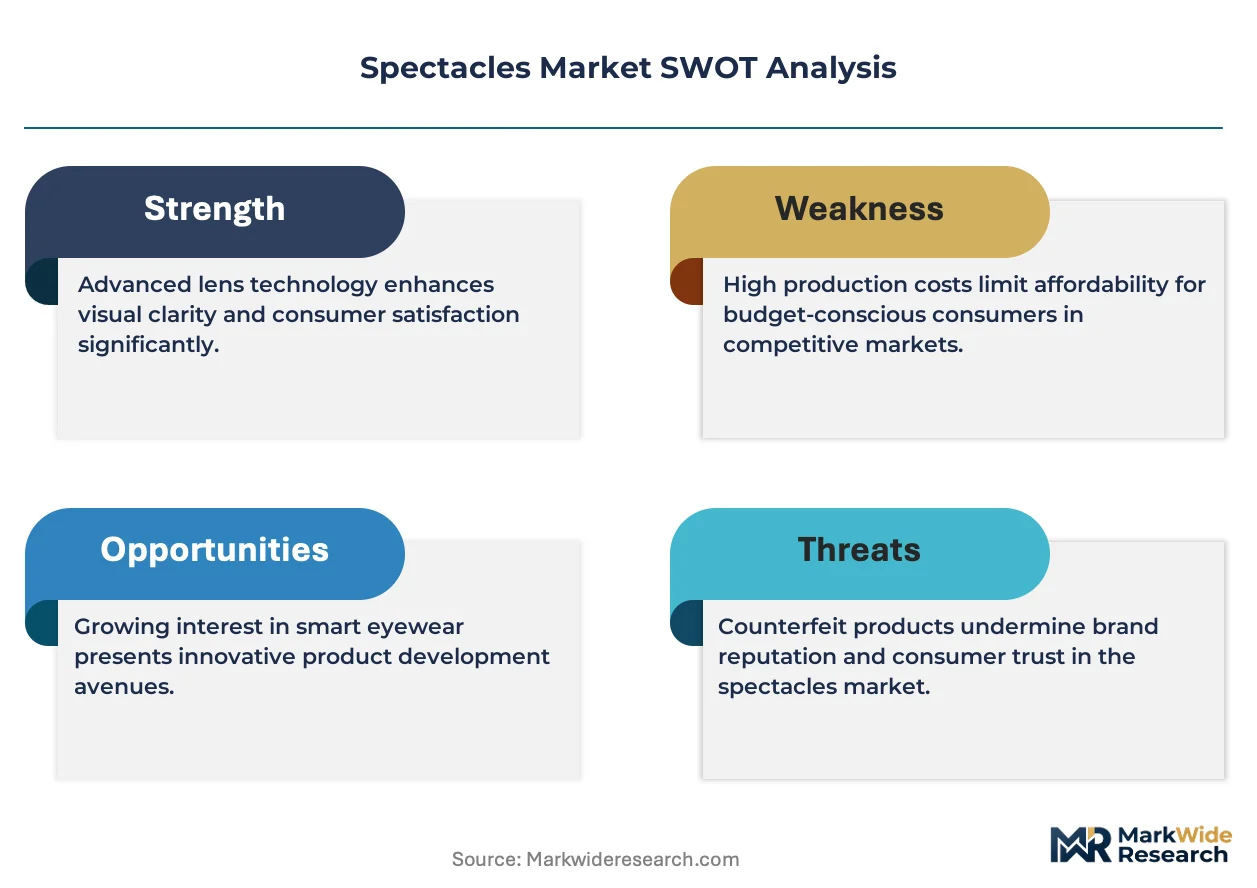
- Raw Material Price Volatility:Price fluctuations for premium frame materials like titanium and specialized polymers such as acetate can compress manufacturer margins, especially for independent brands without large-scale procurement power.
- Channel Domination by Incumbents:The extensive retail and supply chain control exerted by vertically integrated players creates high barriers to entry for new direct-to-consumer brands seeking to secure manufacturing capacity and distribution access.
Strategic Opportunities
- Smart Glass Integration:The convergence of corrective eyewear with smart technology, such as embedded displays and audio, offers a new frontier for product development, targeting tech-savvy consumers and creating new high-margin categories.
- Sustainable Materials:Incorporating recycled plastics and bio-acetates into frame manufacturing appeals to environmentally conscious consumers and can unlock premium pricing, aligning with regulations like the EU's CSRD.
- Rural Market Penetration in India:Expanding access to affordable vision screening and basic spectacles in underpenetrated rural regions of India through mobile clinics and government health initiatives represents a major volume growth opportunity.
Industry Challenges
- Navigating Divergent Regulations:Manufacturers face complexity in ensuring products comply with differing medical device regulations, such as the FDA's requirements in the US and Europe’s MDR, increasing time-to-market and compliance costs.
- Brand and Design Counterfeiting:The proliferation of counterfeit luxury and designer spectacle frames, particularly through online marketplaces, erodes brand value and siphons revenue from legitimate manufacturers, requiring constant legal action.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spectacles Market |
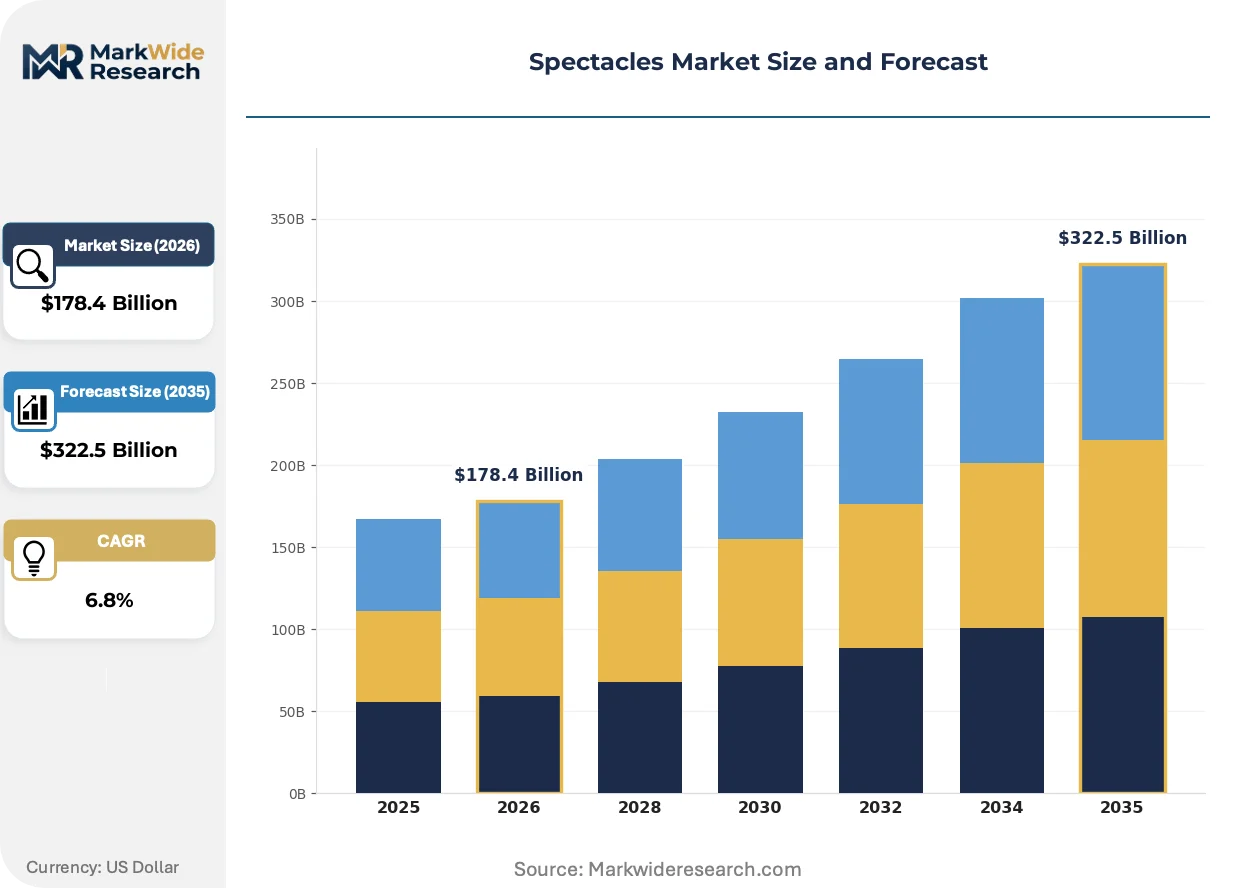
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $322.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Glasses, Sunglasses, Reading Glasses, Computer Glasses, Safety Glasses, Blue Light Blocking Glasses Frame Material: Metal, Acetate, Titanium, Plastic, Wood, Carbon Fiber Lenses Technology: Single Vision, Bifocal, Progressive, Photochromic, Polarized, Anti-Reflective End User: Optometry Clinics, Optical Retailers, Online Stores, Sports Enthusiasts, Fashion Consumers, Industrial Workers |
| Companies Covered | Safilo Group S.p.A, Fielmann AG, EssilorLuxottica, CooperVision, Innovative Eyewear, Inc., Alcon, Bausch & Lomb Inc., Warby Parker, Johnson & Johnson Vision Care, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spectacles Market Strategic Shifts & Innovations
Product development is increasingly focused on personalization and niche functional applications, moving beyond one-size-fits-all vision correction. This evolution reflects a market where specific user needs, from digital wellness to athletic performance, dictate design and material choices.
Advanced sensor technology integrates components like accelerometers and micro-projectors directly into spectacle frames. Adoption is led by early adopters in tech and fitness segments seeking data integration. This trend is miniaturizing complex electronics, enabling unobtrusive smart glasses that merge fashion with augmented reality and health tracking.
Global quality standards, particularly ISO 12870 for spectacle frames, are gaining prominence for market access and consumer trust. This standard's enforcement ensures frame durability and safety, compelling manufacturers to invest in higher-grade materials and quality control. The prescription lens segment is most affected, as compliance becomes a key differentiator.
A shift in purchasing behavior favors online, direct-to-consumer channels offering virtual try-on tools and home delivery. This model disrupts traditional optometry practices, which now compete on service and clinical expertise. This trend is most pronounced in North American and European urban centers among millennial and Gen Z consumers.
Spectacles Market Segmentation
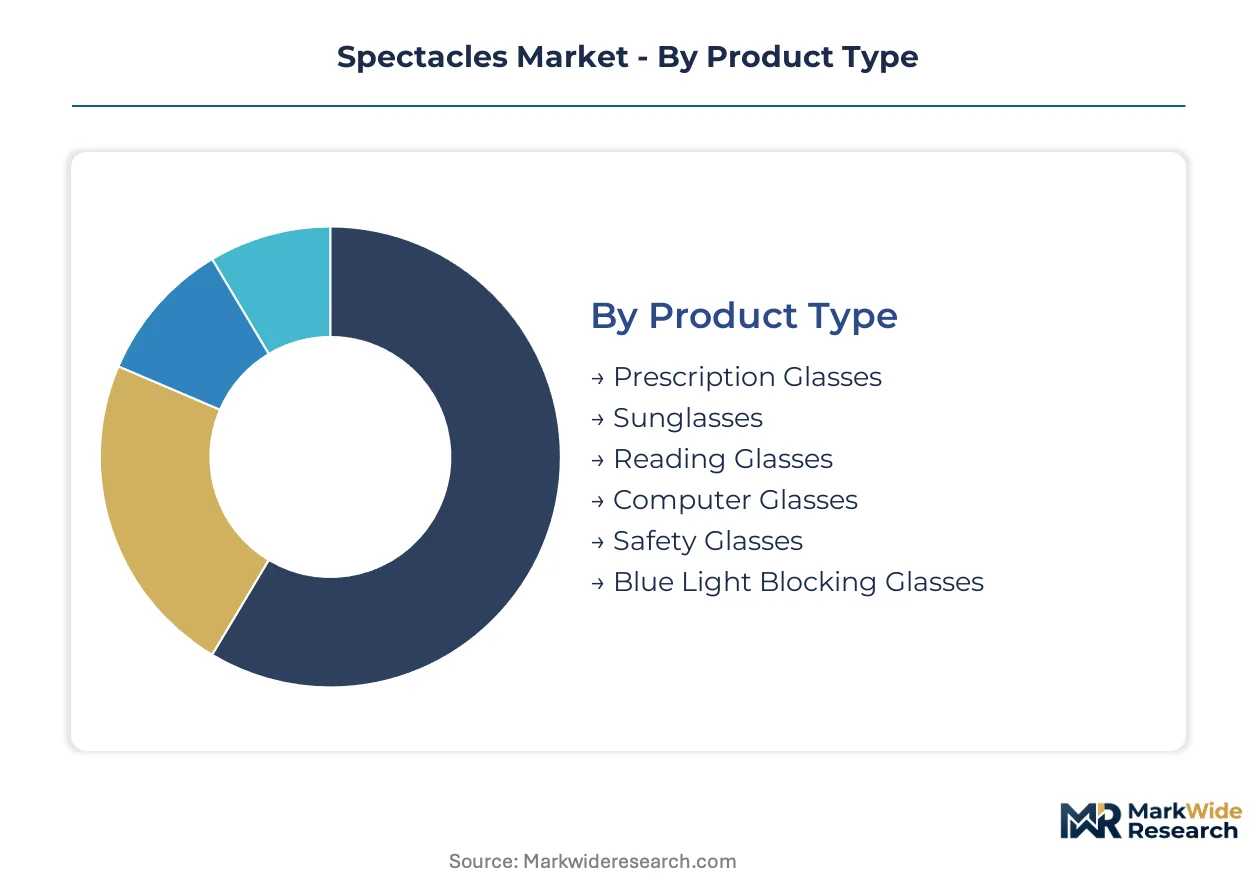
Understanding the Spectacles Market through segmentation reveals distinct consumer needs and competitive battlegrounds. Each product type, material, lens technology, and end-user group presents unique value propositions and growth trajectories. Strategic differentiation across these segments allows manufacturers to capture specific market niches.
Product Type:
The product type segment faces substitution pressure from alternative vision correction methods like contact lenses and refractive surgeries. This dynamic influences demand for traditional corrective eyewear.
- Prescription Glasses:These optical devices feature corrective lenses ground to precise dioptric powers to address visual impairments. Demand concentrates in countries like China due to high myopia prevalence and increasing screen time among younger populations.
- Computer Glasses:Specifically designed with blue light filtering and anti-reflective coatings, these glasses reduce digital eye strain for office professionals. Occupational health mandates in Europe stimulate bulk corporate purchases, expanding their market footprint.
- Sunglasses:These glasses provide UV protection and serve as a fashion accessory, with design trends influencing consumer choices.
- Reading Glasses:Magnification lenses assist individuals with presbyopia, a common age-related vision condition.
- Safety Glasses:Constructed for impact resistance, these protective eyewear items are essential in industrial and hazardous work environments.
- Blue Light Blocking Glasses:These glasses filter harmful blue light emitted from digital screens, addressing growing consumer health consciousness regarding digital eye strain.
Prescription Glasses anchors the volume base while Blue Light Blocking Glasses gains share at the steepest rate.
Frame Material:
The frame material segment differentiates products across various cost tiers, impacting both production costs and consumer pricing strategies. Material selection directly influences durability, aesthetics, and comfort for the end-user.
- Acetate:This plant-based plastic offers rich colors and patterns through a layering process, appealing strongly to fashion consumers seeking design differentiation. Price volatility for specialized polymers like acetate can compress manufacturer margins, especially for independent brands.
- Titanium:Known for its exceptional strength, lightweight properties, and hypoallergenic nature, titanium caters to the premium segment. Its use allows for thin, durable frames that command higher price points for discerning customers.
- Metal:Traditional metal frames provide durability and a classic aesthetic, remaining a cost-effective option for a broad consumer base.
- Plastic:Versatile and lightweight, plastic frames offer a wide range of designs and colors, making them popular in the mass market.
- Wood:Frames made from wood or bamboo appeal to environmentally conscious consumers seeking natural and sustainable product options.
- Carbon Fiber:This advanced composite material offers high strength-to-weight ratio and a modern look, targeting tech-savvy consumers and sports enthusiasts.
Plastic frames maintain the largest market share, while sustainable materials like Wood and Carbon Fiber show the fastest expansion in niche markets.
Lenses Technology:
Lenses technology addresses diverse application requirements, from simple vision correction to specialized protective functions. Innovations in this segment directly enhance user experience and expand market utility.
- Progressive:These lenses offer seamless vision correction across multiple focal zones, effectively addressing presbyopia without visible lines. They provide convenience for individuals requiring correction for near, intermediate, and far vision.
- Anti-Reflective:Applied as a coating, this technology reduces glare from light sources and improves visual clarity, particularly beneficial for digital device users. It enhances aesthetic appeal by making lenses appear almost invisible.
- Single Vision:Correcting a single field of vision, these lenses are the most common type for myopia, hyperopia, and astigmatism.
- Bifocal:Lenses featuring two distinct optical powers, typically for distance and reading, separated by a visible line.
- Photochromic:These lenses automatically adjust their tint based on UV light exposure, providing convenience by eliminating the need for separate sunglasses.
- Polarized:Designed to reduce glare from reflective surfaces like water or snow, polarized lenses are popular among outdoor enthusiasts and drivers.
Single Vision lenses command the highest volume, but Anti-Reflective and Photochromic technologies are gaining traction rapidly through continuous innovation.
End User:
The end-user segment reflects varied purchasing behaviors and service expectations across different customer types. Distribution channels are evolving to meet these distinct consumer preferences.
- Online Stores:These platforms leverage virtual try-on tools and home delivery services, disrupting traditional retail models by catering to millennial and Gen Z consumers in North American and European urban centers. Warby Parker exemplifies this online-first, direct-to-consumer approach.
- Optometry Clinics:Traditional optometry clinics offer clinical expertise, personalized fittings, and medical device compliance, serving as a primary channel for prescription eyewear. Fielmann AG dominates the German market through its extensive network of these clinics.
- Optical Retailers:Brick-and-mortar optical retailers provide a wide selection of brands and immediate purchase options, appealing to consumers seeking a tangible shopping experience.
- Sports Enthusiasts:This segment demands durable, performance-enhancing eyewear tailored for specific athletic activities, often incorporating specialized lens technologies.
- Fashion Consumers:Driven by design and brand identity, fashion consumers prioritize aesthetics and trends in their eyewear choices, often influencing pricing strategies.
- Industrial Workers:Occupational safety regulations stimulate demand for protective eyewear in this segment, with employers often providing necessary devices for VDU workers.
Optometry Clinics maintain significant market share due to clinical trust, while Online Stores are expanding their customer base most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power exhibits asymmetry, with established markets like Germany maintaining premium price points while emerging economies such as India prioritize affordability. This divergence shapes distribution strategies and product offerings across global markets. Manufacturers adapt to varied consumer purchasing behaviors and regulatory environments.
China
Myopia prevalence and digital screen time drive substantial demand for corrective lenses among younger populations. The government's focus on health initiatives promotes vision care awareness. Manufacturing hubs in the Yangtze River Delta concentrate on high-volume spectacle production for domestic and export markets.
Germany
Occupational health mandates requiring employers to provide vision screening for VDU workers create a stable demand base. Europe’s Medical Device Regulation (MDR) ensures high product safety and quality standards. Major optical retailers in cities like Berlin leverage extensive clinic networks for personalized service.
United States
Consumer preference for online-first, direct-to-consumer models is reshaping distribution channels, particularly among younger demographics. U.S. FDA regulations govern prescription eyewear as medical devices, ensuring product efficacy. Technology clusters in Silicon Valley are exploring smart glass integration for tech-savvy consumers.
India
Underpenetration in rural regions presents a significant volume growth opportunity for affordable vision care solutions. Government health initiatives aim to expand access to basic spectacles through mobile clinics. Delhi-NCR serves as a crucial distribution and logistics hub for both domestic and international brands.
South Korea
High rates of myopia among school-aged children and extensive digital device usage sustain demand for advanced corrective lenses. The MFDS (Ministry of Food and Drug Safety) oversees medical device compliance for eyewear products. Seoul's fashion-forward consumer base drives trends in frame design and material innovation.
Spectacles Market Key Industry Players
Concentration sits with vertically integrated incumbents that control extensive retail and manufacturing operations. The market structure exhibits a tiered competitive dynamic, encompassing global brand conglomerates, online-first disruptors, and regional specialists. Key competitive moves include deepening vertical integration into lens production and frame manufacturing, alongside strategic geographic expansion into high-growth emerging markets. Portfolio diversification also allows players to target various consumer segments.
Within the vertically integrated incumbent tier, EssilorLuxottica leverages its vast retail footprint and brand portfolio to maintain market leadership across numerous geographies. Fielmann AG, a prominent regional specialist, dominates the German market through its extensive network of optometry clinics and value-oriented positioning. Disrupting conventional sales channels, Warby Parker exemplifies an online-first, direct-to-consumer model, appealing to digitally native consumers with virtual try-on tools and home delivery services, thereby challenging traditional optical retail.
| Leading Market Players |
|---|
| Safilo Group S.p.A |
| Fielmann AG |
| EssilorLuxottica |
| CooperVision |
| Innovative Eyewear, Inc. |
| Alcon |
| Bausch & Lomb Inc. |
| Warby Parker |
| Johnson & Johnson Vision Care, Inc. |
Cost & Logistics Intelligence
Three-month inventory cycles for premium spectacle frames directly influence pricing power, especially for brands managing diverse material sourcing and complex manufacturing. This dynamic shapes the competitive landscape for both established players and emerging online retailers.
Pricing Analysis
Configured-to-order spectacle frames command a premium over standard mass-produced models, reflecting customization and brand value. The dominant pricing structure is a three-tier system across premium, standard, and economy levels, driven by material quality and design differentiation. Geographic delivery costs also influence final consumer pricing. Pricing softness affects the mass-market plastic frame segment due to high volume production and intense competition. Online shoppers, particularly millennial and Gen Z consumers, exhibit the highest price sensitivity for basic vision correction.
Supply Chain Analysis
China and South Korea anchor high-volume spectacle production, leveraging established manufacturing hubs and skilled labor for both frames and lenses. The market draws from specialized polymers like acetate and high-index plastics, alongside metals such as titanium. Commodity price volatility for these raw materials presents a structural risk for manufacturers without long-term supply contracts. Distribution runs through a hybrid model, with traditional optometry clinics maintaining clinical trust and online stores expanding their customer reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term regulatory entrenchment, particularly for prescription eyewear classified as medical devices, creates a defensive moat around this market. This structural advantage ensures sustained demand and high barriers to entry for new players.
For Market Incumbents: Consolidate market share through strategic acquisitions of niche technology firms specializing in smart glass components or advanced lens coatings. Deepen backward integration into lens production to mitigate raw material price volatility, countering threats from low-cost online disruptors. Invest in R&D for sustainable materials to align with evolving consumer preferences and regulatory mandates like Europe’s CSRD. Expand retail footprints in high-growth urban centers to maintain channel control against online-first models.
For New Entrants and Emerging Players: Certification fast-track pathways for innovative blue light blocking lens technologies offer a rapid entry point into the market. Target the underserved rural regions of India with affordable, basic spectacles, leveraging mobile clinics for vision screening. Focus on sustainable materials like bio-acetates for frame manufacturing, appealing to environmentally conscious consumers. An online-first, value-oriented go-to-market angle can disrupt traditional retail channels effectively.
For Investors and Strategic Acquirers: Long-term, this sits as a resilient growth play because vision correction remains a fundamental human need, evolving from medical necessity to a fashion accessory. Identify regional specialists with strong optometry clinic networks or innovative smart glass technology developers as prime acquisition targets. A key signal to watch is the adoption rate of smart glass features within the tech-savvy consumer segment, indicating future high-margin category expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Backward Integration | Secures critical lens and frame material supply, mitigating commodity price fluctuations. |
| Expand Online-First Channels | Captures digitally native consumers and broadens market reach beyond traditional retail. |
| Invest in Smart Glass R&D | Develops high-margin products integrating augmented reality and health tracking features. |
| Target Rural India Penetration | Unlocks significant volume growth by addressing underpenetrated, price-sensitive consumer bases. |
| Integrate Sustainable Materials | Appeals to environmentally conscious consumers and aligns with evolving global regulations. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation across publicly available data. Opticians, product designers, regulatory affairs specialists, and supply chain managers provided critical qualitative insights into market dynamics. Bottom-up and top-down triangulation of data ensured robust market sizing and segmentation across various product types.
The analytical framework projected market trajectories across the analysis window, modeling segmentation dimensions including product type, frame material, lens technology, end-user, and key geographic regions. Compound annual growth rates were derived through a comprehensive assessment of historical trends and projected demand drivers. Key forecast inputs included evolving screen time trends and global myopia prevalence rates.
Underlying assumptions cover stable economic conditions and consistent regulatory frameworks, with deviation risk concentrated in raw material price volatility. Advancements in alternative vision correction methods also pose a potential risk to demand forecasts. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Wooden Eyewear Market
Eyewear
Plano Sunglasses Market
Eyewear
Smart Sunglasses Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Polarized Sunglasses Market
Eyewear
Blue Light Glasses Market
Eyewear
Eyewear Market
Eyewear
Goggles Market
Eyewear
Luxury Sunglass Market
Eyewear
Glasses Frame Market
Eyewear
Anti-Blue Light Glasses Market
Eyewear
Luxury Eyewear Market
Eyewear
North America Eyewear Market
Eyewear
3D Printing in Eyewear Market
Eyewear
Sunglasses Pouch Market
Eyewear
Latin America Eyewear Market